
 Animal Feed Enzymes Market | 2026-2036
Animal Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Enzymes Market Analysis
Project finance and leasing arrangements for large-scale bioreactor installations is reshaping competitive entry in feed enzyme manufacturing. Novonesis leverages its consolidated fermentation infrastructure to sustain cost leadership across European and Asian supply corridors. Cargill, Inc. anchors North American distribution through backward integration into grain origination and premix formulation networks. BASF SE differentiates via specialized enzyme engineering platforms that optimize thermal stability during pelleting processes.
Animal feed enzymes are proteinaceous biological catalysts—typically derived from fungal or bacterial fermentation—that hydrolyze anti-nutritional factors in feedstuffs, with phytase operating optimally at pH 2.5-5.5 and temperatures between 40-60°C to liberate bound phosphorus from phytate complexes. These additives primarily reduce feed costs, improve nutrient digestibility, and lower environmental nutrient loading in intensive livestock operations. Phytase commands the largest revenue pool among product types due to universal deployment across monogastric species, while protease exhibits the fastest trajectory as producers seek to valorize alternative protein meals with lower amino acid digestibility. Poultry applications dominate volume consumption, though aquaculture represents the most margin-attractive expansion frontier as marine and shrimp operations adopt high-performance enzyme blends.
The EU Green Deal and REACH frameworks restrict antibiotic growth promoter residues and mandate nutrient management plans, directly elevating enzyme incorporation rates in compound feeds. FDA and USDA oversight in the United States governs GRAS determinations and label claims for direct-fed microbials and enzymes, creating compliance thresholds that favor established manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving maximum permitted levels for phosphorus and nitrogen in manure across multiple jurisdictions, as tightening thresholds will determine which enzyme portfolios retain formulation relevance.
Market Dynamics
EU Green Deal mandates are compressing phosphorus discharge limits for intensive livestock operations, forcing compound feed manufacturers to reformulate with higher phytase inclusion rates and triggering upstream capacity investments across fermentation-based enzyme production.
Growth Catalysts
- REACH Nutrient Management Protocols:EU member states now enforce manure phosphorus ceilings that elevate enzyme incorporation in swine and poultry rations above baseline levels.
- Brazilian Integrated Operations:Large-scale poultry and swine producers in Mato Grosso and Paraná states are deploying multi-enzyme programs to capture feed conversion efficiency gains.
- Thermostable Phytase Engineering:Next-generation variants withstand pelleting temperatures above 85°C, eliminating the need for post-pelleting liquid application systems.
Market Restraints
- Fermentation Input Volatility:Corn steep liquor and soybean meal prices for microbial culture media fluctuate with commodity grain markets, compressing manufacturing margins unpredictably.
- Danish Supply Concentration:Novozymes and Novonesis control critical fermentation infrastructure in Kalundborg and Copenhagen corridors, creating single-source dependencies for European compounders.
- Phytase Efficacy Plateaus:Diminishing returns on phosphorus liberation beyond 500 FTU/kg in finishing diets limit premium pricing for super-dosed formulations.
Strategic Opportunities
- Indonesian Aquaculture Expansion:Shrimp and marine finfish operations in Sulawesi and Sumatra remain underpenetrated for protease-carbohydrate blends targeting plant protein meals.
- USDA Conservation Reserve Incentives:Nutrient management cost-share programs indirectly subsidize enzyme adoption by livestock producers seeking phosphorus compliance credits.
- CRISPR-Edited Strain Development:Precision genome editing of Aspergillus niger and Trichoderma reesei is yielding secretion-enhanced cellulase variants for ruminant fiber degradation.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiology and downstream processing expertise concentrates in legacy biotech hubs, constraining greenfield facility staffing.
- GRAS Timeline Compression:FDA novel enzyme submissions face 18-24 month review cycles that delay product commercialization relative to EU EFSA parallel pathways.
- Legacy Premix Integration:Existing micro-ingredient dosing equipment at feed mills requires retrofitting to handle hygroscopic enzyme granule flow characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Enzymes Market |
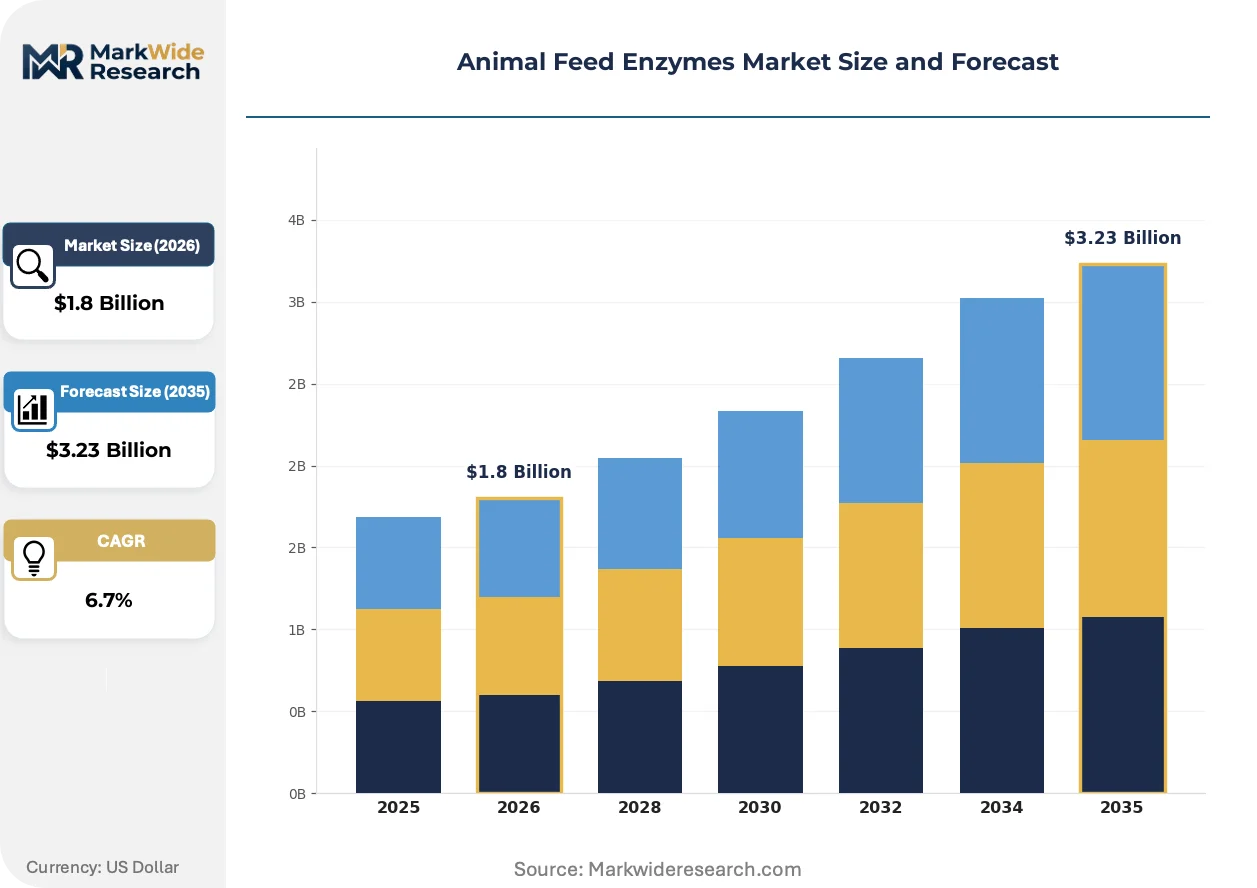
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phytase, Xylanase, Amylase, Protease Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Pelleted Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Adisseo, Archer Daniels Midland Co., Novonesis, Koninklijke DSM NV, IFF (Danisco Animal Nutrition), BASF SE, Kemin Industries, Inc., Elanco Animal Health Inc., Cargill, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Enzymes Market Emerging Trajectories
Enzyme engineering and regulatory chemistry are converging to redefine formulation economics, with thermal stability and substrate specificity emerging as the primary axes of product differentiation in compound feed manufacturing.
Cell-free enzyme synthesis platforms bypass traditional fermentation bottlenecks by producing catalytic proteins through in vitro transcription-translation systems. Early adopters in specialty aquaculture premixes are piloting these biocatalysts at pilot scale. This distributed manufacturing architecture is rendering obsolete the capital-intensive bioreactor networks that historically constrained geographic supply flexibility.
EPA nutrient trading frameworks in Chesapeake Bay and Ohio River watersheds create marketable phosphorus credits for livestock operations achieving verified excretion reductions. Industrial consequence includes mandatory third-party verification protocols that enzyme suppliers must support with digestibility trial documentation. Poultry integrators in Maryland and Virginia are most affected, with contract growers now specifying enzyme inclusion in nutrition specifications.
Compounders are consolidating procurement around full-service nutrition partners who bundle enzyme supply with formulation software and on-farm technical service. This displaces traditional ingredient trading houses that lacked in-house enzymology capabilities. The shift is most visible among mid-sized swine operations in Iowa and North Carolina, where margin pressure favors integrated input sourcing over spot-market enzyme purchasing.
Animal Feed Enzymes Market Segmentation
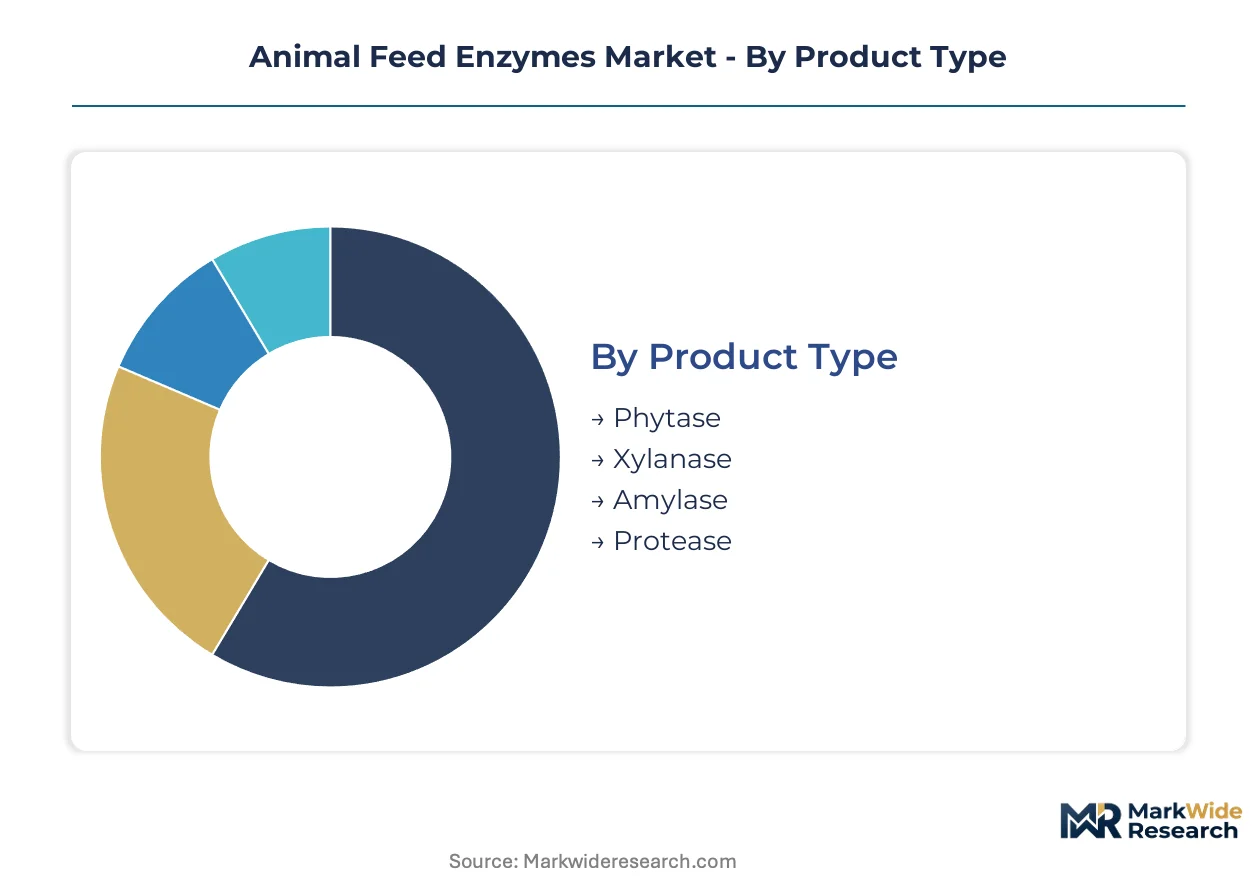
Feed enzyme segmentation reflects divergent technical requirements across species digestive physiology and manufacturing process constraints. Formulation decisions cascade from thermal stability needs in pelleting operations through to species-specific substrate targeting in the gastrointestinal tract.
Product Type:
Phytase and protease command disproportionate development investment due to contrasting value capture mechanisms in monogastric nutrition.
- Phytase:This phosphohydrolase enzyme liberates inositol phosphate-bound phosphorus from plant-derived phytate, operating optimally in the acidic pH range of the avian and swine proventriculus. Brazilian integrated poultry operations in Mato Grosso deploy phytase at elevated inclusion rates to meet EU export standards for manure phosphorus limits. The dominant share belongs to phytase, while protease is closing the gap fastest.
- Protease:Endo- and exopeptidase cocktails hydrolyze protein substrates into absorbable amino acids, enabling valorization of alternative meals with inferior digestibility coefficients. Indonesian shrimp farmers in Sulawesi are adopting protease-carbohydrate blends to reduce fishmeal dependency in high-density marine systems.
- Xylanase:Hemicellulase targeting arabinoxylan backbones in cereal cell walls, primarily deployed in wheat-based rations for viscosity reduction in the small intestine.
- Amylase:Starch-hydrolyzing enzyme supplementing endogenous pancreatic secretion, most relevant in young animal diets with immature digestive enzyme production.
Phytase retains formulation ubiquity across species, though protease is expanding most quickly as amino acid economics intensify.
Application:
Volume concentration tracks intensive production system density and regulatory pressure on nutrient excretion.
- Poultry:Broiler and layer operations generate the largest absolute enzyme consumption due to short production cycles and precise feed conversion ratio optimization. EU Green Deal phosphorus ceilings have triggered reformulation across Dutch and Polish compound feed mills. Poultry captures the dominant share, while aquaculture is gaining share fastest.
- Aquaculture:Marine finfish and shrimp systems command premium pricing for thermostable, broad-pH-range enzyme cocktails addressing plant protein anti-nutritional factors. Vietnamese pangasius producers in the Mekong Delta are scaling multi-enzyme programs to substitute soybean meal for fishmeal.
- Swine:Post-weaning and finishing diets incorporate phytase and carbohydrase blends to manage nitrogen and phosphorus output under tightening watershed regulations.
- Ruminants:Fiber-degrading enzyme research targets cellulase and hemicellulase efficacy in the rumen environment, though commercial deployment lags monogastric applications.
Broiler integration drives volume leadership, though aquaculture exhibits the steepest expansion trajectory as marine protein substitution accelerates.
Form:
Physical presentation determines handling characteristics through feed mill processing stages and storage stability requirements.
- Granular:Spray-dried enzyme concentrates on inert carriers provide flowability for automated micro-ingredient dosing systems and protection against thermal degradation during pelleting. Iowa-based swine operations are retrofitting legacy premix equipment to handle hygroscopic granule characteristics.
- Liquid:Post-pelleting application systems bypass heat exposure entirely, preferred for super-concentrated thermolabile enzyme variants in high-temperature feed manufacturing.
- Powder:Direct-to-farm blending for on-site mash feed production, prevalent in smaller-scale operations with limited pelleting infrastructure.
- Pelleted:Co-extruded enzyme-matrix combinations for specialized applications requiring extended release kinetics in the digestive tract.
Granular formulations dominate commercial supply, while liquid application is climbing fastest as thermostable engineering reduces but does not eliminate post-pelleting demand.
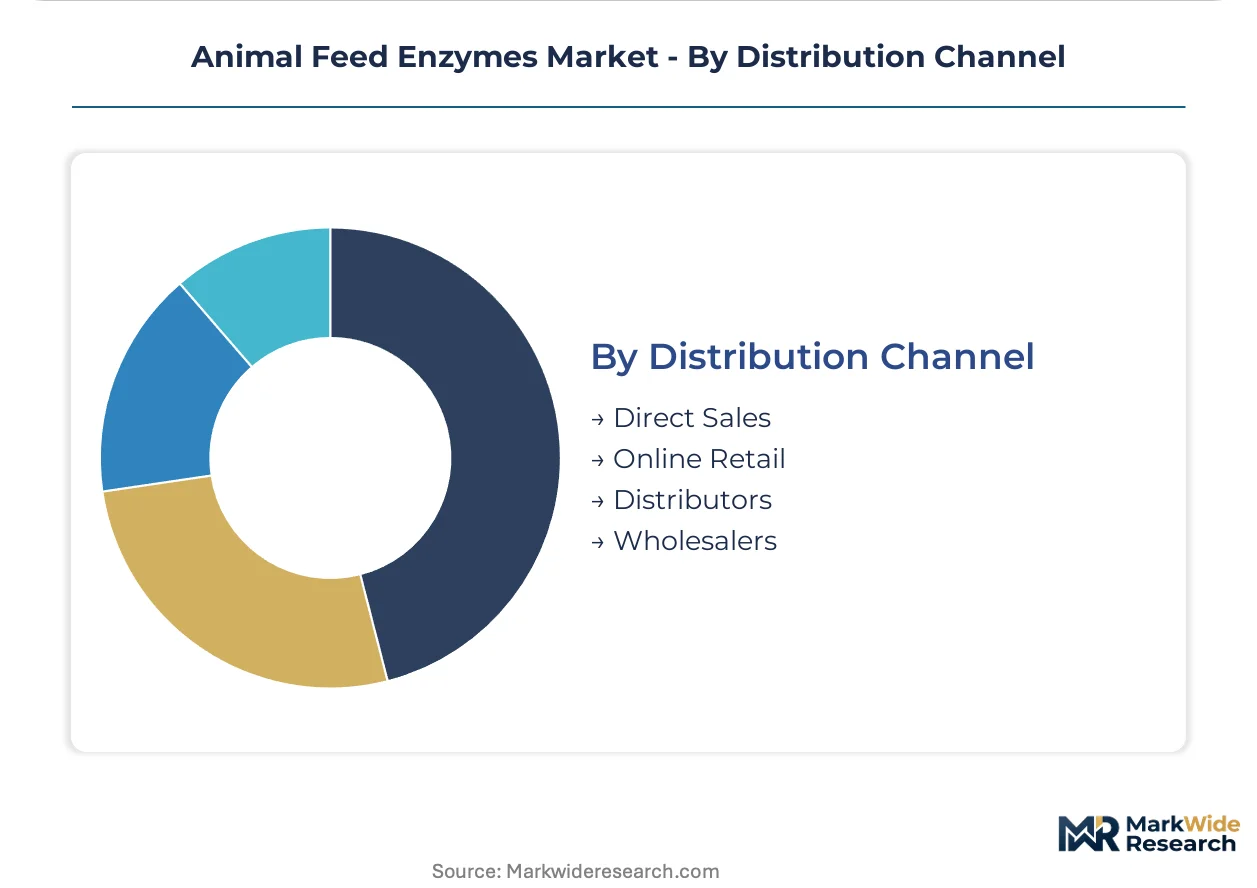
Distribution Channel:
Procurement patterns are shifting from commodity trading toward integrated nutrition partnerships with technical service bundling.
- Distributors:Regional compound feed ingredient specialists maintain inventory positions and formulation support capabilities across fragmented customer bases. North Carolina swine operations increasingly specify enzyme inclusion through distributor-managed nutrition programs.
- Direct Sales:Large-scale integrators contract directly with fermentation manufacturers for volume commitments and customized technical service. Cargill's backward integration into grain origination anchors direct channel strength.
- Online Retail:E-commerce platforms serve smaller livestock operations and specialty aquaculture producers with standardized enzyme products and rapid replenishment.
- Wholesalers:Bulk commodity handlers with limited technical capabilities, losing share to distributors with in-house enzymology expertise.
Distributors retain channel leadership, though direct sales are expanding most quickly as consolidation concentrates buyer power among large integrated operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for enzyme-supplemented feed concentrates are tightening as major producing regions face divergent regulatory pressures on phosphorus discharge. Brazil and the United States maintain surplus positions in poultry and swine feed formulations, while European compounders absorb higher compliance costs under nutrient management mandates.
United States
Poultry integrators in Maryland and Virginia now specify enzyme inclusion in contract grower specifications to meet EPA nutrient trading frameworks in Chesapeake Bay and Ohio River watersheds. USDA Conservation Reserve cost-share programs indirectly subsidize adoption by producers seeking phosphorus compliance credits. Iowa-based swine operations are retrofitting legacy premix equipment to handle hygroscopic enzyme granule characteristics.
Brazil
Integrated poultry and swine producers in Mato Grosso and Paraná states are deploying multi-enzyme programs to capture feed conversion efficiency gains and reduce phosphorus excretion. ANVISA governs feed additive registrations, though EU export standards for manure phosphorus limits drive domestic reformulation intensity. São Paulo corridor compound feed mills are scaling backward integration into grain origination to anchor enzyme program economics.
Germany
REACH nutrient management protocols and EU Green Deal phosphorus ceilings force compound feed manufacturers to reformulate with elevated phytase inclusion rates. EFSA parallel pathways for novel enzyme approvals operate faster than FDA GRAS timelines, attracting development-stage manufacturers to Hamburg and Frankfurt regulatory consulting clusters. Bavarian swine operations face the strictest manure nitrogen thresholds in the federal system.
China
Domestic enzyme demand concentrates in Shandong and Guangdong provinces where poultry integration density matches European intensity levels. NMPA and Ministry of Agriculture standards for feed additive safety create compliance thresholds favoring established fermentation manufacturers. Yangtze River Delta compound feed mills are piloting thermostable phytase variants to eliminate post-pelleting liquid application systems.
Indonesia
Shrimp and marine finfish operations in Sulawesi and Sumatra remain underpenetrated for protease-carbohydrate blends targeting plant protein meals. The country's national feed regulator enforces safety standards that enzyme suppliers must navigate with local distributor partnerships. Jakarta-based aquaculture nutrition service providers are bundling enzyme supply with formulation software to displace commodity trading houses.
Animal Feed Enzymes Market Vendor Landscape
On the supply side, the industry is consolidating around fermentation infrastructure holders with captive strain development capabilities. Three strategic archetypes dominate: integrated nutrition conglomerates with backward integration into grain origination, specialized enzyme engineering platforms with thermal stability IP, and regional fermentation specialists serving single-geography compound feed markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with project finance arrangements for large-scale bioreactor installations lowering entry barriers for mid-scale players.
Within the integrated nutrition tier, Cargill, Inc. and Archer Daniels Midland Co. exemplify the archetype of supply chain conglomerates leveraging captive grain origination networks to anchor enzyme distribution economics. Novonesis occupies a position representing consolidated fermentation infrastructure holders with cost leadership across European and Asian supply corridors. BASF SE sits within the specialized engineering tier, with company nomenclature indicating German corporate structure and thermal stability platform differentiation.
| Leading Market Players |
|---|
| Adisseo |
| Archer Daniels Midland Co. |
| Novonesis |
| Koninklijke DSM NV |
| IFF (Danisco Animal Nutrition) |
| BASF SE |
| Kemin Industries, Inc. |
| Elanco Animal Health Inc. |
| Cargill, Inc. |
| Others |
Supply Flow & Price Mechanics
Kalundborg fermentation corridor overcapacity in Denmark is compressing spot enzyme prices while forcing suppliers toward long-term offtake contracts. This utilization dynamic rewards compound feed manufacturers with procurement leverage against multi-year formula pricing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium thermostable grades, standard pelleting-stable tiers, and economy liquid-application variants. Price differentiation rests on EFSA registration status and volume scale commitments above 500 metric tons annually. Cost compression in standard phytase tiers is intensifying because Brazilian integrated operations are consolidating procurement around full-service nutrition partners. Mid-sized independent compounders in Iowa and North Carolina exhibit highest price sensitivity, while EU export-oriented integrators accept premium positioning for compliance documentation.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate supplier-buyer negotiations as working capital pressure mounts across fermentation infrastructure holders. Geographic supply concentration centers on Denmark, China, and the United States, with corn steep liquor and soybean meal culture media drawing from commodity grain markets. Single-source vulnerability from Novonesis and legacy Novozymes fermentation assets in Copenhagen-Kalundborg corridor threatens European compounder security of supply. Distribution runs through integrated nutrition partners bundling enzyme supply with formulation software, displacing commodity trading houses with limited technical capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal feed enzymes are entering cyclical recovery as EU Green Deal phosphorus mandates force reformulation intensity across compound feed manufacturing. Brazilian export compliance requirements and Chesapeake Bay nutrient trading frameworks provide synchronized demand pull.
For Market Incumbents: Entrench fermentation infrastructure advantage through captive strain development capabilities in Aspergillus niger and Trichoderma reesei platforms. Lock in multi-year supply agreements with Mato Grosso poultry integrators facing EU manure phosphorus limits. Prioritize thermostable phytase engineering to eliminate post-pelleting liquid application systems and defend against cell-free synthesis platform disruption. For New Entrants and Emerging Players: Indonesian aquaculture operations in Sulawesi and Sumatra represent the most penetrable entry point for protease-carbohydrate blends targeting fishmeal substitution in high-density shrimp systems. CRISPR-edited cellulase variants for ruminant fiber degradation offer white-space positioning ahead of commercial deployment. Pursue distributor-managed nutrition program partnerships rather than direct sales to bypass legacy premix equipment retrofit barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation infrastructure holders with captive regulatory affairs capabilities navigating EFSA parallel pathways. Long-term viability across the projection horizon favors specialized enzyme engineering platforms with thermal stability IP over commodity phytase manufacturers facing efficacy plateaus. Monitor FDA GRAS timeline compression signals as inflection indicator for novel enzyme commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Kalundborg corridor bioreactor installations lower unit costs for thermostable phytase variants. |
| Backward Integration | São Paulo compound feed mills anchor enzyme economics through captive grain origination control. |
| Regulatory Approval Pathway | EFSA parallel pathways attract development-stage manufacturers to Hamburg consulting clusters. |
| Joint Venture | Jakarta aquaculture nutrition providers bundle enzyme supply with formulation software displacement. |
| Technology Licensing | Cell-free synthesis platforms bypass capital-intensive bioreactor networks for specialty aquaculture premixes. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA novel food enzyme submissions, ANVISA feed additive registrations, and EU compound feed production statistics. Fermentation plant managers, regulatory affairs leads at enzyme manufacturers, procurement directors at Brazilian integrated poultry operations, and nutrition specification officers at Iowa swine integrators provided operational validation. Customs data for enzyme concentrate trade flows, SEC filings from listed nutrition conglomerates, and EPA nutrient trading verification protocols supplied secondary triangulation. Bottom-up volume modeling from species-specific inclusion rates converged with top-down market sizing from fermentation capacity utilization.
Forecast inputs span species application splits, thermal stability tier adoption curves, and regulatory enforcement intensity across EU member states. Segmentation dimensions include product type, species application, physical form, and distribution channel structure, with geographic regulatory cluster as cross-cutting variable. CAGRs derive from logistic adoption curve fitting against reformulation trigger points. Enzyme efficacy plateaus at 500 FTU/kg and cell-free synthesis platform maturation serve as industry-specific trajectory modifiers throughout the forecast period.
Macroeconomic conditions sit as an overlay; deviation in corn steep liquor pricing, soybean meal volatility, or Brazilian real exchange rates would shift the trajectory. Forecasts reflect documented assumptions around EU Green Deal enforcement timelines and FDA GRAS review cycle durations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
Feed Micronutrients Market