
 Agricultural Antibacterials Market | 2026-2036
Agricultural Antibacterials Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Antibacterials Market Outlook
ISO 17034 reference material certification is collapsing the supplier base for residue-compliant antibacterial formulations. Bayer AG leverages its veterinary pharmaceutical pipeline to sustain positions in livestock health across European dairy belts. Syngenta AG anchors its crop protection antibacterial portfolio through integrated seed-treatment distribution. BASF SE competes on fermentation-derived macrolide capacity at its Ludwigshafen complex.
Agricultural antibacterials comprise synthetic and semi-synthetic antimicrobial compounds formulated for prophylactic and therapeutic intervention in plant and animal agricultural systems, typically delivered at ppm-scale concentrations with defined withdrawal intervals for food safety compliance. The tetracycline class occupies mature volume positions in livestock feed additives, while macrolide demand accelerates in aquaculture systems requiring shorter residue-degradation profiles. Crop protection applications concentrate margin pools in high-value fruit and vegetable segments, whereas soil treatment formulations face substitution pressure from microbial biocontrol alternatives.
The FDA's Veterinary Feed Directive and the EU's MDR-aligned veterinary medicine framework constrain over-the-counter antibacterial deployment, forcing reformulation toward prescription-controlled delivery systems. China's NMPA and SAMR impose parallel GB standard residue ceilings that gate export-market access for meat and aquaculture producers. Stakeholders must monitor regulatory divergence between jurisdictions to determine manufacturing location and registration sequencing.
Market Dynamics
ISO 17034 certification requirements are collapsing the supplier base for residue-compliant antibacterial formulations, concentrating procurement among vertically integrated pharmaceutical manufacturers with captive reference material production.
Growth Catalysts
- Integrated poultry operations:Large-scale broiler and layer facilities in Brazil's Mato Grosso soy belt are consolidating feed-medication procurement under single-source veterinary contracts.
- F-Gas Regulation residue limits:The European Union's tightening withdrawal periods are accelerating demand for rapid-degradation macrolide formulations in dairy systems.
- Aquaculture macrolide uptake:Shorter residue-degradation profiles in fish farming are displacing tetracycline-class prophylaxis across Southeast Asian shrimp ponds.
Market Restraints
- Fermentation feedstock volatility:Macrolide production depends on corn steep liquor and soybean meal pricing, exposing BASF's Ludwigshafen complex to agricultural commodity swings.
- Supplier base concentration:Only three ISO 17034-certified reference material producers remain capable of supporting EU MDR-aligned veterinary medicine registration.
- Microbial biocontrol substitution:Bacillus-based soil treatments are capturing margin pools in high-value vegetable segments previously served by synthetic antibacterial drenches.
Strategic Opportunities
- Prescription-controlled delivery systems:The FDA's Veterinary Feed Directive mandate creates white space for smart-medicated feed technologies with embedded compliance tracking.
- Seed-treatment antibacterial convergence:Syngenta's integrated distribution networks enable co-formulation of antibacterials with fungicides in hybrid corn and soybean coatings.
- China GB standard alignment:NMPA and SAMR residue ceilings for export-bound aquaculture producers favor early-registration of rapid-clearance actives.
Industry Challenges
- Veterinary pharmacovigilance talent scarcity:Qualified professionals capable of managing FDA adverse event reporting and EU pharmacovigilance master files command premium compensation.
- Withdrawal period validation timelines:Residue depletion studies for new aquaculture formulations require 18-24 month regulatory review cycles before market authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Antibacterials Market |
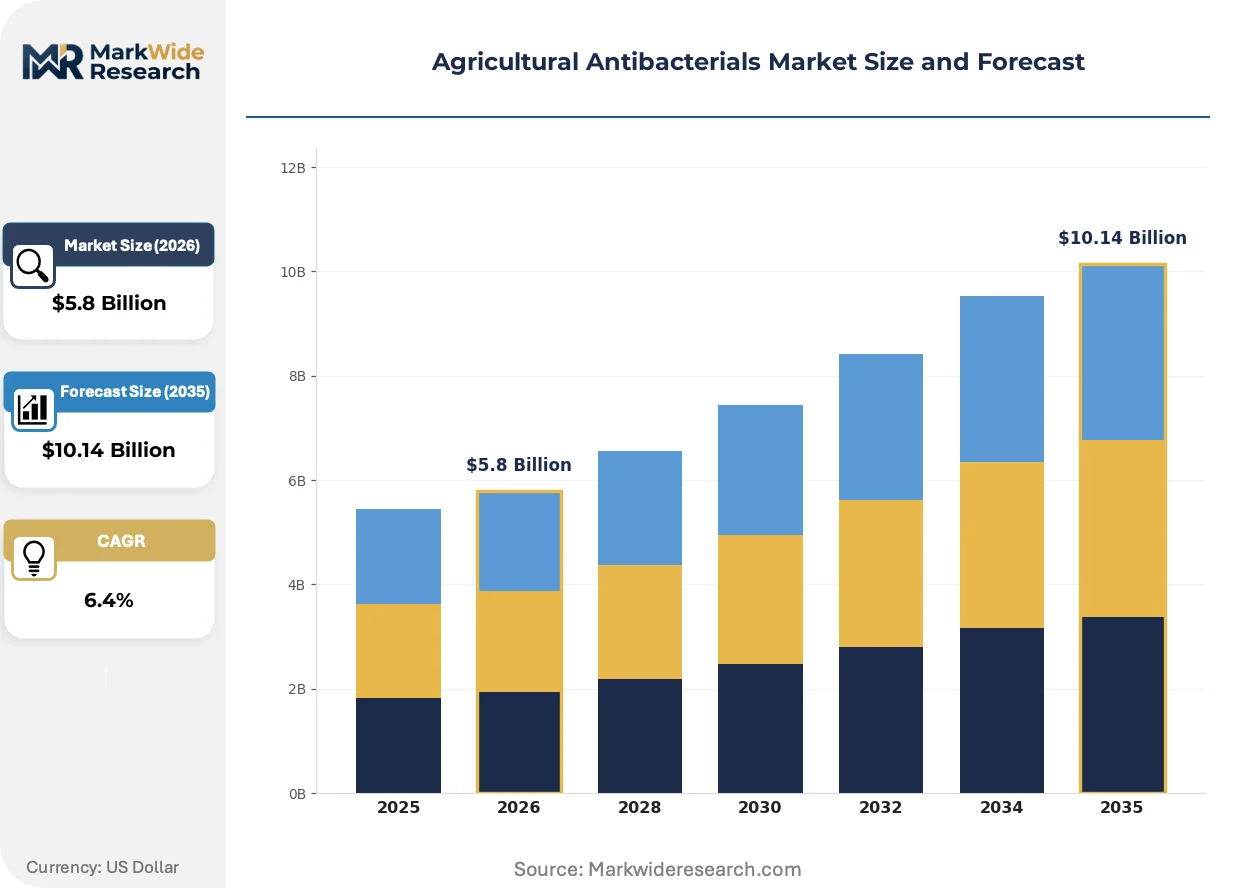
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tetracyclines, Penicillins, Macrolides, Aminoglycosides Application: Crop Protection, Livestock Health, Aquaculture, Soil Treatment End User: Farmers, Agricultural Cooperatives, Veterinary Clinics, Research Institutions Formulation: Granules, Liquid Solutions, Powders, Suspensions |
| Companies Covered | Bayer AG, Syngenta AG, Corteva Agriscience, BASF SE, Sumitomo Chemical Co., Ltd., FMC Corporation, Nufarm Limited, UPL, Albaugh LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Antibacterials Market Strategic Shifts
Precision-delivery technologies and regulatory compliance architectures are compressing formulation development cycles while fragmenting procurement authority across specialized veterinary service providers.
Nanosuspension technology for macrolide delivery is miniaturizing particle size distributions to sub-micron scales, enabling intramuscular depot formulations with extended release profiles. Integrated cattle feedlots in Australia's Queensland corridor are adopting these systems to reduce handling stress and labor requirements. The technology is miniaturizing dosing volumes and injection-site tissue reactions, compressing withdrawal intervals for export-compliant beef production.
The EU's F-Gas Regulation and aligned veterinary medicine reform are mandating environmental risk assessments for antibacterial metabolites in manure and wastewater. Pharmaceutical manufacturers must now submit fate-and-transport studies alongside efficacy data for new product registrations. Dairy operations in Germany's Lower Saxony region are responding by installing on-farm manure digestion systems to accelerate residue degradation before land application.
Consolidated procurement by veterinary service organizations is displacing direct manufacturer relationships among mid-sized livestock operations. These organizations negotiate volume-based formularies and manage compliance documentation on behalf of member farms. The model is most visible across southern Brazil's cattle corridors, where cooperatives now control antibacterial selection for over sixty percent of breeding stock.
Agricultural Antibacterials Market Segmentation
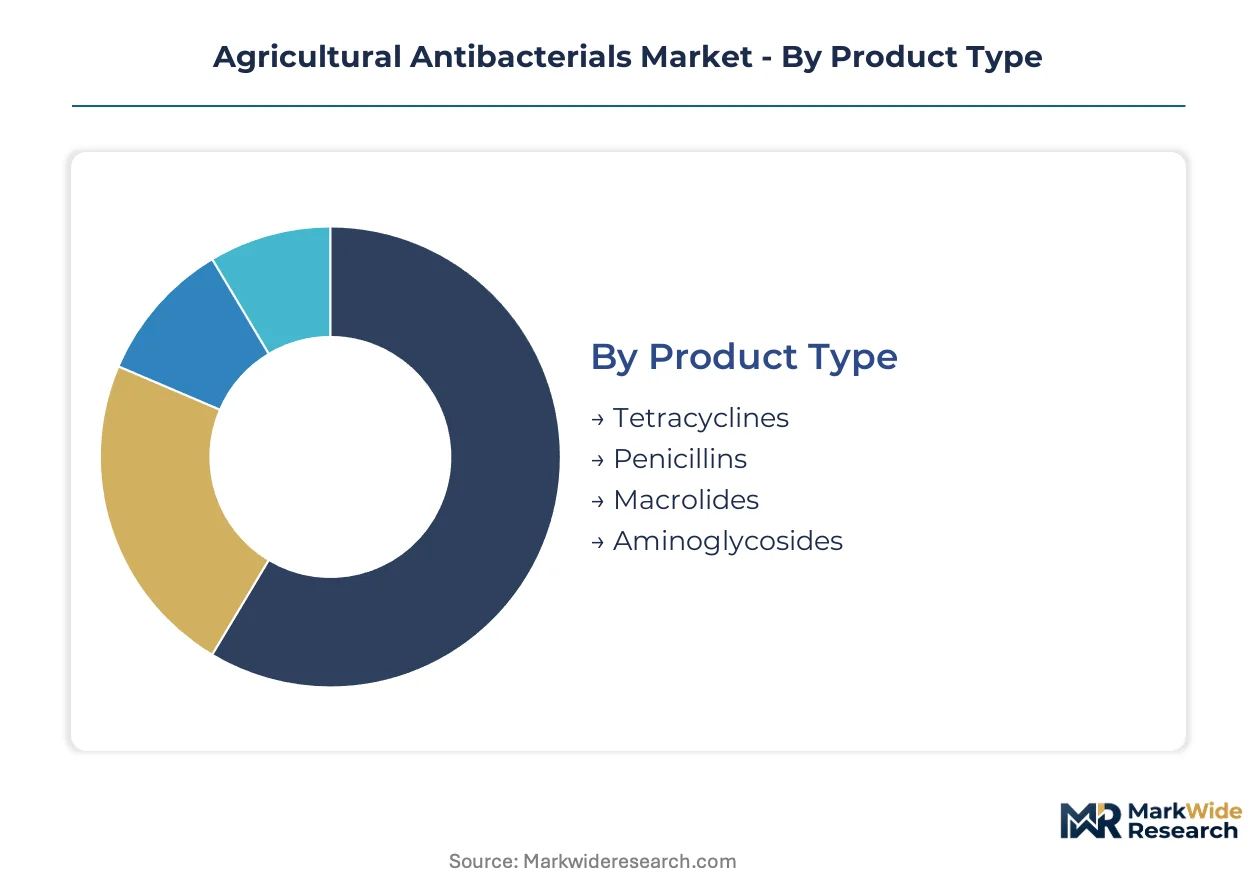
Segmentation in agricultural antibacterials reveals distinct procurement pathways shaped by regulatory compliance burdens and residue management requirements. Each dimension channels through specialized distribution networks that concentrate authority among vertically integrated service providers.
Product Type:
Tetracyclines and macrolides flow through veterinary prescription channels, while aminoglycosides concentrate in aquaculture supply chains and penicillins anchor dairy herd health programs.
- Tetracyclines:Broad-spectrum bacteriostatic agents formulated as feed-grade premixes for prophylactic livestock intervention. Demand concentrates in Brazil's Mato Grosso integrated poultry operations where cost-efficient prophylaxis at scale drives procurement consolidation under single-source veterinary contracts.
- Macrolides:Fermentation-derived antibiotics with rapid residue clearance profiles suited for export-market compliance. Australia's Queensland cattle feedlots are adopting nanosuspension depot formulations to compress withdrawal intervals for China-bound beef exports under NMPA residue ceilings.
- Penicillins:Beta-lactam compounds with established efficacy in mastitis treatment protocols across European dairy systems.
- Aminoglycosides:Bactericidal agents deployed in Southeast Asian shrimp aquaculture requiring short degradation timelines.
Tetracyclines dominate installed base volumes. Macrolides are where expansion concentrates as residue regulations tighten across export markets.
Application:
Cost tier differentiation separates commodity livestock prophylaxis from premium crop protection margins, with aquaculture occupying an intermediate position shaped by export certification requirements.
- Crop Protection:Foliar and soil-applied formulations targeting bacterial pathogens in high-value fruit and vegetable production. Spain's Almería greenhouse complexes drive demand for residue-compliant drenches serving EU supermarket chains with strict private standards.
- Livestock Health:Therapeutic and prophylactic systems for cattle, swine, and poultry operations. Germany's Lower Saxony dairy belt is installing on-farm manure digestion systems to accelerate antibacterial metabolite degradation before land application under F-Gas Regulation environmental risk assessments.
- Aquaculture:Water-soluble treatments for finfish and shellfish bacterial disease management.
- Soil Treatment:Pre-planting drenches facing substitution pressure from microbial biocontrol alternatives in premium vegetable segments.
Livestock Health commands the largest revenue pool. Aquaculture is climbing the fastest as Southeast Asian export producers upgrade residue management infrastructure.
End User:
Customer type determines compliance documentation intensity, with agricultural cooperatives consolidating procurement authority previously dispersed among individual farm operations.
- Farmers:Individual livestock and crop producers purchasing through veterinary service organizations or direct distributor relationships. Southern Brazil's cattle corridors have seen cooperatives displace direct manufacturer relationships for over sixty percent of breeding stock antibacterial selection.
- Agricultural Cooperatives:Member-owned organizations negotiating volume-based formularies and managing centralized compliance documentation. These entities now control antibacterial procurement across Brazil's Mato Grosso soy belt integrated poultry operations.
- Veterinary Clinics:Prescription-controlled delivery points for therapeutic interventions under FDA Veterinary Feed Directive mandates.
- Research Institutions:Reference material consumers supporting ISO 17034 certification requirements for residue-compliant formulation development.
Agricultural Cooperatives are gaining procurement share fastest. Farmers retain significant volume but with diminishing direct supplier relationships.
Formulation:
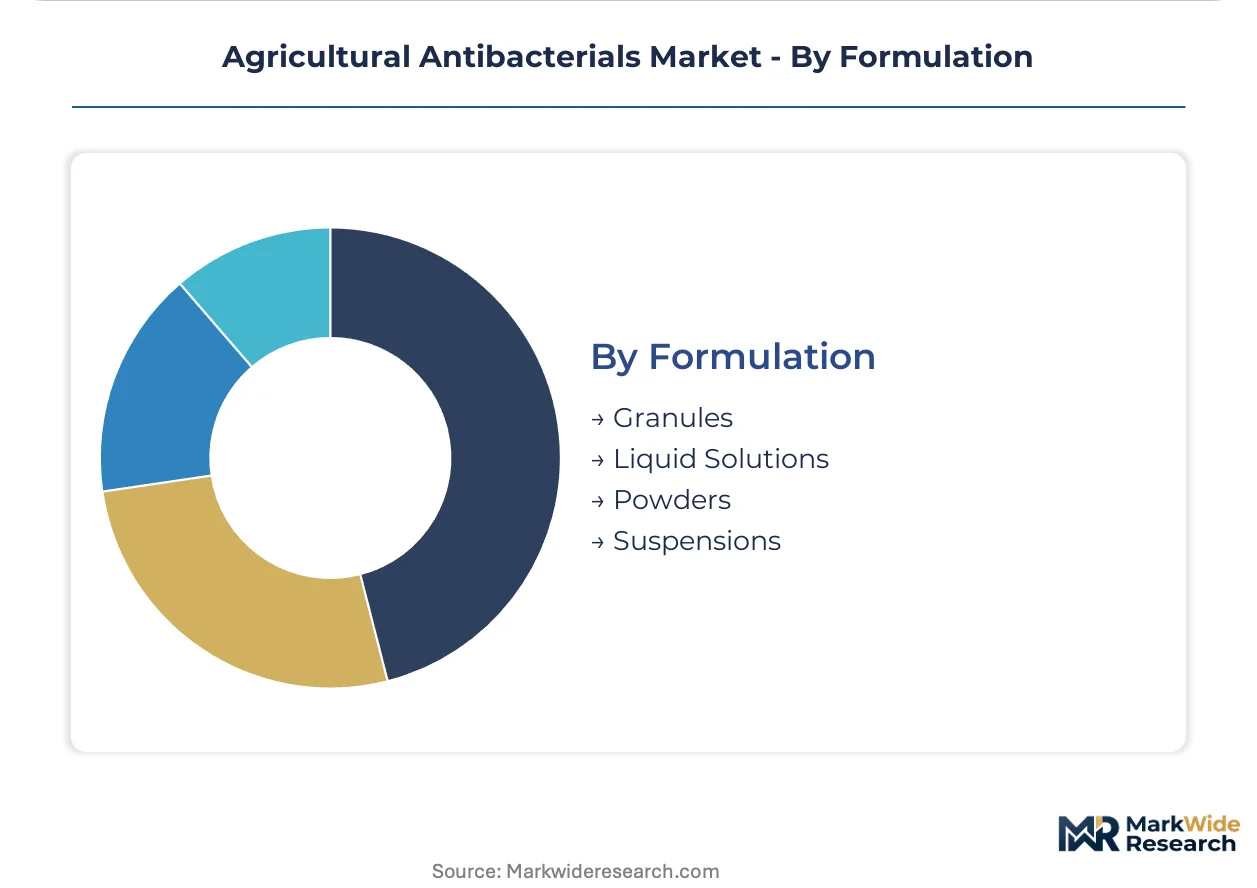
Volume scale separates mass-market feed premixes from precision-delivery suspensions, with liquid solutions capturing aquaculture applications and granules dominating soil treatment.
- Liquid Solutions:Water-soluble concentrates for drinking water medication and aquaculture bath treatments. Vietnam's Mekong Delta shrimp producers favor these formulations for rapid dispersion and dose adjustment flexibility under SAMR export compliance protocols.
- Suspensions:Injectable and oral preparations with extended release profiles enabled by nanosuspension particle size reduction. Australia's Queensland feedlots deploy intramuscular depot formulations to reduce handling stress and labor requirements.
- Granules:Dry-blended feed additives for uniform distribution in total mixed rations.
- Powders:Top-dress and premix formats for on-farm medication preparation.
Liquid Solutions lead aquaculture and poultry water medication. Suspensions are where formulation innovation concentrates for extended-release livestock applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's F-Gas Regulation and veterinary medicine reform are tightening residue limits and withdrawal periods, redirecting procurement toward rapid-clearance formulations. Brazil's Mato Grosso soy belt and southern cattle corridors are consolidating feed-medication contracts under single-source veterinary agreements. China's NMPA and SAMR impose GB standard residue ceilings that gate export-market access for meat and aquaculture producers.
United States
Integrated poultry operations in the Delmarva Peninsula and Georgia's broiler belt are consolidating procurement under veterinary service organizations. The FDA's Veterinary Feed Directive mandates prescription-controlled delivery systems, forcing reformulation toward smart-medicated feed technologies with embedded compliance tracking. Large-scale feedlots in the Texas Panhandle and Nebraska Sandhills are adopting these systems to reduce labor requirements and handling stress.
Germany
Dairy operations in Lower Saxony are installing on-farm manure digestion systems to accelerate antibacterial metabolite degradation before land application. The EMA's aligned veterinary medicine framework requires environmental risk assessments for antibacterial metabolites in manure and wastewater, mandating fate-and-transport studies alongside efficacy data. Pharmaceutical manufacturers with fermentation-derived macrolide capacity at Ludwigshafen supply residue-compliant formulations across the European dairy belt.
Brazil
Integrated poultry operations in Mato Grosso are consolidating feed-medication procurement under single-source veterinary contracts covering breeding stock and broiler production. ANVISA's tightening residue protocols for export-bound beef and poultry are accelerating demand for rapid-degradation macrolide formulations. Cooperatives across Rio Grande do Sul's cattle corridors now control antibacterial selection for over sixty percent of breeding stock, displacing direct manufacturer relationships.
China
Aquaculture producers in Guangdong and Fujian provinces are upgrading residue management infrastructure to meet NMPA and SAMR GB standard ceilings for export-bound shrimp and finfish. The dual carbon goals and MEE environmental enforcement are constraining fermentation feedstock availability for domestic macrolide production. Yangtze River Delta pharmaceutical manufacturers are prioritizing early registration of rapid-clearance actives to capture export-market share.
Australia
Cattle feedlots in Queensland are adopting nanosuspension depot formulations to compress withdrawal intervals for China-bound beef exports under NMPA residue ceilings. The TGA's alignment with international veterinary medicine standards is streamlining registration pathways for extended-release intramuscular preparations. Integrated operations across the Darling Downs are reducing handling stress and labor requirements through precision-delivery technologies.
Agricultural Antibacterials Market Competitive Environment
Player mix skews toward diversified agrochemical conglomerates with captive veterinary pharmaceutical pipelines. The supplier base concentrates among vertically integrated manufacturers with ISO 17034-certified reference material production and fermentation-derived macrolide capacity. Three strategic archetypes dominate: diversified life science conglomerates leveraging cross-divisional R&D, specialized crop protection companies with integrated seed-treatment distribution, and fermentation-focused chemical manufacturers with backward integration into agricultural feedstocks. Competitive moves center on prescription-controlled delivery system development and geographic expansion into Brazil's Mato Grosso soy belt and Southeast Asian aquaculture corridors.
Within the diversified life science tier, Bayer AG and BASF SE exemplify conglomerates with captive veterinary pharmaceutical pipelines and fermentation-derived macrolide manufacturing. Syngenta AG occupies a position among crop protection specialists leveraging integrated seed-treatment distribution networks for antibacterial co-formulation. These three anchors represent the concentration of procurement authority among manufacturers capable of supporting EU MDR-aligned veterinary medicine registration and China GB standard compliance.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta AG |
| Corteva Agriscience |
| BASF SE |
| Sumitomo Chemical Co., Ltd. |
| FMC Corporation |
| Nufarm Limited |
| UPL |
| Albaugh LLC |
| Others |
Value Chain & Pricing Dynamics
ISO 17034 certification gates both supply qualification and price differentiation simultaneously, concentrating procurement authority among three vertically integrated reference material producers while forcing tiered pricing spreads between certified and uncertified formulations. The collapse of compliant supplier alternatives has compressed buyer negotiating leverage across European and Chinese export markets.
Pricing Analysis
Certification level creates the primary spread, with ISO 17034-compliant formulations commanding premium positioning against standard-grade alternatives. Three-tier pricing structure separates EU MDR-aligned veterinary registrations from China GB-standard exports and domestic-only formulations. Pricing pressure stems from fermentation feedstock volatility in corn steep liquor and soybean meal markets. Agricultural cooperatives exhibit highest price sensitivity due to volume consolidation, while research institutions show lowest sensitivity given captive reference material requirements.
Supply Chain Analysis
Germany and China anchor fermentation-derived macrolide production, with India's API manufacturing feeding formulation finishing operations. Corn steep liquor, soybean meal, and specialized fermentation substrates constitute critical input dependencies. Single-source vulnerability concentrates in ISO 17034-certified reference material production, where only three producers remain qualified. Distribution runs through veterinary service organizations that have displaced direct manufacturer relationships across Brazil's integrated poultry and cattle operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where prescription-controlled delivery systems and smart-medicated feed technologies create interoperability moats between hardware, software, and pharmaceutical layers.
For Market Incumbents: Consolidate reference material production capacity through captive ISO 17034 certification investments to defend against supplier base collapse. Deepen channel control across Brazil's Mato Grosso veterinary service organizations before cooperative procurement authority fully crystallizes.
For New Entrants and Emerging Players: Lead with rapid-clearance macrolide formulations targeting China's NMPA-aligned aquaculture export corridors, where residue management infrastructure upgrades create white space. Deploy prescription-controlled delivery system partnerships as the primary go-to-market angle to bypass entrenched feed-premix relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation specialists possessing Ludwigshafen-scale macrolide capacity but lacking veterinary registration infrastructure. Long-term viability hinges on regulatory compliance architecture rather than molecule innovation alone. Watch for ANVISA residue protocol tightening as the signal for Brazilian market consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17034 Certification Investment | Captive reference material production collapses supplier alternatives and concentrates pricing power among three qualified manufacturers. |
| Prescription-Controlled Delivery System Development | FDA Veterinary Feed Directive compliance creates hardware-software-pharma interoperability moats for integrated platform providers. |
| Seed-Treatment Antibacterial Convergence | Syngenta's distribution networks enable co-formulation capture in hybrid corn and soybean coating applications. |
| Rapid-Clearance Macrolide Registration | Early NMPA and SAMR alignment secures export-market access for China-bound aquaculture and beef producers. |
| Veterinary Service Organization Partnership | Cooperative procurement consolidation across southern Brazil cattle corridors displaces direct manufacturer relationships. |
Study Parameters
Operator-level perspectives from veterinary pharmaceutical executives, regulatory affairs leads at fermentation manufacturers, agricultural cooperative procurement managers, and ISO 17034 certification specialists anchored the qualitative base. Secondary validation drew from FDA Veterinary Feed Directive filings, EMA veterinary medicine framework submissions, ANVISA residue protocol updates, and China NMPA GB standard registrations. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and formulation dimensions.
Sensitivity analysis tested forecast outputs against regulatory acceleration scenarios and fermentation feedstock price volatility assumptions across the projection horizon. Segmentation modeling incorporated product type, application, end user, and formulation dimensions alongside residue clearance profile tiers. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Industry-specific inputs included veterinary service organization procurement consolidation rates and ISO 17034 certification timeline assumptions.
Forecasts assume regulatory continuity in FDA Veterinary Feed Directive enforcement and EU F-Gas Regulation alignment; material policy shifts would require re-modeling. Specific risks include ANVISA residue protocol acceleration, China dual carbon goals constraining fermentation feedstock availability, and microbial biocontrol substitution exceeding baseline assumptions. Recalibration cycles align with material shifts in regulatory enforcement intensity and cooperative procurement authority consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market