
 Colombia Agriculture Market | 2026-2036
Colombia Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Agriculture Market Insights
Commodity trading margins is fragmenting between traditional bulk exports and value-added processed agricultural goods. Daabon Organic S.A.S. leverages its organic certification pipeline to command premium positioning in European channels. Cargill, Incorporated anchors its Colombian operations through extensive grain origination networks in the Orinoquia region. Olam Group Limited differentiates via integrated processing facilities that reduce post-harvest loss rates.
Colombia agriculture encompasses crop cultivation, livestock management, and agro-industrial processing across altitudinal zones from sea level to three thousand meters, with coffee arabica requiring specific temperature bands between eighteen and twenty-one degrees Celsius for optimal bean development. The sector supplies domestic food security programs, international commodity markets, and specialized ingredient channels for global food manufacturers. Coffee and fruits capture the highest margin pools within product type segments due to geographic indication protections and established export infrastructure. Food processing dominates end use industry demand as multinational buyers seek traceable supply chains for chocolate, juice concentrate, and soluble coffee production. Cooperative societies within distribution channels sustain farmer bargaining power against volatile spot market pricing.
ICA, Colombia's national agricultural and fisheries institute, enforces phytosanitary protocols that determine export eligibility for live plants and fresh produce shipments. Banco Agrario extends subsidized credit lines conditioned on compliance with sustainability criteria and formal land titling requirements. The EU Green Deal's deforestation-free regulation and REACH-aligned residue standards shape market access terms for Colombian exporters serving European buyers. Stakeholders must monitor how pending domestic land restitution rulings and carbon credit verification methodologies reshape farm-level investment incentives and consolidation patterns.
Market Dynamics
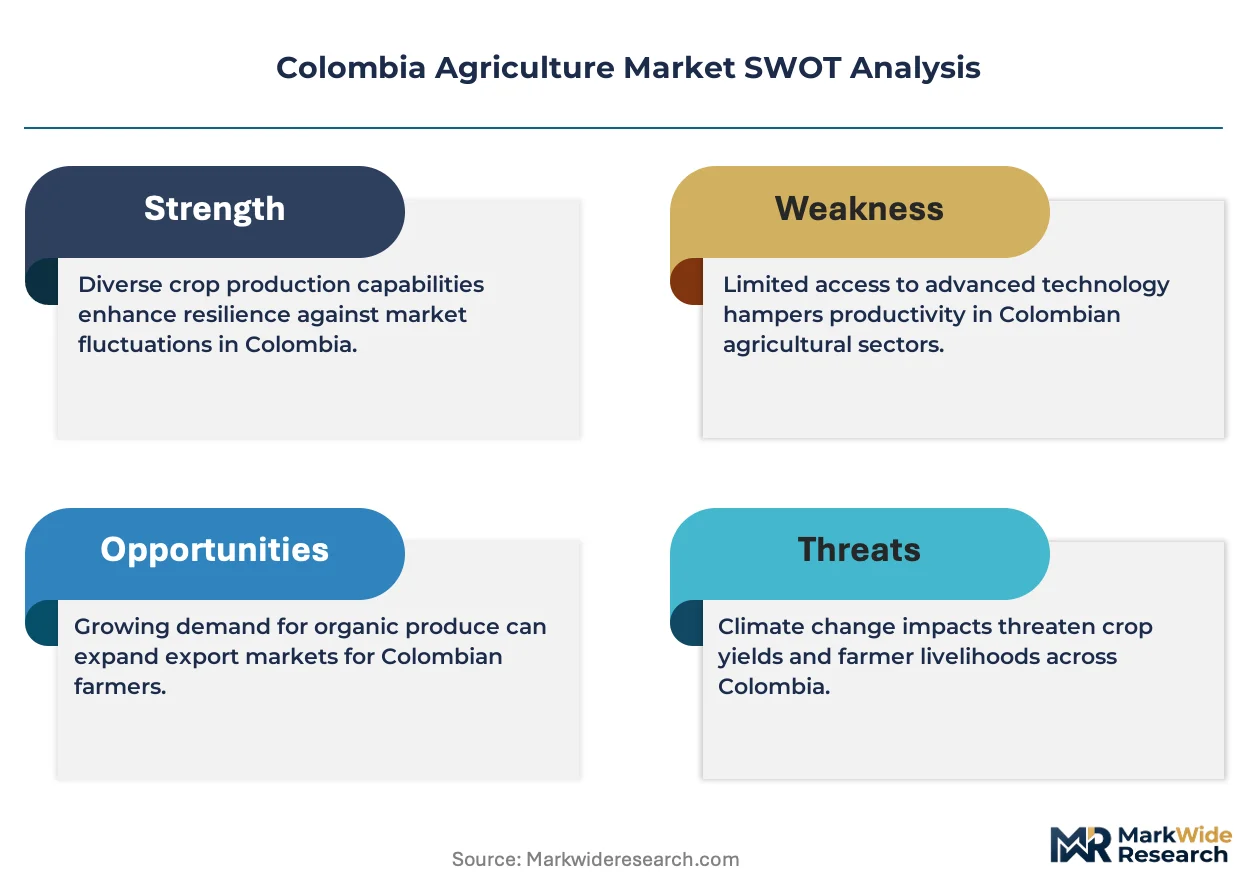
Traceability mandates from the EU Green Deal's deforestation-free regulation are forcing Colombian exporters to restructure farm-level documentation systems and satellite verification protocols.
Growth Catalysts
- Organic certification frameworks:ICA's tightening residue standards unlock premium channel access for Eje Cafetero coffee cooperatives supplying soluble coffee manufacturers.
- Altitudinal diversification:Valle del Cauca's three-thousand-meter elevation range enables year-round tropical fruit production for juice concentrate processors.
- Food processing concentration:Multinational chocolate and beverage makers are consolidating procurement through traceable supply chain partnerships.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings compress margins for Orinoquia grain farmers dependent on imported agrochemicals.
- Land titling fragmentation:Pending domestic restitution rulings create tenure uncertainty that deters long-term orchard investments in conflict-affected zones.
- Phytosanitary compliance friction:ICA's live plant export protocols impose inspection bottlenecks that delay fresh produce shipments to European buyers.
Strategic Opportunities
- Carbon credit verification:Emerging methodologies for agricultural carbon sequestration could unlock new revenue streams for coffee and cacao growers.
- Agro-industrial clustering:Integrated processing facilities in the Eje Cafetero reduce post-harvest losses for specialty arabica destined for single-origin markets.
- Cooperative credit expansion:Banco Agrario's sustainability-conditioned lending lines incentivize formalization among smallholder livestock managers.
Industry Challenges
- Digital traceability integration:Farm-level adoption of satellite monitoring and blockchain documentation requires technical training that extension services currently lack.
- Certification timeline compression:EU REACH-aligned residue testing and organic conversion periods create multi-year gaps before premium pricing activates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Agriculture Market |
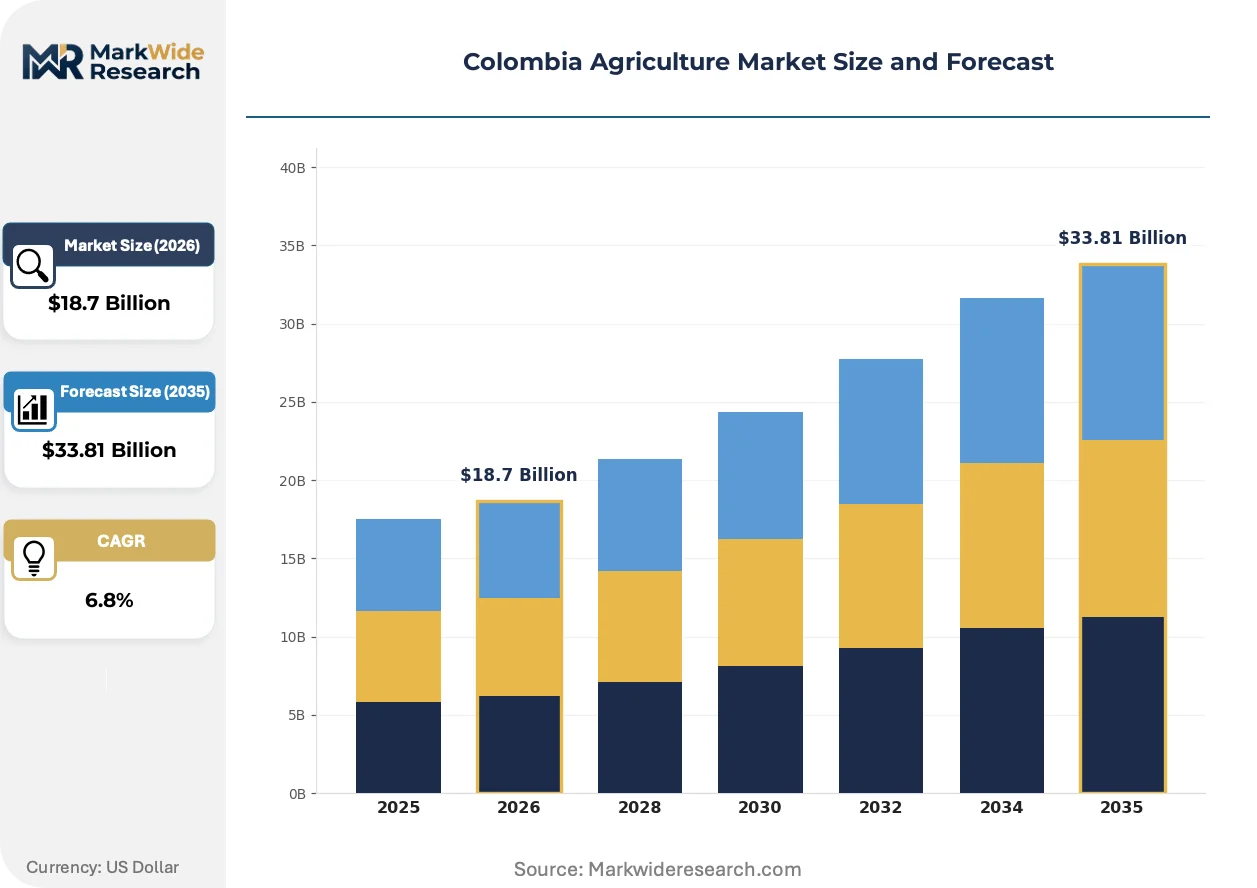
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Vegetables, Fruits, Coffee End Use Industry: Food Processing, Feed Production, Export, Retail Distribution Channel: Direct Sales, Wholesalers, Cooperative Societies, Online Packaging Type: Bags, Cartons, Bulk, Others |
| Companies Covered | Olam Group Limited, Oleoflores S.A., Grupo Nutresa S.A., Ecopetrol, Daabon Organic S.A.S., Cargill, Incorporated, Federación Nacional de Cafeteros de Colombia, Banco Agrario, Louis Dreyfus Company B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Agriculture Market Trends and Innovations
Digital verification systems and climate-adaptive cultivation methods are restructuring how Colombian agricultural output qualifies for protected designation channels.
Precision agriculture using drone-mounted multispectral sensors is migrating from experimental stations to commercial coffee estates. Medium-scale arabica producers in Quindío and Risaralda are deploying these systems to optimize fertilizer application rates. The technology is migrating from yield monitoring tools to integrated farm management platforms that satisfy EU buyer traceability requirements.
EU Green Deal deforestation-free regulations now mandate geolocation proof for all agricultural commodities entering European markets. Colombian exporters must demonstrate that production plots existed before December 2020 through satellite imagery archives. Coffee and cacao supply chains face the steepest compliance curves as these sectors lack legacy traceability infrastructure compared to palm oil.
Buyer consolidation among multinational food manufacturers is compressing supplier qualification cycles. Chocolate and juice concentrate processors now require simultaneous organic, fair trade, and carbon-neutral certifications before contract negotiation. This pattern concentrates procurement volumes through established cooperative societies with existing certification pipelines, marginalizing independent smallholders in Cauca and Nariño.
Colombia Agriculture Market Segmentation
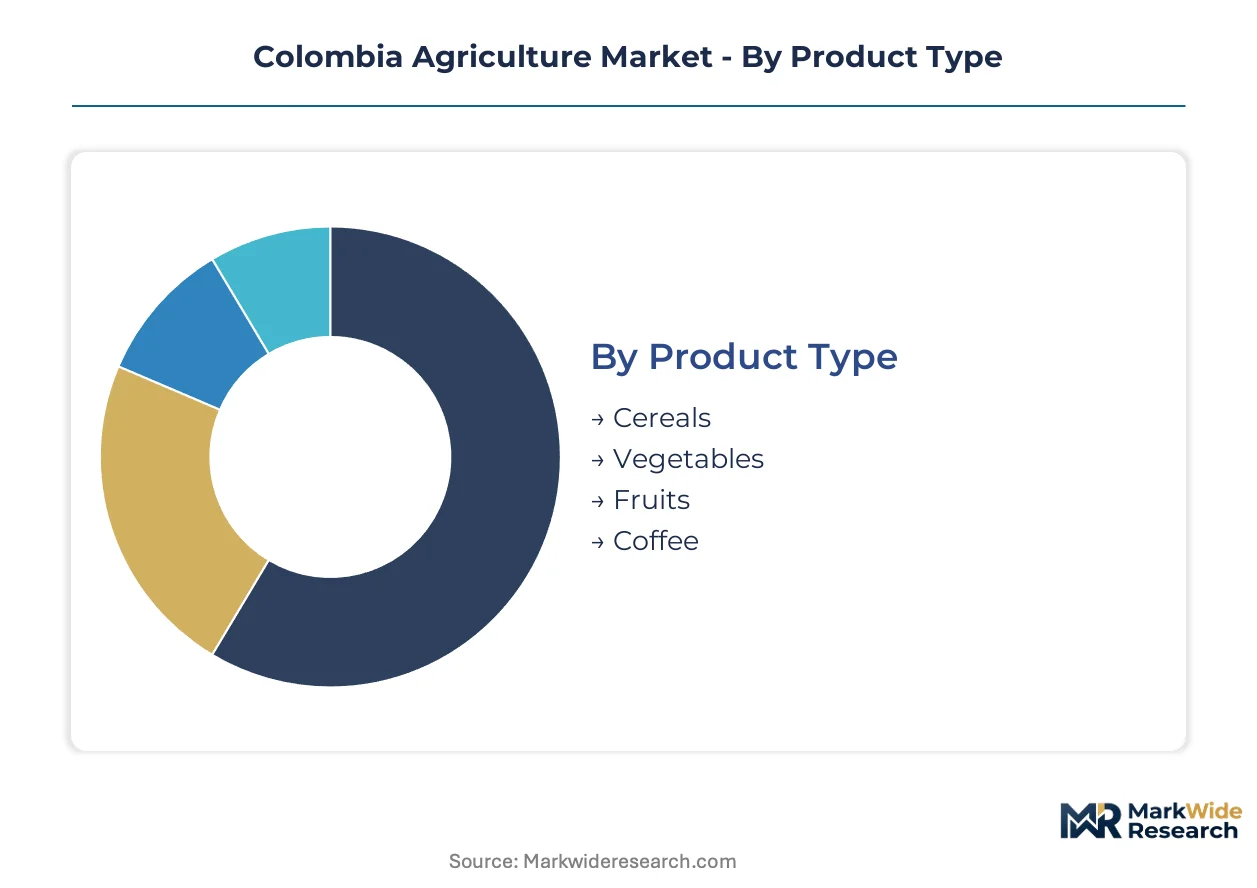
Segmentation in Colombian agriculture reveals how altitude, certification requirements, and buyer consolidation reshape revenue pools across product categories and channel structures. Cooperatives and multinational processors now dictate terms based on traceability infrastructure rather than spot market leverage.
Product Type:
Mature commodity categories dominate export tonnage while emerging specialty segments capture expanding premium margins.
- Coffee:Arabica cultivation concentrates in Eje Cafetero's 1,200-2,000 meter elevation band where temperature differentials produce the acidity profiles soluble coffee manufacturers require. ICA's tightening residue standards and EU Green Deal geolocation mandates are consolidating procurement through cooperative societies with existing certification pipelines.
- Fruits:Year-round tropical production across Valle del Cauca's altitudinal gradient supplies juice concentrate processors with mango, passion fruit, and pineapple harvests. Demand concentrates among multinational beverage makers requiring simultaneous organic and carbon-neutral credentials before contract negotiation.
- Cereals:Maize and rice cultivation in Orinoquia's Llanos plains serves domestic food security programs and regional feed markets.
- Vegetables:Potato and onion production clusters in Boyacá and Cundinamarca highlands for Bogotá wholesale markets.
Coffee handles the majority of throughput; fruits is the fastest mover on share.
End Use Industry:
Cost tier stratification separates commodity bulk handlers from traceability-invested premium channel suppliers.
- Food Processing:Chocolate, juice concentrate, and soluble coffee manufacturers consolidate procurement through multi-certification partnerships. Daabon Organic's European channel positioning demonstrates how organic pipeline investments command contract premiums.
- Export:EU and North American buyers now mandate satellite-verified geolocation proof through ICA phytosanitary protocols.
- Feed Production:Orinoquia grain origination networks supply poultry and livestock operations with maize and soybean meal.
- Retail:Domestic supermarket chains source packaged arabica and processed tropical products for urban consumption.
Food Processing commands the largest procurement volumes; Export is expanding most quickly as traceability infrastructure matures.
Distribution Channel:
Supply concentration favors intermediaries with capital to absorb certification timeline compression and digital verification costs.
- Cooperative Societies:Federación Nacional de Cafeteros and regional fruit cooperatives aggregate smallholder output for multinational buyer qualification. These entities sustain farmer bargaining power against volatile spot pricing through collective certification investments.
- Direct Sales:Large estates in Quindío and Risaralda bypass intermediaries for single-origin specialty contracts.
- Wholesalers:Bogotá and Medellín-based distributors handle domestic cereal and vegetable throughput.
- Online:Emerging platforms connect certified smallholders directly to European specialty roasters.
Cooperative Societies handle the majority of throughput; Online is gaining share fastest as blockchain documentation tools proliferate.
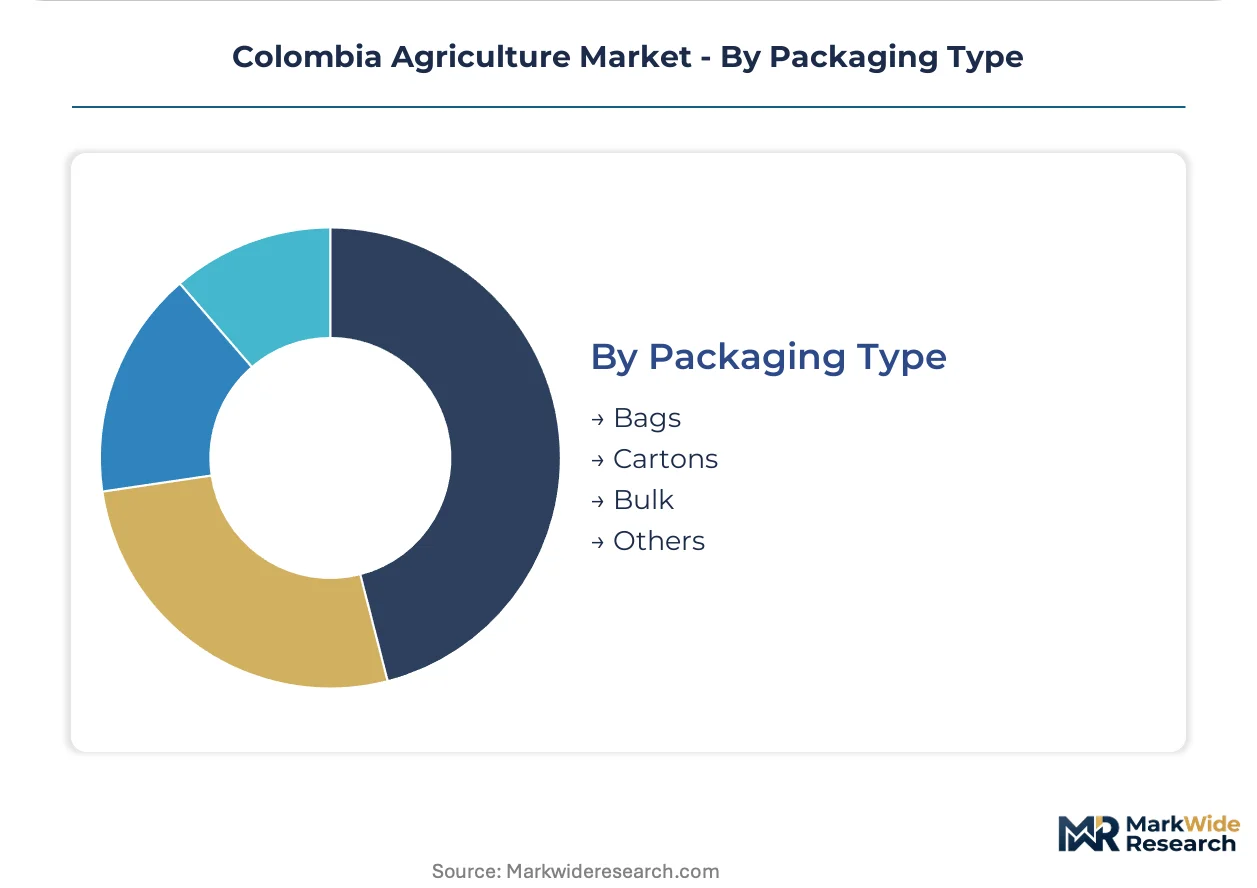
Packaging Type:
Volume scale determines packaging selection, with bulk formats dominating commodity flows and unitized packaging serving premium differentiation.
- Bulk:Grain and green coffee shipments to processing facilities minimize handling costs.
- Bags:Jute and polypropylene sacks protect arabica bean integrity during ocean freight.
- Cartons:Retail-ready formats for processed juice concentrates and chocolate products.
- Others:Modified atmosphere packaging for fresh tropical fruit air shipments.
Bulk handles the majority of throughput; Cartons are climbing the fastest as processed product exports expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombian agricultural output clusters across distinct altitudinal and climatic zones that shape crop specialization and export competitiveness. Eje Cafetero, Valle del Cauca, and Orinoquia concentrate the bulk of certified production and processing infrastructure.
Eje Cafetero
Arabica coffee cultivation dominates Quindío, Risaralda, and Caldas departments between 1,200-2,000 meters elevation. ICA's tightening residue standards and EU Green Deal geolocation mandates are consolidating procurement through Federación Nacional de Cafeteros cooperatives with established organic certification pipelines. Precision agriculture using drone-mounted multispectral sensors is migrating from experimental stations to commercial estates in Armenia and Pereira.
Valle del Cauca
Year-round tropical fruit production supplies juice concentrate processors with mango, passion fruit, and pineapple harvests across a three-thousand-meter elevation gradient. Banco Agrario extends subsidized credit lines conditioned on sustainability criteria and formal land titling requirements. Palmira and Cali anchor agro-industrial processing clusters where integrated facilities reduce post-harvest losses for specialty markets.
Orinoquia
Maize and rice cultivation in the Llanos plains serves domestic food security programs and regional feed markets. Fertilizer and fuel price swings compress margins for grain farmers dependent on imported agrochemicals. Villavicencio and Yopal host origination networks that Cargill leverages for extensive grain collection and distribution infrastructure.
Cauca and Nariño
Conflict-affected southern departments face tenure uncertainty from pending land restitution rulings that deter long-term orchard investments. Buyer consolidation among multinational chocolate makers concentrates procurement volumes through established cooperative societies, marginalizing independent smallholders lacking simultaneous organic, fair trade, and carbon-neutral certifications. Popayán and Pasto serve as logistics nodes for specialty cacao destined for European protected designation channels.
Boyacá and Cundinamarca
Potato and onion production clusters in highland plateaus for Bogotá wholesale markets. Domestic supermarket chains source packaged arabica and processed tropical products for urban consumption. Tunja and Zipaquirá maintain traditional wholesale distribution channels despite emerging online platforms connecting certified smallholders directly to specialty buyers.
Colombia Agriculture Market Competitive Landscape
Vertically integrated agro-industrial conglomerates and cooperative federations split the market between scale-driven commodity handling and premium-channel specialty positioning. Three archetypes dominate: multinational traders with origination networks, domestic organic specialists with European certification pipelines, and cooperative societies sustaining farmer bargaining power. Competitive moves concentrate on strategic partnerships for traceability infrastructure and portfolio diversification into carbon credit verification methodologies.
Within the organic certification tier, Daabon Organic S.A.S. exemplifies premium-channel positioning through European market access. Among multinational traders, Cargill, Incorporated and Olam Group Limited occupy positions anchored in grain origination and integrated processing facilities respectively. Federación Nacional de Cafeteros de Colombia represents the cooperative archetype that aggregates smallholder output for multinational buyer qualification.
| Leading Market Players |
|---|
| Olam Group Limited |
| Oleoflores S.A. |
| Grupo Nutresa S.A. |
| Ecopetrol |
| Daabon Organic S.A.S. |
| Cargill, Incorporated |
| Federación Nacional de Cafeteros de Colombia |
| Banco Agrario |
| Louis Dreyfus Company B.V. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Orinoquia grain origination infrastructure drives supplier consolidation toward cooperative aggregators while simultaneously compressing spot market pricing power for independent farmers. Eje Cafetero coffee processors leverage this utilization gap to enforce longer payment terms and volume commitments from upstream suppliers.
Pricing Analysis
After-sales service revenue from technical assistance and extended storage contracts drives lifetime value for integrated agro-industrial operators. Three-tier pricing structure across premium certified, standard commercial, and economy bulk levels stratifies Colombian agricultural output. Price differentiation rests on organic certification grade and EU Green Deal traceability compliance. Pricing pressure stems from fertilizer import cost volatility squeezing Orinoquia grain margins. Smallholder cooperatives exhibit highest price sensitivity due to working capital constraints, while multinational food processors demonstrate lowest sensitivity given their contract-based procurement models.
Supply Chain Analysis
Supplier-financing facilities through Banco Agrario's sustainability-conditioned credit lines extend payment terms for cooperative societies aggregating smallholder output. Geographic supply concentration centers on Colombia's Eje Cafetero, Valle del Cauca, and Orinoquia sub-regions. Raw material dependencies draw from imported urea, phosphate fertilizers, and palm oil-derived agrochemicals. Supply chain risk hinges on ICA phytosanitary inspection bottlenecks creating single-point delays for fresh produce exports. Distribution runs through Federación Nacional de Cafeteros cooperatives and multinational processor direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombian agriculture presents fragmentation opportunity as EU Green Deal traceability mandates splinter procurement qualifications across multiple certification tiers. Buyer consolidation among chocolate and juice concentrate manufacturers creates niche entry points for specialized organic operators.
For Market Incumbents: Entrench certification pipeline advantages through backward integration into satellite verification infrastructure and blockchain documentation systems. Cargill's Orinoquia grain origination networks demonstrate how captive collection infrastructure defends against spot market volatility. Prioritize cooperative partnership deepening to maintain volume access as ICA tightens residue standards.
For New Entrants and Emerging Players: Cauca and Nariño's underpenetrated specialty cacao corridors offer white-space access for carbon credit-verified operations serving European protected designation channels. Target conflict-affected zones where pending land restitution creates temporary supply gaps. Pursue direct-to-specialty-roaster online platforms as the primary go-to-market angle, bypassing cooperative intermediaries.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated processing facilities as EU geolocation mandates require satellite infrastructure deployment. Five-to-ten year viability favors operators with existing organic certification pipelines and cooperative society relationships. Acquisition target archetype: mid-scale arabica estates with precision agriculture adoption and direct export licensing. Monitor ICA protocol harmonization with EU REACH standards as the key inflection signal for certification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Satellite Verification | EU Green Deal geolocation mandates require farm-level imagery archives for market access. |
| Cooperative Certification Pipeline Expansion | Federación Nacional de Cafeteros aggregation sustains smallholder bargaining power against multinational buyers. |
| Carbon Credit Methodology Development | Emerging verification standards unlock new revenue streams for coffee and cacao growers. |
| Precision Agriculture Platform Deployment | Drone-mounted multispectral sensors optimize fertilizer application for soluble coffee manufacturers. |
| Direct-to-Roaster Online Channel Launch | Blockchain documentation tools enable certified smallholders to bypass traditional cooperative intermediaries. |
Research Methodology
Cross-validation between primary interviews with agricultural cooperative managers and secondary customs export data anchors the qualitative findings. Conversations with ICA regulatory officers, Banco Agrario lending specialists, multinational food processor procurement leads, and Federación Nacional de Cafeteros technical directors informed supply chain dynamics. Secondary sources include ICA phytosanitary protocol filings, EU Green Deal regulatory texts, Banco Agrario sustainability lending disclosures, and Colombian customs agricultural export statistics. Bottom-up farm-level production estimates and top-down sectoral GDP allocations triangulate market sizing.
Calibration against historical production volatility and input cost shocks shapes the projection framework. Segmentation dimensions modeled include product type, end-use industry, distribution channel, and packaging format across the analysis window. CAGRs derive from trend extrapolation of certified acreage expansion, cooperative membership growth, and multinational buyer contract volumes. Forecast inputs incorporate fertilizer import price trajectories and EU regulatory compliance timeline assumptions.
Practitioners should monitor ICA-EU protocol harmonization progress and carbon credit verification standard adoption for early signals. Forecasts reflect assumptions regarding sustained EU market access and cooperative aggregation stability. Macroeconomic deviation in fertilizer import costs, regulatory restriction tightening, or technological disruption in precision agriculture would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Feed Grade Oils Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Europe Poultry Feed Market