
 South America Insecticide Market | 2026-2036
South America Insecticide Market Size, Share, and Industry Trends Forecast 2026-2036
South America Insecticide Market Insights
Pest control operators is redrawing procurement patterns across South America as farmer cooperatives scale contract spraying services. Syngenta Group anchors its position through deep distribution networks in Brazil's soybean belt. FMC Corporation differentiates via biological insecticide pipelines targeting resistance-prone pest complexes. BASF SE competes on formulation innovation for liquid concentrates suited to aerial application.
South America insecticides comprise synthetic and biological active ingredients formulated to disrupt arthropod nervous systems, growth cycles, or feeding behaviors, typically delivered as emulsifiable concentrates, wettable powders, or granules with specified lethal concentration thresholds. Neonicotinoid registrations face structural headwinds amid pollinator toxicity reviews, while biological insecticides derived from Bacillus thuringiensis and botanical extracts capture expanding share in organic-certified operations. Pyrethroid demand persists in public health vector control programs, though resistance monitoring constrains blanket deployment strategies.
ANVISA governs human toxicology assessments, Brazil's Ministry of Agriculture sets residue limits, and Argentina's SENASA administers import equivalency for formulated products. Regulatory divergence between Mercosur harmonization goals and national re-registration requirements complicates multi-country product portfolios. Stakeholders must monitor pending biocide reclassifications and state-level buffer zone mandates that could restrict application windows in high-density cultivation zones.
Market Dynamics
Integrated pest management protocols are compressing blanket spraying cycles across Brazil's soybean belt, forcing suppliers to reconfigure formulation portfolios around biological-synthetic hybrid protocols that satisfy cooperative procurement committees.
Growth Catalysts
- ANVISA Fast-Track Registration:Brazil's streamlined toxicology review for biological actives is accelerating market entry for Bacillus thuringiensis formulations targeting fall armyworm resistance.
- Argentina's Corn Belt Intensification:Double-cropping expansion in Buenos Aires and Córdoba provinces is generating recurring demand for soil-applied neonicotinoid alternatives.
- Drone Application Infrastructure:Aerial spraying cooperatives in Mato Grosso are adopting ultra-low-volume liquid concentrates, creating pull for formulation innovations suited to unmanned platforms.
Market Restraints
- Active Ingredient Import Concentration:China supplies over seventy percent of technical-grade pyrethroids and neonicotinoids, exposing formulators to shipping cost volatility and currency fluctuation.
- Buffer Zone Mandates:São Paulo state's expanded no-spray corridors around water bodies and urban perimeters are mechanically reducing treatable hectarage per application cycle.
- Resistance Management Complexity:Helicoverpa armigera and Spodoptera frugiperda populations across the Cerrado exhibit documented metabolic resistance to multiple chemical classes, complicating rotation protocols.
Strategic Opportunities
- Paraguay's Unpenetrated Soybean Frontier:Eastern Paraguay's expanding cultivation belt lacks established distribution infrastructure, creating first-mover advantage for direct-to-cooperative supply models.
- Organic Certification Premium:Brazil's MAPA organic seal requirements for export-oriented operations are generating price premiums for botanical insecticide formulations derived from azadirachtin and pyrethrin sources.
- Digital Prescription Platforms:Smartphone-based pest identification and dosage recommendation tools are enabling precision application services that bundle biological and synthetic actives based on real-time field scouting.
Industry Challenges
- Field Agronomist Shortage:Brazil's agricultural extension services face capacity constraints in training sufficient personnel to diagnose resistance patterns and calibrate IPM protocols across fragmented landholdings.
- Re-Registration Data Requirements:ANVISA's demand for chronic toxicity studies and environmental fate modeling is extending compliance timelines and elevating dossier preparation costs for legacy active ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Insecticide Market |
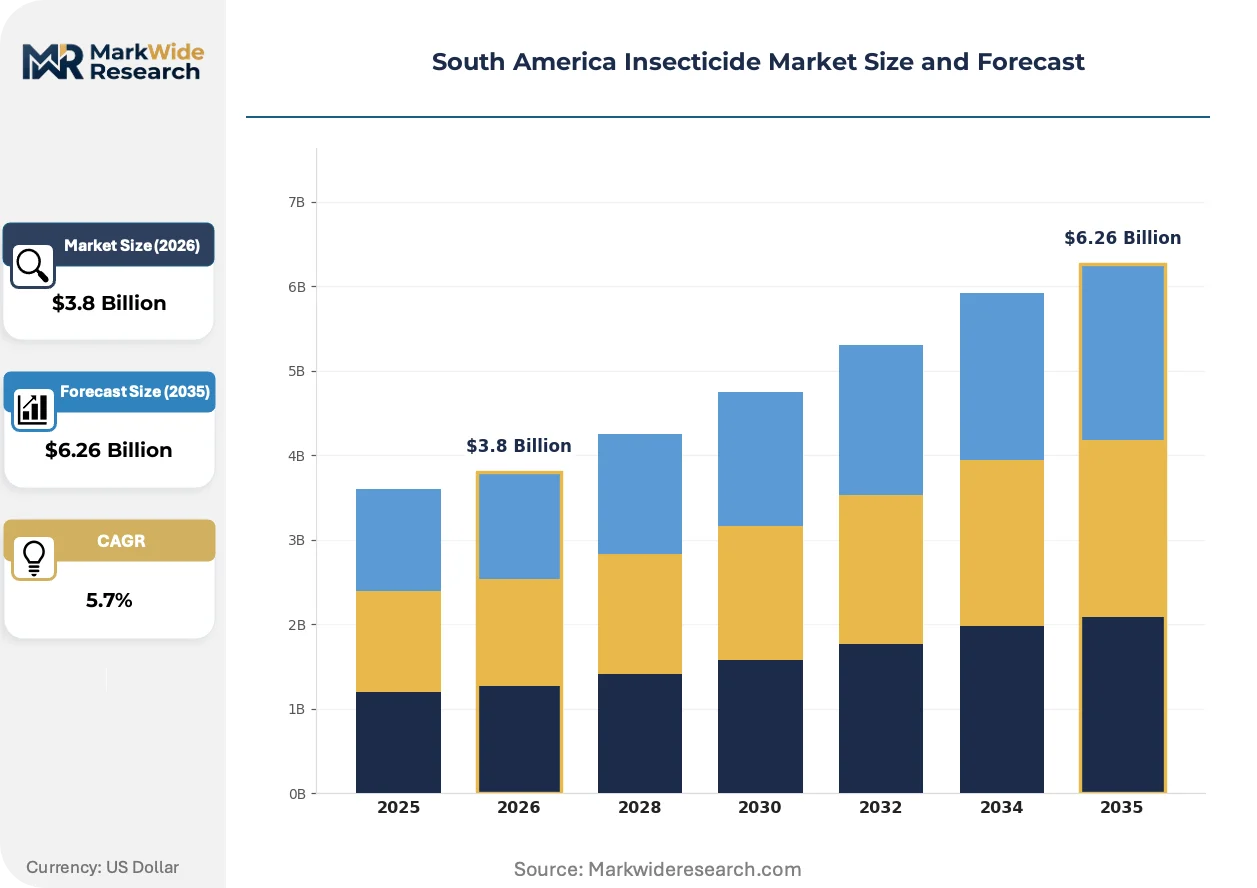
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
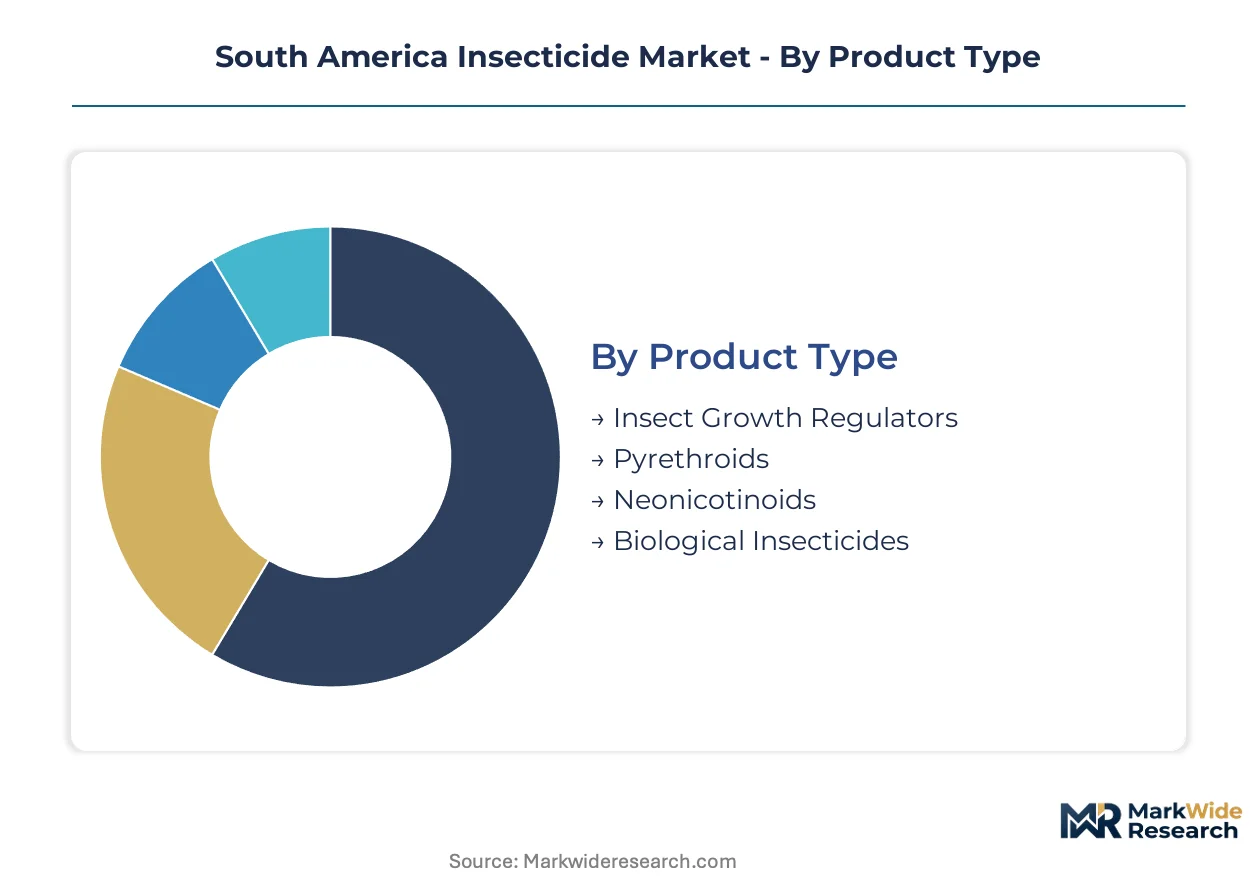
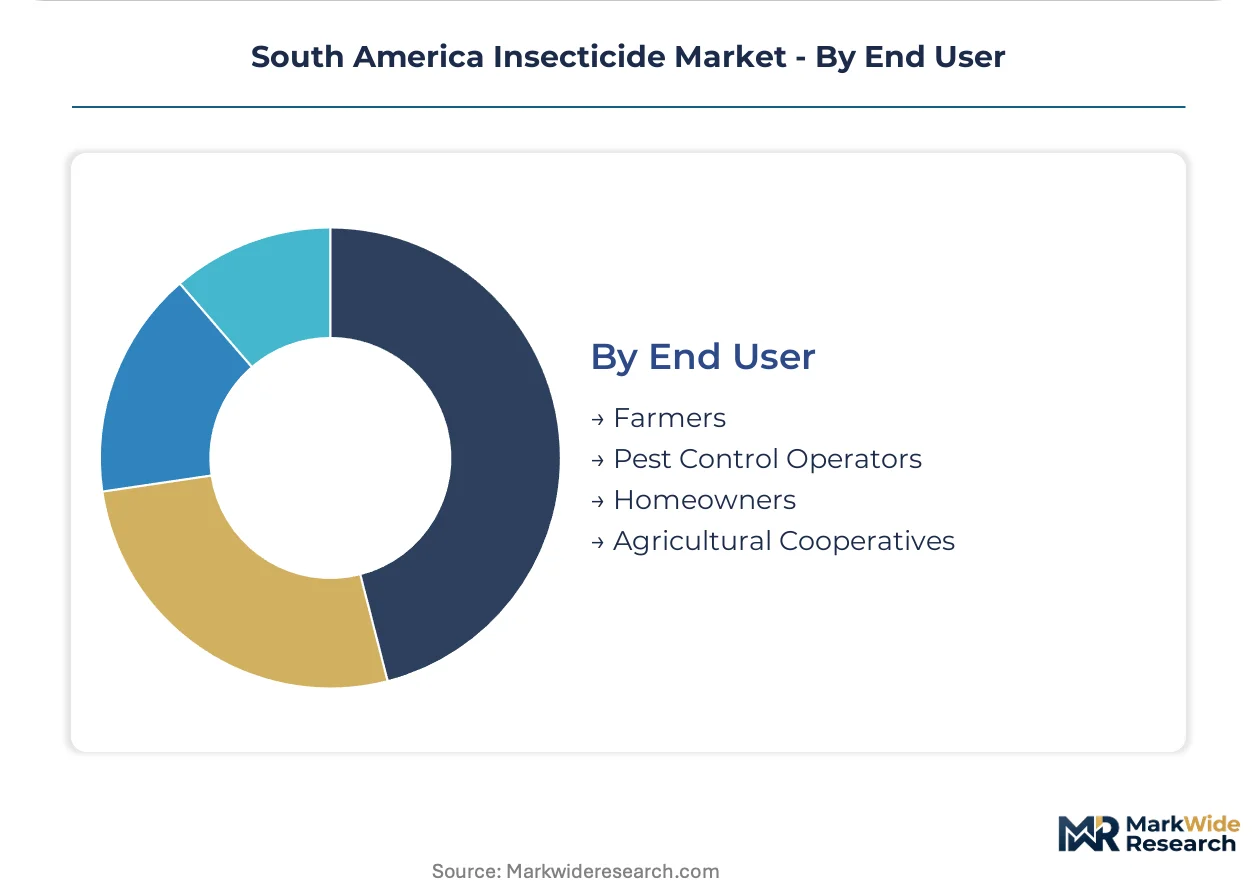
| Segmentation | Product Type: Insect Growth Regulators, Pyrethroids, Neonicotinoids, Biological Insecticides Application: Agricultural Crops, Residential Use, Public Health, Commercial Landscapes Formulation Type: Liquid, Granular, Aerosol, Powder End User: Farmers, Pest Control Operators, Homeowners, Agricultural Cooperatives |
| Companies Covered | FMC Corporation, Syngenta Group, Bayer AG, Corteva Agriscience, ADAMA Agricultural Solutions Ltd, BASF SE, UPL Limited, Sumitomo Chemical Co Ltd, Nufarm Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Insecticide Market Trends and Innovations
Formulation chemistry and application modality are converging to reduce chemical load per hectare while maintaining efficacy against resistant pest populations. Suppliers are repositioning around precision delivery systems and biological-synthetic hybrid portfolios.
RNA interference technology is decomposing conventional neurotoxic modes of action by enabling species-specific genetic disruption of essential pest metabolic pathways. Large-scale soybean producers in Rio Grande do Sul are piloting RNAi sprays against Diabrotica speciosa at experimental scales. This platform is decomposing the market's reliance on broad-spectrum chemical classes by offering target specificity that preserves beneficial insect populations and reduces residue management burdens.
Brazil's updated agrochemical legislation imposes cumulative toxicity assessment protocols that extend beyond acute lethal thresholds to encompass sublethal pollinator effects and soil microbiome disruption. Formulators must now generate multi-generational bee colony data and terrestrial ecotoxicology profiles previously absent from registration dossiers. Biological insecticide categories face streamlined review pathways under this framework, accelerating their relative competitiveness against synthetic benchmarks in ANVISA's evaluation queue.
Cooperative procurement committees are consolidating purchasing decisions across multiple municipalities, displacing individual farmer transactions with volume-negotiated supply agreements that specify application timing and resistance monitoring obligations. This concentration is compressing distributor margins and favoring suppliers capable of delivering technical support alongside chemical inputs. The pattern is most pronounced in Mato Grosso's integrated agricultural cooperatives, where pooled procurement now covers over forty percent of soybean hectarage in key municipalities.
South America Insecticide Market Segmentation
Insecticide procurement across South America fragments across multiple decision hierarchies. Cooperative buying committees, individual farm managers, and municipal vector control programs each impose distinct specification requirements that reshape supplier formulation priorities.
Product Type:
Biological alternatives are displacing synthetic chemistries fastest in segments where residue limits tighten and pollinator toxicity triggers regulatory scrutiny.
- Biological Insecticides:Formulations derived from Bacillus thuringiensis, azadirachtin, and botanical extracts target resistance-prone pest complexes in organic-certified soybean operations. Brazil's MAPA organic seal requirements for export-oriented growers in Mato Grosso and Rio Grande do Sul are accelerating procurement committee specification of these actives.
- Pyrethroids:Synthetic esters of chrysanthemum acid analogs deliver rapid knockdown against public health vectors and agricultural pests. Demand concentrates in Brazil's municipal dengue control programs and aerial spraying cooperatives serving the Cerrado, though metabolic resistance in Helicoverpa armigera populations constrains blanket deployment.
- Neonicotinoids:Systemic nicotinic acetylcholine receptor agonists face structural headwinds amid ANVISA pollinator toxicity reviews and EU export residue alignment pressures.
- Insect Growth Regulators:Juvenile hormone mimics and chitin synthesis inhibitors disrupt molt cycles with lower vertebrate toxicity profiles.
Pyrethroids retain volume leadership; biological insecticides hold the steepest expansion curve.
Application:
End-use concentration varies sharply by country regulatory environment and crop mix intensity.
- Agricultural Crops:Soybean, corn, and cotton production across Brazil's Cerrado and Atlantic corridors consumes the majority of formulated volume, with double-cropping expansion in Argentina's corn belt generating recurring soil-applied demand.
- Public Health:Municipal vector control programs in Brazil's urban peripheries deploy pyrethroid space sprays and larvicides against Aedes aegypti populations.
- Residential Use:Consumer-formulated aerosols and perimeter granules target household pest intrusion in Argentina's Buenos Aires metropolitan zone and Brazil's southeastern cities.
- Commercial Landscapes:Golf course and ornamental maintenance operations in Chile's Santiago basin and Brazil's São Paulo state require scheduled perimeter applications.
Agricultural crops dominate absolute volume; public health programs show the most volatile procurement cycles tied to epidemic declaration protocols.
Formulation Type:
Application modality selection tracks equipment infrastructure maturity and labor cost differentials across cultivation zones.
- Liquid:Emulsifiable concentrates and suspension concentrates suit aerial application platforms and mechanized ground sprayers. Mato Grosso's drone spraying cooperatives are adopting ultra-low-volume liquid formulations optimized for unmanned platforms.
- Granular:Soil-applied microgranules deliver systemic protection at planting, favored in Argentina's no-till corn-soy rotation systems.
- Powder:Wettable powders persist in smallholder operations with limited water access and manual backpack sprayer equipment.
- Aerosol:Pressurized space sprays serve residential and public health vector control with minimal application training requirements.
Liquid formulations command the broadest addressable market; granular products are climbing fastest on no-till adoption.
End User:
Purchasing authority is concentrating away from individual decision-makers toward collective procurement structures.
- Agricultural Cooperatives:Pooled buying committees across Mato Grosso's integrated cooperatives now cover over forty percent of soybean hectarage in key municipalities, displacing distributor relationships with volume-negotiated supply agreements.
- Farmers:Individual growers above five hundred hectares retain direct supplier relationships for resistance monitoring and technical agronomy support.
- Pest Control Operators:Contract spraying services are scaling across Brazil's soybean belt, redrawing procurement patterns as these entities aggregate demand across multiple landholdings.
- Homeowners:Retail channel purchases concentrate in urban centers with limited agricultural extension presence.
Agricultural cooperatives are consolidating procurement authority fastest; pest control operators show the steepest expansion trajectory as contract spraying displaces individual farmer applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports formulated insecticides to Paraguay's expanding soybean frontier while Argentina supplies technical-grade actives to Chile's fruit belt. This trade corridor concentrates procurement authority in São Paulo and Buenos Aires distribution hubs.
Brazil
Soybean intensification across Mato Grosso and Goiás drives recurring demand for fall armyworm control. ANVISA's fast-track registration for biological actives accelerates market entry for Bacillus thuringiensis formulations. São Paulo state's expanded buffer zone mandates around water bodies mechanically reduce treatable hectarage per application cycle.
Argentina
Double-cropping corn-soy rotations in Buenos Aires and Córdoba provinces generate recurring soil-applied insecticide demand. SENASA administers import equivalency for formulated products entering from Brazil and Paraguay. The Pampas agricultural corridor concentrates distribution infrastructure for pyrethroid-based aerial applications.
Paraguay
Eastern Paraguay's unpenetrated soybean belt lacks established distribution networks, creating first-mover opportunities for direct-to-cooperative supply models. The national plant health regulator oversees residue limit alignment with Mercosur standards. The Alto Paraná cultivation zone attracts Brazilian contract spraying cooperatives expanding across the border.
Chile
Export-oriented fruit operations in the Central Valley require residue-compliant insecticides for European and North American market access. The national agricultural service sets maximum residue limits stricter than baseline Mercosur thresholds. Santiago basin golf courses and ornamental maintenance operations sustain niche demand for scheduled perimeter applications.
Colombia
Coffee and palm oil plantations in the Andean and Llanos regions deploy insecticides against broca and rhinoceros beetle infestations. The national agricultural institute manages registration timelines that lag Brazilian ANVISA pathways by eighteen to twenty-four months. The Quindío coffee triangle represents a concentrated demand node for biological-synthetic hybrid protocols.
South America Insecticide Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and distribution reach. The market structure tiers around multinational agrochemical conglomerates, mid-scale regional formulators, and biological-specialist entrants. Three archetypes dominate: scale-driven integrated players, biological-pipeline innovators, and contract-manufacturing-dependent distributors. Competitive moves center on portfolio diversification into biological-synthetic hybrids and backward integration into technical-grade active ingredient sourcing.
Within the multinational tier, Syngenta Group and BASF SE exemplify scale-driven archetypes with deep distribution networks across Brazil's soybean belt. FMC Corporation occupies a position representing biological-pipeline specialization targeting resistance-prone pest complexes. These three entities anchor the competitive structure through distinct strategic postures rather than overlapping capability profiles.
| Leading Market Players |
|---|
| FMC Corporation |
| Syngenta Group |
| Bayer AG |
| Corteva Agriscience |
| ADAMA Agricultural Solutions Ltd |
| BASF SE |
| UPL Limited |
| Sumitomo Chemical Co Ltd |
| Nufarm Ltd |
| Others |
Pricing and Supply Chain Analysis
China's technical-grade active ingredient dominance anchors South American formulator cost structures, compressing margin floors for regional distributors while amplifying volatility exposure to shipping rate fluctuations and yuan-real exchange swings. This concentration simultaneously elevates procurement committee leverage in Mato Grosso and São Paulo, where cooperative volume aggregation extracts price concessions from suppliers competing on formulation service bundles.
Pricing Analysis
Next-generation biological formulations command 40-60% premiums over synthetic pyrethroid baselines, while legacy organophosphate chemistries trade at distressed clearance levels amid ANVISA re-registration uncertainty. Pricing stratifies across premium, standard, and economy tiers keyed to residue certification alignment, application modality compatibility, and bundled technical advisory depth. Cost compression in synthetic categories is intensifying because Chinese technical-grade import concentration exposes formulators to freight cost pass-throughs. Smallholder farmers in Brazil's northeastern cotton belt exhibit highest price sensitivity, while export-oriented soybean cooperatives in Rio Grande do Sul prioritize residue compliance over unit cost.
Supply Chain Analysis
Shanghai-Ningbo port congestion and Panama Canal transit limitations periodically choke active ingredient flows to São Paulo formulation hubs, extending lead times for Brazilian distributors serving the Cerrado. Supply concentration rests on China for pyrethroid and neonicotinoid technical grades, India for intermediate synthesis, and Brazil for terminal formulation and packaging. Single-source vulnerability in fall armyworm-specific Bacillus thuringiensis strains elevates biological pipeline risk. Distribution runs through São Paulo and Buenos Aires distribution hubs serving cooperative procurement committees, with direct-to-farm drone spraying cooperatives emerging as a disintermediation channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital prescription platforms and cooperative procurement aggregation are transforming South American insecticide distribution into a two-sided platform economy, where supplier value migrates from chemical volume to algorithmic pest identification and resistance monitoring interoperability.
For Market Incumbents: Compound technical advisory capabilities with biological-synthetic hybrid portfolios to defend against contract spraying cooperatives disintermediating traditional distributor relationships. Prioritize backward integration into Bacillus thuringiensis strain development and captive supply of RNA interference precursors to reduce Chinese technical-grade dependency. Channel control through exclusive cooperative supply agreements represents the critical defensive lever against emerging biological-specialist entrants. For New Entrants and Emerging Players: ANVISA's fast-track registration pathway for biological actives offers the most penetrable entry vector, enabling market access ahead of synthetic incumbent re-registration timelines. Target eastern Paraguay's unpenetrated soybean belt with direct-to-cooperative supply models bypassing established São Paulo distribution infrastructure. Lead with drone-optimized ultra-low-volume formulations bundled with smartphone-based pest identification tools to differentiate from legacy liquid concentrate suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract spraying cooperatives and digital prescription platform operators, positioning these archetypes for premium valuation multiples relative to commodity formulation businesses. Acquisition targets should emphasize biological pipeline depth and ANVISA registration dossier completeness over scale-driven distribution reach. Monitor RNA interference field trial outcomes in Rio Grande do Sul as the signal indicating platform shift timing from chemical neurotoxicity to genetic pest disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Pipeline Expansion | ANVISA fast-track pathways accelerate market entry ahead of synthetic re-registration delays. |
| Drone Application Formulation | Mato Grosso aerial spraying cooperatives create pull for ultra-low-volume liquid concentrate innovation. |
| Cooperative Procurement Integration | Direct supply agreements with pooled buying committees displace traditional distributor margins. |
| RNA Interference Development | Species-specific genetic disruption reduces resistance management burden versus broad-spectrum chemistries. |
| Backward Integration into Technical Actives | Captive Bacillus thuringiensis strain production mitigates Chinese import concentration risk. |
Research Methodology
Operator-level perspectives from agricultural cooperative procurement committees, contract spraying service managers, ANVISA regulatory affairs specialists, and technical-grade import distributors anchored the qualitative base. Primary fieldwork combined structured interviews with downstream formulation plant managers and resistance monitoring agronomists, validated against secondary sources including ANVISA registration databases, SENASA import equivalency filings, Brazilian customs trade statistics, and SEC 10-K disclosures from listed agrochemical conglomerates. Bottom-up hectarage and application rate estimates triangulated against top-down formulation production and import volume data.
Sensitivity analysis across resistance evolution scenarios, regulatory re-registration timelines, and cooperative procurement concentration trajectories informed projection robustness. Segmentation modeling spanned product type, application modality, formulation chemistry, and end-user purchasing authority across the analysis window. CAGRs derived from weighted average of historical volume trends, crop intensification forecasts, and biological substitution elasticity estimates. Industry-specific inputs included fall armyworm resistance monitoring data from Embrapa research stations and drone spraying cooperative adoption curves from Mato Grosso agricultural extension records.
Underlying assumptions cover ANVISA registration pathway stability, Chinese technical-grade export continuity, and cooperative procurement committee persistence, with deviation risk concentrated in pollinator toxicity regulatory escalation and RNA interference field trial performance. Practitioners should keep alternative scenarios live as Mercosur harmonization negotiations and state-level buffer zone mandate expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South America Acaricides Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Europe Insecticides Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Isoxaflutole Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Pest Control Products Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Global Termite Control Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
India Insecticide Market
Crop Protection
Global Acaricides Market