
 Europe Feed Pigments Market | 2026-2036
Europe Feed Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Pigments Market Analysis
Pharmaceutical-grade carotenoid specifications is unwinding quality premiums across the European supply base. BASF SE leverages its Ludwigshafen manufacturing complex to sustain backward integration into astaxanthin fermentation. DSM-Firmenich anchors its position through R&D intensity in encapsulated delivery systems for heat-stable pigments. Kemin Industries Inc. specializes in poultry-specific formulations that dominate southern European distribution channels.
Feed pigments comprise bioactive colorant compounds, principally carotenoids and betalains, added to animal diets at inclusion rates between 10 and 500 ppm to pigment flesh, egg yolks, and skin for consumer acceptance. Synthetic astaxanthin dominates aquaculture applications due to standardized potency and cost efficiency. Carotenoid concentrates command the largest revenue pool in ruminant and swine nutrition where regulatory caps on synthetic additives push demand toward natural alternatives. Powder formulations lead volume shipments among feed manufacturers seeking dry premix compatibility, while liquid pigments capture premium positioning in aquaculture companies requiring automated dosing systems.
EMA guidelines on feed additive safety assessments and REACH chemical registration requirements shape product development timelines and market access conditions across EU member states. EFSA establishes maximum permitted levels for annatto and spirulina-derived pigments in food-producing species, directly constraining formulation strategies. Stakeholders must monitor the EU AI Act's emerging classification of precision livestock technologies, as automated pigment dosing systems face prospective compliance obligations that could reshape equipment procurement and service models.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing synthetic pigment manufacturing margins while redirecting capital toward fermentation-based extraction and solvent-free processing infrastructure. Producers must reconfigure supply chains around renewable feedstock sourcing and closed-loop water systems to maintain market access.
Growth Catalysts
- Poultry yolk coloration standards:Spanish and Dutch integrators are expanding carotenoid inclusion rates to meet retailer specifications for deep-orange egg yolks in premium retail channels.
- REACH chemical registration pathways:Streamlined dossier approvals for natural pigment concentrates are accelerating product launches relative to synthetic additive timelines.
- Aquaculture flesh pigmentation:Norwegian and Scottish salmon producers are increasing astaxanthin dosing to achieve consistent fillet coloring for export certification requirements.
Market Restraints
- Carotenoid feedstock volatility:Marigold oleoresin supply from Indian extraction facilities experiences seasonal price swings that compress European formulator margins.
- Synthetic astaxanthin supply concentration:Three fermentation facilities in China and India control over 80% of global intermediate supply, creating single-source vulnerability for European compounders.
- EFSA maximum permitted levels:Caps on annatto and spirulina-derived pigments in laying hens constrain formulation flexibility for natural-only product lines.
Strategic Opportunities
- Polish and Romanian poultry expansion:Greenfield integrator investments in Eastern Europe lack established pigment supply contracts, creating first-mover positioning for formulated premix suppliers.
- Encapsulated delivery systems:Heat-stable microencapsulation technologies enable pelleting temperature tolerance above 85°C, opening compound feed applications previously restricted to liquid dosing.
- EU AI Act precision livestock compliance:Automated pigment dosing systems face prospective classification requirements that favor integrated equipment-service bundling over component sales.
Industry Challenges
- Fermentation scale-up talent scarcity:European bioprocess engineering programs produce insufficient graduates to staff planned astaxanthin fermentation capacity expansions.
- EMA feed additive safety assessment timelines:Novel natural pigment submissions face 18-24 month evaluation windows that delay revenue recognition and strain R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Pigments Market |
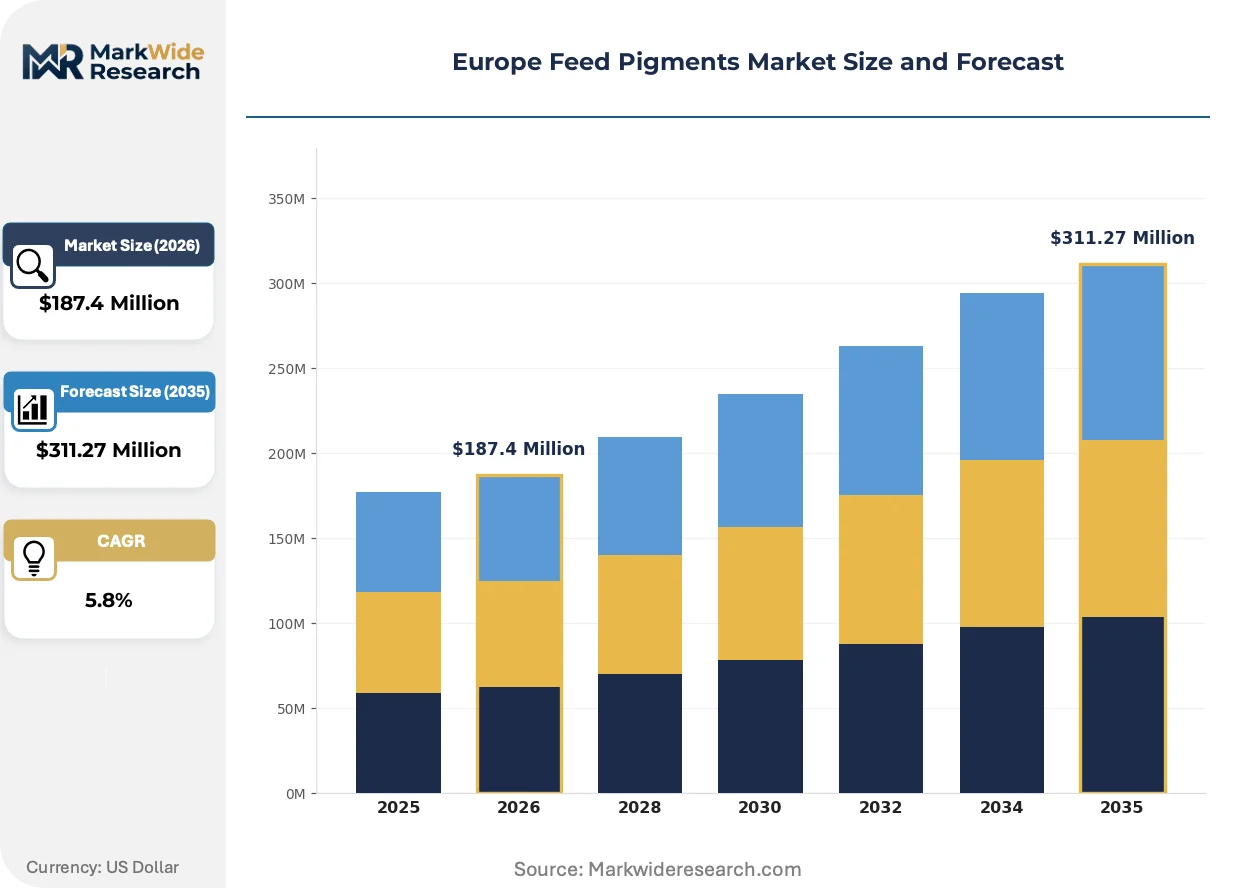
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carotenoids, Beetroot Red, Spirulina Extract, Annatto Form: Powder, Liquid, Granular, Paste Application: Poultry Nutrition, Swine Nutrition, Aquaculture, Ruminants End User: Feed Manufacturers, Pet Food Producers, Livestock Farmers, Aquaculture Companies |
| Companies Covered | BASF SE, DSM-Firmenich, Kemin Industries Inc., Nutrex N.V., EW Nutrition, Synthite Industries Ltd, Impextraco N.V., Bordas S.A., Guangzhou Leader Bio-Technology Co., Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Pigments Market Emerging Trajectories
Biomanufacturing scale-up and regulatory reclassification are fragmenting competitive positioning between synthetic legacy portfolios and fermentation-derived alternatives. Formulation science is pivoting toward stability engineering as thermal processing intensifies in compound feed production.
Microencapsulated carotenoid delivery is bifurcating the pigment market between heat-labile standard concentrates and pelleting-stable premium grades. Poultry integrators in Spain and the Netherlands are adopting encapsulated lutein and zeaxanthin at accelerated rates to eliminate double-dosing requirements. This technology compression is forcing synthetic pigment suppliers to defend position through price repositioning rather than performance claims.
REACH chemical registration requirements are extending development timelines for novel synthetic pigments while grandfathering existing substances until 2027 renewal deadlines. The industrial consequence is a freeze on new molecular introductions and concentration of R&D budgets toward natural source validation. Aquaculture compounders are most affected, as salmon fillet coloration specifications tighten ahead of registration certainty for next-generation alternatives.
Retailer-driven procurement consolidation is displacing spot-market pigment purchasing with annual framework agreements tied to sustainability certification. Dutch and German feed manufacturers are consolidating supplier panels to three approved vendors per pigment category, replacing fragmented multi-source strategies. This channel compression is most visible in the organic poultry segment, where Soil Association and EU Organic logos require auditable pigment chain-of-custody documentation.
Europe Feed Pigments Market Segmentation
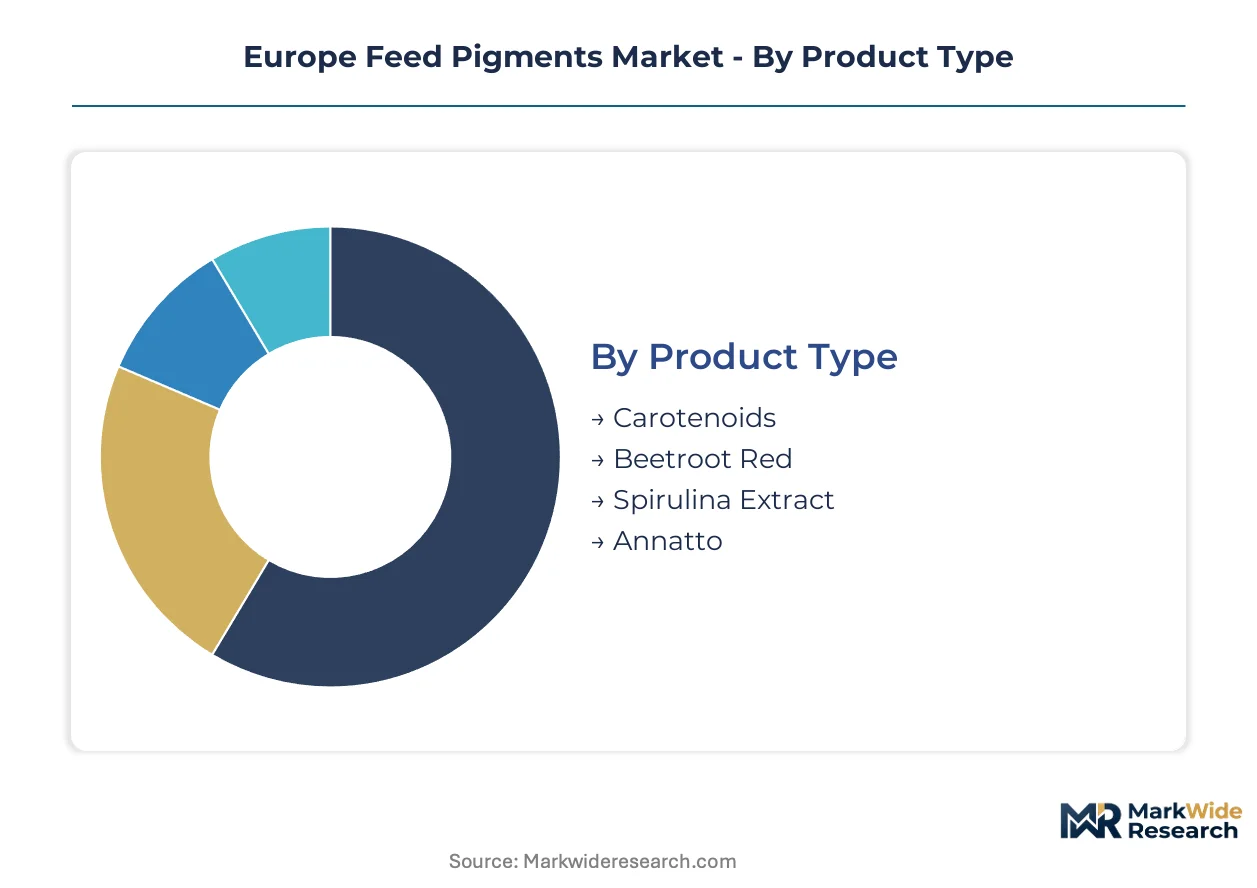
Feed pigment segmentation in Europe tracks divergent margin pools across product chemistry, physical form, and species application. Each dimension carries distinct regulatory exposure and supply chain configuration that shapes procurement strategy for compound feed manufacturers and integrated livestock operations.
Product Type:
Margin concentration tilts toward fermentation-derived and botanical-extracted categories where EFSA registration barriers protect pricing power against synthetic alternatives.
- Carotenoids:Astaxanthin, lutein, and zeaxanthin dominate revenue pools through standardized potency specifications for aquaculture flesh pigmentation and poultry yolk coloration. Norwegian salmon producers and Spanish egg integrators drive demand concentration as retailer specifications tighten for deep-orange fillets and premium shell egg positioning.
- Spirulina Extract:C-phycocyanin and chlorophyll-based concentrates command natural-only formulation premiums in organic poultry and ruminant segments. Dutch and German feed manufacturers source spirulina-derived pigments to meet Soil Association and EU Organic logo requirements where synthetic carotenoid exclusions apply.
- Annatto:Bixin and norbixin carotenoids from achiote seed extraction serve cost-sensitive yolk coloration in standard egg production tiers.
- Beetroot Red:Betalain pigments from Beta vulgaris processing fill niche applications in pet food visual appeal and specialty ruminant feed formulations.
Carotenoids hold installed capacity across Ludwigshafen and Grenzach fermentation complexes. Spirulina Extract is rotating up the share rankings as EFSA caps on synthetic additives accelerate natural substitution.
Form:
Physical format selection directly determines compatibility with compound feed manufacturing infrastructure and automated dosing system investments.
- Powder:Dry concentrates lead volume shipments through premix compatibility and extended shelf stability under standard warehouse conditions. Feed manufacturers in the Netherlands and Spain specify powder grades for integration into vitamin-mineral premixes ahead of pelleting or extrusion.
- Liquid:Pumpable suspensions capture aquaculture positioning where automated dosing systems require flowable consistency for precise inclusion control. Scottish and Norwegian salmon compounders favor liquid astaxanthin for direct injection into extruded feeds without thermal degradation.
- Granular:Dust-free agglomerated forms reduce handling losses in large-scale poultry integration facilities.
- Paste:High-viscosity semi-solids serve niche pet food applications requiring specific texture incorporation.
Powder maintains dominant installed capacity across European toll manufacturing networks. Liquid is climbing fastest as aquaculture automation investments accelerate in North Atlantic production zones.
Application:
Species-specific coloration standards create divergent growth trajectories tied to retail channel premiumization and export certification requirements.
- Poultry Nutrition:Yolk pigmentation and skin coloring specifications from German and French retailers drive carotenoid inclusion rate expansion. Spanish integrators are adopting encapsulated lutein and zeaxanthin at accelerated rates to eliminate double-dosing requirements through pelleting heat tolerance.
- Aquaculture:Salmon fillet coloration for export certification to Japanese and North American markets sustains astaxanthin demand concentration. Norwegian producers face tightening specifications ahead of registration certainty for next-generation alternatives under REACH renewal timelines.
- Swine Nutrition:Subcutaneous fat coloration for certain Southern European traditional product categories maintains steady demand.
- Ruminants:Milk and beef coloration applications remain constrained by regulatory caps on additive transfer to food products.
Poultry Nutrition holds installed capacity across southern European premix formulation plants. Aquaculture is expanding most quickly as Scottish and Norwegian production volumes recover.
End User:
Customer type determines contract structure, with integrated operations favoring annual framework agreements and independent farmers remaining on spot procurement.
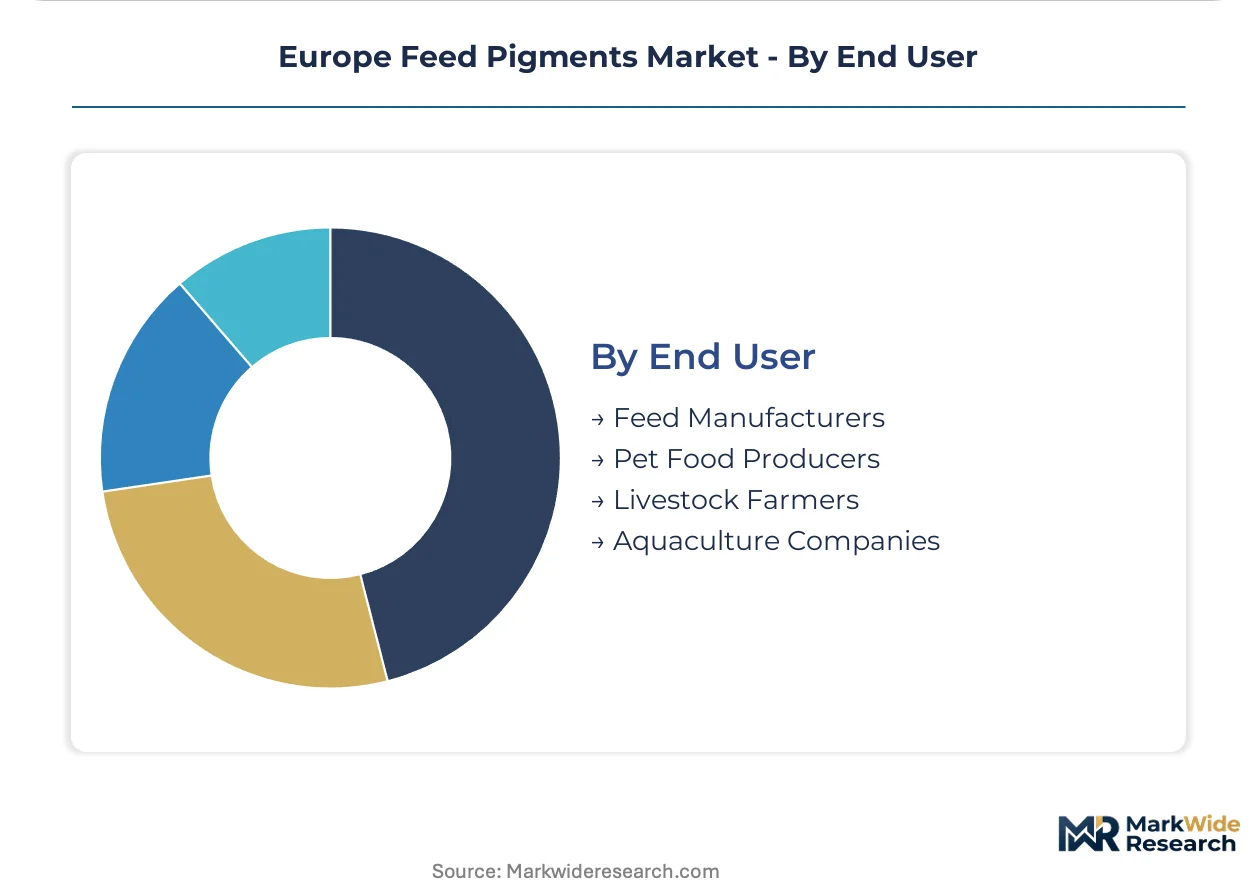
- Feed Manufacturers:Compound feed producers consolidate supplier panels to three approved vendors per pigment category, replacing fragmented multi-source strategies. Dutch and German manufacturers now require auditable chain-of-custody documentation for organic certification compliance.
- Aquaculture Companies:Salmon producers in Norway and Scotland operate captive extrusion facilities with direct pigment procurement bypassing merchant compounders. Automated dosing system investments favor liquid pigment suppliers offering integrated equipment-service bundling.
- Livestock Farmers:Independent poultry and swine operations purchase through distribution cooperatives with limited formulation input.
- Pet Food Producers:Visual appeal specifications in premium pet food segments sustain niche demand for natural colorants.
Feed Manufacturers hold installed capacity across northwest European supply chains. Aquaculture Companies are gaining share fastest as North Atlantic salmon production restructures toward fewer, larger integrated operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European feed pigment trade flows show a structural deficit in fermentation-derived intermediates, with Dutch and German compounders importing over 60 percent of astaxanthin precursors from Asian biomanufacturing clusters. Export strength concentrates in formulated premixes and encapsulated delivery systems where EFSA-registered products command certification premiums in third-country markets.
Spain
Intensive poultry integration in Catalonia and Aragon drives carotenoid consumption for yolk coloration contracts with French and German retailers. The EU Green Deal nitrogen emission caps are accelerating manure-to-biogas investments that offset pigment production energy costs. Zaragoza's feed manufacturing corridor hosts the continent's densest concentration of encapsulated lutein formulation capacity.
Netherlands
Rotterdam-Antwerp port logistics anchor spirulina extract imports for organic poultry premixes serving Soil Association-certified supply chains. REACH streamlined dossier pathways for natural concentrates have shortened product launch cycles versus synthetic additive timelines. The Eindhoven region's toll manufacturing networks specialize in heat-stable microencapsulation for pelleting applications above 85°C.
Norway
Salmon aquaculture in Trøndelag and Vestland sustains liquid astaxanthin demand for automated dosing systems in extruded feed production. EFSA maximum permitted level reviews for next-generation alternatives are creating registration uncertainty ahead of REACH renewal deadlines. Bergen's marine biotechnology cluster is piloting fermentation scale-up for domestic astaxanthin precursor supply.
Germany
Compound feed manufacturers in Lower Saxony and North Rhine-Westphalia are consolidating supplier panels to three approved vendors per pigment category for organic certification compliance. The F-Gas Regulation is compressing synthetic pigment manufacturing margins and redirecting capital toward solvent-free processing infrastructure. Ludwigshafen's chemical complex maintains backward integration into carotenoid fermentation through captive bioreactor capacity.
Poland
Greenfield poultry integrator investments in Greater Poland and Lower Silesia lack established pigment supply contracts, creating first-mover positioning for formulated premix suppliers. EU AI Act emerging classification of precision livestock technologies is reshaping automated dosing system procurement toward integrated equipment-service bundling. Poznań's emerging feed manufacturing belt is attracting toll formulation investments from northwest European suppliers.
Europe Feed Pigments Market Vendor Landscape
Concentration sits with diversified chemical conglomerates and fermentation specialists that control EFSA-registered substance portfolios. The supplier base fragments across botanical extractors serving organic segments and synthetic legacy producers defending position through price repositioning. Three strategic archetypes dominate: backward-integrated fermentation operators, encapsulated delivery system innovators, and regional formulation specialists. Competitive moves center on capacity expansion in heat-stable microencapsulation and strategic partnerships for renewable feedstock sourcing.
Within the diversified chemical tier, BASF SE and DSM-Firmenich exemplify archetype positioning through Ludwigshafen and Grenzach manufacturing complexes. Kemin Industries Inc. occupies the regional specialist tier with poultry-specific formulation concentration. These three anchors represent distinct strategic postures: conglomerate-scale fermentation infrastructure, R&D intensity in delivery systems, and distribution channel specialization in southern European markets.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich |
| Kemin Industries Inc. |
| Nutrex N.V. |
| EW Nutrition |
| Synthite Industries Ltd |
| Impextraco N.V. |
| Bordas S.A. |
| Guangzhou Leader Bio-Technology Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory buffers for marigold oleoresin feedstock concentrate pricing power with Dutch and German compounders capable of forward-contracting Indian extraction volumes. Spanish poultry integrators lacking equivalent storage infrastructure face spot-market exposure that amplifies margin compression during monsoon-driven supply disruptions. The EU Green Deal's nitrogen emission caps further reshape procurement economics by rewarding closed-loop water systems with carbon credit offsets that synthetic pigment producers cannot access.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across northwest European feed manufacturing. Pricing stratifies across pharmaceutical-grade carotenoid, feed-grade concentrate, and commodity extract tiers, with EFSA registration status and Soil Association certification commanding substantial premia. Cost compression in synthetic astaxanthin is intensifying because REACH renewal timelines freeze new molecular introductions and concentrate competition among grandfathered substances. Independent livestock farmers through distribution cooperatives exhibit highest price sensitivity, while Norwegian salmon producers with captive extrusion facilities demonstrate lowest sensitivity due to automated dosing system lock-in.
Supply Chain Analysis
Sixty-day lead times for astaxanthin fermentation intermediates expose European compounders to supply disruption from three concentrated biomanufacturing clusters in China and India. Marigold oleoresin, spirulina biomass, and achiote seed extraction constitute critical raw material dependencies that draw from seasonal agricultural cycles. Single-source vulnerability in synthetic astaxanthin precursors creates acute supply chain risk should export licensing tighten. Distribution runs through Rotterdam-Antwerp port logistics for bulk import, with toll manufacturing networks in the Eindhoven region and Zaragoza corridor handling downstream formulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Dutch and German feed manufacturers consolidating supplier panels to three approved vendors per pigment category, displacing fragmented multi-source strategies that previously fragmented procurement leverage.
For Market Incumbents: Fortify EFSA-registered substance portfolios against natural pigment substitution by accelerating heat-stable microencapsulation capacity in the Eindhoven region. Backward integration into fermentation-derived astaxanthin at Ludwigshafen and Grenzach complexes reduces exposure to Asian intermediate supply concentration. Channel control through annual framework agreements with retailer-driven procurement consolidation locks out challenger brands from organic poultry certification chains. For New Entrants and Emerging Players: Automated dosing system service gaps in Polish and Romanian greenfield poultry operations offer first-mover positioning where northwest European incumbents lack established distribution. Encapsulated delivery system under-penetration in Eastern European compound feed applications enables pelleting-temperature tolerance differentiation. A bundled equipment-service go-to-market angle aligns with EU AI Act precision livestock compliance requirements reshaping procurement toward integrated solutions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core feed additive portfolios amid F-Gas Regulation margin compression. Mid-term viability over the coming decade hinges on fermentation scale-up capabilities and renewable feedstock sourcing credentials. The signal to watch is EFSA maximum permitted level reviews for next-generation natural pigments, which would trigger registration-driven acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive astaxanthin production at Ludwigshafen reduces Asian intermediate dependency. |
| Heat-Stable Microencapsulation Investment | Eindhoven toll manufacturing enables pelleting tolerance above 85°C for poultry integrators. |
| Renewable Feedstock Sourcing Partnerships | Closed-loop water systems align with EU Green Deal nitrogen emission caps. |
| Automated Dosing System Bundling | Integrated equipment-service contracts capture EU AI Act compliance positioning. |
| EFSA Registration Acceleration | Streamlined dossier pathways for natural concentrates shorten product launch cycles versus synthetic timelines. |
Methodological Framework
The analysis maps carotenoid, spirulina extract, annatto, and beetroot red sub-sectors, each validated through formulation scientists at compound feed manufacturers, procurement leads at integrated poultry operations, regulatory affairs specialists navigating EMA guidelines, and technical directors at fermentation facilities. Primary interview insights triangulate against EFSA maximum permitted level documentation, REACH registration dossiers, EU Green Deal implementation reports, and customs trade data for marigold oleoresin imports. Bottom-up volume modeling across species applications reconciles with top-down value estimates from premix manufacturer revenue disclosures.
Consistency checks against external benchmarks validate projections across the analysis window. Segmentation dimensions span product chemistry, physical form, species application, and end-user contract structure. CAGRs derive from fitted growth curves calibrated to poultry integration expansion rates in Spain and Poland, aquaculture production recovery in Norway and Scotland, and regulatory substitution effects from EFSA caps on synthetic additives. Industry-specific inputs include marigold oleoresin price volatility indices and encapsulated delivery system adoption curves.
Underlying assumptions cover EFSA registration timeline stability, REACH renewal grandfathering continuity, and monsoon pattern regularity for Indian extraction output, with deviation risk concentrated in EU AI Act precision livestock classification timing and fermentation scale-up talent availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Agricultural Coatings Market