
 Foliar Spray Market | 2026-2036
Foliar Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Foliar Spray Market Intelligence
The substitution of traditional bulk fertilizers with advanced chelated micronutrient formulations is realigning product economics for crop nutrition. This shift favors precision application over volume, directly impacting nutrient delivery strategies. Yara International ASA leverages its extensive portfolio of specialty nutrients to capture this value shift. Nutrien Ltd. utilizes its vast distribution network to supply both conventional and specialty foliar products, while BASF SE differentiates through its research and development in advanced adjuvant and surfactant technologies.
Foliar spray involves the direct application of liquid nutrients, biostimulants, or crop protection agents onto plant leaves for rapid absorption. Formulations often contain surfactants and adjuvants to ensure uniform coverage and adherence to the leaf surface, bypassing soil-based nutrient limitations. Micronutrient and bio-fertilizer sprays represent the fastest-growing product categories due to their role in enhancing crop quality. High-value application crops such as fruits and vegetables command premium pricing for specialized foliar treatments that improve yield and marketability.
Regulatory frameworks established by bodies like the U.S. Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH govern the chemical composition and safety of foliar products. In Brazil, ANVISA sets strict limits on pesticide residues, influencing formulation choices for export-oriented crops. The key decision for manufacturers now centers on balancing formulation efficacy with an increasingly complex and fragmented international regulatory landscape for active ingredients.
Market Dynamics
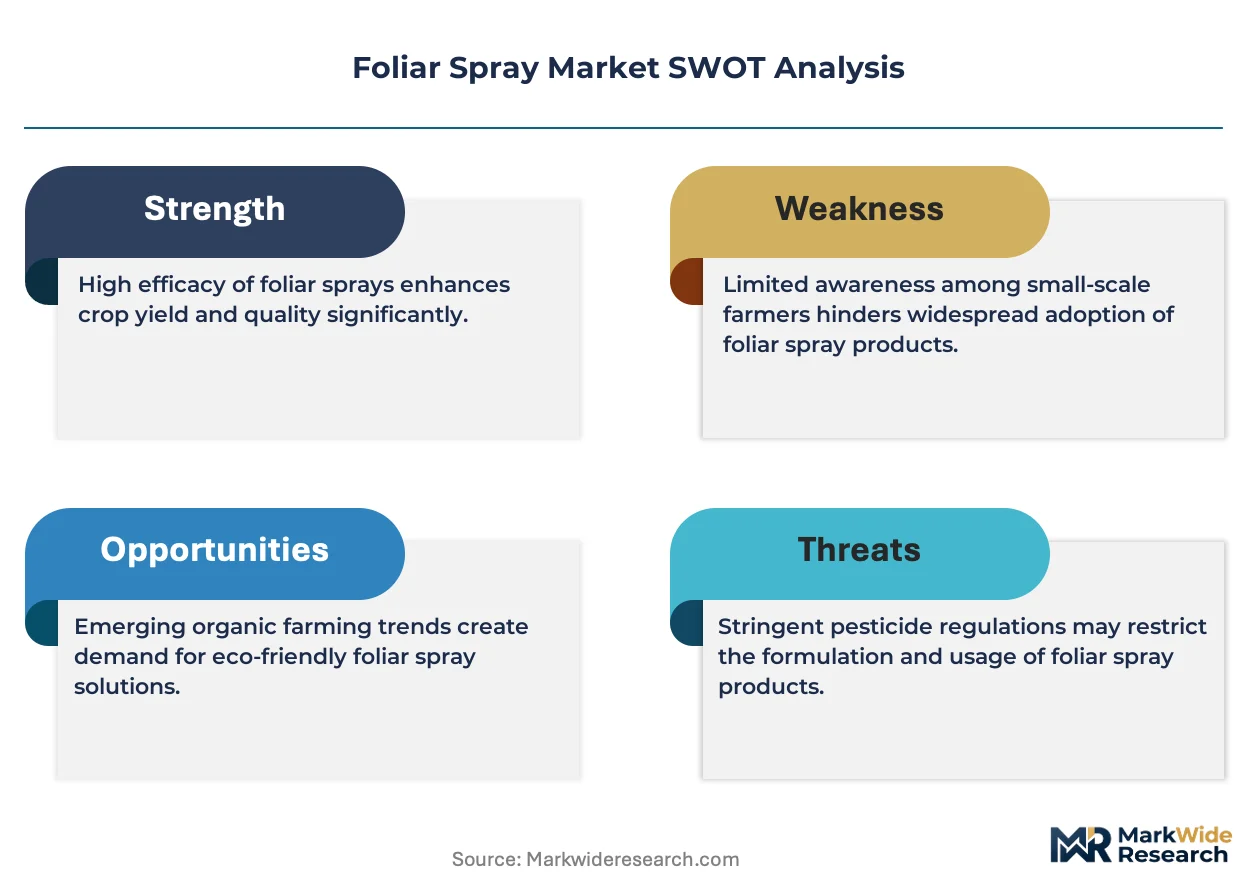
The market's structure is defined by the tension between formulation innovation for higher crop efficacy and the growing complexity of a fragmented global regulatory environment. This dynamic forces manufacturers to balance performance gains against compliance costs across multiple jurisdictions, influencing both product development and market access strategies.
Growth Catalysts
- Precision Agriculture Demand:The expansion of high-value fruit and vegetable cultivation, particularly in Mediterranean climates, requires precise nutrient delivery to enhance crop quality and marketability, favoring foliar methods over soil application.
- European Union Green Deal:This policy framework incentivizes efficient nutrient management to minimize environmental runoff, directly promoting the adoption of targeted foliar sprays as a substitute for less efficient bulk fertilizers.
- Chelated Micronutrient Formulations:Advances in chelation chemistry improve nutrient stability and plant uptake, enabling more effective treatment of deficiencies in large-scale soybean and sugarcane farming in countries like Brazil.
Market Restraints
- Regulatory Divergence:Conflicting maximum residue limits and approved active ingredient lists between jurisdictions like the U.S. Environmental Protection Agency and Europe's ECHA create significant barriers to developing universally accepted product formulations.
- Surfactant Cost Volatility:The price of petroleum-derived adjuvants and surfactants, critical for formulation stability and leaf adhesion, is subject to fluctuations in global oil markets, impacting manufacturer margins.
- Limited Leaf Absorption:The physical capacity of plant leaves to absorb nutrients is finite, placing a technical ceiling on the efficacy of single-application treatments, especially for macronutrients required in large quantities.
Strategic Opportunities
- Biostimulant Integration:Incorporating seaweed extracts and microbial inoculants into foliar sprays for use in controlled environment agriculture presents a new avenue for enhancing stress tolerance and growth in high-density vertical farms.
- Drone Application Systems:The convergence of UAV technology with variable-rate application maps allows for hyper-targeted spraying, opening opportunities in precision viticulture and orchard management where terrain is difficult for ground equipment.
- Southeast Asian Market Entry:The region's expanding horticulture sector, especially in Vietnam and Thailand, remains underpenetrated by advanced foliar products, offering a significant growth frontier for specialized formulations.
Industry Challenges
- Complex Registration Dossiers:Navigating the lengthy and data-intensive product registration processes required by agencies like Brazil's ANVISA or under the EU's REACH framework demands specialized regulatory affairs teams and significant upfront investment.
- Agronomic Expertise Scarcity:Effective sales and support require agronomists who can interpret tissue analysis and provide customized spray recommendations, a skill set that is in short supply and difficult to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foliar Spray Market |
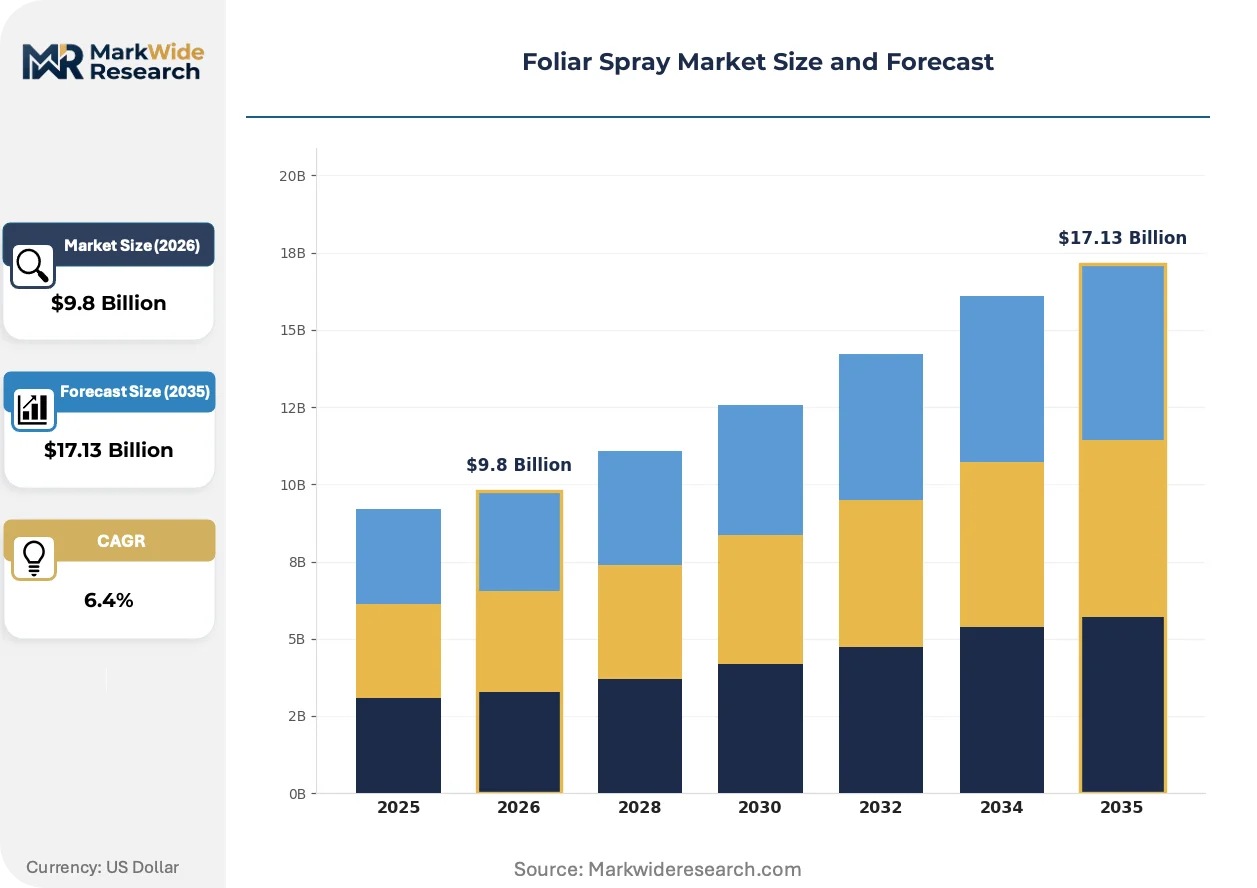
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen-based, Micronutrient, Bio-fertilizers, Pesticide Sprays, Growth Regulators Application Crop: Cereals, Cotton, Fruits, Vegetables, Oilseeds, Pulses Technology: Microemulsion, Suspension Concentrate, Water Dispersible Granules, Emulsifiable Concentrate, Soluble Powder End User: Farmers, Agricultural Cooperatives, Contract Growers, Greenhouses, Nurseries |
| Companies Covered | Yara International ASA, Nutrien Ltd., BASF SE, Syngenta AG, The Mosaic Company, Coromandel International Limited, Eurochem Group, Israel Chemicals Ltd, UPL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foliar Spray Market Strategic Shifts & Innovations
A fundamental shift is underway as foliar application evolves from a corrective measure to a predictive and prescriptive tool. The integration of biological inputs and data analytics is redefining product efficacy and application strategies for modern agriculture.
Nano-encapsulation technology protects active ingredients like micronutrients within a biodegradable polymer shell for controlled release. Growers of high-value specialty crops are early adopters, seeking to maximize nutrient availability during critical growth phases. This technology is modularizing nutrient delivery, allowing formulators to create customized release profiles that match the specific phenological stage of a target crop.
The European Union's Farm to Fork Strategy mandates significant reductions in fertilizer use and nutrient losses. This directive pressures farmers to abandon inefficient broadcasting methods in favor of precision techniques. The cereals and oilseeds sector in member states like France and Germany is most affected, accelerating investment in targeted foliar nutrition to sustain yields while meeting new environmental compliance standards.
Data-driven agronomic service models are gaining traction over simple product transactions. This shift disrupts traditional agricultural retailers who rely on volume-based sales, as growers now purchase integrated packages including soil testing, tissue analysis, and customized spray prescriptions. This trend is most prominent in large-scale row crop operations in the United States and Brazil, where farm management software platforms are widely used.
Foliar Spray Market Segmentation
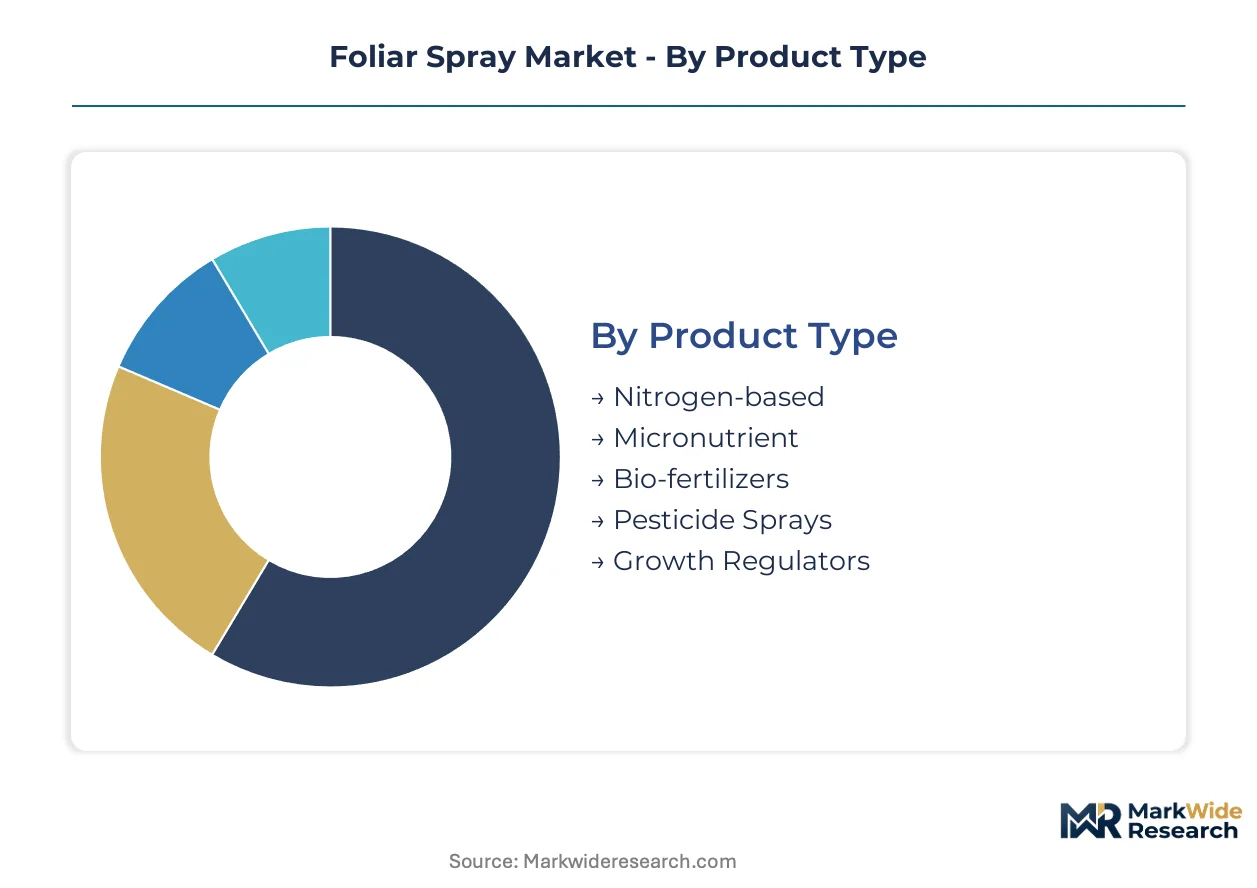
The foliar spray market segments reveal distinct product preferences and application strategies across diverse agricultural practices. Understanding these divisions helps manufacturers tailor formulations and distribution channels to meet specific grower needs, from large-scale commodity production to high-value specialty crops. Each segment reflects unique agronomic requirements and economic considerations for nutrient delivery.
Product Type:
Buyer priorities for foliar spray products often hinge on the specific nutrient deficiency or pest challenge they aim to address.
- Micronutrient:These formulations deliver essential trace elements like zinc, iron, and manganese directly to plant leaves, crucial for enzyme function and photosynthesis. Demand concentrates in high-value fruit and vegetable cultivation, where precise nutrient management improves crop quality and marketability.
- Bio-fertilizers:Comprising beneficial microorganisms or natural substances, these sprays enhance nutrient uptake, plant growth, and stress tolerance. Adoption is accelerating in regions like the European Union due to policies promoting sustainable agriculture and reduced chemical inputs.
- Nitrogen-based:These sprays provide rapidly available nitrogen, supporting vegetative growth and chlorophyll production.
- Pesticide Sprays:Formulations containing insecticides, fungicides, or herbicides are applied directly to foliage for rapid pest and disease control.
- Growth Regulators:These products manipulate plant physiological processes, influencing flowering, fruit set, and overall plant architecture.
Nitrogen-based products leads volumes today; Bio-fertilizers are gaining share fastest.
Application Crop:
The application crop dictates the specific nutrient profile and timing required for optimal foliar treatment.
- Fruits:High-value fruit crops like grapes and citrus require specialized foliar applications for improved fruit size, color, and sugar content. Precision viticulture and orchard management in Mediterranean climates drive demand for these tailored solutions.
- Vegetables:Intensive vegetable cultivation, particularly in controlled environments, relies on foliar sprays for rapid nutrient correction and enhanced yield quality. Growers prioritize formulations that minimize residue and improve shelf life for export markets.
- Cereals:Large-scale cereal production, including wheat and corn, uses foliar sprays to supplement soil nutrients and address specific deficiencies during critical growth stages.
- Oilseeds:Crops like soybeans and rapeseed benefit from foliar applications of micronutrients to optimize oil content and overall yield.
- Cotton:Foliar sprays in cotton cultivation target boll development and fiber quality, often complementing soil-applied fertilizers.
- Pulses:Leguminous crops such as lentils and chickpeas utilize foliar treatments to boost nitrogen fixation and improve seed protein content.
Cereals currently account for the largest volume, while high-value Vegetables show the steepest expansion trajectory.
Technology:
Formulation technology differentiates products based on stability, compatibility, and ease of application across various spray systems.
- Microemulsion:These stable, transparent formulations feature ultra-small droplet sizes, enhancing leaf penetration and nutrient absorption. Adoption is prominent in high-value specialty crops where maximum efficacy and controlled release are critical.
- Suspension Concentrate:This technology suspends solid active ingredients in a liquid, offering high concentration and reduced dust hazards compared to dry formulations. It finds extensive use for insoluble active ingredients in large-scale agricultural operations.
- Water Dispersible Granules:These solid, dust-free formulations disperse readily in water, simplifying handling and reducing exposure risks for operators.
- Emulsifiable Concentrate:Active ingredients are dissolved in a solvent and emulsifiers, forming stable emulsions when mixed with water.
- Soluble Powder:These dry formulations dissolve completely in water, leaving no residue and simplifying tank mixing procedures.
Emulsifiable Concentrate formulations maintain a significant market presence, but Microemulsions are experiencing rapid adoption.
End User:
End-user segments differentiate by their operational scale, crop diversity, and access to advanced application machinery.
- Farmers:Individual farmers, ranging from smallholders to large-scale operators, represent the primary end-users, applying foliar sprays across diverse crop types. Their decisions are influenced by crop specific needs and cost-effectiveness.
- Greenhouses:Controlled environment agriculture operations utilize foliar sprays for precise nutrient delivery, disease prevention, and growth management. The controlled conditions enable highly targeted and efficient application.
- Agricultural Cooperatives:These organizations aggregate demand from multiple farmers, often providing bulk purchasing and advisory services for foliar products.
- Contract Growers:Growers operating under contracts for specific crops adhere to strict quality and yield parameters, often relying on specialized foliar programs.
- Nurseries:Young plant production in nurseries uses foliar sprays for rapid nutrient uptake and robust seedling development before transplanting.
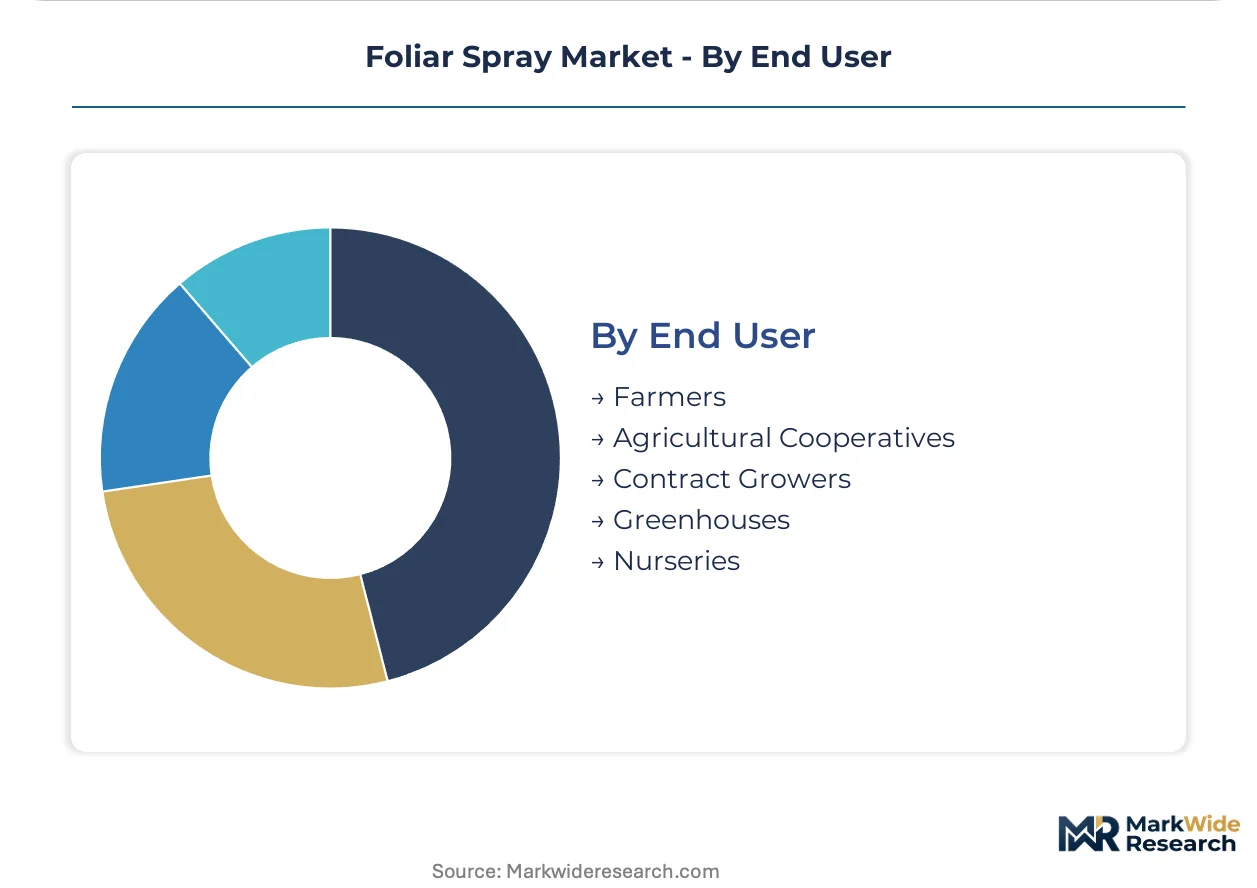
Farmers represent the largest consumer base, with Greenhouses demonstrating accelerated demand for specialized products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's vast agricultural lands drive significant demand for foliar sprays, particularly in large-scale soybean and sugarcane farming operations. This agricultural powerhouse prioritizes nutrient precision to maximize yields. Global market dynamics reflect diverse regional agricultural practices and regulatory landscapes.
Brazil
Brazil's extensive soybean and sugarcane cultivation demands efficient nutrient delivery for optimal yields. ANVISA sets strict limits on pesticide residues, influencing formulation choices for export crops. Mato Grosso's agricultural heartland sees heavy adoption of chelated micronutrients for enhanced crop performance.
United States
Large-scale row crop operations in the United States require foliar applications for micronutrient correction and yield enhancement. The USDA promotes sustainable farming practices, encouraging efficient nutrient use and reduced environmental impact. The Corn Belt region widely uses data-driven agronomic service models for customized spray prescriptions.
Germany
The cereals and oilseeds sector in Germany heavily invests in targeted foliar nutrition to sustain yields while meeting environmental standards. The European Union's Farm to Fork Strategy mandates significant reductions in fertilizer use and nutrient losses. North Rhine-Westphalia's agricultural sector integrates advanced spray technologies to comply with these directives.
Spain
High-value fruit and vegetable cultivation in Spain drives demand for specialized foliar treatments, improving marketability and quality. The EU Green Deal incentivizes efficient nutrient management to minimize environmental runoff from agricultural activities. Andalusia's intensive horticulture utilizes precision foliar methods for rapid nutrient correction and enhanced crop quality.
Vietnam
Vietnam's expanding horticulture sector presents a significant growth frontier for advanced foliar products, particularly biostimulants. The country's Ministry of Agriculture and Rural Development supports sustainable farming initiatives to boost agricultural output. The Mekong Delta region shows increasing adoption of specialized formulations for high-density crop production.
Foliar Spray Market Key Industry Players
Global majors compete with regional champions across product portfolio breadth and distribution reach. The market structure exhibits a tiered consolidation, with large diversified agricultural input providers alongside specialized nutrient formulators. Strategic archetypes include integrated chemical companies, dedicated fertilizer producers, and innovative biostimulant developers. Companies pursue portfolio diversification, geographic expansion, and R&D investment to secure market share.
Specialists in advanced nutrient delivery include Yara International ASA, which exemplifies a focus on an extensive portfolio of specialty nutrients, capturing value shifts towards precision application in high-value crops. Nutrien Ltd. represents a vertically integrated player, leveraging its vast distribution network to supply both conventional and specialty foliar products across diverse agricultural regions, from large-scale row crops to horticulture. BASF SE occupies a position as an innovation-driven entity, differentiating through its research and development in advanced adjuvant and surfactant technologies that enhance formulation efficacy and leaf adhesion, particularly in complex regulatory environments. These entities collectively anchor different strategic approaches within the competitive landscape, from broad market reach and supply chain control to specialized technological leadership and product differentiation.
| Leading Market Players |
|---|
| Yara International ASA |
| Nutrien Ltd. |
| BASF SE |
| Syngenta AG |
| The Mosaic Company |
| Coromandel International Limited |
| Eurochem Group |
| Israel Chemicals Ltd |
| UPL Limited |
| Others |
Cost & Logistics Intelligence
Large diversified agricultural input providers often dictate supply behavior and pricing discipline in the foliar spray market. Their extensive reach and product portfolios influence market stability and cost structures.
Pricing Analysis
Input-cost pass-through directly impacts foliar spray product pricing, especially for petroleum-derived adjuvants. The market primarily utilizes a value-based pricing model for specialized formulations and a per-unit transactional model for conventional products. Price differentiation stems from formulation efficacy, such as advanced microemulsions, and specialized agronomic support. Pricing pressure stems from fluctuating global oil markets affecting adjuvant costs. Large-scale row crop farmers exhibit higher price sensitivity, while high-value fruit and vegetable growers prioritize performance over cost.
Supply Chain Analysis
Single-source vulnerability sits with key chemical intermediates sourced from a few global suppliers, primarily in China and Europe. The foliar spray supply chain relies on essential raw materials like chelating agents, micronutrient salts, and petroleum-derived surfactants. Commodity price volatility for these chemical inputs represents a structural risk to manufacturer margins. Distribution runs through established agricultural cooperatives and direct sales channels to large-scale farming operations globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foliar spray market presents a geographic-arbitrage play, driven by diverging regulatory frameworks between the European Union and other major agricultural regions. Manufacturers can optimize formulation development for specific compliance landscapes.
For Market Incumbents:To counter increasing regulatory divergence and the rise of specialized biostimulant players, incumbents must prioritize R&D investment. They should develop advanced, compliant formulations for diverse regional markets and strategically acquire innovative biostimulant developers. This reinforces market presence, leveraging existing customer relationships and agronomic expertise.
For New Entrants and Emerging Players:E-commerce platforms offer a direct route for new entrants to reach growers in underpenetrated markets. They should target specialized biostimulant formulations for controlled environment agriculture and expand into Southeast Asia's horticulture sector. A data-driven agronomic service model, providing customized spray prescriptions, creates a compelling go-to-market angle.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized nutrient formulators with proprietary technology in emerging application areas. The long-term viability of this market is anchored in the global shift towards precision agriculture and sustainable nutrient management. Investors should target innovative biostimulant developers or firms possessing advanced nano-encapsulation technology. Increased regulatory incentives for bio-based inputs will signal a market inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D for Biostimulant Integration | Enhances crop stress tolerance and growth in controlled environments, meeting sustainability goals. |
| Geographic Expansion into Southeast Asia | Captures demand from an expanding horticulture sector underpenetrated by advanced products. |
| Investment in Nano-encapsulation Technology | Enables controlled release of nutrients, maximizing availability for high-value specialty crops. |
| Development of Data-driven Agronomic Services | Provides customized spray prescriptions, moving beyond product transactions to integrated solutions. |
| Supply Chain Diversification for Adjuvants | Mitigates commodity price volatility and single-source risks for critical formulation components. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with extensive secondary validation. Primary interviews engaged agronomists, R&D directors, procurement managers from large agricultural operations, and regulatory affairs specialists. Secondary data sources included USDA reports, ECHA databases, ANVISA publications, and specialized crop science journals. This approach facilitated bottom-up and top-down triangulation for robust market sizing.
Segment-weighting across product type, application crop, technology, end-user, and regional regulatory compliance defined the analytical framework. Market volumes and values were projected over the projection horizon, with CAGRs derived from historical growth patterns and anticipated demand shifts. Key industry-specific forecast inputs included global crop acreage trends and evolving environmental policy frameworks.
Regulatory policy shifts, commodity price volatility, and climate change impacts are the dominant revision risks for market forecasts. All projections reflect a set of underlying assumptions about technology adoption and agricultural practices. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Field Marking Paint Market