
 North America Plant Growth Regulators Market | 2026-2036
North America Plant Growth Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plant Growth Regulators Market Outlook
Biostimulant-compatible formulation revenue is rewriting margin allocation across the North America Plant Growth Regulators Market. Bayer Crop Science leverages its seed treatment integration to bundle regulators with germplasm platforms. Valent Biosciences LLC anchors its position through fermentation-derived auxin production. Corteva Agriscience competes via its precision agriculture digital layering that ties regulator timing to sensor data.
Plant growth regulators are organic compounds, either natural or synthetic, that modify physiological processes such as cell division, elongation, and fruit ripening at concentrations below those required for nutrition; auxins like indole-3-acetic acid function at parts-per-million doses to govern apical dominance and root initiation in commercial crop systems. Cytokinins command the fastest expansion among product types as greenhouse operators adopt them for post-harvest shelf-life extension in leafy greens. Liquid formulations dominate volume throughput due to compatibility with drip irrigation and aerial application infrastructure across large-scale corn and soybean operations. The turf management application segment sustains premium pricing through golf course and municipal sports field contracts that specify performance-based outcomes.
The EPA governs plant growth regulators under FIFRA pesticide registration pathways, while Health Canada's PMRA imposes parallel data requirements that shape cross-border product development timelines. The USDA's organic certification standards under the National Organic Program restrict synthetic regulator use, creating parallel demand channels for bio-based alternatives. Stakeholders must monitor pending biopesticide classification rulings that could restructure competitive access for microbial-derived cytokinin products.
Market Dynamics
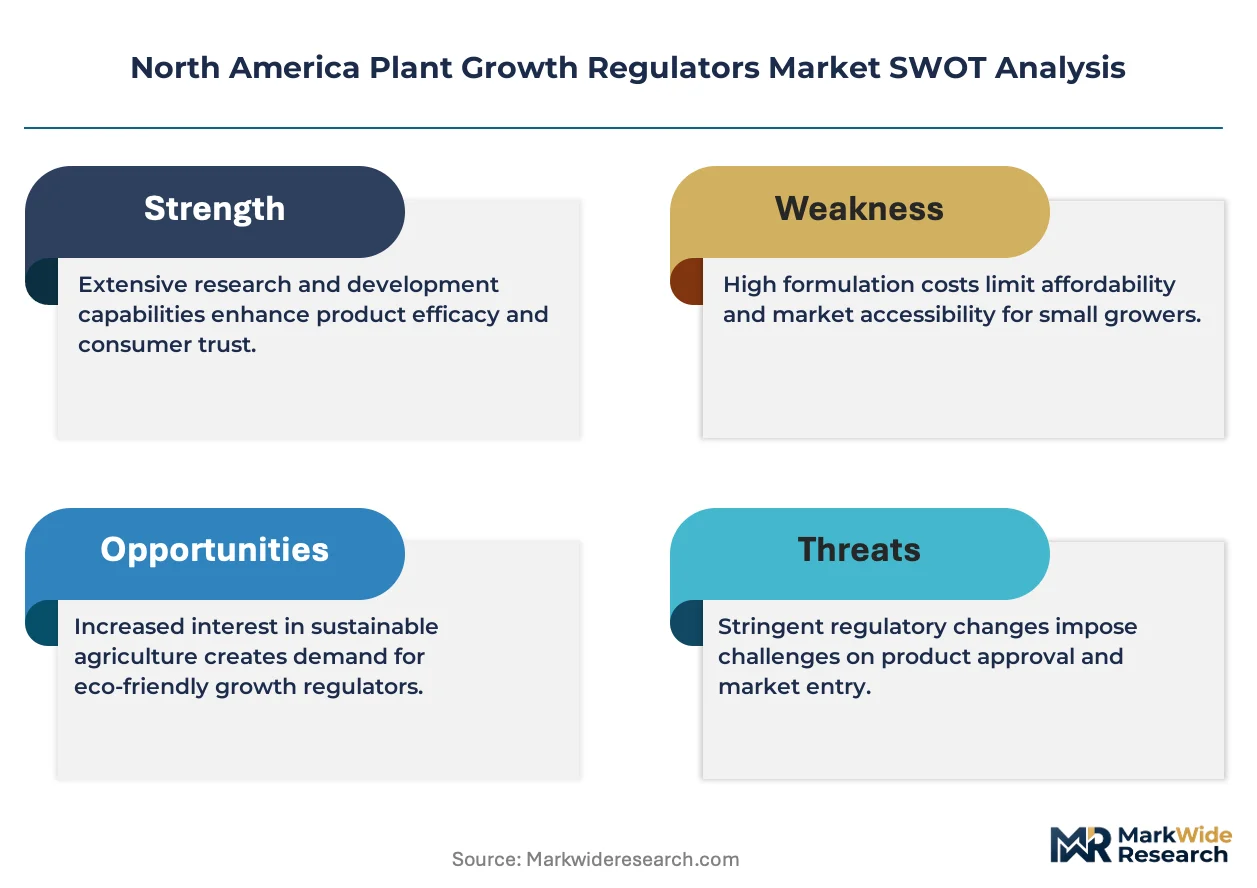
The EPA's biopesticide re-registration pathway is forcing R&D budget reallocation toward fermentation-derived formulations, compressing synthetic chemistry pipelines while expanding microbial production capacity.
Growth Catalysts
- Greenhouse Vegetable Expansion:Ontario and British Columbia operators are scaling cytokinin applications for post-harvest shelf-life extension in leafy greens, creating concentrated demand nodes.
- Precision Agriculture Integration:Sensor-driven regulator timing systems tie application schedules to real-time crop stress indicators, improving input efficiency for large-scale corn and soybean operations.
- USDA Organic Certification Pathways:The National Organic Program's synthetic restriction creates parallel commercial channels for bio-based auxin alternatives, opening premium pricing tiers.
Market Restraints
- FIFRA Registration Timelines:EPA data requirements for novel formulations extend development cycles, freezing capital in multi-year approval processes.
- Active Ingredient Concentration Risk:Cytokinin supply depends on concentrated fermentation capacity in specific biomanufacturing clusters, creating geographic vulnerability.
- Application Equipment Compatibility:Legacy aerial spray infrastructure limits adoption of next-generation nano-emulsion formulations requiring modified nozzle specifications.
Strategic Opportunities
- Florida Specialty Crop Penetration:Citrus and strawberry growers remain underpenetrated for stress-tolerance regulators, offering expansion headroom beyond California's mature adoption curve.
- Health Canada PMRA Harmonization:Cross-border label alignment initiatives could compress dual-registration costs for products entering both US and Canadian markets.
- Seed Treatment Convergence:Coating technologies that embed regulators directly onto germplasm create bundled value propositions distinct from standalone foliar applications.
Industry Challenges
- Formulation Chemistry Talent Scarcity:The specialized skill set bridging plant physiology and fermentation engineering commands premium compensation, constraining mid-tier manufacturer expansion.
- Digital Infrastructure Integration:Legacy farm management software lacks API compatibility with emerging regulator-prescription algorithms, forcing costly system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plant Growth Regulators Market |
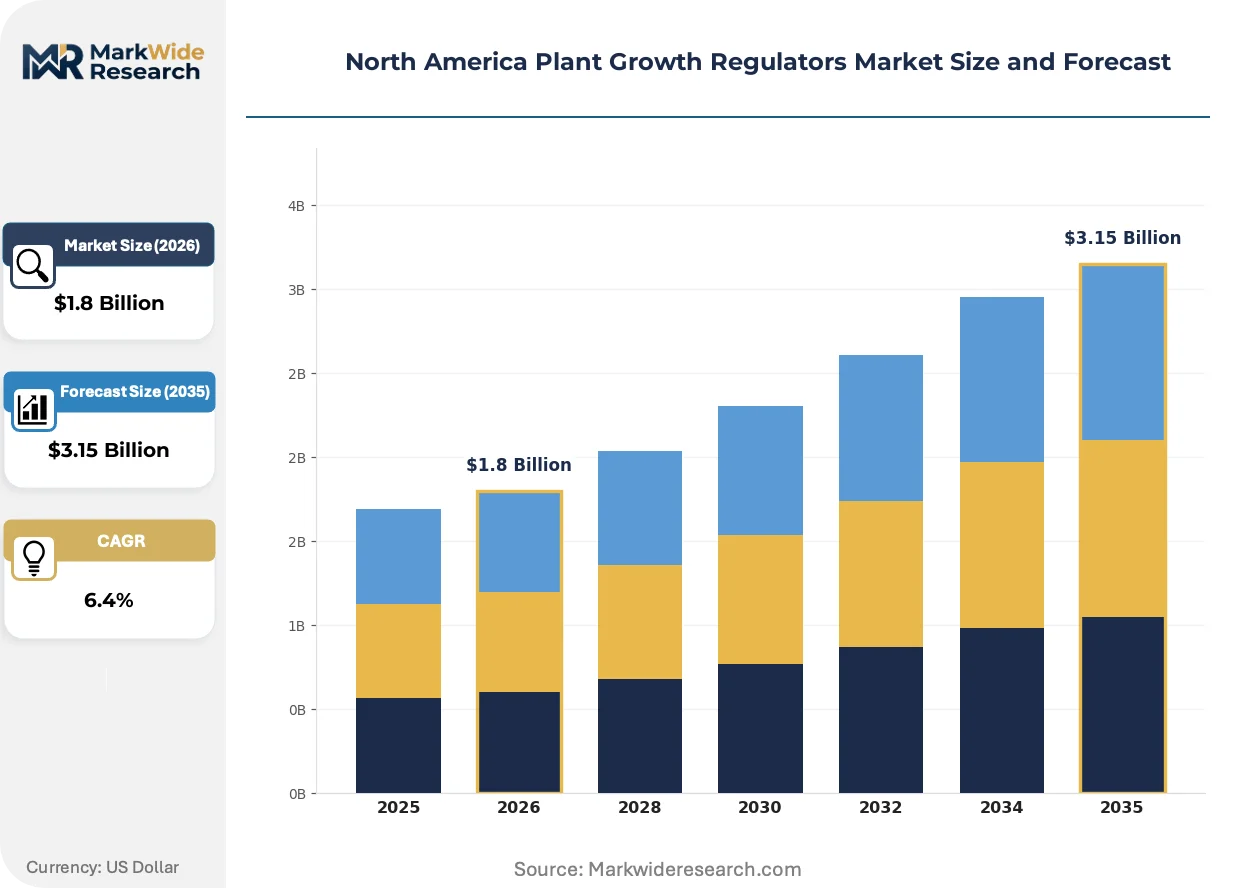
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auxins, Gibberellins, Cytokinins, Ethylene Application: Agriculture, Horticulture, Turf Management, Forestry Formulation Type: Liquid, Granular, Powder, Emulsifiable Concentrate End User: Farmers, Nurseries, Greenhouses, Research Institutions |
| Companies Covered | Bayer Crop Science, ADAMA Agricultural Solutions Ltd, Corteva Agriscience, Nufarm Ltd, Syngenta AG, BASF SE, FMC Corporation, Fine Americas Inc., Valent Biosciences LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plant Growth Regulators Market Strategic Shifts
Biological manufacturing methods are overtaking synthetic chemistry as the dominant production paradigm, with implications for regulatory classification, margin structure, and competitive positioning across the value chain.
Microbial fermentation for cytokinin production is migrating from pilot-scale facilities to commercial bioreactor networks. Midwest contract manufacturers are expanding capacity to serve agricultural input companies seeking EPA biopesticide classifications. This shift compresses synthetic chemistry margins while rewarding firms with in-house fermentation expertise.
The EPA's pending rulings on microbial-derived product classifications are restructuring market access pathways. Formulations meeting biopesticide criteria face streamlined review timelines compared to conventional chemical registrations. California specialty crop registrants are prioritizing submissions that qualify for this accelerated pathway.
Performance-based contracting is displacing volume-based procurement in turf management segments. Municipal sports field operators and golf course superintendents now specify measurable outcomes—root density thresholds, color index scores—rather than purchasing active ingredient volumes. This model concentrates in Florida and Arizona markets with year-round growing seasons.
North America Plant Growth Regulators Market Segmentation
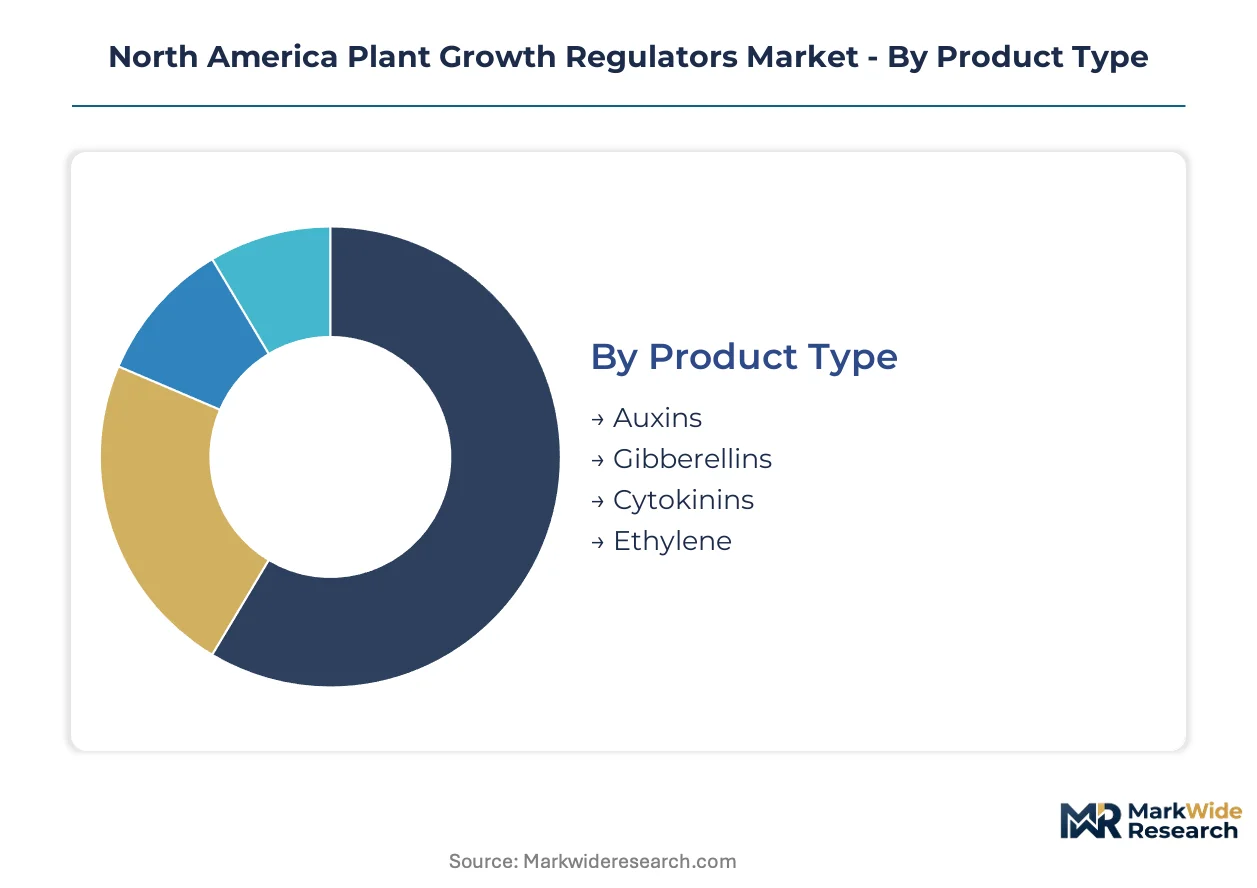
Segmentation in the North America Plant Growth Regulators Market exposes divergent service requirements across product chemistry, application setting, and end-user sophistication. Technical support intensity varies sharply between greenhouse operators demanding precision timing guidance and commodity row-crop farmers seeking bulk logistics efficiency.
Product Type:
After-sales service intensity escalates with formulation complexity and regulatory classification uncertainty.
- Cytokinins:Fermentation-derived cytokinins require specialized storage protocols and shelf-life monitoring. Ontario and British Columbia greenhouse operators drive demand for post-harvest shelf-life extension in leafy greens, with EPA biopesticide classification rulings creating advisory service backlogs.
- Auxins:Synthetic auxin formulations face tightening residue monitoring requirements. California specialty crop growers anchor volume demand for root initiation and apical dominance management, though USDA organic certification restrictions are redirecting inquiries toward bio-based alternatives.
- Gibberellins:Heat-sensitive gibberellin concentrates demand cold-chain logistics support across Florida citrus and strawberry districts.
- Ethylene:Gaseous ethylene application systems require equipment calibration services concentrated in tomato ripening facilities.
By volume, auxins lead. By growth pace, cytokinins are expanding most quickly.
Application:
Cost tier stratification separates premium horticulture services from commodity agriculture procurement.
- Agriculture:Large-scale corn and soybean operations in the Midwest prioritize volume pricing and aerial application compatibility. Precision agriculture integration ties regulator timing to sensor data, raising digital infrastructure requirements.
- Horticulture:Greenhouse vegetable producers in Ontario and British Columbia specify performance outcomes and demand intensive technical consultation. Cytokinin adoption for stress tolerance and shelf-life extension commands premium service contracts.
- Turf Management:Florida and Arizona golf courses specify root density thresholds and color index scores rather than active ingredient volumes.
- Forestry:Nursery stock producers in the Pacific Northwest require seasonal application windows and reforestation project coordination.
Agriculture dominates volume throughput. Horticulture captures the steepest margin expansion.
Formulation Type:
Customer type dictates formulation preference, with equipment legacy constraining nano-emulsion adoption.
- Liquid:Drip irrigation and aerial spray infrastructure across large-scale operations favors liquid compatibility. Modified nozzle specifications for next-generation nano-emulsions are forcing equipment upgrade decisions.
- Granular:Soil-incorporated granular formulations serve turf management segments with controlled-release requirements.
- Powder:Research institutions and small-scale nurseries prefer powder reconstitution for experimental flexibility.
- Emulsifiable Concentrate:Specialty crop penetrants in California and Florida citrus districts favor emulsifiable concentrate tank-mix compatibility.
Liquid formulations lead by volume. Emulsifiable concentrate applications are gaining share fastest in specialty crop districts.
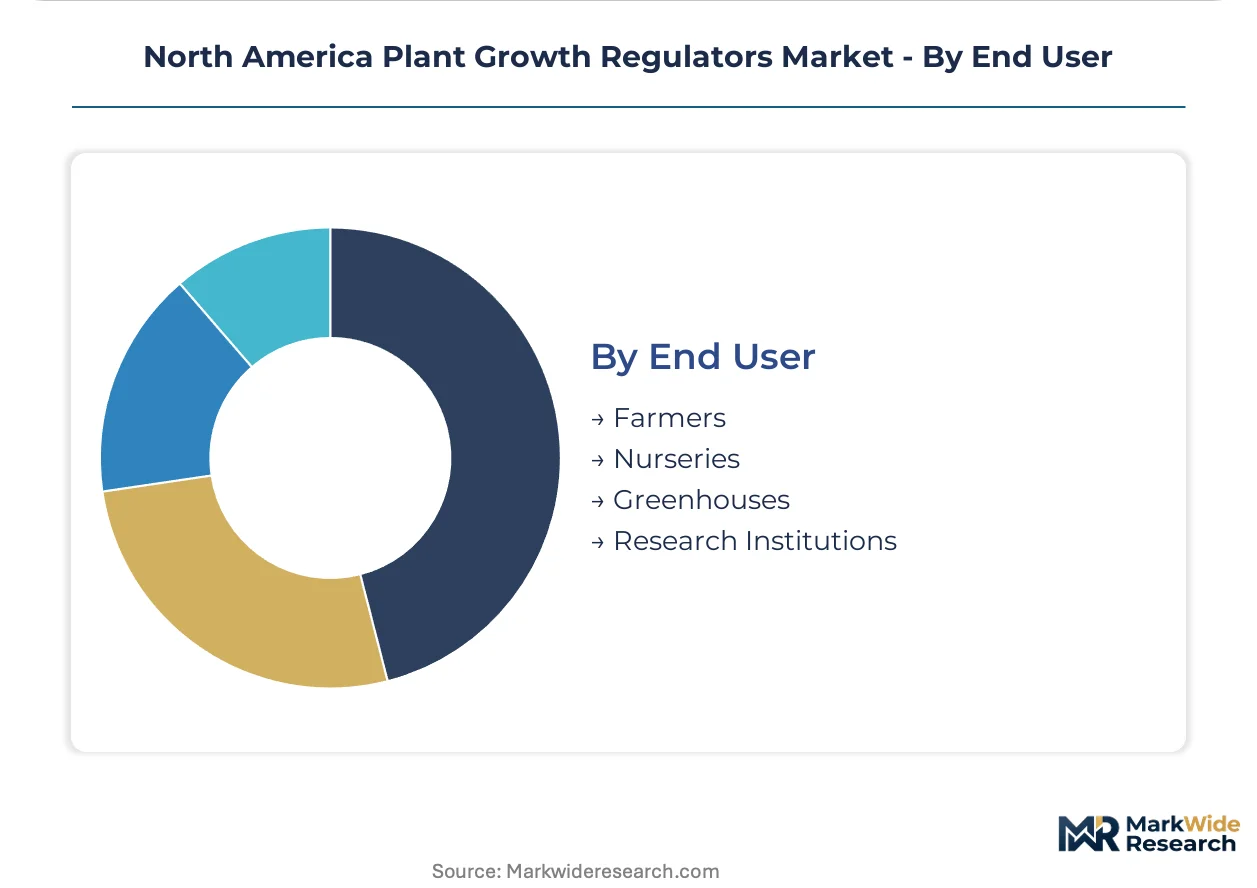
End User:
Supply concentration in fermentation capacity shapes service reach and geographic coverage priorities.
- Farmers:Midwest row-crop operators and California specialty crop growers anchor bulk demand. FIFRA registration timeline uncertainty extends capital commitment cycles and intensifies regulatory advisory needs.
- Greenhouses:Ontario and British Columbia operators concentrate cytokinin demand for post-harvest protocols. Technical service intensity peaks here with climate control integration requirements.
- Nurseries:Container stock producers require seasonal timing optimization and root establishment protocols.
- Research Institutions:University extension programs and agricultural experiment stations drive experimental formulation trials and biopesticide classification data generation.
Farmers represent the largest volume segment. Greenhouses are climbing the fastest on cytokinin adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest commodity growers exhibit the highest price elasticity, squeezing margins on bulk auxin formulations, while Ontario greenhouse operators absorb premium cytokinin pricing for post-harvest shelf-life protocols.
United States
California specialty crop growers anchor cytokinin demand for stress tolerance in citrus and strawberry districts, with Florida operations expanding adoption. The EPA's FIFRA registration pathways and pending biopesticide classification rulings are redirecting R&D budgets toward fermentation-derived formulations. Midwest corn and soybean belt states concentrate liquid formulation volume through aerial application infrastructure.
Canada
Ontario and British Columbia greenhouse vegetable operators drive the fastest cytokinin adoption for leafy greens shelf-life extension. Health Canada's PMRA imposes parallel data requirements to EPA FIFRA, shaping cross-border product development timelines. Prairie provinces sustain granular formulation demand through large-scale wheat and canola operations.
Mexico
Sinaloa and Baja California vegetable export zones generate concentrated demand for ethylene-based ripening systems in tomato and avocado supply chains. Mexico's national agricultural health regulator, SENASICA, coordinates with EPA-equivalent standards for residue monitoring. Jalisco berry districts are emerging as a testing ground for precision agriculture-integrated regulator timing.
North America Plant Growth Regulators Market Competitive Environment
Capability concentration sits with fermentation-derived specialists; scale advantage sits with integrated crop science conglomerates. The market structures around three tiers: global agrochemical majors with seed treatment integration, dedicated plant physiology specialists with biomanufacturing expertise, and regional formulators serving specialty crop districts. Dominant competitive moves include co-development partnerships between microbial fermentation houses and precision agriculture platforms, plus portfolio diversification into biostimulant-compatible formulation chemistries.
Within the integrated agrochemical tier, Bayer Crop Science and Corteva Agriscience occupy positions that bundle regulators with germplasm and digital agriculture platforms. Among dedicated biological specialists, Valent Biosciences LLC exemplifies the fermentation-derived production archetype. ADAMA Agricultural Solutions Ltd represents the regional formulator model with established specialty crop penetration. These three patterns—conglomerate integration, biological specialization, and regional formulation—capture the competitive geometry without exhaustive player mapping.
| Leading Market Players |
|---|
| Bayer Crop Science |
| ADAMA Agricultural Solutions Ltd |
| Corteva Agriscience |
| Nufarm Ltd |
| Syngenta AG |
| BASF SE |
| FMC Corporation |
| Fine Americas Inc. |
| Valent Biosciences LLC |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Midwest contract fermentation facilities is compressing synthetic auxin margins while elevating pricing power for microbial-derived cytokinin specialists serving Ontario greenhouse operators. This utilization asymmetry rewards biomanufacturing investments and penalizes legacy chemical synthesis assets across the value chain.
Pricing Analysis
Long-term offtake contracts dominate procurement between California specialty crop growers and fermentation-derived cytokinin suppliers, insulating premium tiers from spot-market volatility. Price differentiation rests on EPA biopesticide certification status and cold-chain logistics capability, with organic-certified formulations commanding substantial premia over conventional synthetic alternatives. Cost compression in bulk auxin segments is intensifying because Midwest row-crop operators prioritize volume scale over performance guarantees. Greenhouse vegetable producers exhibit the lowest price sensitivity, absorbing premium service bundling for climate-integrated application timing.
Supply Chain Analysis
Tariff exposure between US and Chinese fermentation equipment suppliers dominates capital expenditure planning for cytokinin production scale-ups. Active ingredient supply draws from US Midwest bioreactor networks, Canadian Prairie extraction facilities, and Mexican Sinaloa formulation plants. Raw material dependencies center on corn-derived feedstocks for microbial cultivation, specialized filtration membranes, and gaseous ethylene precursors. Single-source vulnerability concentrates in precision fermentation strain IP held by limited specialist houses. Distribution runs through agricultural input dealer networks with embedded technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as precision agriculture integration creates specialized niches for sensor-compatible formulation developers distinct from commodity bulk suppliers. USDA organic certification pathways and EPA biopesticide rulings are simultaneously opening premium channels and closing mass-market access for synthetic incumbents.
For Market Incumbents: Build regulatory data moats through early EPA biopesticide submission investments that freeze competitor access timelines. Consolidate fermentation capacity in Midwest biomanufacturing clusters to capture cytokinin supply concentration advantages. Synthetic chemistry specialists face substitution threat from microbial-derived alternatives; backward integration into strain development capabilities is the essential defensive lever. For New Entrants and Emerging Players: Florida citrus and strawberry districts represent underpenetrated territory for stress-tolerance regulator applications beyond California's mature adoption curve. Jalisco berry export zones in Mexico offer precision agriculture-integrated testing grounds with lower regulatory entry barriers. Seed treatment convergence creates white-space for coating technology specialists embedding regulators directly onto germplasm platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-derived production segments as commercial bioreactor networks replace pilot-scale facilities. Long-term viability favors acquisition targets with in-house strain libraries and EPA biopesticide registration expertise rather than standalone formulation houses. Monitor pending EPA microbial classification rulings as the critical signal for competitive access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Midwest bioreactor networks capture cytokinin supply concentration as synthetic margins compress. |
| EPA Biopesticide Registration Investment | Accelerated review timelines reward early submitters with frozen competitor access windows. |
| Precision Agriculture Platform Integration | Sensor-driven timing systems tie regulator prescriptions to real-time crop stress indicators. |
| Seed Treatment Convergence Development | Coating technologies embed regulators onto germplasm, creating bundled value propositions. |
| Health Canada PMRA Harmonization Pursuit | Cross-border label alignment compresses dual-registration costs for US-Canada product launches. |
Study Parameters
Desk research of EPA registration databases, USDA organic certification records, and Health Canada PMRA submission filings preceded structured interviews with fermentation facility operators, greenhouse technical directors, and agricultural input procurement managers. Primary fieldwork with California specialty crop growers and Ontario vegetable producers was cross-validated against customs trade data and SEC filings from listed agrochemical conglomerates. Bottom-up volume estimates from application rate assumptions were triangulated against top-down market sizing from input supplier revenue disclosures.
Assumptions regarding EPA biopesticide classification timeline acceleration and Health Canada PMRA harmonization progress were held fixed across scenarios, while fermentation capacity expansion rates and precision agriculture adoption curves were varied. Segmentation modeling captured product type, application setting, formulation chemistry, and end-user sophistication dimensions. CAGRs were derived from regression analysis of historical input volume trends projected against acreage expansion and application intensity assumptions. Industry-specific forecast inputs included greenhouse vegetable acreage growth in Ontario and British Columbia and citrus stress-tolerance adoption rates in Florida.
Practitioners should monitor pending EPA microbial-derived product classification rulings and Health Canada PMRA review timeline changes for early signals of competitive access restructuring. Forecasts reflect assumptions regarding regulatory pathway stability and fermentation capacity commissioning schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market