
 Germany Commercial Construction Market | 2026-2036
Germany Commercial Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Commercial Construction Market Insights
The German Building Energy Act (GEG) is decoupling low-efficiency developers from viable project pipelines by mandating near-zero-energy performance for new commercial structures. HOCHTIEF Aktiengesellschaft leverages its integrated engineering capacity to deliver GEG-compliant office towers at speed. Strabag SE anchors its position through heavy civil expertise tied to transport-linked commercial zones. GOLDBECK GmbH specializes in prefabricated concrete systems that compress construction schedules for warehouse clients.
Germany commercial construction encompasses the design, engineering, and erection of non-residential structures including offices, retail centers, logistics facilities, and hotels, typically employing reinforced concrete frames with steel composite decking to achieve spans exceeding twelve meters for open-plan flexibility. The primary purpose is creating revenue-generating built assets that meet tenant specifications for energy performance, floor-load capacity, and digital infrastructure integration. Office buildings command the deepest margin pools as corporations in Frankfurt and Munich prioritize Class-A space with smart-building certification, while warehouses represent the fastest-growing construction type as e-commerce fulfillment networks expand along the A3 and A7 autobahn corridors. Wood as a structural material is gaining share in mid-rise commercial projects where hybrid timber-concrete slabs satisfy both GEG thermal requirements and corporate sustainability reporting obligations.
KBA construction guidelines, the EU Green Deal taxonomy for sustainable finance, and DGNB certification standards collectively reshape which projects secure financing and tenant commitments in Germany. DGNB criteria now filter institutional investor mandates, directing capital toward developers with verified lifecycle carbon data. Stakeholders must monitor how the EU AI Act's building-management system provisions will alter MEP specification requirements before the next procurement cycle.
Market Dynamics
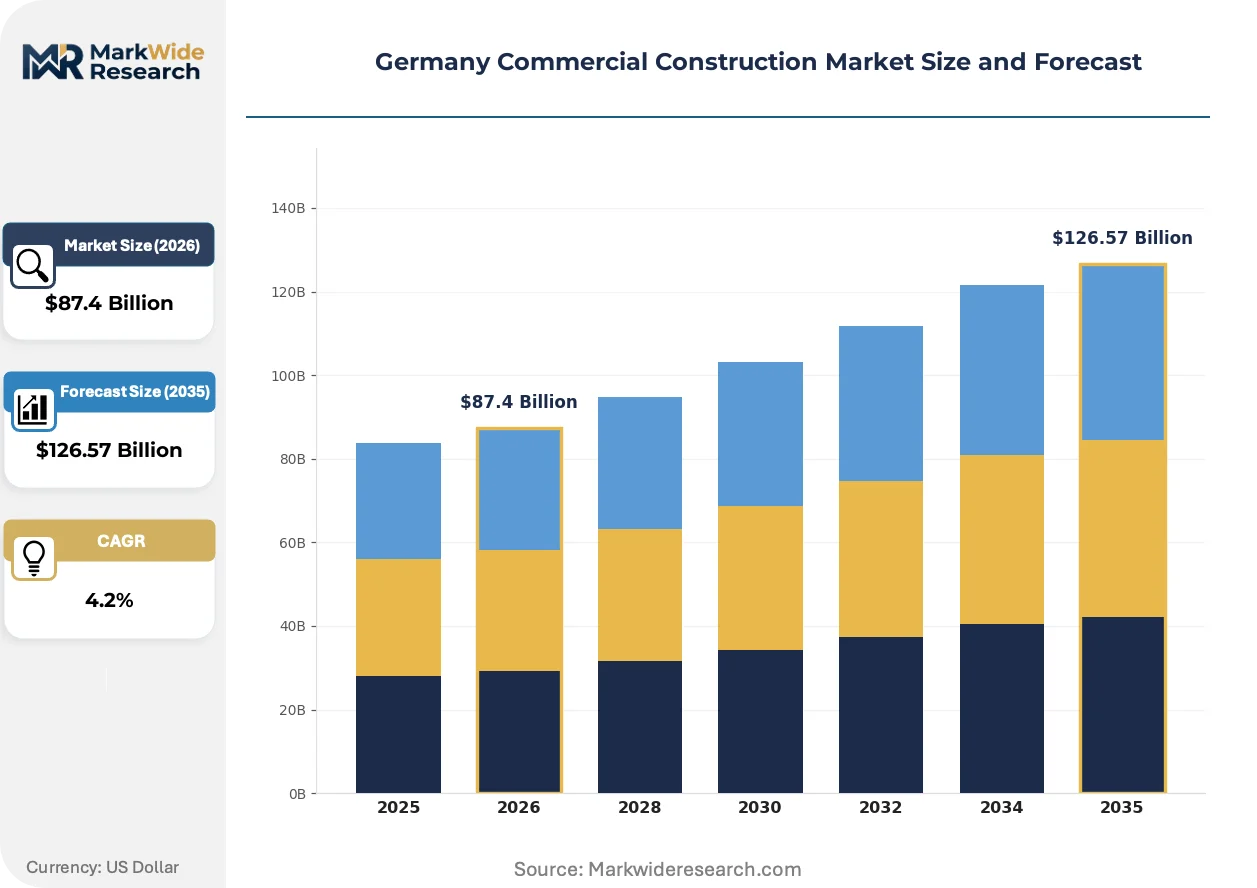
The Germany Commercial Construction Market operates under intense regulatory compression as the Building Energy Act (GEG) rewrites feasibility calculations for conventional development models. Developers must now front-load capital into thermal envelope performance and renewable integration before securing tenant commitments, fundamentally altering project finance structures and contractor selection criteria.
Growth Catalysts
- Logistics corridor densification:E-commerce fulfillment networks are expanding warehouse footprints along the A3 and A7 autobahn corridors, generating sustained demand for high-bay concrete structures with heavy floor-loading capacity.
- EU Green Deal taxonomy alignment:Institutional capital mandates now require DGNB certification or equivalent lifecycle carbon documentation, directing financing toward developers with verified sustainability data.
- Hybrid timber-concrete systems:Mid-rise commercial projects in Berlin and Munich are adopting engineered wood composites to satisfy GEG thermal requirements while meeting corporate ESG reporting obligations.
Market Restraints
- Steel and cement input volatility:Energy-intensive material production faces carbon cost pass-through under EU Emissions Trading System rules, compressing margins on fixed-price contracts.
- Specialized contractor concentration:GEG-compliant MEP installation capacity clusters in the Rhine-Ruhr and Bavaria regions, creating bottleneck risks for projects in eastern federal states.
- Technical limitation in deep renovation:Existing commercial stock built before 1990 presents structural constraints for achieving near-zero-energy retrofits without complete facade replacement.
Strategic Opportunities
- Eastern federal state underpenetration:Saxony and Thuringia hold aging industrial zones with below-replacement commercial stock, offering first-mover advantages for GEG-compliant speculative development.
- EU AI Act building management integration:Smart-building system providers can capture specification requirements by embedding predictive HVAC control algorithms into new office towers before the next procurement cycle.
- Modular prefabrication convergence:Factory-produced concrete core units combined with on-site timber infill panels are compressing construction schedules for warehouse clients with tight occupancy deadlines.
Industry Challenges
- Certified energy auditor scarcity:GEG compliance documentation requires qualified professionals to model building performance, yet training pipeline output lags project application volume in secondary cities.
- Legacy system integration friction:Smart-building sensor networks must interface with existing tenant IT infrastructure, creating commissioning delays and cost overruns in Frankfurt financial district retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Commercial Construction Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $126.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Office Buildings, Retail Spaces, Warehouses, Hospitality Material: Steel, Concrete, Glass, Wood End User: Corporations, Government Agencies, Nonprofits, Educational Institutions Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | HOCHTIEF Aktiengesellschaft, Strabag SE, GOLDBECK GmbH, Ed. Züblin AG, Leonhard Weiss GmbH & Co. KG, BAM Deutschland AG, Max Bögl Bauservice GmbH & Co. KG, Bilfinger SE, AUG. PRIEN Bauunternehmung GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Commercial Construction Market Trends and Innovations
Digital fabrication and material science advances are compressing traditional construction timelines while regulatory mandates force simultaneous performance upgrades. Three interconnected developments are restructuring how commercial assets reach market.
Building information modeling (BIM) coupled with robotic prefabrication is decentralizing project execution away from centralized general contracting models. Mid-size developers in Stuttgart and Hamburg are adopting platform-based coordination tools that distribute design authority to specialized fabricators. This shift compresses decision chains and reduces on-site labor dependency for repetitive structural elements.
KBA construction guidelines now interface directly with EU taxonomy disclosure requirements, forcing transport-linked commercial zones to document embodied carbon across supply chains. Developers along the Rhine-Ruhr corridor must now source steel and concrete with verified Environmental Product Declarations to secure institutional financing. The regulatory stack is filtering out developers lacking lifecycle data infrastructure.
Tenant specification processes now prioritize performance guarantees over capital cost minimization, particularly in Munich's corporate headquarters market. Corporate real estate teams are contracting for energy outcome commitments rather than fixed system specifications, transferring operational risk to contractors with integrated design-build capabilities. This behavioral pivot favors vertically capable firms over traditional bid-based procurement in premium office segments.
Germany Commercial Construction Market Segmentation
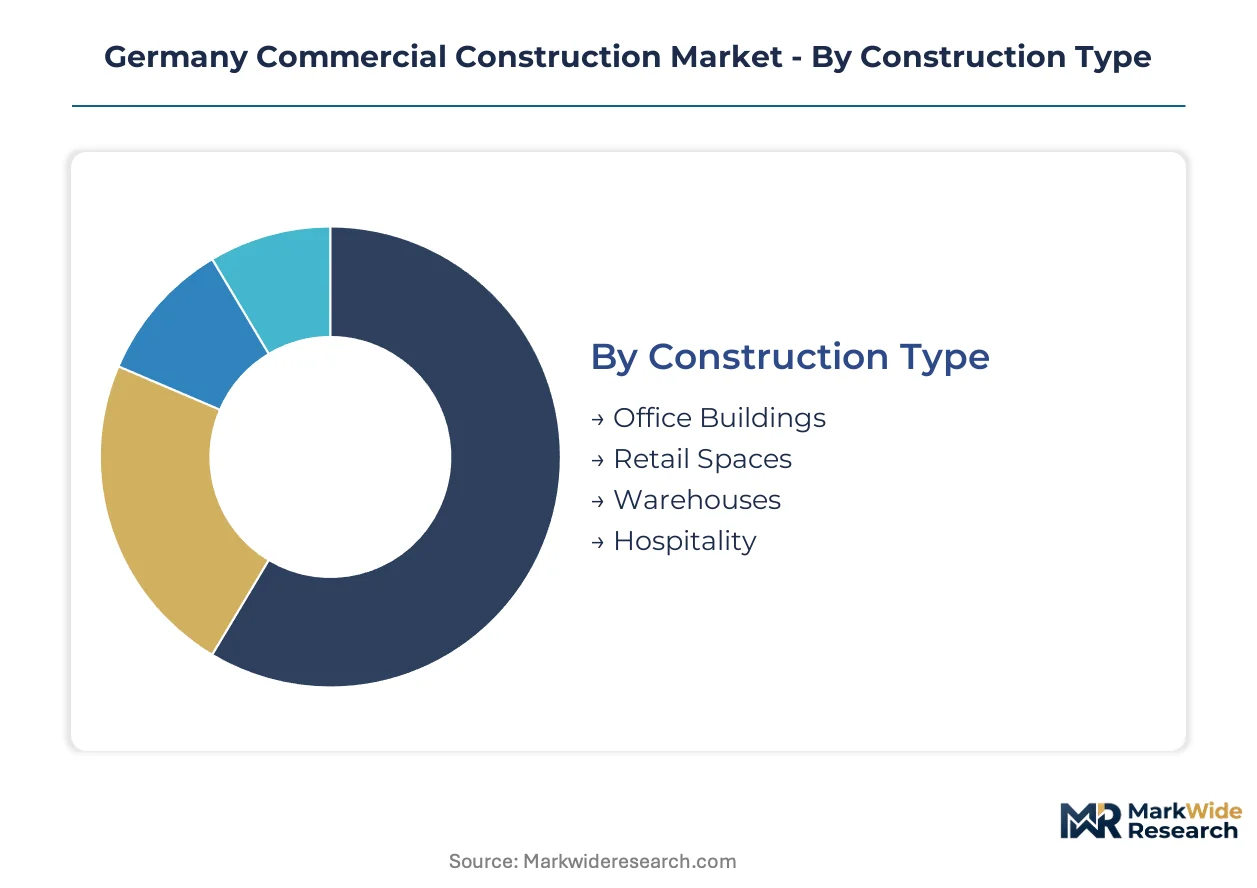
Segmentation in the Germany Commercial Construction Market reveals how regulatory mandates and tenant specifications reshape contractor capabilities across distinct project categories. Differential compliance burdens and financing access create divergent margin profiles that reward specialized positioning.
Construction Type:
Standalone developments dominate capital deployment, while embedded mixed-use configurations concentrate in urban core revitalization zones.
- Office Buildings:Reinforced concrete frames with steel composite decking achieve spans exceeding twelve meters for open-plan flexibility. Frankfurt financial sector and Munich corporate headquarters prioritize Class-A space with DGNB certification and smart-building integration.
- Warehouses:High-bay concrete structures with heavy floor-loading capacity serve e-commerce fulfillment networks. Demand clusters along the A3 and A7 autobahn corridors where logistics developers expand footprints near the Rhine-Ruhr corridor.
- Retail Spaces:Hybrid configurations combining experiential showrooms with last-mile distribution nodes adapt to omnichannel retail models.
- Hospitality:Boutique and extended-stay formats incorporate GEG thermal envelope standards with modular prefabrication for compressed schedules.
Volume placements concentrate in Warehouses; the faster expansion belongs to Office Buildings.
Material:
Cost tiers separate legacy systems from next-generation composites, with premium grades commanding specification priority in institutional mandates.
- Concrete:Factory-produced core units compress construction schedules while meeting heavy floor-loading requirements for logistics clients. Rhine-Ruhr corridor developers source mixes with verified Environmental Product Declarations to satisfy EU Green Deal taxonomy alignment.
- Wood:Engineered timber-concrete hybrid slabs satisfy GEG thermal requirements in mid-rise commercial projects. Berlin and Munich corporate sustainability reporting obligations drive specification for hybrid systems.
- Steel:Carbon-intensive production faces EU Emissions Trading System cost pass-through, compressing margins on fixed-price contracts.
- Glass:High-performance curtain wall assemblies integrate photovoltaic elements for near-zero-energy facade compliance.
Concrete retains dominant volume share; engineered Wood climbs the fastest as ESG mandates harden.
End User:
Customer type determines procurement sophistication, with institutional buyers extracting performance guarantees unavailable to fragmented private purchasers.
- Corporations:Contract for energy outcome commitments rather than fixed system specifications. Munich and Frankfurt corporate real estate teams transfer operational risk to contractors with integrated design-build capabilities.
- Government Agencies:Federal and state procurement mandates DGNB certification with lifecycle carbon documentation for public buildings.
- Educational Institutions:University expansion projects in Bavaria and Baden-Württemberg prioritize hybrid timber systems for visible sustainability signaling.
- Nonprofits:Limited capital access restricts project scale, favoring modular prefabrication for cost containment.
Corporations anchor premium segment volume; Educational Institutions show steepest specification upgrade trajectory.
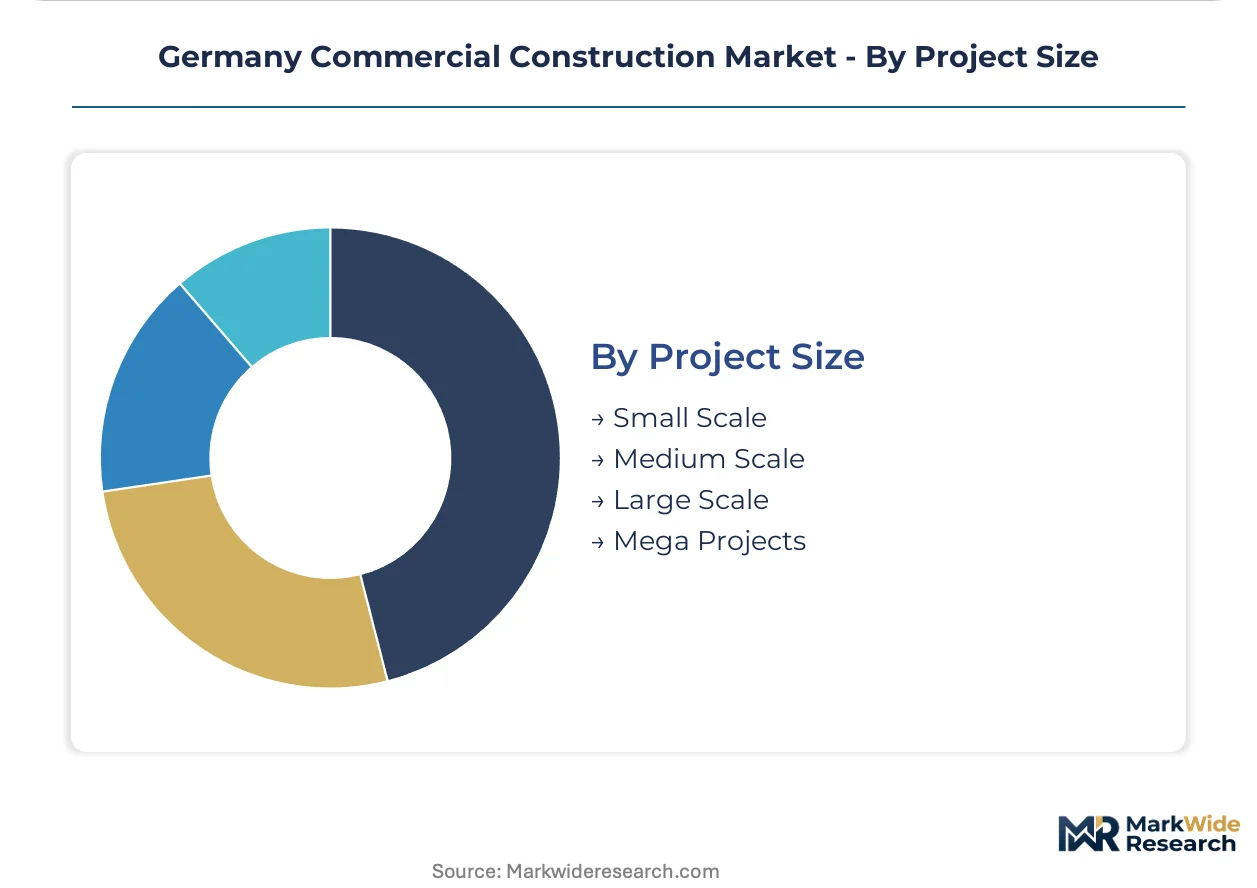
Project Size:
Scale thresholds determine contractor eligibility, with mega-project capacity concentrating among vertically integrated national firms.
- Large Scale:Integrated engineering delivery models compress decision chains for complex commercial towers. Stuttgart and Hamburg developers adopt platform-based coordination tools that distribute design authority to specialized fabricators.
- Mega Projects:Berlin commercial district revitalization and Frankfurt financial sector office modernization require consolidated contracting entities with GEG compliance documentation capabilities.
- Medium Scale:Mid-rise commercial projects in secondary cities face certified energy auditor scarcity, creating bottleneck risks.
- Small Scale:Fragmented owner base limits standardization, though modular prefabrication penetrates warehouse fit-out segments.
Large Scale developments absorb dominant capital deployment; Mega Projects gain share fastest as urban core densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in western and southern federal states where logistics corridors intersect with corporate headquarters clusters. The Rhine-Ruhr corridor and Bavarian metropolitan zones absorb disproportionate capital deployment. Eastern states present underpenetrated catchment zones for GEG-compliant speculative development.
North Rhine-Westphalia
The Rhine-Ruhr logistics corridor drives warehouse construction for e-commerce fulfillment networks. KBA construction guidelines enforce strict documentation for transport-linked commercial zones. Düsseldorf and Cologne host dense contractor ecosystems specializing in high-bay concrete structures with heavy floor-loading capacity.
Bavaria
Munich's corporate headquarters market commands premium office development with DGNB certification requirements. The Building Energy Act mandates near-zero-energy performance for new commercial structures in this high-visibility market. Stuttgart and Nuremberg anchor secondary demand nodes for mid-rise hybrid timber projects.
Baden-Württemberg
Automotive supplier networks generate industrial facility demand alongside Stuttgart's platform-based coordination tool adoption. EU Green Deal taxonomy alignment pressures developers to source steel and concrete with verified Environmental Product Declarations. Karlsruhe and Mannheim concentrate prefabrication expertise for compressed construction schedules.
Hesse
Frankfurt's financial sector office modernization absorbs integrated engineering delivery models for complex commercial towers. Smart-building certification requirements filter contractor selection toward vertically capable firms. The Main-Taunus district clusters MEP installation capacity serving Class-A space procurement.
Berlin-Brandenburg
Commercial district revitalization in Berlin generates mega-project scale developments requiring consolidated contracting entities. Certified energy auditor scarcity creates bottleneck risks for GEG compliance documentation. Potsdam and the peripheral ring host aging industrial zones ripe for speculative GEG-compliant redevelopment.
Germany Commercial Construction Market Competitive Landscape
Rhine-Ruhr producers anchor one tier; Bavarian specialists hold differentiated positions in timber-hybrid execution. The vendor base organizes around three capability clusters: integrated engineering conglomerates, heavy civil transport-linked contractors, and prefabrication-focused mid-size fabricators. Consolidation pressure favors vertically integrated national firms with GEG documentation infrastructure. Competitive moves center on modular prefabrication convergence and eastern federal state geographic expansion.
Within the integrated engineering tier, HOCHTIEF Aktiengesellschaft and Strabag SE exemplify consolidated contracting entities capable of complex commercial tower delivery. GOLDBECK GmbH occupies a distinct position among prefabrication specialists, representing the factory-produced concrete core segment serving warehouse clients with tight occupancy deadlines. These three firms anchor the competitive structure through divergent capability investments rather than direct segment overlap.
| Leading Market Players |
|---|
| HOCHTIEF Aktiengesellschaft |
| Strabag SE |
| GOLDBECK GmbH |
| Ed. Züblin AG |
| Leonhard Weiss GmbH & Co. KG |
| BAM Deutschland AG |
| Max Bögl Bauservice GmbH & Co. KG |
| Bilfinger SE |
| AUG. PRIEN Bauunternehmung GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Certified energy auditor concentration in the Rhine-Ruhr and Bavaria regions creates labor-cost differentials that widen pricing spreads between GEG-compliant premium tiers and conventional economy-tier construction. Developers in eastern federal states face 15-25% cost premiums for mobilizing qualified MEP installation crews from western hubs.
Pricing Analysis
Volume concentrates in warehouse construction with compressed margins, while premium margins pool in DGNB-certified office towers with integrated smart-building systems. Price differentiation separates projects with verified lifecycle carbon documentation from those relying on legacy compliance pathways. Pricing pressure stems from EU Emissions Trading System carbon cost pass-through on steel and cement inputs. Corporate end-users in Munich and Frankfurt demonstrate lowest price sensitivity, prioritizing energy outcome commitments over capital cost minimization.
Supply Chain Analysis
Workforce availability constraints in eastern federal manufacturing geographies limit prefabrication capacity expansion despite demand growth. Material supply concentrates in Germany, Poland, and Czech Republic for factory-produced concrete core units and engineered timber components. Raw material dependencies include low-carbon cement formulations, cross-laminated timber panels, and high-performance glazing with integrated photovoltaics. Supply chain risk centers on single-source vulnerability for GEG-compliant MEP equipment from Rhine-Ruhr specialty manufacturers. Distribution runs through consolidated general contracting entities for mega-projects, with platform-based coordination tools penetrating mid-size developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The German commercial construction sector is transitioning from conventional concrete-steel systems to hybrid timber-concrete composites, with GEG thermal mandates accelerating displacement of legacy envelope technologies.
For Market Incumbents: Hedge margin exposure by securing captive supply of low-carbon cement and cross-laminated timber through backward integration into prefabrication facilities. Diversify contractor networks beyond Rhine-Ruhr and Bavaria clusters to reduce labor-mobilization cost volatility for eastern federal state projects.
For New Entrants and Emerging Players: Digital fabrication platforms offer entry wedge into mid-rise commercial segments where Stuttgart and Hamburg developers seek compressed construction schedules. Target Berlin-Brandenburg's aging industrial zones for speculative GEG-compliant warehouse development with modular concrete core delivery. Lead with BIM-integrated coordination tools that reduce on-site labor dependency.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated regional firms possessing GEG documentation infrastructure and DGNB certification capabilities given EU Green Deal taxonomy alignment mandates. Long-term viability favors developers with verified Environmental Product Declaration databases and lifecycle carbon modeling expertise. Monitor certified energy auditor training pipeline output as inflection indicator for project completion bottleneck risks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prefabrication | Captive supply of factory-produced concrete cores compresses schedules for warehouse clients with tight occupancy deadlines. |
| DGNB Certification Investment | Lifecycle carbon documentation capabilities unlock institutional capital mandates under EU Green Deal taxonomy alignment. |
| Eastern Federal State Geographic Expansion | First-mover positioning in Saxony and Thuringia's aging industrial zones captures below-replacement commercial stock replacement demand. |
| Smart-Building System Partnership | Predictive HVAC control algorithms embedded before EU AI Act procurement cycles secure specification lock-in for office towers. |
| Hybrid Timber-Concrete Platform Development | Engineered wood composites satisfy GEG thermal requirements while meeting corporate ESG reporting obligations in Munich and Berlin. |
Research Methodology
Document review covered KBA construction guidelines, EU Green Deal taxonomy disclosures, DGNB certification databases, and federal building energy compliance records, complemented by interviews with general contracting executives, MEP installation specialists, real estate development directors, and institutional capital allocation officers. Secondary validation drew from federal statistical office construction permits, EU Emissions Trading System carbon price data, and Environmental Product Declaration registries. Bottom-up project pipeline analysis triangulated with top-down sectoral investment flow modeling.
Market size outputs reflect segment-level construction value aggregation across office, warehouse, retail, and hospitality categories, with material-type splits and project-scale distributions modeled throughout the forecast period. CAGRs derive from regression analysis against regulatory compliance cost trajectories, logistics corridor densification patterns, and institutional capital mandate evolution. Forecast inputs incorporate GEG implementation timeline assumptions, e-commerce fulfillment network expansion plans, and hybrid timber system adoption curves.
Several conditions sit outside the modeled scope, including abrupt EU ETS carbon price spikes, KBA guideline amendments, and supply chain disruptions from geopolitical events. Forecasts reflect documented assumptions regarding training pipeline output for certified energy auditors and prefabrication capacity expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Early Production Facility Market
Building Construction
India Commercial Construction Market
Building Construction
Middle East Building Construction Market
Building Construction
France Prefab Homes Market
Building Construction
UAE Facade Market
Building Construction
US Modular Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Precast Construction Market
Building Construction
US Prefabricated Buildings Market
Building Construction
Middle East Data Center Construction Market
Building Construction
North America Construction Market