
 Germany Residential Construction Market | 2026-2036
Germany Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Residential Construction Market Foresight
Buyer concentration among institutional landlords is shifting as Vonovia SE and LEG Immobilien SE expand portfolios while smaller private investors fragment at the entry level. Vonovia SE leverages economies of scale across maintenance and energy retrofit pipelines. HOCHTIEF AG anchors large-scale urban regeneration contracts through its integrated project delivery model. STRABAG SE competes on civil-engineering synergies that reduce site-preparation costs for residential clusters.
Germany residential construction encompasses the erection, renovation, and finishing of dwellings for permanent habitation, typically involving reinforced-concrete foundations, masonry or timber superstructures, and thermal envelopes meeting U-value thresholds below 0.24 W/m²K. Its primary purpose is to supply compliant, financeable housing stock that satisfies KfW efficiency ratings and local zoning plans. Multi-family homes command the largest share of new-build value as municipalities prioritize density bonuses near transit nodes. Wood-frame construction records the fastest expansion among material segments, driven by carbon-accounting rules and factory prefabrication that compresses on-site schedules by roughly one-third. Government subsidies through KfW development bank programs concentrate margin pools in the financing-source segment, particularly for efficiency-class A and A+ certificates.
The German Building Energy Act (GEG), enforced by federal state building authorities, tightens primary-energy limits and effectively phases out fossil-only heating in new dwellings from 2024 onward. KBA construction-type approval intersects with DIN 4109 sound-insulation standards to shape product specifications and market-access conditions for system suppliers. Stakeholders must monitor how federal-state implementation variants of the GEG affect permitted heating technologies, because Bavaria and Baden-Württemberg already enforce stricter local interpretations that prefigure national trajectory.
Market Dynamics
The German Building Energy Act (GEG) is compressing project timelines and redrawing material specifications as developers race to comply with fossil-free heating mandates before enforcement tightens. Timber-frame systems and heat-pump integration now dominate pre-construction planning across southern metropolitan corridors.
Growth Catalysts
- KfW Efficiency Subsidies:Federal development bank programs for A and A+ certificates concentrate financing flows toward passive-house retrofits and new builds. Institutional landlords structure entire portfolios around subsidy eligibility thresholds.
- Urban Density Mandates:Municipal zoning bonuses near transit nodes in Berlin and Munich accelerate multi-family unit approvals. Local authorities prioritize compact footprints to address acute housing shortages.
- Prefabrication Advances:Factory-built timber modules compress on-site schedules by roughly one-third. German manufacturers scale automated cutting and panelization lines to meet carbon-accounting deadlines.
Market Restraints
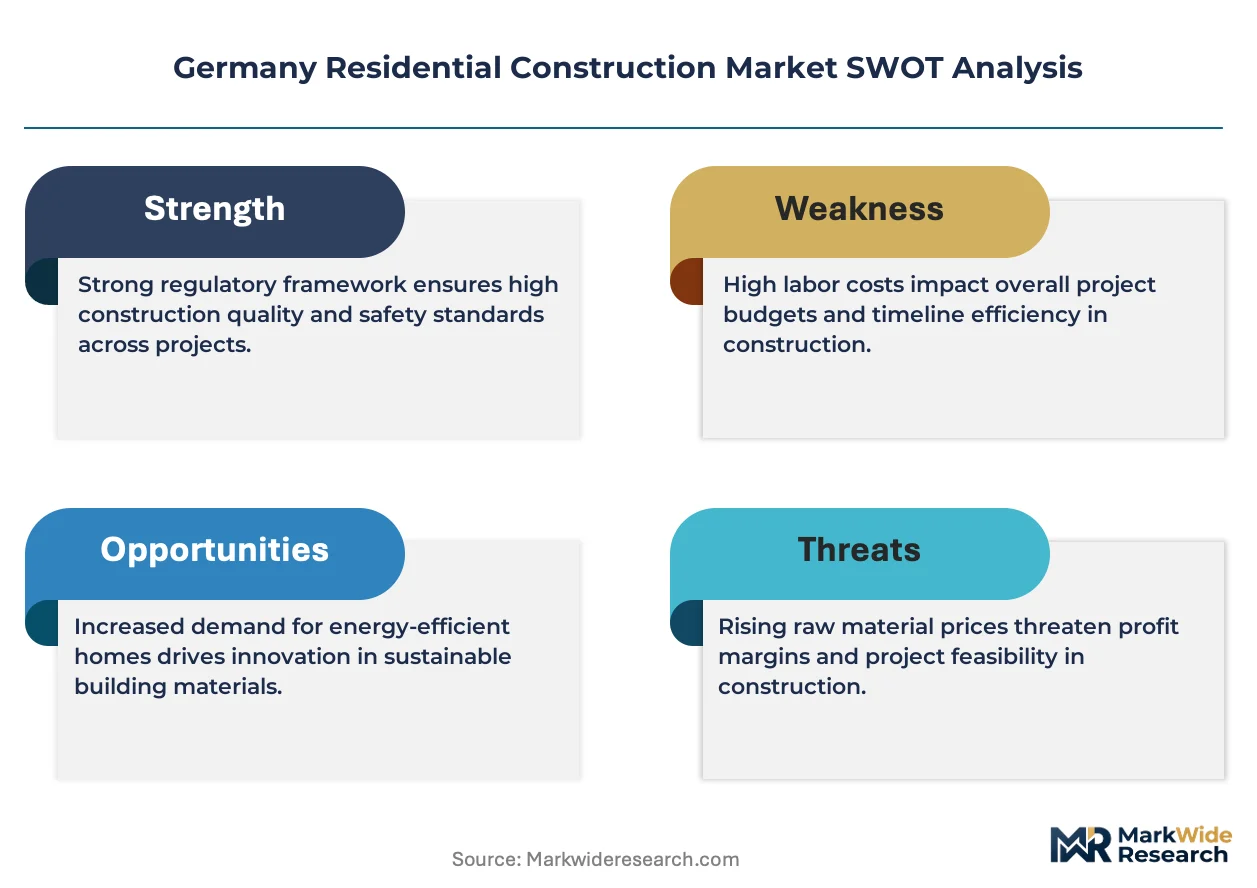
- Skilled Labor Bottlenecks:Certified passive-house trades and timber-frame specialists remain concentrated in Baden-Württemberg and Bavaria. Wage premiums for cross-regional recruitment inflate project overheads.
- Heat-Pump Supply Concentration:European compressor and refrigerant component manufacturers face order backlogs stretching 12-18 months. Installation delays cascade into missed GEG compliance windows.
- Geological Site Variability:Rheinland-Pfalz and parts of North Rhine-Westphalia present karst terrain requiring costly pile foundations. Reinforced-concrete substructures erode timber-frame cost advantages in these zones.
Strategic Opportunities
- East German Urban Regeneration:Cities including Leipzig and Dresden retain surplus industrial land with simplified zoning paths. Developers acquire brownfield parcels at discounts to western comparables.
- GEG Implementation Variants:Bavaria and Baden-Württemberg enforce stricter local heating technology bans than federal baselines. Early movers in these states capture regulatory arbitrage before national harmonization.
- Cross-Laminated Timber Hybridization:Integration with reinforced-concrete cores enables mid-rise construction beyond pure timber structural limits. Engineering consultancies in Stuttgart and Munich pioneer hybrid system certifications.
Industry Challenges
- Sound-Insulation Compliance:DIN 4109 multi-family standards require specialized acoustic detailing for timber floors. Design-build teams struggle to reconcile GEG thermal targets with airborne and impact noise thresholds.
- Foundation System Integration:Existing reinforced-concrete supply chains resist coordination with prefabricated timber superstructure deliveries. Site logistics friction inflates crane and staging costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Residential Construction Market |
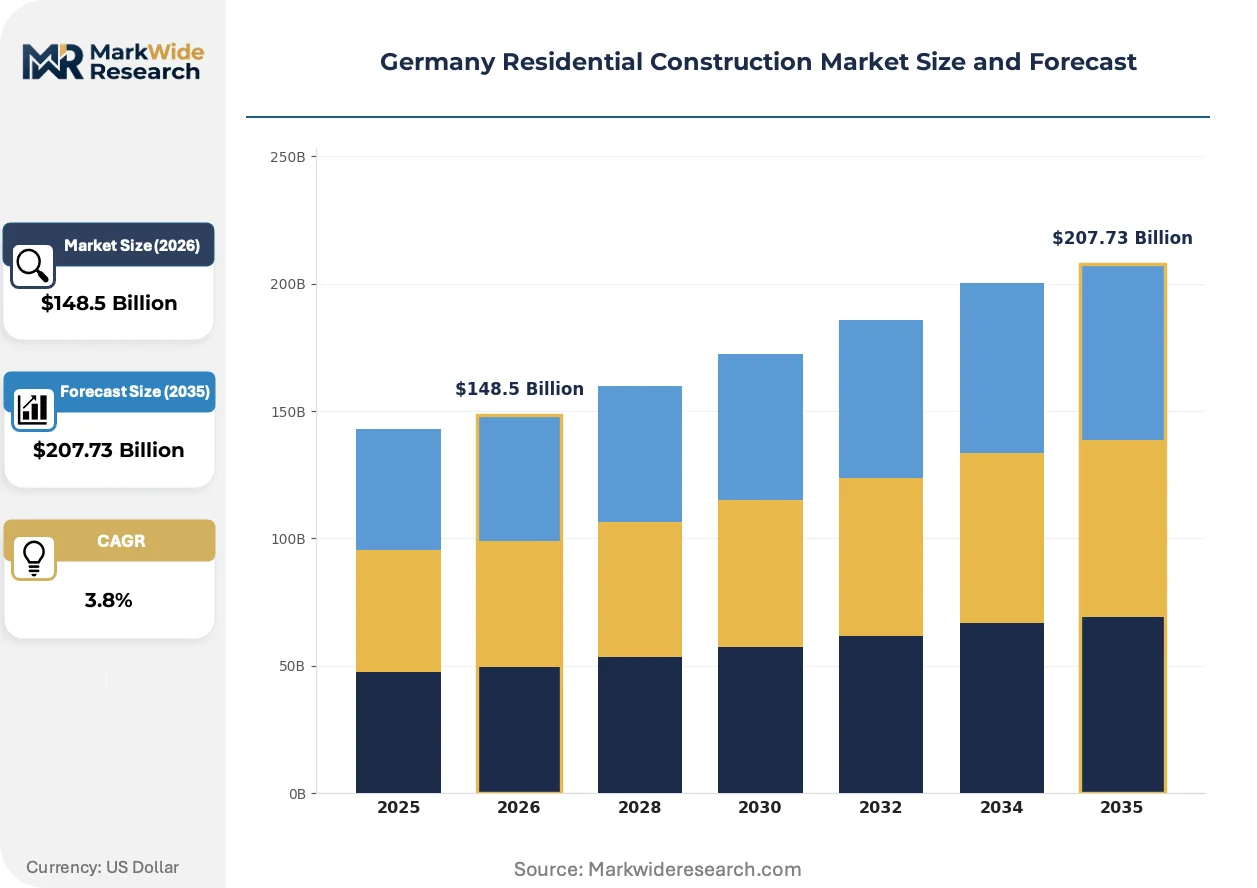
| Market Size in 2026 | $148.5 Billion |
| Market Size in 2035 | $207.73 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Single-Family Homes, Multi-Family Homes, Townhouses, Duplexes, Modular Homes Construction Material: Concrete, Wood, Steel, Brick, Prefabricated Panels, Insulation Materials Financing Source: Private Mortgages, Government Subsidies, Real Estate Investment Trusts, Construction Loans, Crowdfunding Project Stage: Planning & Permitting, Groundwork, Structural Work, Finishing, Interior Design |
| Companies Covered | Max Bögl Group, Vonovia SE, HOCHTIEF AG, Helma Eigenheimbau AG, LEG Immobilien SE, Ed. Züblin AG, Deutsche Wohnen SE, STRABAG SE, GOLDBECK GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Residential Construction Market Shifts & Advancements
Digital fabrication and regulatory carbon accounting are converging to transform how German residential projects move from design to occupancy. Material traceability and automated production systems now determine competitive positioning.
Cross-laminated timber (CLT) and glulam systems are rewriting structural possibilities for mid-rise residential construction. Bavarian and Baden-Württemberg developers specify engineered wood for six-to-eight-story projects previously reserved for concrete frames. Factory precision cutting reduces on-site waste streams and accelerates envelope closure timelines.
The German Building Energy Act (GEG) tightens primary-energy limits and phases fossil-only heating from 2024 onward. Federal state building authorities in Bavaria and Baden-Württemberg already enforce stricter local interpretations than national baselines. Equipment suppliers accelerate heat-pump and district-hydronics R&D to maintain market access across all sixteen Länder.
Institutional landlords now bundle energy-performance contracting with long-term lease structures. Vonovia SE and LEG Immobilien SE structure tenant agreements where efficiency upgrades amortize through operating cost reductions. This model concentrates most visibly in Berlin and Munich where rental yield compression demands alternative revenue streams.
Germany Residential Construction Market Segmentation
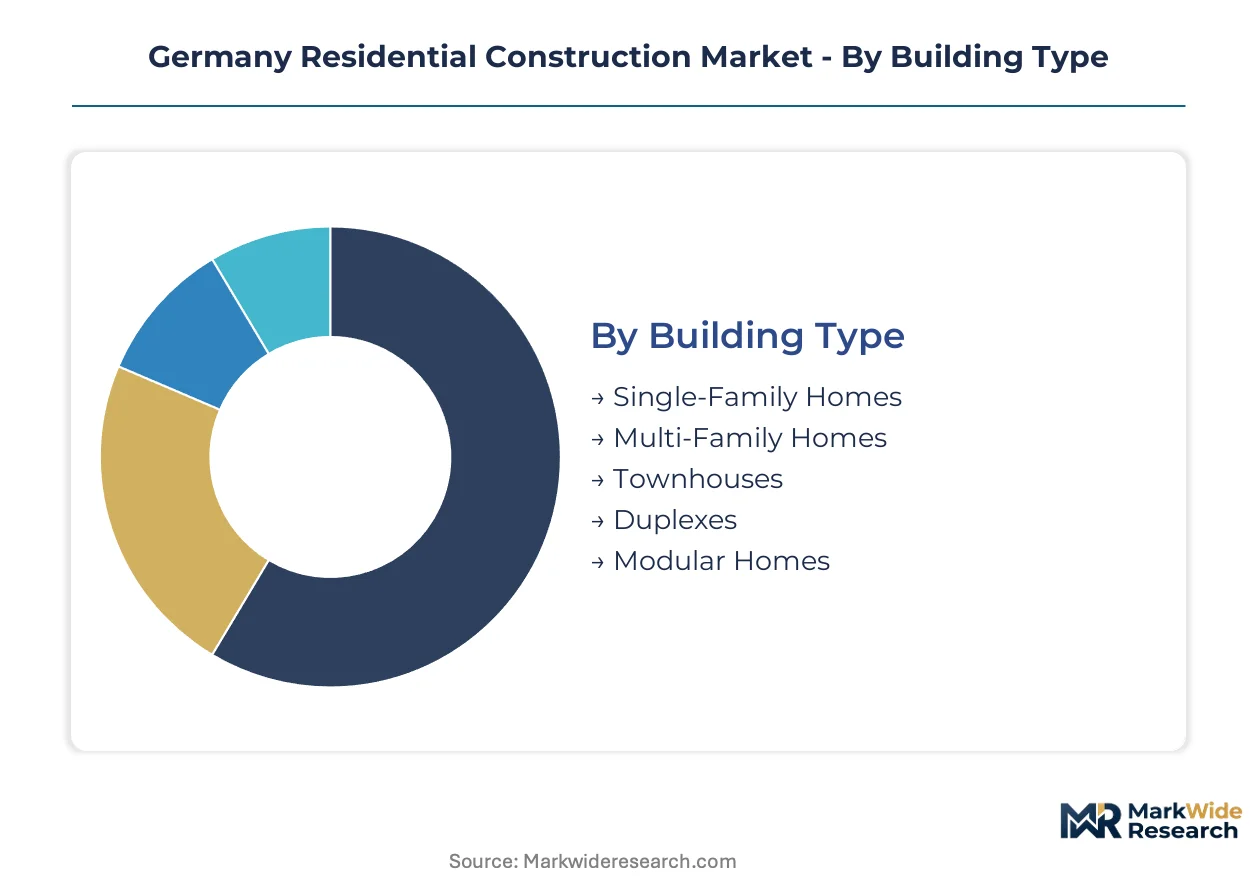
German residential construction segments fragment along regulatory compliance axes rather than pure cost tiers. KfW efficiency certificates and GEG heating mandates reshape which building types and materials capture financing flows. Developers structure portfolios around subsidy eligibility thresholds that vary by federal state.
Building Type:
Structural systems and density bonuses determine where capital concentrates across German metropolitan corridors.
- Multi-Family Homes:Reinforced-concrete frame structures with shared thermal envelopes dominate new-build value in Berlin and Munich transit zones. Municipal density bonuses accelerate approvals where housing shortages persist. Institutional landlords like Vonovia SE concentrate portfolios around these assets for scale economies in maintenance.
- Single-Family Homes:Detached dwellings with individualized heating systems face GEG compliance pressure as fossil-only bans tighten. Bavarian and Baden-Württemberg developers pivot toward heat-pump-ready designs to secure KfW A+ certificates.
- Townhouses:Row-house configurations balance density with individual ownership structures in suburban Leipzig and Dresden corridors.
- Duplexes:Two-unit buildings attract private investors seeking entry-level rental exposure with simplified property management.
- Modular Homes:Factory-built units reduce on-site labor dependency where skilled trades remain scarce.
Mature deployment sits with multi-family homes. Newer deployment is concentrated in modular systems.
Construction Material:
Carbon-accounting rules and factory automation reshape material specification patterns across German project pipelines.
- Wood:Cross-laminated timber and glulam systems enable six-to-eight-story residential construction previously reserved for concrete. Bavarian manufacturers scale automated cutting lines to compress envelope closure timelines. GEG thermal targets align with timber's natural insulating properties.
- Concrete:Reinforced-concrete foundations and cores retain dominance in karst terrain zones of Rheinland-Pfalz where pile systems prove necessary. HOCHTIEF AG and STRABAG SE leverage existing supply chains for large-scale urban regeneration contracts.
- Steel:Structural steel frames support hybrid systems in mid-rise commercial-residential mixed projects.
- Brick:Traditional masonry construction persists in heritage-sensitive renovation districts.
- Prefabricated Panels:Factory-built envelope systems reduce on-site waste streams and accelerate GEG compliance schedules.
- Insulation Materials:Mineral wool and cellulose specifications tighten as U-value thresholds drop below 0.24 W/m²K.
Established volume flows through concrete. Wood-frame construction is expanding most quickly as carbon-accounting deadlines approach.
Financing Source:
Subsidy eligibility thresholds and institutional capital deployment patterns segment funding access across project types.
- Government Subsidies:KfW development bank programs for efficiency-class A and A+ certificates concentrate margin pools in certified passive-house and timber-frame projects. Federal state implementation variants create geographic arbitrage opportunities.
- Private Mortgages:Retail bank financing dominates single-family and townhouse purchases where individual creditworthiness determines access.
- Real Estate Investment Trusts:Vonovia SE and LEG Immobilien SE structure portfolios around subsidy-eligible multi-family assets in Berlin and Munich.
- Construction Loans:Development finance bridges ground-up projects through planning and structural phases.
- Crowdfunding:Retail investor platforms fragment entry-level exposure across small-scale residential developments.
Institutional capital concentrates in REIT structures. Crowdfunding channels are gaining share fastest among private investors.
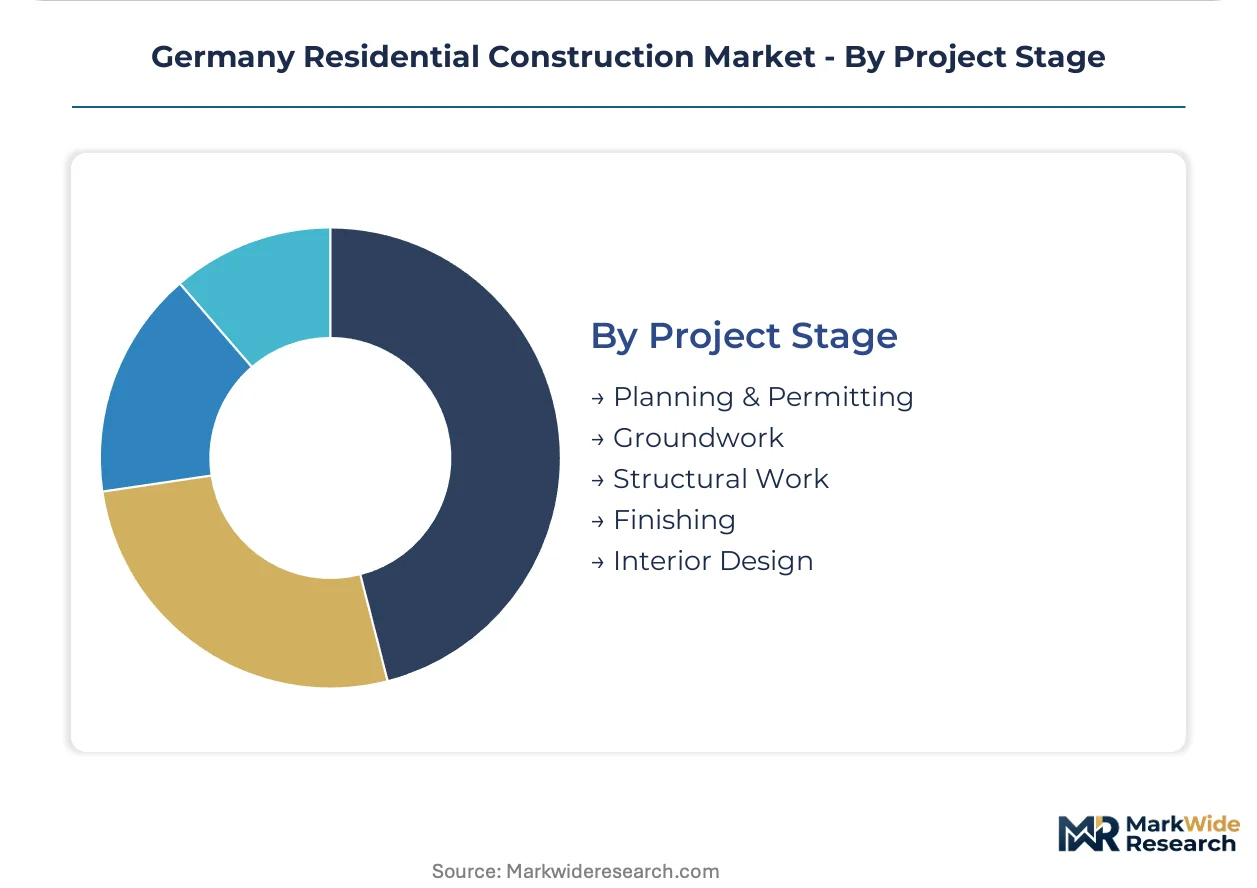
Project Stage:
Regulatory checkpoint sequencing and skilled labor availability compress or extend timelines across phase transitions.
- Planning & Permitting:GEG compliance documentation and federal state building authority approvals create bottlenecks where fossil-heating bans tighten. Bavaria and Baden-Württemberg prefigure national trajectory with stricter local interpretations.
- Structural Work:Timber-frame and reinforced-concrete superstructure erection demands coordination between factory delivery schedules and site crane availability.
- Groundwork:Foundation systems vary by geological conditions with karst terrain requiring specialized pile engineering.
- Finishing:Heat-pump and district-hydronics integration faces component backlogs stretching 12-18 months.
- Interior Design:DIN 4109 sound-insulation compliance for multi-family timber floors requires specialized acoustic detailing.
Longest cycle times persist in planning and permitting. Prefabrication is compressing structural work schedules most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for residential construction concentrates in southern German metropolitan corridors where housing shortages intersect with stringent energy mandates. Urban professionals in Berlin and Munich drive absorption of compact multi-family units. Federal state implementation variants of the German Building Energy Act create divergent compliance landscapes across sub-regions.
Bavaria
Munich anchors the tightest housing market in Germany with vacancy rates below one percent. The Bavarian state building authority enforces stricter GEG interpretations than federal baselines, prefiguring national heating technology bans. Cross-laminated timber manufacturers in the Alpine foothills scale automated production lines to serve six-to-eight-story residential projects.
Baden-Württemberg
Stuttgart and Karlsruhe corridors exhibit acute skilled labor scarcity for passive-house trades. State regulators mandate heat-pump readiness in new dwellings ahead of national deadlines. Engineering consultancies in Stuttgart pioneer hybrid timber-concrete certifications for mid-rise construction beyond pure wood structural limits.
North Rhine-Westphalia
Cologne and Düsseldorf absorb institutional capital seeking scale economies in multi-family portfolios. Karst terrain in Rheinland-Pfalz border zones necessitates costly pile foundations that erode timber-frame cost advantages. HOCHTIEF AG leverages reinforced-concrete supply chains for large-scale urban regeneration contracts.
Berlin-Brandenburg
The capital region leads modular construction adoption as factory-built units reduce on-site labor dependency. Municipal density bonuses near transit nodes accelerate approvals for compact footprints. Vonovia SE and LEG Immobilien SE structure portfolios around subsidy-eligible assets to capture KfW efficiency program flows.
Saxony
Leipzig and Dresden retain surplus industrial land with simplified zoning paths for brownfield conversion. Developers acquire parcels at discounts to western comparables while targeting young professional migration. Prefabrication advances compress construction schedules in markets with limited skilled trade availability.
Germany Residential Construction Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular and carbon-accounting specializations. The market exhibits tiered consolidation with institutional landlords controlling multi-family portfolios and specialized contractors dominating timber-frame segments. Three archetypes predominate: scale-driven integrated developers, regional specialists in energy-efficient systems, and factory-based modular fabricators. Competitive dynamics center on portfolio acquisition velocity and prefabrication capacity expansion.
Within the institutional landlord tier, Vonovia SE and LEG Immobilien SE exemplify scale-driven portfolio strategies structured around subsidy eligibility thresholds. HOCHTIEF AG anchors the integrated project delivery archetype through its positioning in large-scale urban regeneration. Among specialized engineering contractors, STRABAG SE occupies a position leveraging civil-engineering synergies for site preparation cost reduction.
| Leading Market Players |
|---|
| Max Bögl Group |
| Vonovia SE |
| HOCHTIEF AG |
| Helma Eigenheimbau AG |
| LEG Immobilien SE |
| Ed. Züblin AG |
| Deutsche Wohnen SE |
| STRABAG SE |
| GOLDBECK GmbH |
| Others |
Supply & Pricing Matrix
Cross-laminated timber feedstock costs cascade through factory gate pricing to on-site installation tiers, with Bavarian automated cutting lines commanding premium positioning against manual assembly alternatives in eastern federal states.
Pricing Analysis
Volume flows concentrate in standardized multi-family concrete frames while margins pool in certified passive-house timber segments. Price differentiation separates KfW A+ certified projects from baseline GEG compliance builds, with efficiency premiums widening as fossil-heating bans tighten. Cost compression in entry-level single-family construction is intensifying because heat-pump readiness mandates inflate mechanical system budgets. Institutional landlords exhibit lowest price sensitivity; private investors in modular homes face acute budget constraints.
Supply Chain Analysis
Direct-to-fabricator channels handle prefabricated timber module demand from Baden-Württemberg and Bavaria developers. Supply concentrates in German Alpine foothills mills, Austrian engineered-wood specialists, and Nordic glulam exporters. Raw material dependencies span spruce structural lumber, polyurethane adhesives, and mineral-wool insulation. Single-source vulnerability sits with European heat-pump compressor manufacturers facing order backlogs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strategic consolidation accelerates as GEG compliance costs force sub-scale developers toward acquisition or exit. The KfW efficiency subsidy threshold acts as the primary filter eliminating margin-weak competitors.
For Market Incumbents: Anchor portfolio resilience through captive prefabrication capacity in timber-frame segments. Acquire specialized passive-house trades in Baden-Württemberg to lock in scarce labor pools. Defensive positioning requires backward integration into cross-laminated timber supply as imports face carbon-accounting scrutiny.
For New Entrants and Emerging Players: Capture brownfield conversion opportunities in Leipzig and Dresden corridors where simplified zoning reduces approval timelines. Modular factory-built units offer the most penetrable entry path where skilled labor scarcity persists. Go-to-market positioning should emphasize GEG-ready designs pre-certified for Bavarian state authority standards.
For Investors and Strategic Acquirers: Bavarian state authority enforcement of stricter-than-federal GEG variants is the leading indicator that regulatory arbitrage windows are narrowing. Long-term viability favors vertically integrated developers with in-house timber fabrication and heat-pump installation capabilities. Acquisition targets should display established KfW A+ certification pipelines. Monitor federal-state implementation divergence as the signal for portfolio rebalancing urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Capacity Expansion | Factory automation in Bavaria compresses on-site schedules by one-third against conventional builds. |
| Backward Integration into Timber Supply | In-house glulam production secures carbon-accounting traceability for GEG compliance documentation. |
| Heat-Pump Installation Capability Buildout | Captive mechanical contracting reduces exposure to 12-18 month European component backlogs. |
| Brownfield Land Assembly | Surplus industrial parcels in Saxony trade at discounts to western German comparables. |
| Passive-House Certification Investment | KfW A+ eligibility unlocks federal development bank financing flows for institutional portfolios. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with German federal state building authority officials, timber-frame engineering consultants, KfW program administrators, and institutional landlord asset managers validated demand assumptions. Secondary sources encompassed DIN standards documentation, GEG implementation decrees, and construction permit databases. Bottom-up project pipeline enumeration triangulated against top-down residential investment flow estimates.
Data-stream reconciliation across permit volumes, material import records, and financing disbursements shaped the analytical framework. Segmentation dimensions encompassed building type, construction material, financing source, and project stage across the modeling period. CAGRs derived from regression analysis of historical completion rates against policy implementation schedules. Forecast inputs incorporated GEG phase-in timelines and KfW subsidy budget trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal-state regulatory divergence and heat-pump supply normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Canada Residential Construction Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Japan Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Swimming Pool Construction Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
US Residential Remodeling Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Europe Prefabricated Housing Market