
 Girdle Plates Market | 2026-2036
Girdle Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Girdle Plates Market Analytics
North American specialty foundries is repositioning output toward billet-grade girdle plate blanks as racing sanctioning bodies tighten engine integrity rules. Cummins Engine Company leverages its forged-steel expertise to supply heavy-duty diesel reinforcement platforms. PRW Industries Inc. anchors the aftermarket segment through dedicated catalog distribution to circle-track builders. Hughes Engine competes on small-batch CNC finishing for vintage V8 architectures.
Girdle plates are structural reinforcement members that bolt to the bottom of an engine block to limit main cap walk and crankshaft flex under high cylinder pressure, typically machined from 6061-T6 aluminum or 4140 chromoly steel to tolerances within 0.001 inch flatness. The product serves the essential function of extending engine life in forced-induction and racing applications where stock bulkheads deform. Steel girdle plates dominate commercial trucking and marine rebuilds where fatigue resistance outweighs mass penalties, while aluminum variants lead automotive and aerospace retrofit channels where weight reduction drives specification. Composite and polycarbonate segments remain nascent but attract development capital from electric drivetrain integrators exploring noise-vibration-harshness damping solutions.
EPA certification requirements for rebuilt heavy-duty engines and EU REACH restrictions on hexavalent chromium plating processes are reshaping coating and material specifications across export-bound production. NHTSA defect investigation protocols for performance engine components create liability exposure that favors suppliers with documented finite-element analysis and batch traceability systems. Stakeholders must monitor evolving racing-sanctioning body rulebooks and OEM warranty language regarding aftermarket bottom-end reinforcement to anticipate which material grades and fastening configurations will retain competitive eligibility.
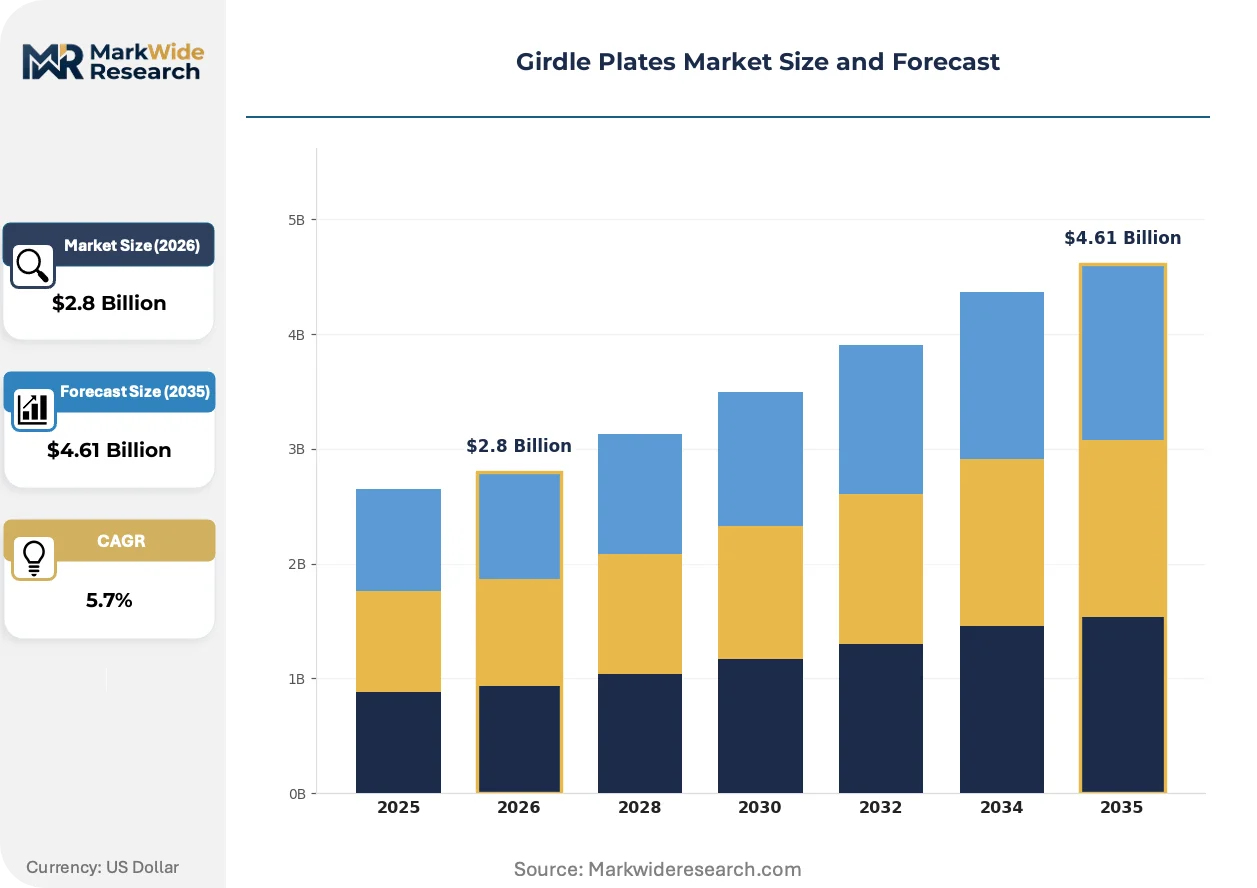
Market Dynamics
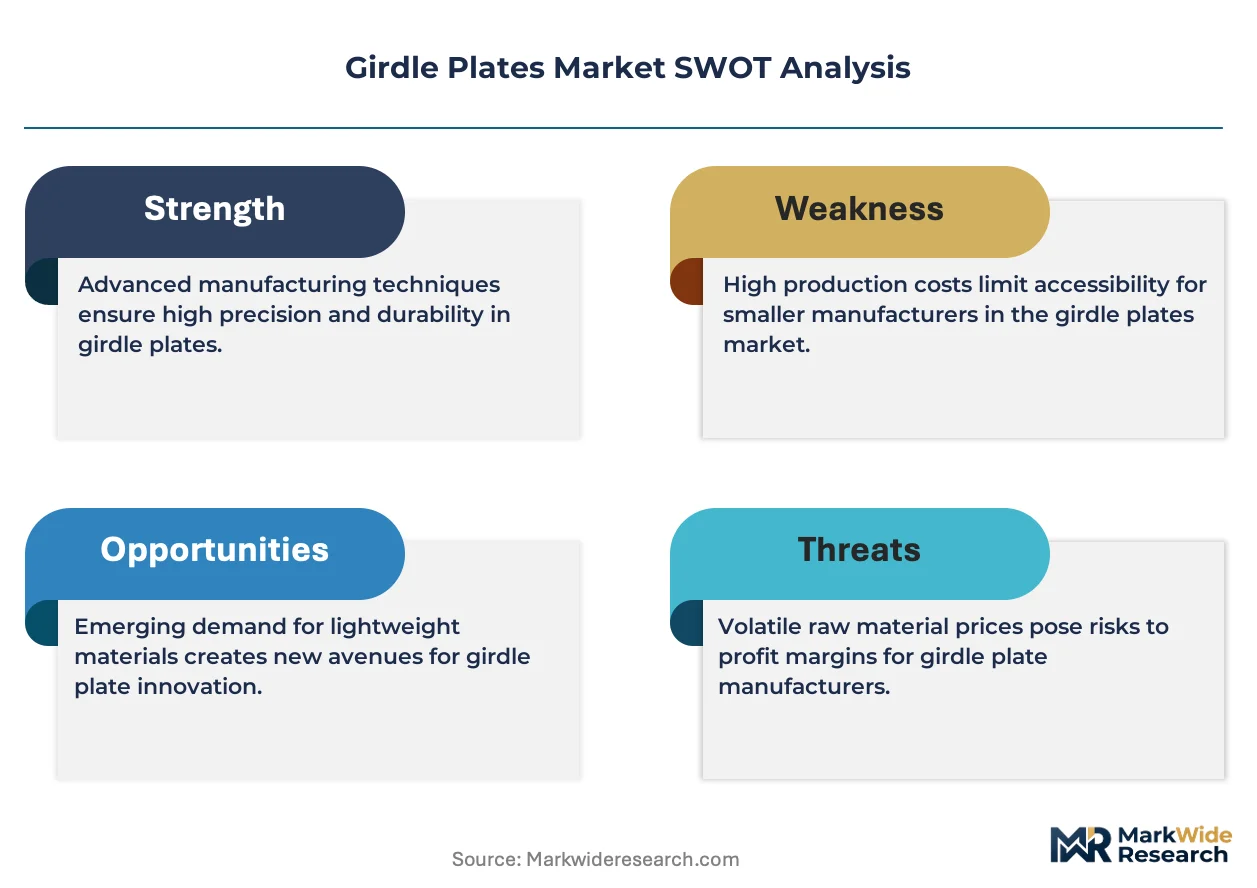
Material substitution toward aluminum and composite girdle plates is compressing the traditional steel-dominated supply base as EPA emissions benchmarks and EU REACH compliance thresholds harden specification requirements across export-bound production.
Growth Catalysts
- EPA Heavy-Duty Engine Certification:Rebuilt commercial powertrain regulations mandate documented crankcase reinforcement for warranty eligibility, pulling girdle plate demand through certified remanufacturing channels.
- Forced-Induction Penetration:OEM turbocharger adoption rates in light trucks and performance passenger vehicles multiply cylinder pressure loads beyond stock bulkhead design limits.
- Germany's Motorsport Valley:Precision engineering clusters around Stuttgart and Munich concentrate tier-one machining capacity serving both domestic OEMs and export racing markets.
Market Restraints
- 4140 Chromoly Price Volatility:Alloy steel input costs fluctuate with scrap metal and energy pricing, squeezing margin on heavy-duty diesel and marine rebuild segments where fatigue resistance specifications prohibit material substitution.
- Hexavalent Chromium Restrictions:EU REACH plating process prohibitions force coating line retooling investments that smaller specialty foundries cannot absorb without volume guarantees.
- Dimensional Tolerance Bottlenecks:0.001 inch flatness requirements demand CNC finishing capacity that concentrates among German and Japanese machine shops, limiting supplier diversification.
Strategic Opportunities
- Electric Drivetrain NVH Damping:Composite and polycarbonate girdle plate variants attract development capital from EV integrators seeking noise-vibration-harshness solutions for high-torque electric motors.
- Vintage V8 Restoration:Small-batch CNC finishing for pre-emissions architectures commands premium pricing as collector vehicle registrations expand in North American and Australian markets.
- Circle-Track Sanctioning Alignment:Racing rulebook harmonization around engine integrity standards creates catalog standardization opportunities for aftermarket distributors serving multiple sanctioning bodies.
Industry Challenges
- Finite-Element Analysis Talent Scarcity:NHTSA defect investigation protocols demand documented simulation capacity that exceeds the engineering bench depth of mid-tier suppliers.
- Batch Traceability System Investment:OEM warranty language requiring aftermarket component provenance forces ERP upgrades that strain working capital for single-product-line manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Girdle Plates Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Polycarbonate, Composite Application: Construction, Automotive, Aerospace, Marine End User: Manufacturers, Contractors, Engineers, Distributors Delivery Model: Direct Sales, Online Marketplace, Retail, Wholesale |
| Companies Covered | Hughes Engine, Speedmaster Inc., BAR TEK Motorsport, Eurocode Tuning Inc., Lane Automotive Inc., Cummins Engine Company, Opus Innovation Pvt. Ltd., Integrated Engineering, PRW Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Girdle Plates Market Evolving Landscape
Active material science development is bifurcating the girdle plate specification landscape into weight-optimized automotive variants and durability-focused commercial segments, with coating chemistry and fastening geometry emerging as primary differentiation vectors.
Carbon-fiber-reinforced polymer girdle plate prototypes are electrifying the electric vehicle aftermarket as tuners adapt legacy internal combustion reinforcement architectures to battery-electric powertrain packaging constraints. EV conversion shops in California and Norway are piloting these composite structures for motor mount integration. The technology is compressing the traditional metal-forming supplier base into specialty niches.
EU REACH restrictions on hexavalent chromium plating processes are forcing coating substitution toward trivalent chromium and electroless nickel formulations. Surface finish houses in Germany and Italy are qualifying new bath chemistries for 4140 steel substrates. Heavy-duty diesel remanufacturers serving export markets face the steepest compliance timeline pressure.
Circle-track builders are consolidating procurement through dedicated catalog distributors rather than direct foundry relationships. This channel compression concentrates specification influence among PRW Industries and similar aftermarket aggregators. The pattern is most visible in US dirt-track and pavement oval segments where rulebook harmonization enables single-SKU regional distribution.
Girdle Plates Market Segmentation
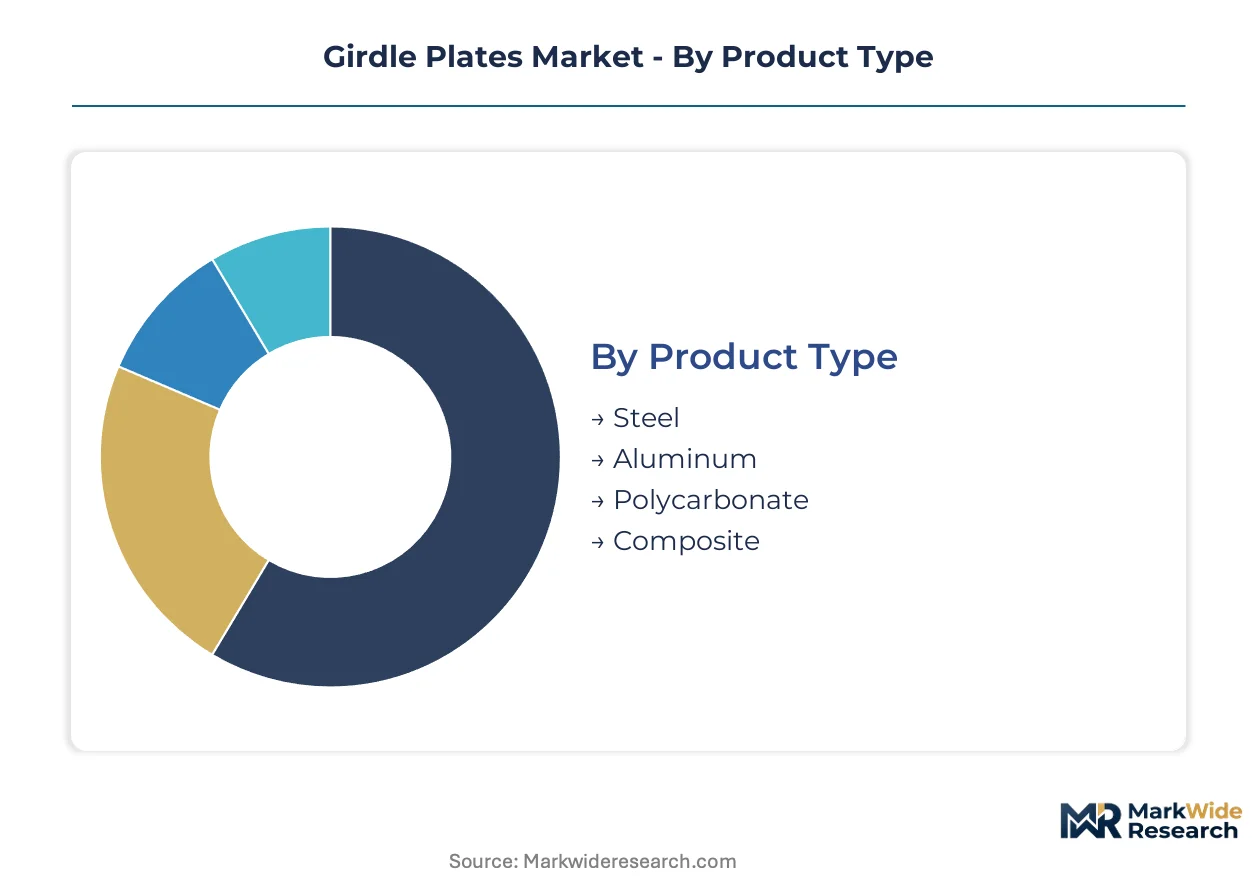
Segmentation in the girdle plates market reveals how material science, application intensity, and procurement channels create divergent margin structures. Suppliers must align specification depth with end-use certification requirements across each dimension.
Product Type:
Integration depth varies sharply across material categories, with standalone structural members demanding distinct engineering validation versus embedded composite systems.
- Steel:Machined from 4140 chromoly to fatigue-resistant specifications, steel girdle plates anchor commercial trucking and marine rebuilds where mass tolerance permits durability prioritization. Cummins Engine Company specifications dominate North American heavy-duty diesel procurement, though EU REACH hexavalent chromium restrictions force coating line transitions toward trivalent alternatives.
- Aluminum:6061-T6 aluminum variants reduce unsprung mass in automotive and aerospace retrofit channels, with Stuttgart-area machine shops holding 0.001 inch flatness capacity that limits supplier competition. EPA emissions benchmarks accelerate OEM specification shifts toward lighter materials in forced-induction passenger vehicle architectures.
- Polycarbonate:Emerging noise-vibration-harshness solutions for electric drivetrain integrators piloting legacy reinforcement geometries in battery-electric packaging.
- Composite:Carbon-fiber-reinforced polymer prototypes attract development capital from California and Norway EV conversion shops adapting motor mount integration concepts.
Steel leads volumes today; composite is gaining share fastest.
Application:
Application intensity determines whether girdle plates serve as preventive maintenance components or performance-critical reinforcements under warranty exposure.
- Automotive:Forced-induction penetration in light trucks and performance passenger vehicles multiplies cylinder pressure loads beyond stock bulkhead limits, pulling demand through both OEM turbocharger programs and aftermarket tuner channels. Germany's Motorsport Valley clusters precision machining capacity serving export racing markets.
- Marine:Saltwater corrosion resistance specifications favor coated steel architectures in commercial vessel rebuilds, with fatigue resistance requirements prohibiting material substitution despite alloy price volatility.
- Construction:Stationary power generation and heavy equipment remanufacturing drives periodic replacement demand through certified rebuild channels.
- Aerospace:Weight-optimized aluminum specifications dominate retrofit channels where FAA certification documentation requirements exceed general industrial standards.
Automotive commands the largest revenue pool; aerospace shows the steepest specification premium trajectory.
End User:
End-user technical sophistication shapes whether procurement flows through specification engineers or catalog distributors.
- Engineers:Design-intensive projects in aerospace and motorsport applications demand documented finite-element analysis and batch traceability systems that strain mid-tier supplier engineering benches.
- Manufacturers:OEM powertrain divisions and tier-one automotive suppliers integrate girdle plates into original equipment specifications with multi-year volume commitments.
- Contractors:Commercial trucking and marine rebuild shops prioritize EPA certification compliance and warranty documentation over material optimization.
- Distributors:Aftermarket catalog aggregators consolidate circle-track procurement through standardized SKUs serving multiple racing sanctioning bodies.
Manufacturers anchor current procurement volumes; distributors are expanding fastest through channel compression.
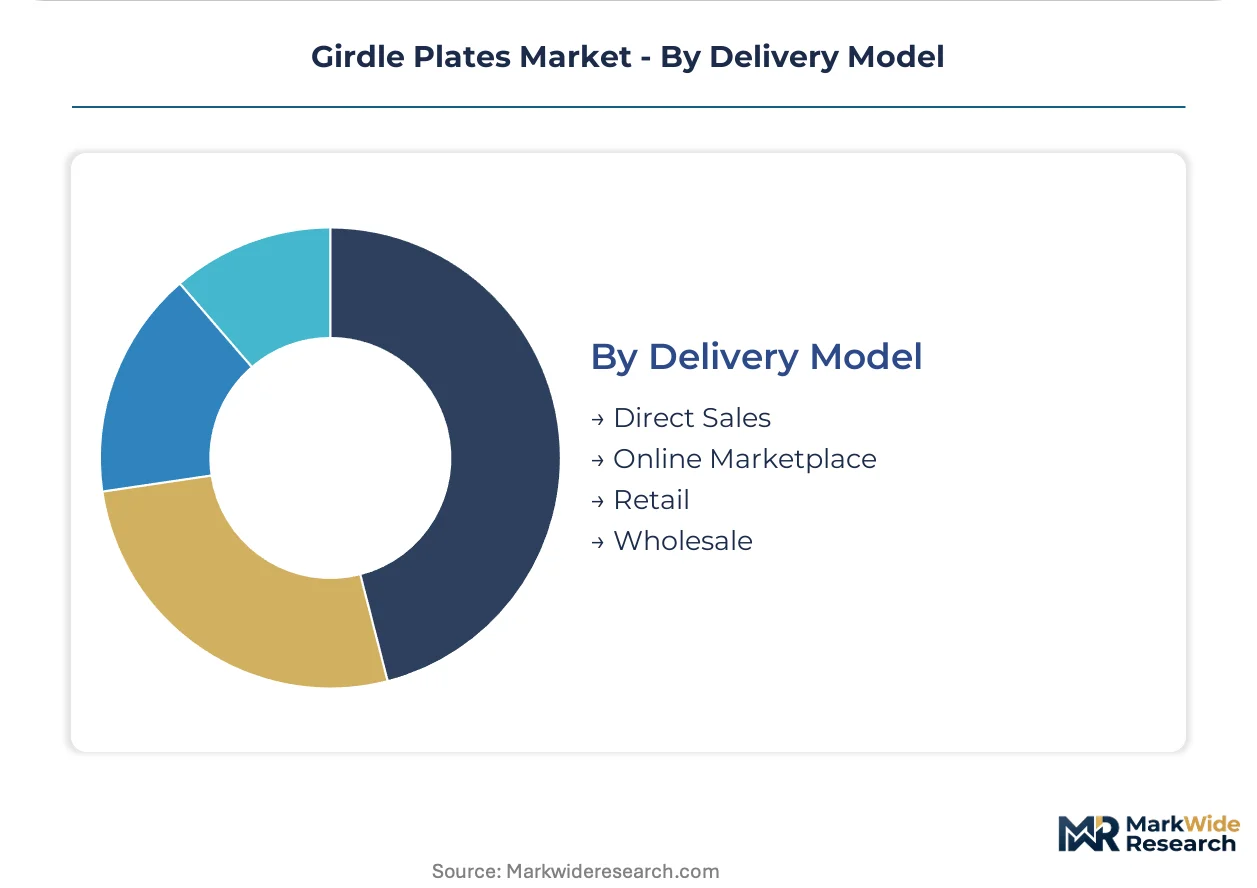
Delivery Model:
Delivery model selection reflects order fragmentation versus scale economics across customer technical requirements.
- Wholesale:Volume commitments from OEM powertrain divisions and certified remanufacturing channels concentrate procurement through direct mill relationships with documented batch traceability.
- Direct Sales:Engineering-intensive aerospace and motorsport applications require technical consultation and custom finishing coordination that bypasses intermediary markup.
- Online Marketplace:Vintage V8 restoration builders and small-batch circle-track shops access catalog-standard specifications through digital procurement platforms.
- Retail:Limited to emergency replacement demand in commercial marine and construction equipment service depots with immediate availability requirements.
Wholesale captures the dominant transaction value; online marketplace channels are expanding most quickly among fragmented aftermarket demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting girdle plate fabrication toward jurisdictions with lower compliance costs for hexavalent chromium alternatives, while precision machining capacity concentrates in established automotive clusters where legacy tooling investments create stickiness.
United States
EPA heavy-duty engine certification mandates pull girdle plate demand through certified remanufacturing channels serving commercial trucking fleets. NHTSA defect investigation protocols for performance engine components create liability exposure that favors suppliers with documented finite-element analysis capacity. Circle-track builders in the Southeast and Midwest consolidate procurement through aftermarket catalog distributors rather than direct foundry relationships.
Germany
EU REACH restrictions on hexavalent chromium plating processes force coating line transitions toward trivalent alternatives for 4140 steel substrates. Stuttgart and Munich precision engineering clusters hold 0.001 inch flatness CNC finishing capacity that limits supplier competition across export racing markets. KBA oversight of motorsport component safety standards shapes specification requirements for both domestic OEMs and tier-one automotive suppliers.
China
GB standards for heavy equipment remanufacturing and MIIT industrial upgrading programs accelerate domestic capacity for billet-grade girdle plate blanks. Yangtze River Delta machine shops are qualifying electroless nickel coating chemistries to serve export-bound production facing EU REACH compliance thresholds. Domestic turbocharger penetration in light trucks multiplies cylinder pressure loads beyond stock bulkhead design limits.
Japan
METI carbon neutrality roadmaps and JIS fatigue resistance specifications favor steel girdle plates in commercial marine rebuilds where mass tolerance permits durability prioritization. Nagoya-area precision fabricators supply both domestic OEM powertrain divisions and aerospace retrofit channels with weight-optimized aluminum variants. Batch traceability systems exceed general industrial standards for FAA certification documentation requirements.
India
BIS automotive component standards and PLI scheme incentives for advanced manufacturing attract tooling investments for CNC finishing capacity. Maharashtra and Gujarat precision engineering clusters serve both domestic commercial vehicle rebuild shops and export markets facing EPA certification requirements. DGFT export documentation protocols shape coating chemistry specifications for heavy-duty diesel reinforcement platforms.
Girdle Plates Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite and polycarbonate noise-vibration-harshness solutions for electric drivetrain integrators. The supplier base stratifies across three maturity tiers: forged-steel specialists serving commercial diesel and marine rebuilds, aluminum precision machinists targeting automotive and aerospace retrofit channels, and development-stage composite fabricators piloting motor mount integration concepts. Dominant competitive moves include coating line retooling investments to satisfy EU REACH compliance timelines and strategic partnerships with racing sanctioning bodies to secure catalog standardization opportunities.
Among North American fabricators, Cummins Engine Company and PRW Industries Inc. represent divergent archetypes within the competitive structure. Cummins anchors the heavy-duty diesel segment through forged-steel expertise and OEM powertrain integration relationships. PRW Industries occupies the aftermarket catalog distribution tier, consolidating circle-track procurement through standardized SKUs serving multiple racing sanctioning bodies. Hughes Engine exemplifies the small-batch CNC finishing specialist targeting vintage V8 restoration builders with premium pricing for pre-emissions architectures.
| Leading Market Players |
|---|
| Hughes Engine |
| Speedmaster Inc. |
| BAR TEK Motorsport |
| Eurocode Tuning Inc. |
| Lane Automotive Inc. |
| Cummins Engine Company |
| Opus Innovation Pvt. Ltd. |
| Integrated Engineering |
| PRW Industries Inc. |
| Others |
Value Network & Pricing Analysis
EPA certification mandates for rebuilt heavy-duty engines and EU REACH plating restrictions are forcing procurement toward documented batch traceability and trivalent chromium alternatives, compressing supplier margins and concentrating pricing power among German and Japanese machine shops with captive finishing capacity.
Pricing Analysis
Aftermarket catalog distributor margins absorb the steepest compression as circle-track builders consolidate procurement through standardized SKUs. Three-tier pricing structure across motorsport-grade, commercial remanufacturing, and economy replacement levels separates premium 0.001-inch flatness specifications from standard-duty tolerances. Pricing pressure stems from 4140 chromoly scrap volatility squeezing steel-variant producers. Commercial trucking rebuild shops exhibit highest price sensitivity; aerospace retrofit channels show least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Cummins and tier-one automotive powertrain divisions, while fragmented aftermarket demand flows through PRW Industries and digital procurement platforms. Raw material supply concentrates in Germany, Japan, and the United States, with 4140 chromoly steel billet and 6061-T6 aluminum extrusions feeding fabrication. Coating chemistry for EU REACH compliance and CNC finishing capacity for dimensional tolerance represent critical dependencies. Single-source vulnerability in Stuttgart-area precision machining creates bottleneck risk. Distribution runs through certified remanufacturing channels, direct technical sales for aerospace, and catalog aggregators for racing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The girdle plates market reads as a late-cycle quality story where forced-induction penetration and racing sanctioning body harmonization are shifting procurement toward documented engineering validation and premium material specifications.
For Market Incumbents: Cement market position through backward integration into billet-grade blank production and captive electroless nickel coating lines that satisfy EU REACH timelines. Defend against composite displacement threats by locking multi-year volume commitments with OEM turbocharger programs. Prioritize finite-element analysis talent acquisition to meet NHTSA defect investigation documentation requirements.
For New Entrants and Emerging Players: Capture white-space in electric drivetrain NVH damping applications where carbon-fiber-reinforced polymer prototypes command development premiums. Target California and Norway EV conversion shops with motor mount integration concepts. Pursue catalog standardization partnerships with emerging racing sanctioning bodies seeking engine integrity rule harmonization.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision machining specialists holding 0.001-inch flatness capacity and documented batch traceability systems. Five-to-ten-year viability favors suppliers with dual aluminum-steel capability and coating line retooling completion. Watch EPA heavy-duty engine certification rule expansions as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Retooling | Trivalent chromium and electroless nickel investments satisfy EU REACH compliance timelines for export-bound production. |
| CNC Capacity Expansion | 0.001-inch flatness finishing capacity in Germany and Japan limits supplier competition and commands specification premiums. |
| Composite R&D Partnerships | Carbon-fiber-reinforced polymer development with EV integrators opens noise-vibration-harshness damping applications. |
| Catalog Standardization | Single-SKU distribution through PRW Industries consolidates circle-track procurement across multiple racing sanctioning bodies. |
| Backward Integration | In-house billet-grade blank production insulates against 4140 chromoly scrap volatility and secures margin control. |
Research Methodology
Bottom-up engine builder and remanufacturing channel modeling reconciled against top-down billet-grade blank production tracking forms the analytical core of this study. Primary interviews with precision machining shop owners, OEM powertrain procurement managers, aftermarket catalog distributors, racing sanctioning body technical directors, and coating chemistry suppliers were validated against secondary sources including EPA certification databases, EU ECHA REACH filings, NHTSA defect investigation records, and racing rulebook archives. Triangulation across these vectors ensures specification-grade segmentation integrity.
Historical trendline analysis of material substitution patterns and forced-induction penetration rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include material category, application intensity, end-user technical sophistication, and delivery model complexity. CAGRs were derived from volume-weighted trajectory analysis incorporating OEM turbocharger program timelines and certified remanufacturing channel growth. Industry-specific inputs encompass 4140 chromoly price volatility indices and racing sanctioning body rulebook harmonization schedules.
Alloy steel commodity swings, REACH regulatory enforcement variance, and electric drivetrain substitution velocity are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Liquid Applied Roofing Market