
 Germany HVAC Market | 2026-2036
Germany HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Germany HVAC Market Insights
Heat pump electrification is fragmenting traditional boiler-centric supply chains across Germany. Robert Bosch GmbH leverages its combustion heritage while building inverter-driven heat pump capacity. Vaillant Group anchors its position through captive distribution networks in residential channels. Viessmann Climate Solutions SE specializes in hybrid systems that bridge hydrogen-ready boilers with electric heat pumps.
Germany HVAC encompasses climate control equipment for heating, ventilation, and air conditioning, typically operating between -15°C and 55°C ambient with refrigerant-based or hydronic heat transfer circuits designed for building thermal comfort and indoor air quality management. Split systems dominate residential retrofits where external space constraints limit centralized plant deployment. Heat pump technology leads growth as Germany's Building Energy Act phases out fossil-fuel-only heating in new construction. Commercial end users concentrate demand in office and logistics assets across Berlin, Munich, and Hamburg.
The EU Green Deal, Germany's Building Energy Act, and KBA efficiency standards shape product certification requirements and installation compliance timelines. Ecodesign regulations from Brussels mandate minimum seasonal performance factors that filter out legacy equipment from German distribution channels. Stakeholders must monitor hydrogen infrastructure commitments and grid capacity expansion plans to calibrate technology portfolios between all-electric and hybrid heating pathways.
Market Dynamics
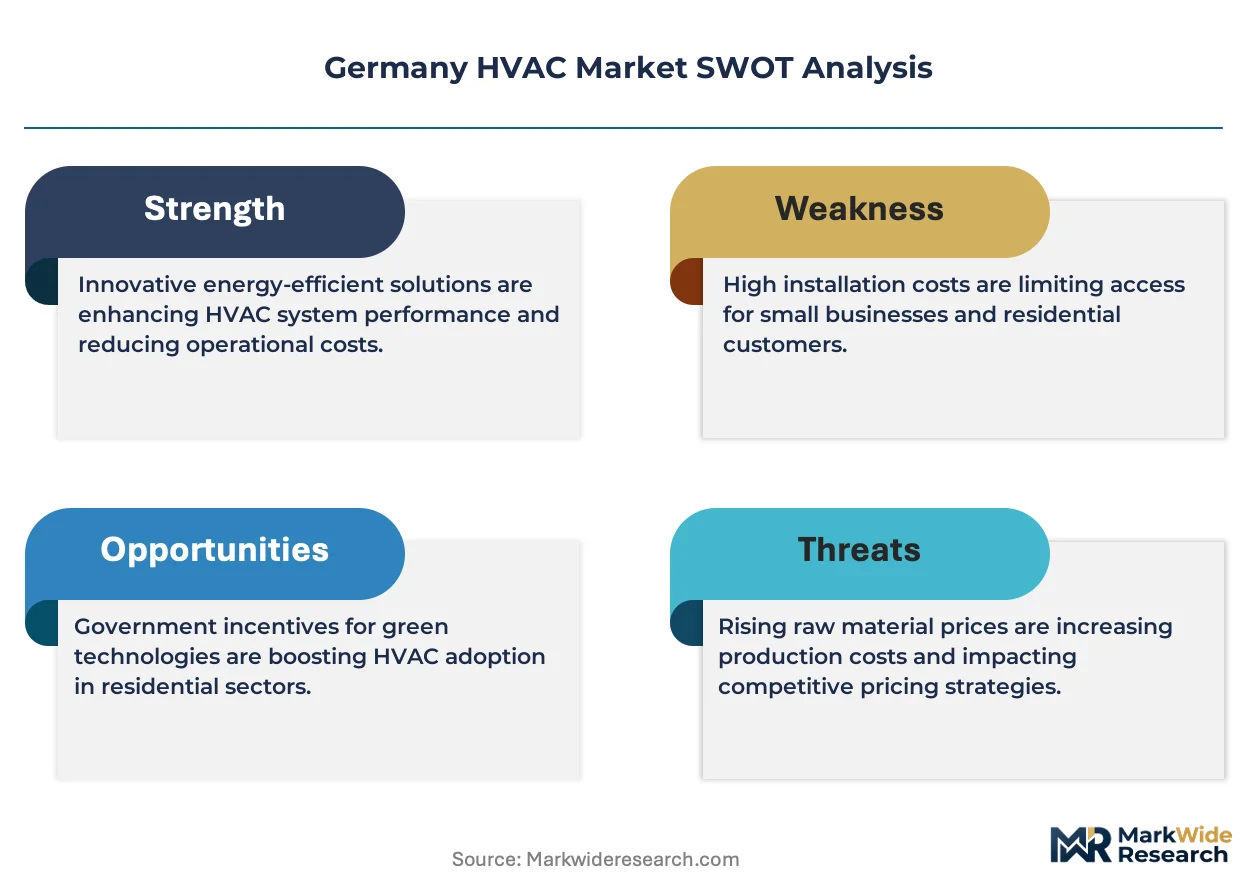
Heat pump electrification is dismantling Germany's century-old boiler-centric supply architecture, forcing incumbents to rebuild inverter-driven manufacturing capabilities while managing stranded combustion assets.
Growth Catalysts
- Building Energy Act:The 2024 mandate phases out fossil-fuel-only heating in new construction, compelling residential developers to specify electric heat pumps or hybrid systems.
- Bavaria commercial construction:Rising office and logistics permits in Munich and Nuremberg drive packaged rooftop unit demand from facility managers seeking centralized climate control.
- EU Green Deal Ecodesign tiers:Seasonal performance factor minimums filter legacy equipment from German distribution channels, clearing shelf space for high-efficiency models.
Market Restraints
- Copper and aluminum input volatility:Heat pump manufacturing depends on non-ferrous metal pricing that fluctuates with energy-intensive smelter economics across European supply chains.
- Grid capacity constraints:Distribution network operators in rural Baden-Württemberg and Saxony cannot guarantee sufficient amperage for widespread residential electrification.
- Natural gas price collapse:Temporary affordability of fossil heating delays payback calculations for heat pump retrofits in cost-sensitive owner-occupied housing.
Strategic Opportunities
- North Rhine-Westphalia industrial heat:Chemical and steel facilities in the Ruhr corridor seek large-scale heat pump integration for process steam decarbonization.
- Hydrogen-ready hybrid convergence:Manufacturers combining electric heat pumps with H2-capable boilers capture transitional demand from risk-averse building owners.
- KfW subsidy channel expansion:Federal promotional bank efficiency programs create direct financing pathways bypassing traditional distributor credit terms.
Industry Challenges
- F-gas refrigerant handling certification:Installer capacity bottlenecks emerge as EU F-Gas Regulation demands specialized credentials for R32 and R290 systems that most plumbing contractors lack.
- Legacy hydronic integration complexity:Retrofit projects confront mismatched flow temperatures between existing radiator circuits and low-temperature heat pump output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany HVAC Market |
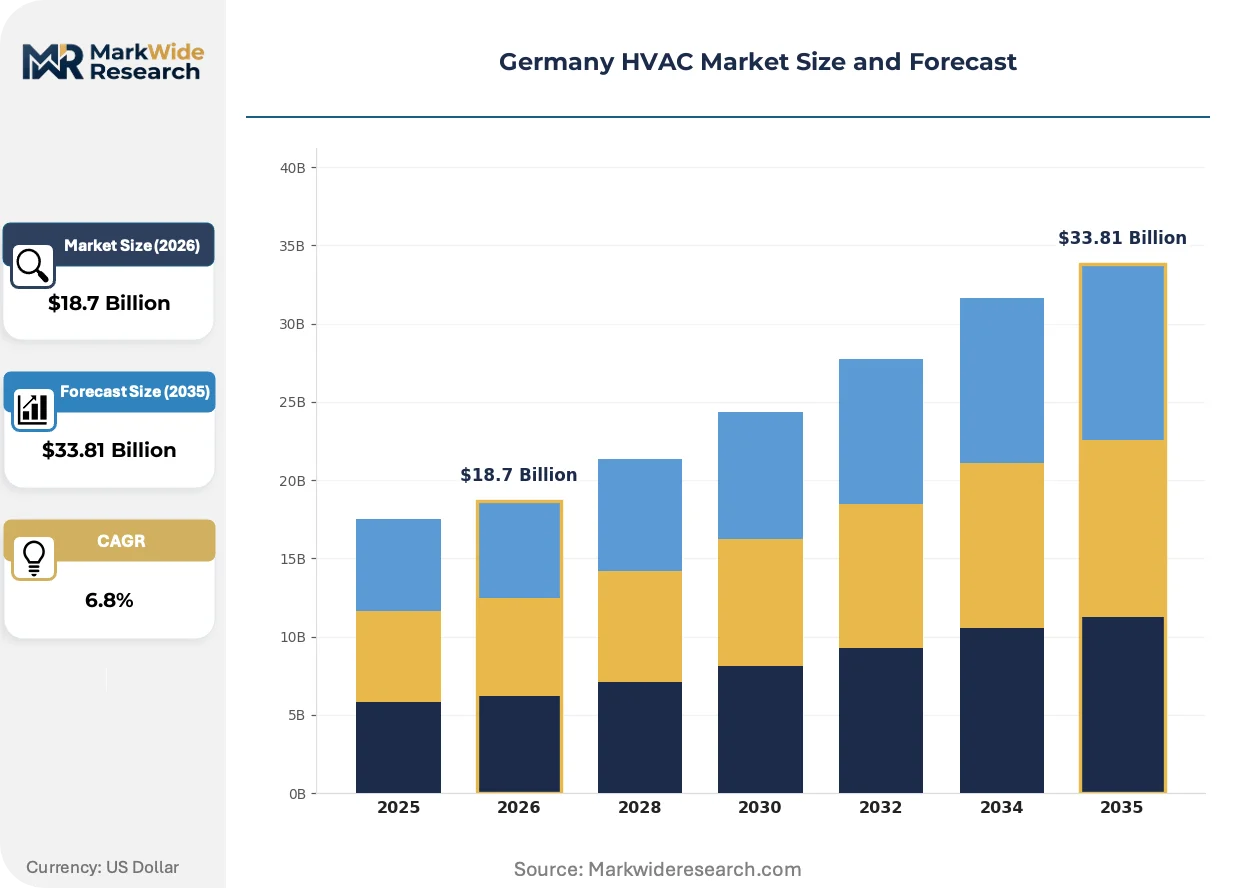
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Centralized Systems, Ductless Systems, VRF Systems End User: Residential, Commercial, Industrial, Government Technology: Heat Pumps, Chillers, Boilers, Radiant Heating Installation Type: New Construction, Retrofit, Modular, Hybrid |
| Companies Covered | Robert Bosch GmbH, Vaillant Group, Viessmann Climate Solutions SE, Daikin Industries Ltd, Johnson Controls International PLC, Carrier Global Corporation, Midea Group Co. Ltd, Stiebel Eltron GmbH & Co. KG, Wolf GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany HVAC Market Trends and Innovations
Digitalization is compressing equipment commissioning cycles and enabling remote diagnostics that alter service revenue models across German HVAC channels.
Refrigerant virtualization is virtualizing system architecture by replacing centralized chillers with distributed inverter-driven units. Facility managers in Berlin commercial assets adopt these modular configurations for zoned control. The technology is virtualizing traditional plant room footprints and enabling floor-by-floor climate autonomy without riser infrastructure.
EU F-Gas Regulation phase-down schedules force refrigerant transitions toward lower-GWP alternatives. Manufacturers reformulate product lines around R290 propane and R32 blends ahead of quota restrictions. Residential heat pump portfolios face the steepest retooling requirements as import limits tighten on legacy HFC compounds.
Building owners now unbundle long-term service contracts from initial equipment procurement. Corporate real estate teams in Hamburg and Frankfurt source climate systems through capital expenditure budgets while contracting maintenance separately to specialized providers. This bifurcation pressures OEMs to defend aftermarket revenue through predictive analytics subscriptions rather than captive service agreements.
Germany HVAC Market Segmentation
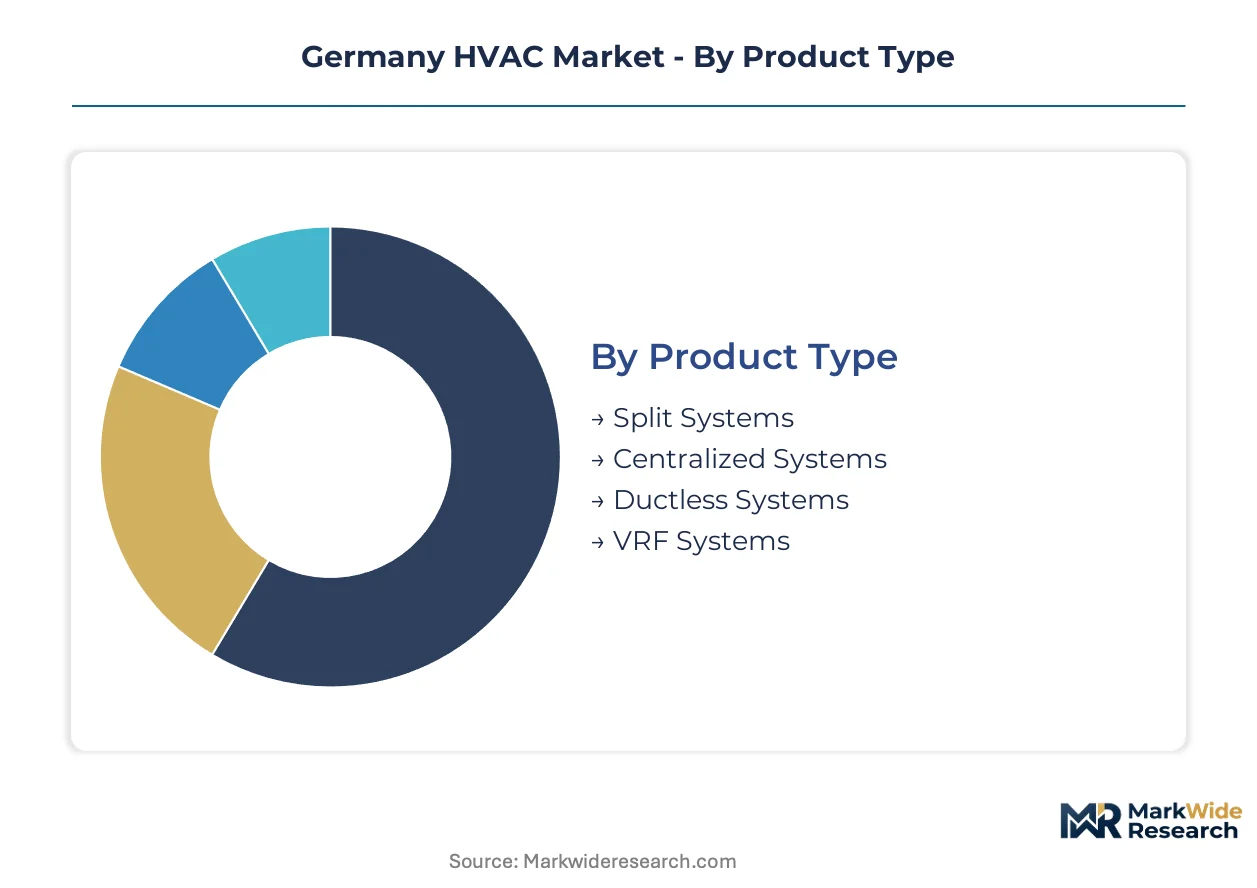
Segmentation in the Germany HVAC market reveals how electrification mandates and building stock characteristics reshape procurement patterns across equipment categories. Understanding these divisions exposes where stranded assets concentrate and where new capacity investments flow.
Product Type:
Mature hydronic systems coexist with emerging refrigerant-based architectures as the Building Energy Act forces technology transitions.
- Split Systems:Outdoor compressor units paired with indoor air handlers use R32 or R290 refrigerant circuits. Bavaria and Baden-Württemberg residential retrofits drive volume where external space constraints prevent centralized plant deployment, though F-gas handling certification bottlenecks slow installer capacity expansion.
- Centralized Systems:Chiller and boiler plants with hydronic distribution serve large floorplates through centralized plant rooms. Munich and Hamburg commercial assets specify these for base-load efficiency, but legacy gas boiler conversions face flow temperature mismatches with low-temperature heat pump output.
- Ductless Systems:Wall-mounted or ceiling cassette units deliver zoned cooling without air distribution infrastructure.
- VRF Systems:Variable refrigerant flow configurations enable simultaneous heating and cooling across building zones.
Split systems handle the majority of throughput; VRF systems are expanding most quickly on share as commercial assets pursue zoned efficiency.
End User:
Cost tier stratification separates subsidy-dependent residential demand from commercial procurement governed by total cost of ownership calculations.
- Residential:Single-family and multi-family building owners replace aging gas boilers under KfW promotional bank financing. North Rhine-Westphalia and Lower Saxony concentrate retrofit demand where 1970s building stock reaches replacement age.
- Commercial:Office, retail, and logistics facility managers in Berlin, Munich, and Frankfurt procure through capital expenditure budgets unbundled from long-term service contracts.
- Industrial:Process heating and climate control for manufacturing footprints.
- Government:Public building portfolios including schools, hospitals, and administrative facilities.
Residential dominates absolute unit volume; commercial is climbing the fastest as corporate real estate teams accelerate decarbonization timelines.
Technology:
Application requirements determine whether sites prioritize electrification readiness or transitional hybrid architectures.
- Heat Pumps:Air-source and ground-source electric systems extract ambient thermal energy through vapor compression cycles. New construction mandates under the Building Energy Act compel specification, though rural grid capacity constraints in Saxony and Thuringia limit deployment feasibility.
- Chillers:Refrigeration-based cooling plants serve commercial and industrial process loads.
- Boilers:Condensing gas and hydrogen-ready combustion systems retain share in hybrid configurations.
- Radiant Heating:Hydronic or electric floor and wall panel systems.
Heat pumps command the steepest expansion trajectory; boilers retain defensive share through hybrid integration.
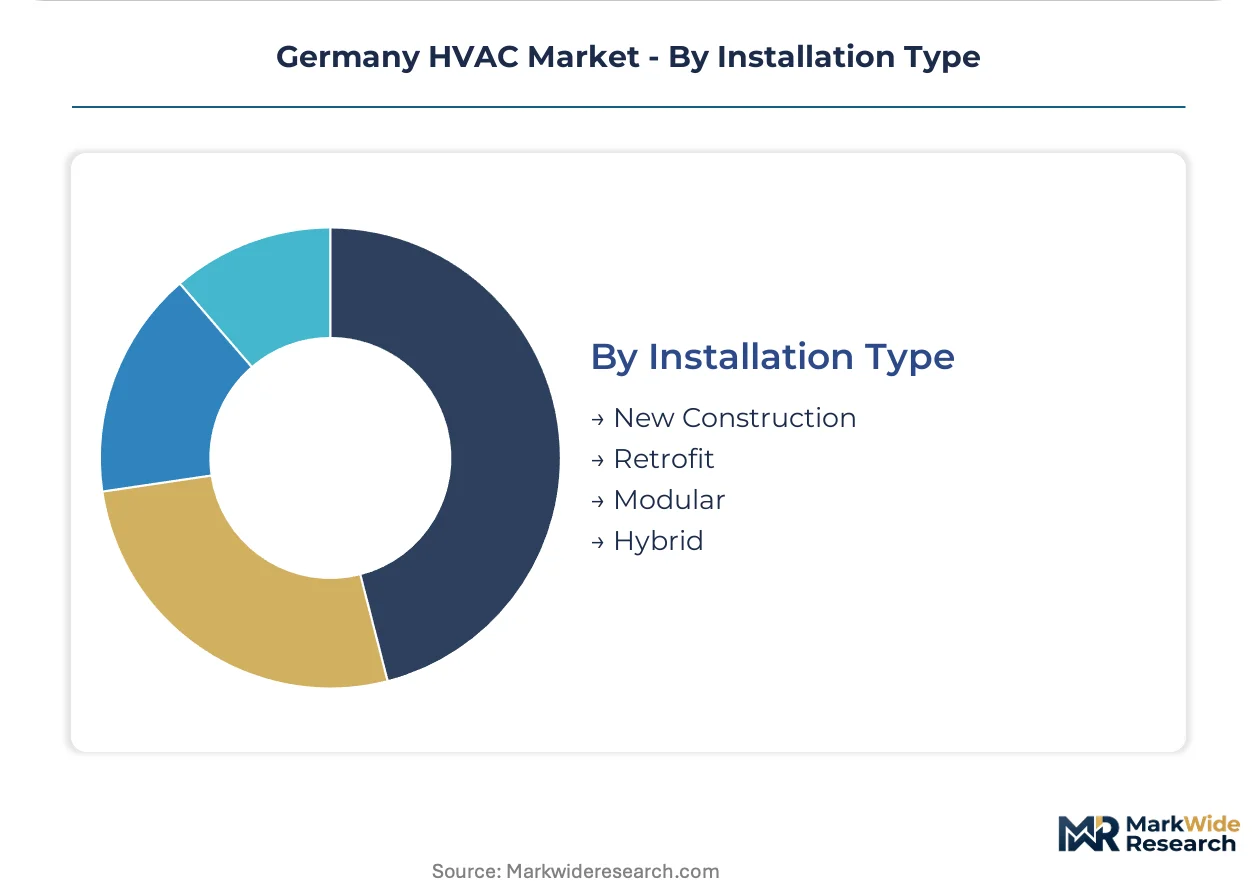
Installation Type:
Volume concentration varies between new construction pipelines and the fragmented retrofit opportunity across Germany's existing building stock.
- New Construction:Greenfield residential and commercial developments specify compliant systems from foundation phase. Rising construction permits in Bavaria's Munich-Nuremberg corridor drive packaged rooftop and heat pump plant demand.
- Retrofit:Existing building system replacements confront legacy hydronic integration complexity and flow temperature mismatches.
- Modular:Prefabricated plant room or distributed unit configurations.
- Hybrid:Combined electric heat pump and hydrogen-ready boiler installations.
New construction maintains steady throughput; retrofit is gaining share fastest as the 2024 mandate accelerates replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German HVAC equipment flows primarily toward domestic installation channels, with limited export activity concentrated in neighboring EU member states seeking high-efficiency heat pump technology compliant with Ecodesign standards.
Bavaria
Commercial construction permits in Munich and Nuremberg drive packaged rooftop unit demand from logistics and office developers. The Building Energy Act mandates heat pump specification in new residential developments across the state. Munich's corporate real estate sector accelerates VRF system procurement for zoned climate control in premium office assets.
North Rhine-Westphalia
Industrial process heat demand from Ruhr corridor chemical and steel facilities creates large-scale heat pump integration opportunities. KfW promotional bank efficiency programs channel direct financing to retrofit projects in Cologne and Düsseldorf residential zones. Dortmund's manufacturing footprint sustains chiller demand for production facility climate control.
Baden-Württemberg
Rural grid capacity constraints limit residential electrification feasibility in Black Forest municipalities despite strong heat pump adoption intent. EU F-Gas Regulation phase-down schedules force local installer networks toward R290 propane certification. Stuttgart's automotive supplier ecosystem generates commercial HVAC demand from precision manufacturing facilities requiring tight environmental control.
Lower Saxony
1970s building stock replacement cycles concentrate retrofit demand in Hanover and Braunschweig suburban corridors. The Building Energy Act accelerates gas boiler phase-out timelines for owner-occupied housing eligible for federal subsidies. Wolfsburg's industrial zone sustains centralized chiller plant demand from automotive assembly operations.
Berlin-Brandenburg
Public building portfolios including schools and administrative facilities drive government segment procurement through centralized tender processes. Ecodesign seasonal performance factor minimums filter legacy equipment from Berlin distribution channels. Potsdam's research campus generates specialized laboratory HVAC demand requiring precision temperature and humidity control systems.
Germany HVAC Market Competitive Landscape
On the supply side, the industry is consolidating around diversified industrial conglomerates with captive combustion heritage rebuilding for electrification, while specialized heat pump manufacturers capture subsidy-driven residential demand. Three strategic archetypes dominate: diversified industrial groups with legacy boiler assets transitioning to inverter-driven manufacturing, pure-play heat pump specialists leveraging subsidy channel access, and Asian-scale manufacturers exporting cost-optimized equipment through distributor partnerships. Competitive moves center on hydrogen-ready hybrid system development and direct-to-installer digital platform deployment that bypasses traditional wholesale channels.
Among Germany-based industrial groups, Robert Bosch GmbH, Vaillant Group, and Viessmann Climate Solutions SE occupy positions that exemplify the combustion-to-electrification transition archetype. These entities anchor the premium tier through established installer relationships and captive distribution networks, representing defensive positioning against Asian-scale competitors. Their market presence reflects century-old hydronic expertise now retooling for refrigerant-based heat pump architectures under regulatory pressure from Brussels and Berlin.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Vaillant Group |
| Viessmann Climate Solutions SE |
| Daikin Industries Ltd |
| Johnson Controls International PLC |
| Carrier Global Corporation |
| Midea Group Co. Ltd |
| Stiebel Eltron GmbH & Co. KG |
| Wolf GmbH |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum smelter concentration in Germany's neighboring EU member states anchors cost volatility for compressor and heat exchanger manufacturing, directing margin pools toward inverter control electronics and refrigerant handling certification tiers where domestic capability scarcity commands premium positioning.
Pricing Analysis
Legacy R410A equipment sits at 15-20% discount to R32 and R290 next-generation systems, creating a technology-generation pricing gap that widens as EU F-Gas Regulation quotas tighten. Project-based transactional pricing dominates residential retrofits through KfW-subsidized channels, while commercial procurement favors three-tier pricing structure across premium, standard, and economy levels differentiated by seasonal performance factor certification and after-sales bundling. Price erosion runs through standard-tier split systems as Asian-scale manufacturers expand distributor partnerships. Residential owner-occupiers in North Rhine-Westphalia show highest price sensitivity, whereas Munich corporate real estate teams prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Contract manufacturing for inverter drives and compressor assemblies concentrates with Flex and Jabil facilities in Poland and Hungary serving German OEM assembly plants. Heat pump manufacturing draws from copper tube mills in Germany and Austria, refrigerant blenders in Belgium and the Netherlands, and power electronics from Taiwanese semiconductor foundries. Single-source vulnerability sits with rare earth magnet supply for high-efficiency compressor motors. Distribution runs through captive installer networks and specialized HVAC wholesalers rather than general construction merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as digital commissioning tools and remote diagnostics subscriptions unbundle hardware from service revenue, creating interoperability standards battles between OEM-proprietary and open-protocol ecosystems.
For Market Incumbents: Build captive certification capacity moats by acquiring R290 propane handling training providers before installer bottlenecks constrain heat pump deployment velocity. Defend against pure-play heat pump specialists by integrating hydrogen-ready boiler architectures into hybrid offerings that preserve existing hydronic customer relationships. Deepen backward integration into inverter control electronics manufacturing to offset copper and aluminum input volatility. For New Entrants and Emerging Players: Pursue white-space penetration in rural Baden-Württemberg and Saxony residential retrofits where grid capacity constraints delay incumbent electrification timelines. Target commercial VRF system segments in Berlin and Frankfurt where corporate real estate decarbonization mandates outpace established service network coverage. Anchor go-to-market through direct-to-installer digital platforms that bypass traditional wholesale markups and capture subsidy channel access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed HVAC distributors holding 1970s-era customer databases across North Rhine-Westphalia and Lower Saxony replacement corridors. Five-to-ten year viability hinges on successful transition from combustion-centric to refrigerant-based service capabilities. Watch hydrogen infrastructure commitment announcements from German transmission system operators as inflection signal for hybrid technology pathway durability.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Control Electronics Backward Integration | Captures margin pool shifting from combustion hardware to power electronics as heat pump volumes displace boilers. |
| R290 Propane Certification Program Expansion | Secures installer capacity ahead of EU F-Gas Regulation phase-down deadlines that constrain R32 supply. |
| Direct-to-Installer Digital Platform Launch | Bypasses traditional wholesale channels where Vaillant and Bosch maintain captive distribution dominance. |
| Hydrogen-Ready Hybrid System Development | Captures transitional demand from risk-averse building owners awaiting grid capacity and hydrogen infrastructure clarity. |
| Predictive Analytics Subscription Rollout | Defends aftermarket revenue as corporate real estate teams unbundle long-term service contracts from equipment procurement. |
Research Methodology
Operator-level perspectives from HVAC installation contractors, facility management directors at Munich and Frankfurt commercial assets, regional distributor procurement managers, and KfW promotional bank program officers anchored the qualitative base. Secondary validation drew from BAFA subsidy disbursement records, VDMA industry association equipment shipment data, and EU Ecodesign compliance filings. Bottom-up equipment unit estimates triangulated against top-down construction permit and building stock replacement cycle projections.
Scenario-bracketing framed the analytical approach across the analysis window, modeling demand sensitivity to natural gas price trajectories and grid capacity expansion timelines. Segmentation dimensions spanned product architecture, end-user cost tier, technology electrification readiness, and installation type feasibility. CAGRs derived from equipment replacement cycle acceleration under Building Energy Act mandates and commercial construction permit trends in Bavaria and North Rhine-Westphalia.
Macroeconomic conditions sit as an overlay; deviation in construction interest rates and non-ferrous metal smelter energy costs would shift the trajectory. Forecasts reflect documented assumptions about subsidy program continuity and hydrogen infrastructure deployment pace. Cross-checking against VDMA quarterly equipment shipment benchmarks and BAFA installation subsidy approval data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
North America Ceiling Cassette Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market