
 United States I-Joist Market | 2026-2036
United States I-Joist Market Size, Share, and Industry Trends Forecast 2026-2036
United States I-Joist Market Intelligence
Market Context with Strategic Players
North American engineered lumber producers is decoupling from traditional sawn lumber cycles through dedicated I-joist capacity expansions. Louisiana-Pacific Corporation leverages vertical integration from timberlands to finished joists across its southern mill network. Weyerhaeuser Company anchors large-scale production through Pacific Northwest facilities serving West Coast construction markets. Boise Cascade Company differentiates via wholesale distribution control and contractor-direct channel relationships.
Technical Definition and Structural Segments
An I-joist consists of laminated veneer lumber or solid sawn flanges bonded to an oriented strand board web, engineered to span longer distances with less material than dimensional lumber. The product primarily supports residential and commercial floor and roof systems where consistent load-bearing performance and dimensional stability matter. Wood I-joists dominate residential construction applications due to cost efficiency and builder familiarity, while composite variants gain traction in renovation projects requiring moisture resistance. Direct sales channels to national home builders capture volume, though wholesalers retain importance for regional contractor supply.
Regulatory Framework and Outlook
APA — The Engineered Wood Association performance standards, IRC structural provisions, and state-level building codes govern I-joist specification, installation, and inspection protocols across US jurisdictions. IRC adoption cycles and local amendments directly determine allowable spans, fire-blocking requirements, and connector hardware mandates that shape product design. Stakeholders must monitor state energy code evolution and potential embodied carbon disclosure rules that could alter material selection criteria in multi-family and commercial segments.
Market Dynamics
Residential construction cycles and APA certification standards are forcing engineered lumber producers to synchronize capacity expansion with regional housing permit volatility and code adoption timelines.
Growth Catalysts
- IRC Structural Provisions:Updated International Residential Code span tables and fire-blocking requirements are mandating engineered lumber in multi-story residential builds across jurisdictions that adopted the 2021 and 2024 cycles.
- Open Floor Plan Architecture:Custom home builders and national production builders specify I-joists to achieve longer clear spans without intermediate bearing walls, reducing material waste and labor hours.
- Southeast Housing Cluster:Georgia, Texas, and Florida permit activity concentrates demand where mass timber mill networks and distribution infrastructure already exist.
Market Restraints
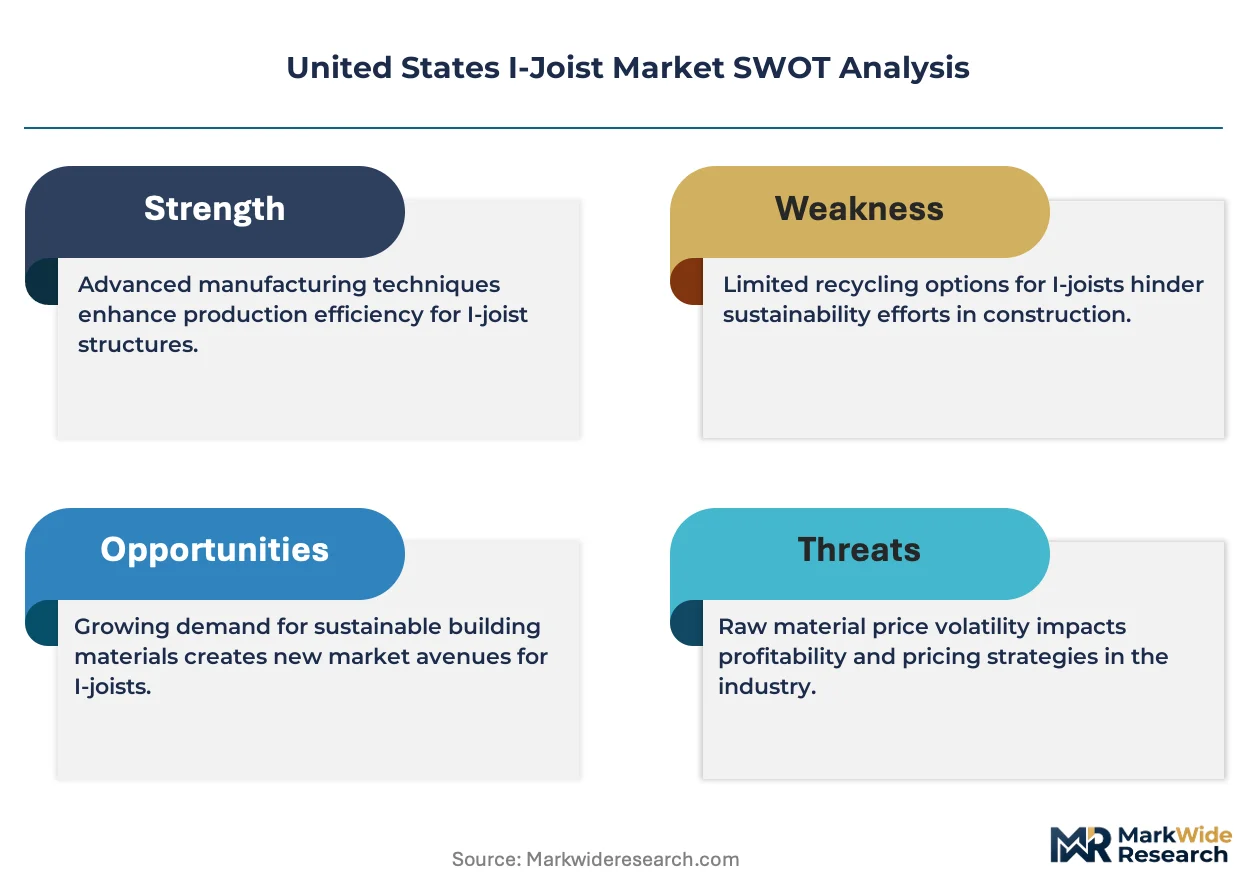
- OSB Web Input Volatility:Oriented strand board pricing fluctuates with North American timber harvest cycles and resin chemical costs, compressing margin predictability for joist fabricators.
- Skilled Installation Shortage:Proper I-joist installation requires familiarity with specific connector hardware and blocking protocols that differ from dimensional lumber practices, creating field execution risk.
- Dimensional Lumber Substitution:Sawn lumber price collapses during housing downturns trigger builder reversion to traditional framing, particularly in entry-level housing segments.
Strategic Opportunities
- Multi-Family Embodied Carbon Rules:Emerging city-level disclosure mandates in California and New York favor mass timber structural systems over steel and concrete in mid-rise construction.
- Moisture-Resistant Composite Webs:Hybrid I-joists incorporating synthetic or treated web materials address renovation markets in flood-prone Gulf Coast and Pacific Northwest regions.
- Direct-to-Builder Digital Platforms:E-procurement channels bypass traditional two-step distribution, capturing specification data and reducing quote-to-delivery cycles for regional contractors.
Industry Challenges
- APA Certification Timelines:New product variant qualification requires extensive third-party testing and mill audits, delaying market entry for modified flange or web configurations.
- Field Modification Risk:Jobsite cutting and notching of I-joists without engineered repair detail creates liability exposure and callback costs for builders and insurers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States I-Joist Market |
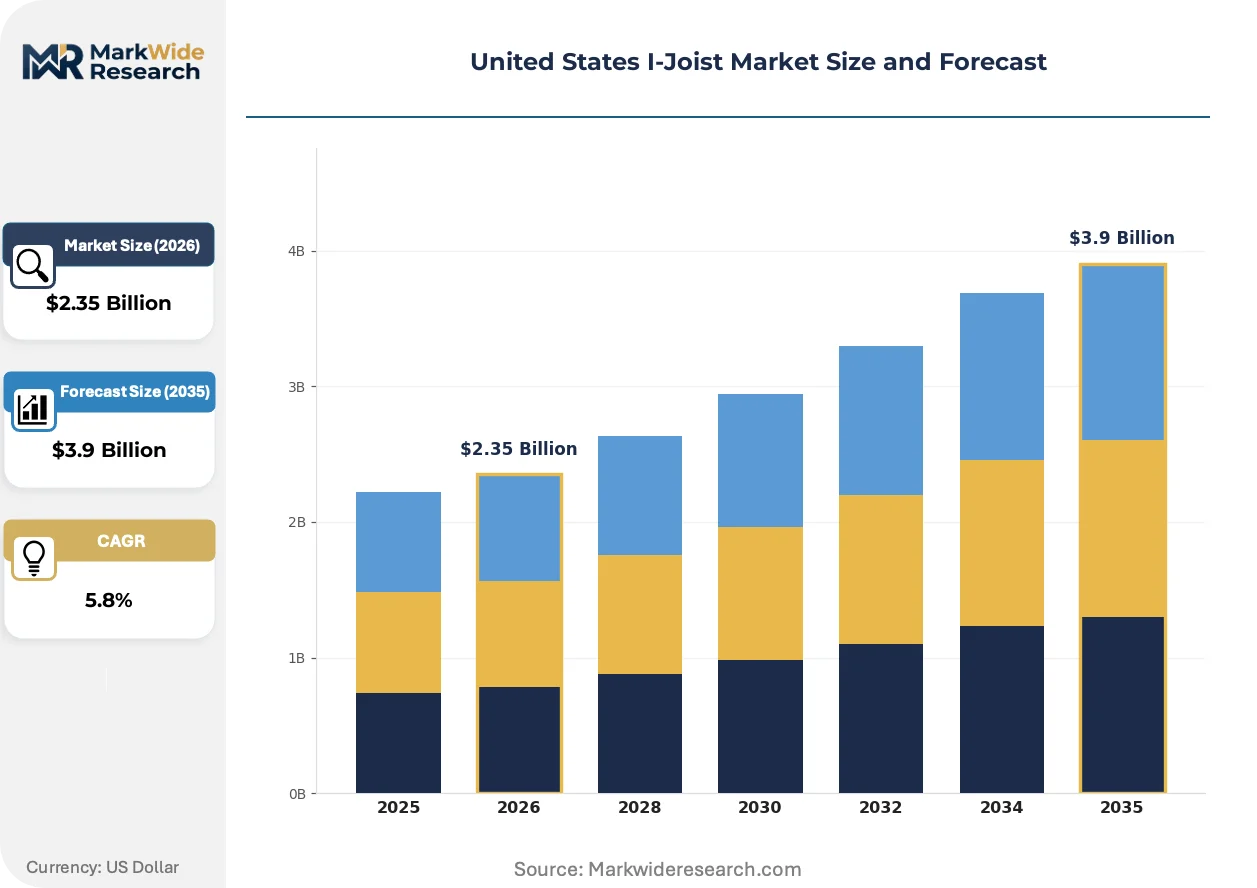
| Market Size in 2026 | $2.35 Billion |
| Market Size in 2035 | $3.9 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Composite, Steel, Hybrid Application: Residential Construction, Commercial Construction, Industrial Applications, Renovation Projects End User: Home Builders, Contractors, Architects, Engineers Distribution Channel: Direct Sales, Wholesalers, Distributors, Retailers |
| Companies Covered | Louisiana-Pacific Corporation, Anthony Forest Products Co, Weyerhaeuser Company, REDBUILT, Stark Truss Company, Inc., Georgia-Pacific LLC, Roseburg Forest Products Co., PFS Corporation, Boise Cascade Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States I-Joist Market Strategic Shifts & Innovations
Digital specification tools and automated manufacturing are compressing design-to-delivery cycles while regulatory pressure on carbon disclosure is elevating engineered wood's competitive position against structural steel.
Automated flange-to-web pressing systems with real-time quality sensing are electrifying production consistency across southern US mill networks. Large-scale producers deploy these lines to reduce lamination defects and scrap rates. The technology is electrifying throughput economics, enabling shorter runs of custom lengths without changeover penalties that previously favored commodity dimension lumber.
State-level energy code evolution and potential embodied carbon disclosure frameworks are reshaping material selection protocols in multi-family and commercial segments. California's CALGreen amendments and pending New York City Local Law 97 expansions create compliance-driven specification pull. Developers in these jurisdictions increasingly pre-specify mass timber systems to meet reporting thresholds and avoid carbon penalties.
Specification authority is consolidating among national production builders with centralized engineering teams that standardize I-joist details across regional divisions. Regional contractors and custom builders lose influence as procurement centralizes at corporate headquarters. This concentration is most visible in Texas and Arizona markets where top-ten builders control over half of single-family starts.
United States I-Joist Market Segmentation
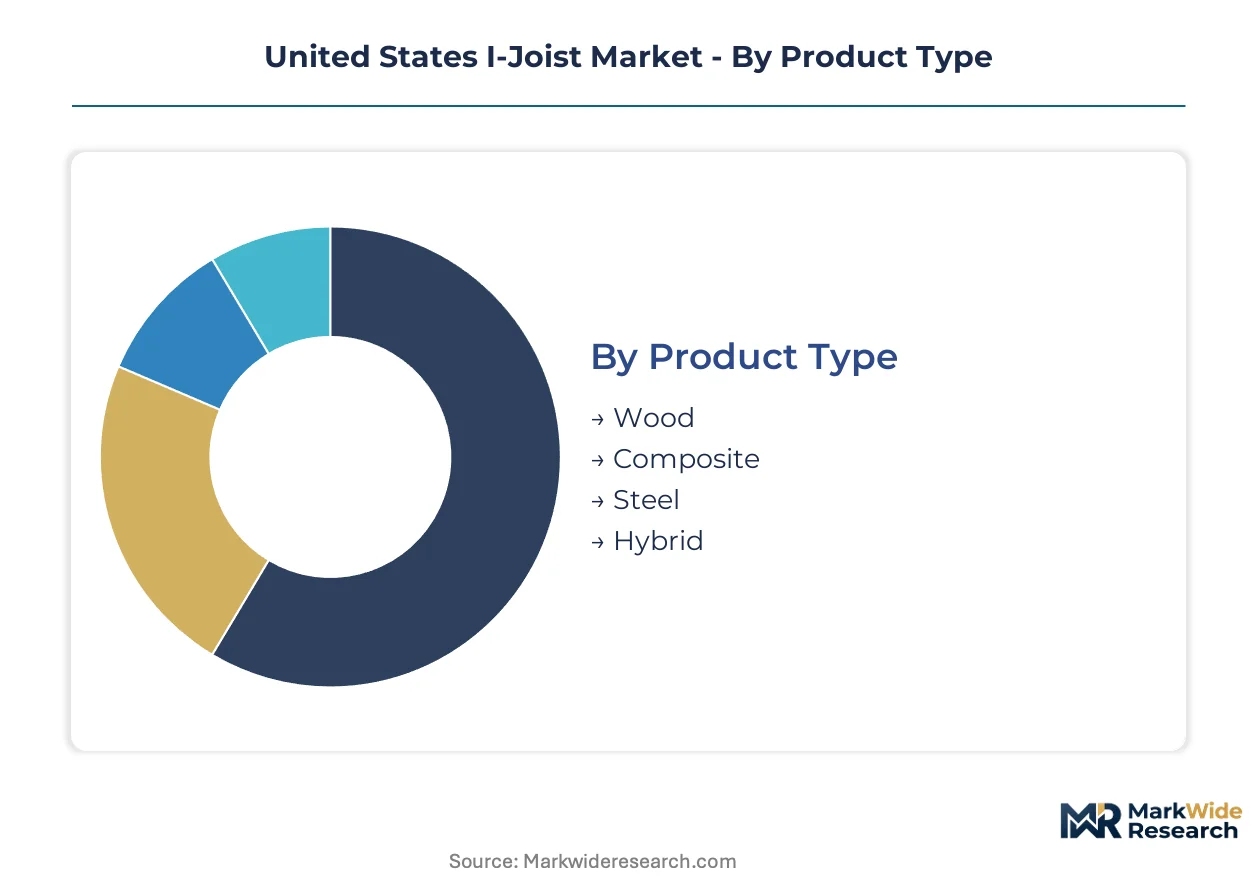
I-joist specification varies sharply by structural application, with APA certification requirements and IRC span table compliance determining which product types qualify for specific build categories. Segmentation reveals how engineered lumber producers align manufacturing capacity with distinct customer procurement patterns and channel economics.
Product Type:
APA certification burdens fall heaviest on wood and composite variants, which require extensive third-party testing for flange-to-web bond integrity and long-term load performance. Steel and hybrid configurations face alternate compliance pathways through AISI standards and proprietary engineering approvals.
- Wood:Laminated veneer lumber or solid sawn flanges bonded to OSB webs dominate residential floor and roof systems. Georgia and Texas home builders specify these for cost efficiency in production housing tracts where IRC span tables govern allowable distances.
- Composite:Synthetic or treated web materials bonded to engineered flanges address moisture-prone renovation markets. Gulf Coast contractors favor these for flood-zone rebuilds where dimensional stability under cyclic wetting matters more than first-cost savings.
- Steel:Cold-formed steel webs with wood or steel flanges serve commercial mid-rise projects requiring longer spans and fire ratings.
- Hybrid:Mixed material configurations combining wood flanges with composite or steel webs target specialized architectural specifications demanding custom load profiles.
Wood sits at the top of the volume ranking, with composite climbing the fastest as moisture-resistant specifications spread beyond traditional coastal markets.
Application:
Cost tier stratification separates commodity residential volume from premium commercial and industrial segments, with renovation projects occupying a mid-tier pricing band driven by labor intensity rather than material specification.
- Residential Construction:Single-family and multi-family floor and roof systems represent the core demand base. National production builders in Arizona and Florida standardize I-joist details across regional divisions, concentrating procurement authority at corporate engineering teams.
- Commercial Construction:Mid-rise office and retail structures specify I-joists for flat roof assemblies and mechanical platform framing. California developers increasingly pre-specify mass timber systems to meet CALGreen embodied carbon disclosure thresholds.
- Industrial Applications:Warehouse and manufacturing facilities utilize I-joists for mezzanine structures and crane support platforms requiring engineered load calculations.
- Renovation Projects:Existing structure modifications demand shorter lead times and flexible lengths, favoring distributors with cutting and kitting capabilities over mill-direct channels.
Residential construction commands the greatest volume concentration, with commercial applications gaining share fastest under carbon compliance pressure in coastal jurisdictions.
End User:
Customer type determines specification authority concentration, with centralized engineering teams at national builders displacing traditional architect and contractor influence over product selection.
- Home Builders:Production and custom builders drive material selection based on cycle time and labor efficiency metrics. Top-ten builders in Texas control over half of single-family starts, standardizing I-joist specifications across their divisions.
- Contractors:Regional framing crews execute installation but lose procurement influence as builder headquarters centralize purchasing. Skilled installation shortages create field execution risk where crews lack familiarity with connector hardware protocols.
- Architects:Design professionals specify I-joists for open floor plan aesthetics and mechanical routing flexibility, particularly in custom residential and boutique commercial projects.
- Engineers:Structural consultants validate span calculations and fire-blocking details, serving as gatekeepers for code compliance in multi-story and non-residential applications.
Home builders sit at the top of the volume ranking, with engineers climbing the fastest as structural complexity rises in mid-rise mass timber construction.
Distribution Channel:
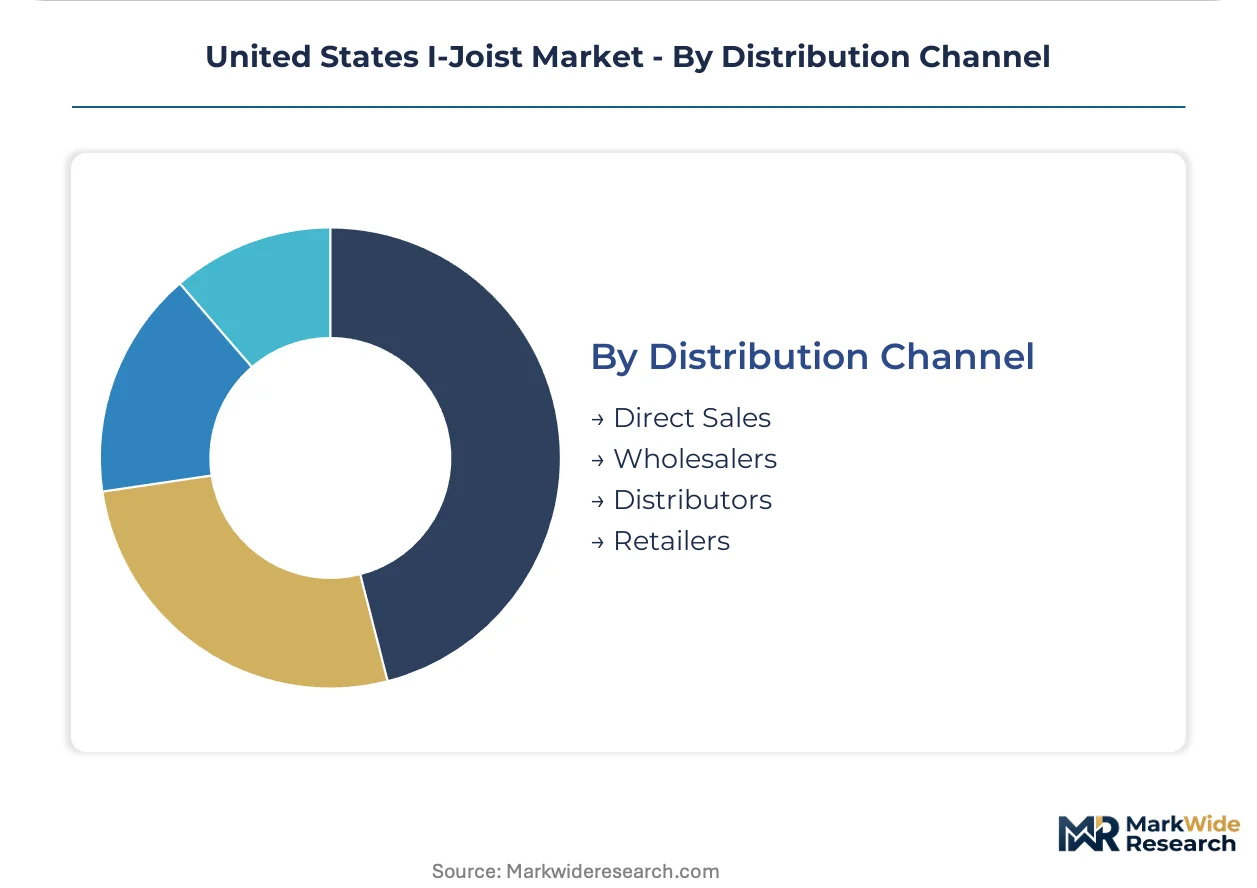
Supply concentration shapes channel economics, with direct sales capturing volume from national accounts while regional wholesalers retain relevance for contractor spot purchases and renovation project fulfillment.
- Direct Sales:Mill-direct relationships with national home builders bypass distribution markups and capture specification data. Large producers deploy e-procurement platforms to compress quote-to-delivery cycles for recurring customers.
- Wholesalers:Regional lumber yards serve contractor accounts requiring immediate availability and credit terms. These intermediaries retain importance in markets where housing permit volatility makes inventory risk unacceptable for mills.
- Distributors:Specialized engineered wood distributors offer technical support, design software, and kitting services for complex commercial projects.
- Retailers:Big-box and independent retailers capture small-project and DIY renovation demand with limited product ranges and standard lengths.
Direct sales sit at the top of the volume ranking, with distributors climbing the fastest as commercial project complexity demands value-added technical services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates North American I-joist consumption, while Canada maintains a smaller but technically advanced production base serving cross-border demand. Regional demand patterns track housing permit volatility, state-level code adoption timelines, and proximity to engineered wood mill networks.
Southeast
Georgia, Florida, and Texas generate the densest housing starts in the nation, concentrating demand for wood I-joists in single-family production tracts. The International Residential Code 2021 and 2024 cycle adoptions across these states mandate engineered lumber for multi-story residential fire-blocking compliance. Mass timber mill clusters in southern Georgia and eastern Texas anchor regional supply chains with direct rail and truck distribution to Atlanta, Dallas-Fort Worth, and Houston construction markets.
Pacific Northwest
Oregon and Washington housing markets favor engineered lumber for moisture-resistant floor systems in wet climate conditions. APA — The Engineered Wood Association certification requirements govern product acceptance across Washington's amended state building code. Portland and Seattle-Tacoma metro areas concentrate specification authority among regional production builders with centralized engineering teams standardizing I-joist details across divisions.
Southwest
Arizona and Nevada desert construction markets specify I-joists for thermal performance and dimensional stability under extreme temperature cycling. California's CALGreen embodied carbon disclosure amendments create spillover specification pull in Phoenix and Las Vegas multi-family developments seeking preemptive compliance frameworks. Distribution infrastructure from southern California engineered wood terminals supplies these inland markets with two-day delivery coverage.
Midwest
Illinois, Ohio, and Michigan industrial corridor markets utilize I-joists for warehouse mezzanine structures and manufacturing facility crane support platforms. State energy code evolution in these jurisdictions lags coastal adoption cycles, delaying mass timber specification in commercial segments. Chicago and Detroit regional distribution hubs maintain inventory positions to serve contractor spot purchasing amid volatile housing permit patterns.
United States I-Joist Market Key Industry Players
Southern US producers anchor one tier; Pacific Northwest specialists hold another in a market structure defined by timberland proximity and distribution infrastructure concentration. The competitive terrain splits between vertically integrated forest products conglomerates with captive timber supply and independent fabricators reliant on purchased veneer and OSB inputs. Two strategic archetypes dominate: scale-driven national suppliers serving top-ten production builders, and regional specialists capturing custom home and renovation project volume. Capacity expansion and direct-to-builder digital platform development constitute the primary competitive vectors reshaping channel economics.
Among vertically integrated forest products companies, Louisiana-Pacific Corporation, Weyerhaeuser Company, and Boise Cascade Company occupy positions representing distinct strategic approaches. Louisiana-Pacific exemplifies the southern mill network archetype with backward integration from timberlands through finished joist production. Weyerhaeuser anchors Pacific Northwest production gravity serving West Coast construction markets with proximity advantages. Boise Cascade sits within the wholesale distribution control archetype, differentiating through contractor-direct channel relationships and e-procurement platform investments.
| Leading Market Players |
|---|
| Louisiana-Pacific Corporation |
| Anthony Forest Products Co |
| Weyerhaeuser Company |
| REDBUILT |
| Stark Truss Company, Inc. |
| Georgia-Pacific LLC |
| Roseburg Forest Products Co. |
| PFS Corporation |
| Boise Cascade Company |
| Others |
Cost & Logistics Intelligence
California's CALGreen embodied carbon disclosure amendments gate qualified supply for premium-tier I-joist specifications and anchor pricing power for APA-certified producers serving multi-family developers in coastal jurisdictions. Builders seeking preemptive compliance face narrower supplier pools and elevated procurement costs relative to standard-grade alternatives.
Pricing Analysis
Capacity additions in Georgia and Texas are reshaping price floors for standard wood I-joists as southern mill networks expand output for single-family production builders. Three-tier pricing structure across APA-certified premium, standard IRC-compliant, and economy-grade tiers differentiates offerings, with certification level and volume scale as primary drivers. Pricing pressure stems from OSB web input volatility as resin chemical costs fluctuate. Entry-level home builders exhibit highest price sensitivity, while national production builders with centralized procurement show lowest sensitivity due to contract-based offtake structures.
Supply Chain Analysis
Skilled press operator availability in southern Georgia and eastern Texas constrains automated flange-to-web bonding line throughput at expanded mill facilities. Geographic supply concentration centers on the United States, with cross-border flows from Canadian engineered wood producers serving northern tier states. Raw material dependencies draw from North American timber harvest cycles, resin chemical markets, and laminated veneer lumber supply. Single-source vulnerability for OSB web inputs creates supply chain risk during housing demand surges. Distribution runs through direct mill-to-builder channels for national accounts and regional lumber yards for contractor spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States I-Joist Market functions as a regulatory compounder where IRC adoption cycles and state-level energy code evolution structurally expand addressable demand for engineered lumber in multi-story residential construction.
For Market Incumbents: Hedge against dimensional lumber substitution risk by deepening captive timberland positions and accelerating APA certification investments for modified web configurations. Louisiana-Pacific and Weyerhaeuser should prioritize southern mill network automation to defend margin position against OSB input volatility. Channel control through e-procurement platform development captures specification data from national production builders consolidating procurement authority.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium APA-certified and economy-grade I-joists creates white-space opportunity for regional fabricators targeting custom home builders and renovation contractors. Moisture-resistant composite web variants for Gulf Coast flood-zone rebuilds represent the most penetrable segment given limited incumbent focus. A go-to-market angle emphasizing kitting services and shorter lead times for flexible-length orders bypasses mill-direct channel dominance.
For Investors and Strategic Acquirers: Roll-up economics work for regional I-joist fabricators because specification authority concentration among national builders fragments addressable demand into sub-scale local accounts that resist direct mill relationships. Target acquisition archetypes include independent southern US producers with purchased veneer supply and established contractor networks. The signal to watch is California and New York City embodied carbon rule expansion creating compliance-driven specification pull that elevates mass timber valuations relative to traditional framing alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| APA Certification Investment | Accelerated third-party testing unlocks IRC 2024 cycle specification eligibility in adopting states. |
| Automated Production Line Deployment | Real-time quality sensing reduces lamination defects and enables custom length runs without changeover penalties. |
| Direct-to-Builder Digital Platform | E-procurement channels compress quote-to-delivery cycles and capture centralized purchasing data from national accounts. |
| Moisture-Resistant Composite Web Development | Treated web materials address flood-zone renovation demand in Gulf Coast and Pacific Northwest markets. |
| Timberland Backward Integration | Captive veneer supply insulates margin stability from North American timber harvest cycle volatility. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply-side estimates for the United States I-Joist Market. Primary fieldwork engaged production builders, regional framing contractors, structural engineers, APA certification officials, and engineered wood procurement directors. Secondary validation drew from APA — The Engineered Wood Association technical bulletins, IRC structural provision amendments, state building code adoption records, and SEC filings of publicly traded forest products companies. Bottom-up volume estimates triangulated against top-down housing permit and construction spending aggregates.
Segment-weighting approaches distributed total market value across product type, application, end user, and distribution channel dimensions. Modeled segments included wood, composite, steel, and hybrid I-joist configurations; residential, commercial, industrial, and renovation applications; home builders, contractors, architects, and engineers; plus direct sales, wholesalers, distributors, and retailers. CAGRs were derived from regression analysis of historical housing start correlations and forward projection of IRC adoption timelines. Industry-specific forecast inputs incorporated mass timber mill capacity expansion schedules and state energy code amendment tracking.
Caveats apply where housing permit volatility, OSB pricing spikes, or accelerated embodied carbon rule implementation could materially shift the outlook. Forecasts reflect assumptions about IRC adoption continuity and builder specification persistence that may revise under severe demand contraction. Material deviation in these triggers warrants pause and re-evaluation of capacity expansion and certification investment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
US Geosynthetics Market