
 Global Aneurysm Clips Market | 2026-2036
Global Aneurysm Clips Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aneurysm Clips Market Foresight
Aftermarket maintenance and clip surveillance protocols are restructuring how hospitals contract for aneurysm clip supply, shifting procurement toward bundled service agreements. Aesculap dominates European manufacturing scale for titanium-based cranial implants. Medtronic leverages its neurovascular distribution network across North American academic medical centers. B. Braun anchors Central European hospital procurement through direct sterilization logistics integration.
An aneurysm clip is a miniature, spring-loaded or bayonet-style implant fabricated from titanium, Phynox, or specialized alloys, designed to occlude the neck of a cerebral aneurysm by applying calibrated closing pressure across arterial tissue. These devices typically measure 5-20 mm in length and require electropolished surfaces below 0.25 μm Ra to prevent thrombogenicity and tissue adhesion during permanent intracranial placement. Titanium clips command the largest installed base due to proven MRI compatibility and decades of clinical validation, while Phynox segments attract premium positioning for their superior elastic recovery in complex fenestration geometries. Polymer clips remain developmental, with structural segments concentrated in research institutes rather than commercial deployment.
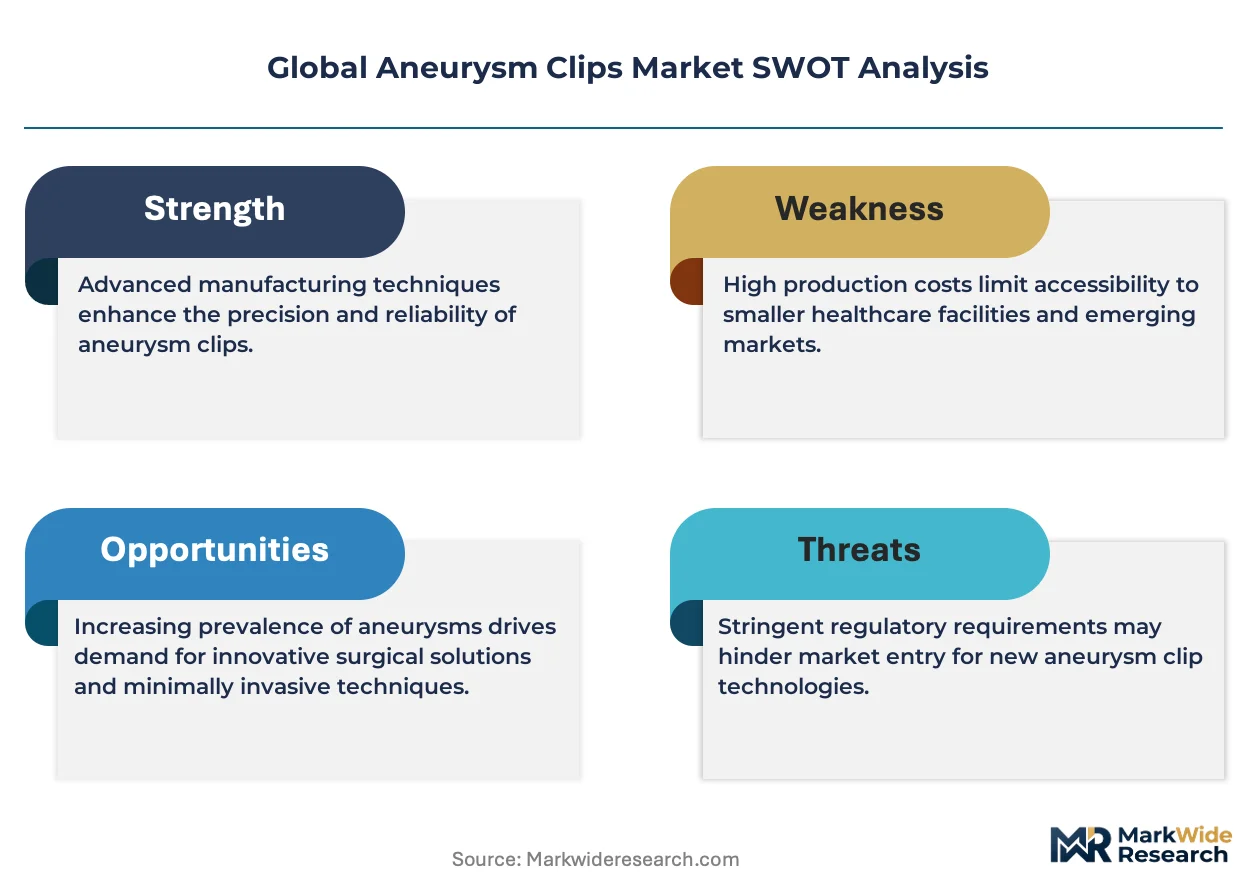
FDA 510(k) clearance pathways and the EU MDR's enhanced clinical evidence requirements are extending development timelines for novel clip materials, while Japan's PMDA mandates additional fatigue-testing protocols that filter market entrants. The EU AI Act's emerging diagnostic imaging standards will intersect with clip placement verification workflows, reshaping postoperative monitoring requirements. Stakeholders must weigh regulatory capital intensity against the clinical pull for patient-specific clip geometries derived from 3D aneurysm modeling.
Market Dynamics
Bundled service agreements for clip surveillance and aftermarket maintenance are restructuring hospital procurement economics, compressing traditional device-only margins while extending manufacturer-patient relationships across the implant lifecycle.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated review timelines for titanium-based predicate devices reduce regulatory capital barriers for established alloy platforms entering cranial implant categories.
- Japan PMDA fatigue-testing mandates:Stringent mechanical validation protocols filter marginal competitors, concentrating supply among manufacturers with metallurgical testing infrastructure.
- Neurosurgical center clustering in Germany:Specialized hospital networks aggregate procedure volumes, creating procurement scale that rewards suppliers with integrated sterilization logistics.
Market Restraints
- Titanium sponge price volatility:Aerospace and defense demand for Grade 1-4 titanium creates input cost pressure that surgical implant manufacturers cannot fully pass through contracted hospital pricing.
- EU MDR clinical evidence escalation:Enhanced post-market surveillance and biocompatibility documentation requirements extend development timelines and regulatory capital intensity for novel clip geometries.
- Endovascular coil substitution:Minimally invasive flow diversion and intrasaccular devices capture aneurysm cases previously routed to open surgical clipping, compressing addressable procedure volumes.
Strategic Opportunities
- Patient-specific 3D modeling convergence:Computational fluid dynamics and additive manufacturing are unifying preoperative aneurysm simulation with custom clip geometry fabrication, enabling premium positioning for complex fenestration cases.
- EU AI Act diagnostic imaging standards:Automated postoperative verification workflows create regulatory tailwinds for clip placement confirmation technologies integrated with surgical navigation systems.
- Direct sterilization logistics integration:Central European hospital networks are consolidating procurement around suppliers offering sterile-to-theater delivery, bypassing traditional distributor markups.
Industry Challenges
- Electropolishing surface finish expertise:Sub-0.25 μm Ra specifications for thrombogenicity control require specialized finishing infrastructure that concentrates among legacy European and North American suppliers.
- Polymer clip structural validation:Bioresorbable and polymer-based alternatives face extended fatigue-testing and long-term biocompatibility certification timelines that delay commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aneurysm Clips Market |
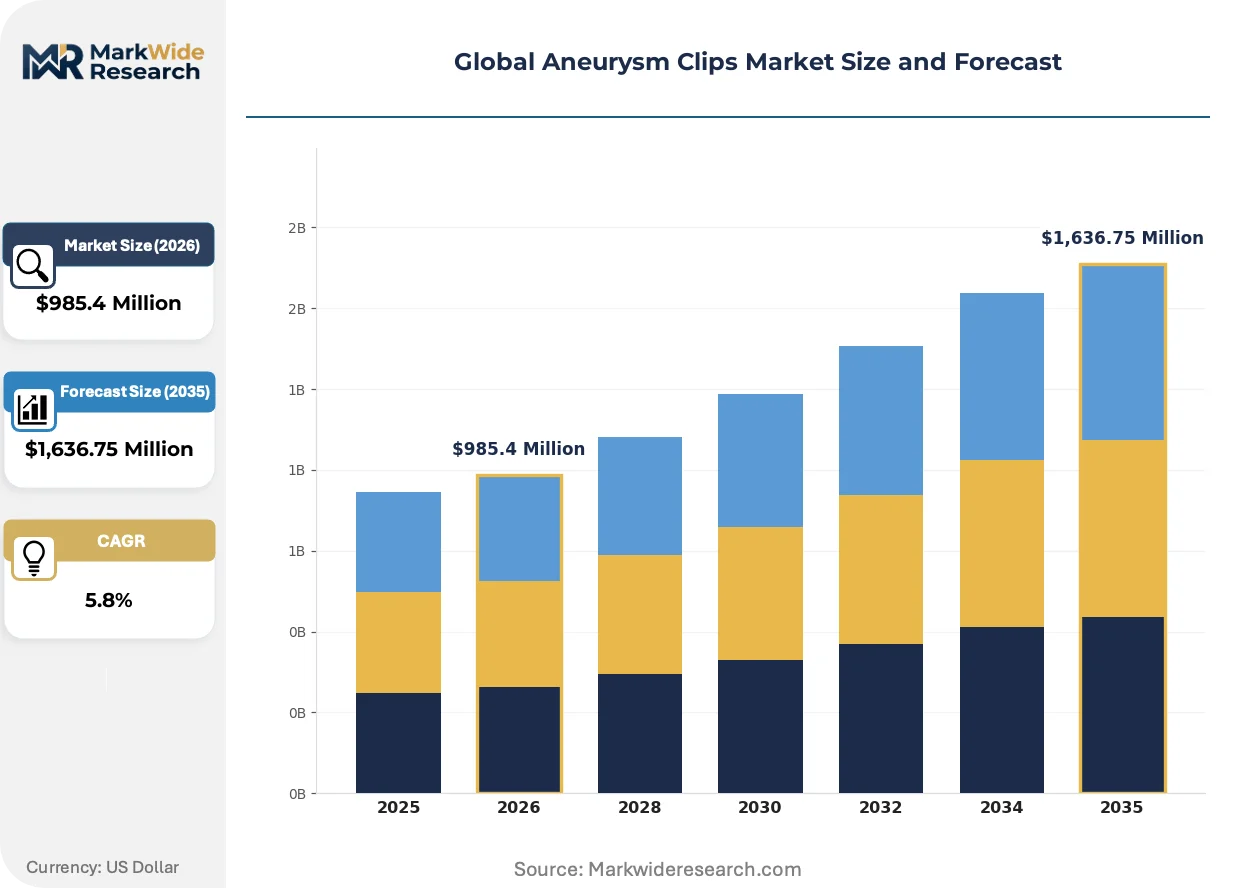
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,636.75 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Clips, Phynox Clips, Alloy Clips, Polymer Clips Application: Cerebral Aneurysm, Intracranial Hemorrhage, Arteriovenous Malformations, Brain Tumors End User: Neurosurgical Centers, Specialty Clinics, Research Institutes, Emergency Care Units Deployment: Hospitals, Ambulatory Surgical Centers, Academic Medical Centers, Trauma Centers |
| Companies Covered | adeor medical, Rebstock Instruments, Aesculap, Medtronic, B. Braun, Mizuho Medical, evonos, Peter Lazic, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aneurysm Clips Market Shifts & Advancements
Computational modeling and advanced manufacturing are compressing the traditional boundary between preoperative planning and implant fabrication, enabling geometries matched to individual aneurysm morphologies.
Additive manufacturing of titanium alloys is unifying topological optimization with patient-specific clip architectures. Academic medical centers in the United States and Germany are piloting these platforms for complex posterior circulation aneurysms. This capability is compressing the traditional separation between diagnostic imaging and implant production, forcing suppliers to integrate computational services or cede premium positioning.
The EU MDR's enhanced clinical evidence requirements are extending post-market surveillance obligations for permanent cranial implants. Manufacturers must now maintain traceability databases and periodic safety update reports across the implant lifecycle. High-volume neurosurgical centers in France and the Netherlands are prioritizing suppliers with established MDR technical documentation and notified body relationships.
After-sales service unbundling is fragmenting traditional device procurement in North American academic hospitals. Separate contracting for clip inventory, sterilization logistics, and long-term surveillance is displacing bundled purchase agreements. This pattern is most visible in neurosurgical departments with dedicated value analysis committees and orthopedic-style implant tracking infrastructure.
Global Aneurysm Clips Market Segmentation
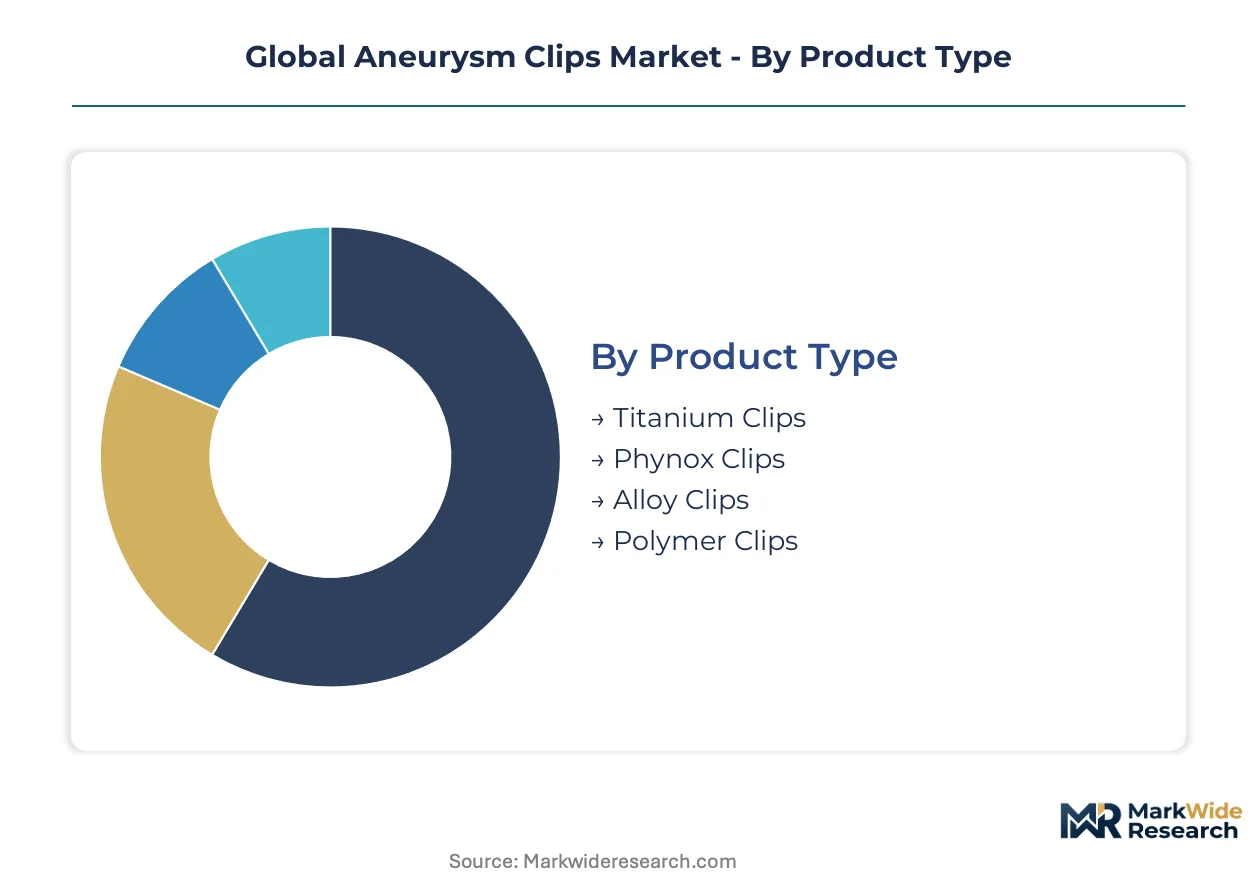
Aneurysm clip procurement patterns diverge sharply between high-volume standardized procedures and low-volume complex interventions. Material selection and deployment setting determine pricing power, regulatory burden, and sterilization logistics requirements.
Product Type:
Volume concentration favors titanium platforms, while premium positioning clusters around cobalt-chromium alloys with superior elastic recovery.
- Titanium Clips:Fabricated from Grade 1-4 titanium with electropolished surfaces below 0.25 μm Ra, these devices command the largest installed base due to proven MRI compatibility and decades of clinical validation. Demand concentrates in German neurosurgical clusters and United States academic medical centers where standardized procurement favors predictable supply chains.
- Phynox Clips:Cobalt-chromium-nickel alloy construction delivers superior spring fatigue resistance and elastic recovery for complex fenestration geometries. Premium positioning targets posterior circulation aneurysms and cases requiring repeated clip repositioning during open surgery.
- Alloy Clips:Specialized stainless and refractory metal blends address niche mechanical requirements for giant aneurysm reconstruction.
- Polymer Clips:Bioresorbable and structural polymer alternatives remain developmental, concentrated in research institutes rather than commercial deployment.
Mature deployment sits with titanium platforms. Newer deployment is concentrated in polymer alternatives.
Application:
Procedure complexity and reimbursement tiers separate high-margin specialized interventions from commoditized emergency stabilization.
- Cerebral Aneurysm:Elective clipping of saccular and fusiform cerebral aneurysms represents the core indication, with preoperative 3D modeling increasingly guiding clip selection. Demand clusters in Japan and Germany where PMDA and EU MDR frameworks validate permanent implant safety.
- Intracranial Hemorrhage:Emergency hematoma evacuation with concurrent aneurysm occlusion requires rapid clip availability and sterilization logistics integration. Volume concentrates in trauma centers across the United States and United Kingdom.
- Arteriovenous Malformations:Nidus resection with feeding artery clipping demands specialized fenestration geometries.
- Brain Tumors:Vascular control during tumor resection utilizes standard clip configurations with lower margin profiles.
Established volume sits with cerebral aneurysm repair. Expanding most quickly are AVM interventions leveraging patient-specific modeling.
End User:
Procurement sophistication and tracking infrastructure separate institutional buyers from smaller clinical settings.
- Neurosurgical Centers:High-volume dedicated cranial surgery units aggregate procedure volumes and negotiate integrated sterilization logistics. German hospital networks and United States academic medical centers dominate this segment with dedicated value analysis committees.
- Specialty Clinics:Focused cerebrovascular practices concentrate on elective cases with premium clip selection.
- Research Institutes:Polymer clip validation and additive manufacturing pilots concentrate in academic medical centers across Germany and the United States.
- Emergency Care Units:Stabilization facilities require rapid clip access with limited inventory depth.
Contracting sophistication sits with neurosurgical centers. Regulatory pilot activity is concentrated in research institutes.
Deployment:
Facility type determines sterilization responsibility, inventory carrying cost, and aftermarket service bundling.
- Hospitals:General acute care facilities with neurosurgical capabilities represent the volume base, with procurement increasingly shifting to bundled service agreements covering clip surveillance and sterilization logistics.
- Ambulatory Surgical Centers:Limited cranial case volumes restrict clip inventory to emergency backup rather than primary treatment setting.
- Academic Medical Centers:United States and German university hospitals pilot patient-specific 3D modeling and additive manufacturing integration.
- Trauma Centers:Emergency clipping for ruptured aneurysms demands immediate clip availability and sterilization capacity.
Service bundling sits with hospital networks. Technology piloting is concentrated in academic medical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European manufacturers concentrate titanium fabrication capacity while United States academic medical centers absorb the highest per-procedure clip volumes. Japan's PMDA fatigue-testing mandates filter import competition. German neurosurgical clusters negotiate integrated sterilization logistics that reshape procurement economics.
United States
FDA 510(k) pathway streamlining accelerates predicate device approvals for established titanium platforms. Academic medical centers in Boston and Baltimore pilot patient-specific 3D modeling workflows. Neurosurgical departments with dedicated value analysis committees unbundle traditional device procurement into separate inventory, sterilization, and surveillance contracts.
Germany
Specialized hospital networks in Bavaria and North Rhine-Westphalia aggregate procedure volumes that reward suppliers with direct sterilization logistics integration. EU MDR technical documentation requirements concentrate procurement among manufacturers with established notified body relationships. Aesculap anchors European manufacturing scale for titanium-based cranial implants from its Tuttlingen base.
Japan
PMDA mandates additional fatigue-testing protocols that filter marginal competitors from the import market. Tokyo and Osaka neurosurgical centers concentrate elective clipping volumes for complex posterior circulation cases. Domestic manufacturers leverage metallurgical testing infrastructure to satisfy stringent mechanical validation requirements.
United Kingdom
Trauma centers across London and Manchester demand rapid clip availability for emergency hematoma evacuation with concurrent aneurysm occlusion. NHS procurement frameworks prioritize suppliers with MDR-compliant technical documentation and traceability databases. Post-market surveillance obligations extend manufacturer-patient relationships across the implant lifecycle.
France
High-volume neurosurgical centers in Paris and Lyon prioritize suppliers with established EU MDR notified body relationships for permanent cranial implants. ANSM oversight intersects with enhanced biocompatibility documentation requirements. Academic hospitals pilot automated postoperative verification workflows that reshape clip placement confirmation technologies.
Global Aneurysm Clips Market Competitive Landscape
Top-tier vendors anchor European manufacturing scale, while mid-tier specialists occupy premium positioning for complex fenestration geometries. The vendor base stratifies across integrated sterilization logistics providers, titanium alloy fabricators, and patient-specific modeling platforms. Two strategic archetypes dominate: legacy European suppliers with electropolishing surface finish expertise, and North American distributors leveraging neurovascular network density. Competitive moves concentrate on direct sterilization logistics integration and computational fluid dynamics service bundling.
Among German-based fabricators, Aesculap and B. Braun occupy positions within the integrated logistics tier, exemplifying suppliers that anchor Central European hospital procurement through sterile-to-theater delivery capabilities. Medtronic represents the North American distribution archetype, sitting within the neurovascular network leverage tier. These three companies illustrate how geographic origin and company structure map onto divergent competitive positioning strategies across the implant lifecycle.
| Leading Market Players |
|---|
| adeor medical |
| Rebstock Instruments |
| Aesculap |
| Medtronic |
| B. Braun |
| Mizuho Medical |
| evonos |
| Peter Lazic |
| Integra LifeSciences |
| Others |
Supply & Pricing Matrix
Bundled service agreements for clip surveillance and sterilization logistics are forcing manufacturers to absorb inventory carrying costs and aftermarket service obligations, compressing traditional device-only margins while extending capital commitments across the implant lifecycle.
Pricing Analysis
Margin tightening in standard titanium platforms reflects aerospace and defense demand competing for Grade 1-4 titanium sponge, creating input cost pressure that surgical implant manufacturers cannot fully pass through to contracted hospital pricing. Three-tier pricing structure across premium Phynox alloys, standard titanium, and economy stainless configurations segments buyer archetypes, with academic medical centers in Germany and the United States showing lowest price sensitivity due to integrated sterilization logistics contracts. Cost-down pressure on polymer alternatives accelerates because extended fatigue-testing and biocompatibility certification timelines delay commercial deployment, forcing research-stage pricing. Emergency care units and trauma centers exhibit highest price sensitivity, prioritizing rapid availability over alloy grade or surface finish specifications.
Supply Chain Analysis
Specialized electropolishing technicians in southern Germany and precision forging expertise in western Japan constrain capacity expansion for sub-0.25 μm Ra surface finish specifications. Manufacturing concentrates in Germany, Japan, and the United States, with Aesculap anchoring European titanium fabrication and Mizuho Medical serving domestic Japanese demand. Raw material sourcing draws from aerospace-grade titanium sponge suppliers, cobalt-chromium alloy foundries, and specialized refractory metal processors. Single-source vulnerability sits with electropolishing infrastructure for thrombogenicity control, as legacy European and North American suppliers retain concentrated expertise. Distribution runs through direct sterilization logistics integration for German hospital networks and GPO-mediated contracts for United States academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Aneurysm Clips Market functions as a cost-of-compliance arena where EU MDR enhanced clinical evidence requirements and Japan PMDA fatigue-testing mandates erect barrier-to-entry moats favoring manufacturers with established metallurgical testing infrastructure and notified body relationships.
For Market Incumbents: Anchor procurement relationships through captive sterilization logistics integration, particularly in German neurosurgical clusters where hospital networks consolidate contracting around sterile-to-theater delivery capabilities. Defend against endovascular coil substitution by embedding computational fluid dynamics services into preoperative planning workflows, creating switching costs for academic medical centers piloting patient-specific 3D modeling. Prioritize backward integration into electropolishing surface finish infrastructure to control the sub-0.25 μm Ra specification bottleneck. For New Entrants and Emerging Players: Digital-channel partnerships with surgical navigation system vendors offer lower-friction entry than direct hospital contracting, enabling placement confirmation technology integration without sterilization logistics overhead. Target polymer clip validation programs at research institutes across Germany and the United States, where regulatory pilot activity concentrates and procurement bypasses traditional GPO structures. Pursue white-space positioning in automated postoperative verification workflows triggered by EU AI Act diagnostic imaging standards. For Investors and Strategic Acquirers: The window for entry favors mid-tier specialists with electropolishing expertise and established PMDA relationships, as these capabilities concentrate among legacy European and Japanese suppliers with defensible technical documentation. Long-term viability hinges on patient-specific additive manufacturing convergence, where computational services bundling displaces pure device economics. Watch FDA 510(k) pathway streamlining for titanium predicate devices as the inflection signal—accelerated review timelines would erode regulatory capital barriers and invite new alloy platform competition.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Establishes notified body relationships that concentrate procurement among compliant manufacturers in France and the Netherlands. |
| Direct Sterilization Logistics Integration | Bypasses traditional distributor markups by delivering sterile-to-theater clips through German hospital network contracts. |
| Patient-Specific 3D Modeling Platform Development | Unifies computational fluid dynamics with additive manufacturing for complex posterior circulation aneurysms in United States academic centers. |
| PMDA Fatigue-Testing Infrastructure Expansion | Filters import competition in Japan by satisfying mechanical validation mandates that domestic manufacturers leverage. |
| Automated Postoperative Verification Workflow Partnership | Integrates clip placement confirmation with surgical navigation systems under emerging EU AI Act diagnostic imaging standards. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation filings, and Japan PMDA fatigue-testing protocol submissions, complemented by interviews with neurosurgical department heads, hospital value analysis committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, GPO contract repositories, and CMS Medicare procedure volume records. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Segmentation outputs by material type, application indication, end-user facility tier, and deployment setting fed into analytical framework calculations over the projection horizon. CAGRs derived from regression analysis of historical procedure growth, regulatory approval velocity, and substitution elasticity between clipping and endovascular interventions. Industry-specific forecast inputs incorporated titanium sponge price volatility indices and EU MDR implementation timeline assumptions.
The model holds under stable regulatory enforcement intensity and continued aerospace titanium demand; deviation in PMDA protocol expansion or EU AI Act diagnostic imaging acceleration would shift competitive positioning and procurement concentration patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Pulse Lavage Market
Medical Devices
Bone Power Tools Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market