
 Anterior Cervical Plating Market | 2026-2036
Anterior Cervical Plating Market Size, Share, and Industry Trends Forecast 2026-2036
Anterior Cervical Plating Market Analysis
MDR is realigning the cost-of-entry calculus for European market access, forcing manufacturers to rebuild clinical evidence packages and quality management systems. Zimmer Biomet leverages its established notified body relationships to sustain CE marking momentum across legacy and next-generation plate portfolios. Globus Medical anchors its competitive stance through specialized titanium plate geometries optimized for single-level and multi-level constructs. Medtronic controls distribution breadth, operating direct hospital contracts that span anterior cervical plating alongside broader spine platform agreements.
Anterior cervical plating systems are titanium or polyether ether ketone implants designed for stabilization of the cervical spine following discectomy or corpectomy, typically ranging from 12 mm to 18 mm in screw diameter compatibility and engineered to restore lordotic alignment while promoting fusion. The primary commercial purpose centers on reducing postoperative graft subsidence and pseudarthrosis rates in degenerative disc disease and trauma indications. Locking plates command margin concentration due to their mechanical superiority in construct rigidity, while polyether ether ketone plates represent the fastest-growing material segment as radiolucency demands intensify for postoperative imaging clarity. Spinal fusion applications dominate volume, though revision surgery is emerging as a higher-acuity subset with specialized plating requirements.
FDA's 510(k) framework and the EU MDR, alongside ISO 13485 quality mandates, collectively shape product standards by requiring biocompatibility testing, fatigue performance validation, and post-market surveillance infrastructure that smaller manufacturers struggle to fund. The FDA's emphasis on substantial equivalence for predicate devices creates pathway differentiation between incremental plate designs and novel material platforms. Stakeholders must monitor how FDA's evolving guidance on cervical total disc replacement interacts with anterior cervical plating volumes, as hybrid surgical strategies reshape the addressable opportunity for standalone plating systems.
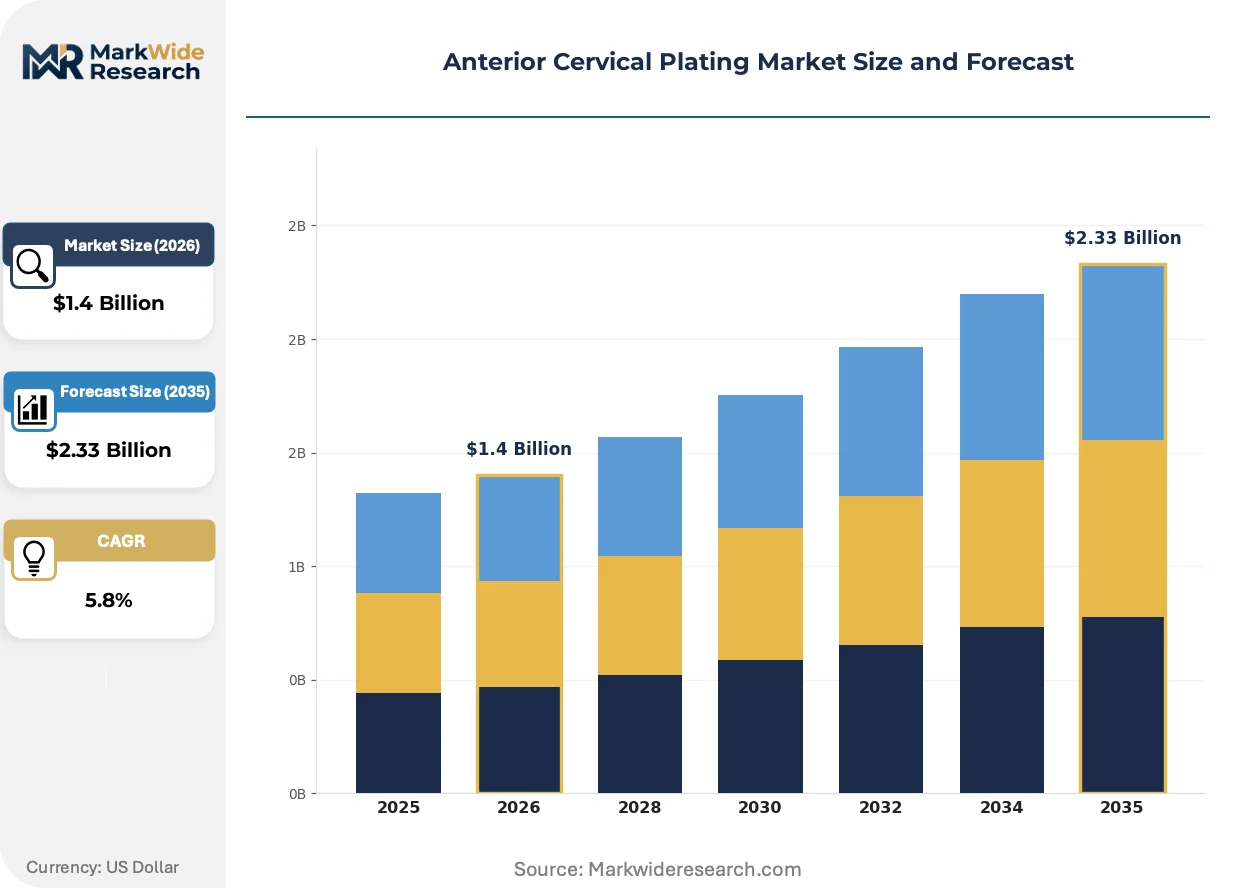
Market Dynamics
EU MDR's clinical evidence requirements are compressing the competitive field, forcing manufacturers to rebuild quality management systems and predicate-based submission strategies for cervical plating systems.
Growth Catalysts
- Aging demographics:Japan's super-aged population and Germany's 65-plus cohort expansion are accelerating cervical fusion volumes in tertiary hospital networks.
- FDA 510(k) pathway compression:Predicate-based submissions for titanium locking plates now clear faster than novel material platforms, rewarding incremental design evolution.
- Radiolucency demands:Postoperative imaging clarity requirements in US academic medical centers are pulling polyether ether ketone plate adoption.
Market Restraints
- Titanium supply concentration:Sponge production bottlenecks in Kazakhstan and Ukraine create input volatility for plate manufacturers.
- MDR clinical evidence burden:European notified body backlogs extend CE marking timelines to 18-24 months for legacy portfolio renewals.
- Cervical total disc replacement substitution:Motion-preserving alternatives in single-level degenerative disc disease are capturing cases previously routed to fusion.
Strategic Opportunities
- Revision surgery specialization:Higher-acuity constructs for pseudarthrosis and adjacent segment disease command premium positioning in US spine centers.
- Japan's reimbursement clarity:Ministry of Health, Labour and Welfare pricing signals for multi-level constructs enable volume planning.
- PEEK-carbon composite convergence:Hybrid material platforms combining radiolucency with modulus-matching properties open differentiated positioning.
Industry Challenges
- Notified body relationship scarcity:MDR-designated body capacity constraints force manufacturers to queue for audit slots.
- Biocompatibility testing capex:ISO 10993 cytotoxicity and sensitization studies require dedicated laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anterior Cervical Plating Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locking Plates, Non-Locking Plates, Titanium Plates, Polyether Ether Ketone Plates End User: Hospitals, Surgical Centers, Rehabilitation Clinics, Orthopedic Practices Material: Titanium, Stainless Steel, Polycarbonate, Biodegradable Plastics Application: Spinal Fusion, Trauma Surgery, Deformity Correction, Revision Surgery |
| Companies Covered | Zimmer Biomet, Globus Medical, Medtronic, B. Braun Melsungen AG, Aesculap Implant Systems, Stryker Corporation, NuVasive, Carlsmed, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anterior Cervical Plating Market Emerging Trajectories
Material science advances and regulatory pathway evolution are compressing product lifecycles while elevating evidence requirements for anterior cervical plating systems.
Patient-specific plate geometries derived from preoperative CT segmentation are automating operative planning workflows in high-volume spine centers. Academic medical centers in the United States are adopting these platforms to reduce screw malposition rates. The technology is automating the transition from standard-sized plates toward construct libraries matched to individual anatomy.
EU MDR's post-market surveillance mandates require manufacturers to maintain systematic complaint databases and periodic safety update reports for cervical plating systems. This obligation is elevating quality management infrastructure costs while advantaging firms with established pharmacovigilance capabilities. German and French hospital procurement groups are prioritizing suppliers with demonstrated MDR compliance maturity.
Hospital network consolidation in the United States is compressing vendor lists and centralizing spine implant purchasing through integrated delivery networks. Independent surgeons and smaller practices are losing direct contracting access as procurement authority concentrates in system-level value analysis committees. The shift is most visible in Texas and Florida markets where hospital mergers have created super-regional purchasing entities.
Anterior Cervical Plating Market Segmentation
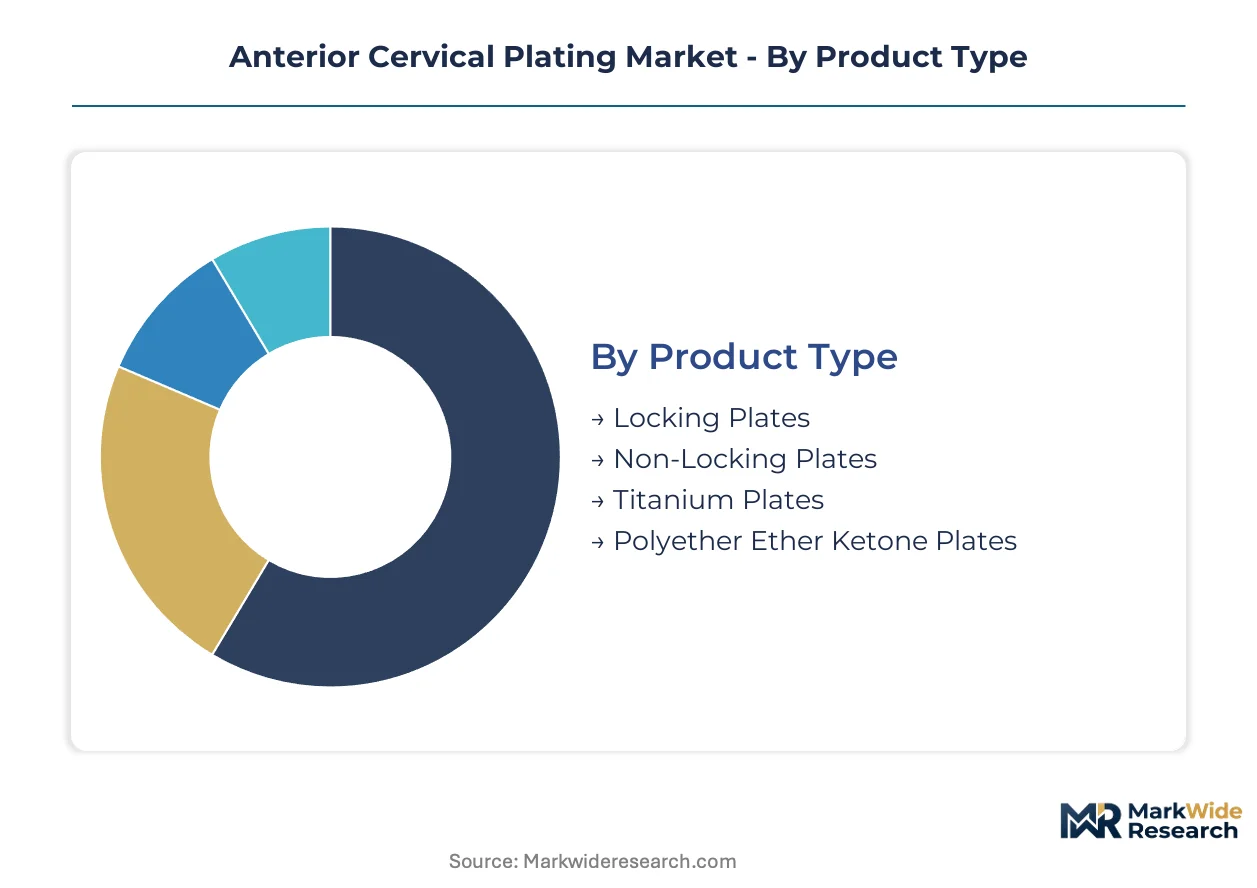
Anterior cervical plating systems fragment across material science, surgical setting, and procedural acuity. Each segmentation axis carries distinct margin profiles and regulatory burdens that reshape competitive positioning.
Product Type:
Locking mechanisms dominate standalone construct sales, while non-locking alternatives persist in cost-constrained procurement environments.
- Locking Plates:Titanium screw-plate interfaces with fixed-angle stability prevent construct subsidence in multi-level fusions. Hospital networks in the United States concentrate procurement here due to mechanical superiority in degenerative disc disease cases.
- Non-Locking Plates:Semi-constrained designs permit micromotion at the bone-screw interface, historically favored in trauma settings. Demand is compressing as locking system pricing converges downward.
- Titanium Plates:Commercially pure and alloy grades dominate current volume with established fatigue performance validation under ISO 13485.
- Polyether Ether Ketone Plates:Radiolucent polymer platforms eliminate MRI artifact in postoperative surveillance imaging.
Volume placements concentrate in locking titanium constructs; the faster expansion belongs to polyether ether ketone platforms.
End User:
Procurement authority concentrates in consolidated hospital systems, fragmenting across ambulatory settings where reimbursement codes differ.
- Hospitals:Tertiary academic centers and community hospital networks control the majority of cervical fusion volume through value analysis committees. Germany's DRG-based reimbursement favors inpatient stays for complex multi-level procedures.
- Surgical Centers:Ambulatory surgical facilities in the United States are capturing single-level cases as anesthesia protocols shorten recovery windows. Medicare site-of-service differentials accelerate this shift.
- Rehabilitation Clinics:Postoperative monitoring sites without implant purchasing authority.
- Orthopedic Practices:Independent spine specialists losing direct contracting access to integrated delivery networks.
Revenue concentrates in hospital system contracts; surgical centers are climbing the fastest as case migration accelerates.
Material:
Biocompatibility testing requirements under ISO 10993 create tiered cost-of-entry barriers across metallic and polymer platforms.
- Titanium:Ti-6Al-4V ELI and commercially pure grades deliver modulus-matching properties with established osteointegration profiles. Supply concentration in Kazakhstan and Ukraine creates input volatility for manufacturers.
- Stainless Steel:316L surgical grade persists in emerging markets where cost sensitivity dominates procurement. Magnetic resonance imaging compatibility limitations constrain adoption in academic centers.
- Polycarbonate:Transparent polymer alternatives for temporary stabilization in specific trauma protocols.
- Biodegradable Plastics:Poly-l-lactic acid and polyglycolic acid platforms under investigation for pediatric applications where permanent implant retention raises long-term concerns.
Volume concentrates in titanium; biodegradable alternatives hold the steepest expansion trajectory as pediatric indications mature.
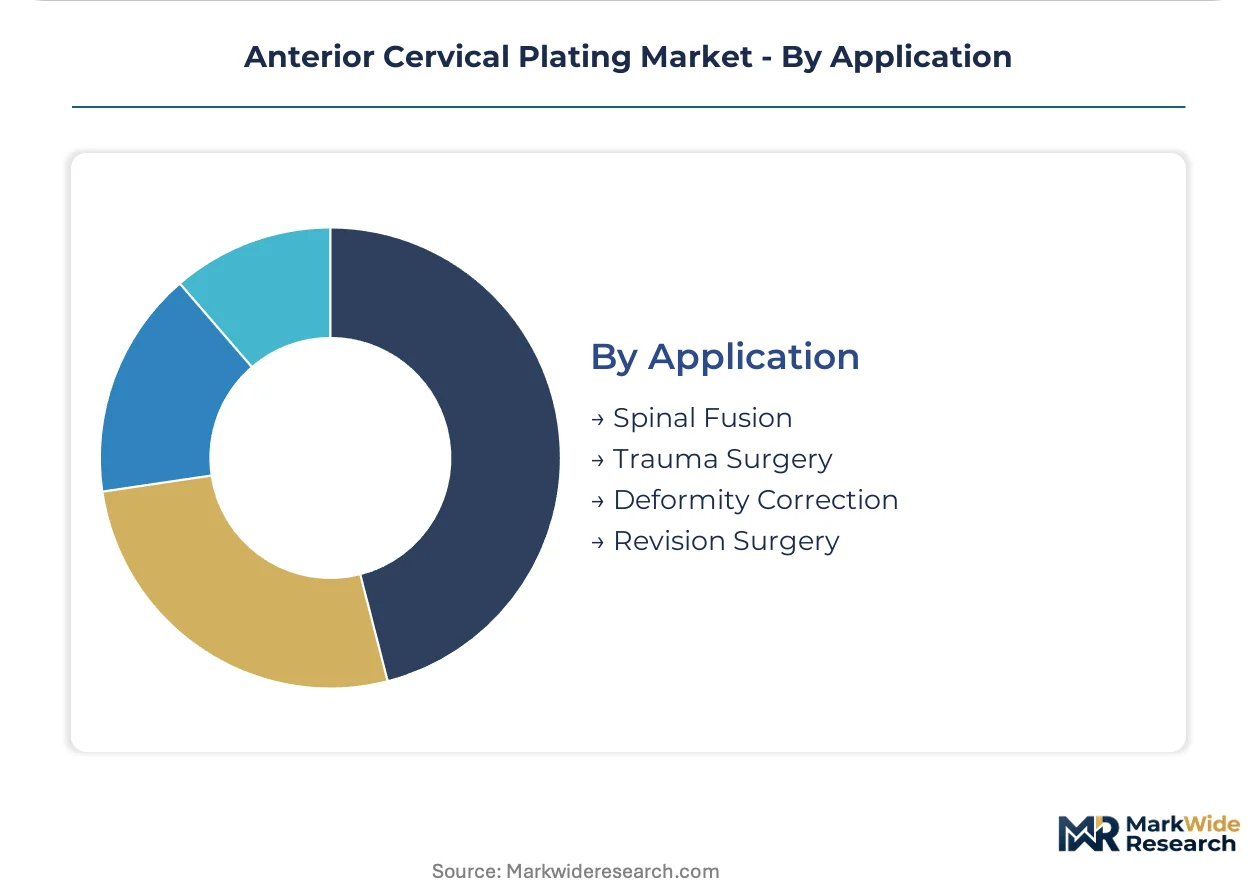
Application:
Procedural acuity determines construct complexity, with revision cases demanding specialized plating geometries.
- Spinal Fusion:Anterior cervical discectomy and fusion procedures constitute the procedural backbone, spanning single-level to four-level constructs. Japan's super-aged population accelerates volume in tertiary networks.
- Trauma Surgery:Acute fracture stabilization requires rapid deployment systems with intraoperative adaptability. Emergency department protocols favor locking plate systems for immediate construct rigidity.
- Deformity Correction:Kyphosis and scoliosis reconstructions employ longer plate constructs with variable screw trajectories.
- Revision Surgery:Pseudarthrosis and adjacent segment disease cases command premium pricing for specialized hardware in US spine centers.
Placement volume concentrates in primary fusion; revision surgery is gaining share fastest as adjacent segment disease incidence rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate titanium processing capacity for spinal implant manufacturers serving Asia-Pacific hospital networks. These zones offer 15% corporate tax rates and expedited customs clearance for medical device exporters. German industrial clusters leverage similar zone benefits through the EU's regional development frameworks.
United States
Integrated delivery networks in Texas and Florida consolidate procurement authority through super-regional purchasing entities. FDA's 510(k) pathway compresses approval timelines for predicate-based titanium locking plate submissions. Academic medical centers in Boston and New York drive PEEK plate adoption for postoperative MRI clarity.
Germany
DRG-based reimbursement favors inpatient stays for complex multi-level cervical fusion procedures in tertiary hospital networks. EU MDR clinical evidence requirements extend CE marking timelines to 18-24 months for legacy portfolio renewals. The Baden-Württemberg medical technology cluster hosts specialized fatigue testing laboratories serving European manufacturers.
Japan
Super-aged demographics accelerate cervical fusion volumes in Tokyo and Osaka tertiary networks. Ministry of Health, Labour and Welfare pricing signals for multi-level constructs enable volume planning for domestic distributors. The Kobe medical device manufacturing zone concentrates titanium plate finishing operations for regional supply.
Switzerland
Swissmedic's streamlined quality system assessments attract manufacturers seeking dual EU-Swiss market access. Geneva and Zurich hospital procurement groups prioritize suppliers with demonstrated MDR compliance maturity. The Basel pharmaceutical cluster extends into orthopedic device supply chain coordination.
China
NMPA's updated medical device classification rules restructure registration pathways for imported spinal implants. Shanghai's Zhangjiang Hi-Tech Park concentrates domestic manufacturers targeting tier-one hospital networks. Beijing's Peking Union Medical College Hospital anchors clinical validation protocols for novel plate geometries.
Anterior Cervical Plating Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base concentrates around three strategic archetypes: multinational platform players with broad spine portfolios, mid-cap specialists with concentrated plating expertise, and regional fabricators serving cost-sensitive procurement environments. Dominant competitive moves include M&A activity consolidating distribution networks and strategic partnerships securing notified body relationships for MDR compliance.
Among diversified platform players, Zimmer Biomet, Globus Medical, and Medtronic occupy positions spanning the premium-mid-market spectrum. Zimmer Biomet leverages established notified body relationships for CE marking momentum. Globus Medical exemplifies specialized geometry optimization for construct differentiation. Medtronic anchors competitive stance through direct hospital contracting breadth across integrated delivery networks.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Globus Medical |
| Medtronic |
| B. Braun Melsungen AG |
| Aesculap Implant Systems |
| Stryker Corporation |
| NuVasive |
| Carlsmed |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Titanium sponge originating from Kazakhstan and Ukraine processing facilities flows through three pricing tiers before reaching hospital value analysis committees, with spot-market volatility compressing margins for manufacturers lacking long-term offtake agreements.
Pricing Analysis
Short lead-time premiums of 15-20% apply to titanium locking plate orders from US integrated delivery networks facing surgical schedule compression, while spot inventory discounts attract cost-constrained surgical centers in Texas and Florida. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified European suppliers from emerging-market fabricators and refurbished inventory channels. Pricing pressure stems from Medicare site-of-service differentials accelerating case migration to ambulatory settings. Surgical centers exhibit highest price sensitivity; academic medical centers prioritize radiolucency performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for explanted cervical plates remain underdeveloped, though Swiss and German manufacturers pilot refurbishment programs for titanium components under MDR quality system oversight. Kazakhstan, Ukraine, and China concentrate titanium sponge supply for plate production, while Japan and Germany anchor precision finishing operations. Raw material dependencies center on Ti-6Al-4V ELI alloy feedstock, PEEK polymer resin, and carbon fiber composite precursors. Single-source vulnerability in Kazakhstan sponge production creates exposure to export restriction risk. Distribution runs through direct hospital contracts for multinational platform players and regional distributor networks for mid-cap specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play as EU MDR clinical evidence requirements force sub-scale manufacturers to exit or sell. The regulatory burden advantages firms with established notified body relationships and pharmacovigilance infrastructure.
For Market Incumbents: Acquire specialized fatigue testing laboratories in Baden-Württemberg or Basel clusters to secure MDR compliance capacity. Lock in direct hospital contracts across Texas and Florida super-regional purchasing entities before mid-cap competitors gain value analysis committee access. Cervical total disc replacement substitution threatens fusion volumes; counter by expanding revision surgery specialization for adjacent segment disease cases. Vertical integration into Kazakhstan titanium sponge sourcing reduces input volatility exposure. For New Entrants and Emerging Players: Ambulatory surgical centers represent the most penetrable channel partner type for single-level PEEK plate offerings. Target Japan's Ministry of Health, Labour and Welfare reimbursement clarity for multi-level construct volume planning. PEEK-carbon composite platforms offer differentiation without predicate device equivalence burdens. Partner with Shenzhen free trade zone fabricators for cost-competitive titanium finishing. For Investors and Strategic Acquirers: FDA 510(k) clearance compression for predicate-based titanium locking plates is the leading indicator that mid-cap specialists with notified body backlogs face acquisition pressure. The 5-10 year viability window favors platform players with hospital system contracting breadth over pure-play plating specialists. Target acquisition archetype: European manufacturers with legacy CE marks facing MDR renewal cliffs but possessing established surgeon training programs. Monitor notified body audit queue lengths for early signals of compliance-driven distress.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR-designated body relationships compress approval timelines for European market access. |
| Hospital System Partnership | Direct contracts with Texas and Florida integrated delivery networks secure volume commitments. |
| Reimbursement Strategy | Japan's Ministry of Health, Labour and Welfare pricing signals enable multi-level construct planning. |
| Software Companion Development | Patient-specific plate geometries from CT segmentation reduce screw malposition rates. |
| Backward Integration | Kazakhstan titanium sponge sourcing mitigates supply concentration risk for manufacturers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EU MDR notified body registers, Japanese Ministry of Health reimbursement bulletins, and hospital procurement databases provided validation layers. Bottom-up construct volume estimates triangulated against top-down market sizing from titanium sponge trade flows and spinal implant customs classifications.
Segment-level modeling tracked material platforms, locking mechanisms, end-user settings, and procedural acuity across the analysis window. CAGRs derived from regression against aging demographic projections, reimbursement code evolution, and surgical volume migration patterns. Procedure volume inputs incorporated DRG-based reimbursement differentials between Germany and US markets, while material mix assumptions reflected radiolucency demand trajectories in academic medical centers.
Caveats apply where FDA guidance on cervical total disc replacement or EU MDR notified body capacity constraints could materially shift the outlook. Forecasts reflect assumptions about reimbursement stability and titanium supply chain continuity. Practitioners should monitor adjacent segment disease incidence rates and PEEK-carbon composite clinical validation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Otoscope Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Global Image Guided Surgery Devices Market