
 Global Pulse Oximeters Market | 2026-2036
Global Pulse Oximeters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pulse Oximeters Market Foresight
The FDA's updated 510(k) premarket notification requirements for pulse oximeter accuracy is consolidating the competitive field around manufacturers with established clinical validation infrastructure. Masimo sustains technology leadership through proprietary signal processing algorithms and hospital-grade certification. Nonin Medical anchors its position in professional segments with FDA-cleared devices for motion-tolerant monitoring. CONTEC MEDICAL SYSTEMS CO., LTD competes aggressively on manufacturing scale, leveraging domestic supply chain density to serve price-sensitive markets across Asia and Africa.
A pulse oximeter is a non-invasive photoplethysmographic device that estimates arterial oxygen saturation (SpO2) and pulse rate by transmitting red and infrared light through vascularized tissue and measuring differential light absorption. The instrument serves critical functions across acute care triage, chronic respiratory disease management, and athletic performance optimization where real-time physiological feedback prevents hypoxic events. Fingertip devices dominate unit volume due to disposable pricing and pharmacy channel penetration, while tabletop systems command premium placements in operating theaters and intensive care units where continuous multi-parameter integration justifies capital expenditure. Wireless communication technology is expanding fastest as Bluetooth-enabled devices feed data into cloud-based remote patient monitoring platforms demanded by home health providers and accountable care organizations.
The FDA governs pulse oximeter accuracy claims and clinical performance labeling under 21 CFR 870.2700, while the EU Medical Device Regulation (MDR) imposes stricter post-market surveillance and clinical evidence requirements for Class IIa devices entering European markets. Japan's PMDA maintains distinct approval pathways that prioritize compatibility with domestic electronic health record standards, creating region-specific product configuration demands. Stakeholders must monitor evolving reimbursement codes for remote physiologic monitoring as CMS and national health technology assessment bodies recalibrate coverage decisions for home-based pulse oximetry.
Market Dynamics
The FDA's tightened 510(k) accuracy standards for pulse oximeters are compressing product development cycles and forcing manufacturers to rebuild clinical validation pipelines from the ground up.
Growth Catalysts
- Remote patient monitoring mandates:Accountable care organizations in the United States are embedding Bluetooth-enabled fingertip devices into post-acute care protocols, creating pull-through demand for cloud-integrated oximetry systems.
- EU MDR clinical evidence requirements:The Medical Device Regulation's post-market surveillance obligations are filtering out marginal competitors and concentrating procurement around manufacturers with established notified body relationships.
- Aging demographics in Germany and Japan:Expanded home health reimbursement for chronic respiratory disease management is driving replacement cycles for tabletop multi-parameter systems in post-acute settings.
Market Restraints
- Optical sensor component concentration:High-precision photodiode supply chains cluster in East Asian manufacturing hubs, exposing OEMs to single-source vulnerability for motion-tolerant signal processing hardware.
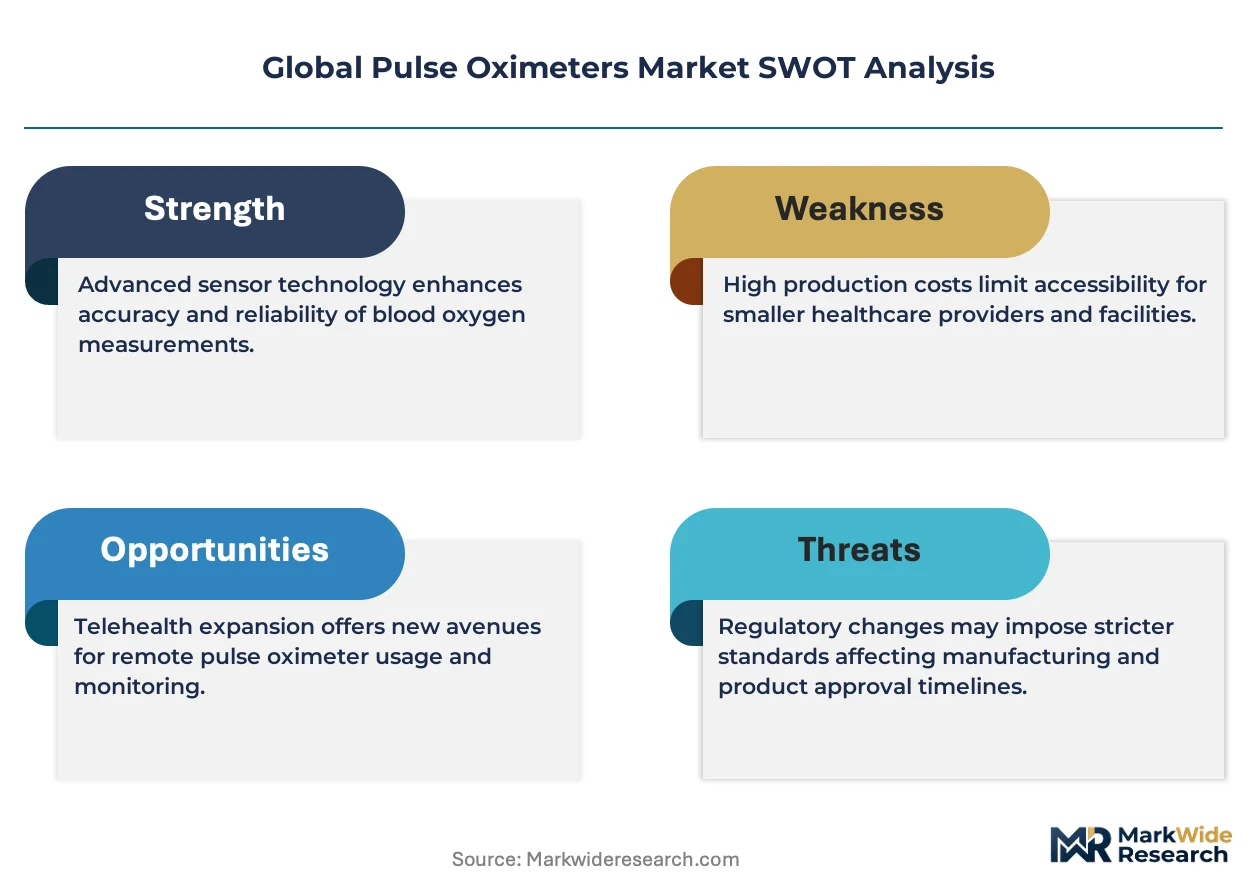
- FDA 510(k) pathway friction:The agency's evolving accuracy validation standards for SpO2 claims are extending premarket notification timelines and inflating regulatory compliance overhead for new market entrants.
- Smartwatch SpO2 substitution:Consumer-grade wrist-worn fitness devices with optical heart rate sensors are capturing price-sensitive demand for basic oxygen saturation screening outside clinical settings.
Strategic Opportunities
- Underpenetrated African markets:South Africa's public health procurement expansion for primary care diagnostics is opening volume opportunities for manufacturers with manufacturing scale and WHO prequalification pathways.
- Pediatric-specific FDA clearances:The absence of validated neonatal oximetry algorithms creates white space for signal processing innovations targeting low-perfusion infant monitoring in NICU environments.
- AI-integrated arrhythmia detection:Machine learning convergence with photoplethysmographic waveform analysis is enabling multi-parameter devices that capture both oxygen saturation and atrial fibrillation signatures.
Industry Challenges
- Biomedical signal processing talent scarcity:The specialized expertise required for motion artifact rejection algorithm development concentrates at a handful of academic medical centers and incumbent manufacturers.
- Legacy EHR integration complexity:Hospital procurement committees are demanding seamless HL7 FHIR connectivity, forcing retrofit investments for devices designed around proprietary data formats.
- Clinical validation timeline compression:Accelerated 510(k) review expectations are colliding with the extended patient enrollment periods required for hypoxia detection accuracy studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pulse Oximeters Market |
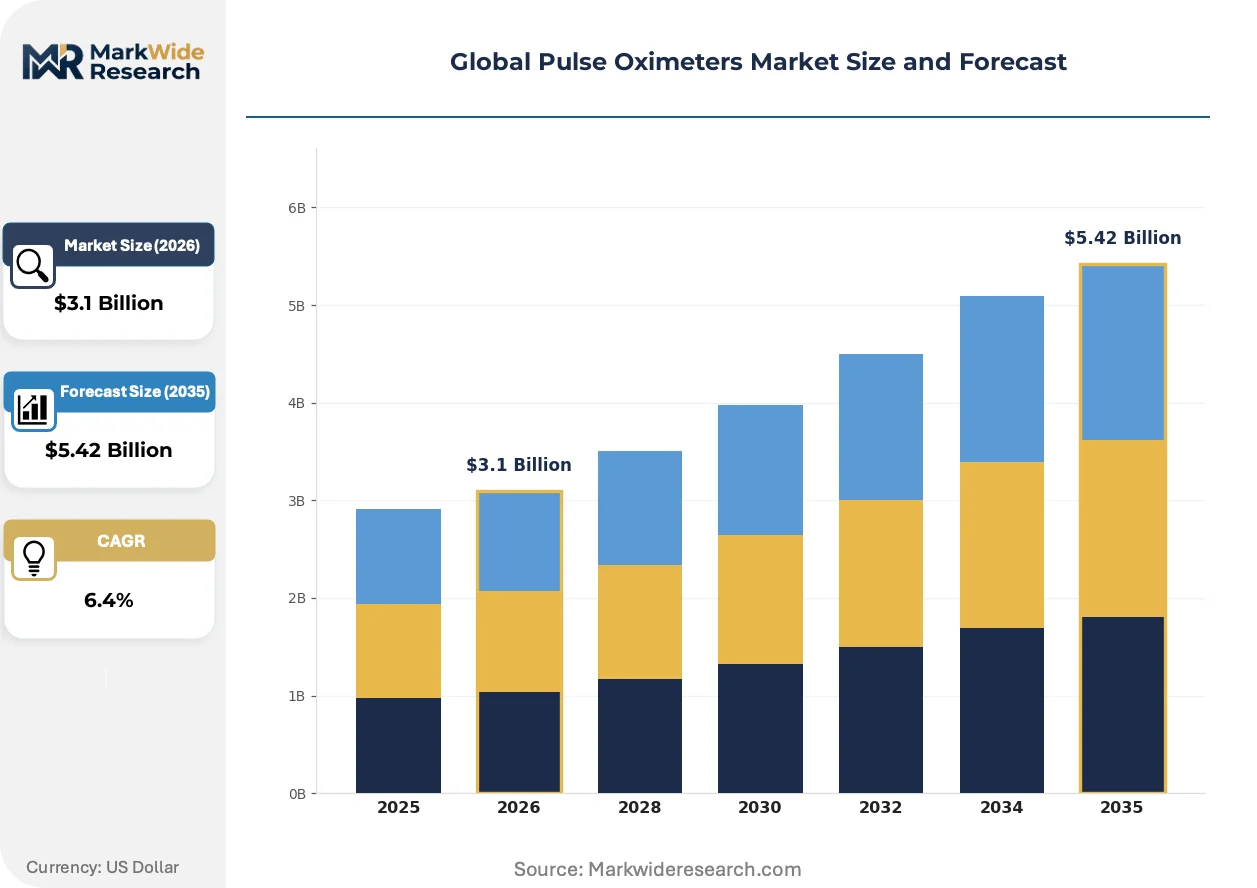
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Wrist-Worn, Fingertip, Tabletop Technology: LED, OLED, Digital Signal Processing, Wireless Communication Application: Home Care, Emergency Response, Sports Training, Sleep Monitoring End User: Hospitals, Ambulatory Services, Sports Facilities, Home Health Providers |
| Companies Covered | Medtronic, Masimo, Koninklijke Philips N.V., GE HealthCare, Nonin Medical, NIHON KOHDEN CORPORATION, ICU Medical, Inc., Drägerwerk AG & Co. KGaA, CONTEC MEDICAL SYSTEMS CO., LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pulse Oximeters Market Shifts & Advancements
Photoplethysmographic sensor miniaturization and cloud-native device architectures are compressing the boundary between consumer wellness and clinical-grade monitoring, forcing incumbents to recalibrate certification strategies.
Reflectance-mode pulse oximetry is electrifying wearable form factor design by enabling SpO2 measurement at the wrist, temple, and earlobe without the vascular compression artifacts that plague transmission-mode fingertip placement. Athletic performance clinics and sleep medicine practices are piloting these devices for overnight desaturation tracking. The technology is electrifying demand for continuous monitoring applications that transmission-mode hardware cannot serve, opening new reimbursement conversations with payers.
The EU MDR's Class IIa clinical evidence requirements are mandating post-market performance studies for pulse oximeters entering European markets, forcing manufacturers to maintain active surveillance registries rather than relying on predicate device equivalence. This regulatory burden is favoring established players with dedicated clinical affairs infrastructure. Hospital procurement in Germany and France is increasingly screening suppliers for notified body certification depth before tender participation.
Direct-to-consumer distribution through pharmacy and e-commerce channels is displacing traditional durable medical equipment supplier networks for fingertip pulse oximeters. Retail buyers are prioritizing Bluetooth connectivity and smartphone app integration over clinical accuracy certifications for home wellness segments. This channel rotation is most visible in the United States, where CVS and Amazon have built dedicated respiratory health device categories.
Global Pulse Oximeters Market Segmentation
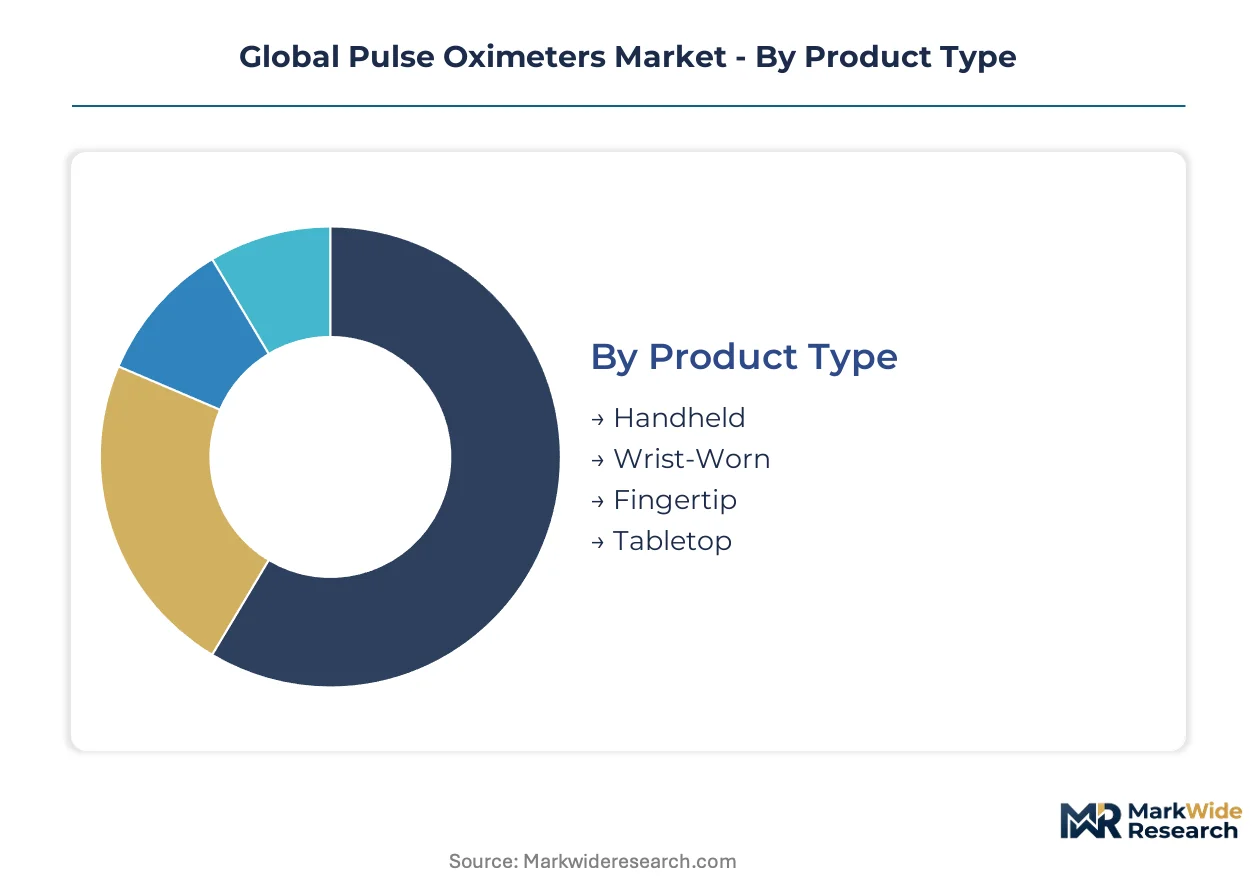
Product configuration in pulse oximetry directly shapes reimbursement pathways and procurement cycles. Manufacturers align form factor investments with specific clinical validation requirements across acute care, ambulatory, and consumer wellness channels.
Product Type:
Replacement cycles vary sharply by placement setting, with hospital capital equipment demanding decade-long service commitments while consumer devices turn over every 18-24 months.
- Fingertip:Clip-on transmission-mode devices using red and infrared LEDs through the distal phalanx. Pharmacy channel dominance in the United States and Germany drives disposable pricing models, though FDA 510(k) clearance requirements separate clinical-grade units from unregulated wellness variants.
- Tabletop:Multi-parameter monitoring stations integrating SpO2 with ECG, NIBP, and capnography for operating theaters and intensive care units. German hospital procurement and Japanese tertiary centers sustain premium placements through continuous monitoring mandates and HL7 FHIR connectivity requirements.
- Handheld:Portable battery-operated units for point-of-care triage and transport monitoring. Emergency medical services in the United States specify motion-tolerant algorithms for ambulance deployment.
- Wrist-Worn:Reflectance-mode sensors enabling overnight desaturation tracking without vascular compression artifacts. Sleep medicine practices in Japan and athletic performance clinics pilot reimbursement for continuous monitoring applications.
Volume placements concentrate in Fingertip devices; the faster expansion belongs to Wrist-Worn form factors.
Technology:
Component selection determines motion artifact rejection capability and regulatory clearance tier, with signal processing architecture representing the primary cost driver.
- Digital Signal Processing:Proprietary algorithms for motion-tolerant SpO2 estimation in low-perfusion conditions. Masimo and Nonin Medical anchor hospital procurement through patented noise reduction architectures that satisfy FDA accuracy validation standards.
- Wireless Communication:Bluetooth Low Energy and proprietary protocols feeding cloud-based remote patient monitoring platforms. Accountable care organizations in the United States mandate this capability for post-acute reimbursement, driving retrofit demand across installed base.
- LED:Conventional dual-wavelength emitters at 660nm and 940nm dominating cost-optimized manufacturing. Chinese supply chain density supports price-sensitive markets across Asia and Africa.
- OLED:Organic emitter arrays enabling multi-wavelength spectroscopy for peripheral perfusion index measurement. Niche adoption in research settings and high-end wellness devices.
Procurement committees prioritize Digital Signal Processing for clinical placements; Wireless Communication climbs fastest as home health reimbursement expands.
Application:
Clinical indication determines accuracy threshold requirements and corresponding regulatory pathway, creating sharp segmentation between prescription and over-the-counter positioning.
- Home Care:Chronic respiratory disease management requiring Bluetooth-enabled data transmission to accountable care organization dashboards. COPD and heart failure protocols in the United States and Germany drive replacement cycles for cloud-integrated devices.
- Emergency Response:Rapid triage in ambulance and disaster medicine settings demanding motion-tolerant performance. Fire departments and emergency medical services specify shock-resistant housings and extended temperature operating ranges.
- Sports Training:Altitude acclimatization and hypoxic training protocols for elite athletic programs. National team facilities in China and commercial fitness chains adopt wrist-worn reflectance devices for continuous field monitoring.
- Sleep Monitoring:Overnight desaturation detection for obstructive sleep apnea screening. Sleep medicine practices in Japan and the United States pilot reimbursement codes for home-based polysomnography alternatives.
Installed base concentrates in Home Care; Sleep Monitoring gains share fastest with reimbursement code expansion.
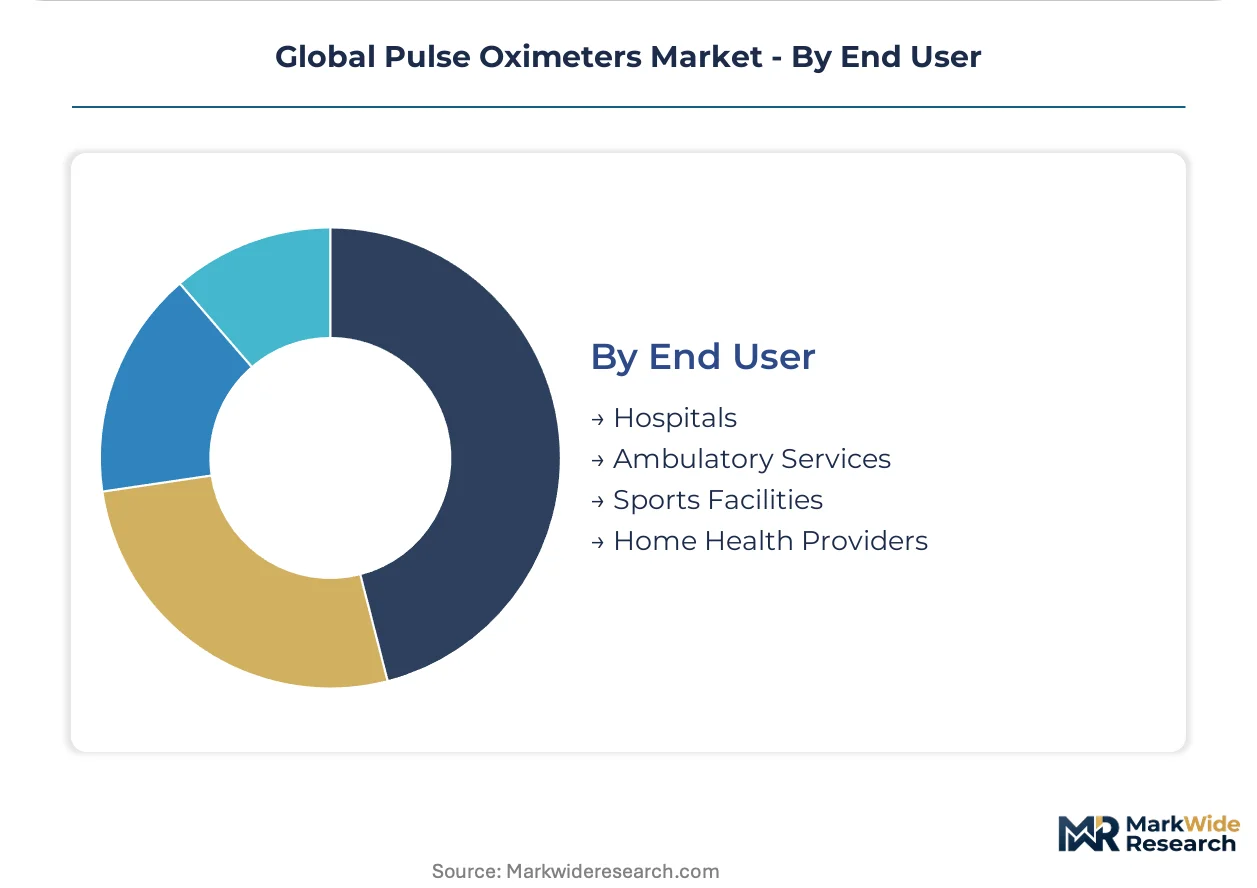
End User:
Buying center composition and procurement authority vary dramatically across institutional settings, dictating sales channel strategy and clinical evidence requirements.
- Hospitals:Capital equipment committees evaluating total cost of ownership, interoperability, and multi-parameter integration. German DRG-based procurement and Japanese electronic health record compatibility mandates shape vendor selection.
- Home Health Providers:Accountable care organizations and visiting nurse associations specifying Bluetooth connectivity and cloud platform integration. United States reimbursement codes for remote physiologic monitoring determine device specification.
- Ambulatory Services:Emergency medical services and urgent care clinics prioritizing portability and rapid deployment. Motion tolerance and battery longevity dominate technical evaluation.
- Sports Facilities:Professional team medical staff and commercial fitness operators seeking wellness-grade screening. Price sensitivity and smartphone app integration outweigh clinical certification.
Procurement volume concentrates in Hospitals; Home Health Providers expand most quickly with remote monitoring mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's free-trade zone incentives for medical device manufacturing have concentrated pulse oximeter assembly operations within the Yangtze River Delta corridor. This tax-advantaged clustering shapes procurement patterns across Asia-Pacific while influencing supply chain decisions for OEMs serving European and North American markets.
United States
Accountable care organizations in California and Texas are embedding Bluetooth-enabled devices into post-acute COPD protocols, driving cloud-integrated procurement. FDA's evolving 510(k) accuracy standards compress development timelines for manufacturers seeking clearance. The Minneapolis medical device corridor hosts established clinical validation infrastructure serving hospital-grade certification requirements.
China
Domestic supply chain density for photodiode components supports cost-optimized manufacturing for price-sensitive markets across Asia and Africa. NMPA's streamlined Class II medical device approvals accelerate market entry for locally manufactured units. Shenzhen's electronics manufacturing ecosystem concentrates reflectance-mode sensor production for wrist-worn form factors.
Germany
DRG-based hospital procurement mandates multi-parameter integration and HL7 FHIR connectivity for operating theater placements. EU MDR post-market surveillance obligations filter procurement toward manufacturers with established notified body relationships. The Baden-Württemberg medical technology cluster anchors tabletop system development for intensive care applications.
Japan
PMDA approval pathways prioritize compatibility with domestic electronic health record standards, creating region-specific product configuration demands. Expanded home health reimbursement for chronic respiratory disease management drives replacement cycles in post-acute settings. The Kansai region's precision manufacturing base supports motion-tolerant algorithm development for low-perfusion monitoring.
South Africa
Public health procurement expansion for primary care diagnostics opens volume opportunities for manufacturers with WHO prequalification pathways. National tender processes increasingly specify durability requirements for rural deployment conditions. The Western Cape medical device distribution hub serves as a logistics gateway for sub-Saharan African markets.
Global Pulse Oximeters Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers and price points. Hospital procurement committees favor established players with dedicated clinical affairs infrastructure capable of navigating FDA 510(k) and EU MDR validation requirements. Three archetypes dominate: diversified health technology conglomerates with multi-parameter portfolios, pure-play pulse oximetry specialists with proprietary signal processing IP, and manufacturing-scale OEMs serving price-sensitive markets. Competitive dynamics center on M&A activity targeting algorithm capabilities and strategic partnerships with cloud-based remote patient monitoring platforms.
Within the diversified health technology tier, Medtronic and Koninklijke Philips N.V. occupy positions spanning acute care capital equipment through ambulatory monitoring solutions. Masimo exemplifies the pure-play specialist archetype with hospital-grade certification concentration. CONTEC MEDICAL SYSTEMS CO., LTD sits within the manufacturing-scale tier, leveraging domestic supply chain density to serve emerging market procurement.
| Leading Market Players |
|---|
| Medtronic |
| Masimo |
| Koninklijke Philips N.V. |
| GE HealthCare |
| Nonin Medical |
| NIHON KOHDEN CORPORATION |
| ICU Medical, Inc. |
| Drägerwerk AG & Co. KGaA |
| CONTEC MEDICAL SYSTEMS CO., LTD |
| Others |
Supply & Pricing Matrix
Photodiode component costs cascade from Yangtze River Delta foundries through three distinct pricing tiers, with FDA-cleared hospital-grade devices commanding premiums over unregulated wellness variants sourced from Shenzhen assembly lines.
Pricing Analysis
Short lead-time premiums separate emergency procurement from scheduled replenishment cycles, with hospital capital committees paying surcharges for motion-tolerant algorithms validated under FDA 510(k) pathways. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth: proprietary signal processing architectures anchor hospital placements, Bluetooth-enabled home health devices occupy mid-market positioning, and pharmacy-channel fingertip units compete on disposable pricing. Cost compression in economy tiers intensifies because smartwatch SpO2 substitution erodes screening-device margins. Emergency medical services and accountable care organizations demonstrate lowest price sensitivity due to reimbursement code protection, while retail pharmacy buyers prioritize connectivity features over clinical accuracy.
Supply Chain Analysis
Domestic-content mandates in China's NMPA Class II approval pathways are reshaping sourcing, requiring local assembly for market access and concentrating photodiode manufacturing in Shenzhen and Suzhou industrial corridors. High-precision LED emitters and motion-tolerant sensor modules draw from South Korean and Japanese component specialists, with German precision optics serving niche research applications. Single-source vulnerability concentrates in East Asian photodiode foundries, exposing OEMs to logistics chokepoint risk during regional disruptions. Distribution runs through hospital GPO contracts in the United States, direct-to-consumer e-commerce channels for wellness segments, and national tender processes in African public health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence obligations and FDA accuracy standard tightening are forcing marginal competitors toward exit, consolidating procurement around manufacturers with dedicated clinical affairs infrastructure.
For Market Incumbents: Anticipate smartwatch SpO2 substitution by embedding hospital-grade certification depth into home health devices, capturing accountable care organization procurement that consumer wellness players cannot satisfy. Deepen backward integration into motion artifact rejection algorithm development, securing biomedical signal processing talent concentrated at academic medical centers before competitors exhaust the limited specialist pool. For New Entrants and Emerging Players: Enter via WHO prequalification pathways for South African public health tenders, where manufacturing scale and durability specifications filter out established premium players. Pediatric-specific FDA clearances for neonatal oximetry represent the most penetrable white space, given absence of validated low-perfusion algorithms for NICU environments. Pursue direct partnerships with cloud-based remote patient monitoring platforms rather than building proprietary data infrastructure. For Investors and Strategic Acquirers: FDA 510(k) clearance timeline compression for accuracy validation is the leading indicator that clinical validation infrastructure scarcity will drive acquisition premiums for specialized CRO networks and algorithm development shops. Five-to-ten year viability favors manufacturers with established notified body relationships in Europe and predicate device libraries for 510(k) submissions. Watch for CMS reimbursement code expansion for remote physiologic monitoring as the signal for home health provider procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Accuracy Validation Investment | Rebuilds clinical evidence pipelines to satisfy tightened SpO2 claim standards before predicate device pathways narrow. |
| Bluetooth Low Energy Platform Integration | Feeds real-time oximetry data into accountable care organization dashboards for remote patient monitoring reimbursement. |
| Neonatal Oximetry Algorithm Development | Captures white space in NICU monitoring where validated low-perfusion infant algorithms remain scarce. |
| WHO Prequalification Pathway Completion | Unlocks African public health procurement tender participation in South Africa and sub-Saharan expansion markets. |
| HL7 FHIR Connectivity Certification | Satisfies German DRG-based hospital procurement mandates for electronic health record interoperability. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, CMS reimbursement code expansions, and EU MDR notified body certification rates anchored the trend analysis, supplemented by interviews with hospital purchasing committee chairs, biomedical engineers specializing in signal processing, GPO contracts managers, home health provider technology officers, and regulatory affairs leads at pulse oximeter manufacturers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR post-market surveillance registries, CMS Medicare remote monitoring reimbursement data, and hospital procurement contract disclosures. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology, application, and end-user segments.
Segment-weighting approaches distributed value and volume estimates across fingertip, tabletop, handheld, and wrist-worn form factors, with technology tiers weighted by digital signal processing, wireless communication, LED, and OLED component costs. Application-level modeling incorporated home care, emergency response, sports training, and sleep monitoring utilization patterns through the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, reimbursement policy trajectories, and demographic demand drivers including aging populations in Germany and Japan.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA accuracy standard acceleration, photodiode supply disruption scenarios, or smartwatch SpO2 clinical validation breakthroughs. Assumptions reflect current regulatory pathways, reimbursement codes, and technology diffusion patterns without anticipating unannounced policy shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Device Connectors Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Asthma Spacers Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Peripheral Nerve Stimulators Market