
 Blood Thawing System Market | 2026-2036
Blood Thawing System Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Thawing System Market Intelligence
Asset-light leasing and instrument-rental programs is narrowing the competitive field for smaller clinical laboratories that lack capital budgets for automated thawing systems. Cardinal Health leverages its distribution scale to bundle thawing equipment with reagent supply contracts across hospital networks. Helmer Scientific sustains technology leadership through controlled-rate thawing protocols that preserve plasma protein integrity. Sarstedt competes with compact benchtop units engineered for satellite blood banks and emergency departments.
A blood thawing system is a thermal processing device engineered to raise frozen blood components from cryogenic storage temperature to infusion-ready state without hemolysis or protein denaturation, typically employing water bath circulation, dry heat conduction, or microwave energy delivery with precision temperature feedback loops and agitation mechanisms to ensure uniform warming. These systems serve transfusion medicine by maintaining FDA-mandated thawing curves that preserve coagulation factor activity in fresh frozen plasma and minimize bacterial proliferation risk in packed red cells. Automated thawing platforms command premium positioning due to their compliance traceability and labor reduction, while manual thawing basins retain share in resource-constrained settings where capital expenditure limits prevail. Microwave and rapid thawing technologies are gaining traction in emergency care and trauma applications where speed-to-transfusion directly impacts patient outcomes.
FDA 21 CFR Part 606 blood product regulations, AABB quality standards, and ISO 13485 medical device management systems collectively define the validation burden for thawing system manufacturers seeking US market access. These frameworks mandate documented temperature monitoring, alarm systems, and cleaning protocols that elevate engineering costs but also create barriers against unvalidated imports. Stakeholders must monitor evolving EU MDR requirements and emerging Asian regulatory harmonization initiatives that will reshape certification pathways and competitive eligibility across major procurement markets.
Market Dynamics
Automated thawing platforms are compressing manual workflows as hospital transfusion services face simultaneous pressure from FDA validation mandates and labor cost inflation. Equipment manufacturers must engineer compliance traceability into thermal processing hardware while defending price positions against rental-model disruptors.
Growth Catalysts
- Fresh frozen plasma protocols:Trauma centers and surgical suites require rapid thawing curves that preserve coagulation factor activity, pulling demand toward controlled-rate systems with precision temperature feedback loops.
- EU MDR implementation:The Medical Device Regulation's enhanced clinical evidence requirements are filtering out unvalidated imports, creating procurement preference for ISO 13485-certified manufacturers with documented quality management systems.
- Japan's aging transfusion infrastructure:Metropolitan blood banks in Tokyo and Osaka are modernizing cryogenic storage-to-thaw workflows, opening replacement cycles for dry heat conduction platforms that reduce water-borne contamination risk.
Market Restraints
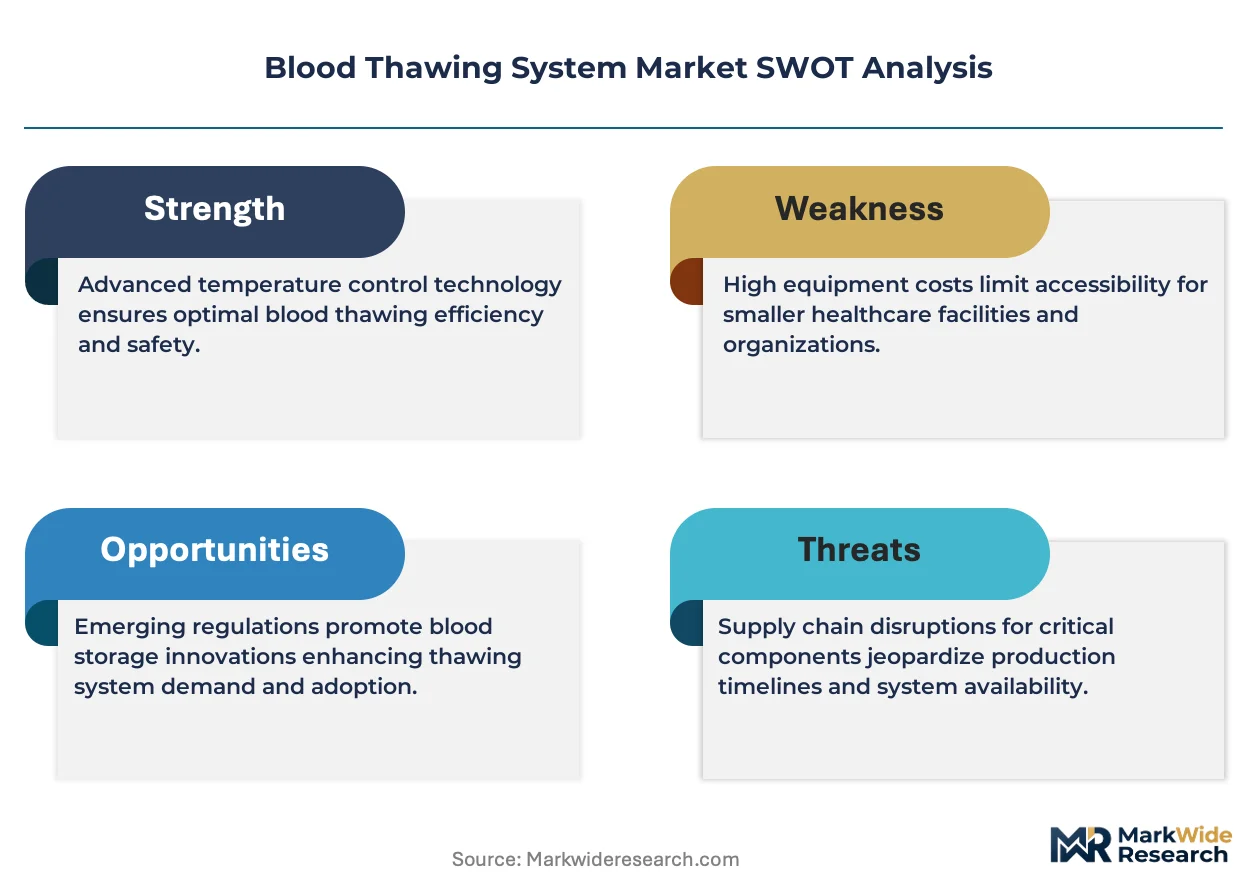
- Stainless steel and electronic component costs:Input price volatility for precision heating elements and medical-grade alloys compresses margin structures for mid-tier equipment manufacturers without captive supply chains.
- Water bath maintenance burden:Manual thawing basins retain installed base in resource-constrained settings where capital expenditure limits and biomedical engineering staffing gaps delay automation adoption.
- Validation timeline friction:FDA 21 CFR Part 606 compliance documentation requirements extend sales cycles by 8-14 months for new market entrants lacking predicate device pathways.
Strategic Opportunities
- Emergency department point-of-care thawing:Microwave and rapid-thaw technologies are penetrating trauma bays where speed-to-transfusion directly impacts mortality outcomes, creating premium pricing power for 10-minute plasma protocols.
- India's blood bank modernization:The country's national pharmaceutical regulator is harmonizing cold chain standards with WHO guidelines, opening certification pathways for automated platforms in tier-2 city hospitals.
- Cloud-connected temperature logging:Integration of thawing systems with hospital information systems enables real-time compliance documentation, differentiating vendors in AABB-accredited transfusion service procurement.
Industry Challenges
- Biomedical engineering specialization:Shortage of technicians trained in thermal processing equipment validation and preventive maintenance limits deployment velocity in community hospital settings.
- Legacy water bath integration:Replacement of installed manual systems requires workflow redesign and staff retraining, slowing automation penetration in satellite blood banks with constrained operational bandwidth.
- Cross-border certification complexity:Divergent electromagnetic compatibility standards between FDA, CE marking, and PMDA jurisdictions force redundant testing expenditures for global product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Thawing System Market |
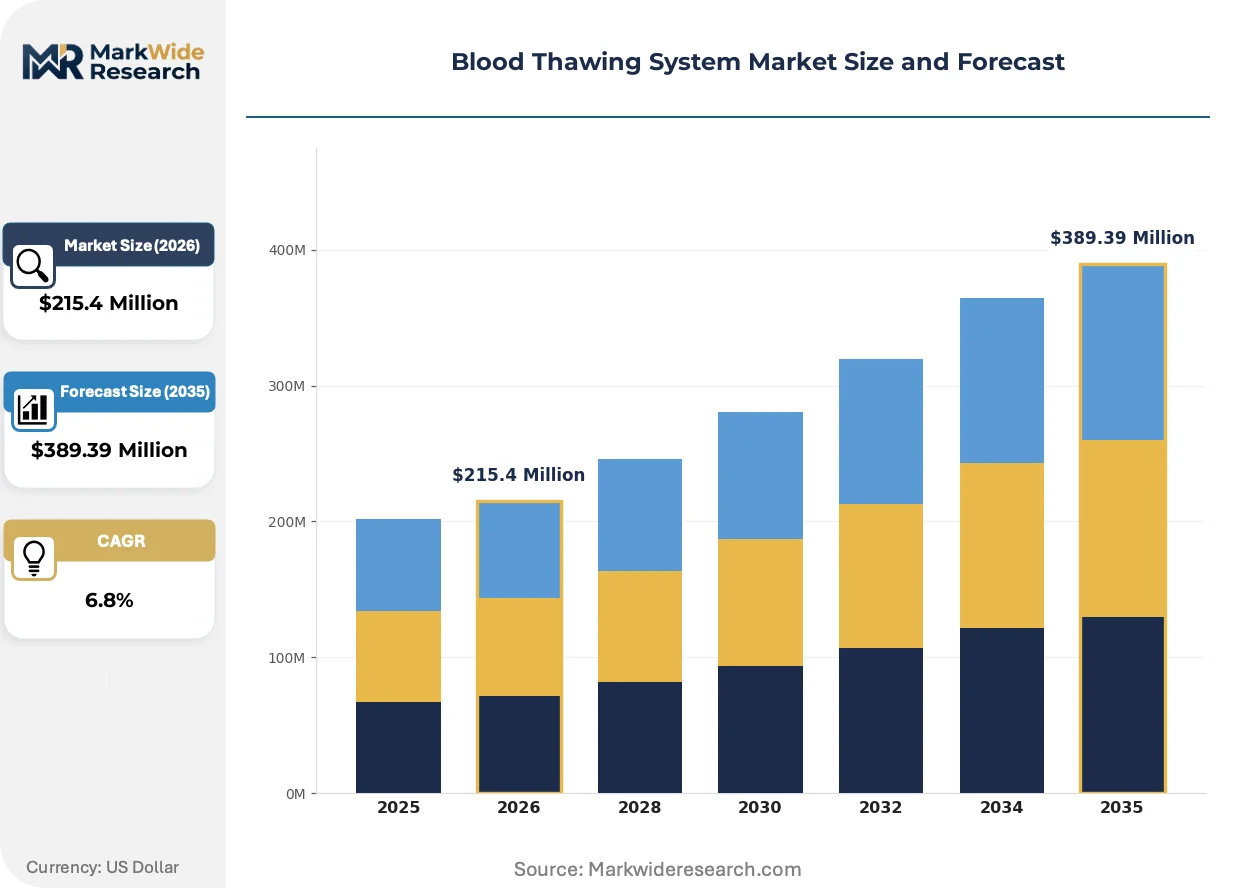
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Thawing, Automated Thawing, Thawing Basins, Consumables End User: Hospitals, Blood Banks, Research Laboratories, Clinics Technology: Water Bath, Microwave Thawing, Passive Thawing, Rapid Thawing Application: Surgical Procedures, Transfusion Services, Emergency Care, Research |
| Companies Covered | Sarstedt, Cardinal Health, Helmer Scientific, Sartorius, Thermo Fisher Scientific, Barkey, BioCision, GE Healthcare, Boekel Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Thawing System Market Strategic Shifts & Innovations
Dry heat conduction technology is displacing water bath circulation as the dominant thermal transfer mechanism, driven by contamination risk aversion and precision control requirements in plasma protein preservation.
Radio-frequency identification is digitizing chain-of-custody documentation for frozen blood components. Blood banks in Germany and the United States are embedding RFID tags in plasma inventory, enabling automated thaw queue management and expiration tracking. This technology is digitizing compliance workflows that previously required manual temperature logging and handwritten batch records.
The FDA's updated guidance on computer software assurance for manufacturing equipment is elevating validation requirements for thawing system control algorithms. Manufacturers must now document cybersecurity risk management and software lifecycle processes alongside traditional thermal performance testing. Automated platform vendors with pre-validated software modules are capturing preference in hospital network procurement.
Transfusion services are consolidating vendor relationships through multi-year equipment service agreements that bundle thawing hardware with preventive maintenance and reagent supply. This pattern is most visible in United States health systems where supply chain rationalization priorities favor single-source contracts over capital purchase models. Rental and lease structures are displacing outright equipment ownership in mid-sized hospitals seeking operational expenditure flexibility.
Blood Thawing System Market Segmentation
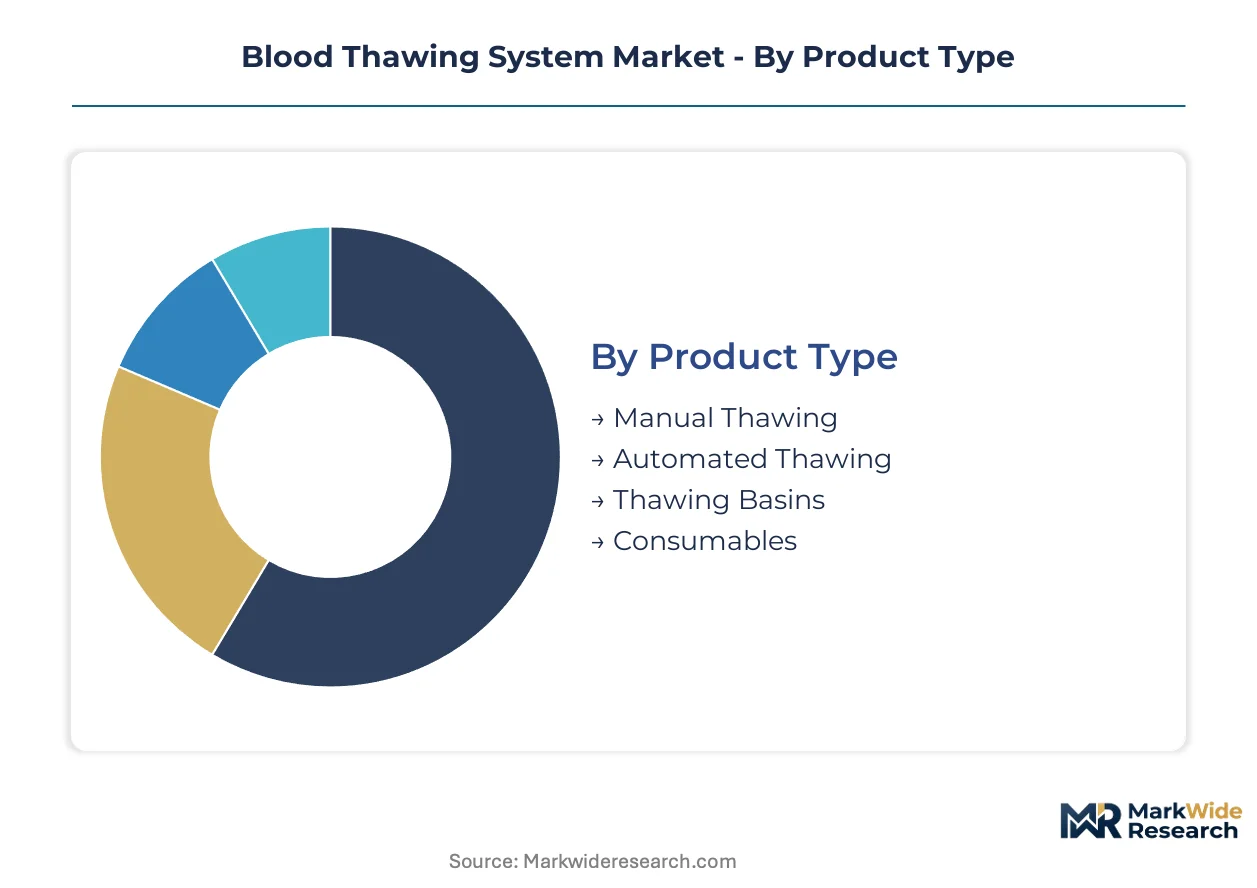
Blood thawing system procurement varies sharply across clinical settings. Transfusion services prioritize validation documentation and throughput capacity. Emergency departments weight speed-to-transfusion above all else. Research laboratories demand precision temperature logging for protocol reproducibility.
Product Type:
After-sales service intensity escalates with automation tier. Automated platforms require quarterly calibration, software updates, and preventive maintenance contracts that lock in vendor relationships for 5-7 year cycles. Manual equipment demands minimal field support but carries higher litigation exposure from temperature excursion events.
- Automated Thawing:Microprocessor-controlled thermal processing with integrated temperature feedback loops and automated agitation preserves coagulation factor activity in fresh frozen plasma. Demand concentrates in United States hospital networks modernizing transfusion services under FDA 21 CFR Part 606 pressure. Service contract bundling is displacing capital purchase models.
- Manual Thawing:Operator-dependent water bath or dry heat systems requiring continuous monitoring and manual rotation of blood bags. Retains installed base in resource-constrained blood banks where biomedical engineering staffing gaps delay automation adoption.
- Thawing Basins:Stainless steel reservoirs with circulating water jackets for batch processing multiple units simultaneously.
- Consumables:Disposable temperature probes, calibration standards, and cleaning agents tied to specific equipment platforms.
By volume, Manual Thawing leads. By growth pace, Automated Thawing is ahead.
End User:
Capital allocation authority and reimbursement pathways fragment demand across institutional types. Hospitals command multi-system procurement budgets. Blood banks operate under cost-recovery constraints that favor rental structures.
- Hospitals:Integrated health systems with centralized transfusion services and emergency departments requiring 24/7 thawing capacity. United States academic medical centers are consolidating vendor relationships through multi-year equipment service agreements.
- Blood Banks:Regional collection and distribution facilities processing plasma inventory for multiple hospital clients. Japan's metropolitan blood banks in Tokyo and Osaka are driving replacement demand for dry heat platforms.
- Research Laboratories:Cell therapy and regenerative medicine facilities requiring documented thawing curves for regulatory submission.
- Clinics:Outpatient infusion centers with intermittent transfusion needs and limited capital budgets.
Hospitals capture the largest revenue share. Research Laboratories are expanding most quickly.
Technology:
Heat transfer modality determines contamination risk, precision control, and maintenance burden. Water bath circulation faces displacement from dry heat conduction despite lower capital cost.
- Water Bath:Circulating heated water providing uniform thermal transfer with established validation protocols. Remains prevalent in blood banks with legacy infrastructure and established cleaning SOPs.
- Microwave Thawing:Electromagnetic energy delivery achieving 10-minute plasma protocols in trauma bays where speed-to-transfusion impacts mortality outcomes. Premium pricing power in emergency department point-of-care applications.
- Passive Thawing:Ambient temperature equilibration without active heating, restricted to non-critical applications.
- Rapid Thawing:Hybrid thermal processing combining conductive and convective heat transfer for intermediate speed requirements.
Water Bath retains volume leadership. Microwave Thawing shows the steepest expansion trajectory.
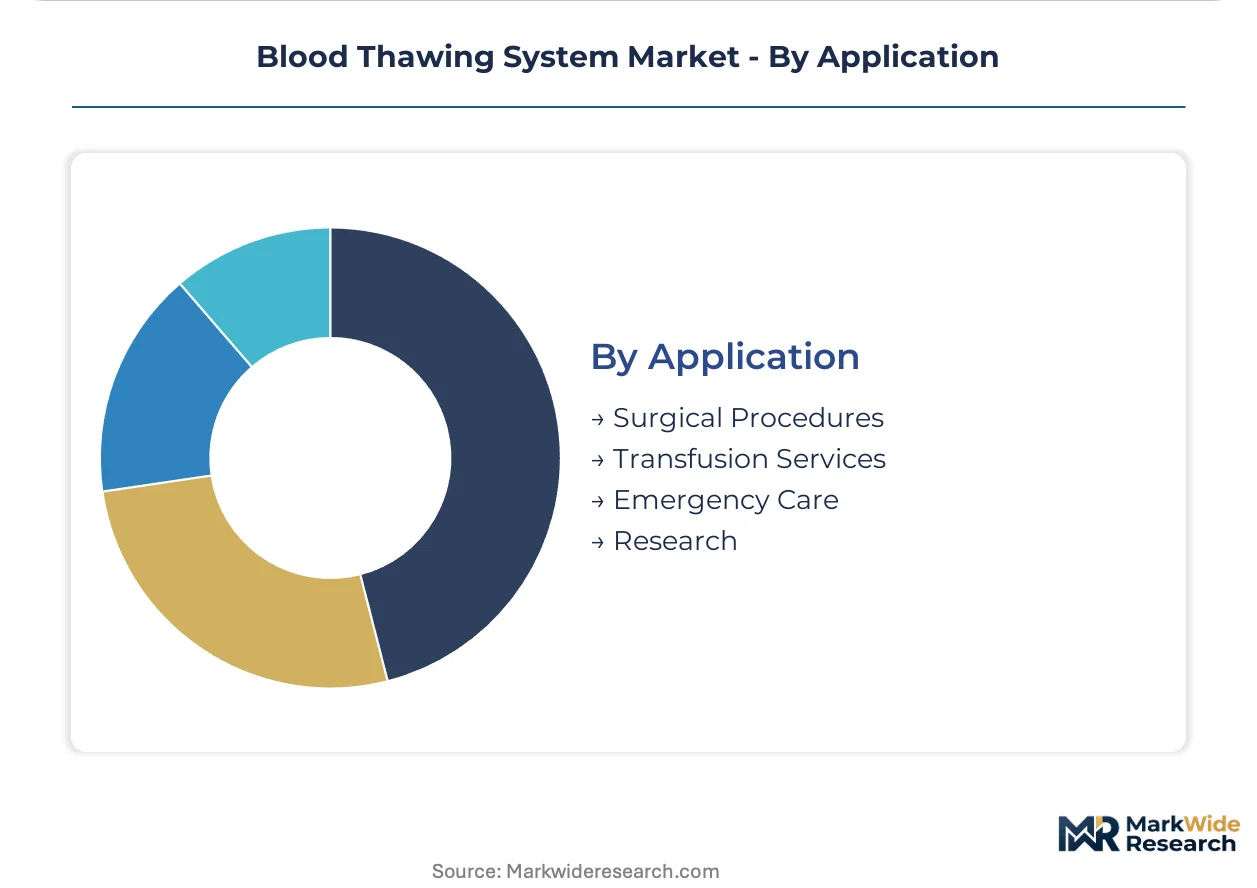
Application:
Clinical urgency and regulatory scrutiny intensity vary across use cases. Surgical schedules permit planned thawing. Emergency protocols demand immediate availability.
- Emergency Care:Trauma bays and emergency departments requiring plasma availability within minutes of patient arrival. Microwave and rapid-thaw technologies are penetrating this segment where mortality outcomes correlate with transfusion speed.
- Transfusion Services:Hospital-based blood banks managing scheduled surgical cases and inpatient needs with controlled-rate thawing protocols. FDA validation mandates and AABB accreditation requirements concentrate demand toward automated platforms.
- Surgical Procedures:Operating room suites with predictable scheduling enabling batch thawing workflows.
- Research:Cell therapy manufacturing and regenerative medicine protocols requiring precise temperature documentation.
Transfusion Services dominates by installed base. Emergency Care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 606 validation mandates and EU MDR implementation are redirecting procurement toward certified manufacturers with documented quality management systems. Hospital networks in high-income markets are consolidating vendor relationships through multi-year equipment service agreements.
United States
Academic medical centers and integrated health systems are modernizing transfusion services under FDA blood-handling guideline pressure. The agency's updated computer software assurance guidance elevates validation requirements for thawing system control algorithms. Major hospital networks in Boston and the Research Triangle are bundling thawing hardware with preventive maintenance contracts.
Germany
Metropolitan blood banks and university hospitals are adopting dry heat conduction platforms to reduce water-borne contamination risk. EU MDR enhanced clinical evidence requirements are filtering out unvalidated imports. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host ISO 13485-certified manufacturers serving hospital procurement consortia.
Japan
Aging transfusion infrastructure in Tokyo and Osaka is driving replacement cycles for automated thawing platforms. PMDA medical device regulations mandate documented temperature monitoring and alarm systems. The Kanto region's blood banking modernization programs favor controlled-rate thawing protocols that preserve plasma protein integrity.
India
Tier-2 city hospitals are expanding cold chain capacity as the national pharmaceutical regulator harmonizes standards with WHO guidelines. CDSCO medical device rules are opening certification pathways for automated platforms. Maharashtra and Karnataka are piloting cloud-connected temperature logging in regional blood bank networks.
United Kingdom
NHS transfusion services are consolidating equipment procurement through framework agreements that emphasize compliance traceability. MHRA post-Brexit regulatory alignment with EU MDR maintains stringent validation requirements. London and Manchester hospital networks are replacing legacy water bath systems with dry heat platforms.
Blood Thawing System Market Key Industry Players
On the supply side, the industry is moderately consolidated around established medical device manufacturers with cryogenic handling expertise. Tiered competition separates premium automated platforms from manual equipment suppliers. Three archetypes dominate: diversified healthcare conglomerates with distribution scale, specialized thermal processing equipment makers, and compact benchtop unit specialists. Strategic moves center on service contract bundling and geographic expansion through distributor partnerships.
Among diversified healthcare suppliers, Cardinal Health leverages distribution infrastructure to bundle equipment with reagent supply contracts. Helmer Scientific occupies a position within the specialized thermal processing tier, while Sarstedt exemplifies the compact benchtop specialist archetype targeting satellite blood banks. These three represent distinct competitive vectors: scale-driven supply chain integration, technology leadership in controlled-rate protocols, and point-of-care form factor optimization.
| Leading Market Players |
|---|
| Sarstedt |
| Cardinal Health |
| Helmer Scientific |
| Sartorius |
| Thermo Fisher Scientific |
| Barkey |
| BioCision |
| GE Healthcare |
| Boekel Scientific |
| Others |
Cost & Logistics Intelligence
Baden-Württemberg's concentration of ISO 13485-certified thermal processing equipment manufacturers feeds downstream pricing power into hospital procurement networks across Germany and neighboring markets. The region's engineering density creates captive supply advantages for precision heating elements that compress margin structures for competitors lacking similar geographic clustering.
Pricing Analysis
Certification level (ISO 13485/FDA-grade versus CE-marked standard tier) creates the primary spread between premium automated platforms and manual equipment. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling intensity rather than hardware differentiation alone. Cost compression in mid-tier equipment is intensifying because stainless steel and electronic component input volatility erodes fixed-cost leverage. Satellite blood banks and resource-constrained clinics exhibit highest price sensitivity, while academic medical centers prioritize compliance traceability over capital expenditure minimization.
Supply Chain Analysis
Export-control restrictions on precision temperature sensors and microprocessor-controlled heating elements limit component flows from certain jurisdictions into medical device manufacturing. Supply concentrates in Germany, Japan, and the United States for finished thawing platforms, with China and South Korea anchoring upstream production of electronic control modules. The supply chain draws from medical-grade stainless steel alloys, precision thermistors, and agitation mechanism motors. Single-source vulnerability in semiconductor-based temperature feedback components creates procurement risk. Distribution runs through hospital group purchasing organizations and specialized medical device distributors serving blood bank networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because preventive maintenance contracts and calibration service agreements are expanding faster than hardware unit sales, locking vendors into multi-year recurring revenue relationships.
For Market Incumbents: Insulate installed base positions by embedding cloud-connected temperature logging capabilities that raise switching costs for hospital transfusion services. Backward integration into precision heating element supply reduces exposure to input price volatility from Asian component suppliers. Cardinal Health and Helmer Scientific have demonstrated that multi-year equipment service agreements bundling thawing hardware with reagent supply contracts create defensive moats against rental-model disruptors targeting capital-constrained buyers. For New Entrants and Emerging Players: India's tier-2 city hospitals present the most penetrable white-space target as CDSCO harmonizes cold chain standards with WHO guidelines and regional blood bank networks pilot automated platforms. Microwave thawing technology for emergency department point-of-care applications offers a second entry vector where speed-to-transfusion commands premium pricing power absent from saturated transfusion service segments. A distributor partnership model leveraging established hospital supply relationships accelerates market access without capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle consolidation play because aging water bath infrastructure in Japan and Western Europe drives predictable demand for dry heat conduction upgrades over the coming decade. Acquisition targets should display ISO 13485 certification with predicate device pathways already established, shortening FDA validation timelines for platform expansion. The signal to watch is PMDA regulatory harmonization initiatives that would streamline multi-jurisdiction product approvals and expand addressable market for certified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Bundled equipment-service contracts with academic medical centers lock in 5-7 year vendor relationships under FDA 21 CFR Part 606 pressure. |
| CE Marking Pathway | EU MDR enhanced clinical evidence requirements filter out unvalidated imports, creating procurement preference for certified manufacturers. |
| Software Companion Development | Cloud-connected temperature logging modules differentiate vendors in AABB-accredited transfusion service procurement processes. |
| Backward Integration | In-house production of precision heating elements compresses cost structures and insulates margin against stainless steel price volatility. |
| Geographic Expansion | Distributor partnerships in India's Maharashtra and Karnataka regions capture blood bank modernization pilots before competitors establish presence. |
Research Approach
Cross-validation between primary interviews with hospital transfusion service directors, biomedical engineering managers, blood bank operations leads, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, AABB accreditation databases, hospital procurement records, and EU MDR notified body certificates. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure analysis triangulate market sizing across product tiers.
Calibration against historical replacement cycles in Japan's aging transfusion infrastructure and documented EU MDR implementation timelines refines growth trajectory assumptions across the analysis window. Segmentation modeling incorporates automation tier, heat transfer modality, end-user facility type, and regional regulatory cluster dimensions. CAGRs derive from installed base erosion rates in manual equipment and penetration velocity of automated platforms in academic medical centers.
Practitioners should monitor FDA guidance evolution on computer software assurance and PMDA regulatory harmonization initiatives for early signals of validation burden shifts. Forecasts reflect assumptions regarding hospital network consolidation patterns and blood bank modernization funding availability. Material shifts in stainless steel input costs or electromagnetic compatibility standard divergence between FDA and PMDA jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Mask Market
Medical Devices
Kirschner Wires Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
3D Printed Implants Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Blood Collection Devices Market
Medical Devices
Otoscope Devices Market