
 Europe Electric Vehicle (EV) Fluids Market | 2026-2036
Europe Electric Vehicle (EV) Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle (EV) Fluids Market Analysis
Market Context
The divergence between premium synthetic formulations and commodity mineral oil blends is repositioning competitive boundaries across Europe. Shell plc leverages its integrated lubricants-to-chemicals chain to control feedstock quality for high-voltage compatible coolants. Castrol anchors its position through OEM co-development programs with German and French vehicle assemblers. FUCHS Petrolub SE differentiates via specialized dielectric fluid portfolios targeting battery thermal management systems.
Technical Definition and Segment Structure
Europe Electric Vehicle (EV) Fluids comprise engineered liquids formulated for thermal stability, electrical insulation, and material compatibility in electrified powertrains, typically specified with dielectric strength above 30 kV/mm and operating ranges from minus 40°C to 150°C. Their primary purpose is to manage heat rejection from battery packs and electric motors while preventing short circuits in high-voltage architectures. Coolants dominate value capture due to the complexity of battery thermal management, while synthetic formulations claim the fastest expansion as OEMs reject mineral oils for direct battery contact applications. Aftermarket providers represent a concentrated margin pool as early BEV cohorts exit warranty and require specialized fluid replacement protocols.
Regulatory Framework and Outlook
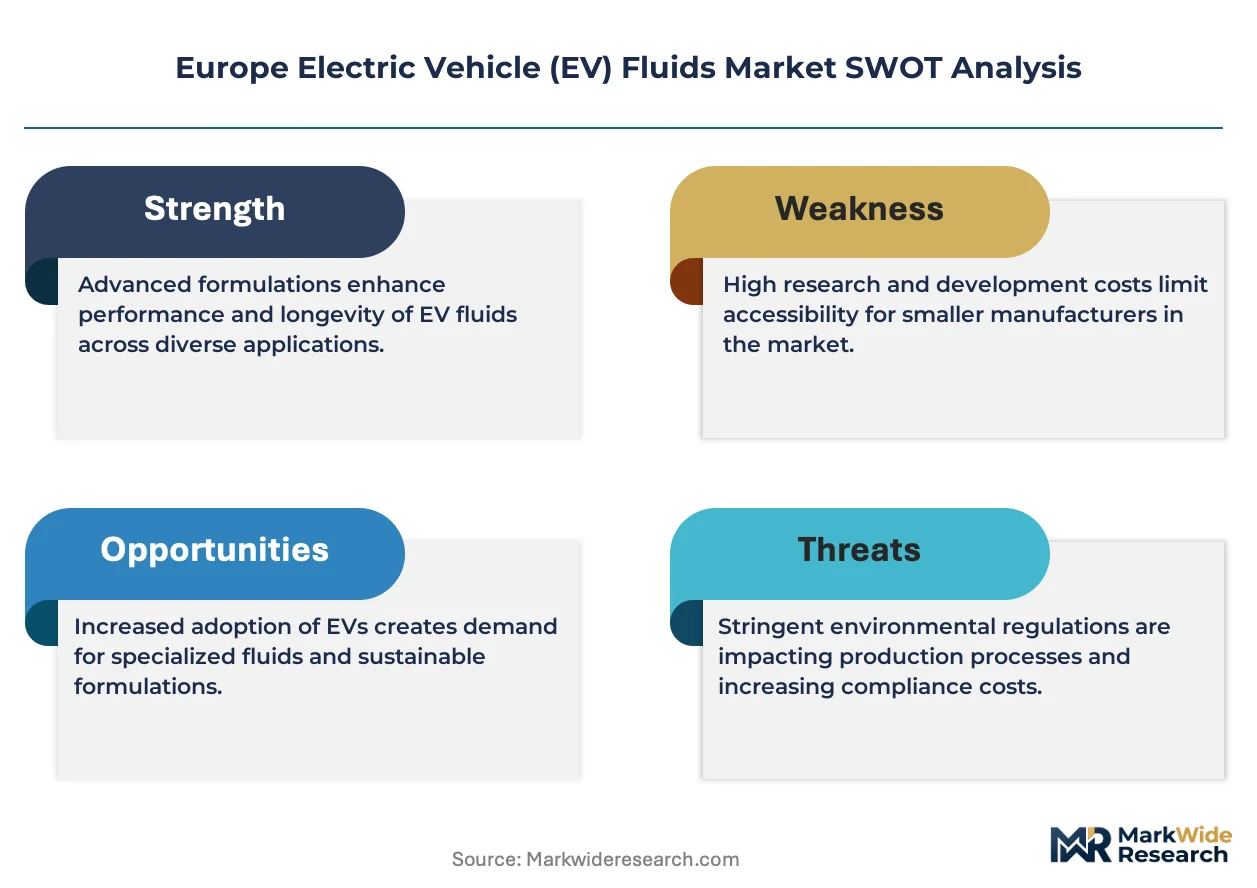
EMA chemical safety assessments, REACH substance restrictions, and the EU F-Gas Regulation collectively constrain coolant formulation choices and mandate lower-global-warming-potential alternatives across member states. ECHA registration requirements for new dielectric chemistries extend product development timelines, favoring incumbents with established substance dossiers. Stakeholders must monitor evolving battery passport traceability rules and thermal management efficiency standards as the primary determinants of formulation R&D allocation.
Market Dynamics
Battery-electric commercial vehicle deployment is concentrating procurement power among fleet operators who now specify dielectric coolant packages as mandatory components in tender documents, forcing formulators to restructure technical service organizations around direct fleet relationships rather than traditional distributor networks.
Growth Catalysts
- EU Green Deal decarbonization mandates:The framework's 2035 internal combustion engine phase-out deadline compels OEMs to accelerate BEV platform launches, creating dedicated fluid specification demand across German and French assembly lines.
- 800V high-voltage architectures:Premium passenger vehicle platforms migrating to higher voltage topologies require reformulated dielectric fluids with enhanced thermal conductivity and electrical insulation properties.
- Fleet electrification procurement:Municipal bus operators in the Netherlands and Scandinavian markets are consolidating supplier relationships through multi-year fluid service contracts tied to battery warranty terms.
Market Restraints
- Base oil supply concentration:Synthetic polyalphaolefin feedstock production clusters in Belgium and Germany, exposing formulators to single-source risk during refinery maintenance cycles.
- ECHA registration timelines:New dielectric chemistry dossier reviews extend 18-24 months, freezing formulation innovation pipelines for mid-tier suppliers lacking pre-registered substance libraries.
- Additive package cost volatility:Corrosion inhibitor and antioxidant raw materials indexed to rare earth metal pricing create margin compression for standardized coolant blends.
Strategic Opportunities
- Poland and Czech Republic manufacturing corridors:Battery cell gigafactory construction in these markets outpaces local fluid blending capacity, creating import substitution openings for regional production facilities.
- Battery passport traceability integration:The EU's emerging digital product passport requirements position fluid formulators to capture value through lifecycle thermal performance data services.
- Second-life battery stationary storage:Repurposed automotive battery packs deployed in grid storage applications require modified coolant maintenance protocols, extending addressable aftermarket volume.
Industry Challenges
- High-voltage safety certification gaps:Field service technician training for EV coolant handling under EMA electrical safety protocols remains underdeveloped across Southern European aftermarket networks.
- Formulation-to-cell chemistry matching:Solid-state and lithium-metal cell architectures entering pilot production demand redesigned thermal interface materials, forcing R&D resource reallocation before volume economics stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle (EV) Fluids Market |
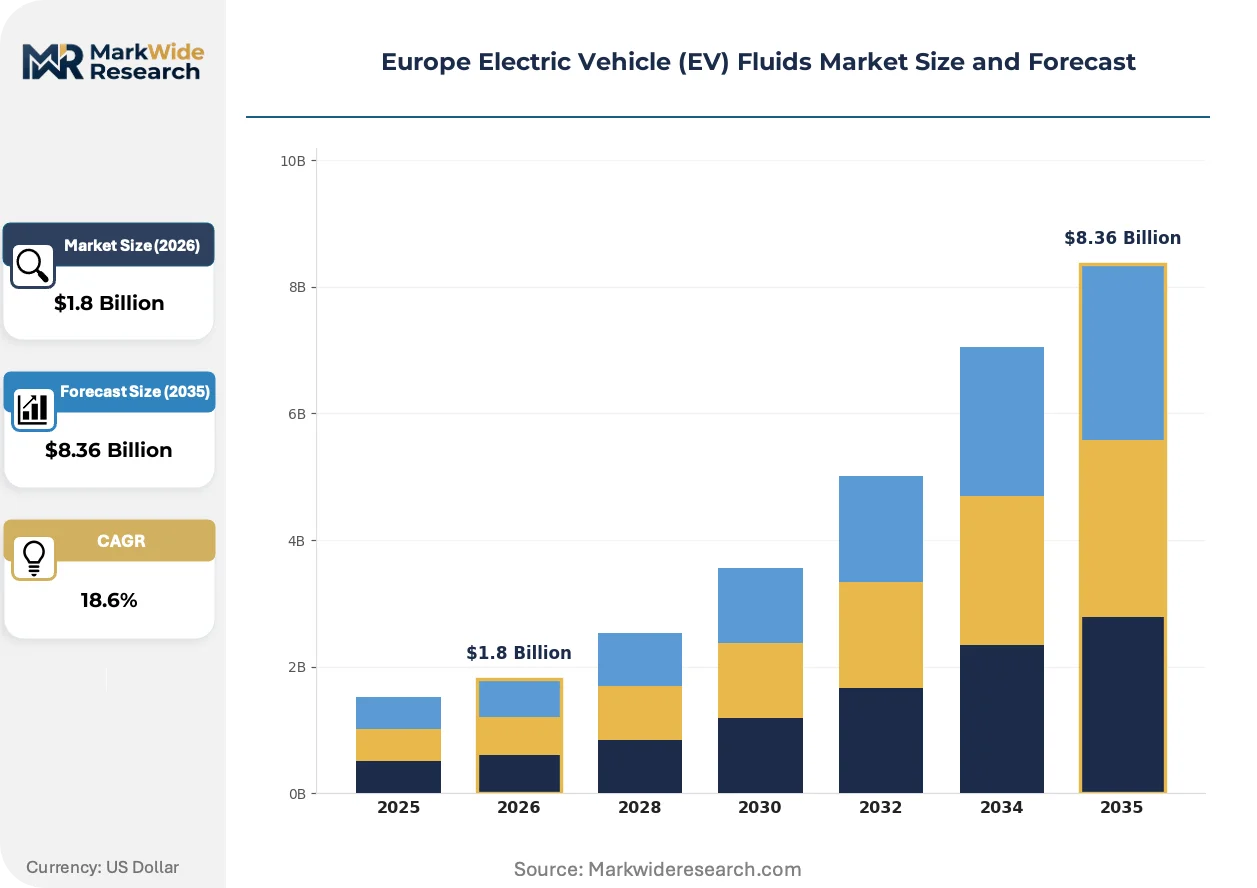
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolants, Lubricants, Brake Fluids, Transmission Fluids Application: Battery Cooling, Lubrication Systems, Brake Systems, Thermal Management Formulation: Synthetic, Bio-based, Mineral Oil, Water-based End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | BP plc, Castrol, Shell plc, Liqui Moly GmbH, Valvoline Inc., TotalEnergies SE, FUCHS Petrolub SE, Motul, ExxonMobil Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle (EV) Fluids Market Emerging Trajectories
Direct battery contact cooling architectures are eliminating intermediate cold plates, forcing fluid formulators to engineer chemistries that manage both thermal transfer and electrical isolation within the same liquid layer. This convergence is compressing the historical separation between powertrain lubricants and battery thermal management systems.
Two-phase immersion cooling utilizing engineered fluorinated fluids is absorbing heat flux densities exceeding 100W/cm² in prototype battery modules, enabling faster charging protocols. European OEMs in Germany and Sweden are piloting these systems in premium SUV platforms scheduled for 2026-2027 production. The technology is absorbing development budgets previously allocated to incremental improvements in single-phase glycol coolants, reshaping supplier R&D prioritization across the region.
REACH substance restriction proposals targeting specific glycol ether compounds are forcing reformulation of established coolant bases before 2027 compliance deadlines. The regulatory pressure accelerates adoption of bio-based polyol alternatives derived from European agricultural feedstocks. Coolant suppliers serving French and Italian OEMs are most exposed, responding with accelerated substance dossier filings and supply chain audits of tier-2 additive providers.
Fleet maintenance contracts are unbundling fluid replacement from general service packages, creating standalone thermal management service lines with performance-guaranteed pricing. Independent workshop chains in Germany and the Netherlands are acquiring specialized EV fluid handling equipment to capture this revenue stream. The shift is most visible in municipal bus depots, where total-cost-of-ownership contracts now specify fluid thermal conductivity maintenance thresholds rather than simple volume replacement schedules.
Europe Electric Vehicle (EV) Fluids Market Segmentation
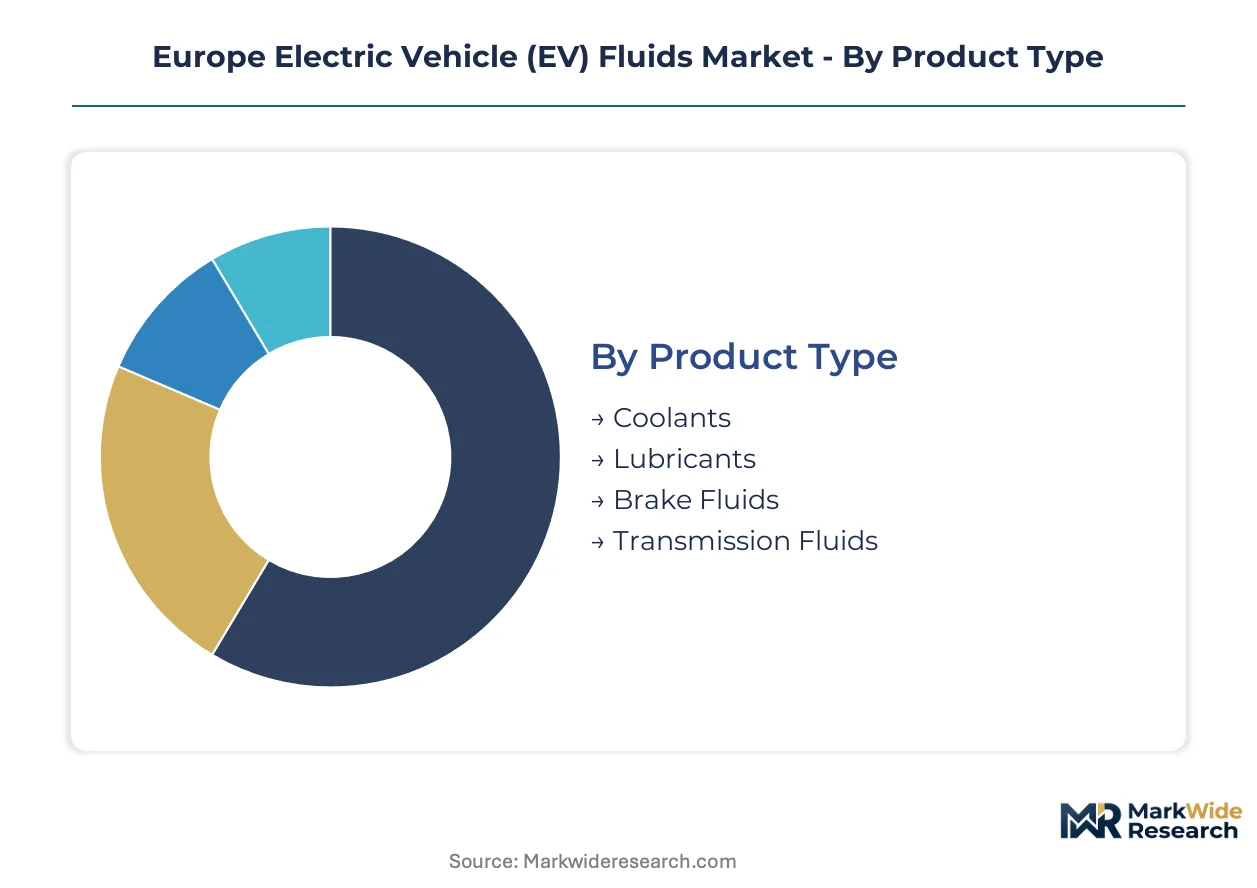
Fluid specification in Europe's EV sector hinges on thermal management intensity and electrical isolation requirements. Procurement decisions increasingly separate high-voltage battery contact applications from legacy powertrain lubrication, reshaping supplier qualification criteria across German and French assembly networks.
Product Type:
Fleet operators specify fluid packages based on thermal load density and replacement frequency rather than unit cost.
- Coolants:Dielectric formulations with thermal conductivity above 0.15 W/m·K manage heat rejection from battery packs and power electronics. Demand concentrates in German OEM thermal management programs where 800V architectures require enhanced electrical insulation properties. ECHA substance dossiers for novel glycol ether alternatives extend development timelines for reformulated bases.
- Lubricants:Synthetic polyalphaolefin-based products reduce friction in reduction gearboxes and electric motor bearings. French vehicle assemblers specify these for premium passenger platforms, rejecting mineral oil blends for direct high-voltage component proximity.
- Brake Fluids:Low-viscosity silicone and glycol ether formulations serve regenerative braking system hydraulic circuits.
- Transmission Fluids:Single-speed reduction gearbox lubricants prioritize thermal stability over friction modification.
Coolants lead on scale; synthetic lubricants lead on momentum.
Application:
Application selection tracks voltage architecture migration and charging speed requirements across European platforms.
- Battery Cooling:Direct contact and cold plate circulation systems demand dielectric strength above 30 kV/mm for high-voltage safety. Netherlands municipal bus fleets specify performance-guaranteed thermal conductivity maintenance thresholds in service contracts.
- Lubrication Systems:Reduction gearbox and motor bearing applications prioritize oxidation stability for extended drain intervals. German OEM co-development programs dominate specification authority for these products.
- Brake Systems:Hydraulic actuation fluids for blended regenerative-mechanical braking architectures.
- Thermal Management:Integrated power electronics and cabin heating circuits require low-viscosity heat transfer fluids.
Battery cooling commands procurement volume; lubrication systems offer margin stability.
Formulation:
REACH compliance deadlines and F-Gas Regulation constraints drive substitution away from established chemistries.
- Synthetic:Polyalphaolefin and ester-based products deliver dielectric stability across minus 40°C to 150°C operating ranges. Belgium and Germany host concentrated feedstock production, exposing formulators to single-source supply risk during refinery maintenance.
- Bio-based:Polyol alternatives derived from European agricultural feedstocks address REACH restriction proposals targeting specific glycol ether compounds. French and Italian OEMs accelerate adoption ahead of 2027 compliance deadlines.
- Mineral Oil:Conventional base stocks retreat to non-battery applications as OEMs reject electrical compatibility risks.
- Water-based:Glycol-water mixtures with corrosion inhibitor packages for non-conductive thermal management circuits.
Synthetic formulations dominate current specification; bio-based alternatives gain share fastest.
End User:
Procurement concentration shifts from distributor networks toward direct technical service relationships.
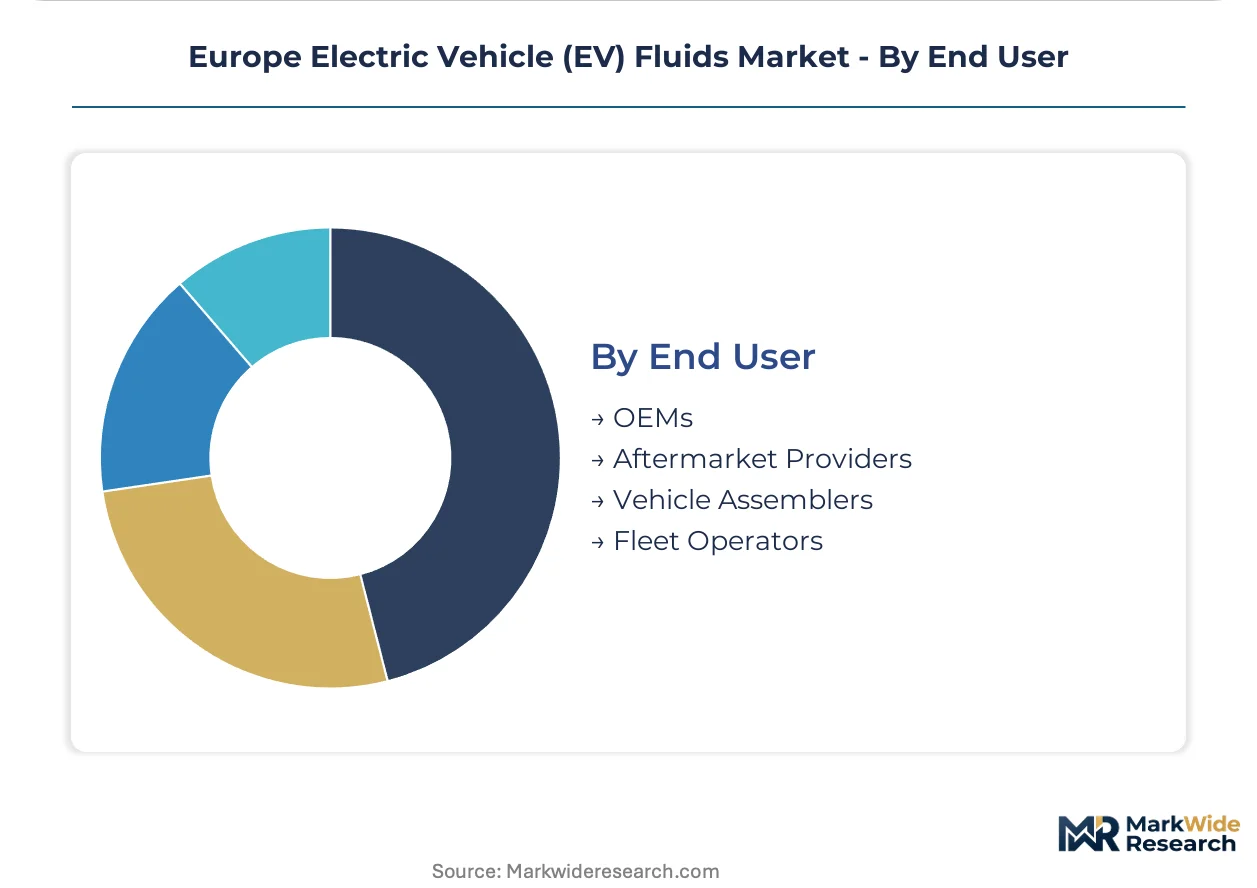
- OEMs:German and French vehicle assemblers specify dedicated fluid packages through co-development programs, locking in multi-year supply agreements. Thermal management efficiency standards in tender documentation favor incumbents with established substance dossiers.
- Fleet Operators:Municipal bus operators in Scandinavian markets and the Netherlands consolidate supplier relationships through total-cost-of-ownership contracts tied to battery warranty terms. These stakeholders now mandate dielectric coolant packages as compulsory tender components.
- Aftermarket Providers:Independent workshop chains acquire specialized EV fluid handling equipment as early BEV cohorts exit warranty coverage.
- Vehicle Assemblers:Contract manufacturing facilities for emerging EV platforms.
OEMs anchor volume commitment; fleet operators drive specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more EV fluid specification authority than any other European market, while the Netherlands leads in fleet procurement consolidation through municipal tender structures. This divergence creates distinct competitive entry points across the region.
Germany
OEM co-development programs with major vehicle assemblers lock in multi-year supply agreements for dielectric coolant packages. The KBA enforces high-voltage safety certification standards that extend product qualification timelines. Stuttgart and Munich anchor thermal management R&D clusters where 800V architecture development accelerates reformulation cycles.
France
Premium passenger platform launches drive synthetic lubricant specification for reduction gearbox applications. The EU Green Deal implementation through national decarbonization mandates compels accelerated BEV platform rollouts. The Auvergne-Rhône-Alpes region hosts formulation facilities serving both domestic OEMs and export markets.
Netherlands
Municipal bus operators consolidate supplier relationships through total-cost-of-ownership contracts tied to battery warranty terms. The F-Gas Regulation drives lower-GWP coolant chemistry transitions ahead of neighboring markets. Eindhoven and Rotterdam concentrate fleet electrification procurement power through regional transport authority coordination.
Poland
Battery cell gigafactory construction outpaces local fluid blending capacity, creating import substitution demand for regional production facilities. ECHA registration requirements for new dielectric chemistries extend development timelines for domestic entrants. The Silesian manufacturing corridor attracts fluid formulators seeking proximity to emerging cell production sites.
Sweden
Premium SUV platforms pilot two-phase immersion cooling systems requiring engineered fluorinated fluids with enhanced heat flux absorption. The EU Green Deal framework accelerates commercial vehicle electrification timelines through national implementation. Gothenburg anchors OEM thermal management program development for 2026-2027 production schedules.
Europe Electric Vehicle (EV) Fluids Market Vendor Landscape
Top-tier vendors anchor specification authority with German and French OEMs, while mid-tier specialists compete on fleet service contracts and aftermarket penetration. The structure consolidates around substance dossier ownership and established ECHA registrations. Three archetypes dominate: integrated energy majors with chemicals-to-lubricants chains, independent lubricant specialists with dielectric fluid portfolios, and regional blenders serving fleet maintenance networks. Capacity expansion and strategic partnerships represent the primary competitive moves, with formulators restructuring technical service organizations around direct fleet relationships.
Among integrated energy majors, BP plc and Shell plc exemplify the feedstock-control archetype through their lubricants-to-chemicals operations. Castrol occupies a position within the OEM co-development tier, anchoring specification relationships with vehicle assemblers. FUCHS Petrolub SE represents the independent specialist archetype, with its GmbH structure signaling German engineering-focused positioning in dielectric fluid portfolios.
| Leading Market Players |
|---|
| BP plc |
| Castrol |
| Shell plc |
| Liqui Moly GmbH |
| Valvoline Inc. |
| TotalEnergies SE |
| FUCHS Petrolub SE |
| Motul |
| ExxonMobil Corporation |
| Others |
Supply Flow & Price Mechanics
Polyalphaolefin feedstock price indices in Belgium and Germany cascade through synthetic coolant formulations into three distinct pricing tiers across European procurement channels. Fleet operators with multi-year service contracts capture volume discounts below spot-market levels, while aftermarket providers absorb premium markups for specialized dielectric handling equipment and technician certification.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for regional fluid blending operations serving battery cell gigafactories. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation anchored in ECHA registration status and dielectric strength certification tiers. Cost compression in standardized glycol-water blends is intensifying because REACH restriction proposals accelerate reformulation timelines. Municipal bus fleets exhibit highest price sensitivity due to total-cost-of-ownership tender structures, while premium passenger OEMs prioritize thermal conductivity performance over unit cost.
Supply Chain Analysis
KBA high-voltage safety certification and ECHA substance dossier approvals gate supplier qualification timelines, extending product development cycles for new market entrants. Synthetic base oil production clusters in Belgium and Germany, with additive package sourcing from specialized chemical producers in France and Italy. The supply chain rests on polyalphaolefin feedstock, corrosion inhibitor additives, and fluorinated compounds for immersion cooling prototypes. Single-source vulnerability concentrates around Belgian refinery maintenance cycles. Distribution runs through direct technical service relationships with fleet operators rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe EV Fluids Market compounds steadily as the EU Green Deal's internal combustion engine phase-out deadline locks in platform conversion timelines across German and French assembly networks.
For Market Incumbents: To counter mid-tier suppliers with pre-registered ECHA substance libraries, anchor specification authority through OEM co-development programs for 800V architectures and accelerate backward integration into polyalphaolefin feedstock production in Belgium or Germany. For New Entrants and Emerging Players: Enter via Poland and Czech Republic manufacturing corridors where battery cell gigafactory construction outpaces local fluid blending capacity, targeting dielectric coolant supply for fleet maintenance contracts with performance-guaranteed thermal conductivity thresholds. For Investors and Strategic Acquirers: Consolidation pressure builds where ECHA registration timelines freeze formulation innovation pipelines for mid-tier suppliers lacking established substance dossiers. Five-to-ten-year viability favors targets with dielectric fluid portfolios and direct fleet technical service relationships. Monitor F-Gas Regulation enforcement intensity as the inflection signal for lower-GWP coolant chemistry substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Production | Captive polyalphaolefin supply from Belgian or German facilities insulates margin compression from refinery maintenance cycles. |
| ECHA Substance Dossier Expansion | Pre-registered dielectric chemistry libraries accelerate product qualification timelines against REACH restriction proposals. |
| Fleet Technical Service Restructuring | Direct relationships with Netherlands and Scandinavian municipal bus operators replace traditional distributor network dependency. |
| Regional Production Facility Establishment | Proximity to Polish and Czech battery cell gigafactories reduces logistics costs and import substitution premiums. |
| Two-Phase Immersion Cooling R&D Partnership | Engineered fluorinated fluid development with German and Swedish OEMs positions for premium SUV platform adoption. |
Methodological Framework
Multiple input streams — executive interviews with thermal management directors at German and French OEMs, procurement leads at Netherlands municipal transport authorities, technical service heads at European fluid blenders, and ECHA regulatory affairs specialists — were reconciled against customs trade data, SEC filings from integrated energy majors, ACC sector reports, and EU regulatory databases. Bottom-up volume modeling across coolant, lubricant, and transmission fluid categories was triangulated with top-down value projections derived from OEM supply agreement disclosures.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include fluid product type, voltage architecture application, synthetic versus bio-based formulation chemistry, and end-user procurement channel. CAGRs were derived from trend extrapolation of battery-electric vehicle production schedules and thermal management content-per-vehicle assumptions, cross-referenced with fleet electrification procurement timelines and aftermarket replacement frequency protocols for exiting warranty BEV cohorts.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in solid-state battery thermal interface material specifications and two-phase immersion cooling commercialization timelines introduce uncertainty bands around synthetic formulation demand projections. Forecasts reflect documented assumptions regarding EU Green Deal implementation velocity and F-Gas Regulation enforcement intensity. A model refresh is warranted upon material change in battery passport traceability rule finalization or 800V architecture adoption rates across premium passenger platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Agricultural Electric Vehicles Market