
 United Kingdom Hybrid Electric Vehicle Battery Market | 2026-2036
United Kingdom Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Hybrid Electric Vehicle Battery Market Insights
Multi-source procurement from Asian cell suppliers is hardening as British automakers diversify beyond single-source dependencies. LG Energy Solution anchors its UK position through established European supply infrastructure. Panasonic Corporation differentiates via cylindrical cell specialization for hybrid architectures. Samsung SDI competes on prismatic format scale suited to European OEM platforms.
A hybrid electric vehicle battery is an electrochemical storage system combining high-power discharge capability with regenerative charge acceptance, typically employing nickel-metal hydride or lithium-ion chemistries with 200-400V nominal architectures to enable parallel torque assist alongside internal combustion operation. Lithium-ion formats now dominate new hybrid designs due to superior gravimetric energy density and faster charge acceptance profiles. Nickel-metal hydride retains structural relevance in cost-sensitive hatchback segments where thermal stability and cycle longevity outweigh pack mass considerations. Fleet operators represent the fastest-growing end-user channel as British logistics firms electrify urban delivery routes under clean air zone pressures.
The UK's Office for Product Safety and Standards enforces battery safety certification under the Electrical Equipment (Safety) Regulations, while the Environment Agency governs end-of-life cell recycling through the Waste Batteries and Accumulators Regulations. The Competition and Markets Authority monitors supply chain concentration risks as cell imports dominate domestic demand. Stakeholders must track how post-Brexit UKCA marking divergence from CE standards reshapes qualification timelines for new cell entrants.
Market Dynamics
The UK's Zero Emission Vehicle mandate is compressing qualification timelines for domestic cell manufacturers while fleet electrification accelerates demand pull from British logistics operators.
Growth Catalysts
- Zero Emission Vehicle Mandate:The UK government's 2035 phase-out deadline for new internal combustion vehicles forces OEMs to expand hybrid lineups, directly expanding qualified battery procurement volumes.
- West Midlands Manufacturing Corridor:England's automotive production cluster concentrates cell demand from Jaguar Land Rover, Aston Martin, and commercial vehicle assemblers within a 50-mile radius.
- Clean Air Zone Expansion:Birmingham, Bristol, and London's Ultra Low Emission Zone penalize diesel van operations, pushing DPD, Royal Mail, and Amazon Logistics toward hybrid delivery fleet procurement.
Market Restraints
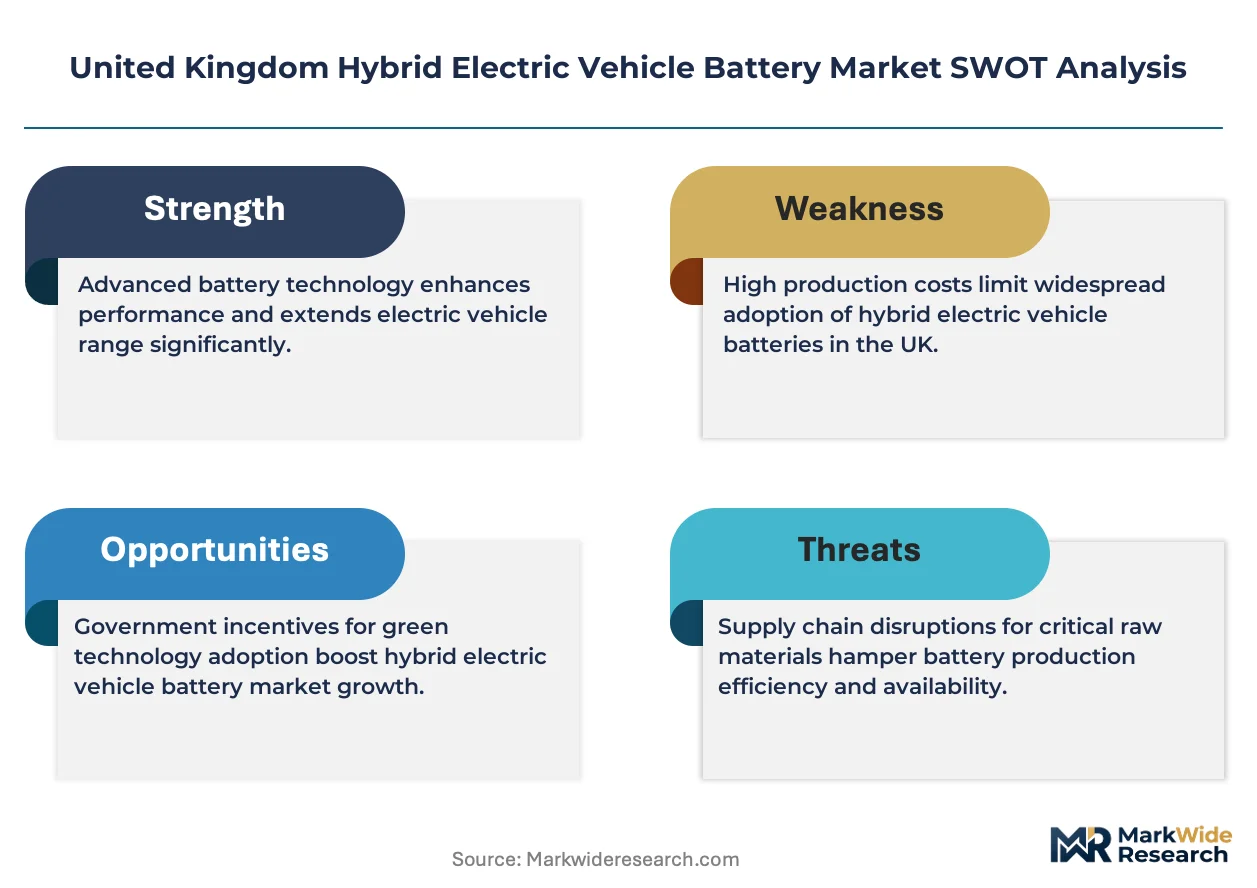
- Asian Cell Import Concentration:Over 80 percent of UK-qualified cells originate from South Korean and Chinese suppliers, creating single-source vulnerability for British pack assemblers.
- Lithium Carbonate Volatility:Cathode-active material pricing swings compress pack margin predictability for UK-based integrators lacking long-term offtake agreements.
- UKCA Marking Divergence:Post-Brexit certification timelines extend 4-6 months versus CE-equivalent approvals, delaying new cell chemistry introductions from European suppliers.
Strategic Opportunities
- Scottish Renewable Integration:Aberdeen and Glasgow's offshore wind surplus offers below-grid power for cell formation and aging facilities, cutting energy opex by 30-40 percent versus Midlands sites.
- Second-Life Stationary Storage:Retired hybrid packs from London's black cab fleet provide 60-70 percent residual capacity for commercial building peak-shaving applications.
- Advanced Propulsion Centre Funding:UK government grants for domestic gigafactory qualification reduce capital barriers for cell entrants targeting the 48V mild-hybrid segment.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:UK universities produce fewer than 200 battery-specialized graduates annually against demand from 15+ active cell and pack facilities.
- End-of-Life Recycling Infrastructure Gaps:The Environment Agency's Waste Batteries and Accumulators Regulations lack enforcement capacity for the 50,000+ tonne annual hybrid pack retirement wave expected by 2032.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Hybrid Electric Vehicle Battery Market |
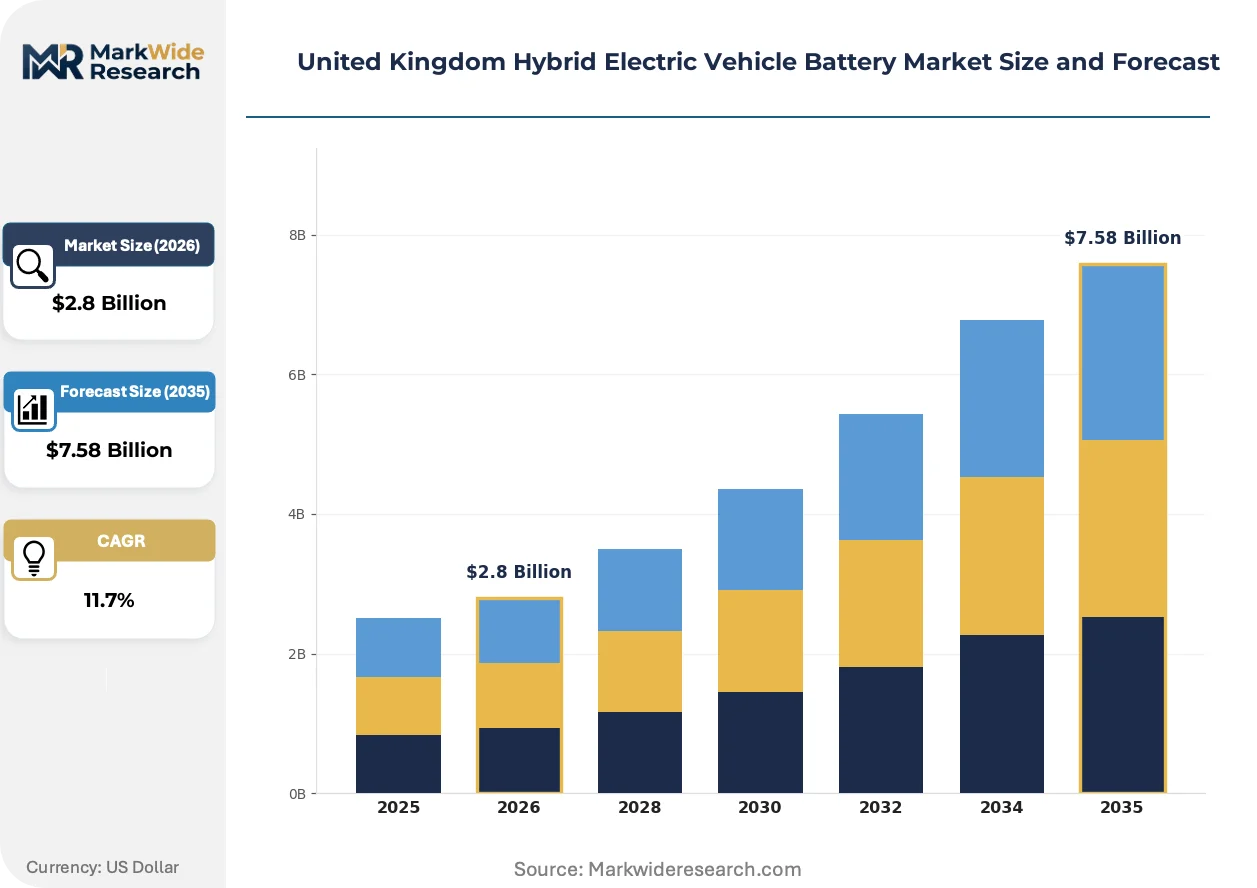
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state Vehicle Type: SUVs, Sedans, Hatchbacks, Trucks End User: Fleet Operators, Individual Consumers, Ride-sharing Companies, Public Transport Charging Technology: Fast Charging, Normal Charging, Wireless Charging, Regenerative Braking |
| Companies Covered | BYD Company, Contemporary Amperex Technology, LG Energy Solution, Panasonic Corporation, Samsung SDI, SK Innovation, Toshiba Corporation, GS Yuasa Corporation, EnerSys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Hybrid Electric Vehicle Battery Market Trends and Innovations
Cell chemistry standardization and pack architecture simplification are compressing supplier qualification cycles while British OEMs accelerate platform consolidation.
Lithium iron phosphate chemistry is consolidating its position in the 48V mild-hybrid segment where thermal stability outweighs energy density requirements. British van manufacturers including Vauxhall and Ford Transit assemblers are adopting LFP for stop-start duty cycles. This chemistry shift is consolidating procurement around cylindrical formats versus prismatic alternatives, reducing pack design complexity for UK integrators.
The UK's Battery Strategy and Automotive Transformation Fund are tightening domestic content thresholds for OEM incentive eligibility. The Office for Product Safety and Standards is accelerating UKCA marking parallel review processes for cell variants already CE-certified in the EU. British pack assemblers serving Stellantis and Nissan Sunderland operations are restructuring supply contracts to meet 40 percent UK value-add requirements by 2027.
Fleet operators are consolidating procurement decisions at the national level rather than regional depot discretion. DPD UK and Evri have established central electrification teams that specify battery performance tiers across their entire van and truck populations. This buyer concentration is most visible in England's logistics corridors where multi-year service contracts now bundle vehicles, charging infrastructure, and battery warranty into single-source arrangements.
United Kingdom Hybrid Electric Vehicle Battery Market Segmentation
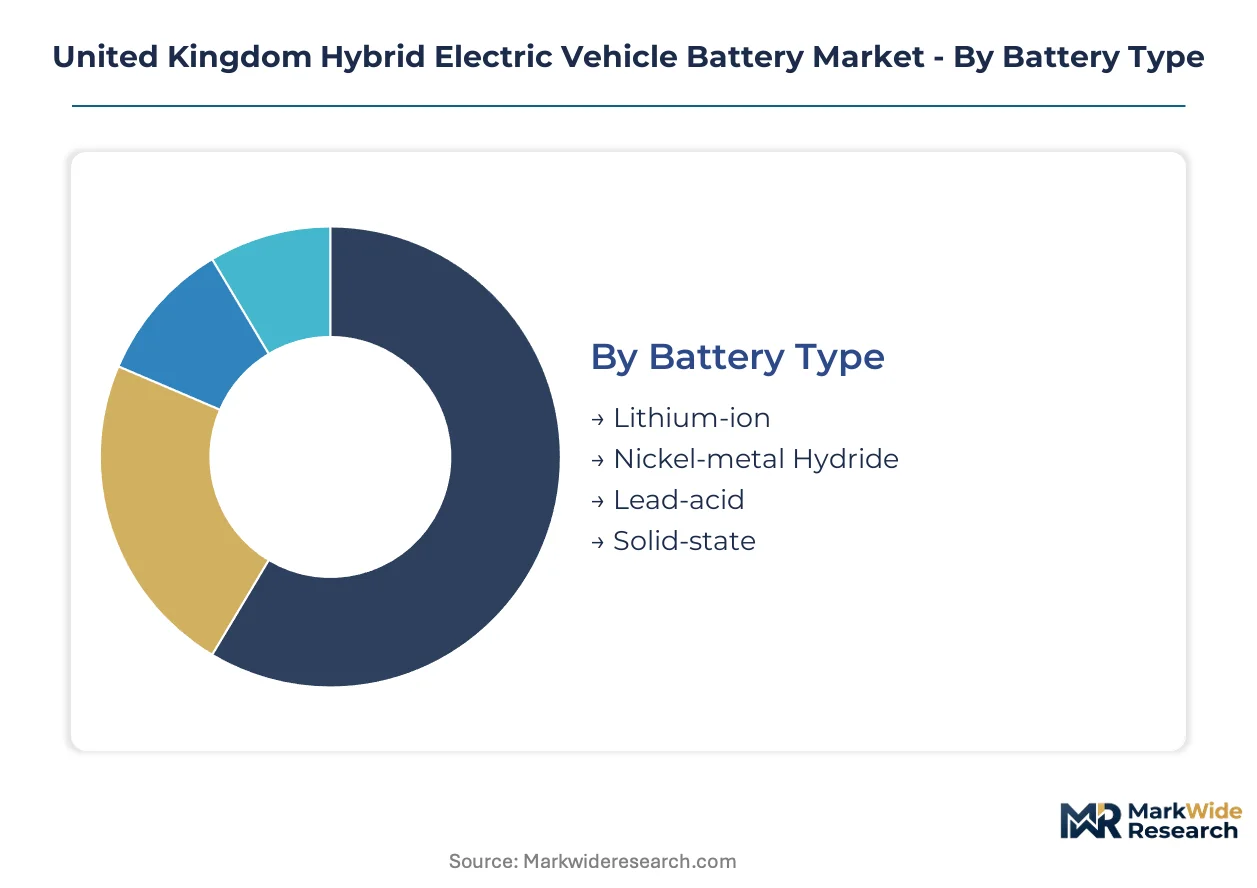
Segmentation in the United Kingdom Hybrid Electric Vehicle Battery Market reveals how procurement patterns diverge across chemistry formats, vehicle architectures, and operational duty cycles. Fleet operators upgrade packs on compressed timelines compared with individual owners, creating distinct replacement-cycle economics for suppliers.
Battery Type:
Upgrade cycles vary sharply by chemistry maturity, with newer lithium-ion formats displacing incumbent nickel-metal hydride systems in high-utilization fleets.
- Lithium-ion:Dominant chemistry employing nickel-manganese-cobalt or lithium iron phosphate cathodes with 200-400V nominal architectures. Demand concentrates in England's West Midlands corridor where Jaguar Land Rover and commercial vehicle assemblers source cylindrical and prismatic formats for full-hybrid platforms.
- Nickel-metal Hydride:Mature chemistry utilizing rare-earth metal hydride anodes with proven thermal stability and cycle longevity. Toyota and Honda hybrid models serving London's private-hire market retain this format where pack mass tolerance allows cost-sensitive procurement.
- Lead-acid:12V auxiliary systems supporting low-voltage electrical loads and redundancy functions in mild-hybrid stop-start architectures.
- Solid-state:Emerging ceramic-electrolyte designs targeting higher energy density with reduced thermal management overhead for next-generation platforms.
Lithium-ion sits at the top of the volume ranking, with solid-state climbing the fastest as OEM qualification programs advance.
Vehicle Type:
Application-specific duty cycles drive divergent pack specifications, with commercial operators prioritizing cycle life over energy density.
- SUVs:Large-format packs with 60-80kWh gross capacity enabling all-electric range extension in premium hybrid architectures. Birmingham and Solihull assembly plants anchor procurement for Land Rover Defender and Discovery hybrid variants.
- Sedans:Mid-size 15-25kWh packs balancing trunk space retention with electric-only urban operation. London's executive chauffeur services drive replacement demand for BMW and Mercedes plug-in hybrid sedans.
- Hatchbacks:Compact 1-2kWh mild-hybrid systems supporting 48V belt-integrated starter-generator architectures. Vauxhall Corsa and Ford Fiesta production at Ellesmere Port concentrates procurement.
- Trucks:Heavy-duty 100-200kWh parallel hybrid packs for last-mile delivery and urban freight. DPD UK and Royal Mail specify these for Birmingham Clean Air Zone compliance.
SUVs command the largest procurement volumes, with trucks expanding most quickly as logistics electrification accelerates.
End User:
Customer concentration patterns determine contract structures, with centralized fleet procurement displacing fragmented retail channels.
- Fleet Operators:National procurement teams at DPD UK, Evri, and Amazon Logistics specify performance tiers across van and truck populations. Multi-year service contracts bundle vehicles, charging infrastructure, and battery warranty into single-source arrangements with volume guarantees.
- Individual Consumers:Retail purchasers of Toyota, Hyundai, and Kia hybrid models through franchised dealer networks. Replacement demand emerges post-warranty as vehicles age in suburban and rural postcode clusters.
- Ride-sharing Companies:Uber and Bolt drivers operating Toyota Prius and Hyundai Ioniq hybrids in London, Manchester, and Birmingham. High daily mileage compresses pack degradation timelines versus private ownership.
- Public Transport:Municipal bus operators in Glasgow, Edinburgh, and London specifying hybrid powertrains for low-emission zone compliance. Transport for London's bus electrification program anchors demand.
Fleet operators dominate current procurement, with public transport gaining share fastest as municipal decarbonization targets tighten.
Charging Technology:
Infrastructure integration requirements shape pack thermal management specifications across operational environments.
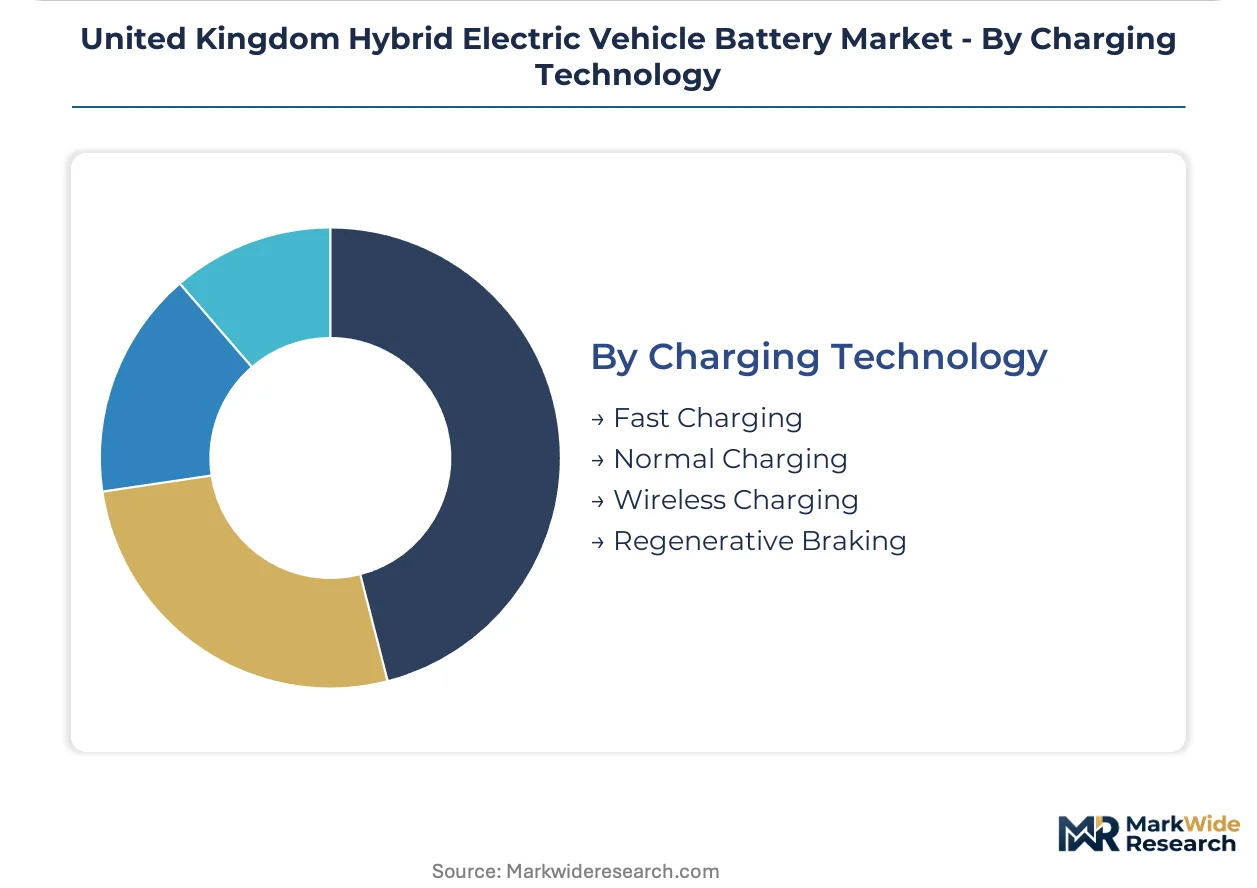
- Fast Charging:DC rapid replenishment at 50-150kW requiring advanced cell cooling and state-of-charge balancing. Motorway service areas and urban hub locations concentrate deployment for intercity hybrid operation.
- Normal Charging:AC overnight replenishment at 3-7kW through domestic wallboxes and workplace installations. Suburban residential patterns dominate this channel.
- Wireless Charging:Inductive pad systems for taxi rank and depot applications eliminating connector wear. Milton Keynes and Nottingham trial deployments inform specification development.
- Regenerative Braking:Kinetic energy recovery during deceleration events, mandatory for all hybrid architectures and determining power electronics integration requirements.
Normal charging retains the highest installation base, with fast charging expanding most quickly as fleet depot infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's West Midlands automotive manufacturing corridor concentrates the majority of UK hybrid battery demand, with Jaguar Land Rover, Aston Martin, and commercial vehicle assemblers driving procurement within a 50-mile radius of Birmingham and Solihull.
London and the Southeast
Transport for London's bus electrification program and the Ultra Low Emission Zone penalize diesel van operations, pushing DPD UK, Royal Mail, and Amazon Logistics toward hybrid delivery fleet procurement. The Environment Agency enforces end-of-life cell recycling through the Waste Batteries and Accumulators Regulations. Milton Keynes hosts wireless charging trial deployments for taxi rank and depot applications.
Midlands
England's automotive production cluster concentrates cell demand from Jaguar Land Rover, Aston Martin, and commercial vehicle assemblers within a 50-mile radius. The Office for Product Safety and Standards enforces battery safety certification under the Electrical Equipment (Safety) Regulations. Birmingham Clean Air Zone compliance drives heavy-duty hybrid pack specification for last-mile delivery operators.
Scotland
Aberdeen and Glasgow's offshore wind surplus offers below-grid power for cell formation and aging facilities, cutting energy opex by 30-40 percent versus Midlands sites. Scottish government renewable integration policies support domestic manufacturing cost advantages. Glasgow municipal bus operators specify hybrid powertrains for low-emission zone compliance targets.
North England
Nissan Sunderland operations restructure supply contracts to meet 40 percent UK value-add requirements by 2027 under the Battery Strategy. The Advanced Propulsion Centre channels government grants toward domestic gigafactory qualification. Ellesmere Port concentrates mild-hybrid system production for Vauxhall Corsa and Ford Fiesta assembly.
Wales
Retired hybrid packs from London's black cab fleet provide 60-70 percent residual capacity for commercial building peak-shaving applications in Cardiff and Swansea second-life stationary storage projects. Welsh government circular economy initiatives support battery recycling infrastructure development. Newport hosts emerging pack integrators serving Stellantis platform requirements.
United Kingdom Hybrid Electric Vehicle Battery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue qualification acceleration under post-Brexit UKCA marking divergence. The market exhibits tiered concentration around Asian cell suppliers, with British pack assemblers dependent on multi-source procurement strategies. Three archetypes dominate: cylindrical format specialists, prismatic scale operators, and LFP chemistry leaders. Capacity expansion and strategic partnerships constitute the primary competitive vectors as OEMs consolidate platform architectures.
Among Asian-headquartered suppliers, LG Energy Solution, Panasonic Corporation, and Samsung SDI exemplify distinct positioning archetypes. LG Energy Solution anchors its UK position through established European supply infrastructure. Panasonic Corporation represents cylindrical cell specialization for hybrid architectures. Samsung SDI occupies the prismatic format scale segment suited to European OEM platforms. These three entities collectively illustrate how chemistry and format differentiation shapes supplier qualification pathways for British automakers.
| Leading Market Players |
|---|
| BYD Company |
| Contemporary Amperex Technology |
| LG Energy Solution |
| Panasonic Corporation |
| Samsung SDI |
| SK Innovation |
| Toshiba Corporation |
| GS Yuasa Corporation |
| EnerSys |
| Others |
Pricing and Supply Chain Analysis
Lithium iron phosphate chemistry migration toward 48V mild-hybrid architectures is compressing pack cost structures while concentrating procurement around cylindrical cell formats that favor high-volume Asian producers. This chemistry-format convergence simultaneously reduces UK integrator design complexity and tightens supplier pricing power around established South Korean and Chinese manufacturing bases.
Pricing Analysis
Input-cost pass-through from lithium carbonate cathode-active materials dominates pack pricing volatility for UK-based assemblers lacking long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates OEM-qualified cells with UKCA marking from CE-only equivalents and uncertified gray-market imports. Cost compression in standard-tier cylindrical formats is intensifying because South Korean suppliers are expanding European formation capacity. Fleet operators at DPD UK and Amazon Logistics exhibit lowest price sensitivity due to bundled service contracts, while independent repair channels serving retail hybrid owners face acute margin pressure.
Supply Chain Analysis
Cathode-active material supply rests on Chinese lithium carbonate refining, South Korean nickel-manganese-cobalt precursor synthesis, and Japanese specialty chemical additives for electrolyte formulations. UK pack assemblers draw from prismatic cells produced in South Korea, cylindrical formats from Japan, and LFP chemistries increasingly sourced through Chinese tier-one suppliers. Single-source vulnerability concentrates around South Korean cell imports exceeding eighty percent of UK-qualified volume. Distribution runs through Midlands-based pack integrators serving Stellantis and Nissan Sunderland, with secondary channels via independent aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Hybrid Electric Vehicle Battery Market functions as a geographic-arbitrage play where Scottish offshore wind power cuts cell formation energy costs by thirty-to-forty percent versus Midlands manufacturing sites, while UKCA marking divergence from CE standards creates six-month qualification delays that favor early domestic entrants.
For Market Incumbents: Anchor European supply infrastructure through established relationships with LG Energy Solution and Samsung SDI while accelerating UKCA parallel review investments to compress qualification timelines. Defend against emerging LFP specialists by securing cylindrical format capacity reservations and deepening backward integration into cell formation equipment. Prioritize certification investment in the 48V mild-hybrid segment where Vauxhall and Ford Transit procurement is consolidating. For New Entrants and Emerging Players: Enter via second-life stationary storage applications in Wales and Scotland where retired London black cab packs provide sixty-to-seventy percent residual capacity for commercial building peak-shaving. Target the Scottish manufacturing corridor where Aberdeen and Glasgow's offshore wind surplus enables below-grid power for cell aging facilities. Pursue a go-to-market angle through Advanced Propulsion Centre grant qualification for domestic gigafactory development serving the 48V segment. For Investors and Strategic Acquirers: Roll-up economics work for UK-based pack integrators because OEM content thresholds require forty percent domestic value-add by 2027, forcing restructuring of existing supply contracts. Long-term viability over a five-to-ten year window hinges on qualification speed for UKCA marking divergence. Acquire mid-cap specialists with established Stellantis or Nissan platform relationships. Watch the Office for Product Safety and Standards acceleration of parallel review processes as the inflection signal for new chemistry introduction timelines.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Marking Parallel Review Investment | Office for Product Safety and Standards acceleration cuts qualification delays for European cell entrants. |
| Scottish Formation Facility Development | Aberdeen offshore wind surplus reduces energy opex for cell aging versus Midlands competitors. |
| Second-Life Stationary Storage Partnership | Welsh circular economy initiatives support retired hybrid pack redeployment for commercial peak-shaving. |
| Cylindrical Format Capacity Reservation | Panasonic specialization in hybrid architectures secures supply for Vauxhall and Ford mild-hybrid programs. |
| Fleet Operator Service Contract Bundling | DPD UK and Evri central procurement teams specify battery performance tiers across national van populations. |
Research Methodology
Multiple input streams — regulatory filing analysis, customs trade data, and OEM procurement disclosure review — were reconciled against primary fieldwork with battery pack integrators, fleet electrification managers, and electrochemical engineering specialists. Secondary validation incorporated UK Office for Product Safety and Standards certification databases, Environment Agency waste battery registration records, and Advanced Propulsion Centre grant award disclosures. Bottom-up cell demand estimates from vehicle production databases were cross-checked against top-down market sizing from trade flow analysis.
Historical volume trajectories were cross-referenced against expert panel inputs from tier-one supplier strategy directors and OEM platform engineering leads. Segmentation modeling across battery chemistry, vehicle architecture, propulsion system voltage, and end-user procurement channel informed volume allocation. CAGRs were derived from regression analysis of qualified cell import volumes against fleet electrification timelines and clean air zone enforcement schedules. Forecast inputs incorporated West Midlands manufacturing corridor capacity expansion announcements and Scottish renewable integration policy developments.
Inputs from UK government procurement databases and OEM supplier qualification records were available through the study window; gaps in private fleet operator contract terms introduce uncertainty bands around replacement-cycle timing assumptions. Forecasts reflect documented assumptions regarding UKCA marking divergence resolution and lithium carbonate price stabilization mechanisms. Material deviation in Office for Product Safety and Standards review acceleration or Scottish offshore wind grid connection timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
EV Thermal Management System Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Electric Shuttle Market