
 UK Electric Vehicle Market | 2026-2036
UK Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
UK Electric Vehicle Market Outlook
Market Context
A capital-intensity divergence between established automakers and newer entrants is rotating competitive dynamics across the UK Electric Vehicle Market. Tesla leverages its proprietary Supercharger network and vertical integration to sustain pricing power in premium segments. BMW Group anchors its position through dedicated EV architectures and in-house battery cell competence. Volkswagen Group competes via platform standardization across multiple brands, extending manufacturing scale advantages that smaller rivals struggle to match.
Technical and Segment Structure
An electric vehicle converts stored electrical energy from rechargeable battery packs into mechanical traction through one or more electric motors, eliminating tailpipe emissions and enabling regenerative braking recovery. The primary commercial purpose centers on decarbonizing road transport while reducing lifetime operating costs through lower energy and maintenance expenditure. Battery technology segments show lithium-ion dominating current production volumes while solid-state chemistries attract the fastest development investment due to energy density and safety advantages. Vehicle type demand tilts toward SUVs and hatchbacks as British consumers prioritize cabin space and practicality, with fleet operators concentrating procurement on sedans for service vehicle standardization.
Regulatory Environment
The UK's Zero Emission Vehicle mandate enforced by the Department for Transport shapes manufacturer compliance obligations and sales mix requirements, while Ofgem regulates grid connection standards and pricing frameworks for charging infrastructure deployment. The Office for Product Safety and Standards oversees battery certification and end-of-life recycling protocols, creating compliance cost layers that favor larger producers with dedicated regulatory teams. Stakeholders must monitor how rapidly tightening CO2 fleet averages interact with consumer affordability constraints and charging network readiness across northern English regions and Welsh corridors where infrastructure lags the South East.
Market Dynamics
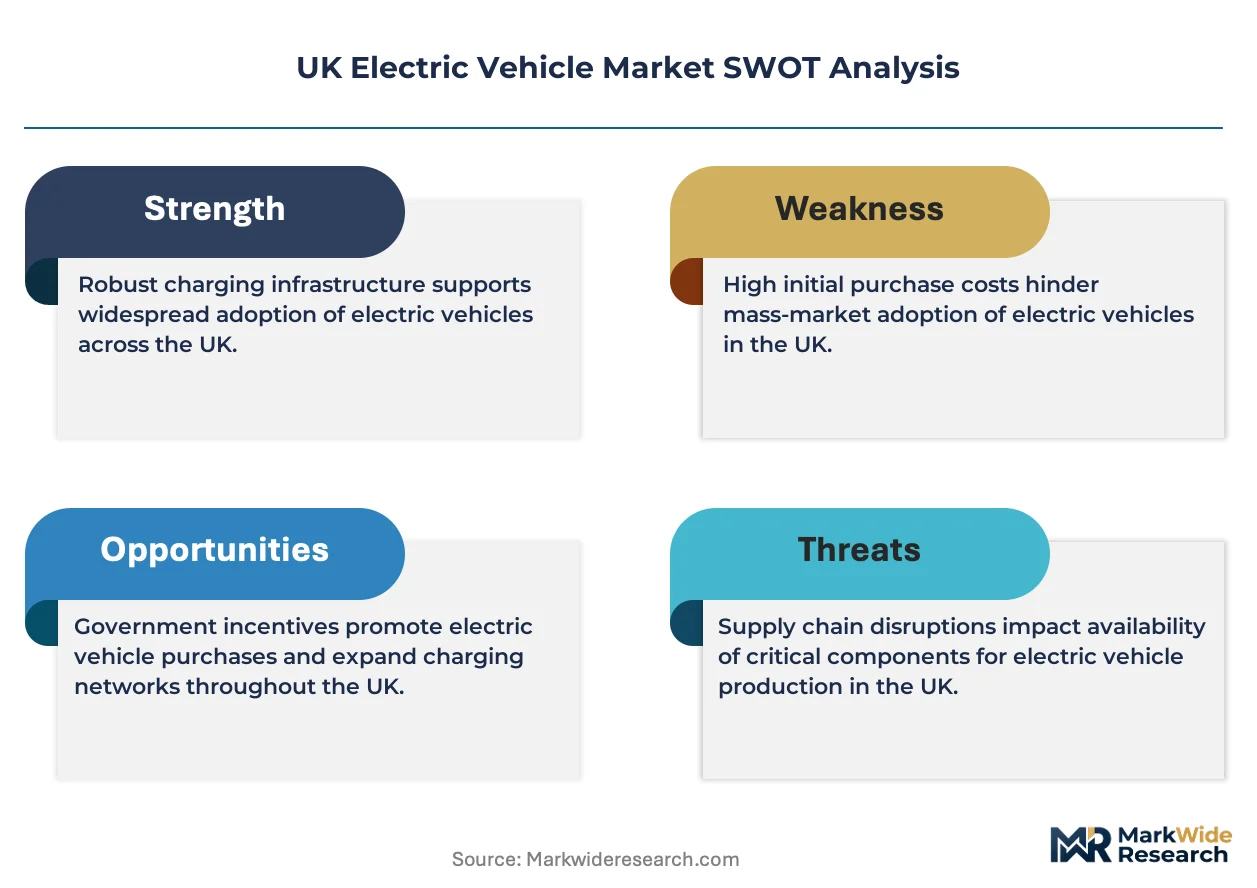
The UK's Zero Emission Vehicle mandate is compressing manufacturer compliance timelines while charging infrastructure deployment lags in northern regions, creating a structural tension between regulatory obligation and operational readiness.
Growth Catalysts
- Clean Air Zone penalties:London's Ultra Low Emission Zone and Birmingham's CAZ impose daily charges on diesel vehicles, accelerating fleet electrification decisions among logistics operators.
- Battery energy density gains:Lithium-nickel-manganese-cobalt chemistries now deliver ranges exceeding 300 miles, eliminating range anxiety for inter-urban commercial routes.
- Fleet standardization mandates:Large service operators including Royal Mail and BT Group are consolidating procurement around battery electric vans for operational uniformity.
Market Restraints
- Lithium supply concentration:Processing capacity concentrates in China and Chile, exposing UK manufacturers to raw material volatility and geopolitical friction.
- Grid connection queuing:Ofgem's connection approval timelines for rapid charging hubs extend 18-24 months in constrained distribution network areas.
- Residual value uncertainty:Fleet buyers hesitate on battery degradation rates and second-hand market depth for commercial electric vehicles.
Strategic Opportunities
- Welsh corridor electrification:The A55 and M4 corridors into Wales show minimal fast-charging coverage, creating first-mover advantages for infrastructure deployers.
- V2G integration:Vehicle-to-grid technology convergence with domestic solar installations opens revenue stacking for fleet operators with depot-based charging.
- Workplace charging scheme expansion:The Department for Transport's WCS grant structure is extending eligibility to smaller enterprises previously excluded from fleet incentives.
Industry Challenges
- High-voltage technician scarcity:The Institute of the Motor Industry reports insufficient qualified engineers for battery system diagnostics and repair across UK service networks.
- Multi-standard charging interoperability:CCS, CHAdeMO, and Tesla NACS connector fragmentation forces fleet operators to specify mixed hardware or accept access limitations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Electric Vehicle Market |
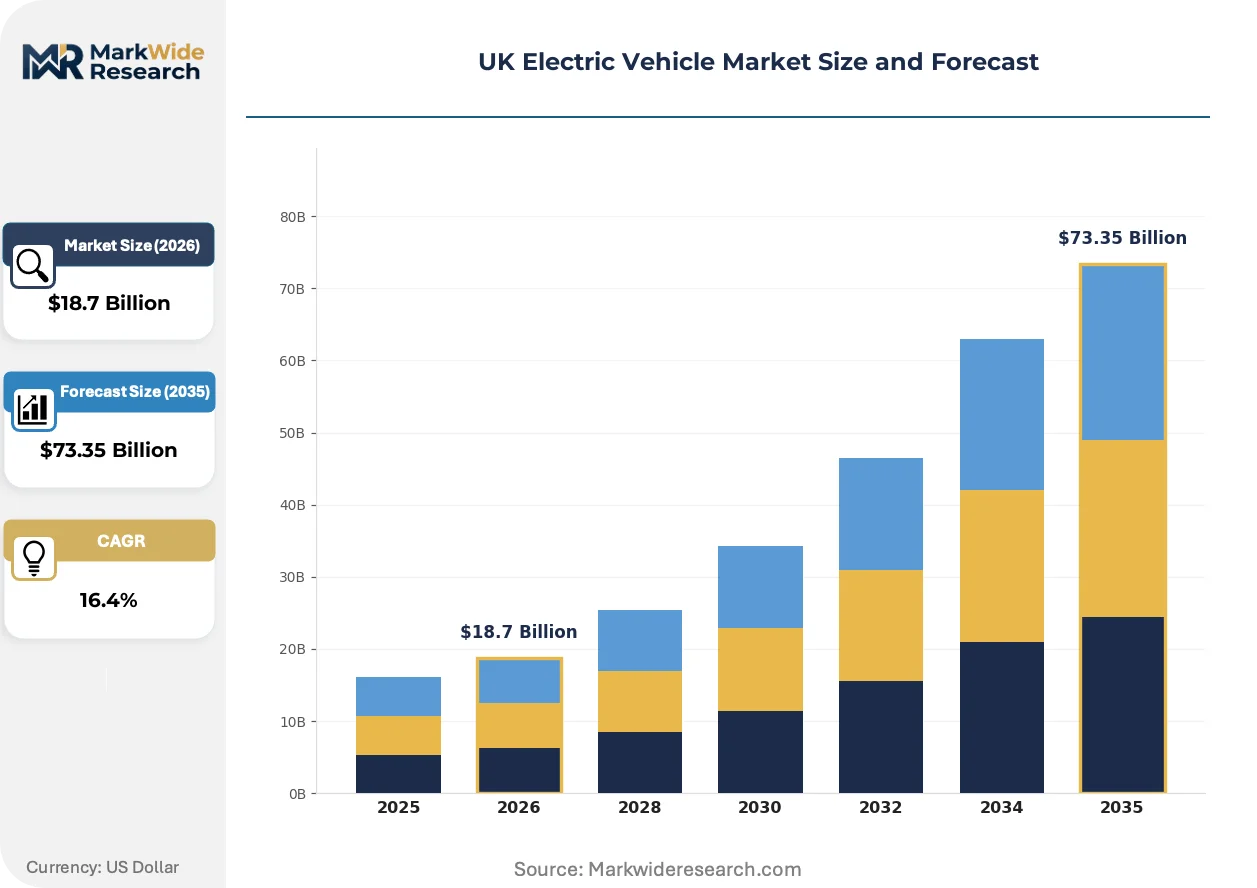
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid Charging Infrastructure: Fast Charging, Ultra-Fast Charging, Home Charging, Workplace Charging Customer Segment: Private Users, Fleet Operators, Government, Car Rentals |
| Companies Covered | Tesla, BYD, Volkswagen Group, BMW Group, Hyundai Motor Company, Nissan Motor Company, Mercedes-Benz Group, Kia Corporation, Stellantis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Electric Vehicle Market Strategic Shifts
Battery chemistry evolution and charging infrastructure densification are restructuring competitive advantage around energy management capabilities rather than traditional manufacturing scale.
Solid-state battery architectures are supplanting conventional liquid electrolyte designs in development pipelines. BMW Group and Nissan have committed production timelines for sulfide-based cells promising 40% energy density improvements. This transition is compressing incumbent lithium-ion supply contracts and forcing cell manufacturers to accelerate dry-electrode coating investments.
Ofgem's Targeted Charging Review is reshaping network access pricing for rapid charging operators. The new residual charging framework shifts cost recovery toward fixed capacity charges, disadvantaging low-utilization sites. Northern England operators with seasonal demand patterns are responding by co-locating battery storage to flatten peak draw and reduce capacity obligations.
Fleet leasing structures are fragmenting as operators reject traditional closed-end contracts with uncertain residual values. Salary sacrifice schemes for company car drivers are expanding fastest in Greater London and the South East, where benefit-in-kind tax advantages compound with congestion charge savings. This channel shift pressures manufacturers to develop guaranteed buyback programs and battery state-of-health certification standards.
UK Electric Vehicle Market Segmentation
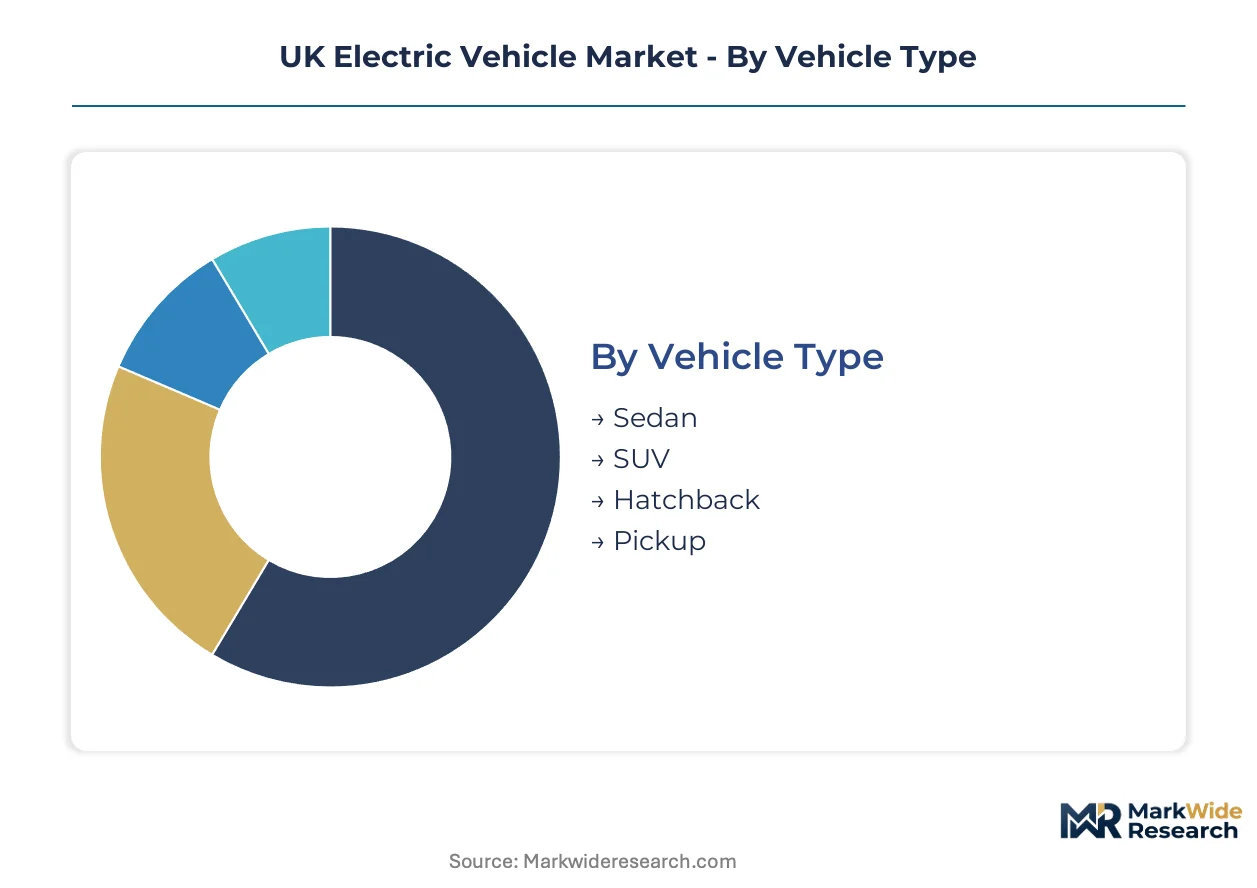
Segmentation in the UK Electric Vehicle Market reveals divergent channel economics across vehicle types and customer profiles. Fleet procurement concentrates on standardized van formats through direct manufacturer agreements, while private demand fragments across retail channels with heavy dependence on salary sacrifice schemes. Understanding these flow patterns is essential for aligning production allocation with margin capture.
Vehicle Type:
Fleet leasing channels favor sedans and hatchbacks for service vehicle standardization, while private retail channels show stronger SUV attachment through PCP finance structures.
- SUV:Higher ground clearance and cabin versatility dominate family purchasing decisions in Greater London commuter belts. Demand clusters among dual-income households accessing salary sacrifice schemes, with Range Rover and BMW X-series variants commanding premium positioning.
- Hatchback:Compact dimensions and urban maneuverability suit dense metropolitan parking constraints. Concentrated demand in Birmingham and Manchester clean air zones where daily charges on diesel alternatives accelerate switching decisions.
- Sedan:Fleet operators including taxi services and corporate transport standardize around three-box configurations for passenger capacity and professional image.
- Pickup:Commercial contractors in construction and agriculture drive limited but growing demand for battery electric load-bed configurations.
By volume, hatchbacks lead through fleet standardization. By growth pace, SUVs are expanding most quickly as PCP affordability improves.
Battery Technology:
Cost tier stratification separates premium solid-state development programs from commoditized lithium-ion volume production serving mass-market segments.
- Lithium-Ion:Lithium-nickel-manganese-cobalt cells currently dominate installed capacity with energy densities exceeding 300 miles range. Manufacturing scale concentrates in Asian cell plants, exposing UK assemblers to shipping cost volatility and currency fluctuation.
- Solid-State:Sulfide-based electrolyte architectures promise 40% energy density improvements and enhanced thermal stability. BMW and Nissan have committed production timelines, positioning these cells for premium SUV and luxury sedan applications.
- Nickel-Metal Hydride:Legacy hybrid applications retain niche presence in commercial vehicle mild-hybrid configurations.
- Lead-Acid:Auxiliary power systems and low-speed urban delivery vehicles sustain minimal residual demand.
By installed base, lithium-ion dominates. By investment trajectory, solid-state is gaining share fastest through OEM R&D commitments.
Charging Infrastructure:
Customer type determines infrastructure preference — fleet operators prioritize depot-based workplace charging while private users split between home installation and public rapid access.
- Home Charging:7kW wallbox installations dominate private residential uptake, particularly in owner-occupied suburban stock across the South East. The Office for Zero Emission Vehicles grant scheme has accelerated penetration, though rental property access remains constrained.
- Fast Charging:50-150kW DC hubs serve inter-urban corridor traffic on the M1, M6 and M40 motorway networks. Grid connection queuing through Ofgem approval processes extends deployment timelines 18-24 months in constrained distribution areas.
- Ultra-Fast Charging:350kW capable sites target premium SUV and executive sedan segments with battery capacities supporting rapid energy replenishment.
- Workplace Charging:Depot-based fleet installations and employer-subsidized staff parking infrastructure concentrate in logistics hubs and corporate campuses.
By connection volume, home charging leads. By capital deployment, ultra-fast charging shows the steepest expansion trajectory as motorway service area operators compete for corridor positioning.
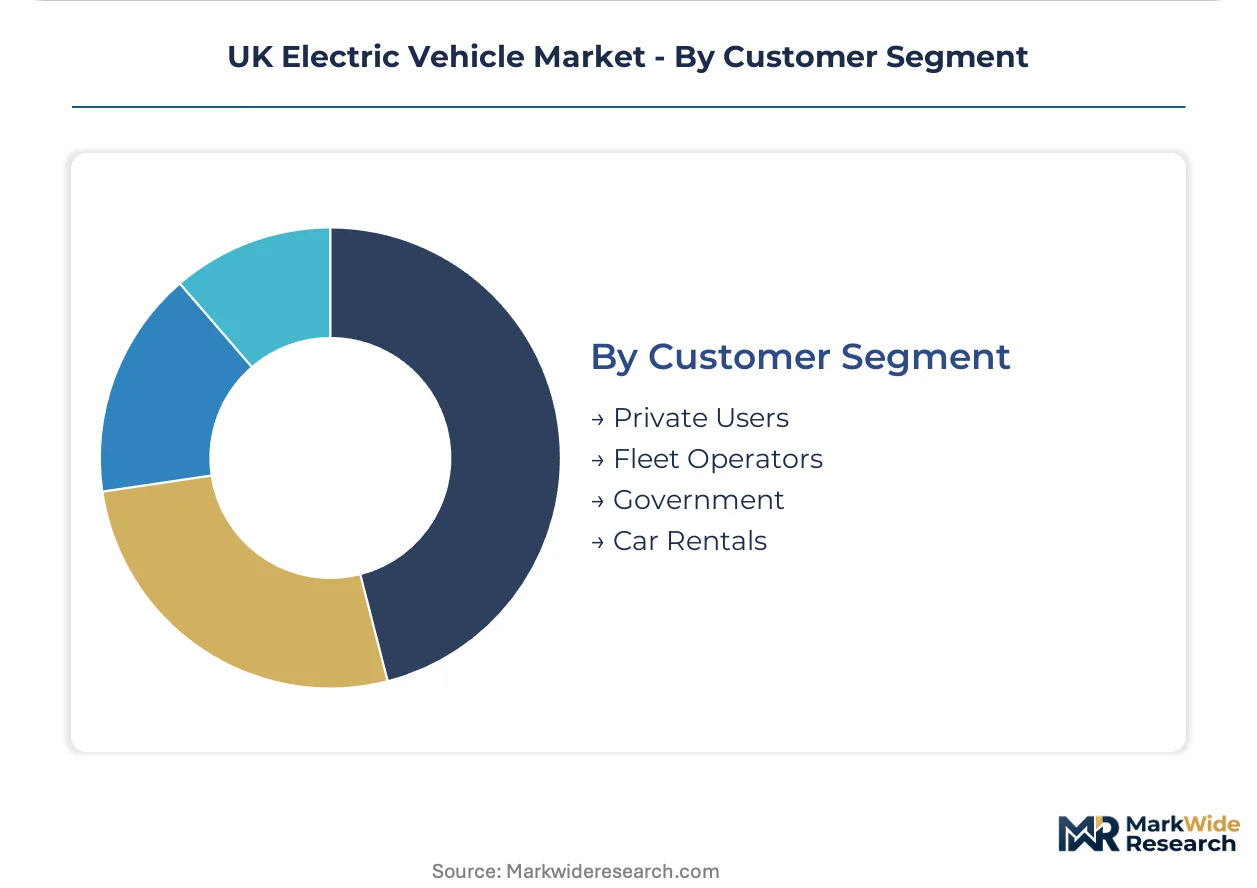
Customer Segment:
Procurement patterns diverge sharply — fleet operators negotiate multi-year supply agreements with guaranteed residual values, while private demand flows through dealer finance and emerging subscription channels.
- Fleet Operators:Royal Mail, BT Group and Amazon Logistics consolidate procurement around battery electric vans for operational uniformity. Standardized maintenance protocols and centralized charging infrastructure support total cost of ownership advantages over diesel alternatives.
- Private Users:Salary sacrifice schemes in Greater London and the South East combine benefit-in-kind tax advantages with congestion charge savings, compressing effective monthly costs below equivalent ICE PCP structures.
- Government:Central and local authority procurement mandates prioritize UK-assembled vehicles where available, supporting domestic manufacturing employment.
- Car Rentals:Enterprise and Hertz are rebuilding post-pandemic fleets with electric options, though residual value uncertainty limits commitment scale.
By vehicle volume, fleet operators lead. By policy sensitivity, government procurement is climbing the fastest as net-zero targets tighten public sector compliance obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London commands pricing premiums 15-20% above northern English markets, while Scottish fleet procurement concentrates around Aberdeen's energy sector transition. This asymmetry shapes manufacturer allocation decisions and charging infrastructure capital deployment.
Greater London and South East
The Ultra Low Emission Zone and expanding clean air penalties drive fleet electrification among logistics operators and private hire services. The Department for Transport's Zero Emission Vehicle mandate tightens manufacturer compliance obligations fastest in this corridor. Charging density in the M25 orbital supports premium SUV and executive sedan demand through salary sacrifice schemes.
Midlands
Birmingham's Clean Air Zone imposes daily charges on diesel vans, accelerating battery electric adoption among last-mile delivery contractors. Ofgem regulates grid connection standards for rapid charging hubs extending into Coventry and Leicester manufacturing belts. The region's automotive heritage clusters battery assembly investments around Warwickshire and Staffordshire.
North England
Grid connection queuing extends 18-24 months for rapid charging deployment across Manchester and Leeds distribution networks. The Department for Transport's Workplace Charging Scheme grant structure is extending eligibility to smaller enterprises previously excluded from fleet incentives. Yorkshire's logistics corridors show infrastructure gaps that create first-mover positioning for depot-based charging operators.
Scotland
Aberdeen's energy sector transition concentrates fleet procurement around battery electric vans for service vehicle standardization. Transport Scotland's funding programs supplement UK-wide incentives with additional grants for rural charging infrastructure. Edinburgh and Glasgow clean air zone planning accelerates switching decisions among taxi and private hire operators.
Wales
The A55 and M4 corridors into Wales show minimal fast-charging coverage, creating structural barriers to inter-urban battery electric adoption. The Welsh Government's transport decarbonization targets outpace current infrastructure deployment across Cardiff and Swansea metropolitan areas. Fleet operators in construction and agriculture drive limited but growing demand for battery electric commercial configurations.
UK Electric Vehicle Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with proprietary charging networks and vertical manufacturing control separating premium positioning from volume scale. The market structure consolidates around three tiers: integrated technology owners, platform-standardized multibrand groups, and emerging cost-optimized entrants. Strategic archetypes include the charging-network-integrated premium player, the architecture-dedicated European incumbent, and the battery-cell-competent Asian challenger. Dominant competitive moves center on dedicated EV platform development and strategic partnerships for raw material security.
Among integrated technology owners, Tesla anchors the premium tier through proprietary Supercharger network access and in-house battery cell production. Volkswagen Group occupies a position exemplifying platform standardization across multiple brands, extending manufacturing scale that smaller rivals struggle to match. BYD represents the emerging cost-optimized archetype, with battery manufacturing integration supporting aggressive fleet pricing.
| Leading Market Players |
|---|
| Tesla |
| BYD |
| Volkswagen Group |
| BMW Group |
| Hyundai Motor Company |
| Nissan Motor Company |
| Mercedes-Benz Group |
| Kia Corporation |
| Stellantis |
| Others |
Value Chain & Pricing Dynamics
Ofgem's Targeted Charging Review gates both supplier qualification for rapid charging operators and price differentiation between high-utilization motorway hubs and low-utilization rural sites. The residual charging framework compresses margins for seasonal demand patterns while rewarding battery-buffered installations that flatten peak draw.
Pricing Analysis
The customization-premium spread in fleet procurement runs wide: configured-to-order van specifications with depot charging integration command substantial premiums over standard retail configurations. Three-tier pricing structure across premium, standard, and economy levels separates Tesla's Supercharger-access bundled pricing from volume hatchback PCP structures and entry-level urban runabouts. Cost compression in the standard tier is intensifying because BYD's battery manufacturing integration enables aggressive fleet pricing. Fleet operators show lowest price sensitivity due to total cost of ownership framing, while private retail buyers in northern England exhibit highest sensitivity where charging infrastructure gaps persist.
Supply Chain Analysis
China and South Korea anchor cathode active material and cell manufacturing, with Japan retaining separator and electrolyte specialization. UK assemblers draw from Asian cell plants for lithium-nickel-manganese-cobalt cells, exposing production schedules to shipping cost volatility and currency fluctuation. Single-source vulnerability concentrates in Chinese lithium hydroxide processing, with limited alternative qualification timelines. Distribution runs through Tilbury and Southampton port clusters into Midlands assembly plants, with just-in-sequence delivery to OEM final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Electric Vehicle Market sits at a platform-economics inflection where charging network interoperability determines manufacturer competitive position. The convergence of CCS, NACS, and legacy connector standards creates ecosystem lock-in risks for fleet operators standardizing procurement.
For Market Incumbents: Fortify proprietary charging network advantages through accelerated NACS adoption timelines before standardization mandates erode differentiation. BMW Group and Volkswagen Group should deepen backward integration into European battery cell capacity to reduce exposure to Asian supply concentration. The emerging threat of BYD's cost-optimized fleet pricing pressures margin structures in commercial van segments.
For New Entrants and Emerging Players: The Office for Zero Emission Vehicles' Workplace Charging Scheme fast-track for smaller enterprises opens white-space penetration below fleet operator procurement thresholds. Welsh corridor infrastructure gaps and Scottish rural charging deficits represent the most penetrable geographies. A depot-based charging hardware and software bundling angle bypasses direct vehicle manufacturing capital intensity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed charging infrastructure operators holding constrained grid connection approvals in northern distribution networks. Long-term viability hinges on vehicle-to-grid revenue stacking and energy management software capabilities. The signal to watch is Ofgem's residual charging implementation timeline and its differential impact on utilization economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with South Korean cell manufacturers reduce exposure to lithium price volatility. |
| Charging Infrastructure Partnership | Co-location with motorway service area operators secures corridor positioning ahead of grid connection queuing. |
| Software-Defined Vehicle Investment | Over-the-air capability and energy management algorithms differentiate premium SUV positioning. |
| Platform Standardization | Multi-brand EV architectures extend manufacturing scale across Volkswagen Group volume tiers. |
| Geographic Manufacturing Footprint | UK battery assembly investments around Warwickshire satisfy government procurement localization mandates. |
Study Parameters
Cross-validation between fleet operator procurement directors and charging infrastructure developers anchors the qualitative findings on deployment constraints. Primary interviews with OEM platform engineers, Ofgem regulatory leads, and Tier 1 supplier procurement teams combined with secondary validation from Department for Transport policy disclosures, Ofgem connection data, and vehicle registration databases. Bottom-up fleet adoption modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis around battery cost decline trajectories and charging infrastructure buildout pace shapes the analytical framework across the projection horizon. Segmentation dimensions include vehicle class, propulsion architecture, battery chemistry tier, and regional infrastructure readiness. CAGRs derive from logistic diffusion curves fitted to fleet replacement cycles and consumer adoption patterns. Industry-specific forecast inputs incorporate Zero Emission Vehicle mandate compliance thresholds and Ofgem's Targeted Charging Review implementation.
Decision-makers should treat outputs as directional under base assumptions of continued lithium-ion cost decline and stable grid connection approval timelines; material deviation in raw material geopolitics or regulatory acceleration would warrant model refresh. Specific risk factors include Chinese export restriction scenarios and Welsh infrastructure deployment shortfalls. Recalibration cycles align with material shifts in battery chemistry commercialization and mandate compliance trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Electric Vehicle Rental Market