
 France Automotive High Performance Electric Vehicles Market | 2026-2036
France Automotive High Performance Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive High Performance Electric Vehicles Market Foresight
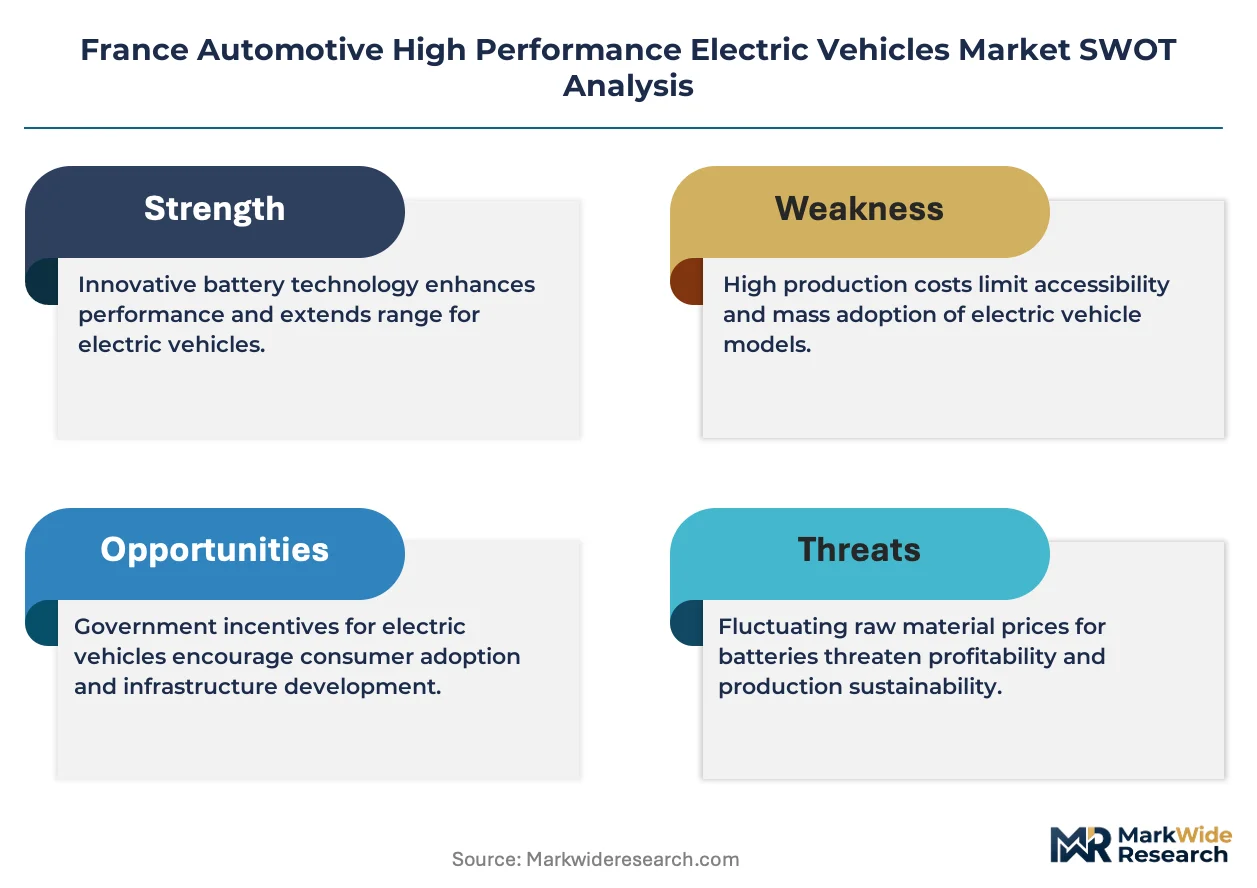
The EU Green Deal is decoupling high-performance EV profitability from legacy combustion-engine scale economics. BMW Group leverages its Munich battery competence center to sustain dual-motor architecture leadership in luxury sedans. Stellantis NV anchors its French manufacturing base through vertical integration into solid-state battery prototyping. Renault Group competes via dedicated performance sub-brand development and motorsport-derived thermal management systems.
France automotive high performance electric vehicles combine dual-motor or solid-state battery architectures with sub-four-second acceleration capability and sustained track-level thermal endurance for premium consumer and motorsport applications. Battery electric configurations dominate installed base while solid-state battery prototypes attract the deepest R&D allocation due to energy density thresholds required by supercar segment buyers. Sports cars and supercars concentrate margin pools through low-volume, high-price positioning, whereas electric SUVs expand addressable reach among high-net-worth individuals seeking dual-purpose daily and leisure mobility.
ANSM oversees occupational safety standards for battery cell manufacturing facilities in France, while EU REACH and RoHS frameworks govern chemical composition and recyclability mandates across the supply chain. The French national automotive regulator enforces type-approval protocols that align with EU AI Act provisions for autonomous performance driving modes. Stakeholders must monitor how DGFT import licensing interacts with EU Battery Regulation origin requirements for cells sourced outside the European Economic Area.
Market Dynamics
The EU Green Deal's fleet emissions targets are forcing powertrain portfolio restructuring among French OEMs, decoupling high-performance EV profitability from legacy combustion-engine scale economics. Battery electric supercars now compete for R&D capital against solid-state prototypes as energy density thresholds become the decisive technical battleground.
Growth Catalysts
- EU Battery Regulation:Origin requirements for cells sourced within the European Economic Area are accelerating localized gigafactory development, strengthening French manufacturing competitiveness.
- Motorsport-derived thermal management:Track-level endurance capabilities developed through Formula E and endurance racing programs are transferring to road-legal supercar architectures.
- Paris and French Riviera charging density:Concentrated high-net-worth purchasing power aligns with premium fast-charging infrastructure deployment, creating natural demand clusters.
Market Restraints
- Lithium and nickel price volatility:Raw material input costs for high-capacity battery cells create margin compression pressures distinct from mass-market EV segments.
- Solid-state battery manufacturing scale:Prototype-to-production yield gaps limit near-term volume expansion for energy-dense architectures required by supercar buyers.
- EU AI Act type-approval protocols:Autonomous performance driving mode certification timelines extend product development cycles beyond traditional supercar refresh rates.
Strategic Opportunities
- Solid-state battery convergence:Electrolyte chemistry advances combined with silicon-anode architectures promise energy density breakthroughs for 1000+ km range supercars.
- Dual-purpose electric SUVs:Daily-leisure mobility positioning expands addressable reach among high-net-worth individuals beyond traditional sports car collectors.
- French national automotive regulator incentives:Type-approval streamlining for low-volume performance manufacturers reduces regulatory entry barriers.
Industry Challenges
- Electrochemistry and thermal engineering talent scarcity:Competition with aerospace and stationary storage sectors constrains hiring pipelines for specialized battery systems engineers.
- Gigafactory capex intensity:Solid-state pilot line investments require capital commitments disproportionate to current supercar production volumes.
- REACH and RoHS supply chain reconfiguration:Chemical composition mandates force supplier base transitions with extended qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive High Performance Electric Vehicles Market |
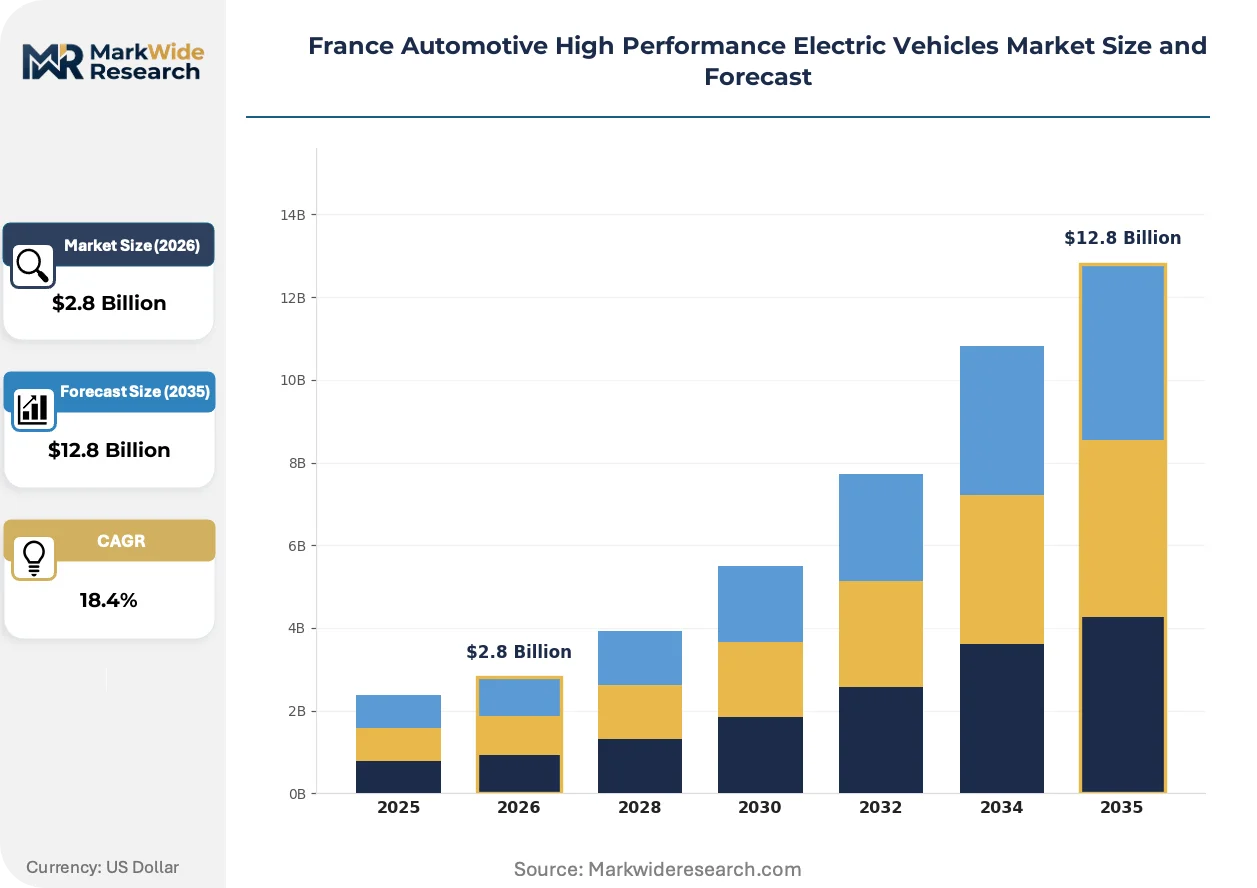
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sports Cars, Luxury Sedans, Electric SUVs, Performance Coupes, Supercars, Roadsters Propulsion Technology: Battery Electric, Hydrogen Fuel Cell, Plug-in Hybrid, Solid-State Battery, Regenerative Braking, Dual Motor End User: Premium Collectors, Motorsport Enthusiasts, Fleet Operators, High-Net-Worth Individuals, Ride-Sharing Networks Sales Channel: Authorized Dealerships, Direct-to-Consumer, Online Marketplaces, Luxury Auto Exhibitions, Corporate Sales |
| Companies Covered | Tesla, Inc., BMW Group, Nissan Motor Corporation, Toyota Motor Corporation, General Motors, Volkswagen Group, Stellantis NV, Daimler AG, Renault Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive High Performance Electric Vehicles Market Shifts & Advancements
Battery architecture evolution is fragmenting competitive advantage away from traditional powertrain expertise toward electrochemical and thermal management specialization. Three developments are compressing the technology adoption cycle.
Silicon-anode cell chemistry is decentralizing energy density leadership away from incumbent cylindrical cell formats. Boutique supercar manufacturers in Provence-Alpes-Côte d'Azur are adopting pouch-cell configurations with silicon-dominant anodes at twice the pace of mass-market programs. This technology is decentralizing pack-level thermal management responsibility toward cell suppliers, compressing OEM vertical integration strategies.
EU AI Act provisions for autonomous performance driving modes are mandating redundant sensor fusion architectures. French national automotive regulator enforcement of these protocols is extending homologation timelines by eight to fourteen months for Level 3+ track-assist features. Sports car segments with high motorsport heritage exposure are responding with driver-centric manual override systems that satisfy safety thresholds while preserving engagement.
Collector buyers are compressing purchase cycles toward limited-production allocation models. Traditional dealership networks in Île-de-France are ceding ground to direct manufacturer reservation platforms with non-refundable deposits. This behavioral pivot is most visible among Paris-based collectors securing build slots for solid-state battery prototypes before regulatory certification completion.
France Automotive High Performance Electric Vehicles Market Segmentation
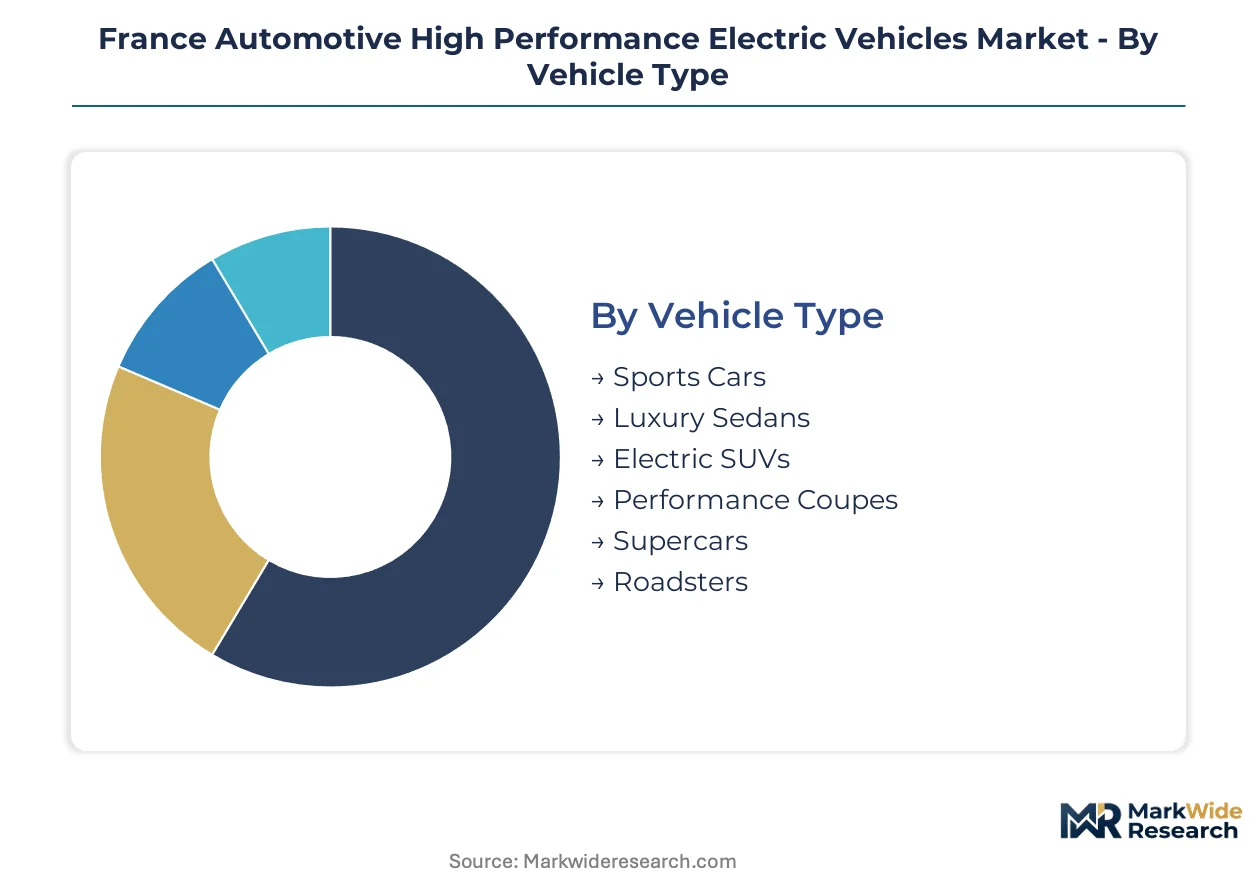
High-performance EV segmentation in France reflects divergent technical architectures and purchasing behaviors. Battery chemistry choices and vehicle form factors determine margin structure, while sales channel preferences signal collector versus daily-use buyer differentiation.
Vehicle Type:
Dual-motor layouts and thermal endurance specifications define competitive positioning across body styles.
- Sports Cars:Two-seat architectures with sub-four-second acceleration dominate track-day demand in Provence-Alpes-Côte d'Azur. Paris-based collectors prioritize limited-production allocations with motorsport-derived chassis tuning.
- Supercars:Solid-state battery prototypes attract the deepest R&D allocation due to energy density thresholds required by this segment. French Riviera charging density supports sustained high-speed touring use cases.
- Luxury Sedans:Dual-purpose daily and leisure mobility positioning expands reach among executives in Île-de-France.
- Electric SUVs:Dual-motor all-wheel-drive configurations capture high-net-worth families seeking versatile performance.
- Performance Coupes:Fixed-roof aerodynamic optimization balances grand touring range with circuit capability.
- Roadsters:Open-top configurations concentrate in seasonal demand clusters along the Mediterranean coast.
Mature deployment sits with Sports Cars. Newer deployment is concentrated in Electric SUVs.
Propulsion Technology:
Energy density trajectories and thermal management requirements are fragmenting powertrain investment priorities.
- Battery Electric:Lithium-ion cell configurations with silicon-anode chemistry achieve 800V architectures for sub-20-minute fast charging. Paris and French Riviera infrastructure density supports daily high-performance use without range anxiety constraints.
- Solid-State Battery:Electrolyte chemistry advances promise energy density breakthroughs for 1000+ km range supercars. Prototype-to-production yield gaps currently limit volume expansion for road-legal deployment.
- Dual Motor:Torque vectoring capabilities enable track-level precision without mechanical differential complexity.
- Plug-in Hybrid:Transitional architectures preserve combustion range extender flexibility for collector garage integration.
- Hydrogen Fuel Cell:Heavy-duty endurance racing applications test fuel cell durability under sustained load.
- Regenerative Braking:Advanced recuperation systems extend thermal endurance during repeated high-deceleration track sessions.
Volume concentration favors Battery Electric. Steepest expansion trajectory belongs to Solid-State Battery.
End User:
Purchasing power distribution and usage intensity patterns determine pricing elasticity across buyer categories.
- Premium Collectors:Non-refundable deposit reservation platforms compress purchase cycles ahead of regulatory certification completion. Build-slot securing behavior concentrates in Île-de-France and the French Riviera.
- High-Net-Worth Individuals:Dual-purpose daily-leisure mobility requirements favor electric SUV form factors with flexible charging schedules.
- Motorsport Enthusiasts:Track-day insurance and circuit membership affiliations drive seasonal demand spikes.
- Fleet Operators:Corporate sustainability mandates accelerate luxury sedan procurement for executive transport.
- Ride-Sharing Networks:Premium service tiers deploy high-performance EVs for brand differentiation in Paris.
Revenue concentration rests with Premium Collectors. Emerging deployment clusters form around Ride-Sharing Networks.
Sales Channel:
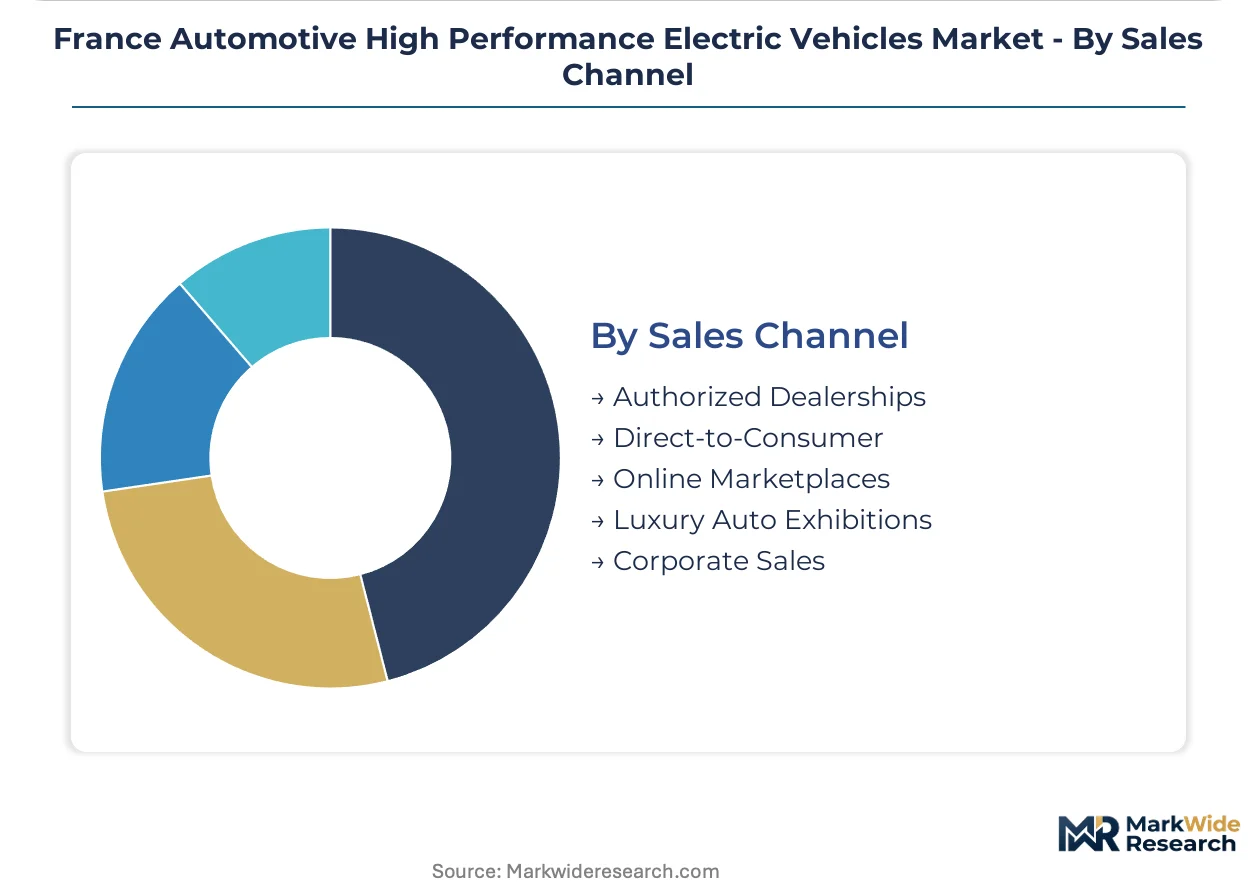
Channel strategy reflects trust requirements and allocation scarcity dynamics in limited-production segments.
- Direct-to-Consumer:Manufacturer reservation platforms with transparent build-queue visibility displace traditional dealership relationships. Paris-based collectors demonstrate strongest adoption of deposit-based allocation systems.
- Authorized Dealerships:After-service integration and certified pre-owned programs sustain relevance for legacy collector relationships.
- Luxury Auto Exhibitions:Concours events in the French Riviera generate pre-launch order commitments before type-approval completion.
- Online Marketplaces:Secondary market liquidity for limited-production slots creates speculative trading dynamics.
- Corporate Sales:Fleet procurement frameworks bypass retail allocation queues for volume commitments.
Established volume flows through Authorized Dealerships. Channel innovation is accelerating fastest in Direct-to-Consumer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The French Riviera's ZEV tax-exemption corridor concentrates high-net-worth purchasing power alongside premium charging infrastructure density. Paris-Île-de-France anchors collector demand through direct-to-consumer reservation platforms. Regional manufacturing clusters in Auvergne-Rhône-Alpes and Hauts-de-France solidify battery supply chain localization under EU Battery Regulation mandates.
Île-de-France
Paris-based collectors compress purchase cycles through non-refundable deposit systems for limited-production allocations. The French national automotive regulator enforces type-approval protocols aligned with EU AI Act provisions for autonomous performance modes. Boulogne-Billancourt and Saint-Cloud host legacy OEM headquarters directing motorsport-derived R&D programs.
Provence-Alpes-Côte d'Azur
Seasonal demand spikes from motorsport enthusiasts concentrate around Monaco and Nice circuit memberships. EU Green Deal fleet emissions targets accelerate local charging infrastructure deployment along coastal corridors. Sophia Antipolis technology park attracts silicon-anode cell chemistry startups serving boutique supercar manufacturers.
Auvergne-Rhône-Alpes
Grenoble's battery research ecosystem supplies thermal management engineering talent to performance EV programs. ANSM oversees occupational safety standards for pilot solid-state battery manufacturing lines. Saint-Étienne's industrial base transitions toward gigafactory component fabrication under EU Battery Regulation origin requirements.
Hauts-de-France
Douai and Maubeuge manufacturing sites anchor Stellantis NV's French production footprint for electrified architectures. REACH and RoHS frameworks govern chemical composition mandates across localized supplier networks. Lille's logistics hub facilitates EEA-sourced cell distribution compliant with EU Battery Regulation traceability protocols.
Nouvelle-Aquitaine
Bordeaux's executive demographic drives dual-purpose electric SUV demand for daily-leisure mobility. The French national automotive regulator streamlines type-approval processes for low-volume performance manufacturers. Arcachon Bay seasonal residence patterns create secondary demand clusters for open-top roadster configurations.
France Automotive High Performance Electric Vehicles Market Competitive Landscape
German producers anchor the premium-tier powertrain segment; French specialists hold manufacturing integration advantages through domestic gigafactory proximity. Market structure consolidates around legacy OEM portfolio restructuring and dedicated performance sub-brand spinouts. Three archetypes dominate: vertically integrated battery competence centers, motorsport-heritage engineering houses, and solid-state battery technology licensors. Competitive intensity centers on strategic partnerships for thermal management IP and capacity expansion into silicon-anode pilot lines.
Among Germany-based conglomerates, BMW Group and Daimler AG occupy positions exemplifying dual-motor architecture leadership in luxury performance segments. Tesla, Inc. anchors the direct-to-consumer reservation model that Paris-based collectors increasingly favor. Stellantis NV and Renault Group represent French manufacturing integration archetypes, with the latter competing through dedicated performance sub-brand development. Volkswagen Group sits within the portfolio diversification tier, balancing mass-market scale economics against high-performance EV R&D allocation.
| Leading Market Players |
|---|
| Tesla, Inc. |
| BMW Group |
| Nissan Motor Corporation |
| Toyota Motor Corporation |
| General Motors |
| Volkswagen Group |
| Stellantis NV |
| Daimler AG |
| Renault Group |
| Others |
Supply & Pricing Matrix
EU Battery Regulation origin requirements gate qualified cell supply and premium-tier pricing access for French high-performance EV manufacturers, compressing margins on non-EEA sourced inputs while rewarding localized gigafactory investments with preferential certification timelines.
Pricing Analysis
Short lead-time premiums dominate allocation economics for limited-production supercar build slots, with Paris-based collectors paying deposit premiums to secure silicon-anode prototypes ahead of regulatory certification. Three-tier pricing structure across motorsport-homologated, road-legal performance, and grand touring specifications separates track-day insurance bundling from standard warranty coverage. Cost compression in solid-state battery tiers is intensifying because prototype-to-production yield gaps constrain volume scaling. Fleet operators demonstrate highest price sensitivity due to corporate sustainability procurement frameworks, while premium collectors exhibit inelastic demand for motorsport-derived chassis allocations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stellantis NV and Renault Group manufacturing footprints, while specialty distributors serve boutique Provence-Alpes-Côte d'Azur supercar assemblers. Cell supply concentrates in South Korea, China, and Japan for lithium-ion configurations, with pilot solid-state lines emerging in Germany and France. Raw material dependencies span lithium hydroxide from Australia, nickel sulfate from Indonesia, and silicon anode precursors from Norway. Single-source vulnerability in solid-state electrolyte chemistry creates qualification bottlenecks for 1000+ km range architectures. Distribution runs through Saint-Étienne component fabrication clusters and Lille logistics hubs under EU Battery Regulation traceability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery architectures are displacing legacy lithium-ion dominance in French high-performance EV programs, forcing portfolio restructuring across powertrain engineering competencies and supplier qualification timelines.
For Market Incumbents: Extend thermal management IP licensing to silicon-anode cell suppliers, decentralizing pack-level responsibility while preserving motorsport-derived chassis tuning differentiation. Accelerate captive supply of solid-state pilot line capacity in Auvergne-Rhône-Alpes to hedge against South Korean cell import dependency. Defensive consolidation must address electrochemistry talent scarcity constraining hiring pipelines for specialized battery systems engineers. For New Entrants and Emerging Players: Luxury auto exhibitions in the French Riviera offer pre-launch order commitment channels before ANSM type-approval completion, bypassing legacy dealership network barriers. White-space concentration sits with dual-purpose electric SUVs targeting Bordeaux executive demographics for daily-leisure mobility. Direct-to-consumer reservation platforms with transparent build-queue visibility represent the most penetrable go-to-market angle for Paris-based collector access. For Investors and Strategic Acquirers: Stellantis NV solid-state battery partnership announcements are the leading indicator that prototype-to-production yield gaps are closing for road-legal deployment. Long-term viability across the analysis window favors vertically integrated manufacturing archetypes with captive gigafactory proximity and motorsport heritage engineering credibility. Acquisition targets should demonstrate thermal management IP portfolios and silicon-anode qualification progress. Practitioners should monitor EU AI Act autonomous performance mode certification timelines for regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Partnership | Stellantis NV anchors French manufacturing competitiveness through localized pilot line investments under EU Battery Regulation. |
| Thermal Management IP Licensing | Renault Group transfers Formula E endurance capabilities to road-legal architectures via supplier decentralization strategies. |
| Direct-to-Consumer Platform Launch | Tesla reservation models displace Île-de-France dealership networks for limited-production allocation transparency. |
| Silicon-Anode Supply Agreement | Sophia Antipolis startups feed Provence-Alpes-Côte d'Azur boutique manufacturers with energy density breakthrough chemistry. |
| Charging Infrastructure Partnership | French Riviera coastal corridor deployment aligns high-net-worth purchasing power with premium fast-charging density. |
Research Methodology
SEC filings, EU Battery Regulation traceability databases, and IHS Markit vehicle registration data formed the secondary backbone, cross-referenced with primary interviews involving OEM platform engineers, Tier 1 supplier procurement leads, and ANSM regulatory affairs specialists. Bottom-up triangulation against top-down macroeconomic drivers validated segment-level volume assumptions. Conversations with motorsport program directors and solid-state battery R&D heads supplied technology adoption timeline inputs.
Bottom-up modeling anchored volume projections across vehicle class, propulsion architecture, and regional production cluster dimensions, with top-down macroeconomic cross-checks for consistency. CAGRs were derived from segment-level growth trajectory analysis incorporating silicon-anode chemistry adoption curves and EU Green Deal fleet compliance deadlines. Forecast inputs included charging infrastructure deployment schedules in Île-de-France and Provence-Alpes-Côte d'Azur, plus solid-state battery yield improvement assumptions.
Caveats apply where lithium and nickel price volatility, solid-state manufacturing scale delays, or EU AI Act certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions around EEA-sourced cell supply qualification and thermal engineering talent availability. Practitioners should monitor ANSM type-approval streamlining progress and DGFT import licensing interactions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Africa Electric Vehicle Market