
 North America E-Bike Market | 2026-2036
North America E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
North America E-Bike Market Analytics
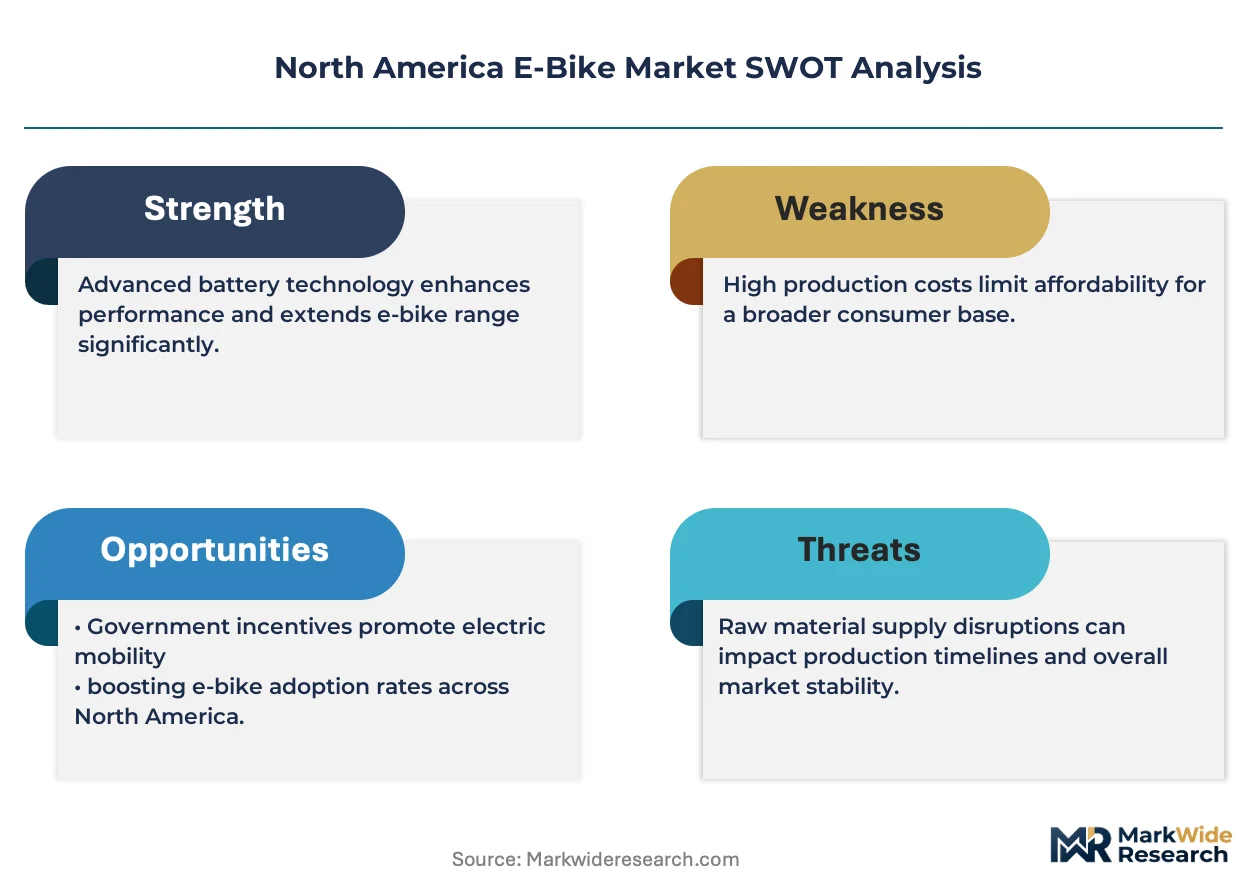
The North America e-bike landscape is restructuring around a sharp split between premium performance machines and sub-thousand-dollar commuter units. Rad Power Bikes anchors the mass-market tier through direct-to-consumer scale and simplified SKUs. Specialized Bicycle Components, Inc. dominates the premium channel with dealer-network quality assurance and race-derived engineering. Trek Bicycle Corporation leverages its domestic manufacturing footprint to control lead times across both tiers.
North America e-bikes are pedal-assisted bicycles integrating rechargeable battery packs, hub or mid-drive motors, and torque or cadence sensors to augment human propulsion up to regulated speed thresholds, typically Class 1 through Class 3 designations. City e-bikes sustain the largest volume base as last-mile commuting normalizes across dense metro areas. Mountain e-bikes represent the fastest-expanding margin pool, driven by trail-access debates and higher average selling prices. Lithium-ion battery configurations occupy the technical mainstream, displacing lead-acid alternatives through energy density advantages and falling cell costs.
The U.S. Consumer Product Safety Commission and Transport Canada set divergent Class 1-3 speed and wattage thresholds that manufacturers must navigate for cross-border compliance. The U.S. EPA and state-level zero-emission vehicle credits in California shape battery sourcing and end-of-life recycling obligations. Stakeholders must monitor how municipal helmet laws, trail access rulings, and potential federal e-bike tax credit extensions alter channel economics and product positioning across the continent.
Market Dynamics
The U.S. Inflation Reduction Act's clean mobility incentives and municipal bike-lane infrastructure expansions are converging to compress adoption timelines across Canadian and U.S. metropolitan corridors. Battery chemistry improvements and Class 1-3 regulatory harmonization pressures are simultaneously pulling demand toward higher-performance configurations while fragmenting compliance requirements.
Growth Catalysts
- Clean Mobility Incentives:The U.S. Inflation Reduction Act's tax credits for electric two-wheelers reduce effective purchase prices for urban commuters in California, New York, and Washington corridors.
- Hub Motor Efficiency Gains:Brushless DC motor refinements and integrated torque sensors are extending range-per-charge metrics for last-mile delivery fleets operating in Toronto, Vancouver, and Chicago.
- Trail Access Normalization:Municipal land-use agencies across British Columbia and Colorado are formalizing e-bike access on multi-use paths, opening margin-rich mountain configurations to recreational buyers.
Market Restraints
- Lithium Cell Supply Concentration:Cathode and cell manufacturing concentrates in East Asian supply bases, exposing North American assemblers to shipping cost volatility and tariff exposure.
- Cross-Border Regulatory Friction:Transport Canada's 500W power ceiling diverges from the U.S. 750W Class 3 threshold, forcing dual-SKU production runs for integrated drive systems.
- Substitution from Micromobility:Shared electric scooters and transit-oriented development in Seattle, Montreal, and Austin compete for the same 0-5 mile trip budgets.
Strategic Opportunities
- Service-Enabled Revenue Models:Subscription-based battery health monitoring and predictive maintenance apps are expanding into direct-to-consumer channels, capturing recurring revenue from Rad Power Bikes and similar mass-market buyers.
- Mexico Assembly Footprint:Nearshoring production to Baja California and Chihuahua reduces landed cost exposure for U.S. distribution while qualifying for USMCA origin rules.
- Commercial Fleet Electrification:Last-mile logistics operators from FedEx Ground contractors to Instacart delivery partners are piloting cargo e-bike deployments in Manhattan, San Francisco, and Vancouver dense zones.
Industry Challenges
- Certification Timeline Compression:UL 2849 fire-safety testing and state-level DMV registration requirements in New York and Massachusetts extend product launch cycles by 4-8 months.
- Technician Training Deficits:Dealer networks lack certified technicians for mid-drive motor diagnostics and battery management system firmware updates, constraining after-sales service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America E-Bike Market |
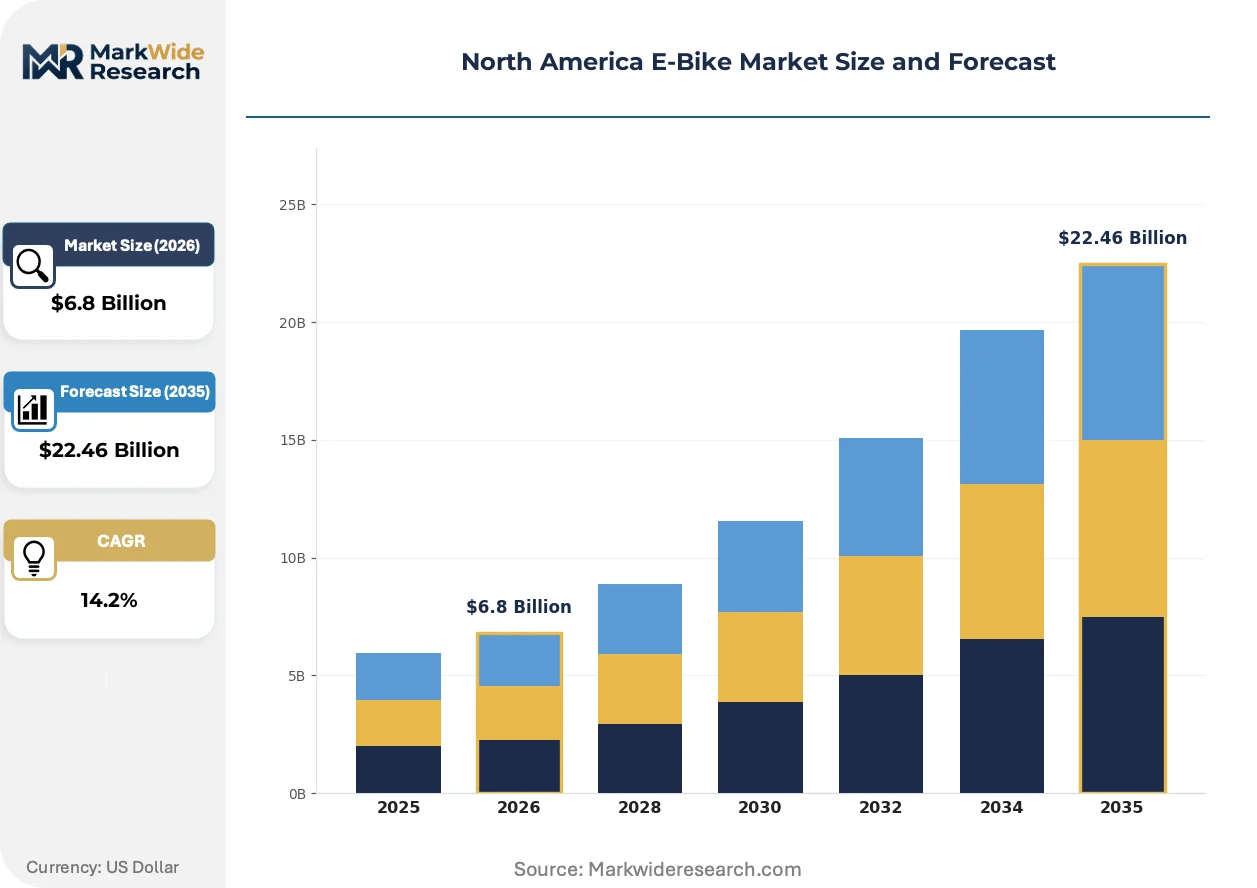
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cruiser E-Bikes Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Lithium polymer End User: Commuters, Recreational Users, Delivery Services, Tourism Price Range: Low-end, Mid-range, Premium, Luxury |
| Companies Covered | Trek Bicycle Corporation, Giant Manufacturing Co., Rad Power Bikes, Specialized Bicycle Components, Inc., Yamaha Motor Co., Ltd., Cannondale (Cycling Sports Group, Inc.), Pedego Electric Bikes, Velotric, HOVSCO, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America E-Bike Market Evolving Landscape
Solid-state battery prototyping and torque-sensor integration are compressing performance gaps between premium and mass-market configurations. Municipal procurement is normalizing e-bikes for parks departments and parking enforcement fleets. Software-defined motor controllers are enabling over-the-air performance tuning.
Silicon-anode lithium-ion cells are expanding into premium mountain and cargo configurations where energy density gains translate directly to range extension. Enthusiast buyers in Colorado and British Columbia trail systems are absorbing 15-20% price premiums for 30% capacity improvements. This chemistry transition is expanding into the mid-market as cell costs normalize through 2026.
The U.S. Consumer Product Safety Commission's pending mandatory reporting rule for e-bike fire incidents is tightening UL 2849 certification requirements across all import channels. Manufacturers sourcing from contract assemblers in Shenzhen and Taichung face documentation burdens that favor vertically integrated producers with captive testing labs. The mass-market direct-to-consumer segment is responding by consolidating supplier relationships around pre-certified battery pack vendors.
Fleet procurement departments are unbundling after-sales service from hardware acquisition, negotiating separate maintenance contracts with third-party bike shops rather than OEM service networks. Last-mile delivery operators in Chicago, Toronto, and Los Angeles are driving this shift, treating e-bikes as consumable assets with 18-24 month replacement cycles. This pattern is compressing margin capture for manufacturers while expanding service revenue pools for regional dealer networks.
North America E-Bike Market Segmentation
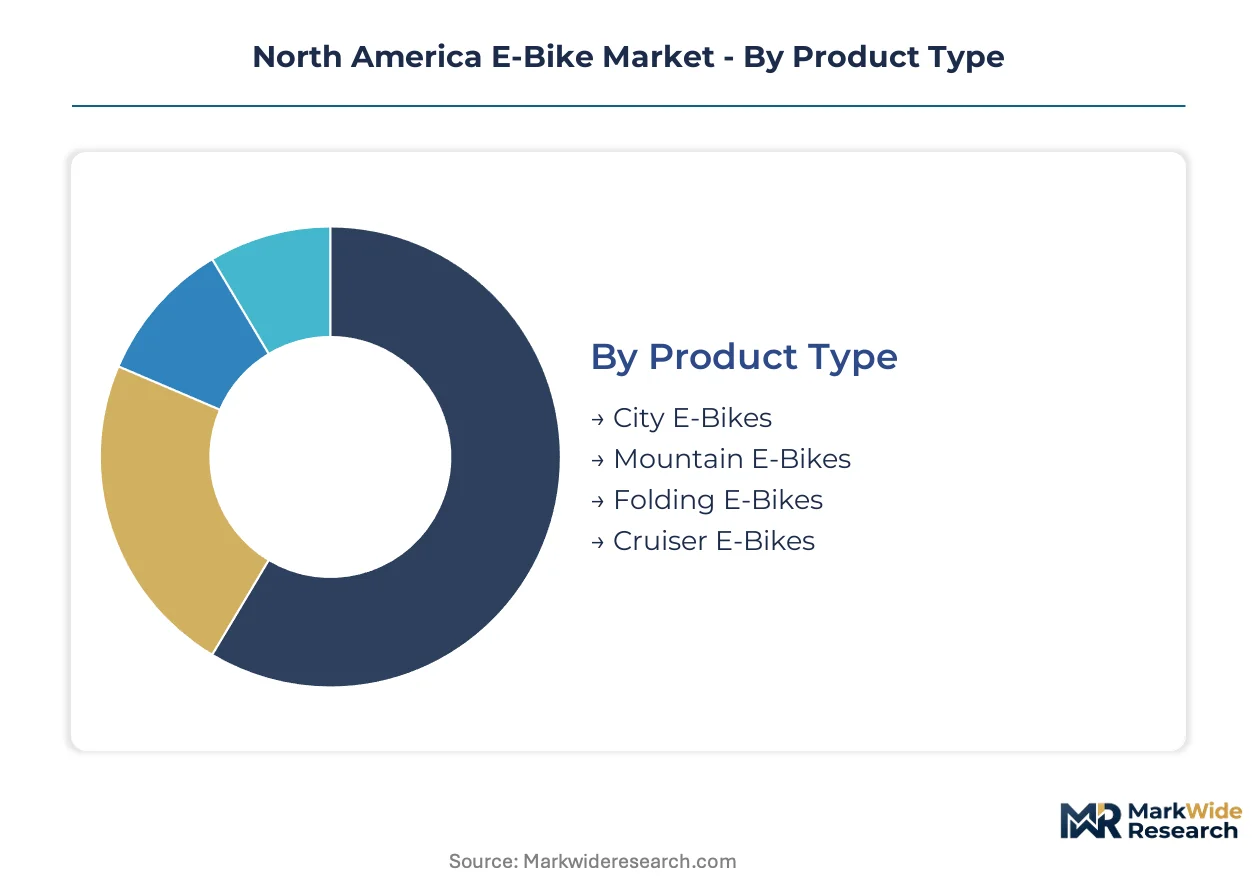
Segmentation reveals how capital deployment and regulatory exposure vary sharply across the North America e-bike landscape. Battery chemistry and motor integration requirements create divergent margin profiles that reshape competitive positioning in each tier.
Product Type:
Capital intensity peaks where frame engineering and suspension systems must withstand higher mechanical loads and certification burdens.
- City E-Bikes:Step-through aluminum frames and hub-drive configurations dominate urban corridors from Manhattan to Vancouver. Municipal procurement departments in Chicago and Toronto are standardizing these units for parking enforcement and parks maintenance fleets, compressing purchase cycles through blanket ordering agreements.
- Mountain E-Bikes:Full-suspension carbon frames paired with mid-drive torque sensors command the highest bill-of-materials costs in the category. Trail-access rulings across British Columbia and Colorado are unlocking recreational demand despite 40% price premiums over city configurations.
- Folding E-Bikes:Hinge mechanisms and compact hub motors target multimodal commuters in Boston and San Francisco.
- Cruiser E-Bikes:Relaxed geometry and step-over frames serve beach communities and retirement corridors in Florida and Southern California.
City E-Bikes absorb the bulk of installed capacity; Mountain E-Bikes are expanding most quickly.
Battery Type:
Cell chemistry selection determines warranty exposure, shipping classification, and end-of-life recycling obligations across the value chain.
- Lithium-ion:NMC and LFP cylindrical cells deliver 250-500 Wh energy densities that define Class 1-3 range expectations. The U.S. EPA's emerging battery passport requirements and California's extended producer responsibility rules are forcing assemblers to document cathode sourcing through Korean and Japanese cell suppliers.
- Lead-acid:Sealed AGM configurations persist in low-speed personal mobility devices and aftermarket retrofits where first-cost sensitivity outweighs cycle-life considerations.
- Nickel-metal Hydride:NiMH packs occupy niche applications in cold-climate fleets where thermal stability trumps energy density.
- Lithium polymer:Pouch-cell formats enable frame-integrated battery designs in premium mountain and cargo configurations.
Lithium-ion carries the heaviest compliance burden; Lithium polymer is gaining share fastest in integrated-frame designs.
End User:
Procurement sophistication and total-cost-of-ownership modeling vary dramatically across buyer categories.
- Commuters:Daily riders in Seattle, Montreal, and Washington D.C. prioritize reliability and theft-deterrence features over performance specifications. The U.S. Inflation Reduction Act's clean mobility incentives reduce effective purchase prices most visibly in this segment.
- Recreational Users:Weekend riders across Colorado and British Columbia trail systems absorb premium pricing for extended-range configurations and smartphone integration.
- Delivery Services:FedEx Ground contractors and Instacart partners in Manhattan and San Francisco are piloting cargo e-bike deployments with 18-24 month replacement cycles.
- Tourism:Rental operators in Napa Valley and Quebec's Route Verte corridor favor low-maintenance hub-drive units with interchangeable battery systems.
Commuters represent the deepest volume base; Delivery Services are climbing the fastest as logistics electrification accelerates.
Price Range:
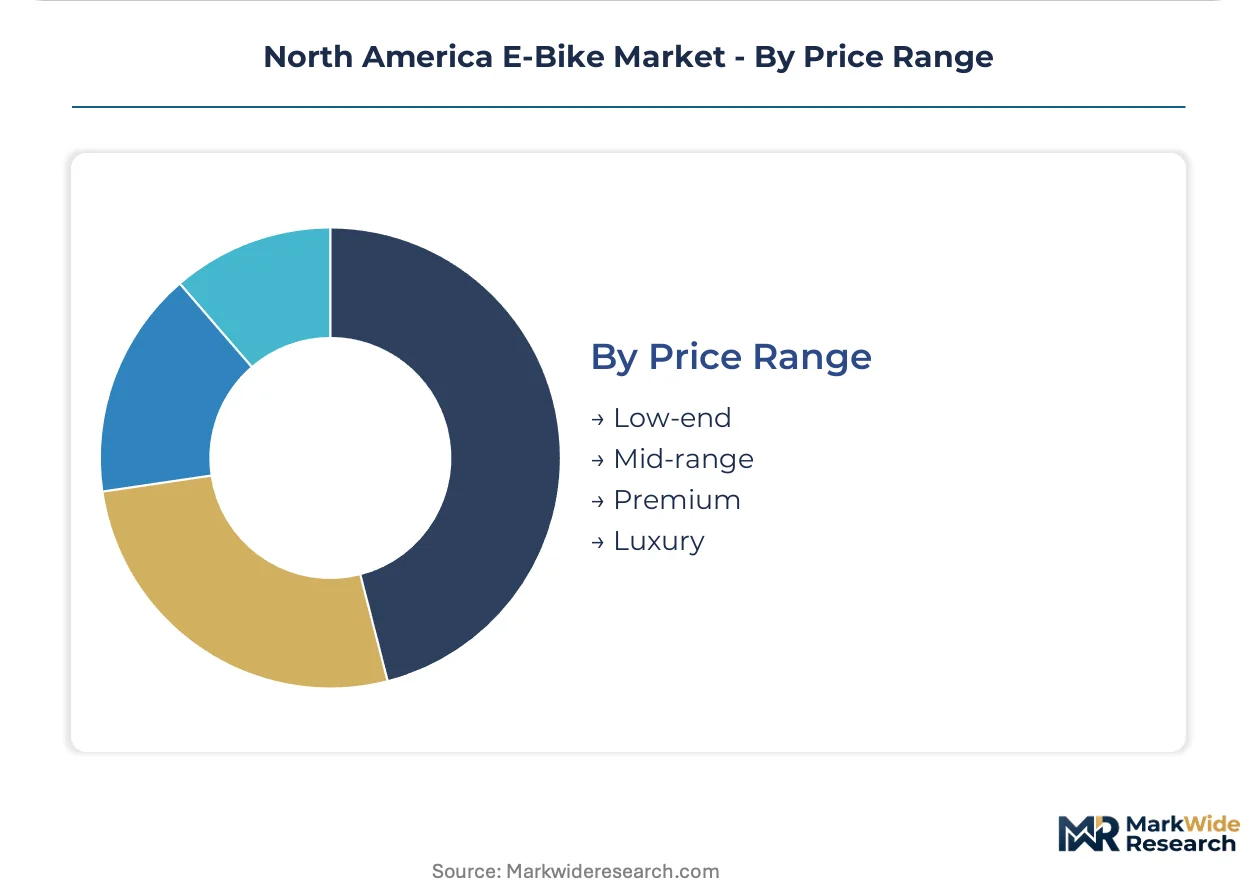
Margin structure and channel economics invert as price tiers ascend, with premium segments capturing service revenue and direct-to-consumer scale dominating the low end.
- Low-end:Direct-to-consumer brands source hub-motor kits from Shenzhen assemblers, shipping flat-packed units to bypass dealer markups. UL 2849 certification gaps in this tier are tightening as the U.S. CPSC mandates incident reporting.
- Mid-range:Dealer-network brands like Trek and Specialized anchor this tier with domestic assembly and two-year warranty coverage. This segment captures the bulk of IRA incentive-eligible volume in California and New York corridors.
- Premium:Bosch and Shimano mid-drive systems, carbon frames, and integrated lighting define specifications here. Technician training deficits constrain after-sales service capacity for these complex drivetrains.
- Luxury:Limited-production European imports and custom builders serve collectors and high-net-worth enthusiasts with bespoke frame geometry and hand-built wheels.
Mid-range configurations absorb the bulk of policy-driven demand; Premium tier is expanding most quickly as battery energy density improvements justify price escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the continent's e-bike demand concentration, with the San Francisco Bay Area and San Diego corridor amplifying California's policy-driven adoption surge. Metropolitan bike-lane investments and state-level zero-emission incentives are compressing purchase timelines across the Pacific Coast urban belt.
United States
The Inflation Reduction Act's clean mobility tax credits are reducing effective purchase prices for commuters in California, New York, and Washington corridors. The U.S. Consumer Product Safety Commission mandates UL 2849 fire-safety certification for all import channels, tightening compliance burdens on direct-to-consumer brands. Brooklyn and Manhattan delivery fleets are piloting cargo e-bike deployments with 18-24 month replacement cycles.
Canada
Transport Canada's 500W power ceiling for Class 3 e-bikes diverges from U.S. thresholds, forcing dual-SKU production runs for integrated drive systems. Municipal bike-share expansions in Toronto and Vancouver are normalizing last-mile commuting patterns. The Greater Toronto Area's parking enforcement and parks maintenance departments are standardizing city e-bike fleets through blanket procurement agreements.
Mexico
Baja California and Chihuahua assembly corridors are capturing nearshoring momentum as manufacturers seek USMCA origin qualification and reduced landed cost exposure. The country's automotive supplier base is pivoting toward e-bike component fabrication. Tijuana and Mexicali industrial zones are hosting contract assembly operations for U.S. distribution networks.
British Columbia
Provincial trail-access rulings are unlocking recreational demand for full-suspension mountain configurations despite 40% price premiums over city units. Vancouver's municipal land-use agencies are formalizing e-bike access on multi-use paths. The Sea-to-Sky corridor is emerging as a testing ground for extended-range premium configurations among enthusiast buyers.
Colorado
Front Range municipalities are expanding Class 1-3 trail access across Boulder and Denver metro park systems. State-level outdoor recreation incentives intersect with lithium-ion energy density improvements to justify price escalation among weekend riders. The Interstate 70 mountain corridor is absorbing premium mountain e-bike volume as trail normalization accelerates.
North America E-Bike Market Competitive Landscape
Premium-margin players sit above commodity-margin players across battery chemistry and motor integration sophistication. The vendor base stratifies into three tiers: vertically integrated domestic assemblers with captive testing labs, direct-to-consumer brands sourcing hub-motor kits from contract manufacturers, and European-import specialists serving luxury collectors. Capacity expansion and strategic supplier consolidation represent the dominant competitive moves as UL 2849 certification requirements tighten.
Within the premium-tier vector, Trek Bicycle Corporation and Specialized Bicycle Components, Inc. occupy positions defined by dealer-network quality assurance and domestic manufacturing footprints. Rad Power Bikes exemplifies the mass-market direct-to-consumer archetype, while Giant Manufacturing Co. represents the Asia-Pacific contract fabrication anchor serving multiple brand labels. These three entities collectively illustrate the margin-structure divergence reshaping channel economics.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Giant Manufacturing Co. |
| Rad Power Bikes |
| Specialized Bicycle Components, Inc. |
| Yamaha Motor Co., Ltd. |
| Cannondale (Cycling Sports Group, Inc.) |
| Pedego Electric Bikes |
| Velotric |
| HOVSCO |
| Others |
Value Network & Pricing Analysis
Municipal fleet procurement departments in Chicago and Toronto anchor demand for standardized city e-bike configurations, compressing price discovery through blanket ordering agreements rather than transactional spot purchasing. This buyer concentration forces manufacturers to absorb certification and warranty costs into unit economics, reshaping margin allocation across dealer and direct-to-consumer channels.
Pricing Analysis
Value-based pricing anchored to total-cost-of-ownership metrics dominates commercial fleet segments, where delivery operators model fuel savings and maintenance avoidance against acquisition premiums. Price differentiation rests on UL 2849 certification grade and after-sales service bundling, with certified mid-drive systems commanding premiums over hub-motor alternatives. Cost compression in the direct-to-consumer tier intensifies as Shenzhen assemblers compete on first-cost metrics, eroding margins for brands lacking dealer-network service revenue. Fleet buyers exhibit lowest price sensitivity due to operational savings modeling, while recreational commuters in dense corridors show highest elasticity to upfront purchase thresholds.
Supply Chain Analysis
Freight cost volatility from East Asian cell manufacturing hubs through Los Angeles and Vancouver ports compresses assembler margins and accelerates nearshoring evaluation. Cathode and cell production concentrates in China, South Korea, and Japan, drawing from lithium carbonate feedstock anchored in Chile and Australia. Single-source vulnerability around NMC and LFP cylindrical cell supply exposes North American assemblers to shipping rate spikes and tariff exposure. Distribution runs through three-channel structures: dealer networks for premium configurations, direct-to-consumer platforms for mass-market units, and fleet procurement departments for commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America e-bike market is consolidating around a vertical-integration race, with captive battery testing labs and Mexico assembly footprints emerging as decisive cost-control levers.
For Market Incumbents: Lock in UL 2849 certification capabilities through captive testing infrastructure or exclusive vendor relationships, insulating against CPSC incident-reporting rule enforcement. Secure Mexico assembly capacity in Baja California or Chihuahua corridors to qualify for USMCA origin rules and compress landed cost exposure. Dealer-network control and certified technician training pipelines defend against direct-to-consumer brands encroaching on service-dependent premium segments. For New Entrants and Emerging Players: Direct-to-consumer subscription models for battery health monitoring and predictive maintenance capture recurring revenue from Rad Power Bikes' installed base without matching its hardware scale. Target the cargo e-bike segment serving last-mile delivery fleets in Manhattan and San Francisco, where 18-24 month replacement cycles normalize rapid supplier switching. Fleet procurement departments unbundling service from hardware acquisition create entry points for specialized maintenance contractors. For Investors and Strategic Acquirers: The window for entry favors vertically integrated assemblers with captive Mexico production and pre-certified battery pack vendor relationships. Mid-cap specialists controlling both frame fabrication and drive system integration offer cleaner diligence profiles than brands dependent on Shenzhen contract manufacturers. Watch municipal trail-access rulings across British Columbia and Colorado as inflection indicators for premium mountain configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Nearshoring Assembly to Mexico | USMCA origin qualification reduces tariff exposure for U.S. distribution networks. |
| Captive Battery Testing Lab Investment | UL 2849 certification acceleration compresses product launch cycles by 4-8 months. |
| Subscription Service Model Launch | Predictive maintenance apps capture recurring revenue from mass-market installed base. |
| Fleet Procurement Partnership | Direct supply agreements with FedEx Ground contractors bypass dealer markup structures. |
| Solid-State Battery Prototyping | Silicon-anode cell integration justifies 15-20% price premiums in premium mountain segment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews conducted across OEM product managers, municipal procurement officers, and fleet operations directors at last-mile delivery contractors. PeopleForBikes industry statistics, U.S. CPSC incident databases, Transport Canada compliance registries, and USMCA certificate-of-origin records supplied quantitative foundations. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Data-stream reconciliation across manufacturer production disclosures, port import manifests, and dealer inventory positioning informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, battery chemistry, end-user category, price tier, and regional regulatory cluster. CAGRs derived from curve-fitting historical adoption patterns against policy incentive trajectories and infrastructure investment pipelines. Forecast inputs incorporated IRA credit extension probabilities and municipal bike-lane completion schedules.
The model holds under stable tariff regimes and continued IRA incentive availability; deviation in trade policy enforcement or federal credit expiration would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Europe Electric Bus Market