
 Europe Automotive Battery Thermal Management System Market | 2026-2036
Europe Automotive Battery Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Battery Thermal Management System Market Analytics
A capital-intensity divergence between integrated thermal module producers and component specialists is unwinding competitive stability across the European supply base. Robert Bosch leverages its electronics-thermal convergence to anchor high-voltage battery contracts with German OEMs. Valeo competes through dedicated e-mobility thermal centers in France, while BorgWarner differentiates via its acquisition-integrated power electronics-cooling portfolio.
Automotive Battery Thermal Management System denotes the engineered assembly of heat exchangers, coolant circuits, sensors, and control electronics that maintain lithium-ion cells within 15-45°C operational windows to prevent thermal runaway and capacity fade. Liquid Cooling Systems dominate value capture due to their heat flux handling above 500 W/kg in premium electric vehicle platforms, while Smart Thermal Management represents the fastest-expanding technology dimension as predictive algorithms reduce energy parasitics. Passive Systems occupy a mature, cost-optimized niche in compact hybrid applications where thermal loads remain moderate.
EMA's battery passport requirements, REACH chemical compliance for coolant formulations, and the EU Green Deal's embodied carbon rules collectively tighten material traceability and recyclability obligations for thermal system suppliers. The F-Gas Regulation's phasedown of fluorinated refrigerants is forcing refrigerant architecture transitions in active cooling loops. Stakeholders must monitor how delegated acts under the EU Battery Regulation redefine thermal system durability testing protocols and supplier accountability frameworks.
Market Dynamics
The EU Green Deal's battery sustainability mandates and tightening CO2 fleet standards are forcing thermal system redesigns across European OEM supply chains, compressing development cycles and elevating supplier accountability requirements.
Growth Catalysts
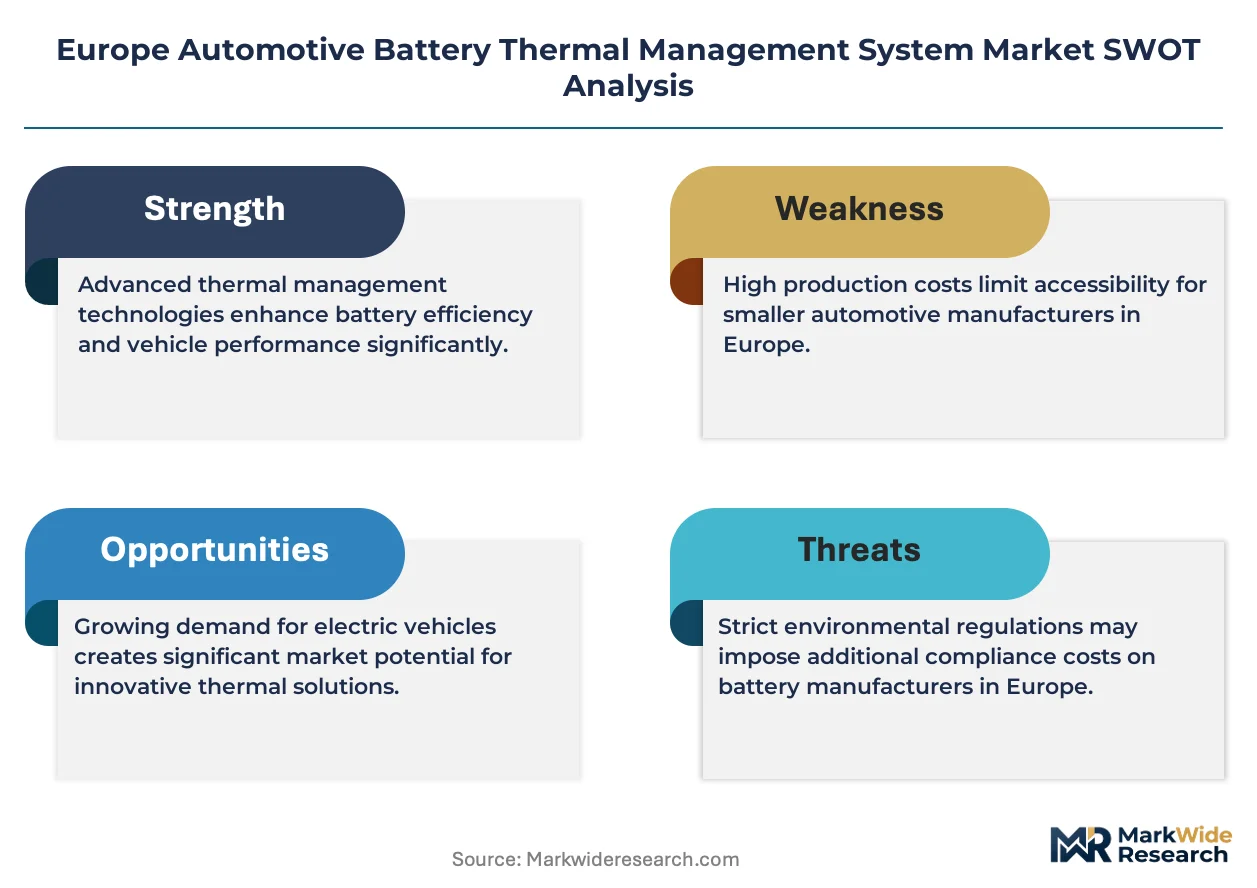
- EU Battery Regulation delegated acts:Durability testing protocols mandate predictive thermal monitoring, creating pull-through demand for sensor-integrated cooling modules in German and French EV platforms.
- Liquid cooling architectures:Heat flux requirements above 500 W/kg in premium electric vehicle platforms are accelerating module standardization across Netherlands-based battery assembly clusters.
- Netherlands charging infrastructure investments:Ultra-fast charging station rollouts require cell conditioning systems capable of managing thermal spikes during 350 kW charging events.
Market Restraints
- Fluorinated refrigerant phaseout:The F-Gas Regulation's steppedown timeline forces costly refrigerant architecture transitions in active cooling loops before cost curves flatten.
- Specialized aluminum alloy supply:Heat exchanger manufacturers face input concentration from Nordic smelters, exposing margin volatility to energy price swings.
- Passive system substitution ceiling:Compact hybrid applications resist liquid cooling upgrades due to packaging constraints and moderate thermal loads, capping addressable expansion.
Strategic Opportunities
- Poland and Czechia EV production corridors:Emerging battery gigafactories in these markets lack established thermal supplier ecosystems, creating first-mover positioning windows.
- Smart thermal-predictive algorithm convergence:Machine learning integration with coolant flow control offers parasitic energy reduction pathways distinct from hardware-centric competition.
- EU Green Deal embodied carbon rules:Recyclable coolant formulation requirements favor suppliers with closed-loop material traceability systems.
Industry Challenges
- Electronics-thermal engineering talent scarcity:Control software development for multi-physics battery models requires cross-trained specialists in short supply across France and Germany.
- REACH chemical compliance timelines:Coolant additive reformulation cycles lag regulatory effective dates, risking product qualification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Battery Thermal Management System Market |
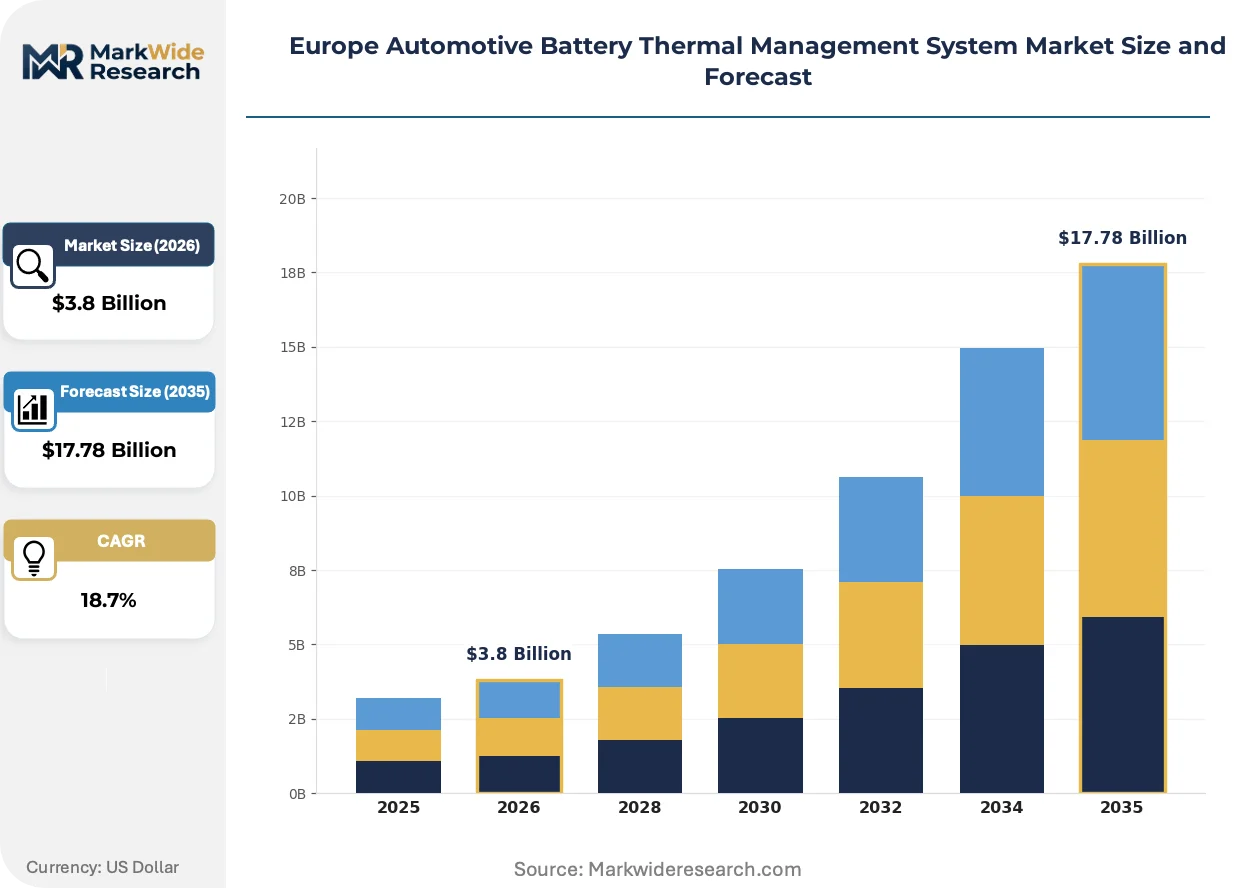
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cooling Systems, Air Cooling Systems, Phase Change Materials, Heat Pipes End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Active Systems, Passive Systems, Hybrid Systems, Smart Thermal Management Application: Electric Vehicles, Hybrid Vehicles, Fuel Cell Vehicles, Others |
| Companies Covered | Robert Bosch, Continental, Valeo, BorgWarner, Dana, Infineon Technologies, Gentherm, Hanon Systems, Webasto Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Battery Thermal Management System Market Evolving Landscape
Technology convergence between predictive software and hardware thermal control is redefining competitive differentiation, while regulatory chemistry mandates and charging infrastructure evolution reshape supplier capability requirements.
Dielectric coolant formulations with enhanced electrical insulation properties are supplanting traditional water-glycol mixtures in high-voltage battery packs. German OEMs are adopting these fluids fastest in 800V architectures. This chemistry transition is supplanting legacy heat exchanger designs that relied on galvanic corrosion resistance rather than dielectric compatibility.
REACH chemical compliance for coolant formulations is tightening material traceability obligations across the European supply base. ECHA substance restriction proposals are forcing reformulation investments ahead of qualification cycles. Thermal system suppliers serving French and Dutch battery assembly plants are responding by integrating recyclability certifications into procurement specifications.
Fleet operators and leasing companies are consolidating thermal system service contracts under battery lifecycle agreements rather than discrete component warranties. This bundling compresses supplier margins while extending accountability windows. The Netherlands and Germany show the fastest contract restructuring, driven by residual value guarantees on commercial EV fleets.
Europe Automotive Battery Thermal Management System Market Segmentation
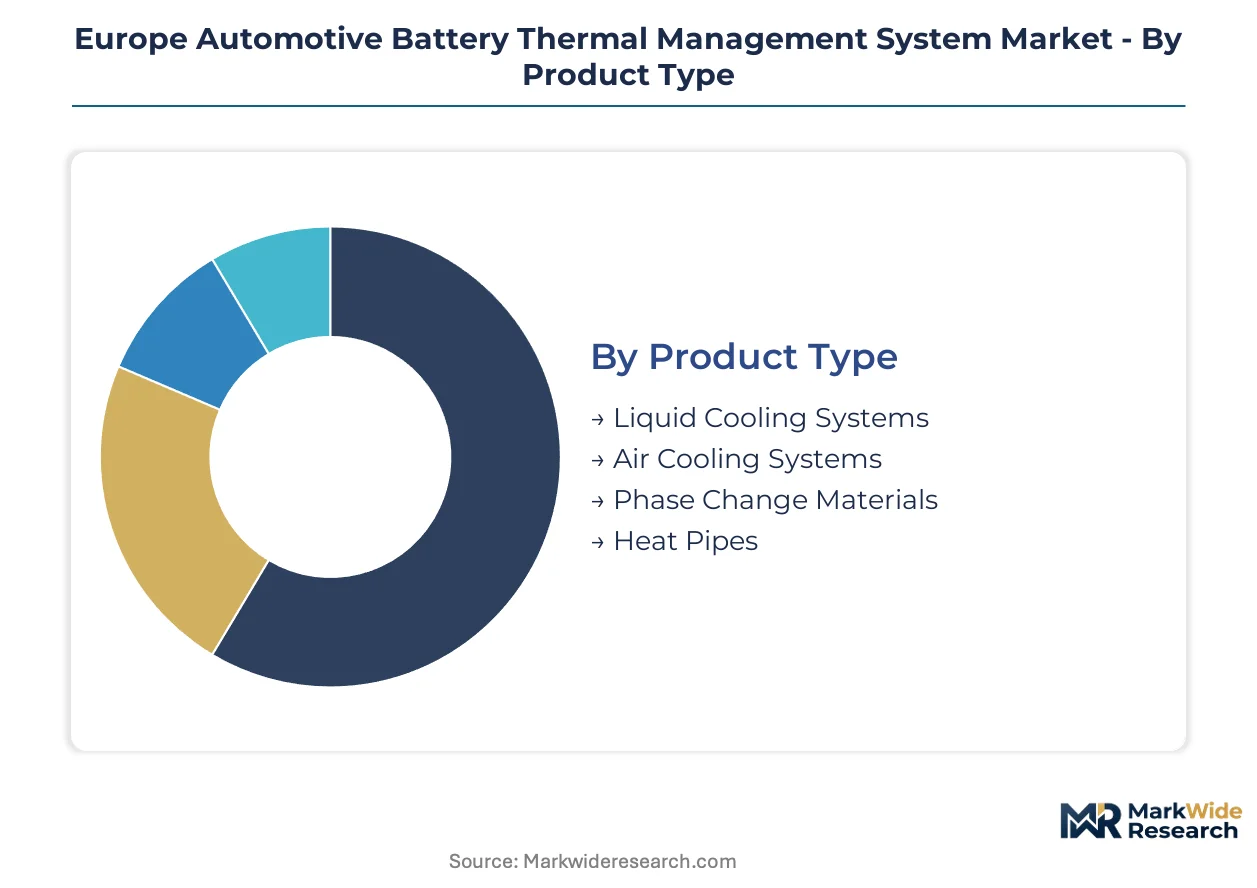
Thermal management architectures diverge sharply across European EV platforms based on voltage class, charging speed requirements, and OEM integration strategies. Segmentation reveals how regulatory chemistry mandates and power density thresholds reshape supplier capability investments across product tiers.
Product Type:
REACH chemical compliance and F-Gas Regulation timelines differentiate coolant formulation investments across thermal hardware categories.
- Liquid Cooling Systems:Engineered assemblies of cold plates, pumps, and dielectric fluid circuits handle heat flux above 500 W/kg in 800V German EV architectures. German and French OEMs concentrate procurement for premium electric vehicle platforms where fast-charging thermal spikes demand active dissipation.
- Air Cooling Systems:Blower-driven convective heat rejection serves compact hybrid applications with moderate thermal loads and packaging constraints. Netherlands-based vehicle assemblers favor these systems for cost-optimized urban mobility platforms where liquid cooling infrastructure adds unacceptable mass.
- Phase Change Materials:Latent heat absorption materials buffer transient thermal spikes without active pumping.
- Heat Pipes:Passive two-phase heat transfer devices bridge spatial gaps between cell modules and external sinks.
Established volume favors Liquid Cooling Systems; emerging adoption favors Phase Change Materials in range-extended hybrid configurations.
End User:
Accountability windows stretch longest for entities capturing residual value risk across battery lifecycle agreements.
- OEMs:German and French automakers internalize thermal system architecture decisions to protect platform differentiation and warranty exposure. These manufacturers specify dielectric coolant chemistries and sensor integration densities that cascade through supply contracts.
- Tier-1 Suppliers:Module integrators in France and the Netherlands consolidate heat exchanger, pump, and control electronics procurement under single-source accountability. REACH compliance documentation requirements favor suppliers with closed-loop material traceability systems.
- Aftermarket Providers:Service contract bundling under battery lifecycle agreements compresses margin structures for independent thermal system maintainers.
- Vehicle Assemblers:Contract manufacturers in Poland and Czechia EV production corridors source thermal modules from established Tier-1 ecosystems rather than developing captive capabilities.
Procurement authority concentrates with OEMs; execution risk concentrates with Tier-1 Suppliers facing chemistry transition timelines.
Technology:
Control software development costs stratify competitive positioning between predictive algorithm providers and hardware-centric module producers.
- Smart Thermal Management:Machine learning integration with coolant flow control reduces energy parasitics through predictive cell conditioning. German OEMs deploy these systems fastest in fleet applications where residual value guarantees demand optimized battery degradation curves.
- Active Systems:Pump and compressor-driven thermal control dominates premium electric vehicle platforms requiring precise temperature maintenance across drive cycles and charging events.
- Hybrid Systems:Combined passive-active architectures balance cost and performance in mid-range battery electric vehicles.
- Passive Systems:Conduction and natural convection satisfy compact hybrid thermal budgets with minimal component count.
Smart Thermal Management gains share fastest in commercial fleet specifications; Passive Systems defend position in cost-optimized hybrid segments.
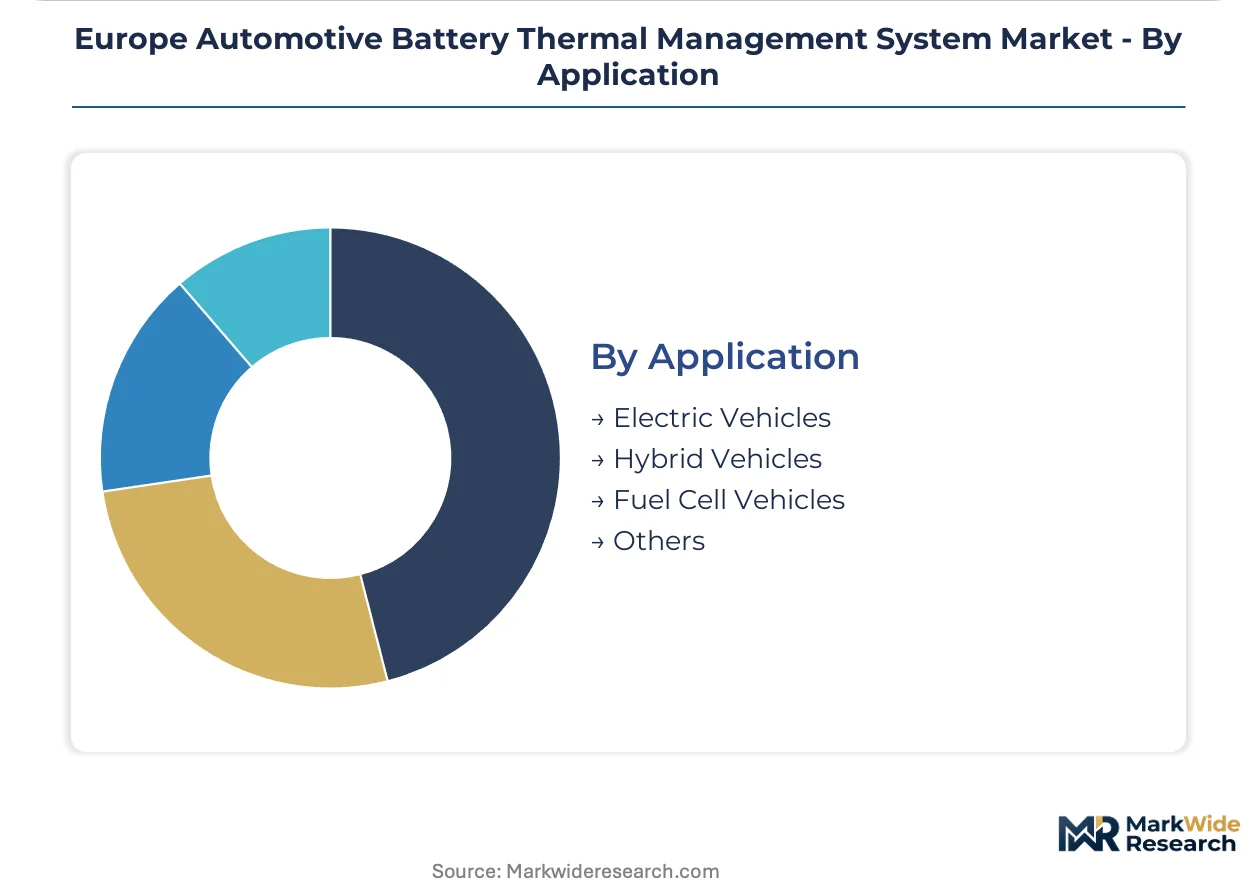
Application:
Charging infrastructure power levels dictate thermal system specification intensity across vehicle electrification categories.
- Electric Vehicles:Battery electric platforms with 800V architectures and 350 kW charging capability require dielectric liquid cooling with predictive cell monitoring. German OEM production volumes anchor European thermal system demand.
- Hybrid Vehicles:Compact hybrid applications with smaller battery packs and moderate discharge rates accommodate air cooling or passive thermal management. Packaging constraints in French urban mobility platforms resist liquid cooling upgrades.
- Fuel Cell Vehicles:Stack thermal management requirements diverge from battery-centric architectures, favoring specialized heat rejection systems.
- Others:Low-volume commercial and off-highway electrification applications source adapted automotive thermal modules.
Electric Vehicles anchor current procurement volumes; Fuel Cell Vehicles present specialized thermal engineering requirements distinct from mainstream battery conditioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs deploy liquid cooling most intensively for 800V architectures, while French and Dutch assemblers retain air-cooled systems for cost-optimized urban platforms. This consumption-mix differential shapes supplier capability investments across the region.
Germany
Robert Bosch and Continental anchor procurement for premium EV thermal modules serving BMW and Mercedes-Benz 800V platforms. The KBA enforces battery durability testing protocols that mandate predictive cell monitoring integration. Stuttgart and Munich production clusters concentrate dielectric coolant formulation expertise for high-voltage architectures.
France
Renault and Stellantis specify thermal systems for compact urban EVs where packaging constraints favor hybrid cooling architectures. ANSM oversight of REACH chemical compliance accelerates coolant additive reformulation cycles. Valeo's dedicated e-mobility thermal centers in Paris-Saclay and Lyon anchor supplier ecosystem development.
Netherlands
VDL Nedcar and commercial fleet operators drive demand for cell conditioning systems managing 350 kW charging thermal spikes. The national charging infrastructure rollout program mandates ultra-fast station compatibility specifications. Eindhoven's Brainport cluster concentrates smart thermal algorithm development for predictive energy management.
Poland
Emerging battery gigafactories in Lower Silesia and Greater Poland lack established thermal supplier ecosystems, creating positioning windows for module integrators. EU cohesion fund allocations for EV supply chain development accelerate facility permitting. LG Energy Solution's Wrocław complex sources thermal components from German Tier-1 ecosystems rather than developing captive capabilities.
Czechia
Škoda Auto's Mladá Boleslav production hub internalizes thermal architecture decisions for Volkswagen Group platform derivatives. The country's automotive supplier association coordinates REACH compliance documentation standardization. Emerging EV production corridors near Ostrava attract Tier-1 thermal module assembly investments from established European suppliers.
Europe Automotive Battery Thermal Management System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European thermal system supply. Robert Bosch, Continental, and Valeo consolidate high-voltage battery contracts through electronics-thermal convergence capabilities. Component specialists concentrate on heat exchanger fabrication and pump subsystems. Dominant competitive moves include strategic partnerships for dielectric coolant formulation and geographic expansion into Poland and Czechia production corridors.
Within the integrated systems tier, Robert Bosch exemplifies electronics-thermal convergence positioning for German OEM contracts. Valeo occupies a comparable anchor position serving French automaker platforms. BorgWarner represents acquisition-integrated portfolio diversification spanning power electronics and cooling architectures. These three entities sit within distinct national industrial ecosystems yet compete for modular thermal system contracts across shared European EV platforms.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| Valeo |
| BorgWarner |
| Dana |
| Infineon Technologies |
| Gentherm |
| Hanon Systems |
| Webasto Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German OEMs and Nordic aluminum smelters lock in heat exchanger input access while constraining price visibility for Tier-1 module integrators facing F-Gas Regulation compliance deadlines. These contracts transfer commodity volatility risk downstream to suppliers without captive smelter relationships.
Pricing Analysis
Project-based capacity reservation dominates procurement for 800V liquid cooling modules serving premium German EV platforms, with price differentiation driven by REACH certification tier and dielectric coolant formulation complexity. Cost compression in air-cooled systems is intensifying because Netherlands-based urban mobility assemblers prioritize mass reduction over thermal performance. Fleet operators capturing residual value risk show lowest price sensitivity, while Polish contract manufacturers exhibit highest sensitivity due to thin margin structures.
Supply Chain Analysis
Nordic smelter concentration for specialized aluminum alloys exposes heat exchanger fabricators to energy price volatility cascading from regional electricity market dynamics. The supply chain draws from Germany for precision pump subsystems, France for sensor-integrated control electronics, and the Netherlands for dielectric fluid formulation expertise. Single-source vulnerability concentrates in high-purity aluminum supply for cold plate manufacturing. Distribution runs through Tier-1 module integrators consolidating component procurement under single-source accountability frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH compliance documentation and EMA battery passport traceability requirements creates defensive moats for suppliers with closed-loop material certification systems. Switching costs escalate as OEMs qualify thermal modules across multi-year platform cycles.
For Market Incumbents: Fortify dielectric coolant formulation capabilities through backward integration into specialty chemical supply, countering margin pressure from refrigerant phaseout timelines. Deepen sensor-integrated module expertise to defend against emerging power electronics-cooling convergence plays from acquisition-integrated competitors. Prioritize certification investment ahead of delegated acts under the EU Battery Regulation redefining durability testing protocols. For New Entrants and Emerging Players: Anchor in Poland and Czechia EV production corridors where established thermal supplier ecosystems remain underdeveloped and first-mover positioning windows persist. Target module assembly contracts for battery gigafactories sourcing from German Tier-1 ecosystems rather than developing captive capabilities. Pursue go-to-market angles emphasizing closed-loop recyclability certifications aligned with EU Green Deal embodied carbon rules. For Investors and Strategic Acquirers: Algorithm-integrated thermal control specialists with machine learning-enabled predictive cell conditioning capabilities represent the most attractive acquisition target archetype. Long-term viability hinges on software-hardware convergence differentiation becoming table-stakes across commercial fleet specifications. Watch for inflection signals in residual value guarantee contract restructuring as fleet operators consolidate thermal service under battery lifecycle agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Dielectric Coolant Formulation Investment | REACH compliance timelines favor suppliers with captive specialty chemical capabilities ahead of ECHA restriction proposals. |
| Smart Thermal Algorithm Development | Eindhoven's Brainport cluster concentrates machine learning talent for predictive energy management integration. |
| Poland Manufacturing Footprint Expansion | EU cohesion fund allocations accelerate facility permitting near LG Energy Solution's Wrocław complex. |
| Battery Lifecycle Service Contract Bundling | Netherlands and Germany fleet operators compress margins while extending supplier accountability windows. |
| Power Electronics-Thermal Convergence | German OEM 800V architectures demand integrated cooling for inverter-battery systems. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement documentation anchors the qualitative findings on thermal system specification trends. Primary interviews with battery pack design leads, thermal module procurement officers, REACH compliance specialists, and aftermarket service contract managers combine with secondary validation from ECHA substance restriction proposals, KBA durability testing protocols, EU Battery Regulation delegated acts, and IHS Markit vehicle production databases. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across the analysis window.
Sensitivity analysis around charging infrastructure deployment pace and refrigerant phaseout cost curves shapes the analytical framework. Segmentation dimensions modeled include cooling architecture type, voltage class, OEM integration strategy, and regional production cluster. CAGRs derive from installed base evolution and content-per-vehicle trajectories for dielectric fluids, sensors, and control electronics. Forecast inputs incorporate EU Green Deal battery sustainability mandate timelines and F-Gas Regulation steppedown schedules.
Material uncertainties — regulatory effective date delays, coolant additive qualification failures, and aluminum alloy supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions on technology adoption curves and supplier consolidation patterns. Practitioners should keep alternative scenarios live as delegated acts under the EU Battery Regulation and ECHA substance restriction proposals evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
E-Bike Market
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market