
 Global Vehicle to Grid Technology Market | 2026-2036
Global Vehicle to Grid Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vehicle to Grid Technology Market Intelligence
The European Union's Green Deal, with its stringent emissions targets for the transport sector, is shifting the economic calculus for electric vehicle ownership and grid interaction. Nissan Motor Corporation leverages its early lead in V2G-capable vehicles to secure fleet partnerships. Meanwhile, Nuvve Holding Corp. specializes in aggregation software platforms, and Enel X operates extensive charging networks across Europe.
Vehicle to Grid (V2G) technology enables bidirectional energy flow, allowing electric vehicle batteries to discharge power back to the electrical grid. This process relies on specialized bidirectional charging hardware and sophisticated communication protocols to manage charge and discharge cycles for grid services. Within applications, frequency regulation offers the highest value-stacking opportunities for commercial fleet operators and utilities. Bidirectional charging hardware represents the core technology segment, while demand from utilities as end users continues to define system requirements.
Regulatory frameworks from bodies like the US Federal Energy Regulatory Commission (FERC) and standards such as ISO 15118 are critical for market development. Compliance with CE marking in Europe and specific utility interconnection rules in Japan dictates market access and hardware design. The key decision for stakeholders revolves around standardizing communication protocols to ensure interoperability between diverse vehicle models and grid operators.
Market Dynamics
The central force shaping the market is the convergence of utility-driven grid stabilization requirements with the escalating penetration of electric vehicles. This dynamic is creating a new asset class where EV batteries, managed by aggregation software, provide ancillary services, turning idle vehicles into revenue-generating grid resources.
Growth Catalysts
- Policy Incentives:Frameworks like the US Inflation Reduction Act and the EU Green Deal provide tax credits and mandates that lower the cost of bidirectional hardware and encourage commercial fleet electrification, directly stimulating V2G adoption.
- Grid Modernization:Utilities in regions like Germany and California are actively seeking non-wires alternatives for grid balancing and frequency regulation, creating direct demand for the services V2G technology provides.
- Economic Viability for Fleets:For commercial fleet operators, V2G offers a clear value proposition by generating revenue through participation in energy markets, offsetting the total cost of EV ownership and improving asset utilization.
Market Restraints
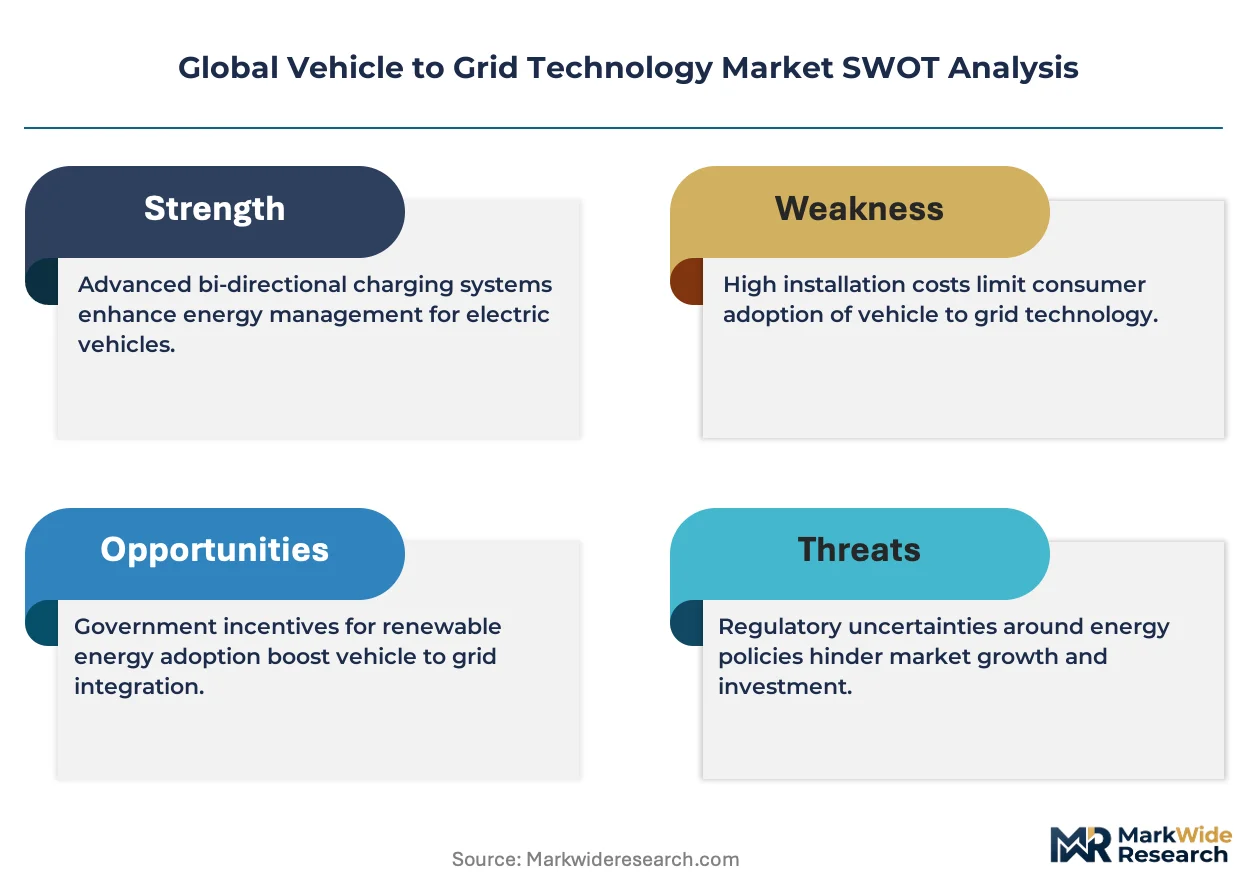
- High Hardware Costs:The initial capital expenditure for bidirectional chargers remains significantly higher than for conventional unidirectional chargers, acting as a primary barrier for individual EV owners and smaller fleet operators.
- Battery Degradation Concerns:Uncertainty and lack of long-term data regarding the impact of frequent, high-power charge and discharge cycles on EV battery longevity deter some vehicle owners and create warranty complexities for automakers.
- Fragmented Standardization:The slow and uneven implementation of communication standards like ISO 15118 across different automotive manufacturers, charger suppliers, and utilities impedes seamless interoperability and market scalability.
Strategic Opportunities
- Vehicle-to-Building/Home (V2B/V2H):Developing solutions for behind-the-meter applications, where EVs power commercial buildings or homes during peak hours, offers a stepping stone to full grid participation with a more straightforward regulatory path.
- Managed Charging Software:Offering sophisticated software-as-a-service (SaaS) platforms that optimize charging schedules for fleets based on electricity prices, grid needs, and vehicle operational requirements represents a high-margin opportunity.
- Expansion in Emerging EV Markets:Targeting countries with rapidly growing EV adoption and grid stability challenges, such as Australia and India, provides a significant avenue for future market expansion beyond established North American and European regions.
Industry Challenges
- Interoperability Complexity:Ensuring seamless communication and control between diverse EV models, multiple charging hardware vendors, and varied utility back-end software systems remains a significant technical and operational hurdle.
- Cybersecurity Vulnerabilities:The networked nature of V2G systems introduces new attack surfaces, requiring robust security protocols to protect vehicles, charging infrastructure, and the electrical grid from potential cyber threats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vehicle to Grid Technology Market |
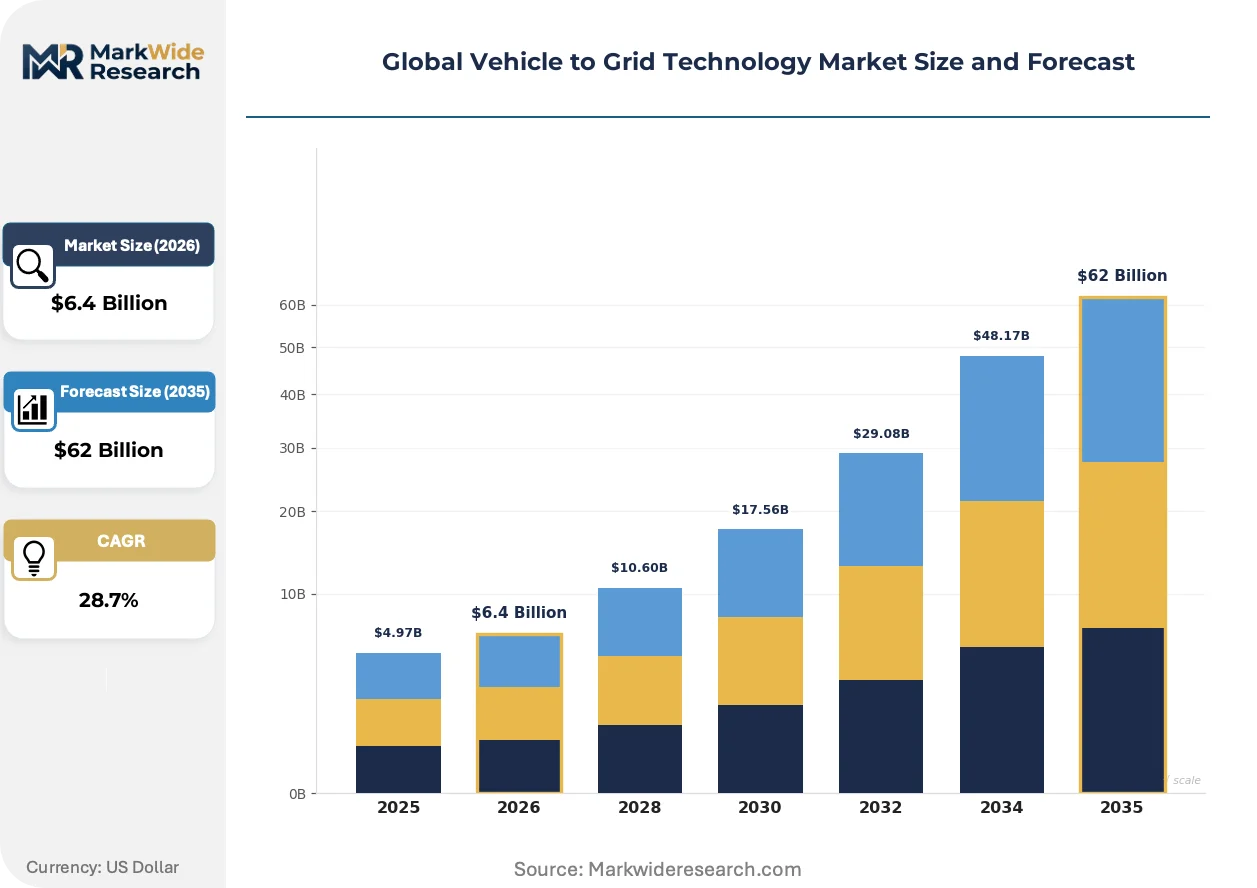
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $62 Billion |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Vehicles, Hybrid Vehicles, Battery Storage Systems, Charging Stations Application: Smart Grids, Renewable Integration, Demand Response, Frequency Regulation End User: Utilities, Transportation Companies, Residential Users, Commercial Enterprises Technology: Bidirectional Charging, Smart Metering, Communication Protocols, Grid Management Systems |
| Companies Covered | Nissan Motor Corporation, BMW Group, Tesla, Inc, General Motors Company, Ford Motor Company, Nuvve Holding Corp., Enel X, ABB Ltd., The Mobility House GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vehicle to Grid Technology Market Strategic Shifts & Innovations
The market is shifting from localized pilot programs to the development of scalable, commercial-grade ecosystems. This evolution is defined by the co-development of intelligent software platforms and advanced hardware capable of meeting stringent utility and automotive requirements for reliability and security.
Bidirectional charging hardware forms the technological core, converting AC power from the grid to DC for the battery and vice-versa. Commercial fleet operators and utilities are the principal adopters, seeking to manage energy costs and improve grid stability. The underlying power electronics architecture is modularizing, enabling scalable deployments and simplifying field service by separating power modules from control and communication units.
Regulatory mandates are creating formal market access for V2G services. The US Federal Energy Regulatory Commission's Order 2222, for instance, requires wholesale energy market operators to allow aggregated Distributed Energy Resources (DERs) to participate. This rule directly benefits V2G aggregators by establishing a pathway to sell grid services. The most affected segment is software providers, who must now develop platforms compliant with complex market participation rules.
A notable behavioral shift is occurring among commercial fleet managers, who now evaluate EV assets based on their potential to generate ancillary service revenue. This disrupts the traditional model of purchasing the lowest-cost charging hardware, creating a preference for vehicles and chargers with native bidirectional capabilities. This trend is most visible in school bus fleets in the United States and last-mile delivery fleets in Europe.
Global Vehicle to Grid Technology Market Segmentation
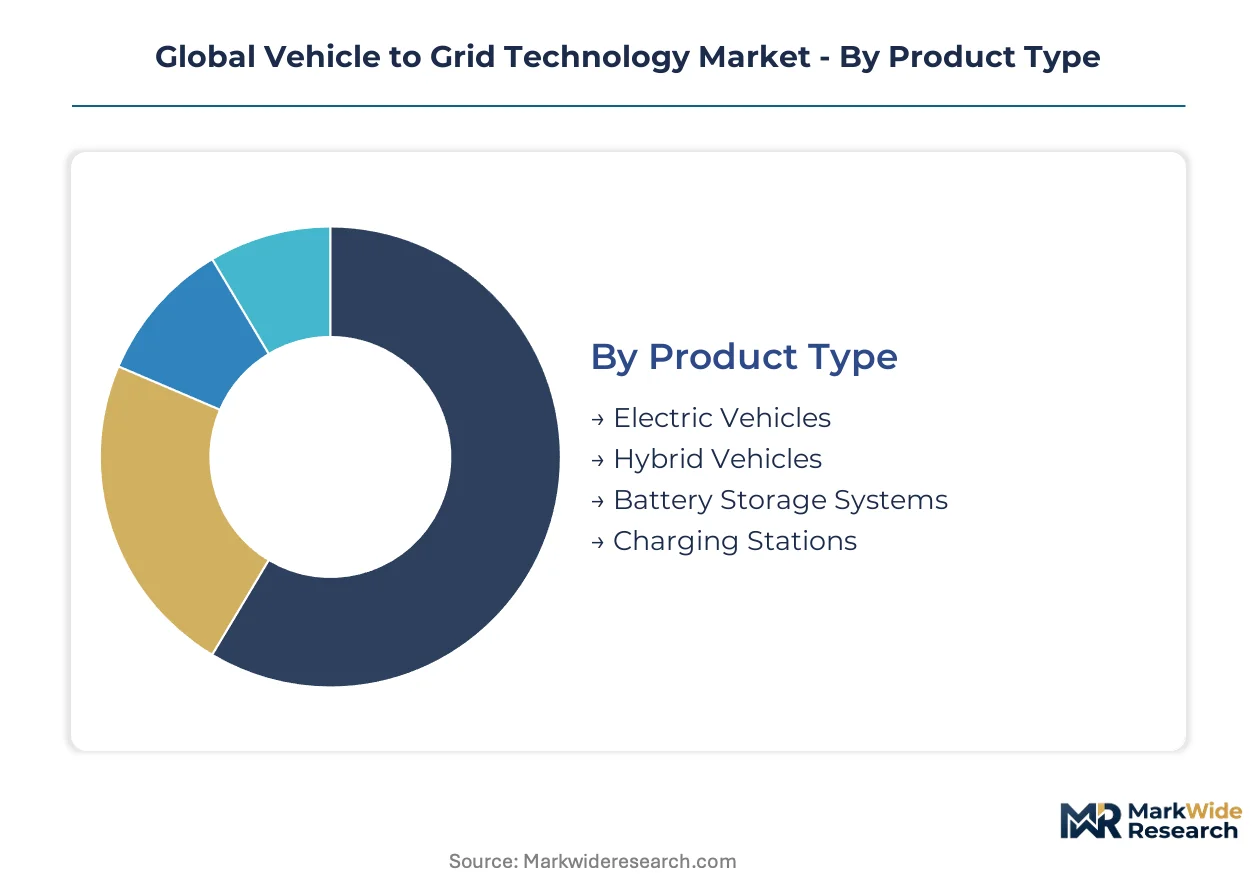
The global Vehicle to Grid (V2G) technology market exhibits diverse operational characteristics across its constituent segments. Understanding these distinctions is critical for stakeholders to optimize product development, target strategic investments, and align with evolving regulatory landscapes and end-user requirements for grid interaction.
Product Type:
The upgrade and replacement cycles for V2G product types are directly linked to electric vehicle adoption rates and grid modernization initiatives.
- Electric Vehicles:These vehicles serve as mobile energy storage units, capable of discharging power back to the grid. Demand for V2G-capable EVs concentrates in Germany and parts of the United States, driven by high EV penetration and supportive policy frameworks like the US Inflation Reduction Act.
- Charging Stations:Specialized bidirectional charging hardware forms the physical interface for V2G, converting AC power from the grid to DC for the battery and vice-versa. Utilities and commercial fleet operators are the principal adopters, seeking to manage energy costs and improve grid stability.
- Hybrid Vehicles:Hybrid vehicles, while featuring smaller battery capacities, can still contribute to localized grid support services, particularly in urban environments with developing V2G infrastructure.
- Battery Storage Systems:Dedicated stationary battery storage systems complement V2G by providing additional grid resilience and balancing capabilities, enhancing overall energy management.
Volume placements concentrate in Electric Vehicles; the faster expansion belongs to Charging Stations.
Application:
Different applications serve distinct operational needs for grid operators and fleet managers, influencing V2G technology deployment priorities.
- Frequency Regulation:This application offers the highest value-stacking opportunities for commercial fleet operators and utilities. It involves rapid, precise adjustments to grid frequency to maintain stability, a critical service for modern electricity networks.
- Smart Grids:V2G technology integrates with advanced smart grid infrastructure to optimize energy flow and manage distributed energy resources. This supports grid modernization efforts in regions like California, enhancing overall system efficiency.
- Demand Response:V2G enables electric vehicles to reduce or shift charging during periods of high electricity demand, alleviating strain on the electrical grid and preventing peak load events.
- Renewable Integration:V2G helps stabilize grids by absorbing excess renewable energy during high generation periods and discharging it when renewable output is low, facilitating greater penetration of intermittent sources.
The utility sector prioritizes Frequency Regulation for grid stability, while fleet operators leverage Demand Response for operational cost reduction and new revenue streams.
End User:
The revenue potential from V2G varies significantly across different end-user segments, reflecting diverse operational models and regulatory environments.
- Utilities:Utilities are primary drivers of V2G adoption, seeking solutions for grid stabilization, frequency regulation, and non-wires alternatives. Their demand continues to define system requirements, particularly in regions like Germany.
- Transportation Companies:Commercial fleet operators utilize V2G to generate revenue by participating in energy markets, offsetting the total cost of EV ownership. This trend is prominent in school bus fleets in the United States and last-mile delivery fleets in Europe.
- Commercial Enterprises:Businesses employ V2G for behind-the-meter applications, enabling EVs to power commercial buildings during peak hours and reduce electricity expenses.
- Residential Users:Individual EV owners can participate in V2G programs to earn incentives or provide backup power for their homes, though initial hardware costs remain a significant barrier.
Grid operators consistently seek solutions for Utilities, whereas Transportation Companies focus on operational cost reduction and new revenue streams.
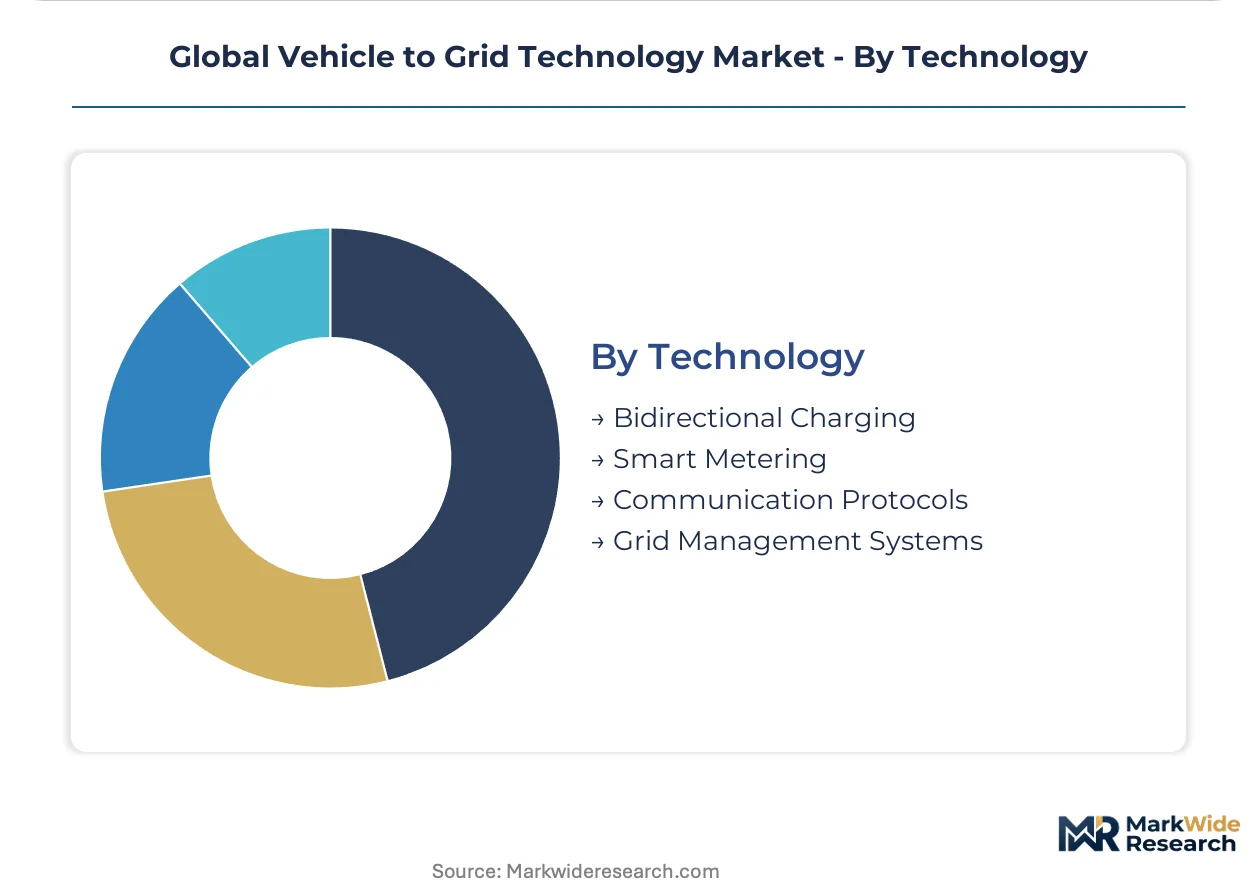
Technology:
Interoperability challenges and evolving standards influence the development and adoption trajectory of various V2G technologies.
- Bidirectional Charging:This hardware forms the technological core of V2G, enabling power flow from the grid to the vehicle battery and vice-versa. Its modular power electronics architecture supports scalable deployments for diverse applications.
- Communication Protocols:Standards such as ISO 15118 are critical for ensuring seamless interoperability between diverse EV models, charging hardware vendors, and grid operators. Regulatory compliance dictates market access and hardware design.
- Smart Metering:Smart meters are essential for accurately measuring energy flows and enabling billing mechanisms for V2G services. They facilitate efficient participation in energy markets.
- Grid Management Systems:These sophisticated software platforms optimize V2G operations, aggregating distributed energy resources for grid services and intelligently managing charge and discharge schedules.
The foundational hardware for V2G depends on Bidirectional Charging, while market scalability hinges on robust development in Communication Protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's automotive innovation hub drives significant V2G development in Europe. This concentration of advanced manufacturing and energy research fosters early adoption of bidirectional charging solutions. Policy support across multiple continents further accelerates market expansion.
Germany
Demand for V2G-capable electric vehicles is strong in Germany, driven by high EV penetration and grid modernization efforts. The European Union's Green Deal provides a supportive regulatory framework for sustainable transport. Automotive manufacturing centers in Bavaria actively pilot V2G solutions with local utilities.
United States
The United States sees growing demand for V2G in grid balancing and commercial fleet electrification, particularly in states with high renewable energy. The US Inflation Reduction Act provides tax credits, lowering bidirectional hardware costs. California's energy market, influenced by FERC Order 2222, shows active V2G aggregation.
Japan
Japanese utilities are exploring V2G technology for enhanced grid stability and efficient energy management, supported by disaster resilience efforts. METI regulations and utility interconnection rules dictate hardware design and market access. Smart grid initiatives in the Tokyo metropolitan area integrate V2G for demand response.
Australia
Australia offers significant V2G opportunity due to rapid EV adoption and grid stability challenges from high renewable energy penetration. The Australian Energy Market Operator (AEMO) explores V2G's role in grid services. Projects in South Australia integrate V2G with solar and wind farms for enhanced local grid resilience.
India
India's escalating electric vehicle adoption creates strong impetus for V2G technology, managing grid loads and improving energy security. The country's PLI scheme for automotive and battery manufacturing supports V2G-capable vehicles. Major smart city projects in Delhi are piloting V2G applications for public transport fleets.
Global Vehicle to Grid Technology Market Key Industry Players
The competitive structure tilts toward a blend of established automotive manufacturers and specialized energy technology providers. The market is moderately fragmented, with distinct capabilities required across vehicle manufacturing, charging hardware, and grid integration software. Automotive OEMs focus on embedding V2G capabilities into their vehicles, while energy firms develop aggregation platforms and bidirectional charging solutions. Strategic partnerships between these diverse entities and geographic expansion are common competitive moves.
Within the automotive OEM tier, Nissan Motor Corporation represents an early mover in V2G-capable vehicles, leveraging its established manufacturing base to secure fleet partnerships. Nuvve Holding Corp., a US-based firm, exemplifies the software-centric approach, specializing in aggregation platforms that optimize charge and discharge cycles for grid services. Enel X, an Italian-headquartered energy services company, occupies a significant position in the charging network segment across Europe, integrating V2G solutions into its extensive infrastructure and expanding its utility partnerships.
| Leading Market Players |
|---|
| Nissan Motor Corporation |
| BMW Group |
| Tesla, Inc |
| General Motors Company |
| Ford Motor Company |
| Nuvve Holding Corp. |
| Enel X |
| ABB Ltd. |
| The Mobility House GmbH |
| Others |
Cost & Logistics Intelligence
Vertical integration by automotive OEMs into V2G-capable vehicles and by energy firms into charging infrastructure anchors supply positions and influences pricing power. This strategic alignment aims to control critical components and service delivery within the nascent V2G ecosystem.
Pricing Analysis
Outcome-based pricing for V2G services, particularly frequency regulation and demand response, anchors value propositions for utilities and fleet operators. Price differentiation stems from hardware certification levels like ISO 15118 compliance and the sophistication of aggregation software platforms. Pricing pressure on bidirectional charging hardware originates from high initial capital expenditures, which deter individual EV owners. Utilities and large commercial fleets exhibit lower price sensitivity when V2G offers clear grid stabilization and revenue-generating opportunities.
Supply Chain Analysis
Regional distribution centers and specialized logistics networks manage the flow of V2G hardware and components across major markets. Supply for bidirectional charging hardware concentrates in automotive manufacturing hubs like Germany and East Asian electronics suppliers, drawing from critical power electronics and advanced battery cells. Single-source vulnerability for specific semiconductor components represents a structural supply chain risk. Distribution runs through OEM dealerships for V2G-capable vehicles and direct sales channels to utilities and commercial fleet operators for charging infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vehicle to Grid technology market is poised for consolidation, driven by the intense capital requirements for developing advanced bidirectional hardware and sophisticated software platforms. This financial pressure will likely force smaller, undercapitalized players to exit or be acquired.
For Market Incumbents: Extend existing automotive and energy infrastructure by integrating V2G capabilities as a standard offering to counter fragmented standardization. Nissan Motor Corporation can deepen its fleet partnerships by offering comprehensive V2G service packages, including financing for bidirectional charging. Investing in advanced power electronics R&D and securing ISO 15118 compliance across all product lines will mitigate the threat from emerging specialized hardware providers.
For New Entrants and Emerging Players: Price-point gaps exist between premium utility-grade V2G solutions and more accessible residential or small commercial offerings. New entrants should target the Vehicle-to-Building (V2B) and Vehicle-to-Home (V2H) segments, which have a more straightforward regulatory path than full grid participation. Australia, with its rapid EV adoption and grid stability challenges, represents a penetrable geography. A software-as-a-service (SaaS) model for managed charging, optimizing for local electricity prices, offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized software aggregators and advanced power electronics manufacturers, offering strategic value in a 5-10 year horizon. Investors should prioritize companies like Nuvve Holding Corp. that possess scalable platforms for managing diverse V2G assets. A significant increase in utility-led V2G pilot programs transitioning to commercial deployments, particularly in Germany and California, signals market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating V2G software with existing smart grid systems enhances overall grid management capabilities for utilities. |
| Strategic Partnership | Forming alliances between automotive OEMs and energy service providers accelerates V2G market development and deployment. |
| Geographic Expansion | Targeting emerging EV markets like Australia and India diversifies revenue streams and leverages new policy incentives. |
| Product Launch | Introducing new bidirectional charging hardware compliant with ISO 15118 standards improves interoperability across the ecosystem. |
| Technology Licensing | Licensing V2G communication protocols to smaller manufacturers promotes wider adoption and standardization within the industry. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, complemented by primary interviews with industry stakeholders. Researchers engaged utility planning officers, commercial fleet managers, automotive R&D leads, and charging infrastructure developers. This approach combined bottom-up data collection from market participants with top-down validation from national energy agency reports and EU Green Deal documents.
Market sizing and forecasts were modeled at granular levels across product type, application, end-user, technology, and regional policy environments. Compound annual growth rates were derived from historical trends and expert projections, integrating electric vehicle penetration rates and grid modernization investments across the analysis window. This framework accounts for evolving regulatory landscapes.
Inputs from public financial disclosures and industry reports were available through the study window; gaps in long-term battery degradation data introduce uncertainty bands. Forecasts reflect assumptions regarding V2G standardization progress and cybersecurity threat mitigation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
China Electric Bus Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
E-Bike Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Foldable Electric Vehicle Market