
 Electric Vehicle Battery Trays Market | 2026-2036
Electric Vehicle Battery Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Trays Market Insights
UN ECE R100 certification is unwinding the competitive landscape for battery tray suppliers, forcing tier-one manufacturers to redesign thermal management interfaces before homologation. Novelis leverages its closed-loop aluminum recycling network to secure virgin-grade sheet supply for tray stampings across North American EV platforms. Constellium sustains aerospace-derived alloy formulations that shave kilograms from passenger vehicle underfloor assemblies without sacrificing crashworthiness.
An electric vehicle battery tray is a structural chassis-mounted enclosure, typically fabricated from 5000 or 6000 series aluminum extrusions or glass-fiber-reinforced thermoplastic composites, designed to house cylindrical or prismatic cells while managing thermal runaway propagation and distributing collision loads. Aluminum extrusion dominates high-volume passenger vehicle programs where torsional stiffness requirements exceed 25,000 Nm/degree, while composite solutions anchor premium architectures seeking 30-40% mass reduction over metallic baselines. Die casting competes aggressively for integrated tray-housing combinations that consolidate 20+ stamped parts into single aluminum castings, though stamping retains cost advantages in economy and mid-market vehicle segments.
FDA-adjacent thermal barrier standards do not apply here; instead, NHTSA's FMVSS 305 electrical safety protocols and China's GB/T 31467 battery abuse testing regimes dictate tray penetration resistance and fire containment thresholds. EMA's alignment with UNECE frameworks ensures European OEMs demand identical crash-test documentation from tray suppliers across multiple production sites. Stakeholders must monitor how solid-state cell formats, with their thicker pack architectures, force tray depth and cooling channel redesigns before committing to next-generation tooling investments.
Market Dynamics
Aluminum alloy supply concentration in Chinese smelter networks is forcing tray manufacturers to redesign sourcing strategies around virgin-grade sheet availability and closed-loop recycling partnerships.
Growth Catalysts
- Cell-to-Pack Architectures:OEM elimination of module housings reduces tray complexity while increasing structural load requirements on the enclosure itself.
- ECE R100 Revisions:Europe's updated homologation standards mandate enhanced thermal runaway containment, accelerating demand for integrated fire-barrier tray designs.
- Die Casting Scale-Up:6,000-ton press installations across automotive supplier parks enable single-piece aluminum tray-housing consolidation previously impossible with stamping.
Market Restraints
- Magnesium Price Volatility:Tray lightweighting alloys containing magnesium face input cost swings tied to Chinese export quota policies.
- Tooling Lead Times:Large-format die casting molds for integrated trays require 18-24 month development cycles, freezing design iterations mid-program.
- Glass-Fiber Composite Substitution:Premium OEMs pilot thermoplastic tray alternatives that threaten aluminum's dominance in mass-sensitive platforms above 100 kWh pack capacity.
Strategic Opportunities
- Solid-State Cell Formats:Thicker prismatic architectures demand deeper tray cavities with redesigned cooling channel geometry, creating first-mover tooling advantages.
- India's PLI Scheme:Localized cell manufacturing incentives under the government's production-linked incentive framework will require domestic tray supply base development.
- Closed-Loop Recycling Mandates:EU battery passport regulations position aluminum recyclers with automotive-grade scrap sorting capabilities as preferred tier-two suppliers.
Industry Challenges
- Multi-Material Joining Expertise:Hybrid tray designs combining aluminum extrusions with composite inserts lack standardized adhesive and mechanical fastening protocols.
- Homologation Testing Bottlenecks:UN ECE R100 certification queues at European notified bodies extend program timelines for tray suppliers serving multiple OEM platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Trays Market |
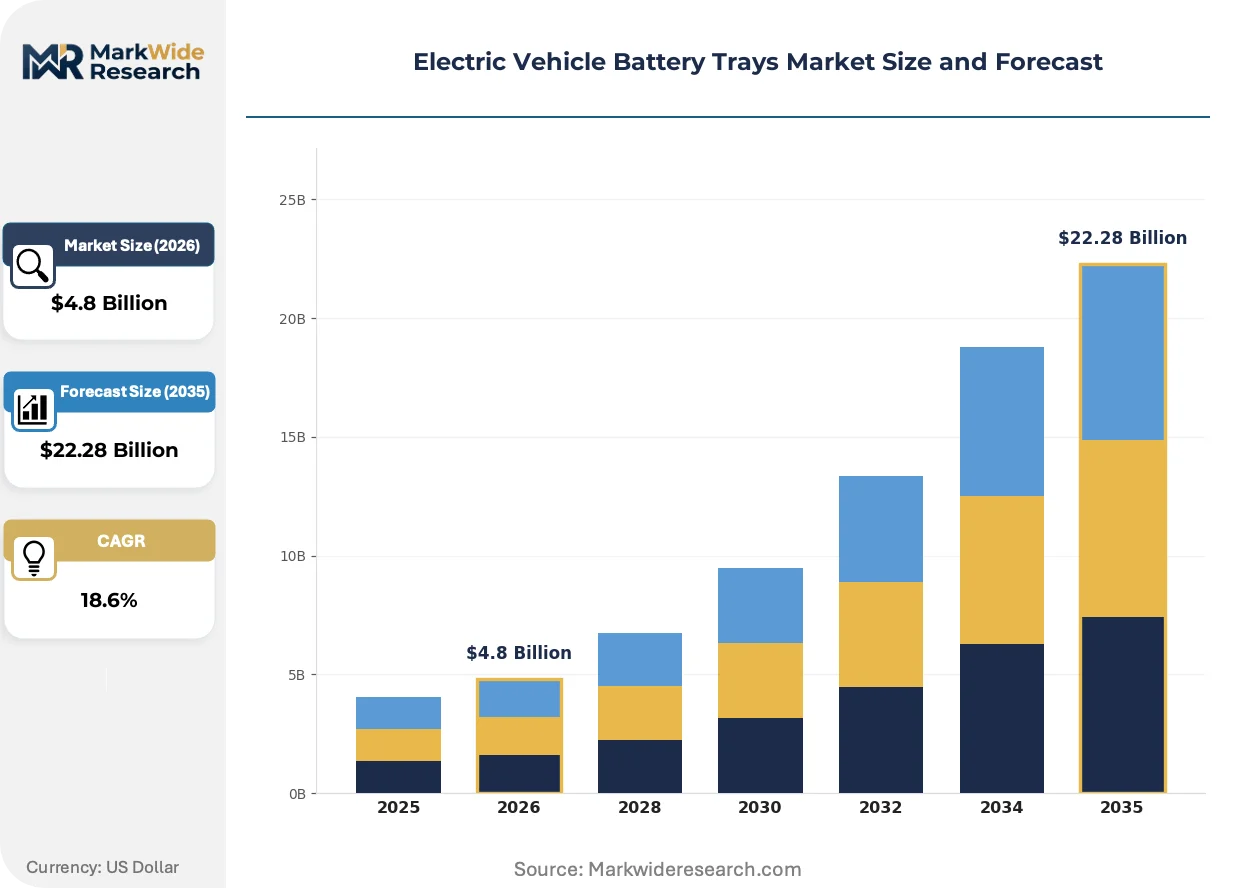
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Composite, Plastic Manufacturing Process: Die Casting, Injection Molding, Stamping, Extrusion Application Area: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses End User: OEMs, Aftermarket, Fleet Operators, Automotive Suppliers |
| Companies Covered | Minth Group, Novelis, Nemak, SGL Carbon, Constellium, Gestamp, Hitachi Metals, Guangdong Hoshion Aluminium, Benteler International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Trays Market Trends and Innovations
Thermal management integration is compressing the boundary between battery trays and cooling hardware, while regulatory pressure on recyclability forces material traceability systems into supplier specifications.
Aluminum extrusion is bifurcating the tray market into high-stiffness passenger vehicle programs and cost-optimized commercial vehicle applications. European OEMs specify 6000-series alloys with 25,000 Nm/degree torsional targets for premium electric sedans. Asian manufacturers serving fleet van platforms accept 5000-series alternatives at 40% lower specific alloy premiums, compressing margin structures for suppliers without grade-flexible casting capacity.
China's NMPA safety protocols now require nail penetration testing documentation for tray designs housing cells above 150 Wh/kg energy density. The regulation forces structural reinforcement in floorpan-adjacent regions previously optimized for weight reduction. Korean and Japanese cell suppliers serving Chinese OEMs must redesign pack interfaces to accommodate thicker tray bottom plates, extending homologation cycles by 6-8 months.
Fleet operators now specify tray replaceability clauses in battery lease agreements, unbundling the enclosure from cell asset ownership. Commercial vehicle financiers in Germany and the Netherlands demand modular tray architectures permitting field replacement without pack disassembly. This contractual shift forces tray suppliers to design mechanical interfaces compatible with third-party service networks rather than OEM-captive tooling.
Electric Vehicle Battery Trays Market Segmentation
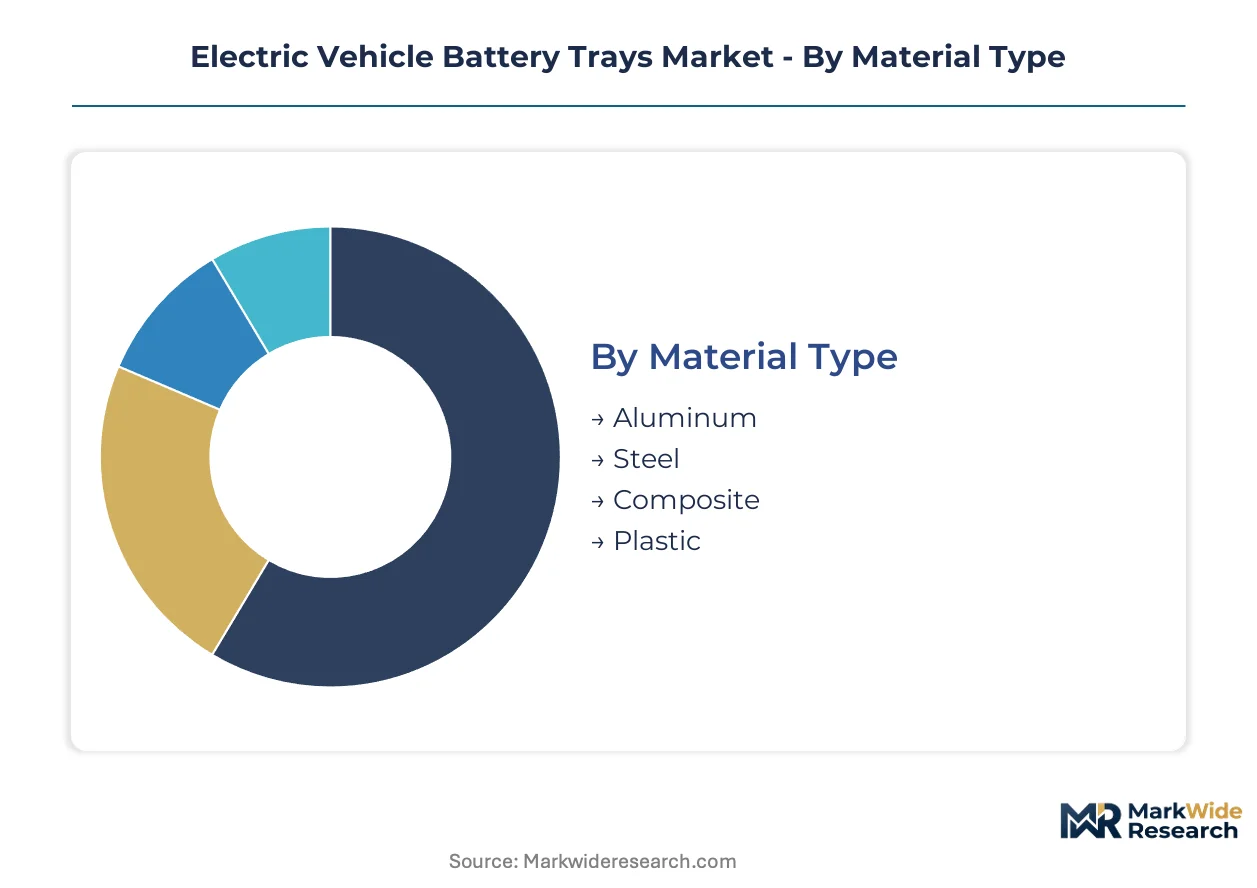
Material selection and manufacturing method determine compliance pathways with UN ECE R100 and China's GB/T standards. OEMs segment procurement across stiffness requirements, thermal runaway containment, and recyclability mandates.
Material Type:
Regulatory differentiation in crashworthiness and fire containment thresholds splits material adoption across passenger and commercial platforms. ECE R100 revisions favor aluminum's thermal conductivity for runaway management, while composite solutions target premium mass reduction.
- Aluminum:5000 and 6000 series alloys dominate high-volume programs requiring torsional stiffness above 25,000 Nm/degree. European OEMs in Germany's automotive corridor specify aerospace-derived formulations from Constellium for underfloor assemblies balancing crashworthiness with weight reduction.
- Composite:Glass-fiber-reinforced thermoplastics deliver 30-40% mass reduction over metallic baselines in premium architectures above 100 kWh pack capacity. Korean cell suppliers redesign pack interfaces to accommodate thicker composite trays for Chinese OEMs under NMPA nail penetration protocols.
- Steel:Cost-optimized commercial vehicle applications in India's emerging EV supply base leverage high-strength grades for fleet van platforms.
- Plastic:Secondary enclosure components and non-structural inserts in economy passenger segments where metal substitution reduces assembly complexity.
Aluminum handles the majority of throughput; composite is expanding most quickly on share as solid-state architectures demand deeper, lighter cavities.
Manufacturing Process:
Cost tier separation between integrated single-piece solutions and multi-part assemblies drives process selection. Die casting commands premium positioning for consolidated tray-housing combinations, while stamping retains mid-market dominance.
- Die Casting:6,000-ton press installations enable single-piece aluminum tray-housing consolidation replacing 20+ stamped components. Tooling lead times of 18-24 months freeze design iterations mid-program, favoring suppliers with captive casting capacity.
- Extrusion:Aluminum extrusion bifurcates between high-stiffness passenger vehicle programs and cost-optimized commercial applications. Asian manufacturers serving fleet van platforms accept 5000-series alternatives at lower alloy premiums.
- Stamping:Retains cost advantages in economy and mid-market vehicle segments where torsional requirements permit multi-part assembly.
- Injection Molding:Thermoplastic tray production for composite-intensive premium platforms seeking field-replaceable modular architectures.
Die casting captures the steepest expansion trajectory as Cell-to-Pack architectures eliminate module housings; stamping maintains volume leadership in price-sensitive segments.
Application Area:
Vehicle class determines structural load specifications and thermal management integration depth. Passenger vehicles prioritize torsional rigidity; commercial platforms emphasize serviceability and lease-compatible replaceability.
- Passenger Vehicles:OEM procurement concentrates in Germany where Volkswagen, BMW, and Mercedes-Benz anchor supplier relationships with tray specialists. Floorpan-adjacent structural reinforcement now required under China's NMPA protocols for cells above 150 Wh/kg energy density.
- Commercial Vehicles:Fleet operators in Germany and the Netherlands specify modular tray architectures permitting field replacement without pack disassembly. Battery lease agreements unbundle enclosures from cell asset ownership.
- Buses:High-floor mounting configurations with standardized pack dimensions across municipal procurement contracts.
- Two-Wheelers:Simplified tray geometries for removable battery formats in India's PLI-supported localized manufacturing.
Passenger vehicles generate dominant revenue share; commercial vehicles are climbing the fastest as fleet electrification accelerates.
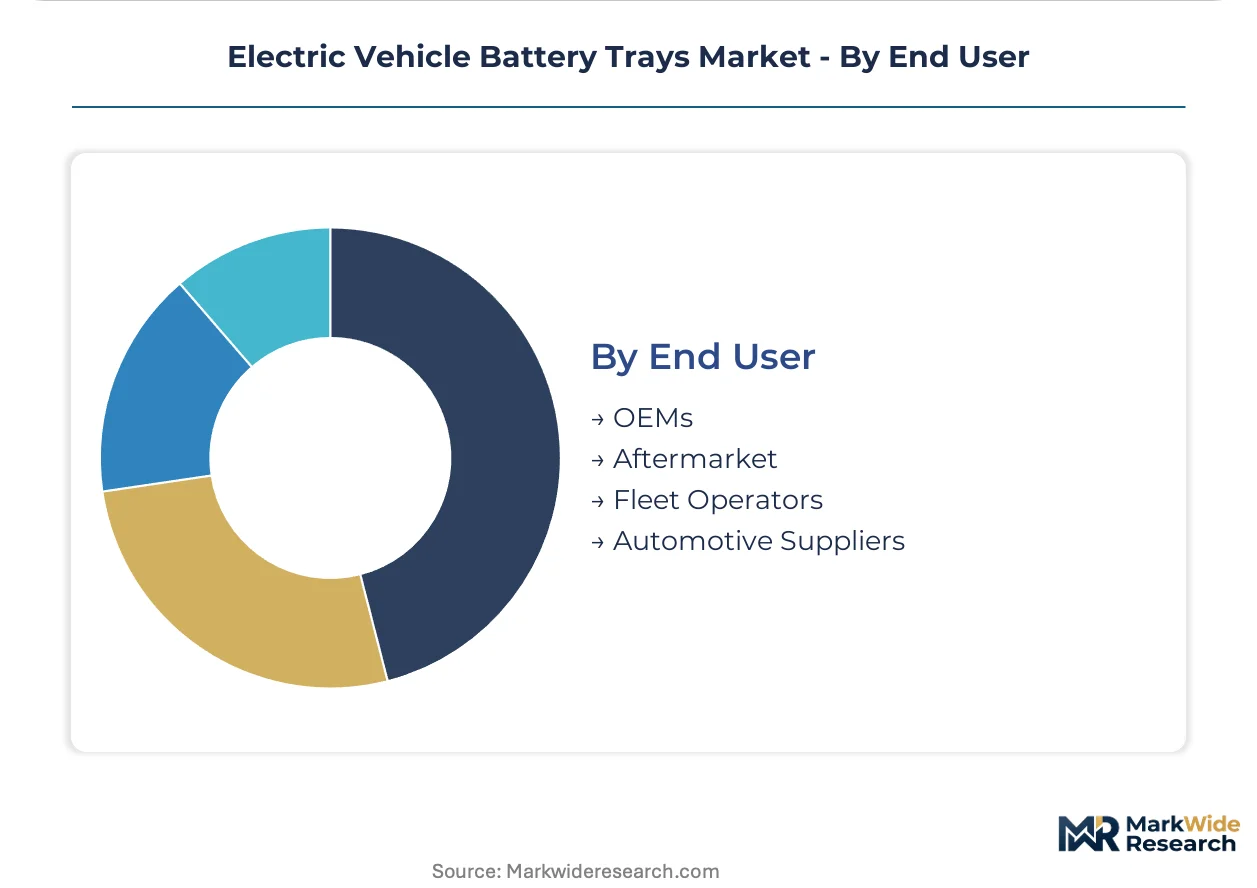
End User:
Customer type dictates design iteration speed, homologation documentation requirements, and aftermarket service network compatibility. OEMs demand crash-test documentation across multiple production sites; fleet operators force standardization for third-party service access.
- OEMs:Direct procurement relationships with tier-one tray manufacturers require UN ECE R100 certification queues at European notified bodies, extending program timelines. EMA alignment with UNECE frameworks ensures identical documentation demands across production sites.
- Fleet Operators:Commercial vehicle financiers demand mechanical interfaces compatible with third-party service networks rather than OEM-captive tooling. Replaceability clauses in battery lease agreements reshape tray architecture specifications.
- Automotive Suppliers:Tier-one manufacturers redesign thermal management interfaces before homologation as certification standards tighten.
- Aftermarket:Emerging segment for crash replacement and upgrade pathways as early EV platforms age out of warranty coverage.
OEMs command absolute volume concentration; fleet operators are gaining share fastest as commercial electrification scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in EV battery tray logistics, while China's Yangshan Deepwater Port anchors Asia-Pacific supply chains for aluminum alloy feedstock.
China
CATL and BYD's gigafactory expansions in Ningde and Shenzhen drive tray demand for cell-to-pack architectures. NMPA's nail penetration protocols for cells above 150 Wh/kg force structural reinforcement redesigns. The Yangtze River Delta cluster hosts Novelis and Nemak production facilities serving domestic OEM procurement.
Germany
Volkswagen, BMW, and Mercedes-Benz anchor supplier relationships with tray specialists in Baden-Württemberg and Lower Saxony. KBA enforces UN ECE R100 certification timelines that extend homologation cycles. The Stuttgart manufacturing corridor concentrates aerospace-grade aluminum formulation expertise from Constellium.
United States
Detroit Three electrification programs and Tesla's Texas operations sustain North American tray procurement. NHTSA's FMVSS 305 electrical safety protocols govern penetration resistance thresholds. Michigan's automotive supplier parks host die-casting capacity for integrated tray-housing consolidation.
South Korea
LG Energy Solution and Samsung SDI's prismatic cell output necessitates tray redesigns for thicker pack geometries. MFDS alignment with international battery safety frameworks ensures export compatibility. The Busan-Ulsan industrial belt concentrates aluminum extrusion capacity for Hyundai-Kia platforms.
India
Tata Motors and Mahindra's EV ramp-ups coincide with PLI scheme incentives for localized cell manufacturing. BIS standards for battery enclosure integrity are converging with UN ECE frameworks. The Tamil Nadu-Gujarat manufacturing corridor attracts tray suppliers establishing domestic production.
Electric Vehicle Battery Trays Market Competitive Landscape
Listed leaders compete with private specialists across capital access and agility dimensions. The vendor base splits between integrated aluminum producers with captive recycling networks and independent fabricators serving regional OEM clusters. Three archetypes dominate: closed-loop recyclers, die-casting scale operators, and composite material specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as tooling lead times freeze design commitments.
Among aluminum-centric producers, Novelis and Constellium occupy positions as integrated material suppliers with automotive-grade formulation expertise, while Nemak exemplifies the die-casting scale archetype with large-format press installations. Guangdong Hoshion Aluminium represents the Asia-Pacific fabrication specialist tier serving cost-optimized commercial vehicle platforms.
| Leading Market Players |
|---|
| Minth Group |
| Novelis |
| Nemak |
| SGL Carbon |
| Constellium |
| Gestamp |
| Hitachi Metals |
| Guangdong Hoshion Aluminium |
| Benteler International |
| Others |
Pricing and Supply Chain Analysis
Large-format die casting press utilization rates above 85% in Germany's automotive corridor compress unit economics for integrated tray-housing combinations while simultaneously elevating entry barriers for suppliers lacking captive 6,000-ton capacity. This scale concentration permits tier-one manufacturers to command premium positioning for ECE R100-certified designs while forcing stampers in cost-optimized segments toward thinner margin structures.
Pricing Analysis
Certification level creates the primary spread between tray suppliers, with UN ECE R100 homologation adding substantial premiums over GB/T-compliant alternatives for Chinese domestic programs. Three-tier pricing structure separates aerospace-grade 6000-series formulations from 5000-series commercial grades and emerging thermoplastic alternatives. Cost compression in mid-market stamping segments is intensifying because Asian fleet van manufacturers accept lower torsional specifications. Fleet operators in Germany demonstrate least price sensitivity due to lease-backed replaceability requirements, while Indian PLI-scheme entrants face acute budget constraints.
Supply Chain Analysis
Just-in-time aluminum sheet delivery dominates European passenger vehicle programs, whereas Chinese cell-to-pack expansions favor strategic stockpiling of virgin-grade 6000-series alloys ahead of NMPA protocol enforcement. Primary supply concentrates in China, Germany, and South Korea, with the Yangtze River Delta hosting Novelis and Nemak facilities. Raw material dependencies center on primary aluminum smelter output, magnesium alloying elements, and glass-fiber thermoplastic feedstock. Single-source vulnerability runs through Chinese magnesium export quotas. Distribution runs through OEM-captive tier-one supplier networks with limited third-party aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tray replaceability clauses in German and Dutch battery lease agreements are expanding field-service revenue pools faster than hardware manufacturing margins, transforming enclosure economics toward recurring-revenue models.
For Market Incumbents: Shield core OEM relationships by accelerating closed-loop recycling certification ahead of EU battery passport mandates. Backward integration into aluminum scrap sorting capabilities secures preferred tier-two positioning under tightening traceability requirements. Defensive capacity additions in India's Tamil Nadu-Gujarat corridor preempt PLI-scheme localization demands from Tata Motors and Mahindra. For New Entrants and Emerging Players: Lead with solid-state cell format tooling investments targeting deeper tray cavity geometries before incumbent die casting commitments freeze. India's emerging EV supply base offers the most penetrable geography given nascent domestic tray production. A go-to-market angle anchored in field-replaceable modular architectures aligns with fleet operator procurement specifications in Germany and the Netherlands. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors die-casting scale operators with 6,000-ton press installations over extrusion-dependent fabricators facing Cell-to-Pack displacement. Long-term viability hinges on recycling network control rather than primary aluminum access. The acquisition target archetype combines automotive-grade alloy formulation with automotive scrap sorting capabilities. Watch for solid-state cell thickness specifications crossing 40mm thresholds as the inflection indicator forcing wholesale tray redesigns.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Transition | Eliminates module housings and concentrates structural load requirements on tray enclosures themselves. |
| Closed-Loop Recycling Certification | EU battery passport regulations position scrap-sorting recyclers as preferred tier-two suppliers to OEMs. |
| Large-Format Die Casting Scale-Up | 6,000-ton press installations enable single-piece tray-housing consolidation replacing 20+ stamped components. |
| Solid-State Cell Format Tooling | Thicker prismatic architectures demand deeper cavities with redesigned cooling channel geometry. |
| Field-Replaceable Modular Design | Fleet lease agreements in Germany and the Netherlands unbundle enclosures from cell asset ownership. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement directors, aftermarket service network operators, and aluminum alloy formulation specialists, then refined against secondary validation. Primary fieldwork combined structured interviews with thermal management interface designers and homologation documentation specialists. Secondary sources included UN ECE R100 certification records, NMPA nail penetration test protocols, vehicle production databases, and customs trade flows for aluminum alloy grades. Bottom-up tray demand estimates triangulated against top-down EV production forecasts.
Variance decomposition across the projection horizon isolates volume drivers from pricing and mix effects. Segmentation dimensions modeled include material type, manufacturing process, vehicle class, pack energy density tier, and regional regulatory cluster. CAGRs derive from logistic growth curve fitting anchored to OEM platform launch timelines and cell supplier capacity announcements. Industry-specific inputs incorporate Cell-to-Pack adoption curves and solid-state cell format transition probabilities.
Forecasts assume regulatory continuity in UN ECE R100, China's NMPA, and India's BIS regimes; material policy shifts would require re-modeling. Specific risks include magnesium export quota disruptions, homologation testing bottlenecks at European notified bodies, and premature solid-state commercialization forcing tooling obsolescence. Revision becomes warranted when solid-state cell thickness specifications or recycling mandate enforcement timelines cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market