
 Agricultural Electric Vehicles Market | 2026-2036
Agricultural Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Electric Vehicles Market Analysis
High-voltage battery architecture with modular pack designs is reconfiguring how agricultural OEMs engineer frame layouts and weight distribution for field equipment. John Deere leverages its precision agriculture ecosystem to anchor customer loyalty through integrated telematics and autonomous-ready electric platforms. CNH Industrial sustains competitive pressure through dedicated R&D centers in Italy and the United States focused on electrified drivelines for heavy tillage applications. Monarch specializes in compact electric tractors with swappable battery systems, occupying the vineyard and orchard niche where maneuverability outweighs horsepower ratings.
Agricultural electric vehicles are self-propelled machines engineered for crop and livestock operations, utilizing battery-electric, plug-in hybrid, or hydrogen fuel cell powertrains with torque outputs typically ranging from 50 to 400 horsepower-equivalent for primary field tasks. These systems replace internal combustion engines to reduce on-farm emissions, cut fuel expenditures, and enable precision-controlled power delivery for implements and autonomous functions. Battery electric tractors currently lead unit shipments due to falling lithium-ion cell costs and established charging infrastructure, while hydrogen fuel cell configurations represent the fastest-growing technology segment for high-horsepower row-crop applications where runtime demands exceed pure-electric feasibility. Utility vehicles command disproportionate margin pools because of shorter replacement cycles and lower engineering barriers that attract specialty manufacturers.
The EPA regulates off-road emissions under Tier 4 Final and emerging zero-emission mandates, compelling manufacturers to certify electric powertrains or face restricted market access in the United States. REACH and the EU Green Deal framework in Europe impose chemical disclosure and carbon-intensity thresholds on battery supply chains and imported equipment. Stakeholders must monitor how divergent certification timelines between the EPA and EMA reshape product development roadmaps and determine which powertrain architectures achieve cross-border scale economics first.
Market Dynamics
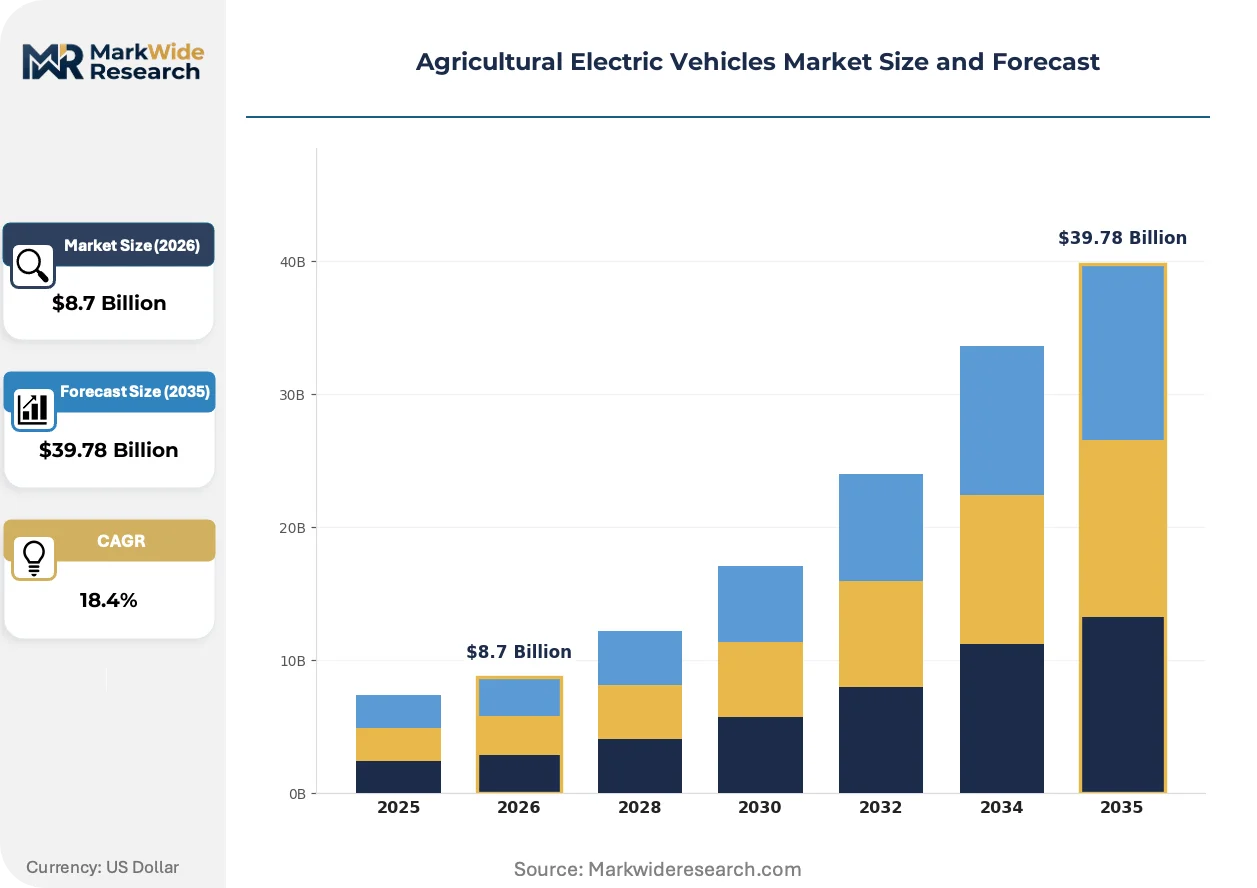
Diesel cost volatility is compressing operating margins across grain operations, forcing capital allocation toward battery-electric tractors with predictable energy economics. Tier 4 Final compliance costs and emerging zero-emission mandates are simultaneously accelerating OEM powertrain diversification.
Growth Catalysts
- EPA Tier 4 Final and zero-emission mandates:Regulatory pressure on off-road equipment emissions is compelling fleet operators to electrify heavy tillage machinery ahead of compliance deadlines.
- Falling lithium-ion cell costs:Battery pack economics now support commercial viability for 200+ horsepower-equivalent tractors in row-crop applications.
- German farm electrification subsidies:National incentive programs are pulling channel inventory toward electric utility vehicles and precision sprayers.
Market Restraints
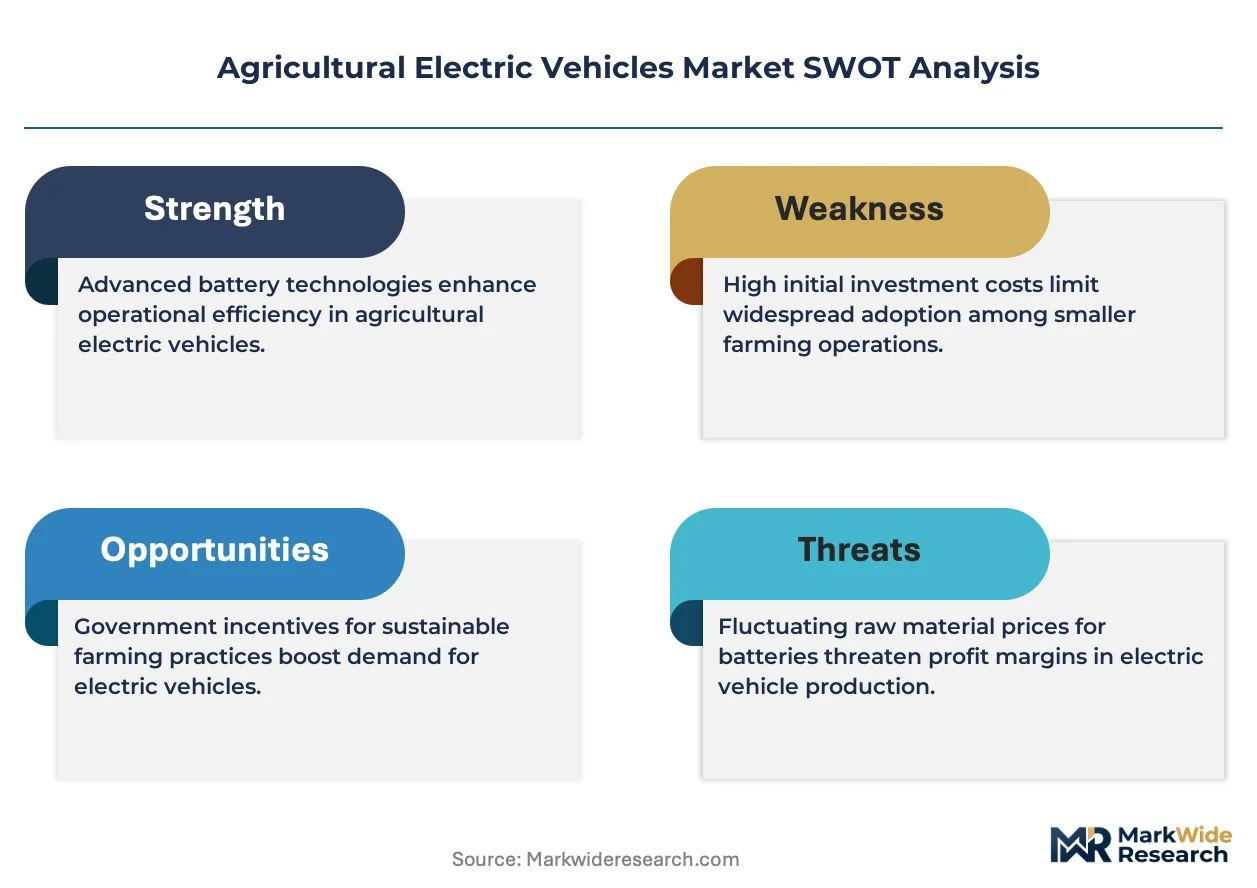
- Lithium supply concentration:Battery cell manufacturing dependence on concentrated upstream refining capacity creates input cost volatility and supply security risks.
- Charging infrastructure gaps:Rural electrical grid capacity limitations and three-phase power availability constrain fleet-scale electrification.
- Runtime limitations of pure-electric architectures:High-horsepower applications exceeding 12-hour field cycles face feasibility constraints without hydrogen fuel cell alternatives.
Strategic Opportunities
- Orchard and vineyard electrification:Compact electric tractors with swappable battery systems address maneuverability-critical segments underserved by conventional equipment.
- EU Green Deal carbon-intensity thresholds:Battery supply chain certification requirements create first-mover advantages for vertically integrated OEMs with verified low-carbon cell sourcing.
- Autonomous-ready electric platforms:Convergence of precision agriculture telematics and electric powertrains enables subscription-based fleet management services.
Industry Challenges
- High-voltage technician shortage:Agricultural equipment dealerships lack certified personnel for battery pack diagnostics and thermal management system repairs.
- Cross-border certification divergence:Misaligned timelines between EPA zero-emission mandates and EMA requirements force parallel product development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Electric Vehicles Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Sprayers, Harvesters, Utility Vehicles Technology: Battery Electric, Plug-in Hybrid, Hydrogen Fuel Cell, Solar Electric End User: Farmers, Agricultural Cooperatives, Contract Farmers, Government Agencies Application: Crop Production, Livestock Management, Soil Preparation, Transportation |
| Companies Covered | CNH Industrial, Caterpillar, John Deere, Kubota Corporation, Monarch, AGCO Corporation, Rigitrac, Yanmar, Alke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Electric Vehicles Market Emerging Trajectories
Power electronics and software-defined control systems are virtualizing traditional mechanical drivetrains, compressing development cycles and enabling over-the-air performance updates. This shift redefines how agricultural equipment generates, distributes, and optimizes torque in field conditions.
Silicon carbide inverters are virtualizing conventional silicon-based power conversion in high-horsepower tractors. Large-scale grain operations in the US Midwest are deploying these systems for improved thermal efficiency and faster charging cycles. The technology is virtualizing legacy generator-set architectures, reducing copper mass and enabling integrated motor-inverter units that simplify frame packaging.
REACH chemical disclosure requirements and the EU Green Deal framework are imposing carbon-intensity verification on battery supply chains imported into Europe. Equipment manufacturers must now document lifecycle emissions from cell production through end-of-life recycling. German and Dutch distributors are prioritizing OEMs with certified low-carbon supply chains, reshaping competitive positioning in Western European procurement.
Subscription-based powertrain service models are displacing traditional equipment ownership in precision agriculture segments. Large cooperative farming operations in Iowa and Illinois are piloting battery-electric tractor leases bundled with precision agriculture software and autonomous function upgrades. This shift is most visible among grain operations managing capital expenditure volatility through operational expenditure conversion.
Agricultural Electric Vehicles Market Segmentation
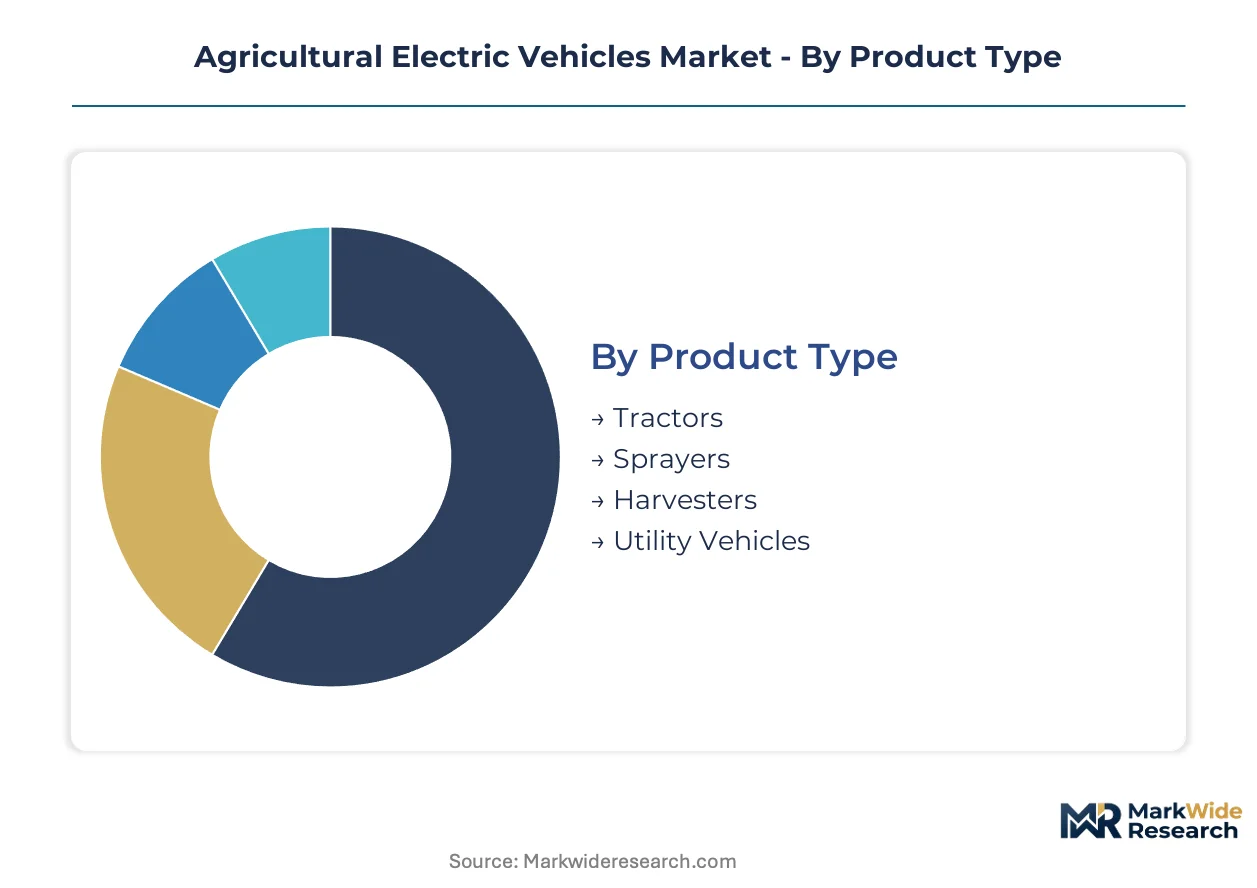
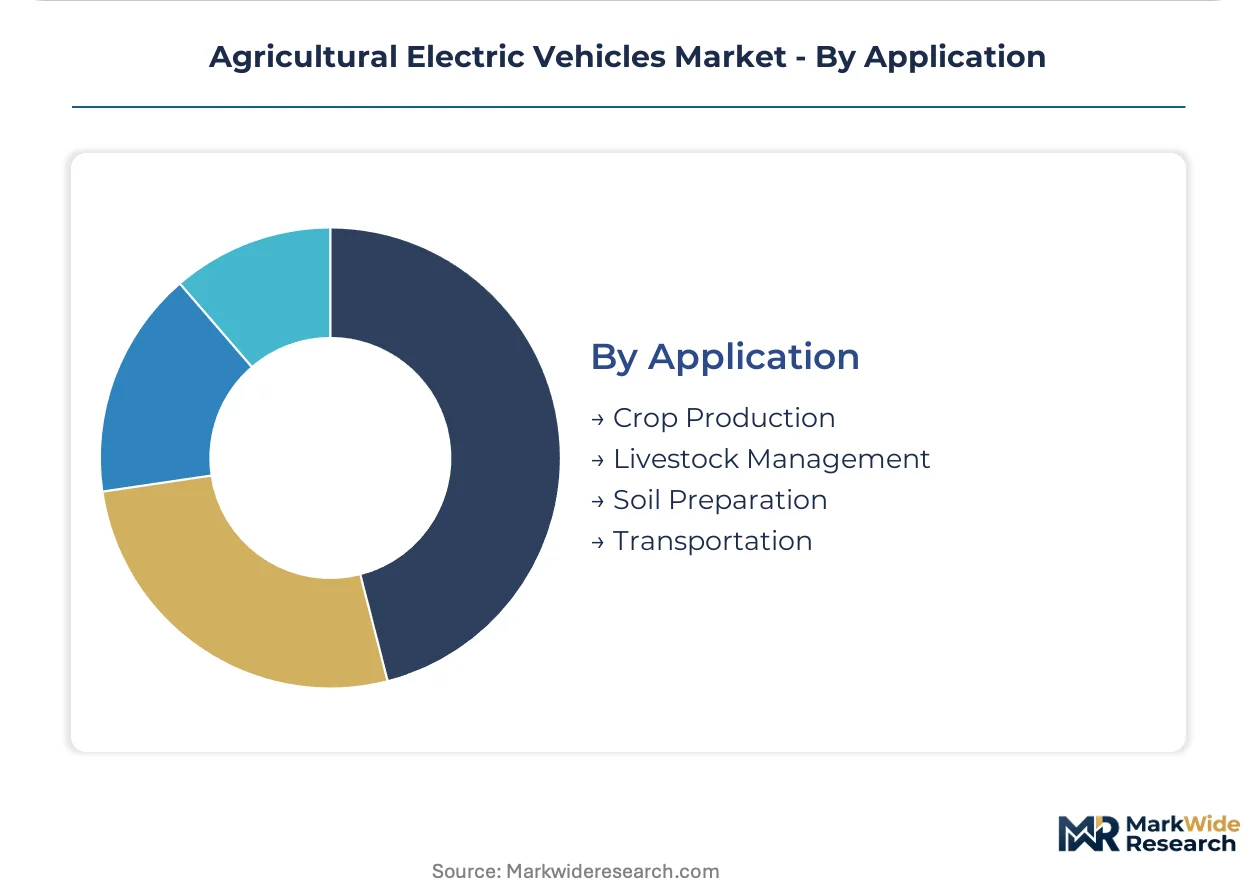
Agricultural electric vehicles serve divergent operational profiles across horsepower bands, duty cycles, and ownership structures. Segmentation reveals where battery economics align with runtime demands and which customer configurations absorb technology premiums fastest.
Product Type:
Equipment category determines frame engineering requirements, battery packaging constraints, and replacement cycle frequency.
- Tractors:Self-propelled machines with torque outputs from 50 to 400 horsepower-equivalent for primary field tasks. Battery electric configurations dominate procurement in Germany and the Netherlands where farm electrification subsidies compress payback periods.
- Utility Vehicles:Compact platforms with shorter replacement cycles and lower engineering barriers that disproportionately attract specialty manufacturers. Demand concentrates in orchard and vineyard operations where maneuverability outweighs horsepower ratings.
- Sprayers:Precision application equipment integrating electric powertrains with variable-rate chemical distribution systems.
- Harvesters:High-capacity grain and specialty crop collection machinery facing runtime constraints in extended field cycles.
Tractors hold installed capacity. Utility vehicles are rotating up the share rankings.
Technology:
Powertrain architecture selection hinges on duty cycle duration, refueling infrastructure access, and total cost of ownership horizons.
- Battery Electric:Lithium-ion cell-based systems with modular pack designs reconfiguring frame layouts and weight distribution. Falling cell costs now support commercial viability for 200+ horsepower-equivalent tractors in US Midwest row-crop applications.
- Hydrogen Fuel Cell:Proton exchange membrane systems delivering extended runtime without battery mass penalties. This segment is expanding most quickly in high-horsepower applications exceeding 12-hour field cycles where pure-electric feasibility faces constraints.
- Plug-in Hybrid:Dual-powertrain configurations bridging diesel dependency and full electrification for transitional fleet operators.
- Solar Electric:Photovoltaic-integrated platforms with supplemental charging capability for low-intensity intermittent operations.
Battery electric maintains volume leadership. Hydrogen fuel cell is climbing the fastest.
End User:
Ownership structure shapes capital allocation patterns, technology risk tolerance, and service model preferences.
- Agricultural Cooperatives:Pooled procurement entities managing capital expenditure volatility through operational expenditure conversion. Iowa and Illinois cooperatives pilot subscription-based battery-electric tractor leases bundled with precision agriculture software.
- Farmers:Individual owner-operators prioritizing equipment reliability and dealership service proximity over technology novelty.
- Contract Farmers:Service providers with asset utilization rates demanding predictable operating economics and rapid turnaround times.
- Government Agencies:Public research stations and demonstration farms absorbing early-adopter premiums for technology validation.
Cooperatives hold installed capacity. Contract farmers are rotating up the share rankings.
Application:
Field operation type dictates power delivery profiles, implement compatibility requirements, and seasonal utilization patterns.
- Crop Production:Seeding, cultivation, and harvest operations spanning complete growing seasons. German large-scale grain operations anchor demand for high-voltage battery architectures with integrated telematics.
- Soil Preparation:Tillage and land forming tasks with high torque demands and variable terrain exposure. EPA Tier 4 Final compliance costs accelerate electrification in heavy tillage machinery ahead of zero-emission mandate deadlines.
- Livestock Management:Feed handling, manure management, and animal movement operations with distributed facility layouts.
- Transportation:On-farm material logistics and short-haul commodity movement with defined route predictability.
Crop production holds installed capacity. Soil preparation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale grain operations and cooperative farming entities concentrate procurement across four distinct national markets where diesel cost volatility and emissions compliance timelines reshape capital allocation patterns.
United States
Iowa and Illinois cooperatives pilot subscription-based battery-electric tractor leases bundled with precision agriculture software. EPA Tier 4 Final compliance costs accelerate fleet electrification ahead of emerging zero-emission mandates. The Midwest grain belt anchors demand for high-voltage architectures with integrated telematics.
Germany
Farm electrification subsidies compress payback periods for battery-electric tractors and precision sprayers. The F-Gas Regulation and EU Green Deal carbon-intensity thresholds impose supply chain verification requirements on imported equipment. North Rhine-Westphalia distributors prioritize OEMs with certified low-carbon cell sourcing.
Netherlands
Intensive horticulture operations drive demand for compact electric utility vehicles with maneuverability-optimized designs. REACH chemical disclosure requirements reshape procurement criteria for battery supply chains. The Randstad agricultural technology cluster concentrates demonstration farms validating autonomous-ready electric platforms.
China
Dual carbon goals and MIIT industrial policy accelerate domestic OEM electrification programs for row-crop machinery. GB standards for off-road equipment emissions tighten compliance windows for conventional diesel powertrains. The Yangtze River Delta hosts manufacturing scale-up for silicon carbide inverter components.
France
Île-de-France research stations absorb early-adopter premiums for hydrogen fuel cell harvesters in extended field cycle applications. The EU Green Deal framework imposes lifecycle emissions documentation on imported battery systems. Auvergne-Rhône-Alpes specialty crop producers trial swappable battery systems for vineyard electrification.
Agricultural Electric Vehicles Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where full-line agricultural OEMs anchor premium positioning and compact equipment specialists capture maneuverability-critical segments. The vendor base organizes around three strategic archetypes: precision agriculture ecosystem integrators, dedicated electrification R&D houses, and swappable battery system specialists. Dominant competitive moves include strategic partnerships for charging infrastructure deployment and portfolio diversification into subscription-based fleet service models.
Within the full-line OEM tier, John Deere and CNH Industrial exemplify ecosystem-integrated competitors, while Monarch occupies a position among compact equipment specialists. These three companies represent divergent strategic postures: the precision agriculture telematics anchor, the transatlantic R&D house, and the vineyard-niche battery innovator.
| Leading Market Players |
|---|
| CNH Industrial |
| Caterpillar |
| John Deere |
| Kubota Corporation |
| Monarch |
| AGCO Corporation |
| Rigitrac |
| Yanmar |
| Alke |
| Others |
Supply Flow & Price Mechanics
Lithium supply concentration in Chile, Australia, and China determines both pricing tier spreads and supply chain shape for agricultural electric vehicles, compressing margins on battery-dependent equipment while rewarding OEMs with captive cell sourcing or long-term offtake agreements.
Pricing Analysis
Cost-plus contracts indexed to lithium carbonate spot prices dominate procurement between cell suppliers and tractor OEMs. Pricing stratifies across premium, standard, and economy tiers based on battery energy density certification and telematics integration depth. Cost compression in the standard tier is intensifying because of falling lithium-ion cell costs and aggressive Chinese manufacturer entry. Agricultural cooperatives exhibit highest price sensitivity due to capital expenditure volatility, while government research stations absorb premium pricing for early technology access.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for agricultural electric vehicle manufacturers. Cell production concentrates in China, South Korea, and Japan, while silicon carbide wafer fabrication feeds from the Yangtze River Delta. The supply chain rests on refined lithium, nickel sulfate, and rare earth permanent magnets as critical inputs. Distribution runs through OEM captive dealer networks and specialized agricultural equipment distributors with certified high-voltage technician capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through EPA Tier 4 Final and EU Green Deal compliance creates durable barriers against unqualified entrants.
For Market Incumbents: Pre-empt hydrogen fuel cell capability gaps by securing proton exchange membrane supply agreements ahead of high-horsepower segment inflection. Lock in certified low-carbon battery supply chains to satisfy EU Green Deal carbon-intensity thresholds before distributor procurement criteria harden. Channel control through dealership high-voltage technician certification programs anchors service revenue against emerging compact equipment specialists.
For New Entrants and Emerging Players: Orchard and vineyard operations in France and Germany represent the most penetrable entry point, where maneuverability requirements and swappable battery compatibility outweigh incumbent scale advantages. Subscription-based fleet service models for Iowa and Illinois agricultural cooperatives offer a go-to-market angle that converts capital expenditure volatility into recurring revenue relationships.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated OEMs with certified supply chains and precision agriculture software ecosystems. Long-term viability over the next decade hinges on regulatory compliance execution and charging infrastructure deployment scale. Watch hydrogen fuel cell harvester pilot results at French research stations as the inflection indicator for high-horsepower segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell volumes from Chinese or South Korean suppliers ahead of farm electrification subsidy windows. |
| Silicon Carbide Inverter Investment | Enables thermal efficiency gains and faster charging cycles for Midwest grain belt deployment. |
| Charging Infrastructure Partnership | Addresses rural three-phase power gaps constraining fleet-scale electrification in cooperative farming regions. |
| Precision Agriculture Platform Integration | Anchors customer loyalty through telematics bundling and autonomous-ready electric tractor subscriptions. |
| EU Green Deal Certification Program | Documents lifecycle emissions from cell production through recycling to satisfy Dutch and German distributor procurement criteria. |
Methodological Framework
Initial hypotheses were tested against primary input from agricultural cooperative procurement directors, OEM platform engineers, dealership service managers, and precision agriculture software specialists and refined through secondary validation against EPA regulatory filings, EU ECHA chemical disclosure databases, lithium trade flow customs data, and agricultural equipment registration statistics. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Demand-supply balance modeling across the projection horizon incorporated segmentation by powertrain architecture, horsepower tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to technology adoption S-cycles, with explicit modeling of lithium-ion cell cost decline trajectories and hydrogen fuel cell system learning curves as agriculture-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in diesel price volatility, lithium spot prices, or rural grid infrastructure investment would shift the trajectory. Forecasts reflect documented assumptions on subsidy duration and emissions mandate enforcement timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
Latin America Automotive High Performance Electric Vehicle Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Solar Electric Car Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
Electric Vehicle Battery on Demand Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
France Electric Bus Battery Pack Market