
 Europe Automotive High Performance Electric Vehicle Market | 2026-2036
Europe Automotive High Performance Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive High Performance Electric Vehicle Market Intelligence
A shift from outsourced powertrain components to in-house development of battery packs and software platforms is repositioning the competitive landscape in Europe. Porsche AG leverages its motorsport heritage to command premium pricing in the luxury sedan and sports car segments. Rimac Automobili specializes in hypercar technology, supplying key systems to other automakers. Volkswagen AG competes across multiple performance tiers through its diverse brand portfolio, including Audi.
Automotive high performance electric vehicles are defined by their ability to achieve rapid acceleration, typically 0-100 km/h in under 4 seconds, using advanced electric motor and battery systems. Their primary purpose is to deliver superior driving dynamics and power output, rivaling traditional internal combustion engine supercars. Within vehicle types, high-performance SUVs are gaining market share against traditional luxury sedans. The Super Sport and Grand Tourer performance tiers attract the majority of investment from private owners.
The EU Green Deal and its 'Fit for 55' package mandate stricter CO2 emission standards, compelling automakers to expand their high-performance EV offerings. Concurrently, the EU's Corporate Sustainability Reporting Directive (CSRD) influences supply chain transparency for battery materials like cobalt. Automakers must now decide whether to develop proprietary battery technology or secure long-term supply agreements to ensure performance and availability.
Market Dynamics
The primary structural force in the Europe Automotive High Performance Electric Vehicle Market is the regulatory pressure from the EU Green Deal, which is forcing a rapid transition from internal combustion engines to electric powertrains in the luxury and sports segments.
Growth Catalysts
- Regulatory Mandates:The EU's 'Fit for 55' package imposes stringent CO2 emission targets, compelling automakers to prioritize the development and sale of high-performance EVs to meet fleet-wide averages and avoid significant penalties.
- Performance Tier Demand:Strong interest from private owners in the Super Sport and Grand Tourer segments, combined with demand from luxury fleet services, creates a consistent customer base for high-priced electric models.
- Battery Technology Advancement:Continuous improvements in battery energy density and electric motor efficiency are enabling longer ranges and faster acceleration, meeting the core performance expectations of buyers in this premium category.
Market Restraints
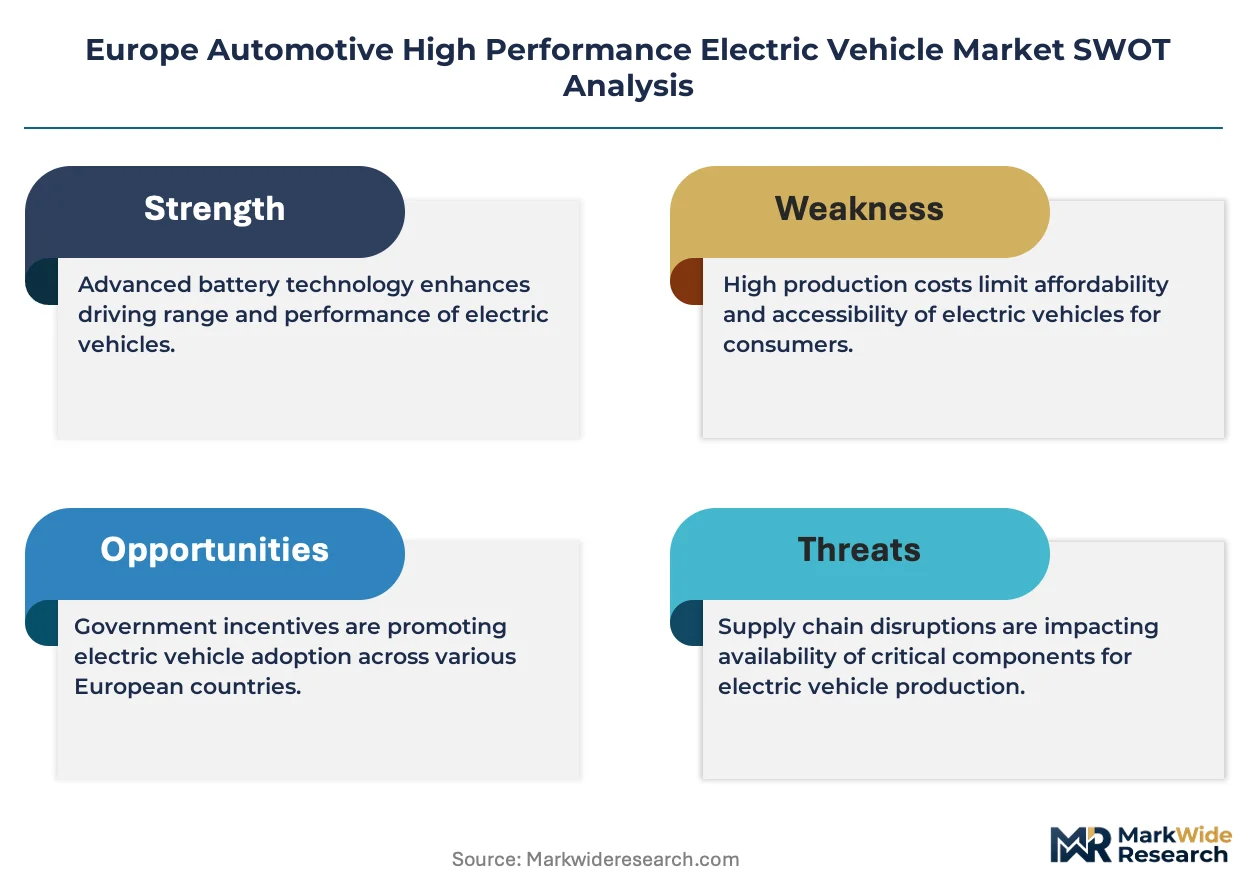
- Component Cost Volatility:The high and fluctuating costs of critical battery raw materials, such as lithium and cobalt sourced from outside Europe, create pricing instability and margin pressure for vehicle manufacturers.
- Charging Infrastructure Gaps:A lack of uniform, high-speed charging infrastructure, especially in parts of Southern and Eastern Europe, limits the practical usability of high-performance EVs for long-distance travel.
- Thermal Management Limits:Sustained high-output driving, such as on a track, presents significant thermal management challenges for current battery systems, leading to performance throttling to prevent overheating and degradation.
Strategic Opportunities
- Proprietary Battery Systems:Developing in-house battery pack technology and software platforms offers automakers a path to differentiate on performance and secure supply chains, reducing reliance on third-party suppliers.
- Specialized Charging Networks:Establishing exclusive, brand-specific charging hubs at premium locations like luxury hotels or private clubs can enhance the ownership experience and create a new recurring revenue stream.
- Solid-State Battery Integration:The future integration of solid-state battery technology presents a significant opportunity to overcome current limitations in energy density, charging speed, and safety for the next generation of hypercars.
Industry Challenges
- Supply Chain Compliance:Automakers face the complex challenge of auditing and reconfiguring global supply chains to meet the stringent transparency requirements of the EU's Corporate Sustainability Reporting Directive (CSRD).
- Specialized Talent Scarcity:A significant shortage of software engineers, battery systems specialists, and power electronics experts within Europe hinders the pace of in-house technology development and innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive High Performance Electric Vehicle Market |
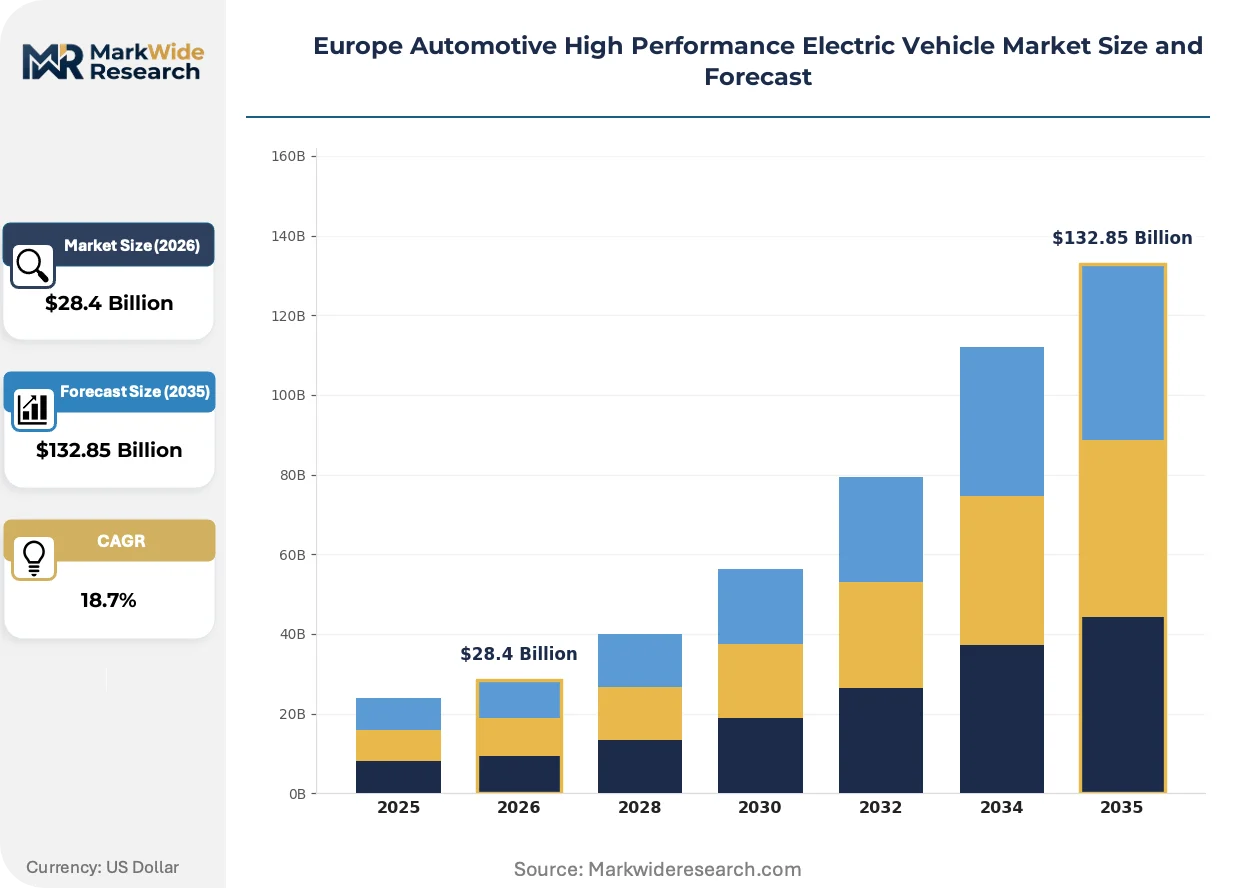
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $132.85 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sports Cars, SUVs, Luxury Sedans, Coupes, Convertibles Battery Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Lithium Iron Phosphate, Ultracapacitors Performance Tier: Sport, Super Sport, Hyper Sport, Grand Tourer, Track Edition End User: Private Owners, Car Collectors, Ride-Hailing Operators, Luxury Fleet Services, Specialty Rentals |
| Companies Covered | Tesla Inc., Volkswagen AG, Daimler AG, Ford Motor Company, BMW Group, Porsche AG, Rimac Automobili, Renault, Audi AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive High Performance Electric Vehicle Market Strategic Shifts & Innovations
The definition of automotive performance is shifting from mechanical hardware to software-defined capabilities. This evolution is reconfiguring value chains as automakers prioritize in-house development of core digital and electrical platforms to control the user experience and create new revenue models.
High-voltage 800-volt system architecture is a key enabler for reducing charging times and improving powertrain efficiency. The luxury sedan and hypercar segments are the primary adopters of this advanced electrical platform. This high-voltage architecture is converging with sophisticated battery thermal management software to deliver repeatable, high-power output without performance degradation.
Europe's Corporate Sustainability Reporting Directive (CSRD) is forcing a major shift in supply chain management. The regulation mandates detailed public disclosure on the environmental and social impact of sourcing, particularly for battery materials like cobalt. Automakers, especially those concentrated in Germany, must now implement rigorous tracking and auditing processes to ensure compliance.
A fundamental change in ownership models is underway, focusing on software-enabled features delivered via over-the-air (OTA) updates. This model disrupts traditional after-sales revenue, allowing manufacturers to sell performance upgrades or new functionalities directly to consumers post-purchase. This trend is most prominent within the premium SUV and sedan segments across Western Europe.
Europe Automotive High Performance Electric Vehicle Market Segmentation
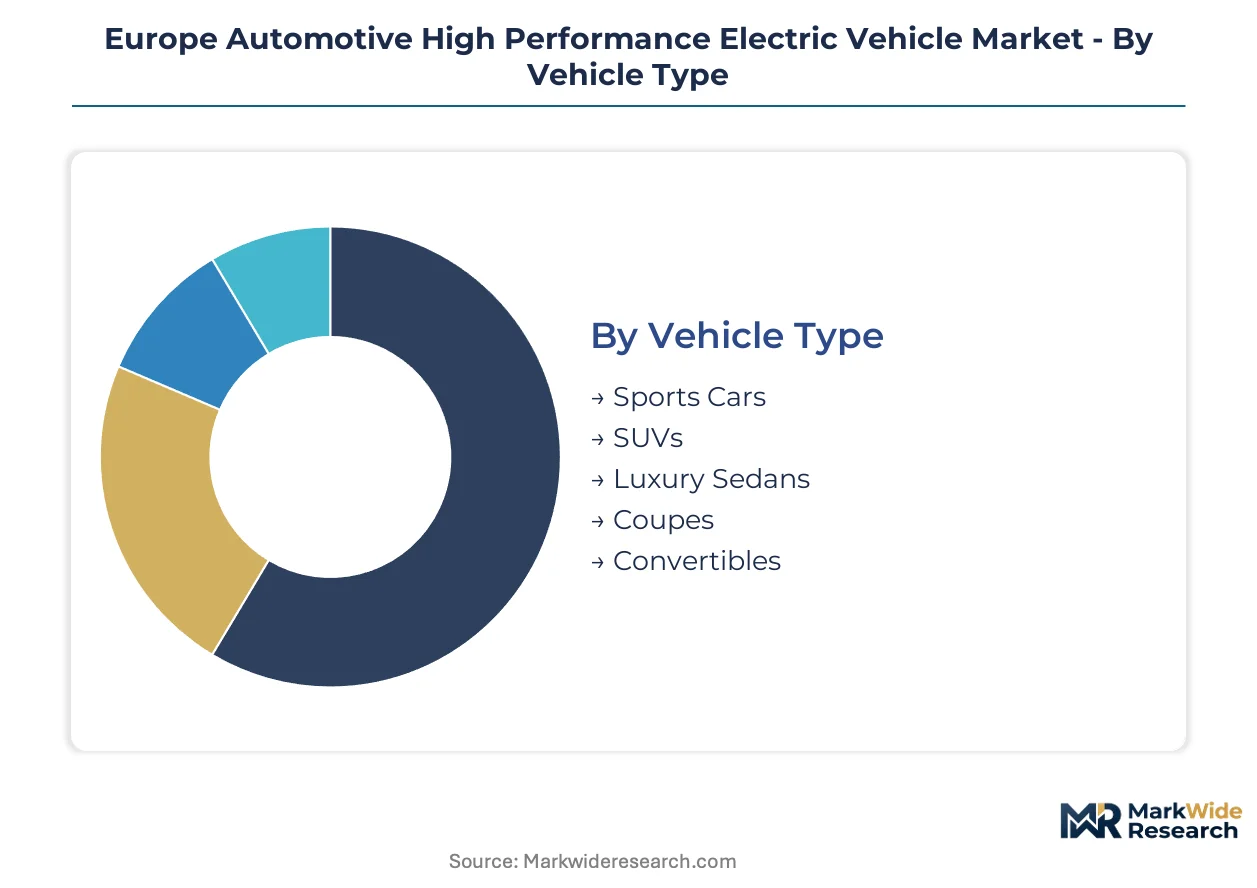
Market segmentation provides a critical framework for understanding the diverse characteristics and preferences shaping the Europe Automotive High Performance Electric Vehicle Market. These distinctions guide product development, investment strategies, and targeted marketing efforts across the continent.
Vehicle Type:
The diverse range of high-performance electric vehicles reflects varying engineering priorities for body styles and aerodynamic profiles.
- Luxury Sedans:These vehicles integrate powerful electric powertrains with advanced comfort features and sophisticated driver assistance systems. Demand from luxury fleet services in Germany and France drives significant sales volumes.
- SUVs:High-performance electric SUVs combine elevated ride height and spacious interiors with rapid acceleration capabilities. European consumers increasingly favor these models for their versatility and family appeal.
- Sports Cars:Dedicated two-seater or 2+2 configurations prioritize extreme acceleration and agile handling for enthusiast drivers.
- Coupes:Sleek, two-door designs offer a blend of performance and style, often with a focus on driver engagement.
- Convertibles:Open-top electric vehicles provide a unique driving experience, combining high performance with sensory immersion.
Mature deployment sits with Luxury Sedans. Newer deployment is concentrated in SUVs.
Battery Technology:
Application focus drives the selection of specific battery chemistries and architectures for optimal performance characteristics.
- Lithium-ion:This technology offers high energy density and power output, making it the current standard for most high-performance EVs. European automakers prioritize advancements in thermal management for these systems.
- Solid State:This next-generation technology promises significantly higher energy density, faster charging, and enhanced safety characteristics. Research and development efforts in Germany are intensely focused on commercializing solid-state cells.
- Nickel-Metal Hydride:This older battery chemistry is largely phased out in new high-performance EV designs due to lower energy density.
- Lithium Iron Phosphate:LFP batteries provide excellent cycle life and safety, finding niche applications where durability is paramount.
- Ultracapacitors:These components offer rapid power delivery and regeneration, typically used in conjunction with batteries for peak power demands.
Lithium-ion technology currently dominates, while Solid State technology exhibits the steepest expansion trajectory.
Performance Tier:
Customer expectations for speed and driving dynamics define the distinct performance tiers within the market.
- Super Sport:These vehicles deliver extreme acceleration and top speeds, often featuring advanced aerodynamics and chassis tuning. Private owners in Western Europe represent a significant demand segment for these high-priced models.
- Grand Tourer:Combining high performance with long-distance comfort and luxury, Grand Tourers offer a refined driving experience. Demand from discerning private owners seeking sophisticated travel vehicles is consistent.
- Sport:This entry-level performance tier offers enhanced dynamics over standard models, balancing performance with everyday usability.
- Hyper Sport:Representing the pinnacle of automotive engineering, these limited-production vehicles push boundaries in power, speed, and exclusivity.
- Track Edition:Designed specifically for circuit driving, these highly specialized models prioritize raw performance and handling over road legality or comfort.
Investment is heavily skewed towards Super Sport and Grand Tourer segments, reflecting strong private owner interest.
End User:
The diverse customer base for high-performance electric vehicles drives varied requirements concerning features, services, and ownership models.
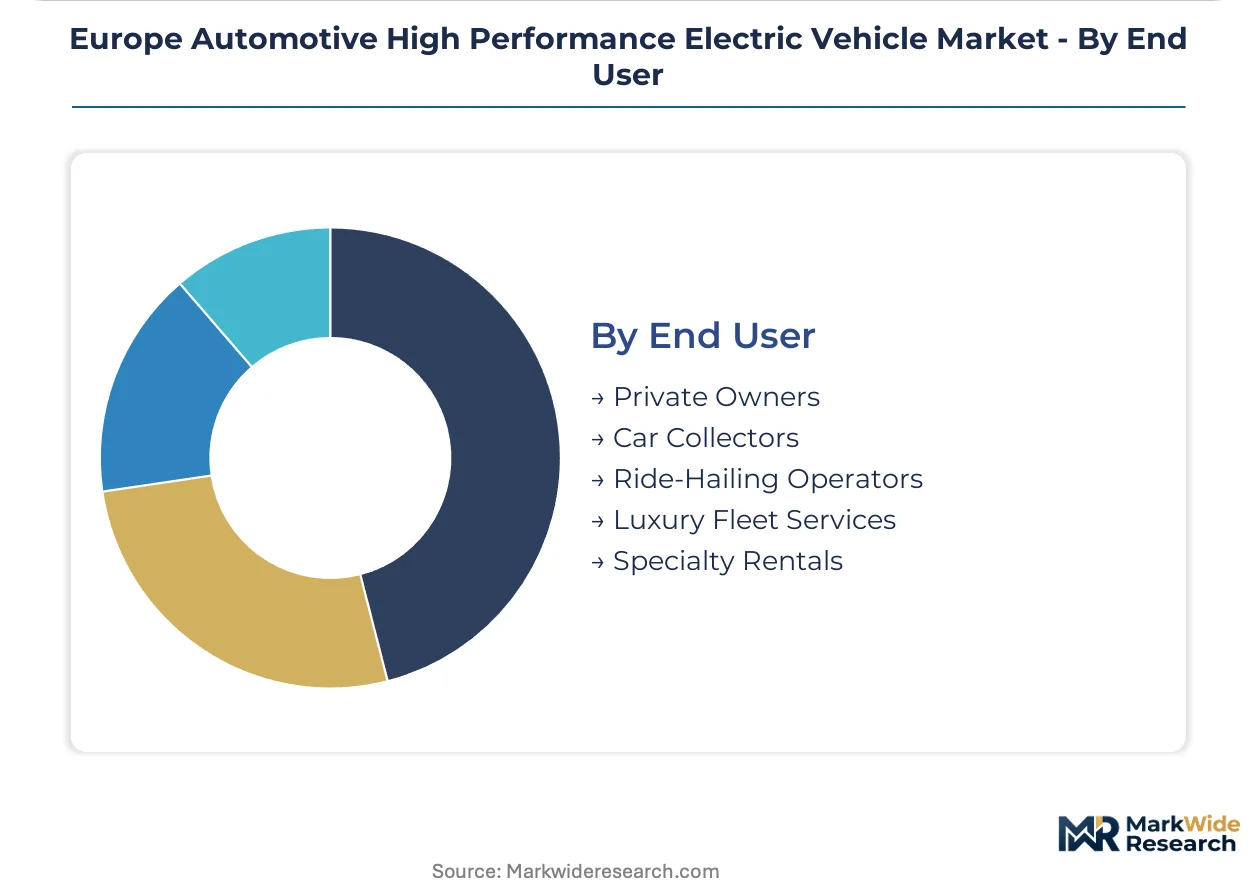
- Private Owners:This largest segment includes individuals purchasing high-performance EVs for personal use, driven by passion for driving and environmental consciousness. These buyers prioritize brand heritage and cutting-edge technology.
- Luxury Fleet Services:These operators integrate high-performance EVs into their premium service offerings for corporate clients and VIP transport. Demand from major European cities like Berlin and Paris is robust.
- Car Collectors:Individuals acquire rare or historically significant high-performance EVs, often viewing them as appreciating assets.
- Ride-Hailing Operators:A nascent but expanding segment, where premium ride-hailing services utilize high-performance EVs for an elevated passenger experience.
- Specialty Rentals:Companies offer short-term leases of high-performance EVs for events, tourism, or luxury experiences.
The largest volume segment is Private Owners, while Luxury Fleet Services represent a rapidly growing commercial application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing strength anchors the European high-performance electric vehicle market. Stringent EU Green Deal targets drive this regional transition, compelling automakers to expand their electric offerings. This includes rapid advancements in battery technology and electric motor efficiency across the continent.
Germany
Demand from luxury fleet services and private owners fuels the high-performance EV market in Germany. The EU's 'Fit for 55' package mandates CO2 emission reductions for German automakers. Munich and Stuttgart serve as key centers for high-performance EV development and production.
France
Luxury fleet services in Paris drive demand for high-performance electric sedans. France adheres to the EU's Corporate Sustainability Reporting Directive for battery material sourcing. The automotive clusters around Paris and Lyon focus on advanced powertrain integration and software development.
United Kingdom
Private owners in the Super Sport and Grand Tourer segments show strong interest in the UK. UK regulations align with broader European emissions standards for new vehicle sales. The Midlands region concentrates on high-performance EV engineering and design capabilities.
Italy
Discerning private owners seek Grand Tourer and Super Sport models in Italy, valuing performance and luxury. The EU Green Deal influences Italian automakers' shift to electric powertrains. Turin's automotive hub is adapting to electric vehicle component manufacturing and assembly.
Sweden
Environmental consciousness among private owners supports high-performance EV sales in Sweden. Sweden implements robust national incentives alongside EU emissions mandates. Gothenburg hosts significant research and development for electric vehicle technologies.
Europe Automotive High Performance Electric Vehicle Market Key Industry Players
In-house technology development dominates the current landscape, as automakers prioritize proprietary battery systems and software platforms. The market exhibits a tiered structure, with established luxury brands competing alongside specialized EV manufacturers. Strategic archetypes include established OEMs, performance-focused luxury brands, and specialized hypercar developers. Key competitive moves involve in-house technology development and strategic partnerships for critical component supply.
Established automotive groups like Volkswagen AG exemplify the multi-brand strategy, covering various performance tiers with diverse offerings. Porsche AG, a German-based subsidiary, represents the premium performance segment, leveraging its strong brand heritage and motorsport expertise. Specialized hypercar manufacturers such as Rimac Automobili occupy the pinnacle of electric performance, often supplying advanced systems to other manufacturers.
| Leading Market Players |
|---|
| Tesla Inc. |
| Volkswagen AG |
| Daimler AG |
| Ford Motor Company |
| BMW Group |
| Porsche AG |
| Rimac Automobili |
| Renault |
| Audi AG |
| Others |
Cost & Logistics Intelligence
Luxury fleet services in major European cities concentrate demand, influencing a value-based pricing model for high-performance EVs. This demand supports premium pricing strategies for advanced electric powertrains and luxury features.
Pricing Analysis
Warranty and service bundling often differentiate high-performance EV offerings. Value-based pricing dominates, reflecting brand heritage and technological sophistication. Brand premium from established luxury marques like Porsche AG, and customization levels for hypercars from specialists like Rimac Automobili, drive price differentiation. Pricing softness stems from component cost volatility, particularly for battery raw materials. Private owners in the Super Sport segment are least price-sensitive, while luxury fleet services exhibit higher sensitivity to total cost of ownership.
Supply Chain Analysis
The EU's Corporate Sustainability Reporting Directive (CSRD) mandates reshaping sourcing for battery materials. The supply chain for high-performance EV batteries concentrates in China and South Korea for raw materials like lithium and cobalt. Germany and France also host significant component manufacturing. Key dependencies include lithium, cobalt, and advanced power electronics. Commodity price volatility for critical raw materials presents a significant structural risk. Downstream distribution runs through brand-specific dealership networks and direct-to-consumer sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Automotive High Performance Electric Vehicle Market is fundamentally a cost-of-compliance story. The EU Green Deal, with its stringent emissions targets, creates a significant barrier-to-entry moat for automakers capable of meeting these mandates.
For Market Incumbents: Lock in long-term supply agreements for battery raw materials to mitigate component cost volatility. Deepen vertical integration into proprietary battery systems and software platforms to differentiate performance against emerging entrants. The threat of specialized hypercar developers displacing traditional luxury brands necessitates continuous R&D in advanced thermal management.
For New Entrants and Emerging Players: Solid-state battery technology presents a technology-first wedge for new entrants to challenge established players. Target underpenetrated segments like high-performance electric SUVs in Southern and Eastern Europe for initial market entry. A direct-to-consumer sales model paired with exclusive charging networks offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized technology developers in Germany and the UK, particularly those focused on 800-volt architecture or advanced software. Long-term viability over the next decade depends on securing intellectual property in battery management systems and electric motor efficiency. Acquisition targets should be innovative startups with proven expertise in power electronics or proprietary charging solutions. The signal to watch is the commercialization timeline for solid-state battery technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing complexity and accelerates new model deployment across Volkswagen AG brands. |
| Battery Supply Agreement | Secures critical raw materials and mitigates component cost volatility for European automakers. |
| Software-Defined Vehicle Investment | Enables new revenue models and enhances user experience through over-the-air updates. |
| Geographic Manufacturing Footprint | Establishes local production hubs to meet regional demand and reduce logistics costs. |
| Charging Infrastructure Partnership | Expands high-speed charging access, improving usability for high-performance EV owners. |
Research Approach
Document review covered automotive industry reports, OEM financial filings, and EU regulatory publications, complemented by interviews with industry stakeholders. Primary interviews included automotive engineers, battery system specialists, and luxury fleet operators across Germany and France. Secondary validation drew from IHS Markit registration data and European Patent Office records, ensuring robust data collection. This approach utilized both bottom-up market sizing and top-down validation.
Historical market data was cross-referenced with expert panel input to develop the forecast framework across the analysis window. Segmentation dimensions modeled included vehicle type, battery technology, performance tier, and end-user, alongside regional production clusters. Compound Annual Growth Rates were derived from a multi-variant regression model incorporating regulatory mandates and technological advancement. High-voltage architecture adoption and battery energy density served as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts or radical shifts in consumer preferences. Forecasts reflect assumptions regarding stable regulatory environments and continued technological progression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
Indian E-Bike Rental Market