
 Automotive Electric Drivetrain Components Market | 2026-2036
Automotive Electric Drivetrain Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Drivetrain Components Market Analysis
Commercial vehicle electrification is shifting faster than passenger car retrofit cycles, pulling inverter and motor volumes toward heavy-duty platforms. ZF Friedrichshafen AG leverages its integrated e-axle architecture to anchor European truck supply chains. Bosch competes through its in-house semiconductor capacity for power electronics. Magna International Inc. specializes in scalable modular drivetrain systems that span multiple OEM programs.
Automotive electric drivetrain components encompass power conversion and propulsion subsystems—specifically inverters switching DC battery current to variable-frequency AC at 400–800V architectures, permanent magnet or induction motors generating 50–300kW continuous output, and thermal-regulated battery packs with liquid-cooled cell arrays. These assemblies convert stored electrical energy into controlled mechanical torque for vehicle propulsion. Electric motors lead component type value pools due to rare-earth magnet content and precision manufacturing intensity. Integrated systems technology is displacing discrete component sourcing as OEMs pursue weight reduction and assembly simplification. Passenger vehicles anchor application volumes, though commercial vehicle electrification is opening the fastest-expanding margin pool.
The EPA tailpipe standards and NHTSA corporate average fuel economy rules in the United States mandate fleet-wide CO2 reductions that force OEM electrification roadmaps. EMA and REACH compliance in Europe restricts hazardous substances in motor windings and battery cell chemistries, reshaping supplier qualification protocols. China's MIIT dual carbon goals and GB standards for new energy vehicles dictate local content requirements and efficiency benchmarks. Stakeholders must monitor how divergent thermal management regulations across these jurisdictions fragment platform standardization and inflate engineering validation costs.
Market Dynamics
Integrated e-axle architectures are compressing supplier tiers as OEMs consolidate inverter, motor, and gearbox sourcing into single-module procurement contracts, forcing component specialists to restructure their commercial models.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-down of fluorinated greenhouse gases in thermal management systems accelerates demand for CO2-based heat pumps and liquid-cooled battery arrays across European vehicle platforms.
- Commercial vehicle electrification:Heavy-duty logistics fleets in Germany's Baden-Württemberg cluster are pulling high-voltage inverter and motor volumes toward 800V architectures faster than passenger car retrofit cycles permit.
- Rare-earth magnet processing:Advances in grain-boundary diffusion techniques for neodymium-iron-boron magnets reduce dysprosium content while maintaining coercivity, easing supply constraints on motor rotor assemblies.
Market Restraints
- Neodymium supply concentration:Processing capacity for rare-earth elements clusters in China's Jiangxi and Inner Mongolia provinces, creating single-source vulnerability for permanent magnet motor production.
- Silicon carbide wafer costs:200mm SiC substrate yields remain below 50% at major foundries, inflating power module costs for 800V inverters versus conventional silicon IGBTs.
- REACH substance restrictions:ECHA classification of certain epoxy resin hardeners as substances of very high concern forces reformulation of motor winding insulation with unproven long-term thermal cycling performance.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive technology manufacturing attract inverter and motor assembly capacity to Tamil Nadu and Gujarat supplier corridors.
- Wireless charging integration:Inductive power transfer coils embedded in road infrastructure create aftermarket retrofit demand for onboard receiver modules and battery management system upgrades.
- Solid-state battery thermal interfaces:Ceramic-polymer composite phase-change materials developed for next-generation cell architectures open adjacent revenue pools for thermal management specialists.
Industry Challenges
- Power electronics engineering scarcity:Shortage of specialists proficient in wide-bandgap semiconductor gate driver design and electromagnetic compatibility testing extends product validation timelines.
- Multi-junction temperature validation:Simultaneous thermal cycling of inverters, motors, and battery packs across -40°C to 150°C operational envelopes requires capital-intensive environmental chamber infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Drivetrain Components Market |
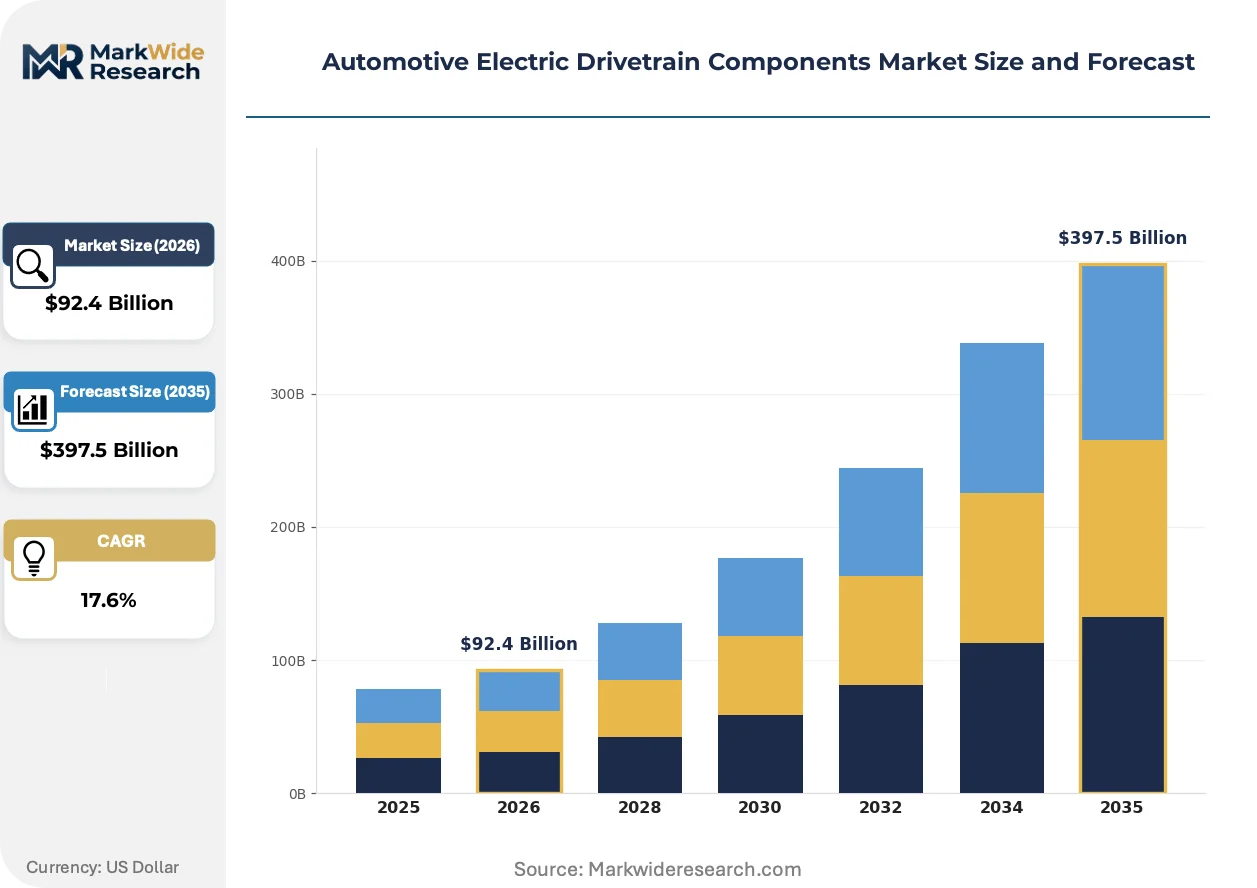
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $397.5 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Inverters, Electric Motors, Battery Packs, Charging Modules Technology: Active Cooling, Integrated Systems, Wireless Charging, Regenerative Braking End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Hybrid Vehicles |
| Companies Covered | Magna International Inc., Continental AG, ZF Friedrichshafen AG, Hyundai Mobis Co., Ltd., Dana Incorporated, Aisin Seiki Co., Ltd., Schaeffler AG, Bosch, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Drivetrain Components Market Emerging Trajectories
Silicon carbide power semiconductors and hairpin winding motor topologies are converging to enable 800V platform architectures that compress charging times and reduce copper mass in high-performance drivetrains.
Hairpin stator winding technology replaces traditional round-wire coils with rectangular copper conductors arranged in precise slot patterns. European premium OEMs in Germany's automotive cluster are adopting this topology for 150kW+ continuous output motors. The manufacturing precision required is expanding into automated laser welding and paperless interphase insulation systems that displace manual assembly lines.
China's MIIT GB/T standards for new energy vehicle charging and battery swapping are mandating unified connector geometries and communication protocols. This regulatory harmonization forces foreign suppliers to redesign power entry modules for compatibility with domestic charging infrastructure. Korean and Japanese component manufacturers are establishing joint validation centers in Shanghai to accelerate local certification cycles.
Fleet operators are consolidating component procurement through long-term service agreements that bundle drivetrain hardware with predictive maintenance analytics. Logistics providers in South Korea's Gyeonggi-do corridor are piloting subscription models where inverter and motor replacement costs are smoothed across vehicle lifecycles. This consumption pattern shift is most visible in commercial vehicle segments where uptime guarantees override upfront capital expenditure minimization.
Automotive Electric Drivetrain Components Market Segmentation
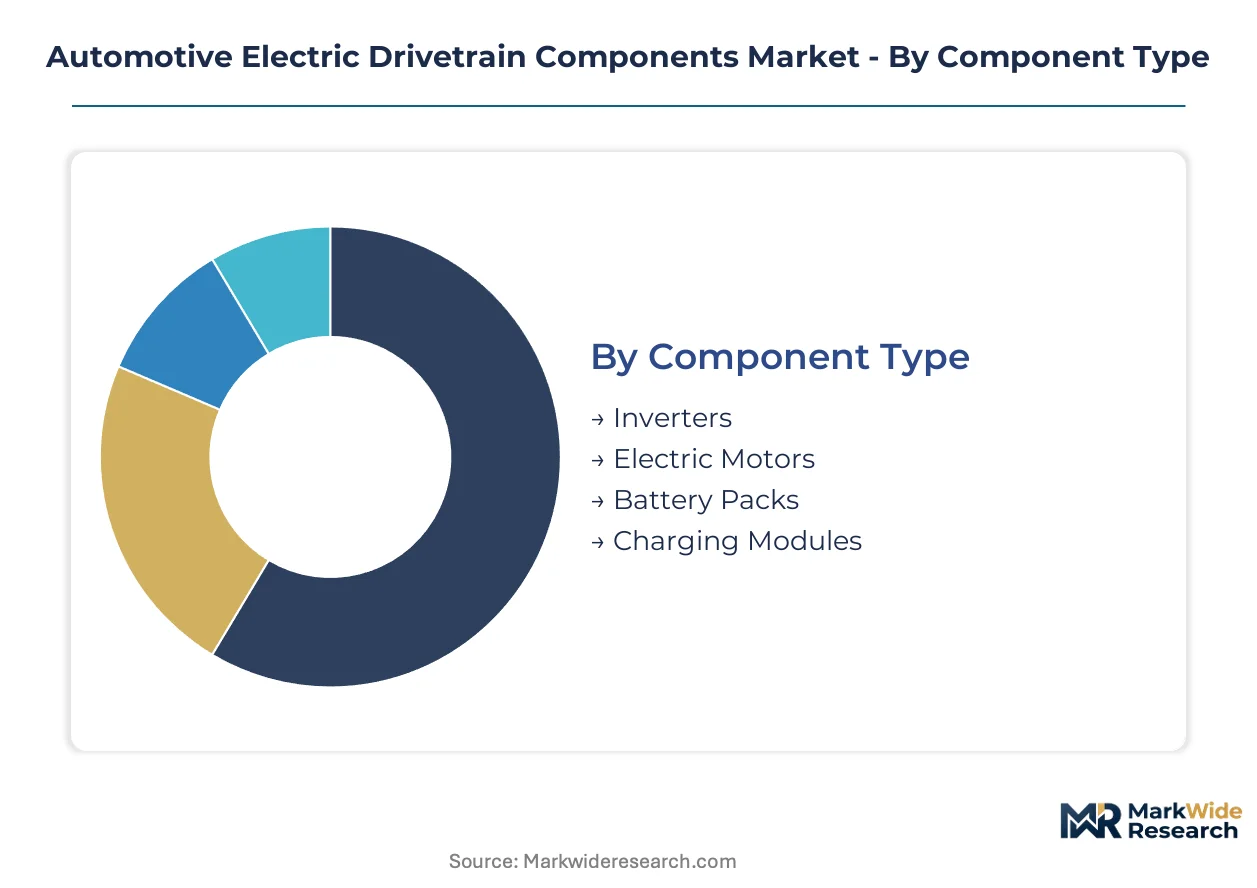
Drivetrain component procurement patterns diverge sharply across vehicle architectures and customer types. OEM platform consolidation favors integrated module sourcing, while aftermarket channels sustain discrete component demand for retrofit and repair applications.
Component Type:
Supply concentration in permanent magnet processing and silicon carbide wafer fabrication shapes which component categories command procurement priority and pricing power.
- Electric Motors:Permanent magnet synchronous machines and induction motors convert electrical current to mechanical torque through rare-earth rotor assemblies. Demand concentrates in Germany's Baden-Württemberg automotive cluster where premium OEMs specify 150kW+ continuous output specifications. Grain-boundary diffusion techniques for neodymium-iron-boron magnets are reducing dysprosium content while maintaining coercivity thresholds.
- Inverters:Power electronics modules switch DC battery current to variable-frequency AC using silicon IGBT or silicon carbide MOSFET architectures. South Korea's Gyeonggi-do supplier corridor is pulling 800V inverter volumes for heavy-duty commercial platforms faster than passenger car retrofit cycles permit. Yield rates below 50% for 200mm SiC substrates continue inflating module costs versus conventional silicon alternatives.
- Battery Packs:Thermal-regulated cell arrays with liquid-cooled architectures store and discharge electrical energy across 400-800V system voltages.
- Charging Modules:Onboard power entry units manage grid-to-battery energy transfer through conductive or inductive coupling interfaces.
Today's leader: Electric Motors. Tomorrow's challenger: Inverters.
Technology:
Cost tier differentiation separates mature thermal management approaches from emerging integration architectures requiring capital-intensive validation infrastructure.
- Integrated Systems:Consolidated e-axle modules combine inverter, motor, and reduction gearbox into single procurement contracts. ZF Friedrichshafen AG leverages this architecture to anchor European truck supply chains. OEM platform consolidation is compressing supplier tiers and forcing component specialists to restructure commercial models toward module-level partnerships.
- Active Cooling:Liquid-cooled cold plates and refrigerant loops maintain cell array temperatures within operational envelopes. China's MIIT battery pack integration standards and the EU's F-Gas Regulation are tightening thermal management requirements across both jurisdictions simultaneously. CO2-based heat pumps are displacing fluorinated greenhouse gas systems in European vehicle platforms.
- Regenerative Braking:Kinetic energy recovery systems convert deceleration events into battery charging current through motor-generator operation.
- Wireless Charging:Inductive power transfer coils embedded in road infrastructure create aftermarket retrofit demand for onboard receiver modules.
Integrated Systems capture current procurement volumes. Wireless Charging faces the steepest expansion trajectory as infrastructure deployment accelerates.
End User:
Volume concentration among fleet operators is reshaping contract structures toward subscription-based service agreements with uptime guarantees.
- Fleet Operators:Logistics providers in South Korea's Gyeonggi-do corridor are piloting long-term service agreements bundling drivetrain hardware with predictive maintenance analytics. Subscription models smooth inverter and motor replacement costs across vehicle lifecycles. Uptime guarantees override upfront capital expenditure minimization in commercial procurement decisions.
- OEMs:Vehicle manufacturers specify integrated drivetrain modules for original equipment installation across passenger and commercial platforms. Magna International Inc. supplies scalable modular systems spanning multiple OEM programs through standardized interfaces.
- Aftermarket Providers:Independent service networks source discrete components for repair, retrofit, and refurbishment applications.
- Research Institutions:Academic and government laboratories procure prototype quantities for next-generation technology validation.
Fleet Operators are gaining procurement influence fastest. OEMs retain volume leadership.
Application:
Margin structure varies significantly between passenger vehicle scale economies and commercial vehicle performance requirements.
- Commercial Vehicles:Heavy-duty logistics platforms specify 800V architectures with high continuous output ratings for sustained highway operation. Germany's Baden-Württemberg automotive cluster anchors European demand for electrified truck and bus drivetrains. Commercial vehicle electrification is opening the fastest-expanding margin pool as fleet operators consolidate procurement through service-based contracts.
- Passenger Vehicles:Light-duty automobiles anchor absolute volume demand across global production footprints. Bosch competes through in-house semiconductor capacity for power electronics serving this segment.
- Hybrid Vehicles:Dual-powertrain architectures combine electric motor assist with internal combustion range extension.
- Two-Wheelers:Motorcycles and scooters deploy compact drivetrain packages with reduced voltage and power specifications.
Passenger Vehicles dominate volume. Commercial Vehicles are climbing the fastest toward margin leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions creates cost-of-compliance arbitrage that redirects production capacity toward markets with harmonized standards. The EU's F-Gas Regulation and China's MIIT battery integration mandates impose divergent thermal management requirements, fragmenting platform engineering while concentrating assembly in corridors with aligned certification pathways.
Germany
Baden-Württemberg's automotive cluster anchors European demand for 800V commercial vehicle drivetrains. The EU F-Gas Regulation accelerates CO2 heat pump adoption across heavy-duty platforms. ZF Friedrichshafen AG leverages integrated e-axle architectures to secure long-term supply contracts with electrified truck OEMs.
China
MIIT dual carbon goals and GB standards for new energy vehicles dictate local content requirements that reshape foreign supplier entry strategies. Jiangxi and Inner Mongolia provinces concentrate rare-earth magnet processing capacity for permanent magnet motors. Domestic OEMs consolidate procurement through state-backed battery swapping infrastructure mandates.
United States
EPA tailpipe standards and NHTSA corporate average fuel economy rules force fleet-wide electrification roadmaps across Detroit's legacy manufacturers. The Inflation Reduction Act's domestic content provisions redirect inverter and motor assembly toward North American supplier corridors. Michigan and Ohio industrial zones attract power electronics engineering talent from coastal technology markets.
South Korea
Gyeonggi-do's supplier corridor pulls high-voltage component volumes toward commercial vehicle platforms faster than passenger car retrofit cycles. The country's national automotive regulator aligns with international charging standards while maintaining proprietary battery cell specifications. Hyundai Mobis Co., Ltd. anchors domestic supply chains through vertical integration into semiconductor packaging for power modules.
India
Tamil Nadu and Gujarat supplier corridors attract inverter and motor assembly capacity through the PLI scheme for auto components. BIS efficiency benchmarks for electric vehicle subsystems create certification barriers that favor established tier-one suppliers over domestic entrants. Fleet operators in Maharashtra pilot subscription-based drivetrain service agreements with uptime guarantees.
Automotive Electric Drivetrain Components Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system suppliers capturing premium pricing in commercial vehicle procurement while discrete component vendors sustain aftermarket repair volumes. The market structure consolidates around tier-one module integrators capable of validating multi-junction thermal performance across -40°C to 150°C operational envelopes. Three archetypes dominate: diversified automotive conglomerates with captive semiconductor capacity, pure-play drivetrain specialists with scalable modular architectures, and rare-earth magnet processors with upstream mining partnerships. Competitive dynamics center on strategic partnerships for 800V platform validation and geographic expansion into PLI-subsidized manufacturing corridors.
Among diversified automotive conglomerates, Bosch and Continental AG occupy positions defined by in-house power electronics manufacturing and cross-segment technology transfer capabilities. Within the pure-play drivetrain tier, Magna International Inc. and ZF Friedrichshafen AG exemplify modular system architectures that span multiple OEM programs through standardized mechanical and electrical interfaces. These four entities represent contrasting strategic postures: semiconductor-backed vertical integration versus design-flexible contract manufacturing.
| Leading Market Players |
|---|
| Magna International Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| Hyundai Mobis Co., Ltd. |
| Dana Incorporated |
| Aisin Seiki Co., Ltd. |
| Schaeffler AG |
| Bosch |
| BorgWarner Inc. |
| Others |
Supply Flow & Price Mechanics
Power electronics engineering talent clustering in Germany's Baden-Württemberg region feeds labor-cost differentials that widen pricing-tier spreads between premium integrated e-axle modules and economy-grade discrete component sourcing. OEM procurement consolidation into single-module contracts compresses margins for component specialists while rewarding tier-one integrators with pricing power anchored in validated thermal performance guarantees.
Pricing Analysis
Direct-to-OEM channel discounts dominate commercial vehicle procurement, with fleet operators extracting volume-based concessions through long-term service agreements bundling hardware and predictive maintenance. Pricing stratifies across premium, standard, and economy tiers based on thermal cycling certification grade and silicon carbide versus silicon IGBT semiconductor content. Cost compression in economy-grade inverter modules is intensifying because yield rates below 50% for 200mm SiC substrates inflate power module costs versus conventional alternatives. Aftermarket providers exhibit highest price sensitivity, while electrified truck fleet operators prioritize uptime guarantees over upfront capital expenditure minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated procurement desks at major vehicle manufacturers, while aftermarket distributors sustain discrete component volumes for repair and retrofit applications. Geographic supply concentration centers on China's Jiangxi and Inner Mongolia provinces for rare-earth magnet processing, South Korea's Gyeonggi-do corridor for high-voltage inverter assembly, and Germany's Baden-Württemberg cluster for integrated e-axle production. Raw material dependencies draw from neodymium-iron-boron magnet alloys, silicon carbide wafers, and copper hairpin winding stock. Single-source vulnerability in rare-earth element processing creates supply chain risk exposure. Distribution runs through tier-one module integrators capable of multi-junction thermal validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU F-Gas Regulation's mandatory fluorinated greenhouse gas phase-down accelerates demand for CO2-based thermal management systems across European vehicle platforms.
For Market Incumbents: Anchor market position through backward integration into silicon carbide semiconductor packaging and captive rare-earth magnet processing partnerships that neutralize single-source supply risk. Secure long-term validation contracts with 800V platform OEMs before emerging Asian competitors complete local certification cycles. Prioritize thermal cycling certification investment as REACH substance restrictions force reformulation of motor winding insulation systems. For New Entrants and Emerging Players: Hairpin winding automation equipment represents a technology-first wedge for specialist machinery suppliers seeking entry into European premium OEM supply chains. Target India's Tamil Nadu and Gujarat supplier corridors where PLI scheme subsidies reduce capital barriers for inverter and motor assembly capacity. Pursue fleet operator subscription service agreements as the most penetrable contract structure, offering predictive maintenance analytics bundled with hardware replacement guarantees. For Investors and Strategic Acquirers: Tier-one automotive conglomerates with captive semiconductor capacity are the most active acquirers in this space, consolidating pure-play drivetrain specialists to secure 800V platform validation expertise. Long-term viability favors targets with demonstrated multi-junction thermal cycling capabilities across -40°C to 150°C operational envelopes. Watch silicon carbide wafer yield improvement rates at major foundries as the critical inflection indicator for inverter module cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around 800V architectures reduces engineering validation costs for tier-one suppliers. |
| Battery Supply Agreement | Long-term cell offtake contracts secure thermal management system volumes for integrated e-axle producers. |
| Software-Defined Vehicle Investment | Predictive maintenance analytics capabilities differentiate fleet service agreements in South Korea's Gyeonggi-do corridor. |
| Geographic Manufacturing Footprint | PLI-subsidized capacity in India's Tamil Nadu reduces landed cost for export-oriented inverter assembly. |
| Charging Infrastructure Partnership | Wireless charging receiver module integration opens aftermarket retrofit demand for battery management upgrades. |
Methodological Framework
Multiple input streams — primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, and aftermarket distributors; secondary validation against vehicle production databases, IHS Markit registration data, MIIT new energy vehicle certification filings, and SEC 10-K disclosures from listed component manufacturers — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned thermal management specialists, power electronics engineering leads, and fleet operator procurement managers across Germany, China, South Korea, and the United States.
Segment-level volume and value outputs were derived through reconciliation of component-level bill-of-materials analysis with vehicle production forecasts across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were computed from fitted growth curves incorporating silicon carbide adoption rates, rare-earth magnet price trajectories, and regulatory compliance cost burdens. Industry-specific forecast inputs included 800V platform penetration assumptions and thermal management system content per vehicle.
The model holds under stable regulatory enforcement intensity and continued OEM platform consolidation; deviation in rare-earth export restriction severity or silicon carbide yield breakthrough timing would shift component-level pricing trajectories and procurement volume allocations. Periodic stress-testing of base assumptions against MIIT policy announcements and ECHA substance restriction updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Automotive Steering System Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Air Brake Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
Traffic Control Products Market
Automotive Parts
Engine Bearings Market
Automotive Parts
France Automotive Actuators Market