
 Commercial Electric Vehicle Resistive Braking System Market | 2026-2036
Commercial Electric Vehicle Resistive Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Electric Vehicle Resistive Braking System Market Outlook
Logistics companies is rebalancing the commercial EV resistive braking system demand profile, pulling share from public transport agencies as e-commerce fleet electrification accelerates. Robert Bosch GmbH leverages its integrated mechatronics portfolio to dominate hydraulic-electronic braking interfaces for heavy-duty platforms. Continental AG sustains technology leadership in electronic control systems, while ZF Friedrichshafen anchors European manufacturing scale through captive production of pneumatic braking modules.
A commercial electric vehicle resistive braking system dissipates excess kinetic energy as heat through resistive elements, typically wire-wound or grid-type resistors rated for continuous duty cycles exceeding 500°C surface temperatures, protecting battery systems from overcharge during regenerative braking saturation. Regenerative braking captures the largest installed base but dynamic braking grows fastest as fleet operators demand thermal redundancy for downhill-grade operations. Electronic control systems command the deepest margin pools where firmware calibrates torque blending between regenerative and resistive modes.
FDA vehicle safety oversight intersects with EPA emissions compliance as commercial EV braking systems eliminate particulate brake dust, while ECE R13 harmonization across EU member states mandates specific fade-resistance thresholds for resistive backup systems. NHTSA FMVSS 135 stopping-distance requirements in the United States force OEMs to integrate dual-circuit resistive braking for fail-safe redundancy on Class 4-8 electric trucks. Stakeholders must monitor how battery energy density improvements alter the duty-cycle economics of resistive versus regenerative braking dominance in next-generation commercial platforms.
Market Dynamics
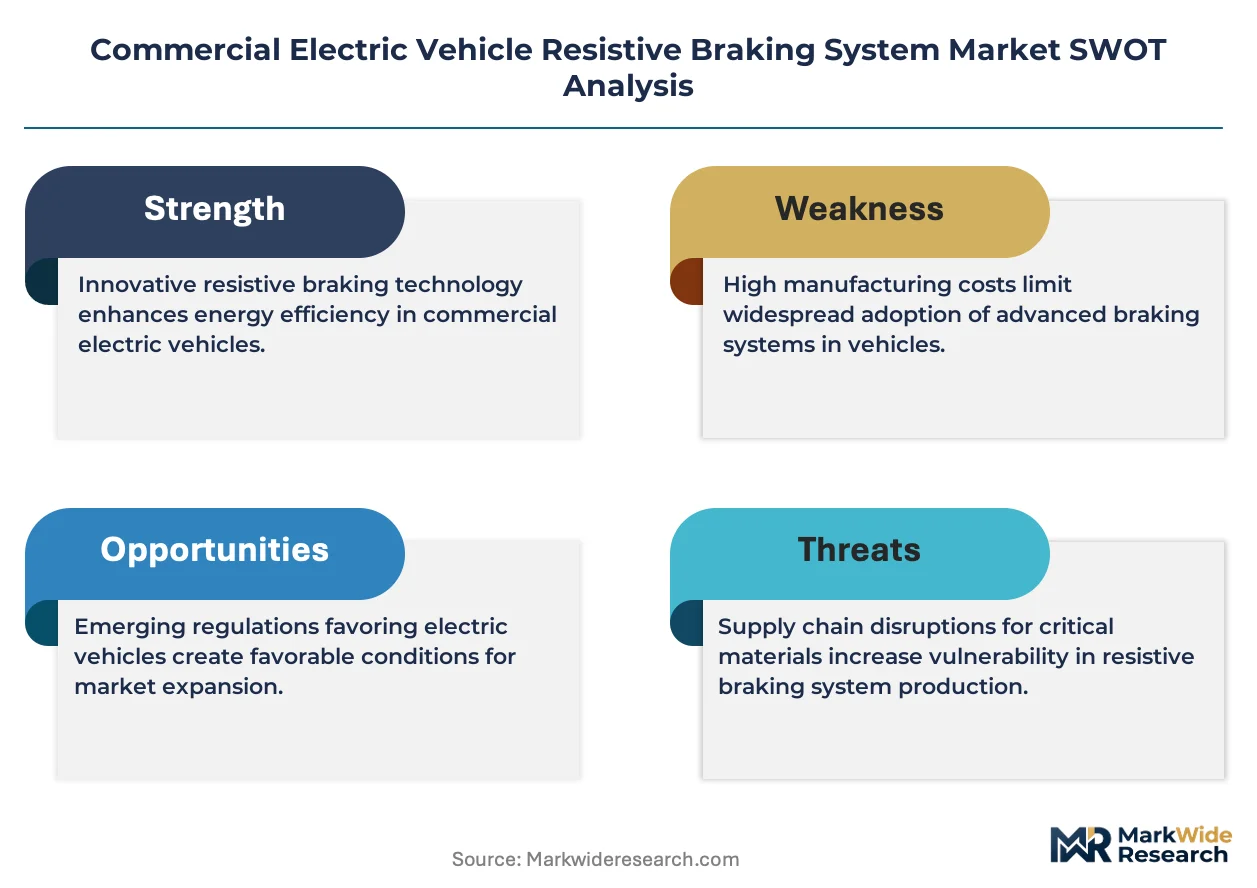
Fleet electrification is forcing a fundamental recalibration of thermal management architectures, as regenerative braking saturation on heavy-grade descents creates non-negotiable demand for resistive backup systems that protect battery integrity under sustained load conditions.
Growth Catalysts
- ECE R13 Harmonization:Europe's braking performance mandates require commercial EVs to maintain fade-resistant backup systems, compelling OEMs to spec resistive modules for Type Approval compliance across EU member states.
- E-Commerce Logistics:Parcel delivery fleets operating in topographically challenging corridors—Swiss Alpine routes, Norwegian fjord roads—require redundant braking thermal capacity that regenerative systems alone cannot guarantee.
- Silicon Carbide Power Electronics:Wider bandgap semiconductors enable higher switching frequencies in braking chopper circuits, improving resistive element duty-cycle efficiency and reducing thermal management mass.
Market Restraints
- Copper Price Volatility:Wire-wound resistor grids depend on copper alloy conductors, exposing manufacturers to London Metal Exchange price swings that compress margin visibility on long-delivery fleet contracts.
- Single-Source Magnet Supply:Rare-earth permanent magnets for braking system servomotors concentrate in Chinese processing facilities, creating geographic chokepoints for European and North American module assemblers.
- Regenerative Efficiency Gains:Advances in battery charge-acceptance rates and motor-generator thermal tolerance threaten to narrow the operational window where resistive braking provides essential redundancy.
Strategic Opportunities
- Indian Commercial Electrification:The country's PLI scheme for automotive component manufacturing offers cost-competitive production bases for resistive braking modules serving ASEAN export markets.
- Mining Truck Electrification:Open-pit haulage operations in Chile and Australia present untapped demand for megawatt-scale resistive braking systems managing continuous downhill payload cycles.
- ISO 26262 Functional Safety:ASIL-D certification for braking control firmware creates service revenue streams through mandatory software update cycles and calibration tool licensing.
Industry Challenges
- Embedded Software Talent Scarcity:Torque-blending algorithm development requires rare cross-functional expertise spanning power electronics, thermal physics, and automotive functional safety standards.
- Homologation Timeline Compression:Parallel certification tracks for NHTSA FMVSS 135, ECE R13, and China's GB/T standards extend product launch windows by 18-24 months for global platform suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Electric Vehicle Resistive Braking System Market |
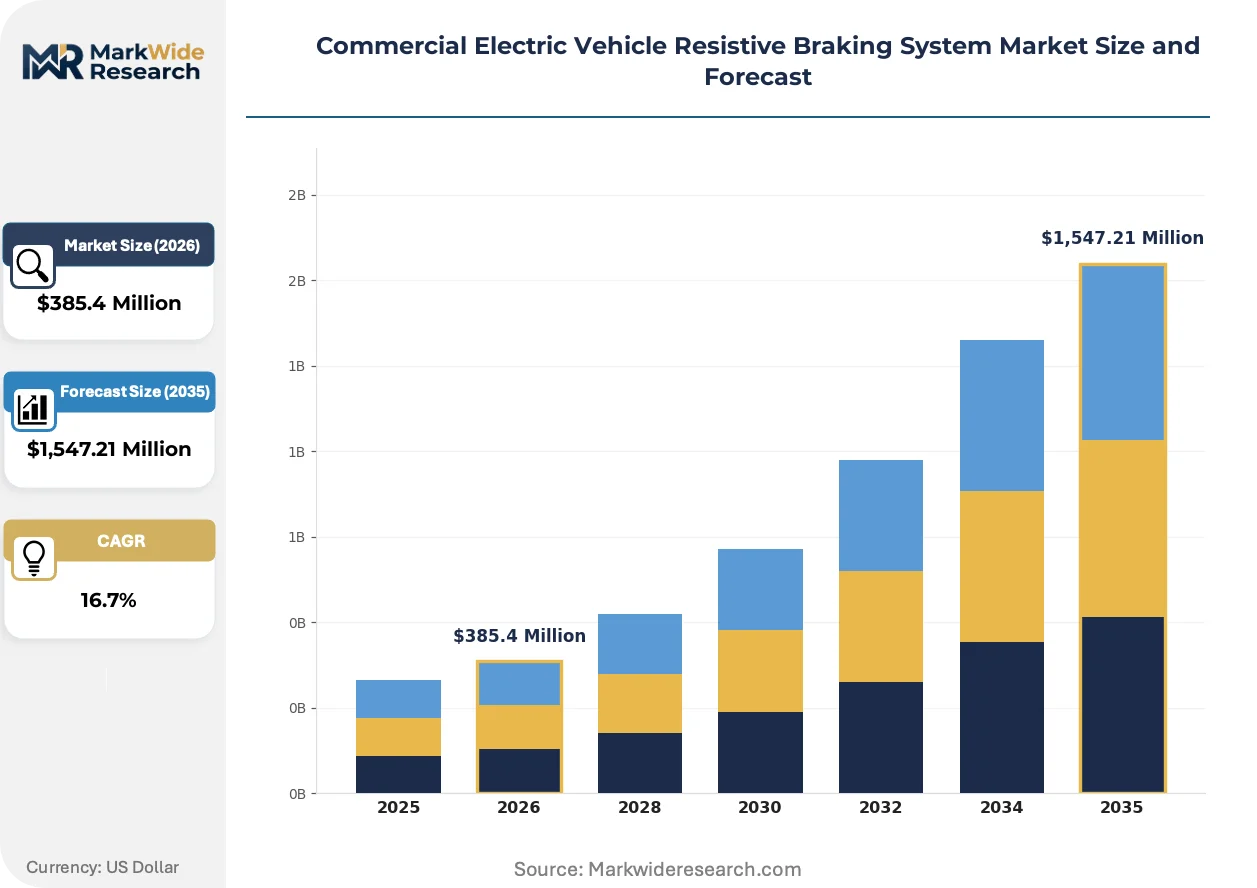
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,547.21 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regenerative Braking, Dynamic Braking, Friction Braking, Electromagnetic Braking Technology: Hydraulic Systems, Pneumatic Systems, Electronic Control Systems, Mechanical Systems End User: Logistics Companies, Public Transport Agencies, Fleet Operators, Delivery Services Installation: OEM Integration, Aftermarket Solutions, Retrofitting, Modular Systems |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Knorr-Bremse AG, Brembo S.p.A., Accelera by Cummins, Denso Corporation, Hitachi Astemo Ltd., BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Electric Vehicle Resistive Braking System Market Strategic Shifts
Commercial EV braking architecture is converging toward intelligent torque-blending systems that dynamically partition kinetic energy dissipation between regenerative recovery and resistive heat rejection based on real-time battery state estimation.
Wire-wound stainless steel resistor grids with active air-gap cooling are integrating into compact module assemblies that mount directly on axle housings, eliminating lengthy power cable runs. Heavy-duty refuse collection operators in German urban centers are specifying these integrated packages to reduce installation complexity on retrofitted diesel chassis. The technology is integrating hydraulic service brakes with electronic resistive control through unified CAN bus architectures, collapsing the supplier tier structure for braking system integration.
REACH substance restrictions on hexavalent chromium coatings are forcing resistor manufacturers to migrate toward trivalent chrome or ceramic passivation surface treatments for corrosion protection. The regulation's industrial consequence is elevated processing cost and extended qualification timelines for wire-wound elements exposed to road salt environments. Scandinavian fleet operators, facing the most aggressive corrosion conditions, are accelerating qualification of alternative coating chemistries ahead of the 2024 sunset date for hexavalent chrome in automotive applications.
Long-term service contracts bundling hardware, firmware updates, and thermal performance monitoring are displacing transactional component sales in municipal bus procurement. European public transport authorities in the Netherlands and Denmark are piloting availability-based payment structures where suppliers guarantee braking thermal capacity over 10-year fleet lifecycles. This model concentrates in markets with mature fleet management software infrastructure and standardized vehicle telematics protocols.
Commercial Electric Vehicle Resistive Braking System Market Segmentation
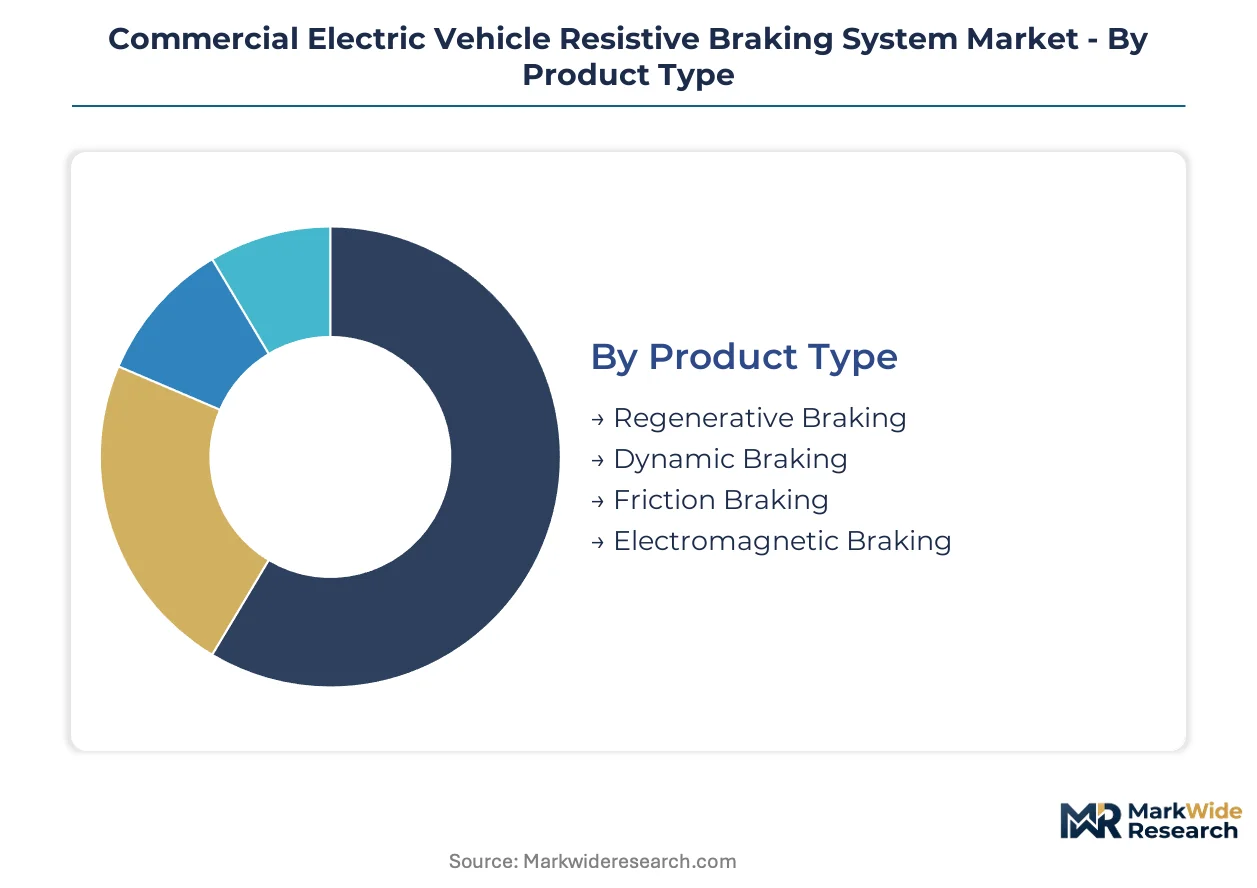
Resistive braking architectures vary sharply in their integration depth, from standalone thermal management modules to embedded firmware layers within unified vehicle control systems. Fleet procurement patterns diverge across these integration levels, with OEM specifications favoring tightly coupled designs while aftermarket channels pursue modular retrofit paths.
Product Type:
Standalone resistive braking modules serve distinct thermal management roles, while embedded configurations blend multiple braking modes through shared power electronics architectures.
- Regenerative Braking:Captures kinetic energy through motor-generator reversal, feeding recovered power back to battery packs. Demand concentrates in urban delivery fleets across Germany and the Netherlands, where stop-start duty cycles maximize energy recovery economics and reduce resistive backup activation frequency.
- Dynamic Braking:Dissipates excess energy through resistive grids when battery charge-acceptance limits are reached. Alpine logistics corridors in Switzerland and Norway drive specification rates, as sustained downhill grades saturate regenerative capacity and mandate thermal redundancy for Class 4-8 electric trucks.
- Friction Braking:Mechanical pad-and-disc systems provide ultimate fail-safe stopping power. Municipal bus operators in Copenhagen and Amsterdam specify hybrid friction-resistive packages for emergency-stop compliance under ECE R13 fade-resistance thresholds.
- Electromagnetic Braking:Eddy-current retarders integrated into driveline housings deliver contactless deceleration. Mining haulage applications in Chile and Australia pilot megawatt-scale electromagnetic modules for continuous-duty downhill payload cycles.
Volume placements concentrate in Regenerative Braking; the faster expansion belongs to Dynamic Braking.
Technology:
Cost tiers separate legacy mechanical implementations from semiconductor-intensive electronic control platforms commanding premium positioning in heavy-duty specifications.
- Hydraulic Systems:Fluid-pressure actuation dominates medium-duty retrofit markets where legacy chassis architectures limit electronic control penetration. German refuse collection fleets specify hydraulic-resistive hybrid packages for compatibility with existing brake line routing.
- Pneumatic Systems:Compressed-air braking retains dominance in heavy-duty long-haul segments through proven reliability under extreme thermal load. ZF Friedrichshafen anchors European manufacturing scale through captive pneumatic module production for 18-tonne and above platforms.
- Electronic Control Systems:Firmware-calibrated torque blending between regenerative and resistive modes commands the deepest margin pools. Robert Bosch GmbH leverages integrated mechatronics portfolios to dominate hydraulic-electronic braking interfaces for heavy-duty OEM integration.
- Mechanical Systems:Direct cable and linkage actuation persists in cost-sensitive emerging market segments. Indian commercial electrification under the PLI scheme favors mechanical-resistive combinations for domestic bus manufacturing cost targets.
Pneumatic Systems retain the largest installed base; Electronic Control Systems are climbing the fastest as silicon carbide power electronics improve switching efficiency.
End User:
Customer types diverge in procurement sophistication, with integrated fleet operators driving availability-based contracting while fragmented delivery services favor transactional component sourcing.
- Logistics Companies:E-commerce parcel fleets operating across topographically challenging European corridors mandate redundant braking thermal capacity. Swiss Alpine routes and Norwegian fjord roads force specification of dynamic braking modules beyond regenerative saturation limits.
- Public Transport Agencies:Municipal bus operators in the Netherlands and Denmark pilot 10-year availability contracts bundling hardware, firmware updates, and thermal performance monitoring. These structures displace transactional sales where fleet management software infrastructure reaches maturity.
- Fleet Operators:Mixed-use commercial vehicle pools balance upfront capital constraints against lifecycle thermal reliability. Scandinavian operators accelerate qualification of trivalent chrome resistor coatings ahead of REACH hexavalent chromium sunset deadlines.
- Delivery Services:Last-mile urban operators prioritize compact module assemblies mounting directly on axle housings. German urban centers specify integrated packages to reduce installation complexity on retrofitted diesel chassis.
Logistics Companies anchor current demand volume; Public Transport Agencies are gaining share fastest through service-contract conversion.
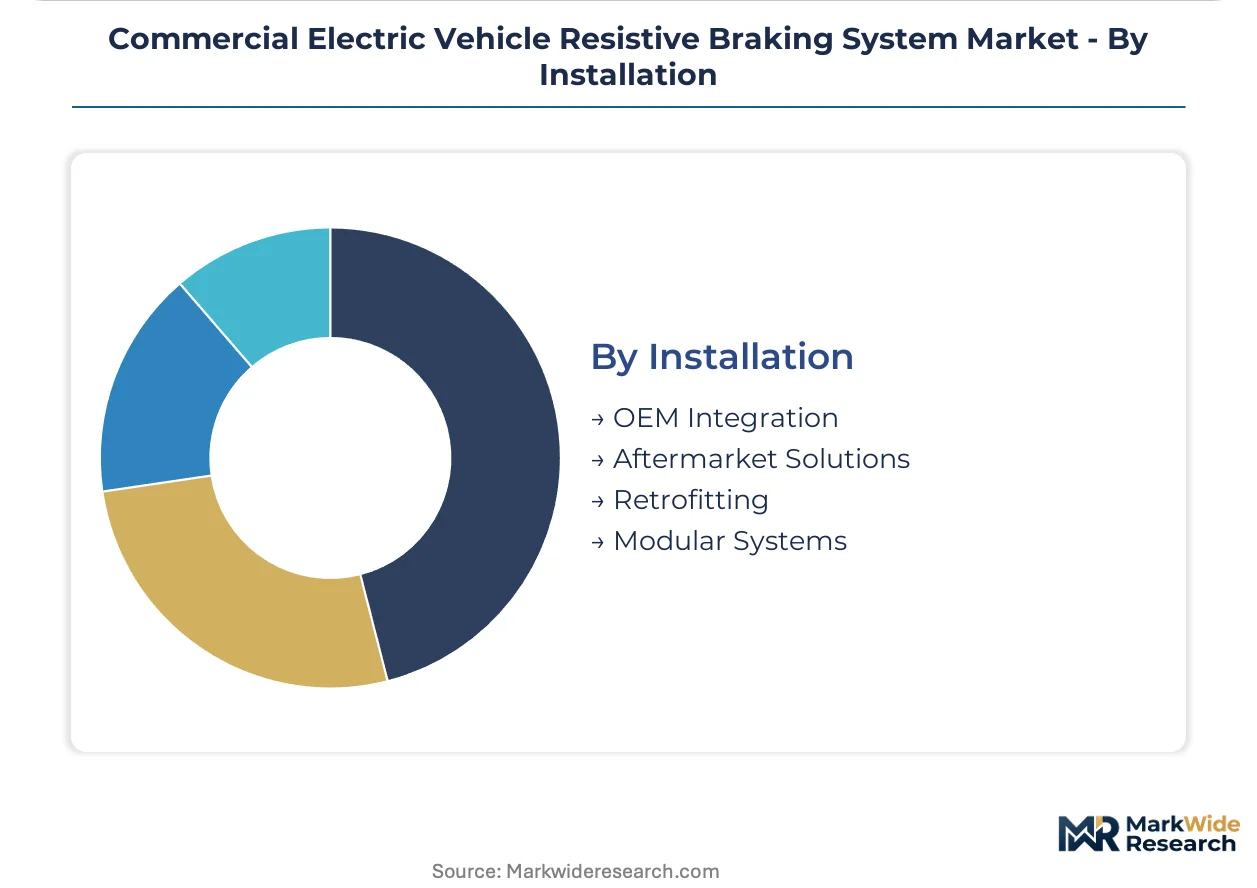
Installation:
Maturity gradients separate factory-integrated designs with unified CAN bus architectures from fragmented aftermarket channels serving fleet electrification retrofits.
- OEM Integration:Factory-installed resistive braking collapses supplier tier structures through unified vehicle control architectures. NHTSA FMVSS 135 stopping-distance requirements in the United States force dual-circuit resistive integration for fail-safe redundancy on Class 4-8 electric trucks.
- Aftermarket Solutions:Post-manufacture installation channels serve diesel-to-electric conversion programs. Copper price volatility from London Metal Exchange swings compresses margin visibility on long-delivery aftermarket contracts.
- Retrofitting:Legacy chassis adaptation demands modular resistor packages with active air-gap cooling. Wire-wound stainless steel grids integrate into compact assemblies eliminating lengthy power cable runs.
- Modular Systems:Standardized resistor and control packages enable rapid field replacement across heterogeneous fleet compositions. ISO 26262 ASIL-D certification for braking control firmware creates service revenue streams through mandatory software update cycles.
OEM Integration commands the revenue concentration; Retrofitting shows the steepest expansion trajectory as fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart industrial corridor anchors European demand through dense OEM supplier networks and ECE R13 Type Approval testing facilities concentrated around ZF Friedrichshafen and Continental AG headquarters.
Germany
Heavy-duty electric truck production in Baden-Württemberg and Lower Saxony drives resistive braking module specifications. ECE R13 braking regulations mandate fade-resistant backup systems for commercial EV Type Approval. Stuttgart anchors R&D clusters where Bosch and Continental co-locate thermal management engineering teams with OEM platform development centers.
United States
Class 4-8 electric truck deployment across Interstate corridor freight routes creates thermal redundancy demand for mountain-grade operations. NHTSA FMVSS 135 stopping-distance requirements force dual-circuit resistive integration for fail-safe compliance. Michigan's Detroit-Warren manufacturing belt concentrates supplier engineering resources for domestic OEM platform integration.
China
Megawatt-scale mining truck electrification in Inner Mongolia and Shanxi province generates demand for continuous-duty resistive braking systems. GB/T standards for commercial vehicle braking performance establish domestic certification thresholds. Yangtze River Delta manufacturing clusters around Shanghai supply resistor grid components for domestic and ASEAN export markets.
Switzerland
Alpine logistics corridors through Gotthard and Simplon passes mandate dynamic braking redundancy beyond regenerative saturation limits. Federal Roads Office braking safety directives enforce thermal capacity verification for heavy electric freight. Zurich-West industrial zone hosts specialist engineering firms calibrating torque-blending algorithms for extreme-grade descent profiles.
India
Commercial bus electrification under the PLI scheme for automotive components creates cost-competitive production opportunities. Central Electricity Authority grid integration standards influence braking energy dissipation specifications for electric commercial vehicles. Tamil Nadu's Sriperumbudur supplier park attracts resistor module assembly investments serving domestic and Southeast Asian fleet operators.
Commercial Electric Vehicle Resistive Braking System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with OEM-integrated electronic control systems commanding premium positioning while pneumatic and hydraulic retrofit channels fragment across regional suppliers. The vendor base concentrates around three strategic archetypes: diversified automotive Tier-1 conglomerates with integrated mechatronics portfolios, captive brake system specialists with heavy-duty thermal management heritage, and emerging power electronics firms leveraging silicon carbide semiconductor advances. Competitive moves center on firmware certification investments for ISO 26262 ASIL-D compliance and backward integration into resistor grid manufacturing to hedge copper price volatility.
Within the diversified Tier-1 tier, Robert Bosch GmbH and Continental AG occupy positions spanning electronic control system development and unified vehicle architecture integration. ZF Friedrichshafen AG anchors European manufacturing scale through captive production capabilities. Knorr-Bremse AG exemplifies the brake-system specialist archetype with concentrated heavy-duty thermal management expertise.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Knorr-Bremse AG |
| Brembo S.p.A. |
| Accelera by Cummins |
| Denso Corporation |
| Hitachi Astemo Ltd. |
| BorgWarner Inc. |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on hexavalent chromium coatings gate qualified supply for corrosion-resistant resistor grids, limiting premium-tier pricing access to manufacturers that have completed trivalent chrome or ceramic passivation qualification ahead of regulatory sunset deadlines. Fleet procurement contracts now embed coating chemistry verification as a price-tier discriminator, compressing margins for non-compliant suppliers while rewarding early adopters with long-delivery offtake premiums.
Pricing Analysis
Short lead-time premiums of 15-25% apply to spot orders for ASIL-D certified electronic control modules, while inventory-heavy distributors discount wire-wound resistor grids to clear copper-price-exposed stock. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified firmware from hydraulic retrofit kits and mechanical-resistive combinations. Cost compression in economy-tier mechanical systems is intensifying because Indian PLI scheme domestic production targets are flooding ASEAN export channels with cost-optimized resistor assemblies. Municipal bus operators in the Netherlands and Denmark show least price sensitivity due to availability-based contract structures, while fragmented last-mile delivery services in German urban centers drive hardest bargain on axle-mounted compact modules.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit-Warren, and Shanghai's Yangtze River Delta anchor hub-and-spoke patterns for resistor grid and power electronics fulfillment. Manufacturing concentrates in Germany, China, and the United States, with wire-wound stainless steel elements drawing from copper alloy suppliers exposed to London Metal Exchange volatility. Rare-earth permanent magnets for braking servomotors rest on Chinese processing facilities, creating single-source vulnerability for European and North American module assemblers. Distribution runs through captive OEM supply agreements for factory-integrated systems, while aftermarket channels fragment across specialized distributors serving diesel-to-electric retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with resistor grid manufacturing and silicon carbide semiconductor sourcing emerging as the decisive upstream levers separating margin leaders from price-takers.
For Market Incumbents: To counter copper price volatility eroding contract margins, secure captive wire-wound resistor production through backward integration into alloy drawing facilities or binding offtake agreements with certified coating suppliers. Anchor electronic control system differentiation through ASIL-D firmware certification investments that lock in 10-year service revenue streams from European public transport authorities. For New Entrants and Emerging Players: Fleet management software vendors represent the most accessible channel partner type for embedded torque-blending algorithm licensing, bypassing capital-intensive hardware manufacturing. Target mining truck electrification in Chile and Australia for megawatt-scale resistive braking white space, and pursue modular retrofit kits for German refuse collection diesel-to-electric conversions as the fastest path to revenue. For Investors and Strategic Acquirers: First-mover trivalent chrome coating qualification ahead of REACH enforcement is the leading indicator that resistor grid specialists will capture sustained premium pricing power. Five-to-ten year viability favors vertically integrated mid-cap manufacturers with captive semiconductor switching component supply, and the signal to watch is silicon carbide foundry capacity allocation announcements from power electronics firms entering automotive braking verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resistor Grid Manufacturing | Captive copper alloy processing hedges London Metal Exchange volatility and secures REACH-compliant coating capacity. |
| ASIL-D Firmware Certification Investment | ISO 26262 compliance enables 10-year availability contracts with Dutch and Danish public transport authorities. |
| Silicon Carbide Power Electronics Partnership | Wider bandgap semiconductors from specialized foundries improve braking chopper duty-cycle efficiency. |
| Mining Truck Electrification Market Entry | Megawatt-scale systems for Chilean and Australian open-pit haulage address untapped continuous-duty demand. |
| Modular Retrofit System Development | Compact axle-mounted packages reduce installation complexity for German urban diesel-to-electric conversions. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, and aftermarket distribution heads. ECE R13 Type Approval documentation, NHTSA FMVSS 135 compliance databases, and REACH substance restriction filings provided regulatory boundary conditions. Bottom-up resistor grid shipment data triangulated against top-down commercial EV production forecasts across the analysis window.
Granularity-level modeling deployed vehicle class, propulsion architecture, and integration depth as primary segmentation dimensions, with regional regulatory cluster and fleet operator procurement sophistication as secondary stratifiers. CAGRs derived from logistic curve adoption modeling calibrated to Alpine logistics corridor deployment rates and municipal bus electrification tender awards. Copper price scenario analysis and silicon carbide semiconductor supply constraints informed sensitivity bounds.
Several conditions sit outside the modeled scope, including unannounced battery chemistry breakthroughs altering regenerative braking saturation thresholds, and geopolitical disruptions to rare-earth magnet supply chains. Forecasts reflect documented assumptions around ECE R13 harmonization timelines and PLI scheme subsidy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Solar Electric Car Market