
 Australia Electric Vehicle Market | 2026-2036
Australia Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Electric Vehicle Market Analysis
Dealer networks and direct-to-consumer digital platforms is reconfiguring how electric vehicles reach Australian buyers, with legacy franchised systems losing ground to manufacturer-controlled channels. Tesla Inc. leverages its company-owned retail and service footprint to control pricing and customer data end-to-end. BYD Company Limited anchors its expansion through partnerships with independent dealer groups and fleet leasing operators. MG Motor Australia competes aggressively on entry-price positioning, sustaining volume through supermarket-style retail locations and online configurators.
An Australia electric vehicle is a road-certified automobile propelled by one or more electric motors drawing energy from rechargeable battery packs, typically lithium-ion configurations with energy densities ranging from 150 to 300 watt-hours per kilogram and operating voltages between 400 and 800 volts. Its primary commercial purpose is to displace internal combustion engines in passenger and light-commercial transport, reducing tailpipe emissions and operational energy costs per kilometer. SUVs dominate current Australian registrations due to consumer preference for ride height and perceived versatility, while sedan volumes are compressing as manufacturers reallocate production capacity. Fleet management channels represent the fastest-expanding demand pool, absorbing vehicles at scale through novated leasing and corporate sustainability mandates, whereas solid-state battery technology remains pre-commercial but holds the deepest margin potential for future premium positioning.
The Australian Design Rules administered by the Department of Infrastructure, Transport, Regional Development, Communications and the Arts govern vehicle safety and emissions compliance, while state-level regulators such as the New South Wales Environment Protection Authority administer zero-emission vehicle rebates and stamp duty exemptions that directly shape purchase timing. The National Electric Vehicle Strategy coordinates federal investment in charging infrastructure along transport corridors, conditioning market access on interoperability standards that manufacturers must satisfy. Stakeholders must monitor how the phase-out of fringe benefits tax thresholds and evolving Australian Competition and Consumer Commission guidance on battery warranty claims will reshape total cost calculations and resale risk profiles.
Market Dynamics
State-based stamp duty waivers and the National Electric Vehicle Strategy are compressing total cost of ownership gaps, pulling fleet operators and private buyers forward in purchase timelines while charging infrastructure deployment lags in regional corridors.
Growth Catalysts
- New South Wales and Victoria incentive stacking:State-level rebates combined with federal fringe benefits tax thresholds reduce upfront acquisition costs for fleet novated leases. Corporate sustainability mandates accelerate bulk procurement decisions.
- Lithium-ion energy density improvements:Cell configurations now deliver 250-300 watt-hours per kilogram, extending range per charge and reducing range anxiety among regional buyers previously locked out of electrification.
- Urban logistics fleet electrification:Last-mile delivery operators face municipal low-emission zone access restrictions, forcing accelerated replacement cycles for diesel vans with battery-electric equivalents.
Market Restraints
- Charging infrastructure deserts:Western Australia and Northern Territory transport corridors lack DC fast-charging density, constraining interstate freight electrification and regional passenger adoption.
- Lithium and cobalt price volatility:Raw material input costs for battery cathode production fluctuate with Democratic Republic of Congo supply disruptions and Chilean lithium brine extraction constraints.
- Grid capacity limitations:Distribution network transformers in older Melbourne and Sydney suburbs require upgrade before supporting residential fast-charging penetration at scale.
Strategic Opportunities
- Solid-state battery pre-commercial positioning:Early mover investment in sulfide-based electrolyte architectures promises 500 watt-hours per kilogram energy density for premium SUV segments.
- Queensland and South Australia penetration gaps:Lower current registration density creates first-mover advantage for manufacturer-direct retail models and independent dealer network expansion.
- Vehicle-to-grid integration:Bi-directional charging hardware enables fleet operators to monetize battery capacity as distributed energy storage during peak demand events.
Industry Challenges
- High-voltage technician certification scarcity:Registered training organizations face capacity constraints producing electricians qualified for 800-volt battery system maintenance and repair.
- Australian Design Rules compliance timelines:Type approval processes for new powertrain architectures extend market entry delays by 12-18 months versus comparable European certifications.
- Residual value forecasting uncertainty:Battery state-of-health measurement standardization gaps complicate secondary market pricing and finance lease structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Electric Vehicle Market |
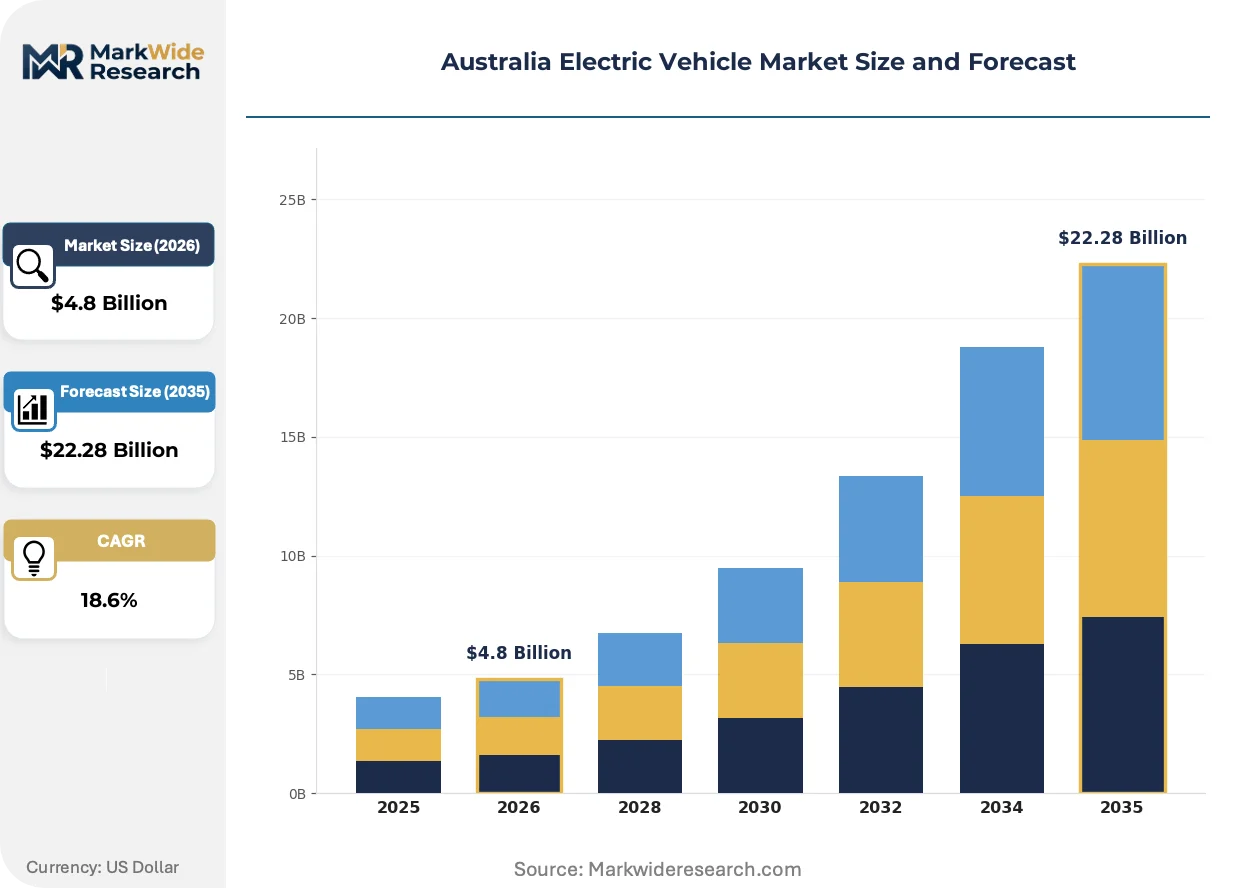
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Hatchbacks, Vans Battery Technology: Lithium-ion, Solid State, Lead Acid, Nickel Metal Hydride Charging Infrastructure: Public Charging Stations, Home Charging Units, Fast Chargers, Wireless Charging Market Segment: Personal Use, Fleet Management, Ride-Sharing, Government Subsidized |
| Companies Covered | BYD Company Limited, Tesla Inc., Kia Motors, Geely Automobile, MG Motor Australia, BMW, Mercedes-Benz, Volvo, Polestar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Electric Vehicle Market Emerging Trajectories
Digital retail platforms and over-the-air software architectures are separating vehicle functionality from hardware refresh cycles, enabling subscription-based feature activation and compressing traditional dealer service revenue streams.
Over-the-air powertrain calibration is virtualizing performance optimization, allowing manufacturers to push efficiency and drivability updates without physical service visits. Fleet operators capture immediate fuel economy gains through remote deployment. This capability compresses competitive differentiation timelines and shifts engineering resources toward continuous software iteration rather than discrete model-year releases.
The Australian Competition and Consumer Commission's evolving guidance on battery warranty claims is reshaping manufacturer liability exposure. Mandatory minimum performance guarantees over eight-year periods force suppliers to reserve balance sheet provisions for replacement cell modules. Premium SUV and light-commercial segments face the steepest compliance cost absorption as these categories carry the largest battery pack capacities.
Direct-to-consumer configurators are displacing traditional showroom negotiation rituals. Buyers in Melbourne and Sydney metropolitan areas complete full purchase journeys online, with physical touchpoints limited to delivery handovers. Independent dealer groups respond by consolidating into multi-brand aggregators, pooling inventory risk across Chinese and European manufacturer portfolios to maintain relevance in lead generation and after-sales service capture.
Australia Electric Vehicle Market Segmentation
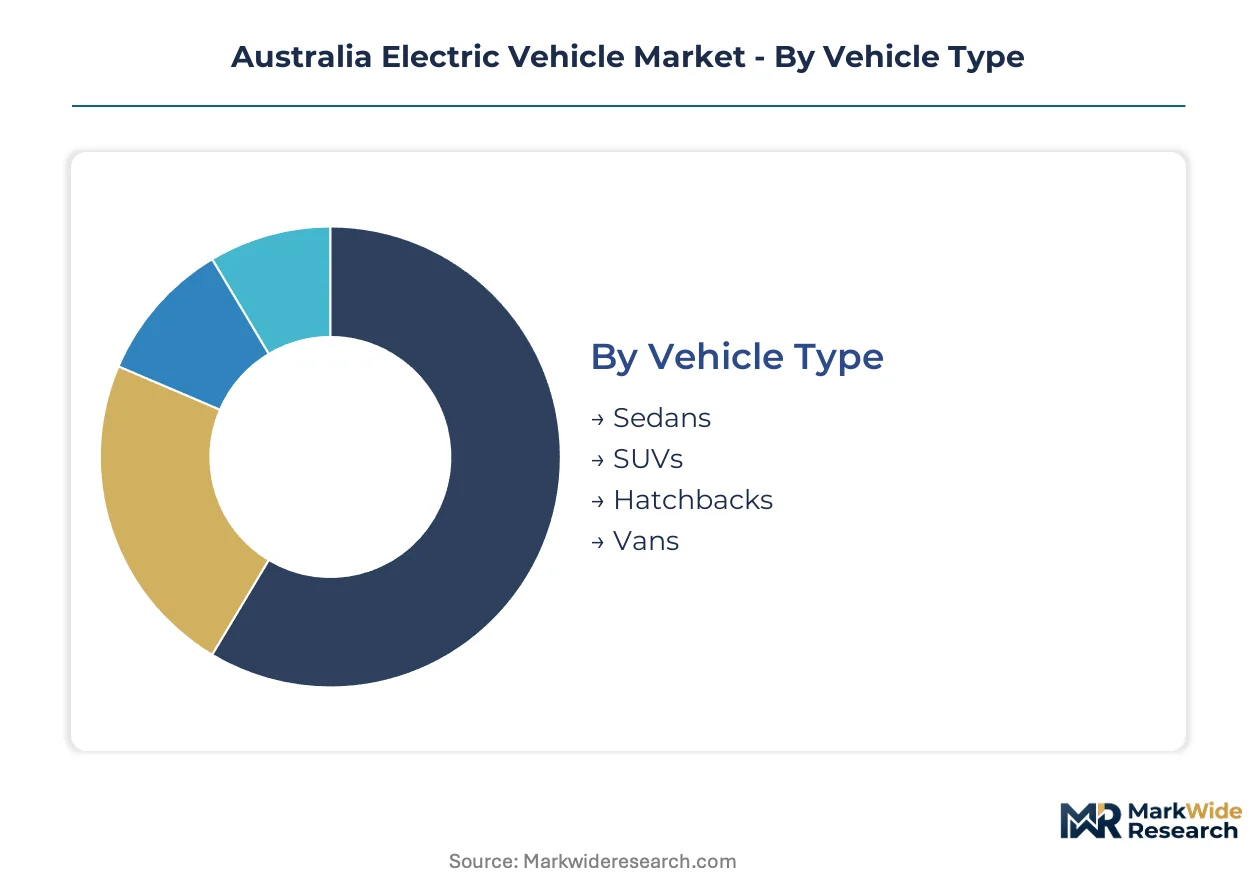
Segmentation reveals how electrification pressures concentrate differently across vehicle architectures, energy storage chemistries, and procurement channels. Fleet operators rotate assets faster than private owners, compressing technology refresh cycles and amplifying demand for standardized charging protocols.
Vehicle Type:
Replacement cycles vary sharply across body styles, with commercial vans turning over every 4-5 years against 8-10 year private passenger horizons.
- SUVs:High ground clearance and towing capacity configurations dominate Australian registrations. Demand clusters in New South Wales and Victoria family segments where all-wheel-drive electrified platforms displace diesel SUVs.
- Vans:Box-body and panel configurations serve urban logistics fleets under municipal low-emission zone mandates. Last-mile operators in Sydney and Melbourne accelerate procurement to maintain CBD access permits.
- Sedans:Three-box passenger configurations carry declining production allocation as manufacturers reallocate capacity toward utility vehicles.
- Hatchbacks:Compact two-box designs attract entry-price private buyers in metropolitan fringe suburbs where garage charging access remains practical.
SUVs dominate installed base. Vans are where expansion concentrates.
Battery Technology:
Cost tiers separate mature cell chemistries from pre-commercial architectures still carrying manufacturing yield penalties.
- Lithium-ion:NMC and LFP cathode configurations deliver 250-300 watt-hours per kilogram with established supply chains. Australian fleet procurement standardizes on these cells for warranty predictability and recycling pathway clarity.
- Solid State:Sulfide and oxide electrolyte architectures promise 500 watt-hours per kilogram density but remain pre-commercial. Premium SUV positioning awaits pilot production scale-up.
- Nickel Metal Hydride:Mature chemistry retains niche presence in hybrid-electric transition vehicles where battery-electric range anxiety persists among regional buyers.
- Lead Acid:Auxiliary power applications and low-speed electric vehicle segments sustain residual demand despite energy density limitations.
Lithium-ion dominates installed base. Solid State is climbing the fastest.
Charging Infrastructure:
Application context dictates hardware specification, with depot-based fleet operations demanding different reliability profiles than opportunistic public charging.
- Public Charging Stations:AC Level 2 and DC fast-charging hardware deployed along transport corridors and retail precincts. Interoperability mandates under the National Electric Vehicle Strategy condition federal funding on multi-network access protocols.
- Fast Chargers:350kW DC hardware enables 10-80% state-of-charge cycles in 20 minutes. Highway corridor gaps in Western Australia and Northern Territory constrain interstate freight electrification.
- Home Charging Units:Wall-mounted AC hardware serves residential garages with overnight charging cycles. Distribution transformer capacity in older Melbourne and Sydney suburbs limits penetration scale.
- Wireless Charging:Inductive pad architectures remain pilot-stage for fleet depot automation and premium residential positioning.
Public Charging Stations dominate installed base. Fast Chargers are gaining share fastest.
Market Segment:
Customer type separates volume procurement with standardized specifications from individualized configuration with extended decision timelines.
- Fleet Management:Novated leasing and corporate sustainability mandates drive bulk procurement through aggregated tender processes. Telstra, Australia Post, and major supermarket chains anchor electrification commitments with thousand-unit orders.
- Personal Use:Individual acquisition through dealer networks or manufacturer-direct platforms. Stamp duty waivers in New South Wales and Victoria compress total cost of ownership calculations for metropolitan buyers.
- Ride-Sharing:Uber and DiDi driver-partners face platform-mandated electrification deadlines with vehicle eligibility restrictions tightening in capital cities.
- Government Subsidized:State-level rebate programs and federal fringe benefits tax thresholds reduce acquisition barriers for eligible applicants through administered application processes.
Fleet Management dominates installed base. Ride-Sharing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Highway Network and Trans-Australian Railway freight corridors underpin interstate commerce flows that condition where electric vehicle charging infrastructure investment concentrates first.
New South Wales
Sydney's metropolitan sprawl and Wollongong industrial corridor generate concentrated fleet procurement from logistics operators. The state Environment Protection Authority administers stamp duty waivers up to specific thresholds for eligible zero-emission vehicles. Newcastle port electrification projects anchor heavy commercial vehicle trials for interstate freight routes.
Victoria
Melbourne's grid density and Geelong manufacturing heritage sustain consumer demand alongside corporate fleet novated leasing. State-based zero-emission vehicle rebates stack with federal fringe benefits tax concessions for qualifying purchasers. The Latrobe Valley transition zone hosts battery energy storage pilot projects tied to vehicle-to-grid integration testing.
Queensland
Brisbane-Southeast Queensland population growth outpaces current charging infrastructure deployment rates. The state transport department coordinates electric vehicle strategy implementation without matching New South Wales incentive depth. Gold Coast tourism operators trial airport transfer electrification to align with sustainability marketing commitments.
Western Australia
Perth's geographic isolation and mining sector fleet requirements create distinctive demand profiles for heavy-duty electrification. The state lacks comparable stamp duty relief, compressing private adoption timelines against eastern state benchmarks. Pilbara resource corridor operators evaluate battery-electric haul truck conversions for site-specific deployment.
South Australia
Adelaide's compact urban footprint supports residential charging penetration with lower grid upgrade urgency than larger capitals. State government procurement mandates for fleet electrification create predictable demand anchors for light-commercial vehicle suppliers. Port Adelaide hydrogen-electric hybrid trials run parallel to pure battery-electric deployment in selected municipal applications.
Australia Electric Vehicle Market Vendor Landscape
On the supply side, the industry is bifurcated between manufacturer-direct retail architectures and legacy franchised dealer networks, with control over pricing and customer data emerging as the decisive competitive variable. Three strategic archetypes populate the field: vertically integrated manufacturers operating owned retail footprints, partnership-dependent entrants leveraging independent dealer aggregators, and price-positioned challengers utilizing supermarket-style retail locations. Dominant competitive moves include direct-to-consumer digital platform deployment and fleet leasing operator alliances that secure volume commitments ahead of production allocation.
Within the manufacturer-direct tier, Tesla Inc. exemplifies end-to-end channel control, while BYD Company Limited anchors partnership-based expansion through independent dealer group relationships. MG Motor Australia occupies the entry-price positioning vector, sustaining volume through retail format experimentation that compresses traditional showroom economics.
| Leading Market Players |
|---|
| BYD Company Limited |
| Tesla Inc. |
| Kia Motors |
| Geely Automobile |
| MG Motor Australia |
| BMW |
| Mercedes-Benz |
| Volvo |
| Polestar |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Western Australian lithium hydroxide refining is compressing margin capture for cathode manufacturers and amplifying price volatility for Australian fleet operators negotiating long-term battery supply agreements. This utilization gap feeds directly into procurement posture, with buyers front-loading orders to lock in cell volumes ahead of further feedstock tightening.
Pricing Analysis
Volume-discount tiering structures separate thousand-unit fleet commitments from single-vehicle retail transactions, with novated leasing aggregators commanding steepest rebates. Price differentiation hinges on battery capacity tier and state-based incentive stacking eligibility, with New South Wales and Victoria registrations carrying implicit premium over Western Australian equivalents. Cost compression in entry-price hatchback segments is intensifying because MG Motor and BYD are reallocating Chinese domestic production surplus into Australian distribution. Fleet management channels exhibit lowest price sensitivity due to total cost of ownership amortization across depreciation cycles, while personal use buyers in Queensland and South Australia remain most responsive to sticker-price movements.
Supply Chain Analysis
Upstream feedstock concentration in Chilean lithium brine operations and Indonesian nickel laterite deposits anchors cathode precursor cost structures for Australian-bound cell production. Battery supply chains draw from Chinese cell manufacturing, South Korean electrolyte formulation, and Japanese separator membrane technologies. Single-source vulnerability in lithium hydroxide refining exposes procurement timelines to Atacama Basin water extraction restrictions. Distribution runs through Port Melbourne and Port Botany container terminals, with last-mile logistics handled by independent dealer group warehousing networks and manufacturer-direct delivery fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from over-the-air software subscriptions and battery health monitoring contracts is expanding faster than hardware sales, reframing manufacturer economics toward recurring-revenue capture.
For Market Incumbents: Entrench control over high-voltage technician certification pipelines by partnering with registered training organizations in Victoria and New South Wales. Lock in fleet leasing operator exclusivity through multi-year service bundling that wraps charging infrastructure deployment with vehicle supply. BYD and Tesla face margin pressure from MG Motor's entry-price positioning, demanding defensive certification investment in Australian Design Rules compliance acceleration. For New Entrants and Emerging Players: Build out independent dealer aggregator partnerships in Queensland and South Australia where manufacturer-direct penetration remains shallow. Regional freight corridors in Western Australia and Northern Territory present the most penetrable white space, with charging infrastructure gaps currently excluding incumbent volume plays. A go-to-market angle anchored in vehicle-to-grid integration pilot programs with state government fleet procurement offers differentiated access against established retail channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet management platform operators with embedded charging infrastructure service layers. Long-term viability over the next decade hinges on solid-state battery pilot production scale-up and sulfide electrolyte manufacturing yield improvement. Acquisition targets should screen for bi-directional charging hardware capabilities and state-level rebate administration relationships. The signal to watch is Australian Competition and Consumer Commission guidance evolution on battery warranty liability allocation between manufacturers and fleet lessors.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with CATL or LG Energy Solution secure cell allocation for Australian fleet deployment. |
| Charging Infrastructure Partnership | Collaboration with Chargefox or Evie Networks accelerates highway corridor coverage in Western Australia and Queensland. |
| Software-Defined Vehicle Investment | Over-the-air architecture development enables subscription revenue from performance and efficiency feature activation. |
| Platform Standardization | Shared skateboard architectures across SUV and van variants compress Australian Design Rules compliance costs. |
| Geographic Manufacturing Footprint | Regional assembly partnerships in Southeast Asia reduce logistics exposure to Port Melbourne container congestion. |
Methodological Framework
Operator-level perspectives from fleet procurement managers at Telstra and Australia Post, dealership operations directors, state transport department electrification leads, and charging network deployment engineers anchored the qualitative base. Primary interview findings triangulated against vehicle registration databases, Australian Bureau of Statistics trade flow records, National Electric Vehicle Strategy implementation reports, and Department of Infrastructure type approval filings. Bottom-up fleet order pipeline aggregation and top-down state-level incentive expenditure tracking were reconciled to validate market sizing.
Scenario-bracketing around lithium price volatility bands and charging infrastructure deployment pace variations framed the projection horizon. Segmentation dimensions modeled include vehicle class, battery chemistry tier, procurement channel, and state-level regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and elasticity-adjusted response to stamp duty waiver introductions. Industry-specific forecast inputs incorporated Australian Design Rules compliance timeline assumptions and grid capacity upgrade scheduling by distribution network service providers.
Stress conditions across lithium carbonate spot price spikes, fringe benefits tax threshold phase-out acceleration, and DC fast-charging deployment shortfalls in regional corridors were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cell energy density improvement trajectories and fleet turnover cycle compression. Cross-checking against state-level zero-emission vehicle registration data published by transport departments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Battery Trays Market