
 Electric Vehicle (EV) Range Extender Market | 2026-2036
Electric Vehicle (EV) Range Extender Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Range Extender Market Foresight
Power electronics engineering talent scarcity is reorganizing how suppliers allocate R&D resources across the EV range extender value chain. Mahle leverages its thermal management expertise to integrate compact combustion-based range extenders into light commercial platforms. AVL anchors European development activity through its powertrain testing and simulation capabilities. Rheinmetall competes via its defense-sector heritage in compact, high-reliability auxiliary power units adapted for civilian automotive use.
An electric vehicle range extender is an auxiliary power generation system—typically comprising a small internal combustion engine, micro-turbine, or fuel cell paired with a generator—that replenishes battery charge during operation rather than directly driving the wheels, thereby extending total driving distance beyond pure-electric range. Fuel cell technology segments command premium positioning due to zero-emission compatibility with hydrogen infrastructure buildouts, though hybrid system deployments currently occupy the broadest manufacturing scale across OEM supply agreements. Generator-based architectures sustain margin concentration in aftermarket retrofit channels serving fleet operators with existing battery electric vehicle assets.
The EPA tailpipe standards and NHTSA fuel economy regulations in the United States shape product certification requirements for range-extended vehicles, while EMA and REACH frameworks in Europe govern chemical substance restrictions in battery and thermal management components. China's MIIT and GB standards dictate domestic homologation protocols that foreign suppliers must navigate for market access. Stakeholders must monitor evolving carbon border adjustment mechanisms and battery passport mandates that will determine which range extender configurations qualify for preferential fleet procurement policies.
Market Dynamics
Fleet operators are eliminating route anxiety through auxiliary power units rather than larger battery packs, compressing total cost of ownership calculations and redirecting supplier R&D toward compact generator architectures.
Growth Catalysts
- EU F-Gas Regulation:Stricter tailpipe emissions standards compel OEMs to integrate auxiliary power units into light commercial platforms to maintain fleet access rights in urban low-emission zones.
- Commercial fleet electrification:Logistics operators with fixed depot infrastructure deploy range-extended vehicles to preserve route flexibility without doubling battery capital expenditure.
- Stuttgart engineering clusters:Concentrated automotive R&D talent in southern Germany accelerates prototype-to-production cycles for compact combustion-based range extender modules.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack pricing fluctuations compress margin visibility for range extender suppliers negotiating long-term fleet supply agreements.
- Power electronics talent scarcity:Semiconductor engineering concentration in East Asian foundries limits European supplier capacity to scale controller production domestically.
- Direct battery electric substitution:Improving energy density in solid-state cell chemistries threatens to obsolete auxiliary power units in premium passenger segments.
Strategic Opportunities
- Hydrogen infrastructure buildouts:Fuel cell range extenders qualify for zero-emission procurement preferences in Germany and the Netherlands as refueling networks expand along freight corridors.
- Aftermarket retrofit channels:Independent fleet service providers install generator-based architectures onto existing battery electric vehicle assets to extend operational life.
- EU Green Deal fleet mandates:Carbon border adjustment mechanisms create procurement advantages for range-extended commercial vehicles with documented supply chain emissions.
Industry Challenges
- Power electronics integration complexity:Thermal management engineers must reconcile combustion engine heat rejection with battery thermal stability in compact packaging envelopes.
- Multi-jurisdiction homologation timelines:Suppliers face divergent EPA, NHTSA, and MIIT certification protocols that delay product launches across Atlantic and Pacific markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Range Extender Market |
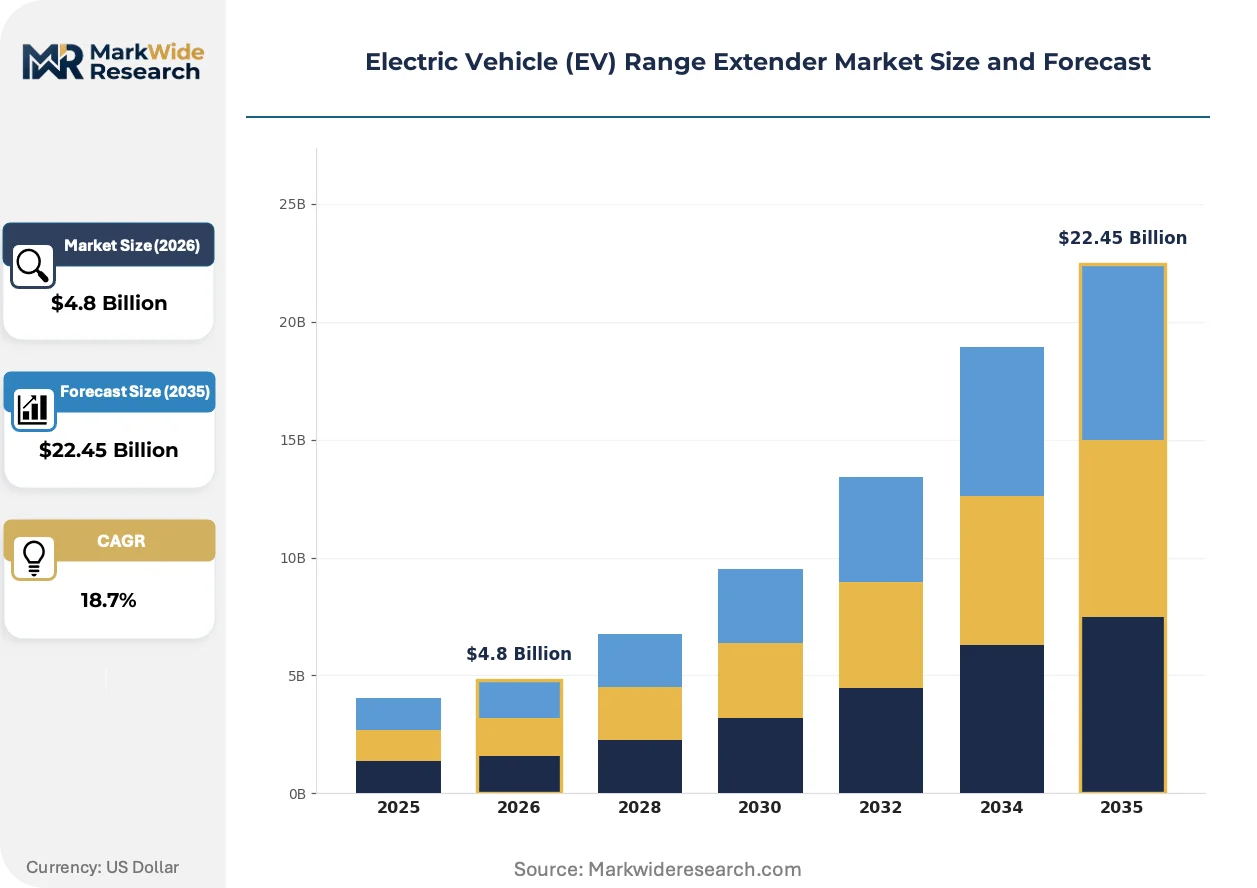
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Battery Electric, Fuel Cell, Hybrid System, Generator End User: OEMs, Fleet Operators, Individual Consumers, Research Institutions Deployment: On-road, Off-road, Urban, Rural Component: Battery, Electric Motor, Control Unit, Thermal Management |
| Companies Covered | Horse Powertrain, AVL, Mahle, Rheinmetall, Hyundai Mobis, AB Volvo, Valeo, Magna International, Schaeffler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Range Extender Market Shifts & Advancements
Compact fuel cell architectures are compressing the technical boundary between zero-emission compliance and operational range flexibility, forcing incumbent suppliers to recalibrate thermal management competencies.
Micro-turbine range extenders are supplanting reciprocating combustion engines in premium commercial applications. Urban delivery fleets with predictable duty cycles adopt these systems for reduced vibration and maintenance intervals. The technology is supplanting conventional auxiliary power units in segments where noise regulations and driver comfort premiums command pricing power.
The EU F-Gas Regulation and REACH frameworks are restricting chemical substances in battery thermal management components. OEMs reformulate coolant chemistries and sealing materials to maintain market access. Light commercial vehicle platforms face the steepest compliance redesign burden as they balance cost sensitivity with substance restriction adherence.
Service-unbundling is fragmenting how fleet operators acquire range extender capability. Leasing companies separate hardware provision from maintenance and energy supply, compressing supplier margin capture. Germany and the Netherlands exhibit the most advanced unbundling as fleet managers prioritize operational expenditure predictability over capital ownership.
Electric Vehicle (EV) Range Extender Market Segmentation
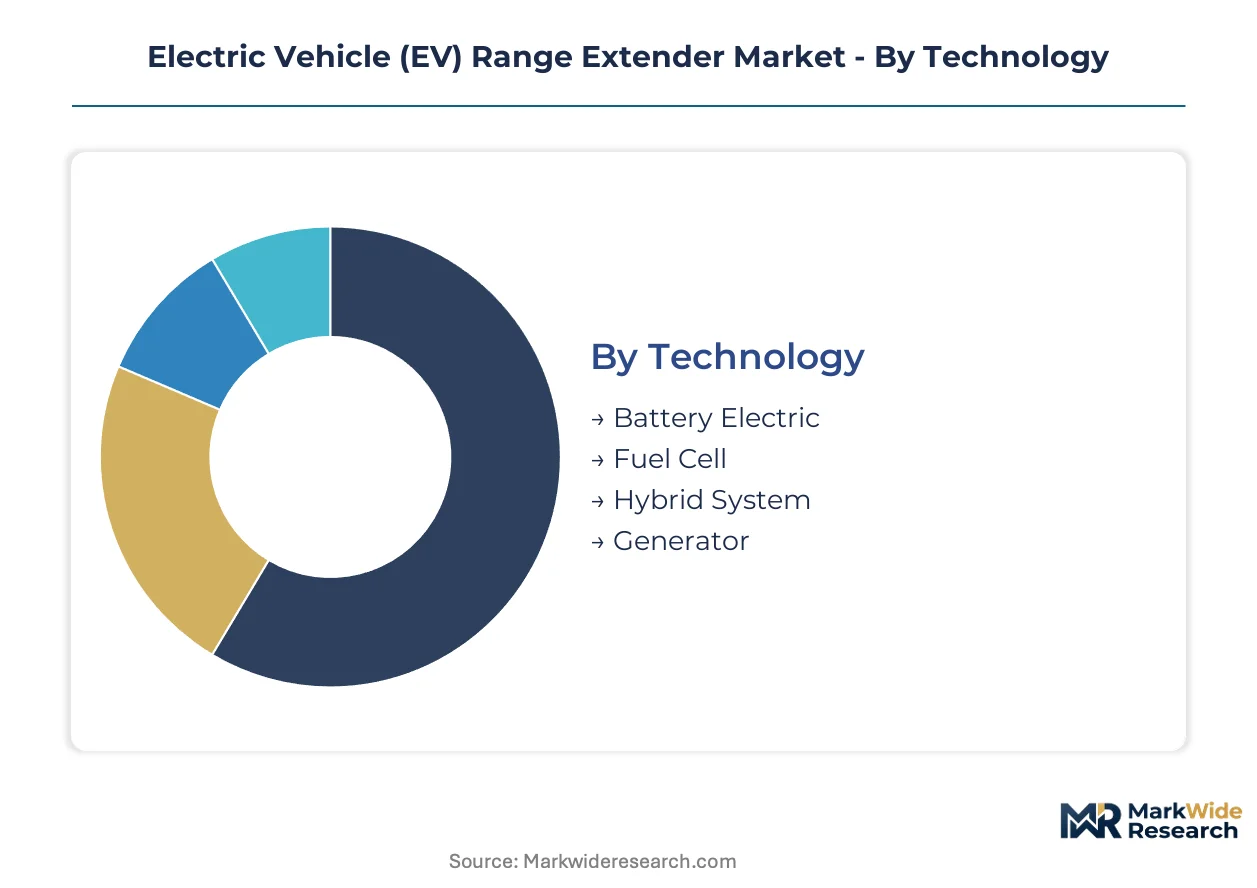
Technology differentiation determines regulatory compliance pathways and procurement eligibility across fleet segments. End-user concentration shapes volume allocation between factory-integrated and aftermarket retrofit channels.
Technology:
EPA tailpipe standards and EU F-Gas Regulation create divergent certification burdens that segment manufacturers by emissions compliance capability.
- Hybrid System:Combines combustion-based auxiliary power units with battery electric architectures to preserve urban low-emission zone access. Demand concentrates among German light commercial fleets balancing route flexibility with EU Green Deal fleet mandates.
- Fuel Cell:Hydrogen-fed proton exchange membrane systems deliver zero-emission operation compatible with carbon border adjustment mechanisms. Procurement preferences in the Netherlands and Germany along freight corridors concentrate adoption among long-haul operators.
- Battery Electric:Extended-range configurations through larger pack capacities.
- Generator:Compact combustion-based architectures for aftermarket retrofit deployment.
Established volume favors Hybrid System; emerging adoption favors Fuel Cell.
End User:
Capital deployment patterns separate factory-integrated procurement from operational expenditure models in aftermarket channels.
- Fleet Operators:Logistics providers with fixed depot infrastructure deploy range-extended vehicles to eliminate route anxiety without doubling battery capital expenditure. German urban delivery networks concentrate procurement volume.
- OEMs:Stuttgart and Munich engineering clusters integrate compact range extender modules into light commercial platforms during original assembly.
- Individual Consumers:Private vehicle owners seeking extended-range passenger applications.
- Research Institutions:Prototype testing and validation programs for next-generation thermal management integration.
Procurement scale tilts toward Fleet Operators; technology validation concentrates with Research Institutions.
Deployment:
Duty cycle predictability determines auxiliary power unit sizing and thermal management packaging constraints.
- Urban:Stop-start delivery routes with predictable regeneration profiles favor compact generator architectures.
- On-road:Highway freight corridors with steady-state operation.
- Off-road:Construction and agricultural applications with variable load profiles.
- Rural:Extended distances between refueling infrastructure.
Volume concentration sits with Urban deployment; infrastructure gaps sustain Rural demand.
Component:
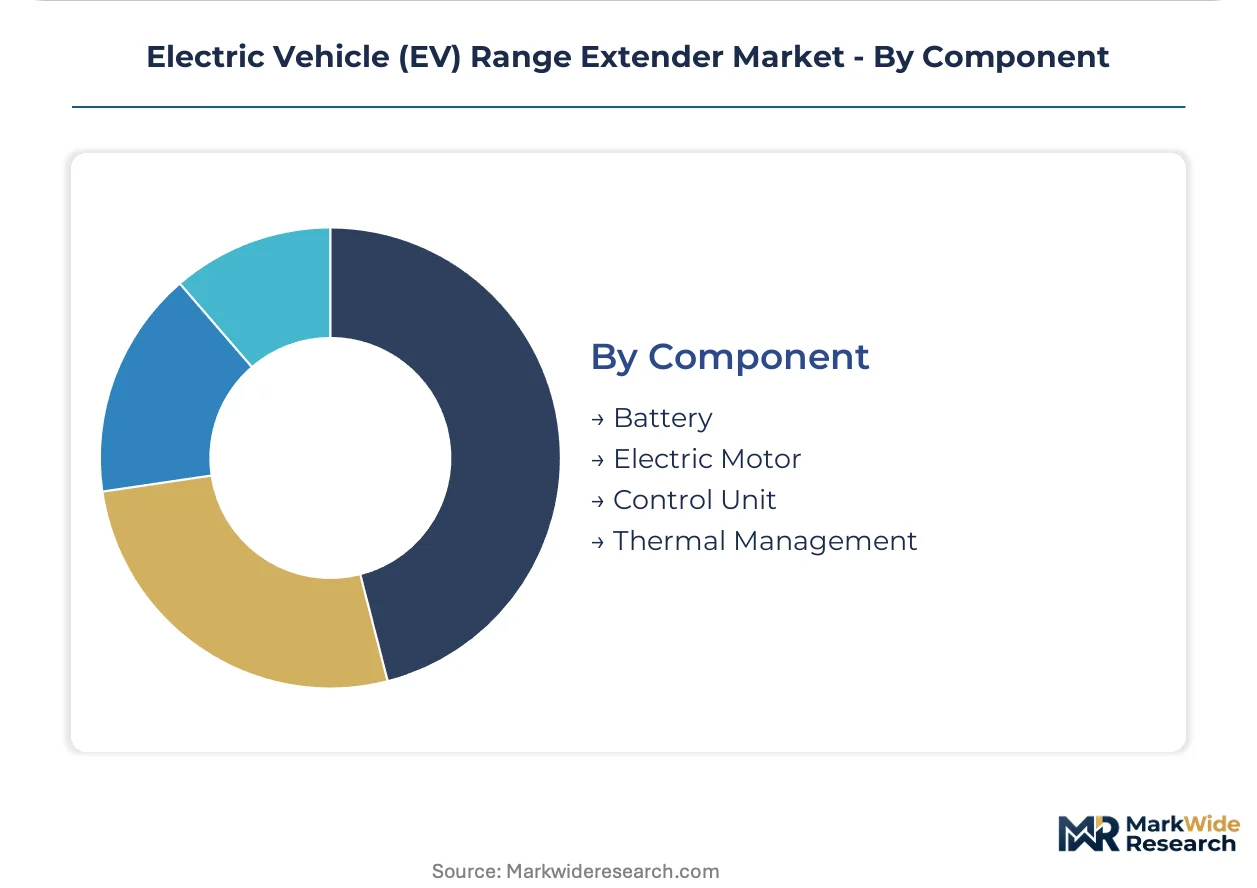
REACH framework substance restrictions reshape supplier qualification for thermal management and battery subsystem integration.
- Thermal Management:Coolant chemistries and sealing materials face reformulation requirements under EU chemical substance restrictions. Light commercial platforms bear the steepest compliance redesign burden.
- Control Unit:Power electronics engineering scarcity limits European domestic scaling capacity.
- Battery:Cell chemistry selection determines range extender duty cycle and charging protocol compatibility.
- Electric Motor:Traction motor specification for auxiliary power unit integration.
Margin capture concentrates in Thermal Management; engineering scarcity elevates Control Unit pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European demand as Stuttgart engineering clusters accelerate compact range extender prototype-to-production cycles. Fleet operators across multiple geographies deploy auxiliary power units to eliminate route anxiety without doubling battery capital expenditure.
Germany
Urban low-emission zone access drives light commercial fleet procurement of hybrid range extenders. The EU Green Deal fleet mandates and carbon border adjustment mechanisms shape OEM integration strategies. Stuttgart and Munich engineering clusters concentrate R&D talent for compact combustion-based module development.
United States
EPA tailpipe standards and NHTSA fuel economy regulations compress product certification timelines for range-extended vehicles. Fleet operators with fixed depot infrastructure prioritize operational expenditure predictability over capital ownership. Detroit automotive engineering centers prototype generator architectures for aftermarket retrofit channels.
China
MIIT and GB standards dictate domestic homologation protocols that foreign suppliers navigate for market access. Logistics operators along freight corridors deploy range-extended commercial vehicles to preserve route flexibility. Yangtze River Delta manufacturing clusters scale power electronics controller production for auxiliary power unit integration.
Netherlands
Hydrogen infrastructure buildouts along freight corridors concentrate fuel cell range extender adoption among long-haul operators. Carbon border adjustment mechanisms create procurement advantages for vehicles with documented supply chain emissions. Rotterdam port logistics networks pilot zero-emission range-extended heavy commercial platforms.
Japan
METI industrial policy supports fuel cell technology development for zero-emission range extender applications. Solid-state battery research threatens to compress auxiliary power unit relevance in premium passenger segments. Nagoya automotive engineering clusters advance micro-turbine architectures for reduced vibration commercial deployment.
Electric Vehicle (EV) Range Extender Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the EV range extender value chain. The supplier base organizes around thermal management specialists, powertrain testing integrators, and defense-sector heritage manufacturers with compact auxiliary power unit expertise. Three archetypes dominate: integrated tier-one automotive suppliers with captive thermal management capabilities; independent engineering services firms anchoring European development activity; and diversified industrial conglomerates adapting military-specification reliability standards for civilian automotive use. Competitive moves concentrate on strategic partnerships for power electronics sourcing and geographic expansion into hydrogen infrastructure corridors.
Among European-based engineering specialists, AVL occupies a position exemplifying powertrain testing and simulation capabilities that anchor continental development activity. Mahle represents the integrated tier-one archetype, leveraging thermal management expertise for compact combustion-based range extender integration. Rheinmetall sits within the defense-heritage manufacturer tier, adapting compact high-reliability auxiliary power unit designs for civilian light commercial platforms.
| Leading Market Players |
|---|
| Horse Powertrain |
| AVL |
| Mahle |
| Rheinmetall |
| Hyundai Mobis |
| AB Volvo |
| Valeo |
| Magna International |
| Schaeffler |
| Others |
Supply & Pricing Matrix
Capacity utilization at Yangtze River Delta power electronics foundries compresses margin structures for European range extender suppliers while elevating price floors for thermal management subsystems. German OEM procurement teams negotiate long-term offtake agreements that lock in generator architecture costs against lithium-ion cell volatility.
Pricing Analysis
Price spreads between Stuttgart-integrated factory systems and Dutch aftermarket retrofit channels reflect certification-grade differentiation under EU F-Gas Regulation tiers. Three-tier pricing structure across premium fuel cell, standard hybrid, and economy generator configurations tracks thermal management complexity and REACH compliance burden. Cost compression in economy generator tiers intensifies because fleet operators unbundle hardware from maintenance contracts. Light commercial fleet operators exhibit highest price sensitivity; long-haul hydrogen corridor operators show lowest.
Supply Chain Analysis
Strategic stockpiling of power electronics controllers dominates supplier inventory strategy as semiconductor engineering scarcity extends lead times for European domestic scaling. Component sourcing draws from China for battery cells, South Korea for power semiconductors, and Germany for precision thermal management hardware. Rare earth magnet dependencies for traction motors and proton exchange membrane supply concentration create single-source vulnerability exposure. Distribution runs through captive OEM supply agreements and independent fleet service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as fleet electrification capital expenditure cycles bottom and EU Green Deal procurement mandates accelerate replacement demand.
For Market Incumbents: Fortify thermal management subsystem control through backward integration into coolant chemistry formulation, countering REACH-driven supplier qualification disruptions. Expand controller production partnerships with Yangtze River Delta foundries to offset European power electronics engineering scarcity. Prioritize certification investment for EU F-Gas Regulation tier advancement. For New Entrants and Emerging Players: Aftermarket retrofit service gaps where incumbent suppliers under-serve aging battery electric vehicle fleets present immediate white-space opportunity. Target German urban delivery networks with highest route anxiety concentration and lowest hydrogen infrastructure proximity. Pursue leasing company partnerships for operational expenditure-based hardware provision. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors thermal management specialists with REACH-compliant material portfolios over pure power electronics plays. Five-to-ten year viability hinges on solid-state battery substitution timelines in premium passenger segments. Monitor hydrogen infrastructure buildout velocity along Rotterdam-Antwerp freight corridors as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Power Electronics Sourcing Partnership | East Asian foundry agreements offset European engineering scarcity for controller production scaling. |
| Hydrogen Infrastructure Alignment | Freight corridor refueling network proximity qualifies fuel cell architectures for zero-emission procurement preferences. |
| REACH Compliance Certification | Thermal management subsystem qualification secures OEM integration slots under EU chemical substance restrictions. |
| Aftermarket Service Channel Development | Independent fleet service partnerships capture retrofit demand from existing battery electric vehicle assets. |
| Compact Generator Architecture R&D | Micro-turbine development addresses noise regulation premiums in urban commercial delivery applications. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, and thermal management R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with aftermarket service providers and hydrogen infrastructure developers. Secondary validation drew from MIIT homologation filings, EPA certification databases, EU F-Gas Regulation implementation guidance, and vehicle production registration data. Bottom-up volume estimates triangulated against top-down fleet electrification expenditure models.
Segmentation dimensions modeled span technology architecture, end-user procurement pattern, deployment duty cycle, and component subsystem across the projection horizon. CAGRs derived from fitted growth curves applied to fleet penetration scenarios and regulatory mandate timelines. Industry-specific forecast inputs incorporated hydrogen refueling station deployment trajectories and solid-state battery chemistry advancement indicators.
Underlying assumptions cover EU Green Deal fleet mandate enforcement consistency and lithium-ion cell cost stabilization, with deviation risk concentrated in carbon border adjustment mechanism implementation timing and power electronics trade flow disruptions. Revision becomes warranted when hydrogen infrastructure buildout velocity or solid-state battery commercialization timelines cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
US Electric Vehicle Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market