
 Global Automotive High-Performance Electric Vehicles Market | 2026-2036
Global Automotive High-Performance Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive High-Performance Electric Vehicles Market Analysis
Subscription-based leasing and battery-as-a-service financing is reshaping how buyers access high-performance electric vehicles without full capital outlay. Tesla leverages its captive finance arm to control the ownership lifecycle, while BYD Auto anchors its competitive edge through in-house battery production that compresses cost structures. Rimac Automobili specializes in hypercar powertrain systems, supplying technology to multiple OEM partners rather than competing solely at the vehicle level.
Automotive high-performance electric vehicles integrate multi-motor drivetrains producing over 500 kW, liquid-cooled battery packs with energy densities exceeding 250 Wh/kg, and torque-vectoring control systems for sub-three-second acceleration. The primary commercial purpose centers on delivering internal-combustion-equivalent or superior driving dynamics while eliminating tailpipe emissions. Sedans currently dominate volume shipments among product types, though SUVs are capturing margin pools as consumers prioritize cabin space alongside acceleration metrics. Solid-state battery technology sits furthest from commercialization but commands the deepest R&D allocation due to its energy density and thermal stability advantages.
The EU Green Deal and EPA tailpipe standards in the United States are tightening CO2 thresholds, forcing OEMs to expand high-performance electric lineups to offset fleet averages. China's MIIT dual carbon goals and NEV credit mandates push domestic manufacturers toward premium electrification segments. Stakeholders must monitor how solid-state battery manufacturing scale and charging infrastructure density evolve as the decisive variables for mass-market accessibility of high-performance variants.
Market Dynamics
Silicon-anode lithium-ion cell chemistry is redrawing competitive boundaries as manufacturers chase energy density thresholds above 300 Wh/kg, forcing capital reallocation toward South Korean and Japanese production clusters while marginalizing legacy nickel-cobalt supply chains.
Growth Catalysts
- EU Green Deal fleet targets:Germany's premium consumer segments and commercial fleet operators are expanding high-performance EV orders to meet tightening CO2 thresholds, pulling volume through the EU regulatory framework.
- Battery-as-a-service financing:Subscription-based leasing models are eliminating upfront capital barriers for buyers, accelerating adoption among price-sensitive performance enthusiasts who previously deferred purchases.
- South Korean manufacturing concentration:Advanced cell fabrication capabilities in Gwangju and Ulsan are attracting powertrain engineering talent and R&D investment, creating self-reinforcing ecosystem effects.
Market Restraints
- Lithium price volatility:Raw material input swings are compressing gross margins for battery pack assemblers unable to pass through costs to locked-in vehicle contracts.
- Single-source silicon anode supply:Dependence on Japanese chemical processors for high-purity metallurgical-grade silicon creates geographic concentration risk with limited near-term alternatives.
- Thermal runaway limitations:Current liquid-cooled architectures impose hard caps on sustained track-day performance, restricting addressable market to street-use cases.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic manufacturing incentives are opening white space for localized assembly of performance EV components previously imported from East Asia.
- Vehicle-to-grid integration:Bidirectional charging capabilities are converging with home energy storage systems, creating new revenue streams for owners in deregulated electricity markets.
- EPA tailpipe standard tightening:US regulatory pressure is forcing OEM portfolio expansion into high-performance electrified variants to offset ICE fleet averages, generating supplier demand.
Industry Challenges
- Power electronics engineering scarcity:Shortages of specialists in wide-bandgap semiconductor integration are extending development timelines for 800V architectures.
- Homologation timeline compression:Accelerated certification requirements under evolving UN ECE regulations are straining validation resources across multiple target markets simultaneously.
- Legacy dealership integration friction:Direct-to-consumer sales models are clashing with established franchise networks, creating channel conflict in key states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive High-Performance Electric Vehicles Market |
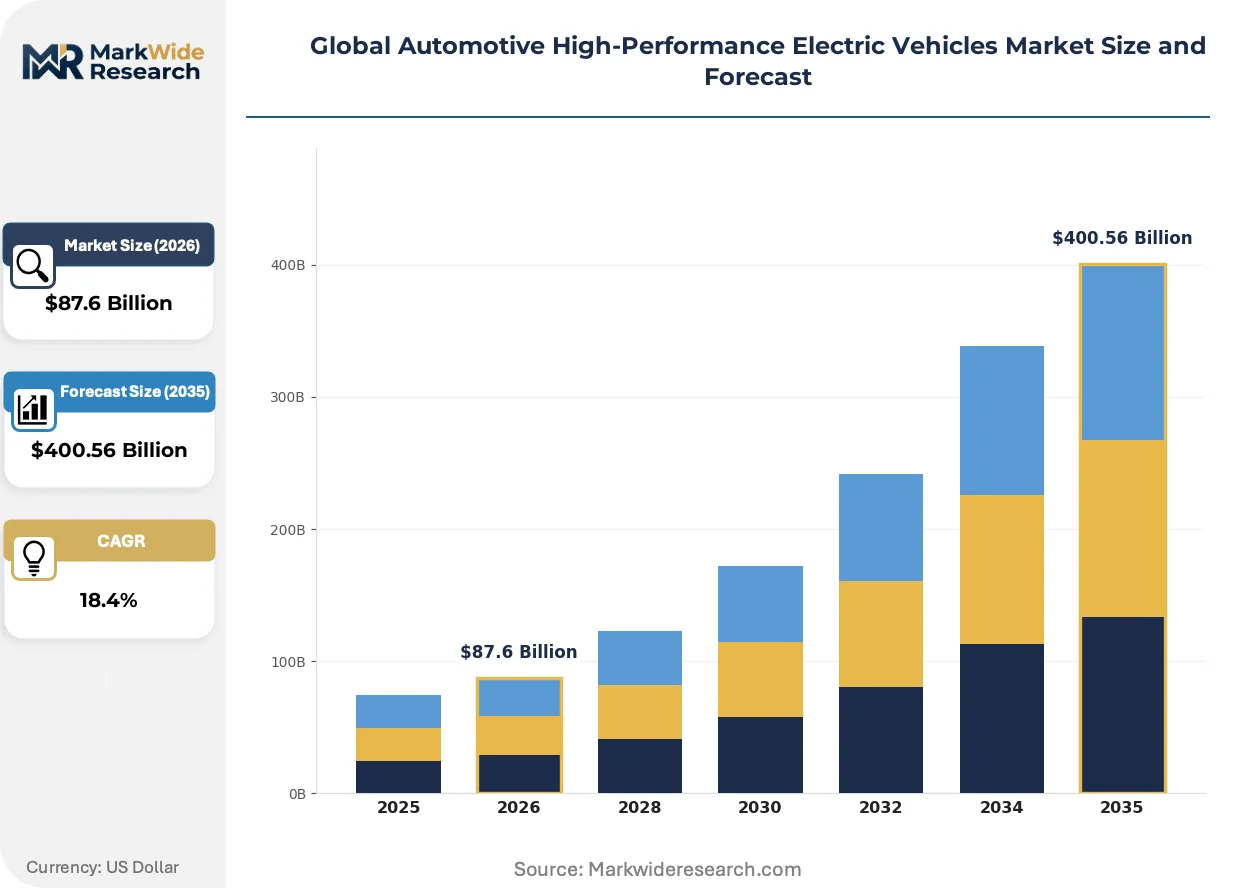
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Coupes, Hatchbacks Battery Technology: Lithium-ion, Solid-State, Nickel-Metal Hydride, Lead-Acid Performance Category: High-Performance, Eco-Friendly, Luxury, Off-Road Charging Infrastructure: Fast Chargers, Home Chargers, Public Charging Stations, Wireless Charging |
| Companies Covered | Tesla, BYD Auto, Volkswagen Group, BMW Group, Mercedes-Benz Group, Rimac Automobili, Porsche, General Motors, Hyundai Motor Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive High-Performance Electric Vehicles Market Emerging Trajectories
Powertrain architecture and ownership models are diverging simultaneously as silicon-anode cells enable new performance envelopes while financing innovation unlocks customer segments previously priced out of the category.
Silicon-anode lithium-ion technology is hybridizing conventional graphite anodes with metallurgical silicon composites to boost energy density beyond 300 Wh/kg. Performance EV manufacturers in South Korea and Japan are adopting this chemistry at pilot scale for 2026 model year platforms. The technology is hybridizing cost structures by reducing cobalt dependency while extending range benchmarks that previously required larger, heavier packs.
EPA tailpipe standards and the EU Green Deal are tightening CO2 fleet thresholds in parallel, forcing OEMs to expand high-performance electric lineups as compliance instruments rather than niche offerings. German fleet operators are responding with accelerated procurement timelines to lock in vehicle allocations ahead of stricter phase-in dates. Sedan and SUV segments are most affected, with product planners rebalancing ICE-to-EV mix ratios in real time.
Subscription-based vehicle access is displacing traditional ownership among urban performance enthusiasts who prioritize flexibility over asset accumulation. Direct-to-consumer digital channels are capturing these buyers, bypassing legacy dealership networks that lack inventory transparency. This pattern is most visible in California and Germany, where charging infrastructure density supports usage without home garage requirements.
Global Automotive High-Performance Electric Vehicles Market Segmentation
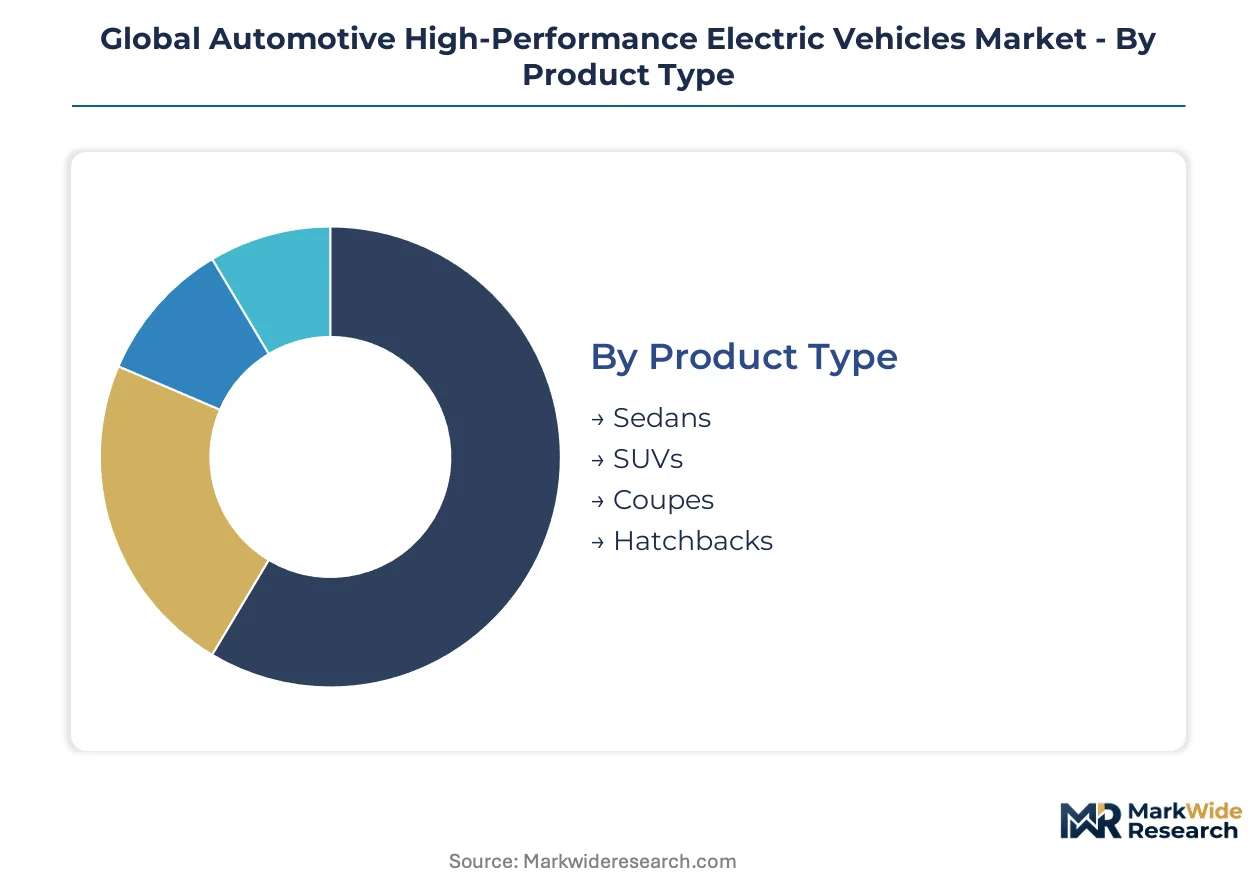
High-performance electric vehicles fragment across four structural dimensions that determine engineering investment priorities and go-to-market economics. Product type and battery chemistry drive manufacturing scale decisions, while performance positioning and charging infrastructure shape regional deployment strategies and margin capture.
Product Type:
Mature volume categories coexist with emerging body styles as consumer preferences split between established silhouettes and utility-driven alternatives.
- Sedans:Low-slung aerodynamic profiles optimize battery pack integration beneath the cabin floor, preserving center-of-gravity advantages for torque-vectoring dynamics. German and South Korean fleet operators in the premium corporate segment anchor procurement volumes as EU Green Deal compliance deadlines tighten.
- SUVs:Elevated ride heights accommodate larger battery enclosures without compromising interior packaging, though aerodynamic drag penalties demand higher energy density cells to maintain range benchmarks. Cabin space priorities among family-oriented buyers in California and Bavaria are pulling margin concentration toward this body style.
- Coupes:Two-door configurations sacrifice rear passenger accessibility for structural rigidity and weight reduction, appealing to enthusiast segments prioritizing track-day performance over daily utility.
- Hatchbacks:Compact footprints with versatile cargo openings serve urban density constraints in Tokyo and Seoul, where parking scarcity and narrow roadways favor shorter wheelbases.
Sedans retain volume leadership; SUVs hold the steepest expansion curve.
Battery Technology:
Cost tier stratification separates commercially deployed chemistries from laboratory-stage alternatives, with manufacturing scale determining near-term feasibility.
- Lithium-ion:Silicon-anode variants hybridizing graphite with metallurgical silicon composites are achieving energy densities above 300 Wh/kg in South Korean pilot lines. Liquid-cooled thermal management architectures dominate current production, though sustained high-load operation remains constrained by runaway risks.
- Solid-State:Ceramic or polymer electrolyte architectures promise thermal stability and energy density thresholds exceeding 400 Wh/kg, but manufacturing yield challenges and dry-room fabrication costs limit commercialization timelines.
- Nickel-Metal Hydride:Mature chemistry retains niche applications in mild-hybrid performance variants where power density requirements fall below full electrification thresholds.
- Lead-Acid:Auxiliary power applications in legacy vehicle electrics persist for 12V subsystem support, though energy-to-weight ratios exclude propulsion duty.
Lithium-ion retains volume leadership; solid-state holds the steepest expansion curve.
Performance Category:
Customer type differentiation separates compliance-driven procurement from discretionary enthusiast purchases, with distinct margin profiles across each tier.
- High-Performance:Multi-motor drivetrains exceeding 500 kW output with sub-three-second acceleration capabilities define this segment. Track-day enthusiasts and premium fleet operators in Germany and California drive specification demands for thermal management and brake regeneration systems.
- Eco-Friendly:Efficiency-optimized powertrain calibrations prioritize range extension over absolute acceleration, appealing to carbon-conscious buyers balancing environmental credentials with daily usability.
- Luxury:Cabin material quality, autonomous driving feature integration, and brand heritage command price premiums independent of raw performance metrics.
- Off-Road:Raised suspension travel, underbody protection, and torque-vectoring calibration for loose surfaces address recreational and commercial applications in terrain-constrained geographies.
High-performance retains volume leadership; eco-friendly holds the steepest expansion curve.
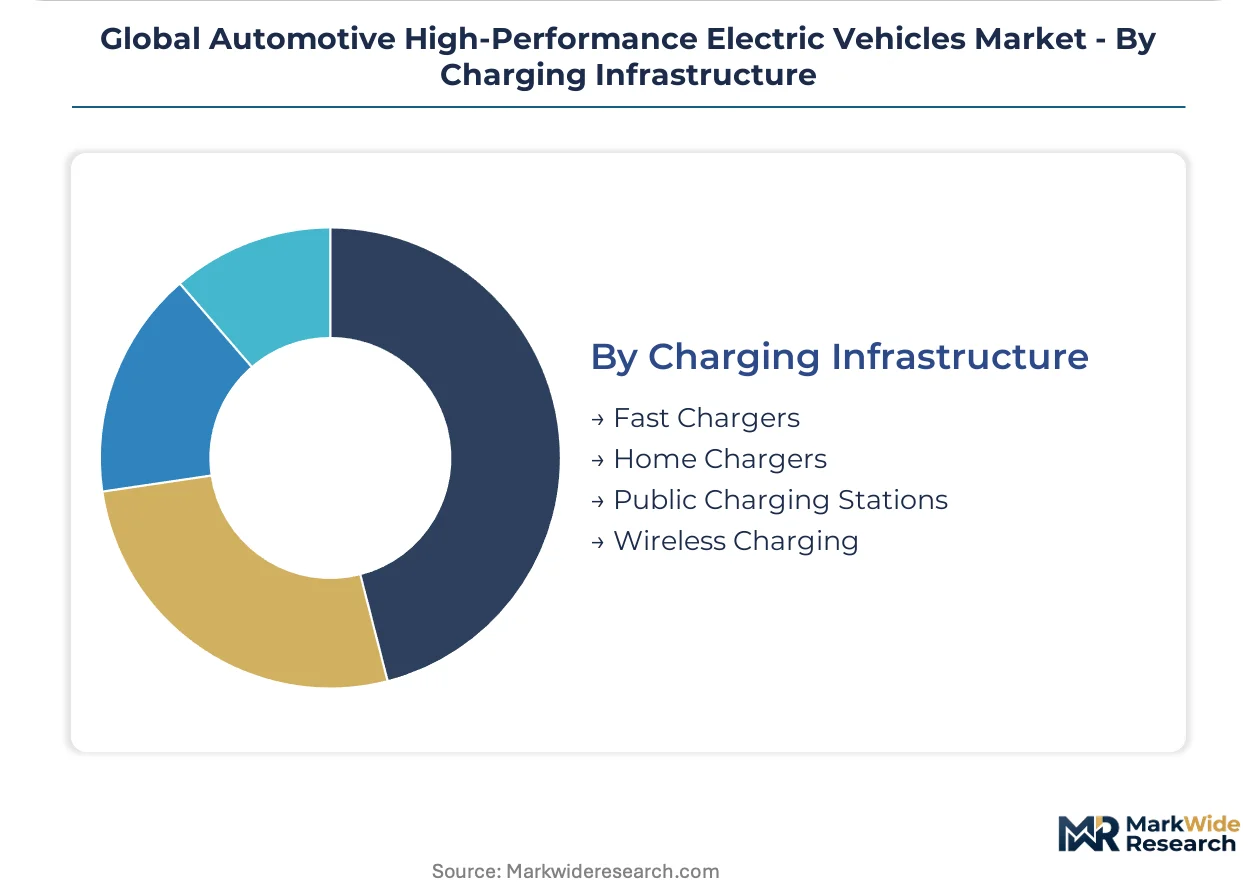
Charging Infrastructure:
Geography determines infrastructure deployment patterns, with urban density and grid reliability shaping ownership economics across markets.
- Fast Chargers:DC rapid charging above 150 kW enables corridor travel and fleet turnaround efficiency, though battery degradation concerns from repeated high-C-rate cycling temper utilization frequency.
- Home Chargers:Level 2 AC installations in detached residential garages dominate overnight charging patterns in suburban California and German single-family zones, leveraging time-of-use electricity tariffs.
- Public Charging Stations:Curbside and parking structure deployments serve apartment dwellers in dense Tokyo and Seoul districts lacking private garage access.
- Wireless Charging:Inductive pad systems eliminate connector wear and enable automated fleet charging, though efficiency losses and infrastructure retrofit costs constrain adoption.
Home chargers retain volume leadership; fast chargers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany posts the strongest export surplus in high-performance electric vehicle components, while South Korea and Japan concentrate battery cell fabrication capacity. The United States and China balance substantial domestic demand against growing import dependency for specialized powertrain subsystems.
United States
EPA tailpipe standard tightening forces Detroit manufacturers to expand electrified performance lineups as compliance instruments. California's Advanced Clean Cars II regulation accelerates fleet turnover timelines for premium segments. The San Francisco Bay Area and Greater Los Angeles anchor consumer demand, with Austin emerging as a secondary cluster for engineering talent recruitment.
Germany
EU Green Deal fleet targets pull volume through corporate procurement channels as commercial operators lock in vehicle allocations ahead of stricter phase-in dates. KBA homologation requirements strain validation resources across multiple powertrain variants simultaneously. Bavaria and Baden-Württemberg concentrate R&D investment, with Stuttgart hosting powertrain engineering clusters for torque-vectoring systems.
China
MIIT dual carbon goals and NEV credit mandates push domestic manufacturers toward premium electrification segments previously dominated by foreign brands. The country's national automotive regulator enforces GB standards for battery safety and electromagnetic compatibility. The Yangtze River Delta and Pearl River Delta dominate cell-to-pack integration capacity, with Shanghai hosting foreign joint venture headquarters.
South Korea
Advanced silicon-anode lithium-ion pilot production attracts capital reallocation from legacy nickel-cobalt supply chains. METI-equivalent industrial policy supports domestic cell fabrication scale-up through targeted tax incentives. Gwangju and Ulsan manufacturing clusters draw powertrain engineering talent from Japanese competitors, creating self-reinforcing ecosystem effects in cell chemistry innovation.
Japan
Conservative fleet procurement patterns among domestic corporate buyers limit near-term volume growth despite technical leadership in solid-state battery research. METI standardization efforts for 800V charging infrastructure aim to preserve interoperability with South Korean and Chinese systems. Nagoya and Osaka prefectures retain concentration in power electronics engineering, though talent migration to South Korean clusters accelerates.
Global Automotive High-Performance Electric Vehicles Market Vendor Landscape
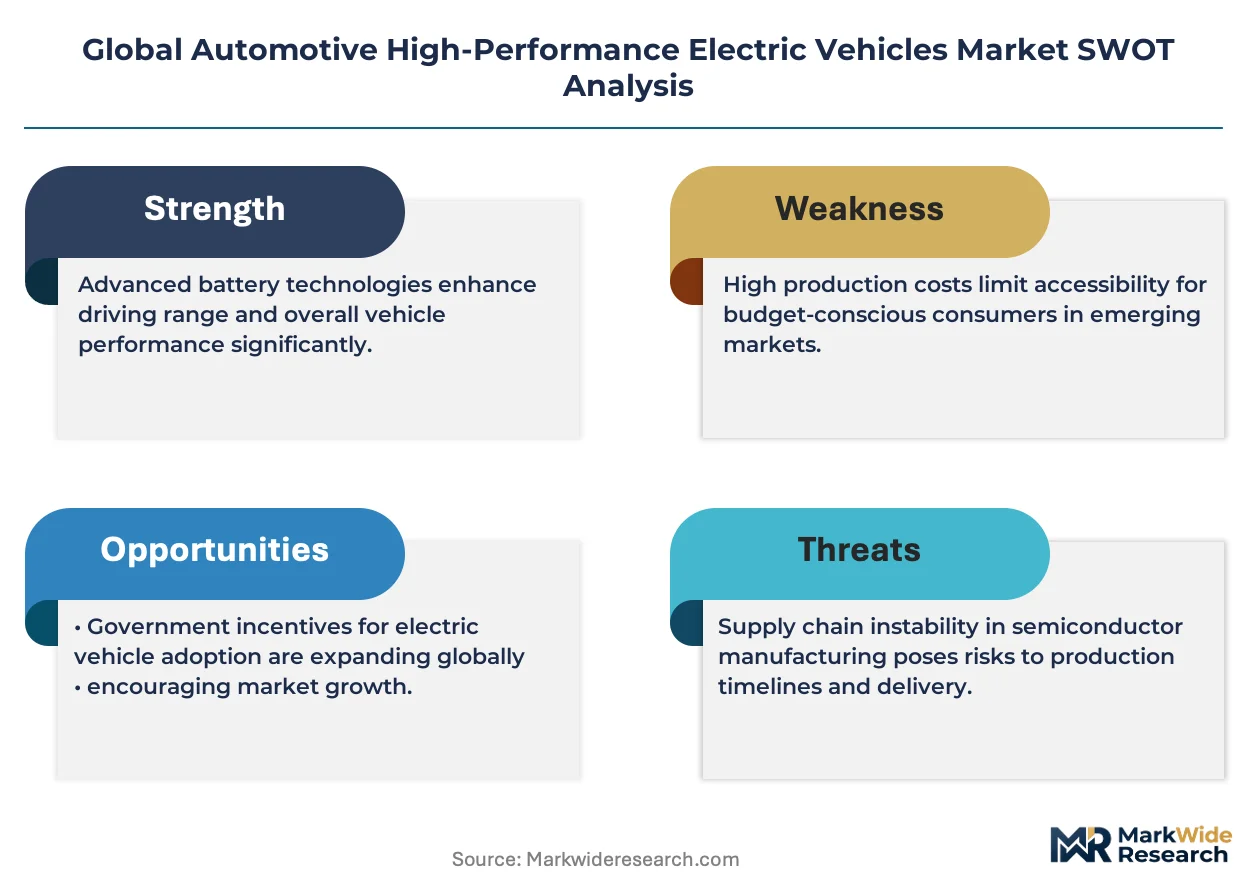
On the supply side, the industry is consolidating around three distinct capability tiers. Vertically integrated battery producers compete against pure-play vehicle assemblers and technology-licensing specialists. Strategic archetypes include captive finance arms controlling ownership lifecycles, in-house cell fabricators compressing cost structures, and powertrain subsystem suppliers serving multiple OEM partners. Dominant competitive moves center on backward integration into cell production and geographic expansion through direct-to-consumer digital channels.
Among the named players, Tesla exemplifies the captive-finance archetype through lifecycle ownership control, while BYD Auto anchors the in-house battery production tier. Rimac Automobili occupies the specialist position, supplying hypercar powertrain technology to multiple OEM partners rather than competing solely at the vehicle level. These three represent distinct strategic postures rather than direct peer competitors, with each targeting different margin pools across the value chain.
| Leading Market Players |
|---|
| Tesla |
| BYD Auto |
| Volkswagen Group |
| BMW Group |
| Mercedes-Benz Group |
| Rimac Automobili |
| Porsche |
| General Motors |
| Hyundai Motor Group |
| Others |
Supply Flow & Price Mechanics
Gwangju and Ulsan manufacturing clusters in South Korea concentrate silicon-anode lithium-ion cell fabrication capacity, granting battery pack assemblers downstream pricing leverage over OEMs locked into long-term offtake contracts. This geographic concentration creates asymmetric power dynamics where cell producers capture margin expansion during raw material volatility while vehicle manufacturers absorb cost pass-through.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that span multi-year vehicle platform cycles. Pricing stratifies across premium performance tiers with sub-three-second acceleration capabilities, standard variants targeting fleet compliance procurement, and economy segments for battery-as-a-service subscription models. Cost compression in standard tiers is intensifying because silicon-anode yield improvements lag capacity expansion timelines. Fleet operators in Germany exhibit lowest price sensitivity due to EU Green Deal compliance deadlines, while individual enthusiasts in California show highest elasticity to monthly subscription rates.
Supply Chain Analysis
LG Energy Solution, SK On, and Samsung SDI hold dominant contract-manufacturing capacity for high-performance EV cells across South Korea, China, and Hungary facilities. The supply chain draws from metallurgical-grade silicon processors in Japan, lithium carbonate from Chilean and Australian extraction operations, and cobalt hydroxide from the Democratic Republic of Congo. Single-source vulnerability concentrates in Japanese high-purity silicon chemical processing with limited near-term alternative qualification. Distribution runs through captive OEM supply agreements rather than spot market procurement, with Tesla and BYD Auto controlling upstream cell production internally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineering talent scarcity constrains 800V architecture deployment timelines, creating competitive moats for firms with secured semiconductor integration capabilities. The gap between silicon-anode pilot production and mass-scale yield consistency determines which OEMs capture compliance-driven fleet volumes.
For Market Incumbents: Insulate proprietary battery chemistry roadmaps through in-house metallurgical silicon processing partnerships that reduce dependence on Japanese chemical suppliers. Expand validation laboratory capacity in Stuttgart and Nagoya to compress homologation timelines under tightening UN ECE regulations. Lock in multi-year offtake agreements with South Korean cell producers before capacity allocation tightens further. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme subsidized manufacturing zones for localized performance EV component assembly previously imported from East Asia. Target white space in vehicle-to-grid bidirectional charging integration for deregulated electricity markets in Texas and Germany. Pursue direct-to-consumer digital channels bypassing legacy dealership networks in California and Bavaria where charging infrastructure density supports subscription ownership models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors powertrain subsystem suppliers with multi-OEM licensing revenue over pure-play vehicle assemblers exposed to homologation timeline compression. Long-term viability hinges on solid-state battery manufacturing yield breakthroughs and 800V charging infrastructure density expansion. Watch silicon-anode cell cost curves against nickel-cobalt legacy chemistry as the inflection indicator for capital reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with South Korean cell producers secure capacity allocation ahead of EU Green Deal compliance deadlines. |
| Software-Defined Vehicle Investment | Torque-vectoring control system upgrades enable over-the-air performance calibration differentiation against hardware-fixed competitors. |
| Geographic Manufacturing Footprint | Localized assembly in India's PLI scheme zones reduces import dependency and tariff exposure for premium performance variants. |
| Charging Infrastructure Partnership | DC fast charging network density expansion in California and Germany unlocks subscription-based ownership model economics. |
| Platform Standardization | Multi-motor drivetrain architecture reuse across sedan and SUV body styles compresses R&D amortization per vehicle. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and OEM powertrain engineering disclosures preceded structured interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations managers. Primary fieldwork captured silicon-anode cell fabrication yield data and 800V architecture development timelines. Secondary validation triangulated against customs records for lithium carbonate trade flows and SEC filings for captive finance arm performance. Bottom-up segment sizing converged with top-down regulatory compliance volume mandates.
Assumptions around EU Green Deal phase-in schedules, EPA tailpipe standard enforcement intensity, and solid-state battery manufacturing yield curves were held fixed across baseline scenarios while lithium price volatility and charging infrastructure deployment pace were stress-tested. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs were derived from segment-level volume build-ups validated against fleet compliance procurement commitments. Silicon-anode cell energy density improvement trajectories and thermal management system cost curves served as primary forecast inputs.
Stress conditions across lithium carbonate spot prices, metallurgical-grade silicon supply disruption, and UN ECE regulatory timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM platform cycle timing and battery chemistry transition curves. Quarterly review of silicon-anode pilot line yield reports and 800V charging infrastructure deployment metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market