
 Electric All-Terrain Vehicle (ATV) Market | 2026-2036
Electric All-Terrain Vehicle (ATV) Market Size, Share, and Industry Trends Forecast 2026-2036
Electric All-Terrain Vehicle (ATV) Market Insights
The electric ATV segment is rebalancing between premium lithium-ion configurations and commodity lead-acid alternatives as battery costs diverge. Polaris Inc. leverages its powersports distribution network to dominate North American dealer channels for recreational electric ATVs. BRP sustains engineering intensity across four-seater utility platforms aimed at agricultural buyers. Eco Charger specializes in ruggedized battery enclosures for wet-climate operations in Ireland and the United Kingdom.
An electric all-terrain vehicle is a battery-powered, off-highway vehicle with four low-pressure tires, a straddle seat, and handlebar steering, typically producing zero direct emissions at speeds below 50 mph for utility or recreational tasks. Manufacturing emphasizes sealed battery enclosures meeting IP67 standards and regenerative braking systems to extend range during descent-heavy terrain use. The end-user segmentation shows agricultural and industrial applications outpacing recreational demand as fleet operators electrify maintenance and patrol vehicles. Lithium-ion battery technology leads product type configurations while lead-acid occupies price-sensitive emerging markets with shorter duty cycles.
The EPA enforces off-road emissions standards under 40 CFR Part 1051 that effectively bar new gasoline ATV sales from certain federal lands, redirecting procurement toward electric alternatives. The EU Green Deal and F-Gas Regulation accelerate electrification mandates for vehicles operating in Natura 2000 conservation zones across Germany, France, and Italy. Stakeholders must monitor how NHTSA safety classification rulings for low-speed electric vehicles reshape insurance and roadway access rules for street-legal electric ATV variants.
Market Dynamics
The electric ATV market is compressing around battery chemistry bifurcation as lithium-ion cell costs diverge from lead-acid alternatives, forcing manufacturers to choose between premium range performance and emerging-market accessibility.
Growth Catalysts
- EPA 40 CFR Part 1051:Off-road emissions standards are redirecting federal land management procurement toward zero-emission alternatives for ranger patrol and maintenance fleets.
- Agricultural fleet electrification:Brazilian operations under new emissions mandates are converting diesel utility vehicles to electric models for crop monitoring and equipment transport.
- Lithium-ion energy density gains:Pack-level improvements are extending range per charge beyond prior thresholds for utility applications with heavy payload cycles.
Market Restraints
- Cathode material cost volatility:Lithium carbonate and nickel price swings are compressing gross margins for manufacturers without long-term offtake agreements.
- Charging infrastructure gaps:Remote agricultural regions and federal wilderness areas lack high-amperage charging points for fleet replenishment.
- Lead-acid substitution persistence:Price-sensitive buyers in emerging markets continue selecting flooded battery configurations despite shorter cycle life.
Strategic Opportunities
- Natura 2000 conservation zones:The EU Green Deal and F-Gas Regulation are accelerating electrification mandates for vehicles operating in German, French, and Italian protected areas.
- Regenerative braking integration:Descent-heavy terrain in mountainous regions is creating demand for kinetic recovery systems that extend effective range.
- Direct-to-fleet distribution:Agricultural cooperatives and federal procurement offices are bypassing traditional dealer networks for volume purchasing agreements.
Industry Challenges
- IP67 certification timelines:Sealed battery enclosure validation for wet-climate operations is extending product development cycles by six to nine months.
- Power electronics talent scarcity:Motor controller firmware engineering and thermal management design capabilities are concentrated among a limited supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric All-Terrain Vehicle (ATV) Market |
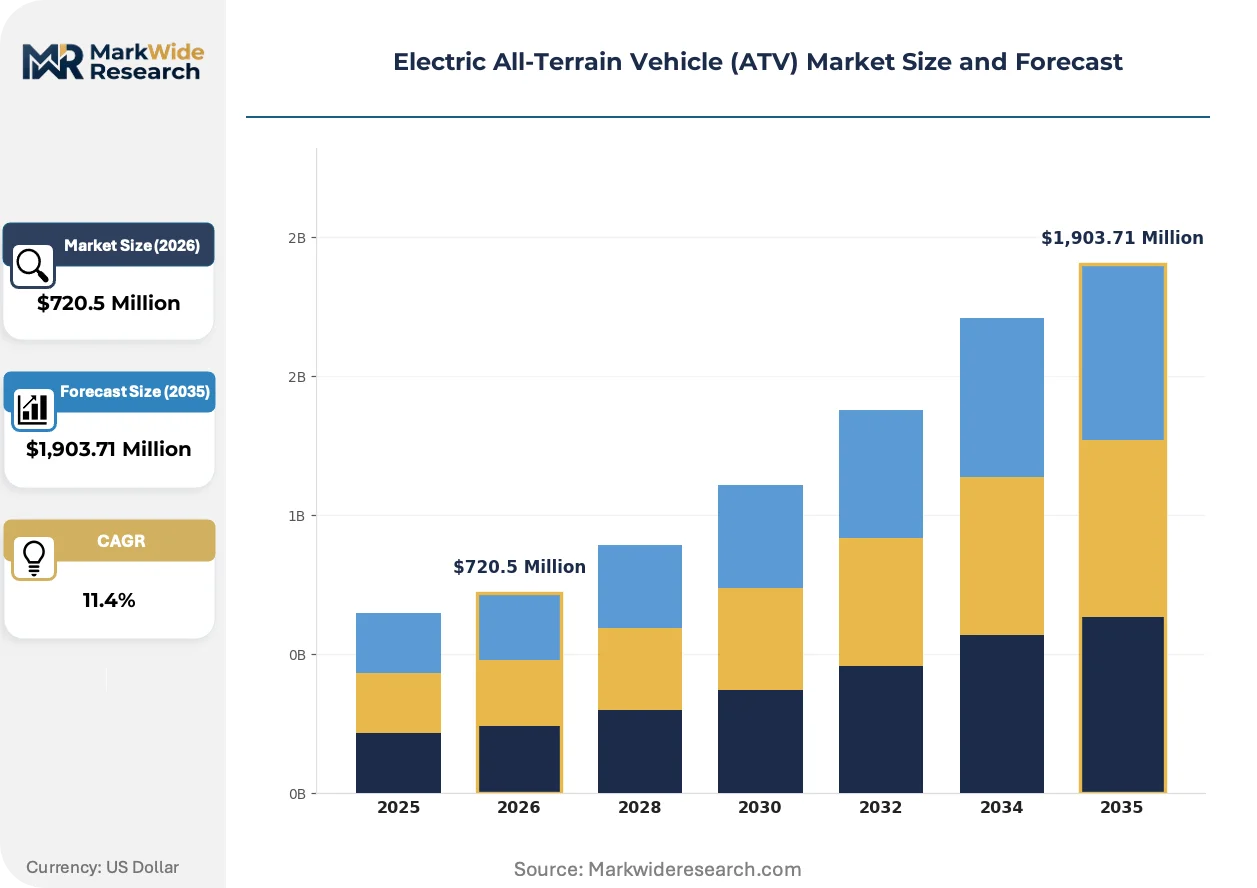
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,903.71 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Seater, Four-Seater, Cargo, Sports End User: Recreational, Agricultural, Industrial, Military Power Rating: 0-25 HP, 26-50 HP, 51-75 HP, 76+ HP Battery Technology: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Others |
| Companies Covered | Polaris Inc., BRP, Arctic Cat Inc., Daymak Inc., DRR USA, Eco Charger, Eco Rider, Powerland, Tesla, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric All-Terrain Vehicle (ATV) Market Trends and Innovations
Active thermal management systems are reshaping battery durability expectations as manufacturers compete on total cost of ownership rather than upfront purchase price.
Solid-state battery prototyping is absorbing development resources from major cell suppliers seeking to eliminate thermal runaway risks in rough-terrain applications. Agricultural fleet operators in California and Arizona are piloting early samples for irrigation equipment towing. This chemistry transition is absorbing capital that previously flowed into incremental lithium-ion improvements, compressing the window for conventional pack architectures.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in vehicle climate systems, forcing electric ATV manufacturers to adopt CO2-based heat pumps for cabin and battery conditioning. Industrial buyers in Germany and France are prioritizing compliant models for Natura 2000 zone access permits. Suppliers without certified thermal systems are losing bid eligibility for conservation agency contracts.
Fleet managers are consolidating maintenance spend through integrated service agreements that bundle predictive diagnostics with scheduled component replacement. Traditional dealer service departments are losing aftermarket revenue to manufacturer-direct subscription programs. This pattern is most pronounced among United States federal land management agencies electrifying ranger patrol vehicles under multi-year operating leases.
Electric All-Terrain Vehicle (ATV) Market Segmentation
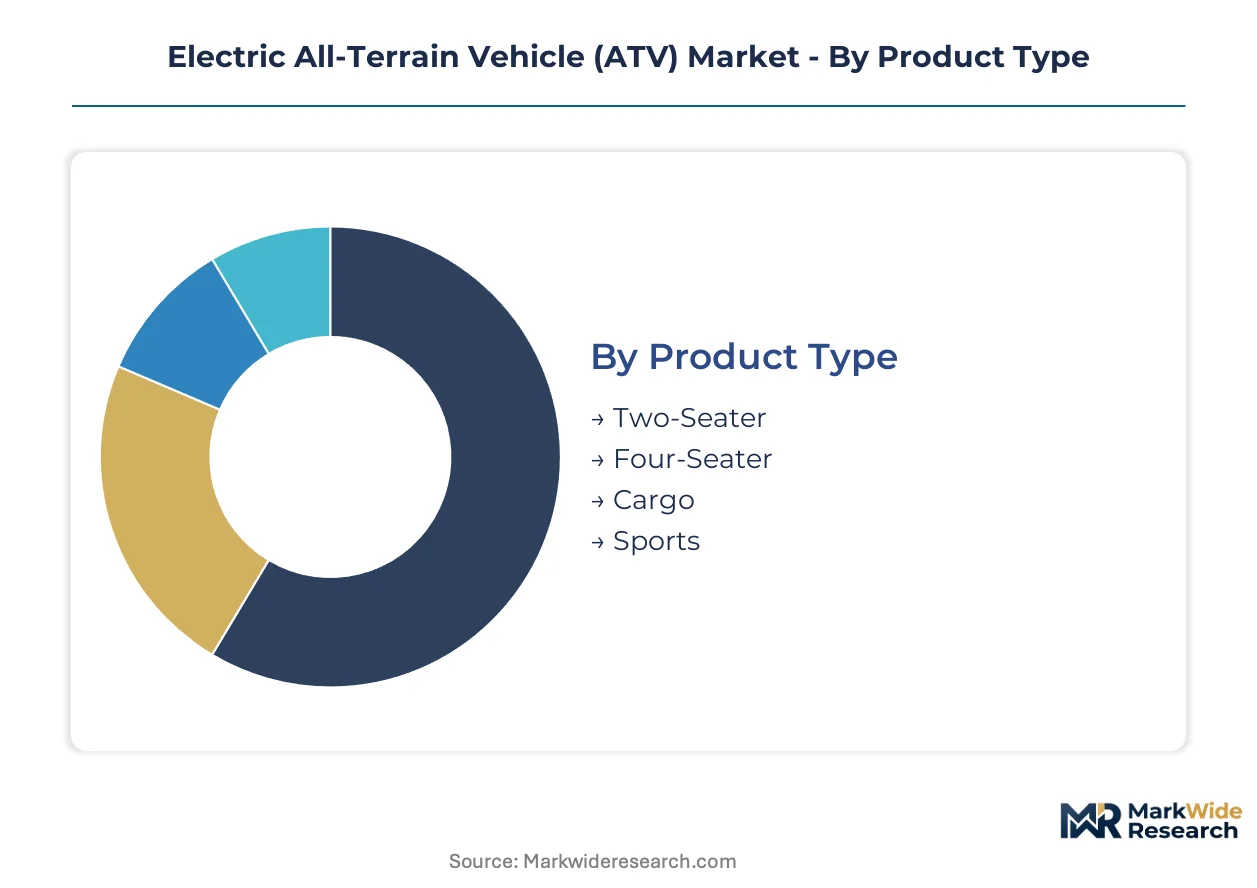
Electric ATV configurations diverge sharply between standardized utility platforms for fleet procurement and customized recreational builds. Battery chemistry and seating capacity drive the largest pricing spreads, while power rating tiers separate agricultural workhorses from patrol vehicles.
Product Type:
Standardized four-seater frames dominate fleet procurement, while two-seater and cargo variants command customization premiums for specialized terrain.
- Two-Seater:Compact straddle-seat designs optimize for trail width restrictions in dense forestry and narrow vineyard rows. California agricultural cooperatives specify these for steep-slope crop monitoring where vehicle footprint limits maneuverability.
- Four-Seater:Extended wheelbase utility platforms carry four occupants plus equipment loads across ranch and federal land patrol applications. Brazilian agricultural fleets under emissions mandates are converting diesel UTV fleets to these electric equivalents for crew transport.
- Cargo:Flatbed and box configurations prioritize payload capacity over passenger count for equipment hauling and supply runs.
- Sports:High-torque motor tuning and suspension travel target recreational trail riding with acceleration-focused performance profiles.
Most installed capacity flows through Four-Seater. Expansion is steepest in Cargo configurations for agricultural mechanization.
End User:
Procurement concentration separates volume fleet operators from fragmented recreational buyers across application requirements.
- Recreational:Individual and rental-fleet purchasers prioritize trail-access compliance and charging network proximity over payload specifications. United States Forest Service trail permit systems are restricting gasoline ATV access, redirecting weekend riders toward electric alternatives.
- Agricultural:Crop monitoring, livestock management, and equipment towing across large landholdings demand sealed battery enclosures for dust and moisture exposure. Brazilian operations facing emissions mandates are electrifying diesel utility vehicle fleets for daily ranch operations.
- Industrial:Mining, construction, and facility maintenance applications specify IP67-rated enclosures and regenerative braking for descent-heavy terrain.
- Military:Silent-running patrol and reconnaissance platforms prioritize acoustic signature reduction over range optimization.
Agricultural procurement generates the highest unit volumes. Recreational channels are expanding most quickly as trail access restrictions proliferate.
Power Rating:
Motor output tiers align with duty cycle intensity, separating light patrol applications from sustained heavy-load operations.
- 0-25 HP:Low-speed utility tasks including security patrol, grounds maintenance, and light equipment transport. Federal land management agencies in the United States specify these for ranger station proximity operations with minimal payload demands.
- 26-50 HP:Mid-range agricultural workhorses balance towing capacity with battery conservation for all-day field use. German and French conservation zone contractors select this band for Natura 2000 access compliance with adequate hill-climb torque.
- 51-75 HP:Heavy-duty cargo and industrial applications requiring sustained high-draw motor performance.
- 76+ HP:Maximum torque configurations for extreme terrain and specialized military specifications.
Production volumes concentrate in the 26-50 HP band. The 0-25 HP segment is gaining share fastest as urban-adjacent recreational use expands.
Battery Technology:
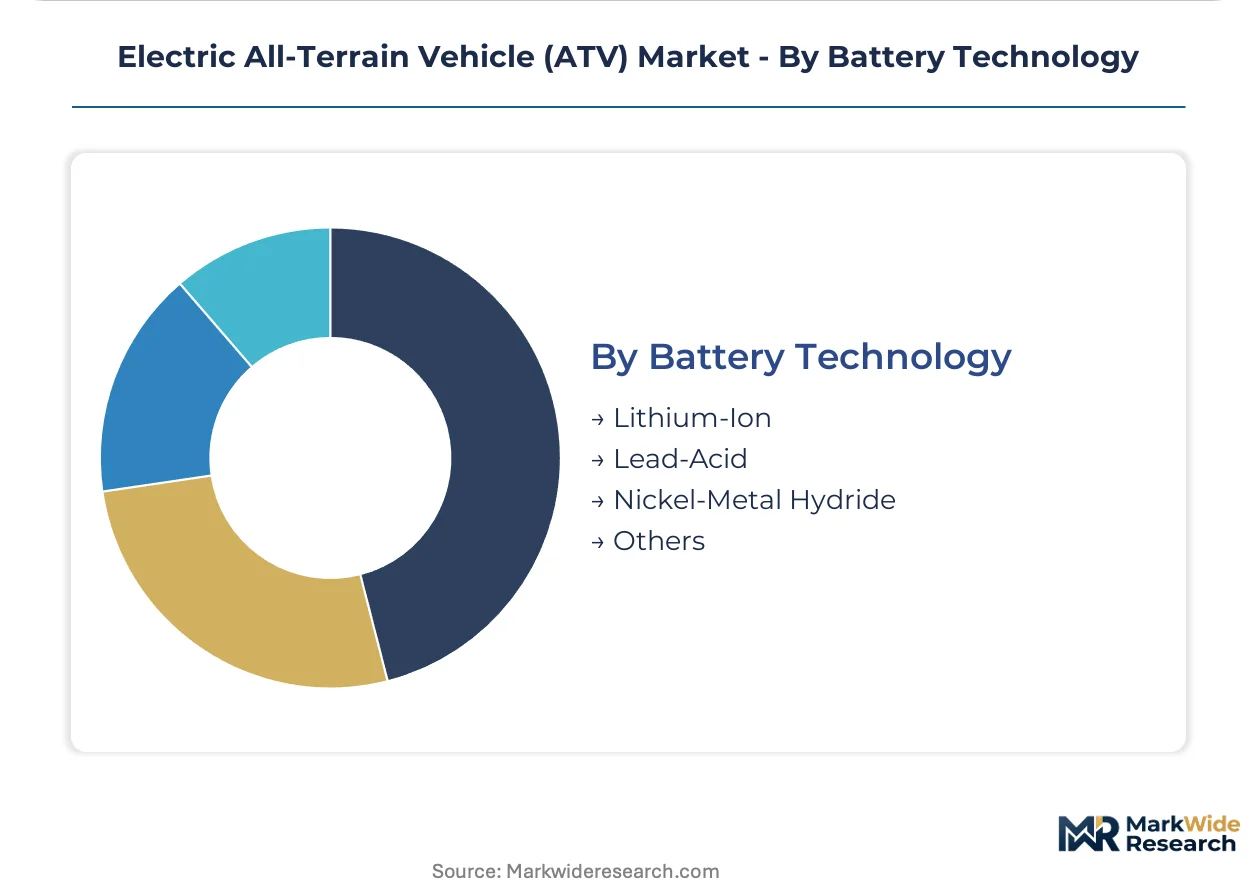
Cost-performance tradeoffs separate premium lithium-ion deployments from commodity alternatives in price-sensitive applications.
- Lithium-Ion:NMC and LFP cell configurations deliver energy density above prior thresholds for range extension in utility cycles. Active thermal management and sealed IP67 enclosures meet wet-climate operations in Ireland and the United Kingdom.
- Lead-Acid:Flooded and AGM configurations occupy emerging-market price points with shorter cycle life acceptable for intermittent duty. Brazilian agricultural buyers in cost-constrained regions continue selecting these despite replacement frequency penalties.
- Nickel-Metal Hydride:Intermediate chemistry persists in legacy fleet retrofits and temperature-extreme applications where lithium thermal sensitivity creates operational risk.
- Others:Solid-state prototypes and sodium-ion experimental cells absorb development resources from major suppliers seeking thermal runaway elimination.
Lithium-Ion carries the majority of installed capacity. Solid-state and alternative chemistries are climbing the fastest as cell suppliers redirect capital from incremental improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal procurement outpaces Brazilian agricultural conversion in unit volume, though both markets accelerate under emissions mandates. Germany and France enforce conservation-zone access restrictions that favor zero-emission alternatives. Ireland and the United Kingdom specialize in wet-climate ruggedization for maritime and upland operations.
United States
Federal land management agencies electrify ranger patrol fleets across national parks and wilderness areas. EPA 40 CFR Part 1051 bars gasoline ATV sales from certain federal lands, redirecting procurement toward battery-powered alternatives. California agricultural cooperatives in the Central Valley deploy compact two-seaters for steep-slope crop monitoring where vehicle footprint limits maneuverability.
Brazil
Agricultural operations under new emissions mandates convert diesel utility vehicle fleets to electric models for daily ranch operations. ANVISA-equivalent environmental enforcement accelerates fleet electrification timelines for crop monitoring and equipment transport. São Paulo state ranchers lead adoption of four-seater utility platforms for crew transport across large landholdings.
Germany
Natura 2000 conservation zone contractors select mid-range power configurations for access compliance with adequate hill-climb torque. EU F-Gas Regulation bans hydrofluorocarbon refrigerants in vehicle climate systems, forcing CO2-based heat pump adoption. Bavarian conservation agencies prioritize compliant models for protected area permits, disqualifying suppliers without certified thermal systems.
France
Conservation zone access permits drive procurement toward EU Green Deal-compliant electric ATVs for German and Italian border region operations. F-Gas Regulation enforcement accelerates thermal system certification requirements for bid eligibility. Auvergne-Rhône-Alpes contractors specialize in descent-heavy terrain applications requiring regenerative braking integration.
Ireland and United Kingdom
Wet-climate operations demand sealed battery enclosures meeting IP67 standards for maritime and upland use. Eco Charger anchors ruggedized battery enclosure supply for Irish and British agricultural and conservation applications. Scottish Highlands patrol operations and Welsh upland farms specify active thermal management for temperature-extreme deployments.
Electric All-Terrain Vehicle (ATV) Market Competitive Landscape
Top-tier vendors anchor premium lithium-ion configurations, while commodity specialists occupy lead-acid price points in emerging markets. The vendor base stratifies across three competitive tiers: powersports incumbents leveraging established distribution, battery-system specialists focusing on ruggedized enclosures, and diversified technology entrants exploring adjacent mobility applications. Dominant competitive moves include direct-to-fleet distribution bypassing traditional dealer networks and regenerative braking technology licensing for terrain-specific range extension.
Within the powersports incumbent tier, Polaris Inc. and BRP exemplify established distribution leverage for North American and agricultural market penetration. Eco Charger occupies a specialist position representing wet-climate ruggedization expertise for maritime and upland operations. Arctic Cat Inc. and Daymak Inc. sit within the recreational-access tier, while DRR USA anchors the utility-platform segment for fleet procurement. Tesla, Inc. represents technology-diversified entry from adjacent electric mobility domains.
| Leading Market Players |
|---|
| Polaris Inc. |
| BRP |
| Arctic Cat Inc. |
| Daymak Inc. |
| DRR USA |
| Eco Charger |
| Eco Rider |
| Powerland |
| Tesla, Inc. |
| Others |
Pricing and Supply Chain Analysis
Motor controller firmware engineering talent concentrated in Germany and South Korea drives labor-cost differentials that widen pricing-tier spreads between premium lithium-ion configurations and commodity lead-acid alternatives. Battery pack assembly labor arbitrage between these engineering hubs and emerging-market manufacturing zones feeds into three-tier pricing stratification across fleet procurement channels.
Pricing Analysis
Service bundling splits sharply between manufacturer-direct subscription programs covering predictive diagnostics and unbundled transactional sales through traditional dealer networks. Three-tier pricing structure across premium, standard, and economy levels separates lithium-ion platforms with active thermal management from lead-acid alternatives with shorter cycle life. Price differentiation rests on IP67 certification grade and volume scale in fleet procurement agreements. Cost compression in the lead-acid tier is intensifying because Brazilian agricultural buyers face emissions mandate compliance deadlines. Federal land management agencies in the United States exhibit least price sensitivity due to multi-year operating lease structures, while emerging-market ranchers show highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Dual-sourcing requirements from United States federal procurement offices and German conservation agencies mandate multi-supplier qualification for battery cell and power electronics components. Geographic supply concentration centers on China for lithium carbonate processing, South Korea for NMC cell manufacturing, and Japan for power semiconductor fabrication. Raw material dependencies draw from Chilean lithium brine operations, Indonesian nickel laterite mines, and Chinese graphite processing facilities. Single-source vulnerability in motor controller firmware engineering creates bottleneck risk for manufacturers without captive development capabilities. Distribution runs through powersports dealer networks for recreational channels and direct-to-fleet agreements for agricultural and federal procurement segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric ATV market functions as a stable compounder anchored by emissions mandate compliance deadlines that lock in replacement demand cycles across agricultural and federal fleet segments.
For Market Incumbents: Hedge against solid-state battery disruption by maintaining dual-development tracks for conventional lithium-ion incremental improvements and next-chemistry prototyping partnerships. Secure long-term offtake agreements for lithium carbonate and nickel to defend margins against cathode material cost volatility. Deepen backward integration into power electronics firmware development to reduce dependency on concentrated German and South Korean engineering talent pools. For New Entrants and Emerging Players: Begin with wet-climate ruggedization specialization targeting Irish and Scottish upland agricultural operations where IP67-certified active thermal management commands premium positioning. The cargo configuration segment for Brazilian agricultural mechanization represents the most penetrable white-space target given emissions mandate-driven fleet conversion timelines. Pursue direct-to-fleet distribution partnerships with agricultural cooperatives to bypass entrenched powersports dealer networks. For Investors and Strategic Acquirers: Agricultural equipment manufacturers are the most active acquirer in this space, seeking electrification capabilities to complement existing diesel utility vehicle portfolios. The acquisition target archetype is mid-cap battery-system specialists with certified thermal management platforms and established conservation agency contract relationships. Watch solid-state battery sample validation timelines in California and Arizona irrigation towing applications as the inflection indicator for chemistry transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term lithium carbonate offtake secures margin stability against price volatility. |
| IP67 Certification Investment | Wet-climate enclosure validation unlocks Irish and Scottish conservation agency contracts. |
| Regenerative Braking Licensing | Terrain-specific kinetic recovery technology extends effective range in mountainous Natura 2000 zones. |
| Direct-to-Fleet Distribution | Bypassing dealer networks captures agricultural cooperative volume procurement agreements. |
| CO2 Heat Pump Integration | F-Gas Regulation compliance maintains bid eligibility for German and French conservation contracts. |
Research Methodology
Bottom-up agricultural and federal fleet modeling reconciled against top-down battery cell production tracking forms the analytical core of this study. Primary interviews with fleet procurement officers at United States land management agencies, agricultural cooperative equipment managers, and power electronics engineering directors were validated against secondary sources including EPA 40 CFR Part 1051 regulatory filings, EU F-Gas Regulation implementation guidance, and customs trade data for lithium-ion battery pack imports. Triangulation between demand-side fleet conversion timelines and supply-side cell manufacturing capacity announcements ensures convergence between bottom-up and top-down estimates.
Historical trendline analysis of agricultural utility vehicle electrification patterns and federal procurement cycle timing informs the projection framework. Segmentation dimensions modeled include battery chemistry tier, seating capacity configuration, power rating band, and end-use application across the analysis window. CAGRs were derived from fitted trend extrapolation adjusted for regulatory mandate enforcement calendars and cell energy density improvement curves. Forecast inputs incorporate Brazilian ANVISA-equivalent enforcement acceleration and Natura 2000 zone access permit expansion timelines.
Caveats apply where lithium carbonate price volatility, solid-state battery commercialization acceleration, or NHTSA low-speed electric vehicle reclassification could materially shift the outlook. Deviation in federal land management procurement budget allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Pedelec Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market