
 Electric Vehicle Reducer Market | 2026-2036
Electric Vehicle Reducer Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Reducer Market Foresight
Aftermarket service revenue is narrowing as OEMs tighten control over reducer calibration and software-locked replacement cycles. BorgWarner Inc. leverages its integrated eAxle platforms to capture downstream service value. ZF Friedrichshafen anchors European supply through dedicated EV transmission facilities in Germany. Robert Bosch competes by extending its mechatronics expertise into reducer-integrated motor control units.
An electric vehicle reducer is a precision gear assembly that steps down rotational speed from the electric motor to the drive axle while multiplying torque output, typically achieving ratios between 8:1 and 12:1 through helical or planetary gear configurations. Its primary purpose is to optimize motor efficiency across vehicle speed ranges without the complexity of multi-gear transmissions. Planetary gear technology leads in passenger vehicle applications due to compact packaging and load distribution advantages, while multi-speed architectures are gaining traction in commercial vehicles where torque demands vary across duty cycles. Direct drive systems occupy a niche in high-performance segments but face margin pressure from simpler single-speed alternatives.
EPA tailpipe regulations in the United States and EU Green Deal vehicle CO2 targets are forcing faster electrification timelines, which tightens reducer efficiency requirements and accelerates validation cycles. China's MIIT enforces GB standards on EV powertrain energy consumption that directly specify reducer efficiency thresholds. NHTSA safety standards in the United States govern reducer durability under crash-load conditions. Stakeholders must monitor how software-defined vehicle architectures shift reducer value from mechanical precision to integrated control algorithms.
Market Dynamics
Fleet electrification mandates are compressing reducer validation cycles as commercial vehicle operators demand multi-speed architectures capable of variable torque delivery across duty cycles.
Growth Catalysts
- EU Green Deal vehicle CO2 targets:Stringent emission ceilings force OEMs to accelerate powertrain electrification timelines, tightening efficiency specifications for reducer subsystems.
- Commercial fleet operators:Heavy-duty logistics providers in Germany and China are expanding procurement of multi-speed reduction systems to optimize motor performance across highway and urban duty profiles.
- Planetary gear configurations:Compact packaging advantages in passenger vehicles drive specification preference for helical-planetary hybrid architectures over traditional spur gear alternatives.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in integrated eAxle systems compress reducer margin structures for independent suppliers.
- Supply concentration in Stuttgart-Munich corridor:German automotive manufacturing clusters concentrate precision gear machining capacity, creating geographic vulnerability to regional energy or labor disruptions.
- Direct drive substitution:In-wheel motor architectures in high-performance electric sports segments threaten single-speed reducer volume in premium passenger categories.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentive structures attract reducer manufacturing investment targeting domestic EV assembly and export to Southeast Asian markets.
- Software-defined calibration services:Over-the-air parameter updates for reducer-motor integration create recurring revenue streams previously captured by aftermarket service providers.
- GB standards compliance exports:China's MIIT efficiency thresholds establish de facto technical benchmarks that qualified suppliers leverage for market access across Belt and Road jurisdictions.
Industry Challenges
- Mechatronics systems integration:Convergence of mechanical gear design with motor control algorithms demands cross-functional engineering teams scarce in traditional transmission supplier bases.
- Crash-load certification timelines:NHTSA durability protocols for reducer housing integrity under collision forces extend validation schedules, delaying platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Reducer Market |
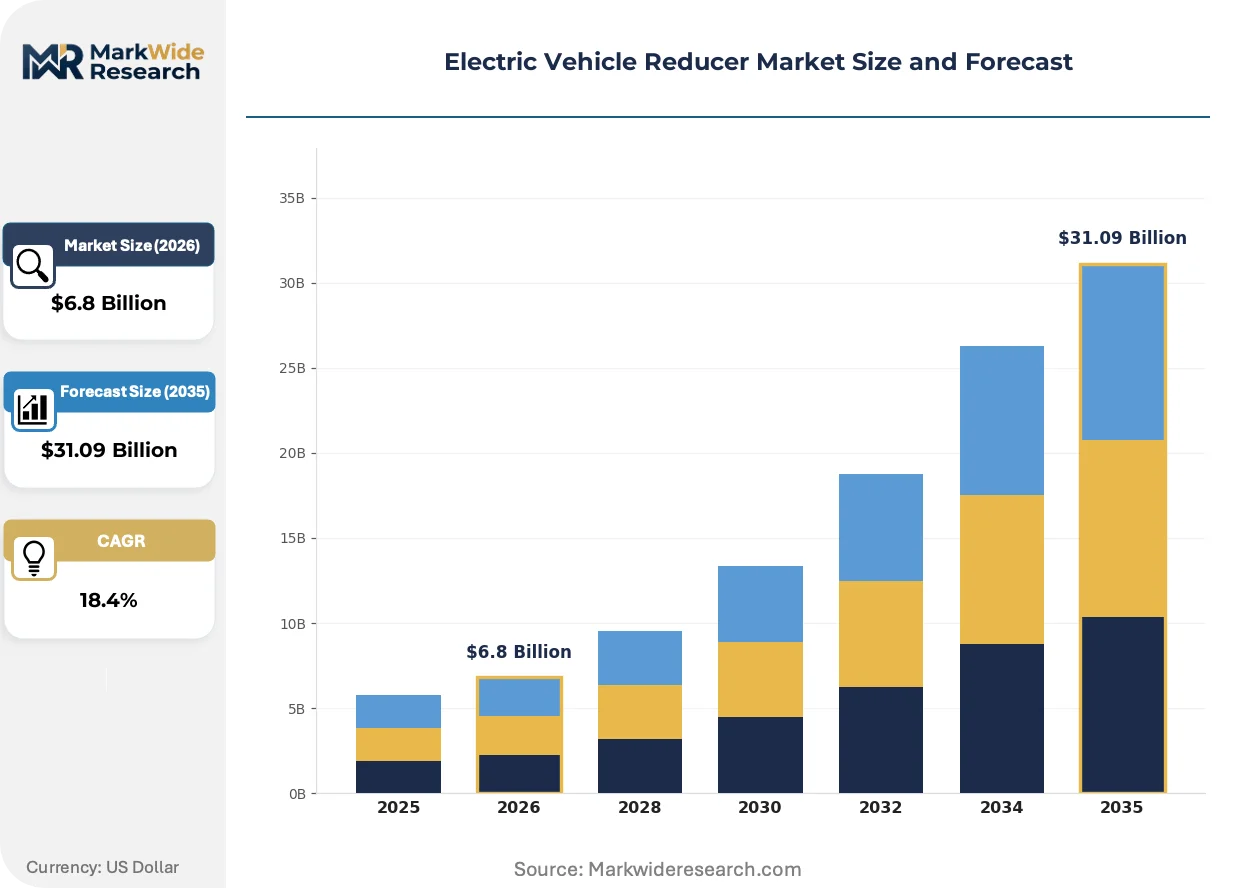
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reduction Gear, Motor Controller, Transmission System, Voltage Converter End User: Automotive OEMs, Aftermarket Providers, Fleet Operators, R&D Institutions Technology: Direct Drive, Planetary Gear, Multi-Speed, Variable Gear Ratio Application: Passenger Vehicles, Commercial Vehicles, Hybrid Vehicles, Others |
| Companies Covered | BorgWarner Inc., ZF Friedrichshafen, Robert Bosch, GKN Automotive, Magna International, Schaeffler AG, Nidec Corporation, HOTA Industrial, Aichi Machine Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Reducer Market Shifts & Advancements
Digital twin technology is virtualizing reducer development workflows, compressing prototyping cycles while regulatory efficiency mandates intensify hardware-software integration requirements across supplier tiers.
Multi-physics simulation platforms are virtualizing gear contact fatigue analysis and thermal management prediction for planetary reducer architectures. Tier-1 suppliers in Germany and Japan deploy these tools to halve physical prototype iterations before production validation. The technology is virtualizing traditional hardware-centric development cost structures, enabling smaller engineering houses to compete against capital-intensive testing facilities.
China's MIIT enforcement of GB/T energy consumption standards for EV powertrains mandates minimum reducer efficiency thresholds that cascade into supplier qualification protocols. Domestic OEMs must demonstrate compliance through certified test cycles to receive new energy vehicle production permits. Passenger vehicle platforms targeting premium segments face the steepest certification burden, driving consolidation toward vertically integrated powertrain suppliers with in-house testing capabilities.
Fleet procurement contracts are unbundling reducer calibration from motor supply agreements, creating standalone specification competitions for multi-speed architectures. Commercial vehicle operators in North America and Europe now issue separate RFPs for gear reduction systems, bypassing integrated eAxle bundles. This pattern concentrates most visibly among heavy-duty logistics providers operating cross-border European routes, where duty-cycle variability rewards modular subsystem sourcing.
Electric Vehicle Reducer Market Segmentation
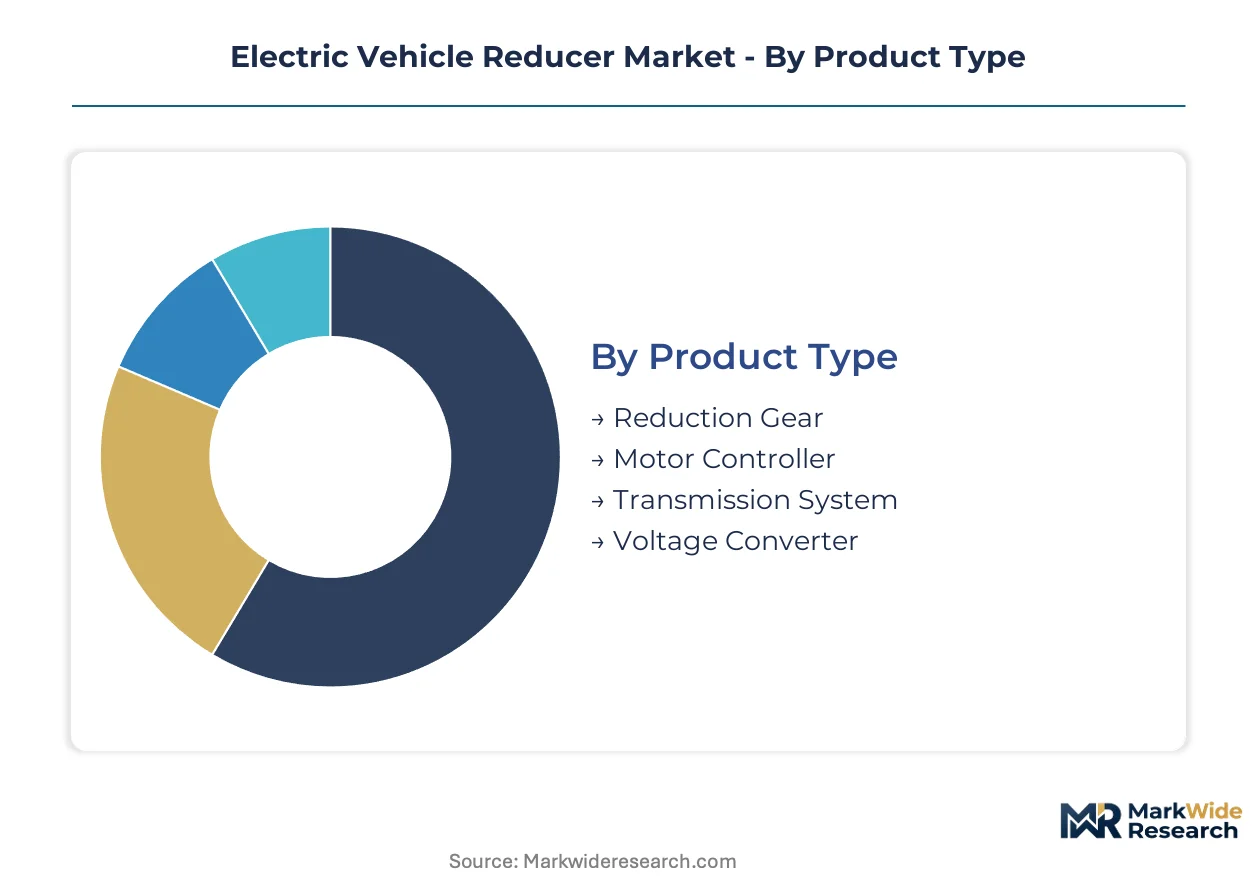
Reducer architectures diverge sharply across vehicle electrification strategies, with planetary and direct-drive systems serving fundamentally different torque multiplication requirements. Segmentation clarity enables suppliers to align R&D investment with the specific efficiency mandates and duty-cycle demands of each customer category.
Product Type:
Mature mechanical components dominate installed base volumes, while integrated electromechanical systems represent the emerging value concentration point for Tier-1 suppliers.
- Reduction Gear:Helical and planetary configurations achieve 8:1 to 12:1 speed reduction ratios through precision-machined gearsets. Passenger vehicle platforms in Germany specify these units for single-speed eAxle integration, driven by MIIT efficiency thresholds that penalize mechanical losses above 3% per stage.
- Transmission System:Multi-speed architectures incorporate synchronizer mechanisms and clutch packs to enable torque optimization across highway and urban duty profiles. Fleet operators in North America procurement contracts unbundle these from motor supply agreements, creating standalone specification competitions for commercial vehicle platforms.
- Motor Controller:Power electronics modules govern torque delivery precision through IGBT or SiC switching topologies.
- Voltage Converter:DC-DC units step high-voltage battery output to auxiliary system requirements.
Reduction gear retains volume leadership; transmission systems hold the steepest expansion curve.
End User:
Customer concentration shifts upstream as OEMs internalize calibration expertise and restrict aftermarket access to software-locked replacement cycles.
- Automotive OEMs:Vertical integration into reducer-motor matching algorithms dominates procurement patterns for volume passenger platforms. BorgWarner and ZF Friedrichshafen capture downstream service value through integrated eAxle platforms that bundle mechanical hardware with proprietary control firmware.
- Fleet Operators:Heavy-duty logistics providers issue separate RFPs for gear reduction systems, bypassing integrated bundles to optimize duty-cycle variability across cross-border European routes. This procurement pattern rewards modular subsystem sourcing with explicit efficiency guarantees.
- Aftermarket Providers:Service revenue channels narrow as OEMs tighten control over reducer calibration protocols.
- R&D Institutions:Testing facilities validate prototype architectures against NHTSA crash-load durability standards.
Automotive OEMs retain volume leadership; fleet operators hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium multi-speed architectures from economy single-speed alternatives, with direct-drive systems occupying a narrow performance niche.
- Planetary Gear:Compact coaxial arrangements distribute load across multiple planet gears, enabling higher torque density than spur alternatives. China's domestic OEMs specify these for premium passenger segments facing the steepest GB/T certification burden under MIIT energy consumption standards.
- Multi-Speed:Two or three ratio sets optimize motor efficiency maps across variable speed demands. Commercial vehicle procurement in Germany concentrates specification preference here, as highway-urban duty profile variability rewards discrete gear selection over fixed-ratio compromises.
- Direct Drive:In-wheel motor architectures eliminate mechanical reduction entirely.
- Variable Gear Ratio:Continuously variable mechanisms adjust ratio dynamically without discrete steps.
Planetary gear retains volume leadership; multi-speed architectures hold the steepest expansion curve.
Application:
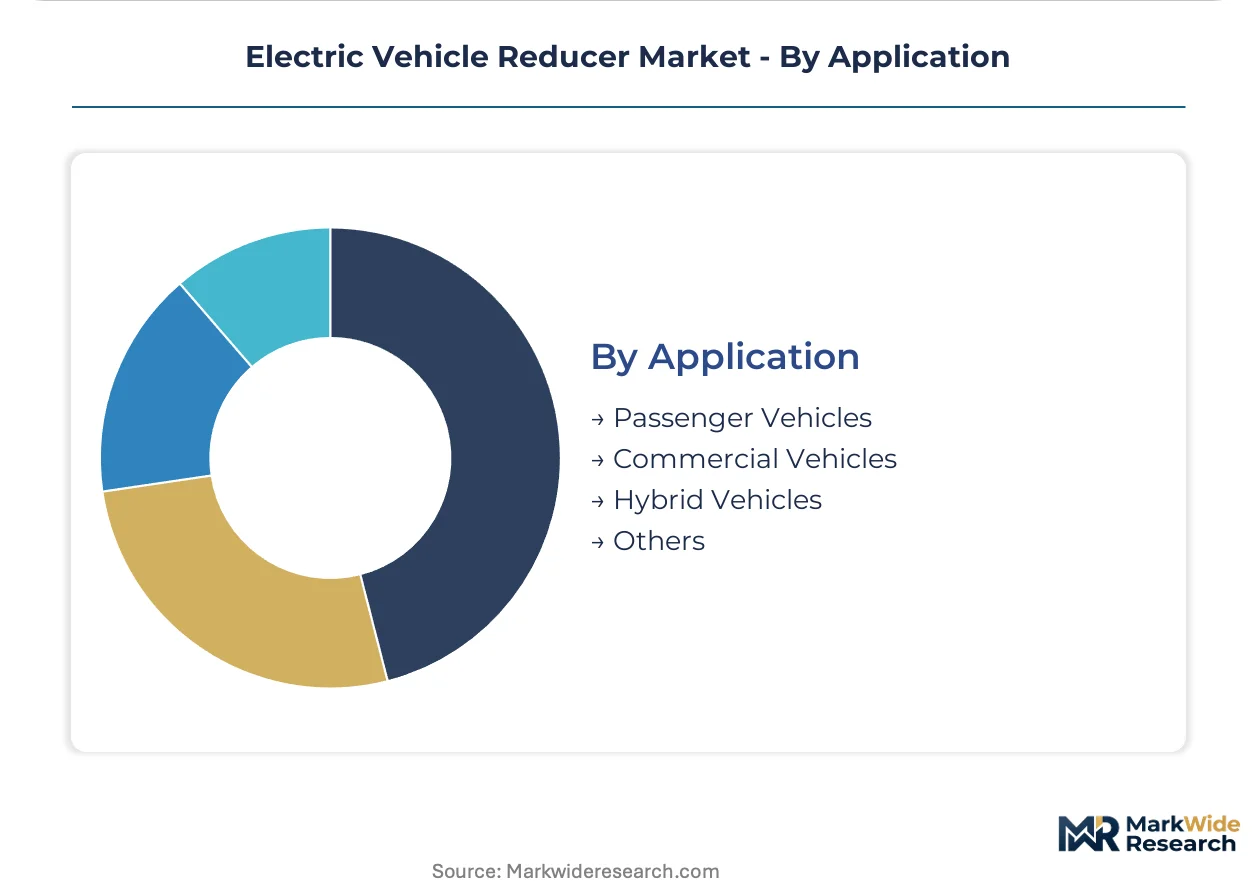
Passenger vehicle standardization around single-speed planetary units contrasts with commercial vehicle demand for configurable multi-speed systems.
- Commercial Vehicles:Heavy-duty platforms require torque multiplication across gross vehicle weight ranges from 7.5 to 40 tonnes. Fleet electrification mandates in Europe compress validation cycles as operators demand architectures capable of variable torque delivery across duty cycles spanning urban distribution and long-haul corridors.
- Passenger Vehicles:Compact packaging constraints favor helical-planetary hybrid configurations with integrated differential functions. Stuttgart-Munich manufacturing clusters concentrate precision gear machining capacity for these volume applications.
- Hybrid Vehicles:Dual powertrain architectures impose additional packaging complexity on reducer integration.
- Others:Specialty applications include off-highway equipment and motorsport derivatives.
Passenger vehicles retain volume leadership; commercial vehicles hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reducer deployment patterns diverge sharply by geography. China consumes integrated eAxle bundles for mass-market passenger platforms. Germany separates multi-speed transmission procurement from motor supply. The United States concentrates single-speed planetary units for light-duty trucks.
China
Domestic OEMs source planetary reducers under MIIT's GB/T energy consumption standards for new energy vehicle permits. The MIIT mandates minimum efficiency thresholds that cascade into supplier qualification protocols. The Yangtze River Delta manufacturing belt concentrates vertically integrated powertrain suppliers with captive testing capabilities for premium passenger segments.
Germany
Commercial fleet operators in heavy-duty logistics issue separate RFPs for multi-speed reduction systems to optimize duty-cycle variability. The EU Green Deal vehicle CO2 targets tighten efficiency specifications for reducer subsystems across passenger and commercial platforms. The Stuttgart-Munich corridor concentrates precision gear machining capacity for helical-planetary hybrid configurations.
United States
Light-duty truck electrification drives specification preference for single-speed planetary units with integrated differential functions. The EPA tailpipe regulations force faster powertrain electrification timelines that compress reducer validation cycles. The Midwest automotive manufacturing belt around Michigan and Ohio anchors domestic eAxle assembly capacity.
Japan
Passenger vehicle platforms favor compact coaxial planetary arrangements for torque density optimization. METI industrial policy supports domestic supplier consolidation around mechatronics-integrated reducer-motor systems. The Nagoya-Chubu manufacturing region concentrates precision gear production for hybrid and battery-electric powertrains.
India
Domestic EV assembly growth attracts reducer manufacturing investment under the PLI scheme for auto components. The scheme's production-linked incentive structures target export capacity for Southeast Asian markets. The Gujarat-Tamil Nadu industrial corridor hosts emerging precision machining clusters for gear reduction systems.
Electric Vehicle Reducer Market Competitive Landscape
Capability concentration sits with integrated Tier-1 suppliers possessing mechatronics expertise; scale advantage sits with diversified automotive component conglomerates with multi-platform supply relationships. The market structure tiers into three archetypes: vertically integrated powertrain specialists, independent precision gear manufacturers, and diversified automotive suppliers extending into electrification. Dominant competitive moves include backward integration into motor control firmware and geographic expansion through dedicated EV transmission facilities.
Within the integrated powertrain tier, BorgWarner Inc., ZF Friedrichshafen, and Robert Bosch occupy positions that exemplify the convergence of mechanical gear design with proprietary control algorithms. These companies anchor the competitive landscape through archetype representation rather than discrete product claims. BorgWarner's corporate structure suggests North American origins, while ZF Friedrichshafen's designation indicates German limited liability incorporation. Robert Bosch represents the diversified industrial conglomerate model extending mechatronics capabilities into reducer-integrated systems.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| ZF Friedrichshafen |
| Robert Bosch |
| GKN Automotive |
| Magna International |
| Schaeffler AG |
| Nidec Corporation |
| HOTA Industrial |
| Aichi Machine Industry |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container rate volatility feeds directly into reducer landed costs for European OEMs, amplifying price spreads between German-machined precision units and Asian alternatives while fleet procurement contracts harden efficiency guarantees as non-negotiable terms.
Pricing Analysis
Long-term offtake agreements dominate procurement between Tier-1 suppliers and volume OEMs, with spot purchasing limited to aftermarket channels and project-based contracting reserved for fleet customization. Three-tier pricing structure across premium, standard, and economy levels separates helical-planetary hybrids with MIIT certification from unverified alternatives, with price differentiation hinging on GB/T efficiency grade and captive testing capability. Cost compression in economy-tier single-speed units is intensifying because Chinese domestic suppliers are expanding machining capacity. Fleet operators exhibit the highest price sensitivity due to total-cost-of-ownership modeling, while premium passenger OEMs prioritize efficiency guarantees over unit cost.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese rare earth processing clusters, with precision gear steel sourcing anchored in Germany and Japan. Machined gearsets and motor control firmware represent critical component dependencies, while thermal management substrates feed from South Korean electronics suppliers. Single-source vulnerability concentrates around MIIT-certified testing facilities in the Yangtze River Delta. Distribution runs through OEM captive assembly plants for integrated eAxle bundles, with modular reducer-only supply reaching fleet operators via Tier-1 logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as fleet procurement unbundles reducer specification from motor supply, creating standalone competitive arenas for efficiency-guaranteed subsystems across duty-cycle-variable applications.
For Market Incumbents: Entrench control over calibration firmware through over-the-air update architectures that lock aftermarket service revenue. Deepen backward integration into rare earth magnet supply chains to buffer margin compression from dysprosium price swings. Prioritize crash-load certification pre-positioning ahead of NHTSA protocol expansions. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized precision machining corridor, targeting export capacity for Southeast Asian EV assembly. Multi-speed commercial vehicle architectures offer the most penetrable segment given fleet RFP unbundling. Pursue GB/T compliance certification as a go-to-market credential for Belt and Road market access. For Investors and Strategic Acquirers: Mechatronics-integrated engineering houses with captive testing capabilities represent the priority acquisition archetype, as software-defined vehicle architectures shift value toward control algorithms. Long-term viability centers on suppliers capable of spanning mechanical precision and firmware development. Watch for MIIT efficiency threshold escalations as the inflection signal forcing consolidation toward vertically qualified players.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Calibration Investment | Over-the-air parameter updates capture recurring revenue from fleet operators. |
| GB/T Certification Pre-Positioning | MIIT efficiency thresholds create de facto technical barriers for Belt and Road access. |
| Rare Earth Supply Security | Upstream magnet sourcing buffers margin pressure from neodymium price volatility. |
| Multi-Speed Architecture Development | Commercial fleet procurement unbundling rewards standalone gearbox specification. |
| Digital Twin Deployment | Virtual prototyping halves validation cycles under compressed OEM launch timelines. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement leads, fleet operations managers, and MIIT certification specialists provided ongoing calibration against secondary validation from customs trade data, vehicle production databases, SEC supplier filings, and IHS Markit registration statistics. Bottom-up unit economics triangulated against top-down powertrain investment disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning vehicle class, propulsion architecture, reducer technology type, and regional production cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating fleet electrification mandate timelines and MIIT permit issuance patterns.
Sensitivities concentrate around rare earth commodity price shocks, NHTSA crash-load protocol amendments, and MIIT efficiency threshold escalations. Forecasts reflect documented assumptions on OEM vertical integration propensity and fleet procurement unbundling velocity. Material shifts in Chinese export license regimes for processed rare earths would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
South America E-Bike Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Special Purpose Electric Vehicle Market