
 Germany and Netherlands Medical Marijuana Market | 2026-2036
Germany and Netherlands Medical Marijuana Market Size, Share, and Industry Trends Forecast 2026-2036
Germany and Netherlands Medical Marijuana Market Intelligence
Pharmacy dispensing margins is reconfiguring competitive economics across the value chain. Tilray leverages European cultivation assets to secure GMP-certified supply for German pharmacies. Bedrocan anchors Dutch production capacity with standardized strain portfolios for clinical consistency. Demecan GmbH specializes in domestic German greenhouse operations to reduce import dependency.
Medical marijuana comprises dried cannabis inflorescences, concentrated oils, and formulated tinctures standardized to delta-9-tetrahydrocannabinol and cannabidiol ratios, produced through controlled-environment agriculture, supercritical CO2 extraction, and pharmaceutical-grade formulation for physician-supervised therapy of refractory symptoms. Flower products retain dominant prescription volume in Dutch pharmacy channels, while oil formulations capture expanding share in German home care settings where precise titration protocols matter. The chronic pain therapy area generates the deepest prescription pool, though epilepsy applications attract premium pricing due to orphan-drug-like regulatory pathways.
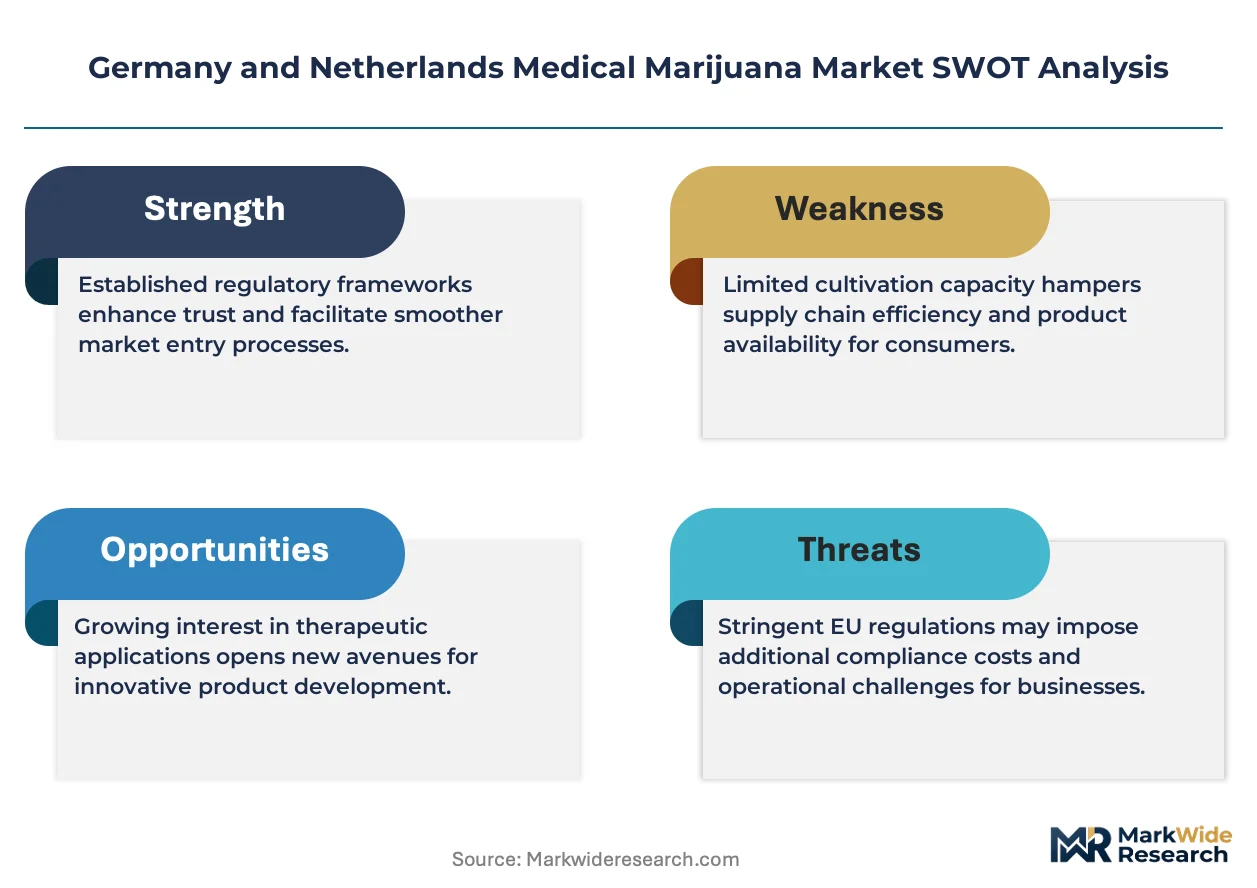
BfArM's cannabis agency licensing, the Dutch Office of Medicinal Cannabis quality monographs, and EU-GMP manufacturing standards collectively gate market access and define batch-release requirements for cross-border supply. German narcotics law amendments and Dutch tolerance policy frameworks shape prescriber behavior and reimbursement eligibility for reimbursed therapies. Stakeholders must monitor BfArM tender allocation shifts and Dutch export permit reciprocity negotiations to calibrate capacity investments against evolving supply rules.
Market Dynamics
BfArM's domestic cultivation licensing framework is restructuring supply security by displacing import-dependent pharmacy networks with greenhouse-certified domestic production, forcing capital reallocation toward controlled-environment agriculture assets.
Growth Catalysts
- Chronic pain therapy expansion:Dutch hospital pain management programs are integrating standardized cannabis extracts into multimodal protocols, driving prescription volume through clinical consistency requirements.
- BfArM tender allocation mechanism:Germany's cannabis agency licensing creates predictable offtake channels for domestic cultivators, reducing price volatility and enabling long-term capacity planning.
- Supercritical CO2 extraction scale-up:Pharmaceutical-grade oil formulation capacity is expanding to serve German home care settings where precise THC-CBD titration protocols dominate physician preference.
Market Restraints
- Import dependency concentration:Dutch pharmacy channels remain tethered to Canadian and Portuguese supply for standardized strains, exposing margins to currency fluctuation and shipping delays.
- Narcotics law compliance costs:Germany's BtMG scheduling requirements impose dual-locked storage, serialized tracking, and specialized pharmacy personnel certification, elevating operational overhead.
- Reimbursement friction:German statutory health insurers apply case-by-case prior authorization for cannabis prescriptions, creating cash flow gaps for patients and dispensing volume uncertainty for pharmacies.
Strategic Opportunities
- North Rhine-Westphalia pharmacy network densification:Germany's most populous state offers underpenetrated dispensing infrastructure where specialized cannabis pharmacies can capture chronic pain and oncology referral flows.
- Amsterdam clinical research corridor:Dutch tolerance policy frameworks enable real-world evidence generation partnerships between cultivators and academic medical centers, accelerating indication expansion.
- EU-GMP certification arbitrage:German cultivators achieving pharmaceutical manufacturing standards can supply export-permitted Dutch channels while domestic Dutch capacity focuses on research-grade material.
Industry Challenges
- Batch-release timeline compression:EU-GMP quality control and BfArM agency testing protocols create 8-12 week delays between harvest and pharmacy availability, straining working capital cycles.
- Pharmaceutical formulation talent scarcity:Germany lacks sufficient GMP-certified chemists with cannabinoid stability expertise, forcing competitors to recruit from traditional generic drug manufacturers.
- Legacy IT integration friction:German pharmacies must interface cannabis tracking systems with existing narcotics dispensing software, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany and Netherlands Medical Marijuana Market |
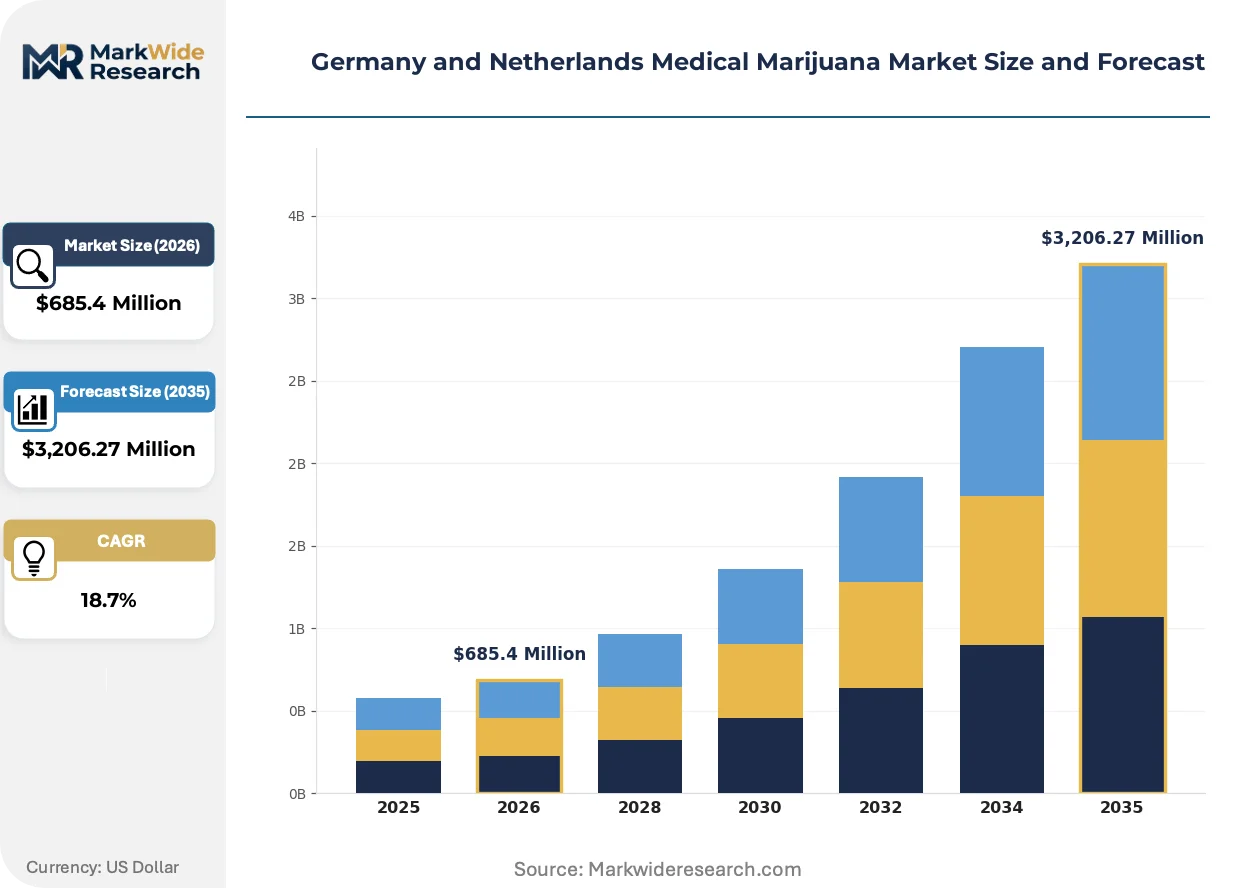
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flower, Oils, Tinctures, Capsules End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Online Retail, Wholesalers, Direct Sales, Distributors Therapy Area: Chronic Pain, Epilepsy, Cancer, Multiple Sclerosis |
| Companies Covered | Tilray, Demecan GmbH, ADREXpharma GmbH, Bedrocan, Cannamedical Pharma GmbH, Canopy Growth Corporation, GW Pharmaceuticals, Cantourage, Aurora Cannabis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany and Netherlands Medical Marijuana Market Strategic Shifts & Innovations
Pharmaceutical-grade standardization is displacing artisanal cultivation methods across the value chain, compressing quality variance and enabling outcome-based reimbursement negotiations with statutory insurers.
Blockchain seed-to-patient traceability is digitizing custody documentation for German pharmacy dispensing. BfArM-licensed cultivators are deploying distributed ledger systems to satisfy narcotics law audit requirements. This technology is digitizing compliance cost structures while creating competitive differentiation for supply chain transparency.
EMA's evolving cannabis-derived medicine guidance is harmonizing quality monographs across member states. Dutch Office of Medicinal Cannabis specifications are converging with German BfArM release standards, reducing cross-border batch rejection rates. German oil formulation manufacturers are responding by unifying specification sheets for dual-market supply.
Hospital procurement consolidation is compressing supplier rosters for standardized cannabis extracts. Dutch academic medical centers are centralizing purchasing through joint tendering vehicles, displacing fragmented pharmacy-level contracting. North Rhine-Westphalia's university hospital alliance exemplifies this concentration, negotiating multi-year supply agreements with cultivators holding EU-GMP certification.
Germany and Netherlands Medical Marijuana Market Segmentation
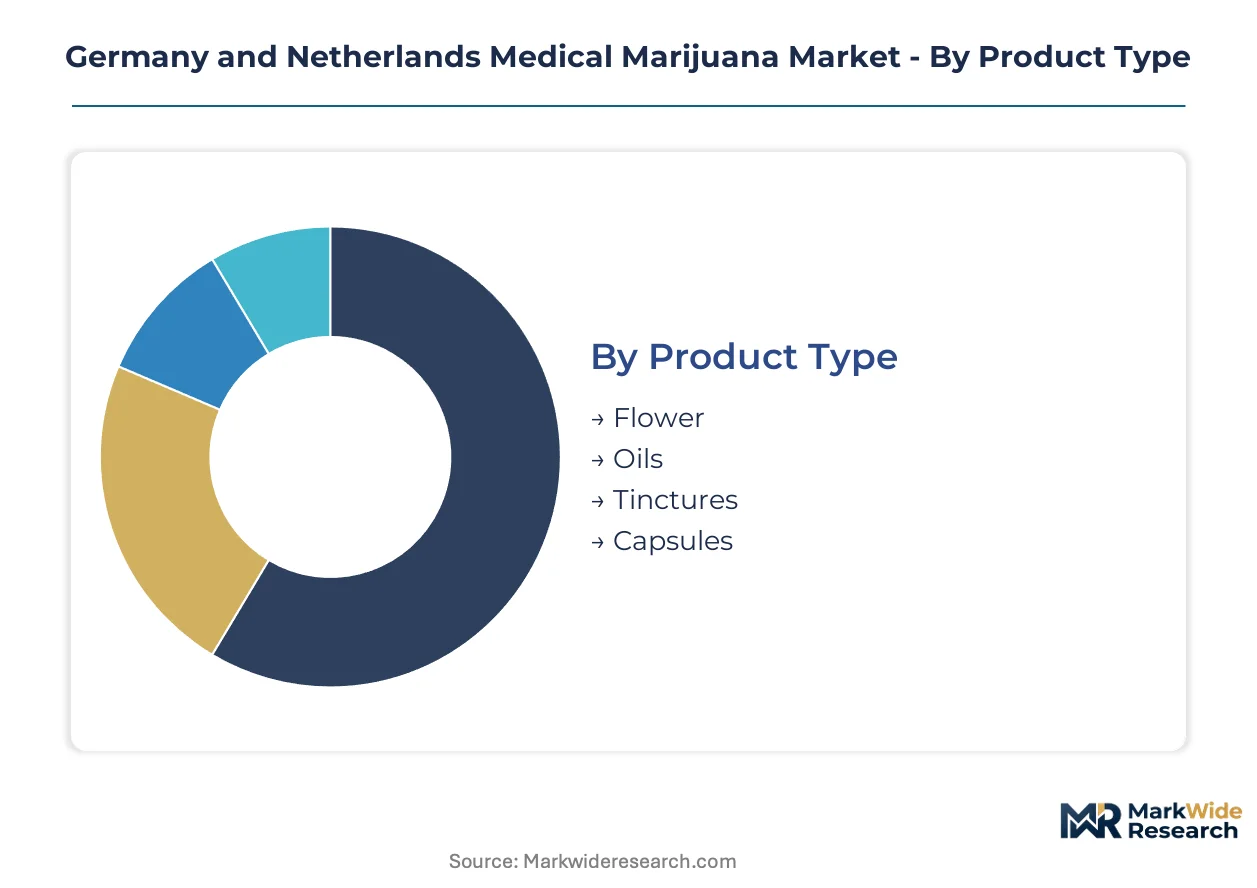
Medical marijuana demand in Germany and the Netherlands fragments across product formats, care settings, and therapeutic applications. Each segment carries distinct regulatory requirements, reimbursement pathways, and supply chain configurations that reshape competitive economics.
Product Type:
Flower products anchor prescription volume in Dutch pharmacy channels, while oil formulations serve German home care titration protocols.
- Flower:Dried cannabis inflorescences standardized to THC-CBD ratios through controlled-environment agriculture. North Rhine-Westphalia's pharmacy network generates the deepest prescription pool for unprocessed flower, driven by chronic pain management programs seeking cost-effective therapy entry points.
- Oils:Supercritical CO2 extracts formulated to pharmaceutical-grade specifications enabling precise milligram dosing. German home care settings concentrate demand for oil products where BfArM-licensed cultivators supply GMP-certified material supporting physician-supervised titration protocols.
- Tinctures:Alcohol-based suspensions offering rapid sublingual absorption for acute symptom episodes.
- Capsules:Encapsulated oil formulations providing discrete dosing and extended shelf stability for travel-sensitive patients.
The dominant share belongs to Flower, while Oils is closing the gap fastest.
End User:
Cost tier differentiation separates institutional procurement from retail dispensing economics.
- Hospitals:Dutch academic medical centers in Amsterdam's clinical research corridor drive standardized extract procurement through joint tendering vehicles. These institutions negotiate multi-year supply agreements with EU-GMP certified cultivators, displacing fragmented pharmacy-level contracting for chronic pain and oncology applications.
- Home Care:German statutory health insurance reimbursement for home-based therapy creates predictable demand channels. BfArM's tender allocation mechanism enables long-term capacity planning for domestic cultivators serving patients requiring precise THC-CBD ratio management outside institutional settings.
- Clinics:Specialized pain management centers in the Netherlands integrate cannabis extracts into multimodal protocols.
- Pharmacies:German narcotics law compliance costs elevate operational overhead for dual-locked storage and serialized tracking systems.
Hospitals command the largest institutional volume, though Home Care is expanding most quickly as reimbursement frameworks mature.
Distribution Channel:
Supply concentration patterns favor wholesale intermediaries with BfArM agency relationships over direct manufacturer access.
- Wholesalers:Licensed pharmaceutical distributors with narcotics handling permits dominate German pharmacy supply. These intermediaries manage BfArM batch-release documentation, EU-GMP certificate verification, and cold-chain logistics for temperature-sensitive oil formulations.
- Direct Sales:Hospital procurement consolidation enables cultivators to bypass wholesale margins for large-volume institutional contracts. Dutch academic medical center alliances negotiate directly with producers holding standardized strain portfolios for clinical consistency requirements.
- Online Retail:Prescription-verified digital platforms serve dispersed German home care patients with pharmacy fulfillment partnerships.
- Distributors:Regional logistics specialists manage last-mile delivery to North Rhine-Westphalia's dense pharmacy network.
Wholesalers retain the dominant channel position, while Direct Sales is gaining share fastest through hospital procurement consolidation.
Therapy Area:
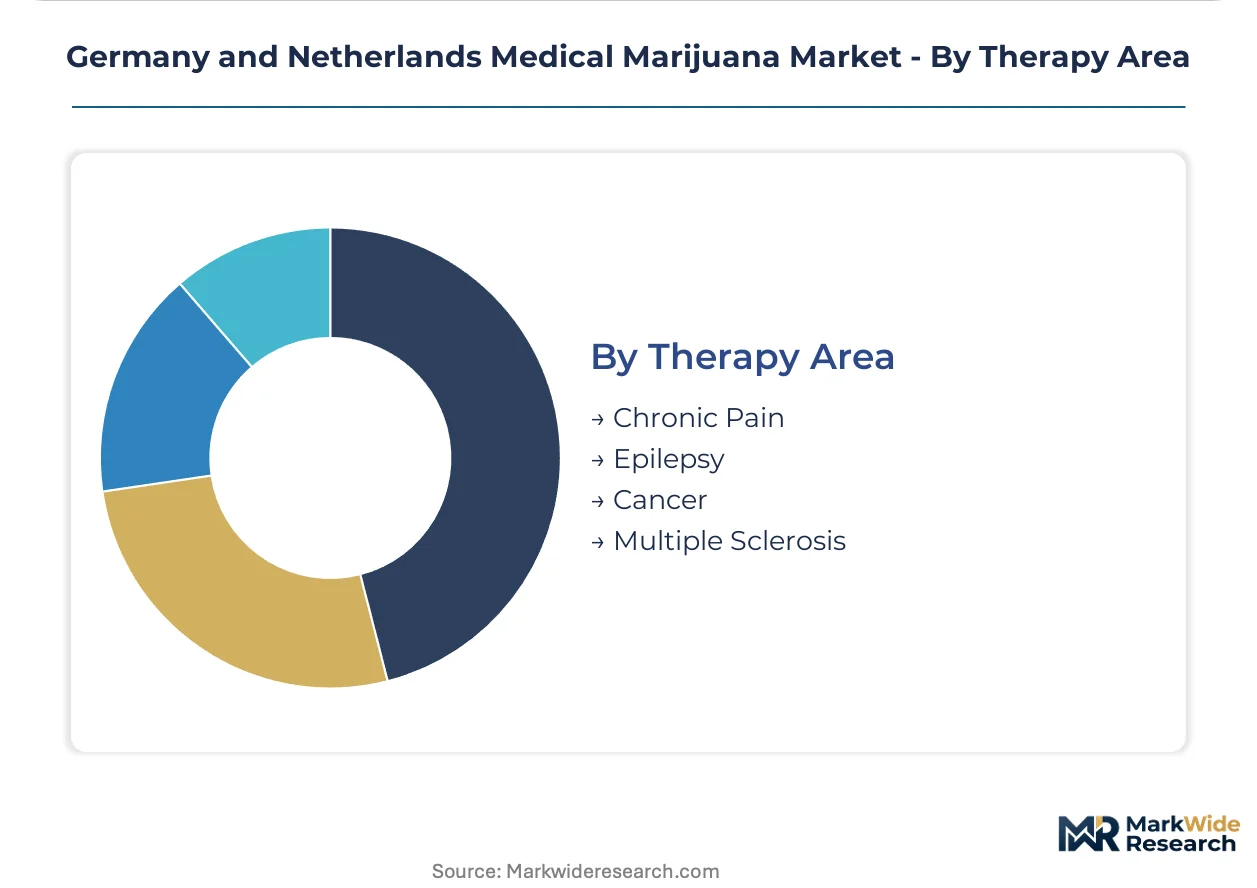
Application maturity separates established chronic pain protocols from emerging orphan-disease pricing premiums.
- Chronic Pain:The deepest prescription pool across both markets, served by standardized cannabis extracts integrated into multimodal hospital protocols. Dutch pain management programs drive volume through clinical consistency requirements, while German statutory insurers apply case-by-case prior authorization creating dispensing uncertainty.
- Epilepsy:Cannabinoid formulations for treatment-resistant pediatric epilepsy attract premium pricing through orphan-drug-like regulatory pathways. Amsterdam's clinical research corridor generates real-world evidence partnerships accelerating indication expansion for standardized extracts.
- Cancer:Oncology supportive care applications concentrate in Dutch hospital settings with joint tendering procurement.
- Multiple Sclerosis:Spasticity management represents a reimbursed indication in German pharmacy channels with established prescribing guidelines.
Chronic Pain holds the dominant therapeutic position, while Epilepsy is climbing the fastest on pricing premium and regulatory pathway advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the Netherlands diverge sharply in consumption patterns. Dutch hospital procurement concentrates on standardized extracts for institutional protocols, while German home care settings drive pharmacy-dispensed flower and oil formulations through statutory insurance reimbursement channels.
North Rhine-Westphalia
Germany's most populous state generates the deepest prescription pool for unprocessed flower products. BfArM's domestic cultivation licensing creates predictable offtake channels for greenhouse-certified producers. The dense pharmacy network in cities like Cologne and Düsseldorf anchors chronic pain management dispensing volume.
Bavaria
Specialized pain clinics in Munich integrate cannabis extracts into multimodal therapy protocols. Germany's narcotics law amendments shape prescriber behavior through dual-locked storage requirements. The region's academic medical centers generate referral flows for oncology supportive care applications.
Amsterdam Metropolitan Area
Dutch tolerance policy frameworks enable real-world evidence generation partnerships between cultivators and academic hospitals. The Office of Medicinal Cannabis quality monographs govern standardized strain portfolios. Amsterdam's clinical research corridor accelerates indication expansion for pediatric epilepsy formulations.
Utrecht-Central Netherlands
Joint tendering vehicles for academic medical centers centralize procurement of standardized extracts. EMA's evolving cannabis-derived medicine guidance harmonizes quality specifications with German BfArM standards. Hospital alliances negotiate multi-year supply agreements with EU-GMP certified cultivators.
Lower Saxony
Domestic greenhouse operations in this northern German state reduce import dependency for pharmacy networks. BfArM tender allocation mechanisms enable long-term capacity planning for cultivators. The region's logistics infrastructure supports cold-chain distribution of temperature-sensitive oil formulations.
Germany and Netherlands Medical Marijuana Market Key Industry Players
Capability concentration sits with domestic cultivators holding BfArM licenses; scale advantage sits with integrated operators leveraging European cultivation assets. The market structures around three tiers: EU-GMP certified domestic producers, import-dependent wholesale intermediaries, and research-grade specialists serving academic partnerships. Dominant competitive moves include capacity expansion into controlled-environment agriculture and strategic positioning for hospital procurement consolidation.
Within the domestic cultivation tier, Demecan GmbH and ADREXpharma GmbH exemplify German greenhouse operators reducing import dependency through BfArM-licensed production. Tilray represents integrated operators leveraging European assets to secure GMP-certified supply for pharmacy networks. Bedrocan occupies a position as a Dutch research-grade specialist anchoring standardized strain portfolios for clinical consistency requirements.
| Leading Market Players |
|---|
| Tilray |
| Demecan GmbH |
| ADREXpharma GmbH |
| Bedrocan |
| Cannamedical Pharma GmbH |
| Canopy Growth Corporation |
| GW Pharmaceuticals |
| Cantourage |
| Aurora Cannabis |
| Others |
Cost & Logistics Intelligence
Undercapacity in German greenhouse operations drives cultivator pricing power while forcing Dutch buyers toward volatile import channels. BfArM's tender allocation mechanism compresses price variance for domestic supply, yet import-dependent pharmacy networks absorb currency fluctuation and shipping premium costs.
Pricing Analysis
Long-term offtake contracts dominate German procurement through BfArM's tender mechanism, while Dutch hospital joint tendering vehicles negotiate multi-year supply agreements. Price differentiation rests on EU-GMP certification tier and volume scale, with orphan-disease formulations commanding premium positioning. Cost compression in standardized flower products intensifies as domestic German capacity expands, reducing import dependency. Statutory health insurers exhibit highest price sensitivity through case-by-case prior authorization protocols, while academic medical centers prioritize clinical consistency over unit cost.
Supply Chain Analysis
Tariff exposure between Canadian suppliers and Dutch pharmacy channels dominates supply chain risk calculations for standardized strain imports. Geographic supply concentration centers on Germany, Canada, and Portugal, with German domestic greenhouse operations expanding fastest. Raw material dependencies include cannabis biomass, pharmaceutical-grade ethanol for extraction, and specialized packaging for narcotics-compliant serialization. Single-source vulnerability persists for GMP-certified oil formulation capacity. Distribution runs through licensed pharmaceutical wholesalers with narcotics handling permits managing BfArM batch-release documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities are expanding faster than product revenue, with blockchain seed-to-patient traceability and compliance-documentation subscriptions outpacing flower sales growth. Recurring-revenue layers around EU-GMP audit support and narcotics-law IT integration are deepening customer retention.
For Market Incumbents: Harden supply security through backward integration into controlled-environment agriculture assets in Lower Saxony and North Rhine-Westphalia. Lock in hospital procurement consolidation via multi-year EU-GMP supply agreements with Amsterdam's academic medical center alliances. Defend against import-dependent competitors by leveraging BfArM tender allocation predictability for working capital advantage. For New Entrants and Emerging Players: Establish a beachhead in German home care oil formulation, where precise THC-CBD titration protocols create service differentiation opportunities. Target underpenetrated pharmacy networks in North Rhine-Westphalia's dense urban corridors for chronic pain referral flows. Pursue go-to-market partnerships with narcotics-compliant IT middleware providers to bypass legacy system integration barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across domestic German greenhouse operations as BfArM licensing requirements tighten. Long-term viability favors EU-GMP certified cultivators with proven BfArM agency relationships over import-dependent wholesale intermediaries. Acquisition target archetype: mid-scale German operators with tender allocation history and expansion-ready greenhouse assets. Monitor BfArM tender volume allocation shifts as the key inflection signal for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Pathway | Pharmaceutical manufacturing standards unlock BfArM tender eligibility and Dutch export permit reciprocity. |
| Backward Integration into Greenhouse Operations | Domestic German cultivation reduces import dependency and currency exposure for pharmacy supply security. |
| Hospital System Partnership | Amsterdam academic medical center alliances enable multi-year standardized extract procurement contracts. |
| Blockchain Traceability Platform | Distributed ledger systems satisfy BfArM narcotics law audit requirements while creating competitive differentiation. |
| Reimbursement Strategy Development | Statutory health insurer prior authorization navigation reduces patient cash flow gaps and dispensing uncertainty. |
Research Approach
Desk research of regulatory filings, pharmaceutical trade databases, and hospital procurement records preceded structured interviews with BfArM-licensed cultivator executives, Dutch Office of Medicinal Cannabis officials, German pharmacy dispensing managers, and statutory health insurance formulary directors. Secondary validation drew from EU-GMP inspection reports, narcotics law amendment documentation, and academic medical center tender announcements. Bottom-up prescription volume modeling and top-down market sizing triangulation anchored value estimates.
Assumptions around BfArM tender allocation continuity, Dutch export permit reciprocity stability, and statutory insurance reimbursement pathway expansion were held fixed across baseline scenarios while sensitivity testing varied domestic cultivation capacity buildout rates and hospital procurement consolidation velocity. Segmentation modeling spanned product format, care setting, therapeutic application, and regional regulatory cluster dimensions. CAGRs were derived from prescription volume trend extrapolation cross-referenced against greenhouse capacity utilization data and pharmaceutical oil formulation scale-up trajectories.
Sensitivities concentrate around BfArM licensing timeline delays, Dutch tolerance policy framework revisions, and statutory health insurer reimbursement restriction tightening. Forecasts reflect these documented assumptions with explicit acknowledgment that regulatory pathway disruptions or narcotics law compliance cost spikes could materially revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Europe Medical Cannabis Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
Cannabinoid CB2 Products Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
Cannabis Edibles Market