
 Cannabidiol Extract Market | 2026-2036
Cannabidiol Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabidiol Extract Market Insights
Asset-light contract extraction and toll-processing arrangements are fragmenting competitive boundaries in cannabidiol supply. Canopy Growth Corporation leverages its integrated cultivation infrastructure across multiple licensed facilities. Folium Biosciences anchors its position through proprietary hemp genetics and bulk isolate production at industrial scale. ENDOCA competes via direct-to-consumer channels with certified organic positioning across European markets.
Cannabidiol extract comprises non-psychoactive phytocannabinoids derived from Cannabis sativa L., typically standardized to contain less than 0.3% delta-9-tetrahydrocannabinol by dry weight and processed through CO2 or ethanol extraction methods for therapeutic and wellness applications. Full spectrum formulations retain minor cannabinoids and terpenes that generate the entourage effect, commanding premium positioning in nutraceutical channels. Pharmaceutical-grade isolates now attract the fastest margin expansion as drug developers pursue FDA-registered active pharmaceutical ingredient qualification. Broad spectrum variants occupy a narrowing mid-market position between wellness positioning and clinical credibility.
The FDA's ongoing evaluation of CBD as a food additive and dietary supplement ingredient creates parallel compliance tracks for pharmaceutical and consumer product entrants. EMA's Committee for Medicinal Products for Human Use has established precedent through GW Pharmaceuticals Plc's Epidyolex approval, shaping European regulatory expectations for prescription cannabinoid therapies. Stakeholders must monitor whether the FDA finalizes a regulatory pathway for over-the-counter CBD products or maintains the current enforcement discretion framework that fragments market access across state jurisdictions.
Market Dynamics
Pharmaceutical formulators are consolidating procurement around cGMP-certified extraction capacity, compressing the supplier base as prescription-grade CBD therapies secure formulary placement and FDA registration pathways mature.
Growth Catalysts
- Prescription cannabinoid reimbursement:Epidyolex's EMA precedent and expanding US Medicaid coverage for seizure disorders create institutional demand pull. Hospital formularies in Germany and the United Kingdom now list reimbursable CBD therapies.
- CO2 extraction scale-up:Supercritical fluid equipment manufacturers have reduced capital intensity per liter of throughput by half, enabling mid-scale processors to achieve pharmaceutical-grade purity thresholds previously reserved for industrial operators.
- State hemp program expansion:Licensed cultivation acreage under the USDA Domestic Hemp Production Program now spans 47 US states, saturating raw biomass supply and compressing input costs for toll processors.
Market Restraints
- FDA enforcement discretion fragmentation:The absence of a finalized over-the-counter regulatory pathway forces consumer product entrants to navigate 50-state patchworks of cosmetic, food, and supplement regulations, elevating compliance overhead.
- THC remediation cost volatility:Broad spectrum extractors face margin pressure from chromatography resin pricing and solvent recovery energy costs, with seasonal biomass THC variance requiring batch-by-batch process adjustment.
- European Novel Food authorization backlog:EFSA's pending safety opinions for synthetic CBD and hemp-derived extracts freeze market access for non-pharmaceutical ingestible products across EU member states.
Strategic Opportunities
- Veterinary therapeutic white space:The absence of approved CBD therapeutics for companion animals in the US and major European markets leaves room for first-mover veterinary drug sponsors pursuing MUMS pathway designations.
- Direct-to-clinic distribution:Specialty compounding pharmacies and functional medicine practices are bypassing retail markup by sourcing bulk isolates under practitioner-only licensing frameworks.
- Synthetic biology cannabinoid production:Yeast fermentation of rare cannabinoids (CBG, CBN) offers supply security independent of agricultural cycles, attracting pharmaceutical partners seeking API supply chain redundancy.
Industry Challenges
- Analytical chemist scarcity:The intersection of HPLC method development, terpene profiling, and residual solvent validation requires specialized talent rarely available outside cannabis-dominant state labor markets.
- EU-GMP certification timelines:Active pharmaceutical ingredient manufacturing site approvals average 18-24 months, locking capital in non-revenue-generating facilities during qualification.
- Certificate of Analysis standardization:Inconsistent potency reporting methodologies across third-party laboratories create batch rejection risk and customer disputes in bulk ingredient trading.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabidiol Extract Market |
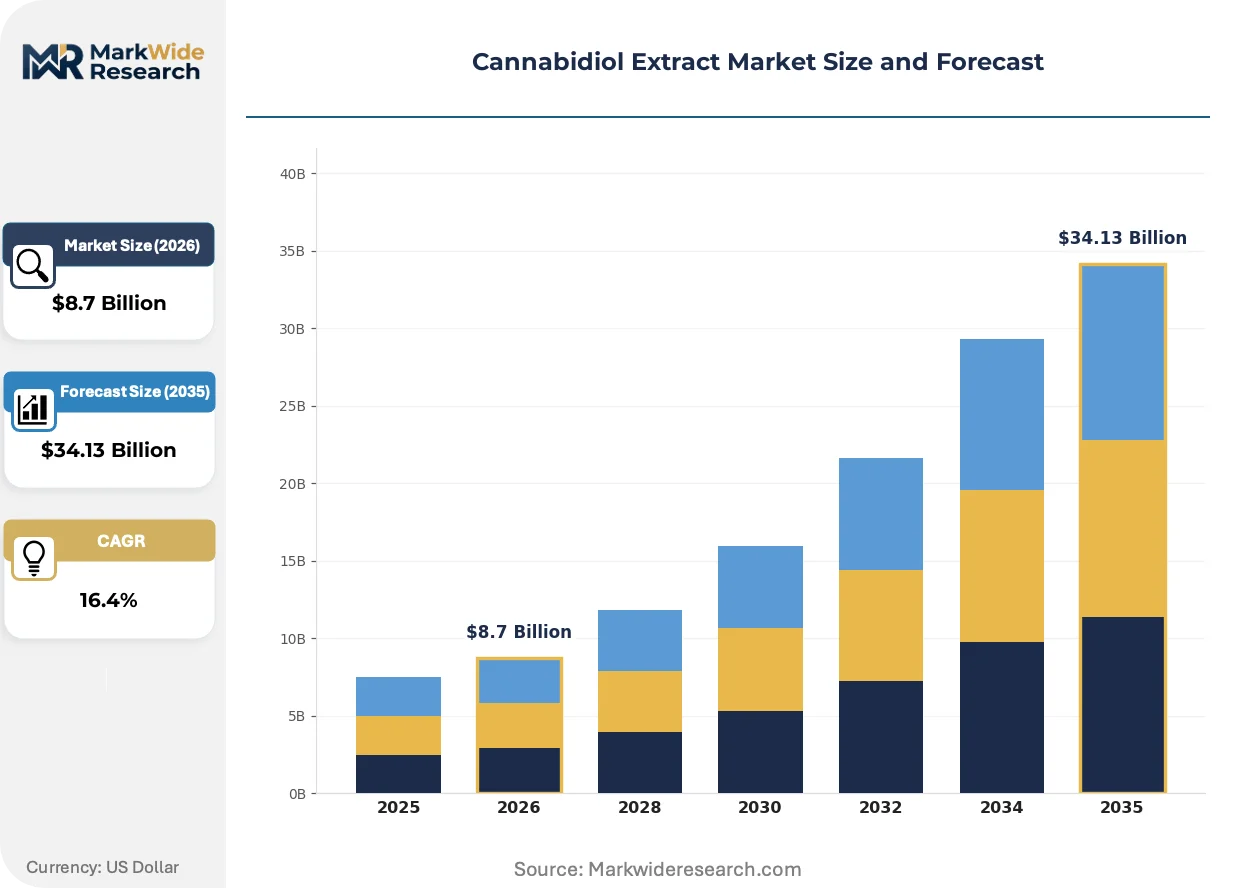
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Spectrum, Broad Spectrum, Isolate, Oil Application: Cosmetics, Food & Beverage, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Stores, Retail Pharmacies, Health Food Stores, Specialty Shops End User: Healthcare Providers, Retail Customers, Wholesalers, Manufacturers |
| Companies Covered | Canopy Growth Corporation, Aurora Cannabis Inc., Tilray Brands Inc., The Cronos Group, GW Pharmaceuticals Plc, Folium Biosciences, Medical Marijuana Inc., ENDOCA, CV Sciences Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabidiol Extract Market Trends and Innovations
Extraction technology and regulatory science are converging to bifurcate the market between pharmaceutical-grade isolates and wellness-positioned full-spectrum oils, with processing methods becoming the primary competitive differentiator.
Supercritical CO2 extraction is migrating from boutique craft positioning to industrial-scale pharmaceutical supply. Mid-cap processors in Colorado and Oregon are retrofitting 500-liter vessels with automated back-pressure regulators, achieving throughput parity with ethanol systems while preserving terpene profiles for wellness applications. This capability migration from craft to commodity is compressing margins for legacy ethanol operators dependent on winterization and distillation steps.
EMA's Committee for Herbal Medicinal Products is evaluating CBD monograph status under the Traditional Use Registration procedure, creating a parallel compliance track distinct from the full marketing authorization pathway used for Epidyolex. German and Polish regulators are piloting simplified quality documentation for hemp extracts below 2.5% CBD concentration, enabling botanical drug preparation status for compounding pharmacies.
Hospital procurement committees are consolidating supplier lists around vertically integrated extractors with DEA Schedule V registration and USP monograph compliance. Academic medical centers in California, New York, and Massachusetts now require chain-of-custody documentation from cultivation through final formulation, displacing toll-processed materials from non-affiliated biomass sources. This concentration of buying power favors extractors with captive cultivation and in-house analytical laboratories.
Cannabidiol Extract Market Segmentation
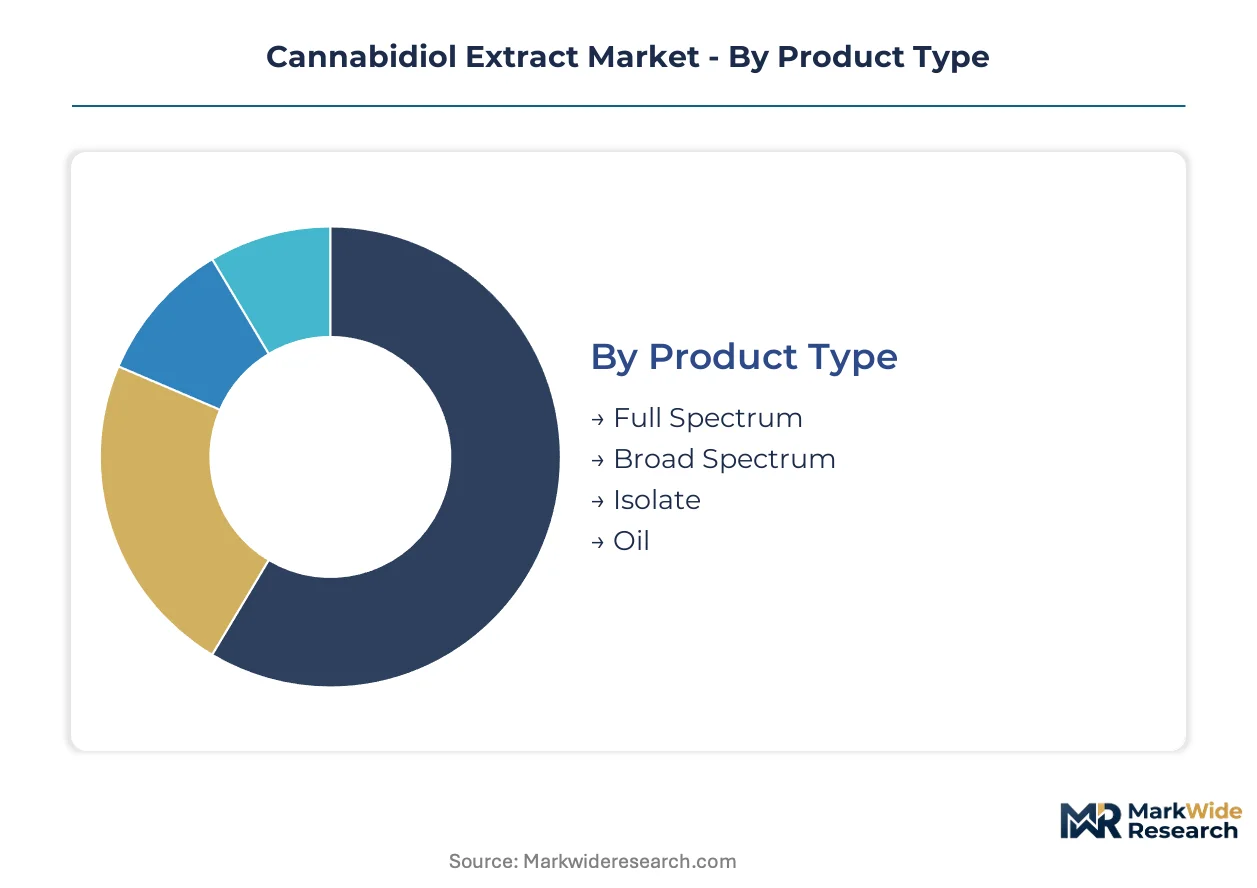
Segmentation in cannabidiol extract reveals divergent compliance burdens and margin structures across product grades. Pharmaceutical isolates command qualification-heavy procurement protocols, while wellness-positioned full-spectrum oils navigate fragmented state-level retail frameworks.
Product Type:
Mature extraction technologies now serve distinct therapeutic positioning tiers, with purity specifications determining regulatory pathway eligibility.
- Full Spectrum:Retains minor cannabinoids and terpenes below 0.3% THC threshold, preserving entourage effect synergy for wellness applications. German compounding pharmacies and California functional medicine clinics concentrate procurement here, drawn by botanical drug preparation status under simplified EMA documentation pilots.
- Broad Spectrum:THC-free formulations achieved through chromatography remediation, occupying mid-market positioning between clinical credibility and retail accessibility. Polish and Czech retailers increasingly stock these variants as EFSA Novel Food opinions remain pending.
- Isolate:Crystalline CBD exceeding 99% purity enables USP monograph compliance and DEA Schedule V registration for prescription drug developers.
- Oil:Lipid-based carrier formulations dominate direct-to-consumer channels with standardized potency labeling.
Isolate handles the majority of pharmaceutical throughput; full spectrum is gaining share fastest among practitioner-directed wellness protocols.
Application:
End-use concentration patterns reflect divergent regulatory gatekeeping intensity across consumer and clinical channels.
- Pharmaceuticals:FDA-registered active pharmaceutical ingredients and finished dosage forms for seizure disorders, requiring cGMP-certified extraction and batch release testing. US Medicaid reimbursement for Epidyolex analogues and German hospital formulary placement drive institutional procurement consolidation.
- Nutraceuticals:Dietary supplement positioning in capsules, tinctures, and softgels, navigating FDA enforcement discretion and state-level hemp program alignment. Colorado and Oregon processors supply bulk ingredients to contract manufacturers serving practitioner-only distribution.
- Cosmetics:Topical formulations leveraging INCI nomenclature and cosmetic safety substantiation without drug claims.
- Food & Beverage:Infused products awaiting finalized GRAS or food additive pathway determination.
Pharmaceuticals absorbs the highest qualification overhead; nutraceuticals is expanding most quickly through compounding pharmacy bypass channels.
Distribution Channel:
Channel selection determines documentation burden and margin retention for extractors navigating fragmented compliance landscapes.
- Retail Pharmacies:Chain and independent dispensaries requiring DEA registration, state board compliance, and prescription or behind-counter protocols. CVS and Walgreens pilot programs in select US states concentrate volume for validated isolates.
- Online Stores:Direct-to-consumer platforms with Certificate of Analysis transparency and subscription fulfillment, dominant in UK and Netherlands markets where novel food enforcement varies.
- Health Food Stores:Natural products retailers stocking wellness-positioned full-spectrum oils with third-party certification.
- Specialty Shops:Cannabis-focused retailers in state-legal jurisdictions with higher-THC adjacent product mixes.
Retail pharmacies captures the steepest margin premiums; online stores is climbing the fastest on cross-border accessibility.
End User:
Customer type dictates contract structure, with institutional procurement consolidating around vertically integrated suppliers.
- Healthcare Providers:Academic medical centers, specialty clinics, and compounding pharmacies requiring chain-of-custody documentation and USP compliance. New York Presbyterian and Massachusetts General now mandate captive cultivation sourcing.
- Manufacturers:Finished product formulators purchasing bulk isolates and distillates under master service agreements with audit rights.
- Wholesalers:Distributors serving multi-state retail networks with consolidated logistics and regulatory navigation support.
- Retail Customers:Individual consumers purchasing through direct channels with potency verification demands.
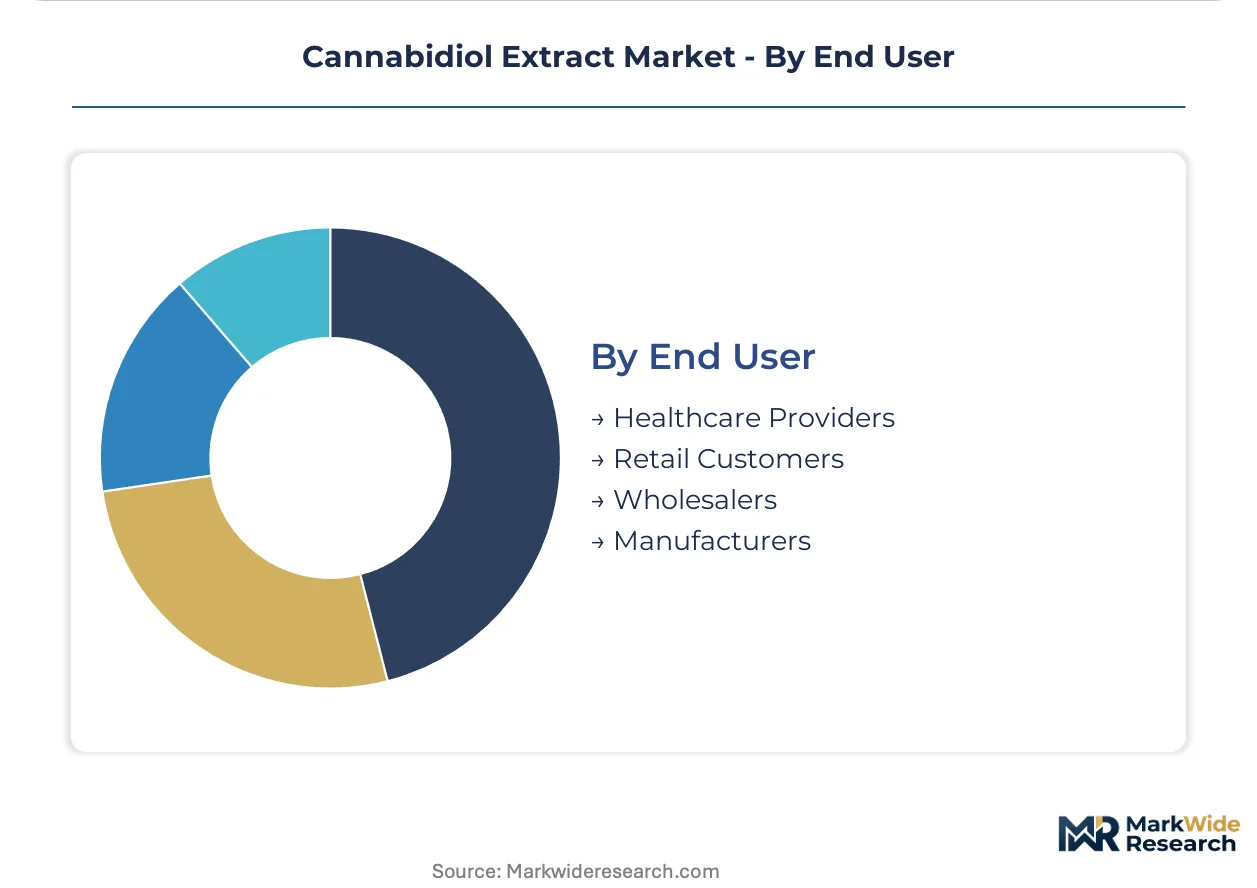
Healthcare providers enforces the strictest supplier qualification; manufacturers is expanding most quickly on pharmaceutical partnership pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in cannabidiol extract tilt heavily toward raw biomass outbound from North American cultivation zones and finished isolates inbound to European pharmaceutical manufacturers. The United States maintains a structural surplus in hemp-derived CBD raw material while importing limited volumes of specialty extracts from Swiss and Israeli suppliers.
United States
State-level hemp programs in Colorado, Oregon, and Kentucky drive cultivation volume while DEA Schedule V registration requirements concentrate pharmaceutical-grade processing in licensed facilities. The USDA Domestic Hemp Production Program now spans 47 states, saturating biomass supply and compressing input costs for toll processors near Denver and Portland.
Germany
Hospital formularies in Berlin and Munich now list reimbursable CBD therapies for seizure disorders, creating institutional procurement pull. The BfArM maintains strict import licensing for cannabis-derived APIs, favoring EU-GMP certified suppliers with established pharmacovigilance systems. Industrial extraction clusters concentrate in North Rhine-Westphalia near pharmaceutical manufacturing infrastructure.
Switzerland
Swissmedic's relatively permissive stance on low-THC hemp extracts has positioned Basel and Zurich as European distribution hubs for wellness-positioned full-spectrum oils. The country's pharmaceutical heritage attracts toll-processing contracts from German and French brands seeking quality association. Geneva-based traders coordinate cross-border logistics into EU member states pending Novel Food authorization.
United Kingdom
The MHRA's recognition of CBD as a medicinal product requiring marketing authorization has bifurcated the market between prescription Epidyolex distribution and unregulated wellness products sold online. London and Manchester host compounding pharmacy networks sourcing bulk isolates under practitioner-only frameworks. Post-Brexit regulatory divergence from EFSA Novel Food processes creates parallel compliance tracks.
Netherlands
Amsterdam and Rotterdam serve as logistics gateways for hemp extracts entering European distribution, leveraging the country's advanced cold-chain infrastructure and customs efficiency. The Office of Medicinal Cannabis maintains controlled cultivation quotas that limit domestic supply, forcing reliance on imported isolates for pharmaceutical formulation. Dutch retailers increasingly stock broad-spectrum variants as EFSA opinions remain pending.
Cannabidiol Extract Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with extraction capacity and genetic IP. The supplier base compresses around cGMP-certified processors as pharmaceutical formulators consolidate procurement. Three archetypes dominate: vertically integrated cultivator-processors with captive biomass, toll-processing specialists with equipment scale, and direct-to-consumer brands with certified organic positioning. Competitive moves concentrate on EU-GMP certification acquisition and synthetic biology partnerships for rare cannabinoid production.
Within the integrated cultivation tier, Canopy Growth Corporation and Aurora Cannabis Inc. represent the multi-licensed facility archetype with backward control over supply chains. Folium Biosciences anchors the industrial-scale processing segment with proprietary hemp genetics and bulk isolate production. ENDOCA occupies a position in certified organic direct-to-consumer channels across European markets. GW Pharmaceuticals Plc exemplifies the pharmaceutical-grade isolate pathway with FDA-registered active pharmaceutical ingredient qualification.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Aurora Cannabis Inc. |
| Tilray Brands Inc. |
| The Cronos Group |
| GW Pharmaceuticals Plc |
| Folium Biosciences |
| Medical Marijuana Inc. |
| ENDOCA |
| CV Sciences Inc. |
| Others |
Pricing and Supply Chain Analysis
Regulatory chokepoint exposure at the FDA enforcement discretion boundary determines both the three-tier pricing structure across pharmaceutical, nutraceutical, and wellness grades and the geographic fragmentation of supply chain nodes. Biomass processors in Colorado and Oregon face margin compression from THC remediation cost volatility while pharmaceutical-grade isolates command premium positioning through DEA Schedule V registration barriers.
Pricing Analysis
Pharmaceutical formulators anchor pricing stratification across premium, standard, and economy tiers through cGMP certification requirements and USP monograph compliance. Price differentiation stems from analytical validation depth and captive cultivation sourcing, with academic medical centers in New York and Massachusetts enforcing the strictest supplier qualification protocols. Cost compression in broad-spectrum extraction is intensifying because chromatography resin pricing and solvent recovery energy costs erode processor margins. Toll-processing specialists serving nutraceutical contract manufacturers exhibit the highest price sensitivity, while hospital procurement committees with consolidated buying power demonstrate the least.
Supply Chain Analysis
DEA Schedule V registration controls and EU-GMP certification requirements limit cross-border flows of pharmaceutical-grade active pharmaceutical ingredients. Raw biomass supply concentrates in Kentucky, Oregon, and Colorado under the USDA Domestic Hemp Production Program, while finished isolate production clusters near Denver and Portland. The supply chain rests on supercritical CO2 equipment from specialized manufacturers, chromatography resins for THC remediation, and certified reference standards for potency validation. Single-source vulnerability sits with analytical chemist scarcity in cannabis-dominant state labor markets. Distribution runs through vertically integrated extractors with captive cultivation, toll-processing specialists with equipment scale, and direct-to-consumer brands with certified organic positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of HPLC method development talent intersecting with terpene profiling and residual solvent validation expertise constrains capacity expansion across all market tiers. This capability gap favors incumbents with established analytical laboratories and creates acquisition premiums for qualified technical teams.
For Market Incumbents: Harden analytical laboratory capabilities through EU-GMP certification investment and in-house reference standard production to defend against synthetic biology entrants producing rare cannabinoids via yeast fermentation. Deepen upstream control over proprietary hemp genetics to secure biomass supply security independent of seasonal THC variance. Prioritize DEA Schedule V registration maintenance as hospital procurement committees consolidate supplier lists around vertically integrated extractors with chain-of-custody documentation. For New Entrants and Emerging Players: Pursue veterinary therapeutic white space through MUMS pathway designations for companion animal indications, where regulatory precedent remains unsettled and first-mover positioning offers formulary capture potential. Target direct-to-clinic distribution through specialty compounding pharmacies and functional medicine practices bypassing retail markup. Enter with certified organic positioning and practitioner-only licensing frameworks to establish credibility before scaling to mass retail channels. For Investors and Strategic Acquirers: FDA finalization of an over-the-counter CBD regulatory pathway reshapes the acquisition landscape by either legitimizing mass-market wellness positioning or maintaining enforcement discretion fragmentation that favors pharmaceutical-grade specialists. Position for five-to-ten-year horizon viability by targeting toll-processing specialists with 500-liter supercritical CO2 vessel scale and established German or Swiss distribution relationships. Monitor EFSA Novel Food authorization timelines as the critical inflection signal distinguishing legitimate European market access from continued regulatory limbo.| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Acquisition | Unlocks German hospital formulary placement and BfArM import licensing for prescription-grade APIs. |
| Synthetic Biology Partnership | Yeast fermentation of CBG and CBN offers pharmaceutical partners supply security beyond agricultural cycles. |
| Veterinary Drug Sponsorship | MUMS pathway designation in companion animals captures white space before regulatory precedent hardens. |
| Direct-to-Clinic Distribution | Practitioner-only licensing frameworks bypass retail markup and build prescriber loyalty. |
| Proprietary Genetics Development | Cultivar IP with sub-0.3% THC stability reduces chromatography remediation costs and batch rejection risk. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement discretion guidance documents, EMA Committee for Medicinal Products for Human Use precedent decisions, and state-level hemp program administrative records. Extraction technology providers, pharmaceutical formulators, compounding pharmacy procurement managers, and regulatory affairs specialists contributed structured interviews. Secondary validation drew from USDA Domestic Hemp Production Program acreage reports, DEA controlled substance registration databases, and hospital formulary placement records. Bottom-up capacity modeling triangulated against top-down demand segmentation across pharmaceutical, nutraceutical, and wellness positioning tiers.
Forecast inputs span biomass cultivation yield assumptions, supercritical CO2 equipment throughput scaling, and regulatory pathway probability weightings across the projection horizon. Segmentation dimensions include product grade tier, application channel, distribution model, and regional regulatory cluster. CAGRs derive from installed base growth rates and pricing trajectory synthesis. Industry-specific inputs incorporate EFSA Novel Food opinion timing scenarios and Medicaid reimbursement expansion patterns for seizure disorder therapies.
Sensitivities concentrate around FDA enforcement discretion finalization, EFSA Novel Food authorization backlog resolution, and DEA scheduling reconsideration. Forecasts reflect assumptions regarding state hemp program stability and EU-GMP certification timeline consistency. Material shifts in federal regulatory pathway determination or European ingestible product authorization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Synthetic Cannabinoids Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Global Cannabis Market
Cannabis/Marijuana
Global Cannabis Extract Market