
 US Medical Marijuana Market | 2026-2036
US Medical Marijuana Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Marijuana Market Intelligence
Dispensary-to-patient delivery channels is narrowing as state regulators tighten logistics licensing and inventory tracking mandates. Curaleaf Holdings Inc. leverages multi-state operational scale to sustain vertically integrated production across 19 jurisdictions. Green Thumb Industries anchors retail density in Illinois and Pennsylvania through controlled store footprints. Trulieve Cannabis Corp dominates Florida's vertically structured market with cultivation, processing, and dispensary assets under unified control.
US Medical Marijuana comprises pharmacologically active cannabis plant derivatives—primarily delta-9-tetrahydrocannabinol and cannabidiol—formulated as oils, extracts, edibles, topicals, capsules, and tinctures for therapeutic administration under physician supervision. Standardized extraction methods using supercritical CO2 or ethanol yield defined cannabinoid profiles with batch-level consistency for clinical dosing. CBD Oil and THC Extracts command the deepest margin pools due to manufacturing complexity and pharmacy-grade certification requirements. The Chronic Pain therapy area leads patient volumes, while Cancer Care applications generate premium pricing through oncologist-directed protocols.
FDA, DEA, and state-level medical cannabis programs collectively govern product safety testing, scheduling classifications, and dispensing authorization across the United States. The Controlled Substances Act maintains federal prohibition, forcing operators to navigate fragmented state-by-state compliance architectures without interstate banking or standardized insurance frameworks. Stakeholders must monitor rescheduling proceedings and state-level adult-use ballot initiatives that could reshape medical program exclusivity and pricing power.
Market Dynamics
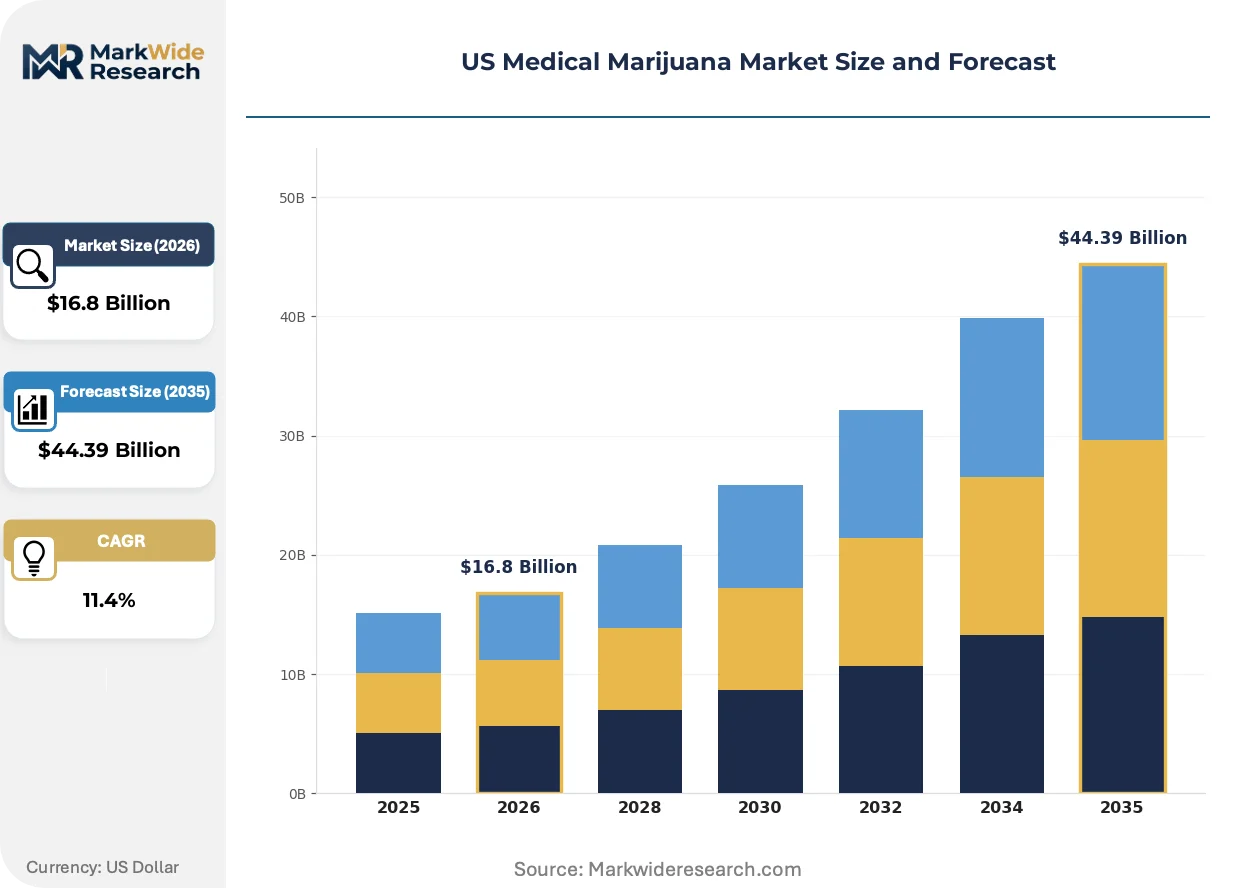
State-level medical cannabis programs are fragmenting supply chains into 38 distinct regulatory jurisdictions, forcing operators to replicate cultivation and testing infrastructure across state lines without interstate commerce relief.
Growth Catalysts
- State Program Expansion:New York and Virginia launched adult-use frameworks with medical priority licensing, accelerating patient enrollment and dispensary density in the Northeast corridor.
- Oncology Protocol Integration:NCI-designated cancer centers in Texas and Ohio established cannabis-integrated supportive care pathways, creating institutional demand for standardized cannabinoid formulations.
- Supercritical CO2 Extraction:This manufacturing technology yields pharmaceutical-grade cannabinoid isolates with batch-level consistency, satisfying pharmacy certification requirements for clinical dosing protocols.
Market Restraints
- 280E Tax Burden:The Internal Revenue Code provision denies standard business deductions to cannabis enterprises, compressing operating margins by 30-40 percentage points versus conventional pharmaceutical manufacturers.
- Banking Exclusion:Federal prohibition under the Controlled Substances Act bars access to FDIC-insured lending and treasury services, forcing cash-intensive operations and armored transport dependency.
- Interstate Commerce Blockade:The 2018 Farm Bill's hemp-CBD provisions exclude THC-containing products, preventing economies of scale in distribution and manufacturing footprint consolidation.
Strategic Opportunities
- Telehealth Expansion:Florida and Pennsylvania authorized remote physician certifications, reducing patient onboarding friction and expanding addressable geography beyond urban clinic clusters.
- Minor Cannabinoid Formulations:CBG and CBN therapeutic applications in sleep and inflammation represent formulation white space with limited competitive saturation and premium pricing potential.
- Research License Pathways:DEA expanded domestic cannabis cultivation permits for Schedule I research, enabling FDA-compliant drug development pipelines and pharmaceutical partnership structures.
Industry Challenges
- Quality Control Talent Scarcity:Analytical chemists with cannabis-specific method validation experience command 40-60% salary premiums, constraining laboratory scale-up timelines.
- Batch Release Delays:State-mandated microbial and potency testing creates 14-21 day inventory holds, complicating just-in-time distribution and working capital management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Marijuana Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $44.39 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CBD Oil, THC Extracts, Edibles, Topicals, Capsules, Tinctures Therapy Area: Chronic Pain, Epilepsy, PTSD, Multiple Sclerosis, Cancer Care, Anxiety Disorders End User: Hospitals, Specialty Clinics, Pharmacies, Rehabilitation Centers, Home Care Providers, Research Institutes Distribution Channel: Dispensaries, Online Pharmacies, Medical Clinics, Licensed Retail Stores, Telemedicine Platforms, Direct-to-Patient Delivery |
| Companies Covered | Curaleaf Holdings Inc., Green Thumb Industries, Trulieve Cannabis Corp, Cresco Labs, Verano Holdings, Tilray Brands Inc., Acreage Holdings, PharmaCann Inc., Ascend Wellness Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Marijuana Market Strategic Shifts & Innovations
Digital infrastructure is penetrating cultivation compliance and patient access layers simultaneously, compressing operational transparency gaps that previously separated legacy operators from institutional healthcare standards.
Seed-to-sale tracking platforms is digitizing inventory chain-of-custody documentation across cultivation, processing, and dispensing nodes. Multi-state operators in Illinois and Arizona deployed Metrc and BioTrackTHC integrations to satisfy state audit requirements. This technology is digitizing regulatory compliance workflows, reducing manual reconciliation labor while creating data assets for yield optimization analytics.
FDA issued warning letters to CBD marketers making unsubstantiated therapeutic claims, signaling enforcement priority on product labeling integrity. This policy pressure is compressing marketing flexibility for hemp-derived operators while creating competitive shelter for state-licensed medical cannabis programs with established physician oversight protocols. California and Colorado regulators tightened residual solvent testing thresholds in response, accelerating laboratory equipment upgrade cycles.
Hospital procurement committees are establishing formal cannabis product evaluation frameworks, displacing informal physician-directed purchasing. Oncology departments at Cedars-Sinai and MD Anderson developed pharmacy-and-therapeutics review processes for cannabinoid adjunctive therapies. This institutionalization concentrates demand authorization within pharmacy benefit managers and formulary committees, raising vendor qualification barriers in California and Texas metropolitan markets.
US Medical Marijuana Market Segmentation
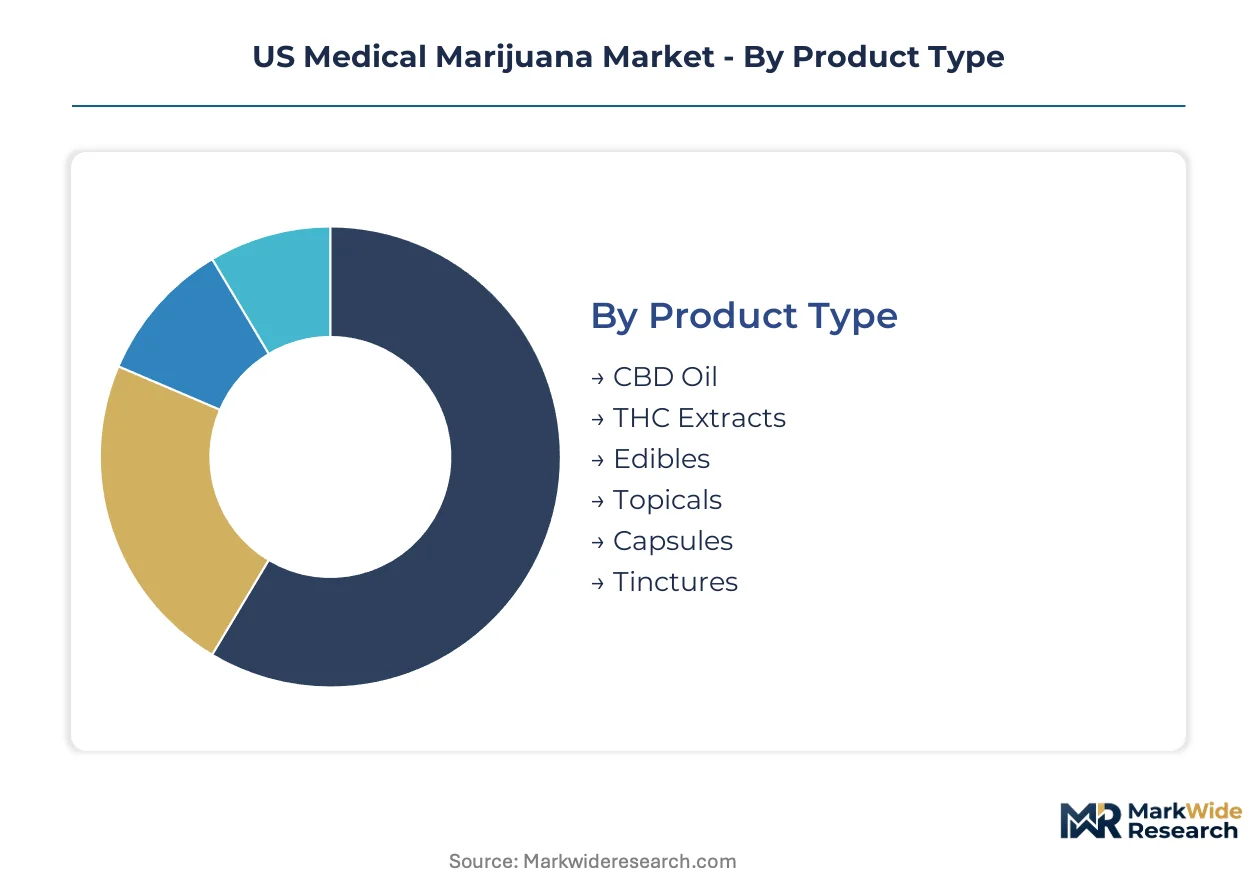
Segmentation in the US Medical Marijuana Market reveals how regulatory fragmentation and clinical adoption patterns create distinct commercial battlegrounds. Product formulation standards, therapy-specific reimbursement pathways, and distribution licensing requirements vary sharply across state jurisdictions, forcing operators to prioritize segment-specific capabilities rather than broad horizontal plays.
Product Type:
Mature extraction technologies dominate high-volume segments while novel delivery formats capture emerging patient preferences in restrictive regulatory environments.
- CBD Oil:Supercritical CO2 extraction yields pharmaceutical-grade isolates with defined cannabinoid ratios for physician-directed dosing protocols. Demand concentrates in Florida and Pennsylvania oncology departments where hospital pharmacy committees require batch-level consistency documentation for formulary inclusion.
- THC Extracts:Concentrated delta-9-tetrahydrocannabinol formulations delivered via vaporization or sublingual routes provide rapid onset for breakthrough pain management. California and Illinois pain clinics drive volume through established relationships with state-licensed cultivators maintaining GMP-adjacent manufacturing standards.
- Edibles:Gastric-absorbed cannabinoid products in precise milligram denominations serve patient populations averse to inhalation, with Ohio and Arizona regulators mandating child-resistant packaging and homogeneity testing that extends production cycles.
- Topicals:Transdermal formulations targeting localized inflammation avoid first-pass metabolism, finding traction in physical therapy and sports medicine clinics across Colorado and Oregon where topical-only recommendations require no patient registry enrollment.
- Capsules:Encapsulated oil formulations standardize dosing for polypharmacy patients, with Veterans Affairs facilities in New Mexico and Michigan piloting capsule-based protocols for PTSD symptom management under institutional review board oversight.
- Tinctures:Alcohol or oil-based sublingual solutions offer titration flexibility for geriatric populations, particularly in Minnesota and Maryland where medical programs restrict smokable flower and drive demand for liquid alternatives.
CBD Oil handles the majority of throughput; THC Extracts is the fastest mover on share.
Therapy Area:
Patient enrollment volumes and reimbursement complexity stratify therapy areas into institutional anchors versus emerging indications requiring evidence development.
- Chronic Pain:Neuropathic and inflammatory pain conditions generate the largest addressable patient pools, with Ohio and Illinois establishing dedicated cannabis pain clinics that integrate with existing opioid tapering programs under state health department guidelines.
- Cancer Care:Chemotherapy-induced nausea and appetite stimulation command premium pricing through oncologist-directed protocols, with MD Anderson and Memorial Sloan Kettering developing institutional supportive care pathways that standardize cannabinoid adjunctive therapy selection.
- Epilepsy:Pediatric and treatment-resistant seizure disorders drove initial FDA engagement with cannabinoid pharmaceuticals, with Texas and Georgia maintaining restricted-access programs focused on low-THC formulations for qualifying patients.
- PTSD:Veterans Affairs healthcare systems in Arizona and New Mexico have authorized physician cannabis recommendations for service-connected trauma, creating concentrated demand within federally adjacent but state-regulated treatment frameworks.
- Multiple Sclerosis:Spasticity and neuropathic pain symptoms in progressive neurodegenerative disease attract specialty neurology practice adoption, particularly in Colorado and Michigan where MS centers maintain dedicated cannabis consultation services.
- Anxiety Disorders:Generalized anxiety and panic disorder indications face stricter scrutiny in states requiring qualifying condition lists, with New Jersey and Connecticut recently adding anxiety to approved indications after clinical registry data accumulation.
Chronic Pain absorbs the greatest patient volume; Cancer Care commands the steepest expansion trajectory as institutional protocols proliferate.
End User:
Procurement authority and formulary control determine end-user segment attractiveness, with hospital systems imposing vendor qualification barriers that exclude smaller operators.
- Hospitals:Academic medical centers in California and Texas are establishing pharmacy-and-therapeutics review processes for cannabinoid products, requiring Certificate of Analysis documentation and manufacturing site inspections that favor multi-state operators with quality management infrastructure.
- Specialty Clinics:Pain management and neurology practices in Florida and Pennsylvania generate high prescription volumes through dedicated cannabis certification physicians, with state medical boards monitoring recommendation patterns for compliance enforcement.
- Pharmacies:Hospital outpatient and independent pharmacies in Connecticut and Minnesota dispense medical cannabis alongside conventional prescriptions, with state boards of pharmacy imposing storage security and inventory tracking requirements distinct from retail dispensary standards.
- Rehabilitation Centers:Substance use and physical rehabilitation facilities in Massachusetts and Washington incorporate cannabinoid therapies into multimodal treatment plans, navigating federal funding restrictions that complicate service delivery.
- Home Care Providers:Home health agencies in Oregon and Colorado support registered patients with delivery and administration assistance, operating within state-specific caregiver designation frameworks that limit interstate service expansion.
- Research Institutes:DEA-registered research institutions in Mississippi and California conduct Schedule I cannabis studies under expanded domestic cultivation permits, generating demand for standardized investigational formulations with batch documentation exceeding commercial requirements.
Specialty Clinics manage the highest prescription throughput; Hospitals are climbing the fastest on institutional adoption curves.
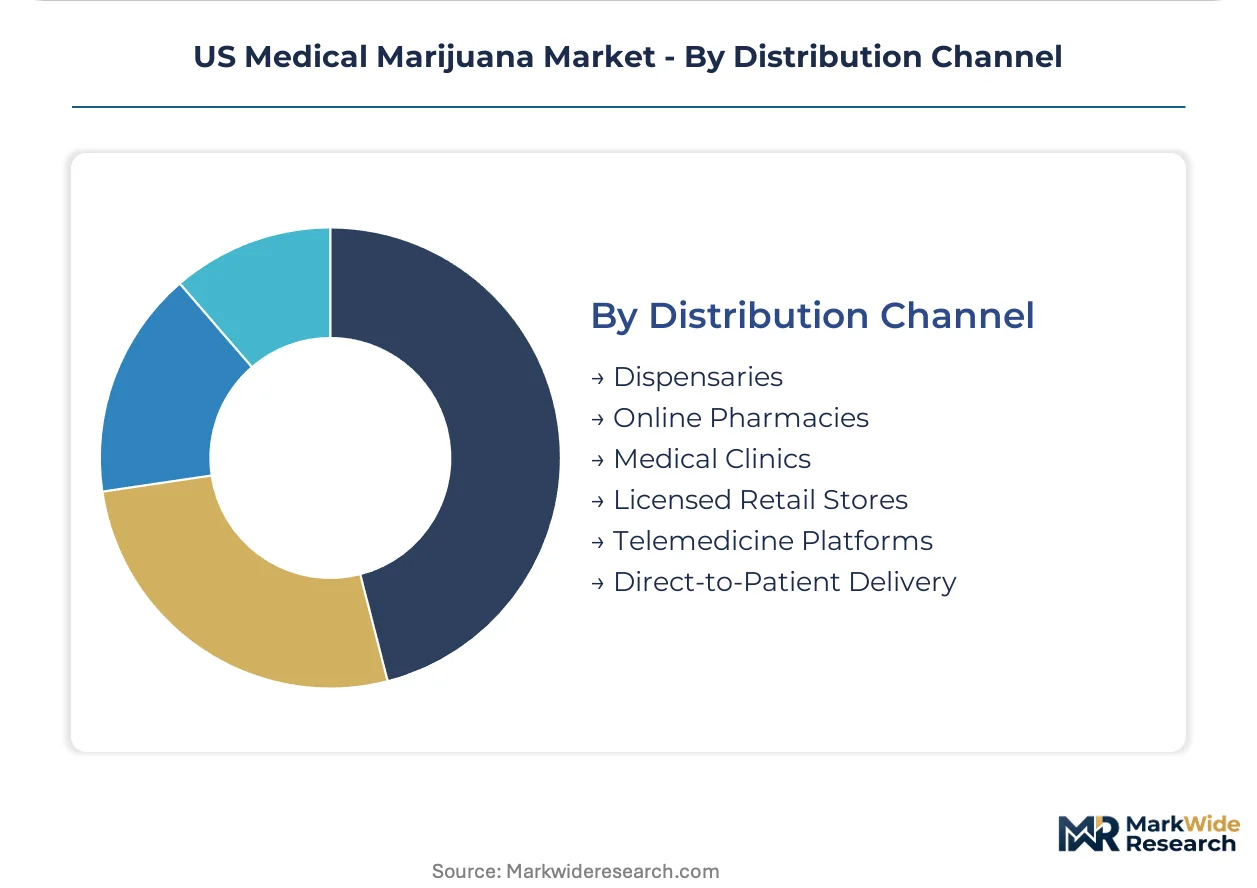
Distribution Channel:
Regulatory licensing density and patient access convenience define channel viability, with state-mandated vertical integration requirements preventing pure-play distribution models in key markets.
- Dispensaries:State-licensed retail facilities in Florida and Illinois maintain exclusive rights to medical cannabis sales, with Florida's vertical integration mandate requiring operators to control cultivation, processing, and dispensing under unified ownership structures.
- Online Pharmacies:Telehealth-integrated dispensing platforms in Pennsylvania and New York reduce patient onboarding friction through remote physician certification and home delivery, with state regulators requiring real-time inventory synchronization with seed-to-sale tracking systems.
- Medical Clinics:Physician office dispensing in Arizona and New Mexico allows qualified practitioners to provide cannabis directly to registered patients, with limited product selection compared to dedicated dispensary environments.
- Licensed Retail Stores:Adult-use retailers with medical priority licensing in Virginia and New York serve dual customer bases, with tax exemptions and purchase quantity advantages incentivizing medical program enrollment despite recreational availability.
- Telemedicine Platforms:Remote consultation services in Florida and Ohio expanded patient geography beyond urban clinic clusters, with state medical boards establishing specific informed consent and follow-up requirements for virtual cannabis certifications.
- Direct-to-Patient Delivery:Courier services in California and Nevada transport products from dispensaries to registered patient residences, with state transportation licensing and GPS tracking mandates increasing operational complexity and insurance costs.
Dispensaries retain the dominant share of transaction volume; Telemedicine Platforms are gaining share fastest as remote care infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 95 corridor and its feeder highways anchor the eastern seaboard's distribution architecture, while the Central Valley's agricultural processing infrastructure underwrites California's cultivation dominance. State-level regulatory fragmentation prevents unified national supply chains.
California
Los Angeles and San Diego anchor the nation's largest state-legal cannabis economy. The Department of Cannabis Control enforces batch-level testing mandates that extend inventory cycles. Oakland's manufacturing corridor concentrates supercritical CO2 extraction facilities serving oncology supply chains at Cedars-Sinai and Stanford Medicine.
Florida
Vertical integration requirements force operators to replicate cultivation, processing, and retail under unified ownership. The Department of Health's Office of Medical Marijuana Use mandates real-time seed-to-sale tracking through Metrc. Miami-Dade and Orange County clusters concentrate dispensary density alongside aging population corridors driving chronic pain demand.
Illinois
Chicago's metropolitan statistical area generates the Midwest's highest prescription volumes through integrated pain management networks. The Department of Financial and Professional Regulation imposes social equity licensing requirements that reshape competitive entry. Cook County's pharmaceutical logistics hub enables just-in-time distribution to hospital outpatient pharmacies.
Pennsylvania
Pittsburgh and Philadelphia anchor dual demand centers for oncology and chronic pain applications. The Department of Health's medical marijuana program requires physician certification through state-approved practitioners. Delaware Valley's biopharma manufacturing belt supplies analytical chemistry talent for laboratory quality control functions.
New York
The Hudson Valley's agricultural zones host greenhouse cultivation serving New York City metropolitan demand. The Office of Cannabis Management's adult-use framework maintains medical program priority licensing. Buffalo-Rochester corridor industrial real estate attracts processing investments from multi-state operators seeking northeastern manufacturing footholds.
US Medical Marijuana Market Key Industry Players
On the supply side, the industry is bifurcated between multi-state operators with compliance infrastructure and single-state cultivators with localized cultivation advantages. The vendor base stratifies into three tiers: vertically integrated giants controlling 19-state footprints, regional specialists dominating single jurisdictions, and emerging license holders navigating social equity pathways. Dominant competitive moves include license portfolio accumulation through asset acquisitions and backward integration into proprietary genetics and extraction IP.
Among publicly traded multi-state operators, Curaleaf Holdings Inc., Green Thumb Industries, and Trulieve Cannabis Corp occupy distinct strategic positions. Curaleaf exemplifies the scale-driven archetype with cultivation and retail assets spanning fragmented regulatory jurisdictions. Green Thumb Industries represents the retail-density specialist model, concentrating controlled store footprints in high-barrier Midwestern and Northeastern markets. Trulieve anchors the vertically integrated single-state dominance pattern, unifying cultivation, processing, and dispensary operations under unified control structures. These three entities collectively illustrate how capital access and regulatory navigation capabilities determine competitive positioning across state-by-state compliance architectures.
| Leading Market Players |
|---|
| Curaleaf Holdings Inc. |
| Green Thumb Industries |
| Trulieve Cannabis Corp |
| Cresco Labs |
| Verano Holdings |
| Tilray Brands Inc. |
| Acreage Holdings |
| PharmaCann Inc. |
| Ascend Wellness Holdings |
| Others |
Cost & Logistics Intelligence
Cultivation concentration in California's Central Valley and Florida's greenhouse corridors feeds directly into margin capture at the extraction and formulation tiers, where pharmacy-grade certification requirements create pricing power for operators with analytical chemistry infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs product positioning, with pharmacy-grade isolates commanding spreads over unprocessed biomass based on batch-level consistency documentation and residual solvent testing thresholds. Cost compression in mid-tier extracts is intensifying because state-mandated testing extends production cycles and laboratory equipment upgrade demands. Dispensary buyers exhibit highest price sensitivity on commoditized flower products, while hospital pharmacy committees show lowest sensitivity for oncology-directed formulations with institutional formulary inclusion.
Supply Chain Analysis
Upstream cannabis biomass draws from controlled-environment agriculture in California, Florida, and Colorado, with genetic stock and propagation materials resting on nursery operations subject to plant quarantine regulations. Supercritical CO2 extraction equipment, child-resistant packaging, and analytical reference standards constitute critical component dependencies. Single-source vulnerability concentrates in state-licensed testing laboratories where microbial and potency validation creates 14-21 day inventory holds. Distribution runs through vertically integrated dispensary networks in Florida and Illinois, with direct-to-patient courier services expanding in California and Nevada under GPS tracking mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
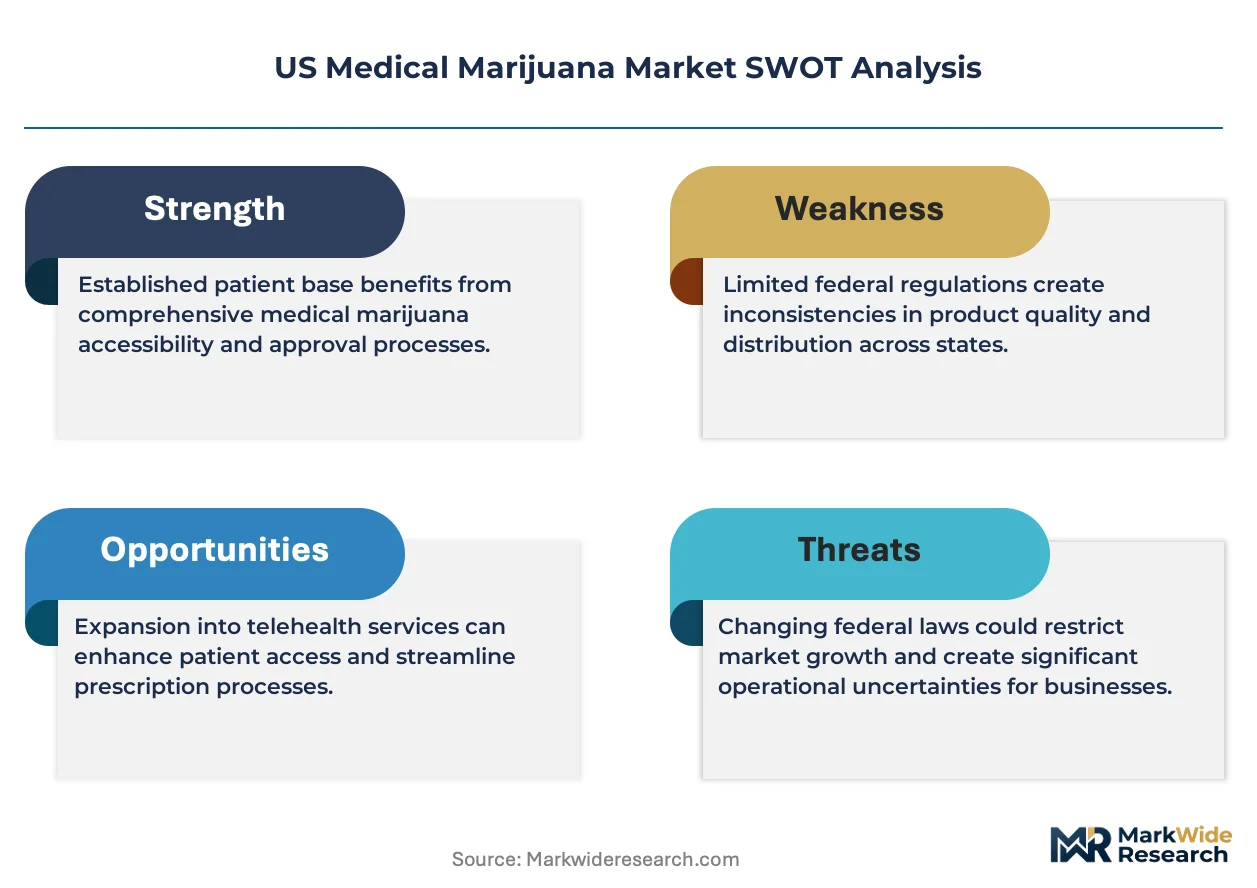
This market functions as a regulatory entrenchment story, where state-level licensing scarcity and compliance infrastructure requirements create switching costs that protect incumbent positions against fragmented new entry.
For Market Incumbents: Build regulatory moats through backward integration into proprietary genetics and extraction IP, while accumulating multi-state license portfolios to amortize compliance infrastructure across jurisdictions. Federal rescheduling proceedings and adult-use ballot initiatives threaten medical program exclusivity; prioritize capacity addition in Northeast corridor markets with social equity licensing requirements to preempt competitive entry. For New Entrants and Emerging Players: Establish a beachhead in minor cannabinoid formulations targeting sleep and inflammation applications, where CBG and CBN therapeutic white space offers limited competitive saturation. Pennsylvania and New York telehealth-integrated dispensing platforms represent the most penetrable channel geography; pursue remote physician certification partnerships as the primary go-to-market angle to bypass capital-intensive dispensary licensing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multi-state operators possessing 15-plus jurisdiction footprints and quality management infrastructure qualifying for hospital formulary review. Long-term viability hinges on federal regulatory clarity and pharmaceutical partnership structures; watch DEA expanded domestic cultivation permit issuance as the inflection signal for Schedule I research pipeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Pharmaceutical-grade isolates satisfy Cedars-Sinai and MD Anderson pharmacy certification requirements for clinical dosing protocols. |
| Multi-State License Portfolio Accumulation | Compliance infrastructure amortization across 19 jurisdictions reduces per-unit regulatory burden versus single-state operators. |
| Telehealth Platform Integration | Remote physician certifications in Florida and Pennsylvania expand addressable geography beyond urban clinic clusters. |
| Minor Cannabinoid Formulation Development | CBG and CBN sleep applications capture formulation white space with premium pricing potential and limited competitive saturation. |
| Hospital Formulary Inclusion Pathway | Certificate of Analysis documentation and manufacturing site inspections unlock oncology department procurement at academic medical centers. |
Research Approach
Desk research of FDA warning letters, state medical cannabis program regulations, and DEA scheduling proceedings preceded structured interviews with cultivation operations directors, state regulatory compliance officers, hospital pharmacy and therapeutics committee members, and multi-state operator executives. Secondary validation drew from state health department patient registry disclosures, seed-to-sale tracking platform data, and SEC filings of publicly traded cannabis enterprises. Bottom-up patient volume modeling and top-down market sizing triangulation anchored value estimates.
Assumptions held fixed include state-level medical program continuity, federal prohibition under the Controlled Substances Act, and 280E tax burden persistence across the projection horizon. Segmentation dimensions modeled encompass product formulation, therapy area, end-user procurement authority, and distribution channel licensing requirements. CAGRs derived from patient enrollment trajectory analysis and dispensary transaction volume trends, with inputs from oncology protocol integration pace and telehealth regulatory expansion.
Stress conditions across federal rescheduling outcomes, interstate commerce liberalization, and state adult-use conversion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory fragmentation persistence. Material shifts in DEA scheduling classification or FDA cannabinoid drug approval pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
Morocco Medical Cannabis Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
CBD Pouches Market