
 Global Cannabis ERP Software Market | 2026-2036
Global Cannabis ERP Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cannabis ERP Software Market Foresight
Modular bundling of compliance, inventory, and financial modules into unified platform suites is expanding buyer choice across cultivation and retail operations. Flourish Software leverages deep integration with state traceability systems to anchor its position among multi-facility operators. BioTrackTHC sustains technology leadership through specialized seed-to-sale workflows. MJ Freeway competes on geographic coverage across diverse state regulatory environments.
Cannabis ERP software denotes enterprise resource planning systems architected for the legal cannabis industry, incorporating batch-level inventory tracking, plant-tag synchronization, and audit-ready reporting protocols that satisfy jurisdictional compliance requirements. The primary commercial purpose centers on replacing fragmented spreadsheets and manual logs with automated workflows that reduce regulatory exposure and operational leakage. Cloud-based deployment leads solution delivery by removing infrastructure burdens from emerging operators with limited IT staff. Inventory management and compliance tracking solution types capture concentrated margin pools as these functions carry the highest failure costs from regulatory penalties. Among end users, cultivators and dispensaries drive disproportionate platform investment due to their direct interface with state traceability mandates.
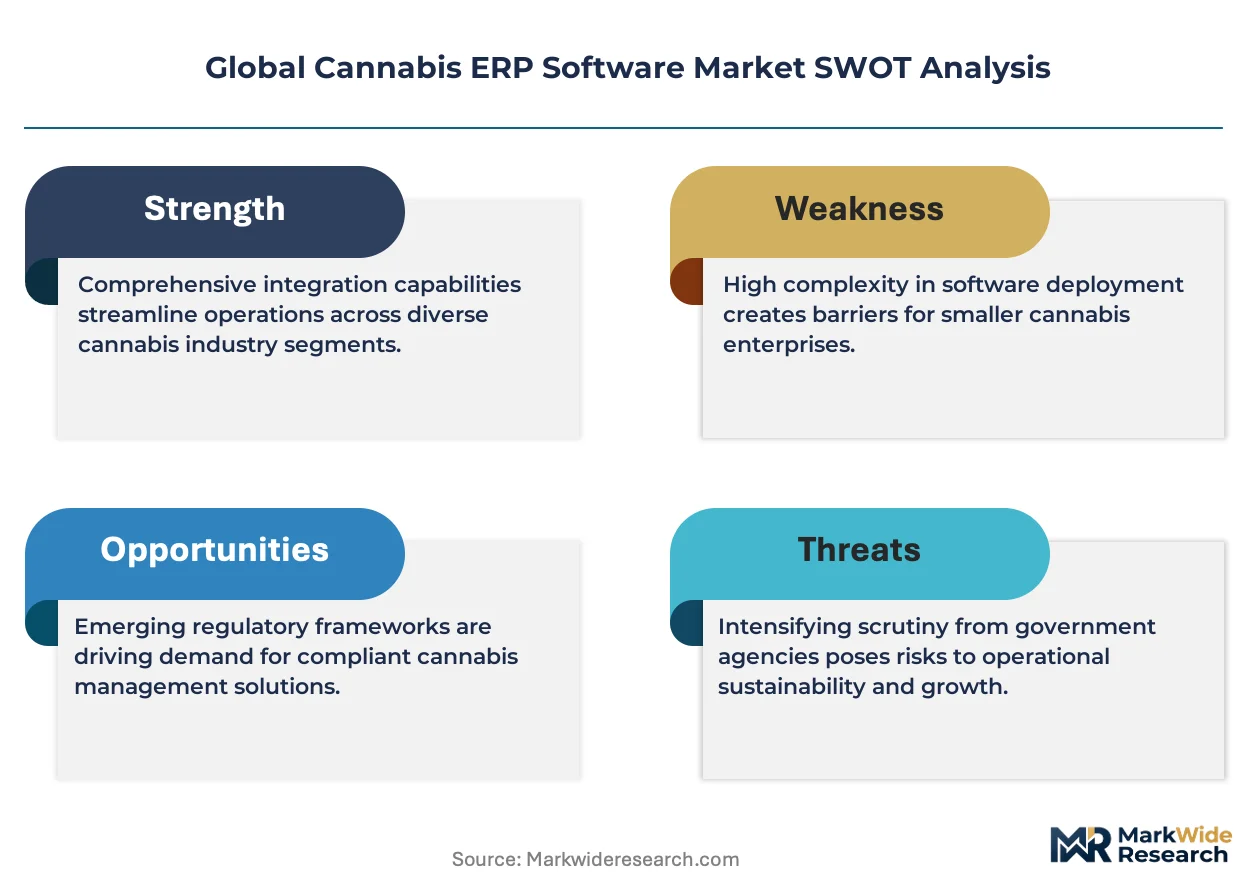
The United States FDA maintains oversight of cannabis-derived pharmaceuticals while the EPA governs pesticide applications on cultivated crops, creating dual compliance layers that ERP systems must accommodate. State-level regulators in Colorado, California, and Illinois impose distinct seed-to-sale reporting formats that force software vendors to maintain jurisdiction-specific module variants. Stakeholders must monitor evolving federal rescheduling discussions and their potential to standardize or fragment compliance requirements further.
Market Dynamics
State-level seed-to-sale tracking mandates in the United States are forcing licensed operators to abandon fragmented spreadsheets and manual compliance logs. This regulatory pressure is compressing replacement cycles for legacy point solutions and accelerating consolidation around integrated platform suites.
Growth Catalysts
- Batch-level inventory tracking:Cultivators in Colorado and California require plant-tag synchronization with state traceability portals. ERP vendors embedding direct API connections capture replacement demand from operators facing audit exposure.
- Cloud deployment models:Emerging multi-state dispensaries with limited IT staff favor SaaS architectures that remove infrastructure burdens. This delivery mode lowers barriers to entry for smaller operators entering newly legalized state markets.
- Dual-layer compliance requirements:The United States FDA oversees cannabis-derived pharmaceuticals while the EPA governs pesticide applications. ERP systems accommodating both regulatory streams attract pharmaceutical-grade cultivators seeking unified audit trails.
Market Restraints
- Jurisdiction-specific module variants:Software vendors must maintain separate reporting formats for Illinois, Colorado, and California seed-to-sale systems. This fragmentation elevates development costs and slows feature rollouts across customer bases.
- Federal scheduling uncertainty:Ongoing rescheduling discussions in the United States Congress create investment hesitation among operators fearing rapid compliance requirement changes. Capital deployment delays extend sales cycles for ERP providers.
- Technical debt in legacy systems:Early adopter operators built custom integrations with state traceability APIs that resist migration. Switching costs and data migration complexity protect incumbent point solutions despite functional limitations.
Strategic Opportunities
- Underpenetrated state markets:Newly legalized jurisdictions in the United States Midwest and Southeast lack mature regulatory frameworks. Vendors establishing early compliance module templates capture operator relationships before competitive consolidation.
- Financial module convergence:Integration of cannabis-specific tax calculations and banking compliance workflows addresses a critical pain point. Operators currently patch together separate accounting and inventory systems.
- EU regulatory preparation:Germany's evolving cannabis legalization framework and Health Canada's established track-and-trace requirements create export-ready compliance templates. Vendors building multi-jurisdictional modules position for cross-border operator expansion.
Industry Challenges
- Cannabis-specific accounting expertise scarcity:ERP implementation partners with knowledge of Section 280E tax constraints and cash-handling compliance remain concentrated in legacy state markets. This talent gap prolongs deployment timelines and elevates professional services costs.
- API stability with state systems:Traceability portal downtime and unannounced format changes in California and Colorado disrupt real-time inventory synchronization. Vendors must maintain rapid-response engineering teams to preserve customer operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cannabis ERP Software Market |
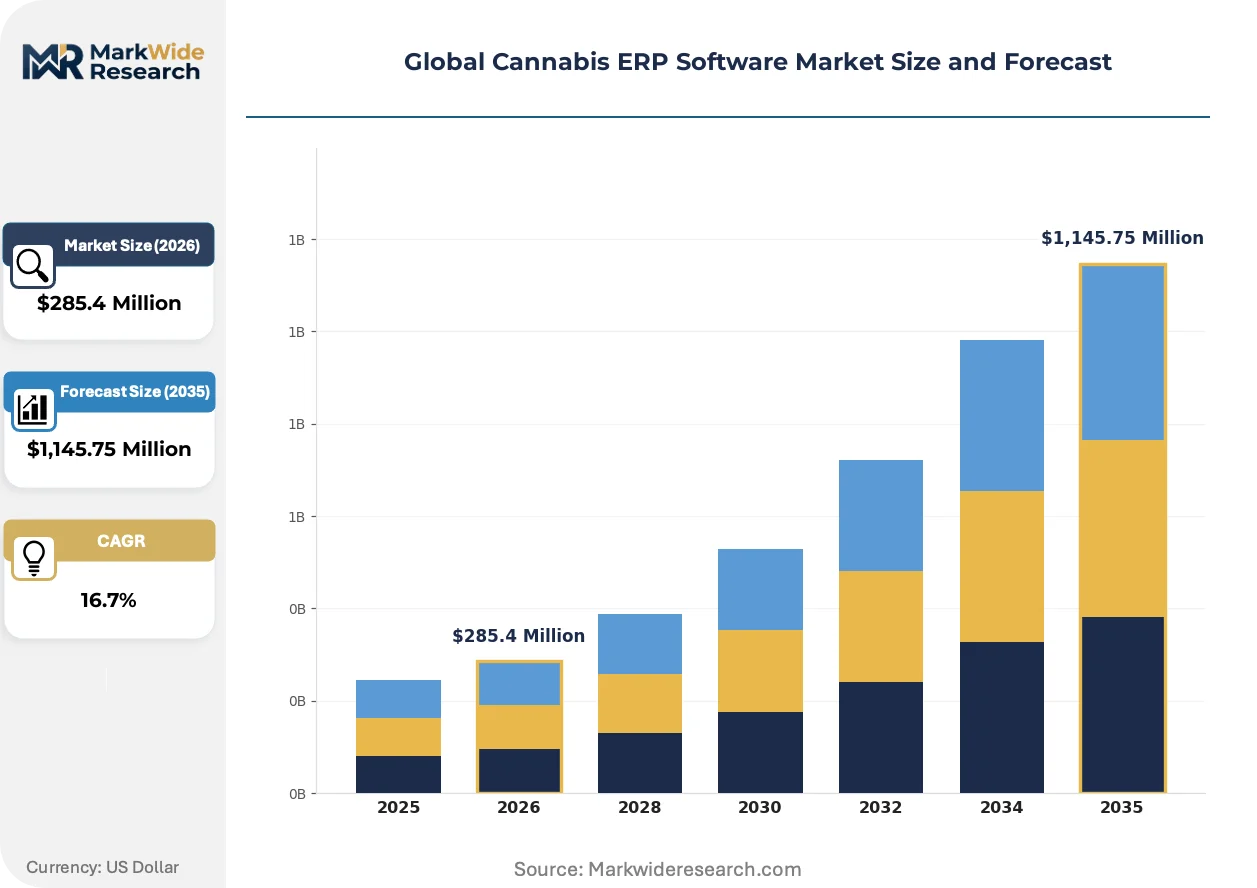
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,145.75 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Private Cloud Solution Type: Inventory Management, Supply Chain Management, Financial Management, Compliance Tracking, Customer Relationship Management End User: Cultivators, Processors, Distributors, Dispensaries, Testing Laboratories Application: Seed-to-Sale Tracking, Regulatory Reporting, Quality Assurance, Billing & Invoicing, Procurement Management |
| Companies Covered | BioTrackTHC, MJ Freeway, Leaf Logix, Wherefour, Flourish Software, Canix, Acumatica, 365 Cannabis, CannaBusiness ERP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cannabis ERP Software Market Shifts & Advancements
Artificial intelligence and machine learning capabilities are embedding into compliance and forecasting modules, reshaping how operators anticipate regulatory exposure and optimize cultivation cycles. These technologies are compressing the gap between raw operational data and actionable intelligence.
Machine learning algorithms trained on historical compliance violation patterns are expanding into predictive audit risk scoring. Multi-facility cultivators in California and Colorado deploy these tools to prioritize inspection preparation across dispersed operations. The technology is compressing manual compliance review cycles from weeks to hours.
Health Canada's cannabis tracking system and Germany's emerging regulatory framework are mandating standardized data exchange formats that diverge from United States state-level approaches. ERP vendors must architect modular compliance engines capable of rapid jurisdiction reconfiguration. European pharmaceutical-grade cultivators are driving demand for systems accommodating both GMP and seed-to-sale requirements simultaneously.
Buyer concentration among multi-state operators is consolidating vendor relationships around platforms demonstrating proven cross-jurisdictional scalability. Procurement committees now prioritize API reliability and state-specific module depth over generic feature breadth. This pattern is most visible in Illinois and Massachusetts, where vertically integrated license holders command disproportionate platform investment budgets.
Global Cannabis ERP Software Market Segmentation
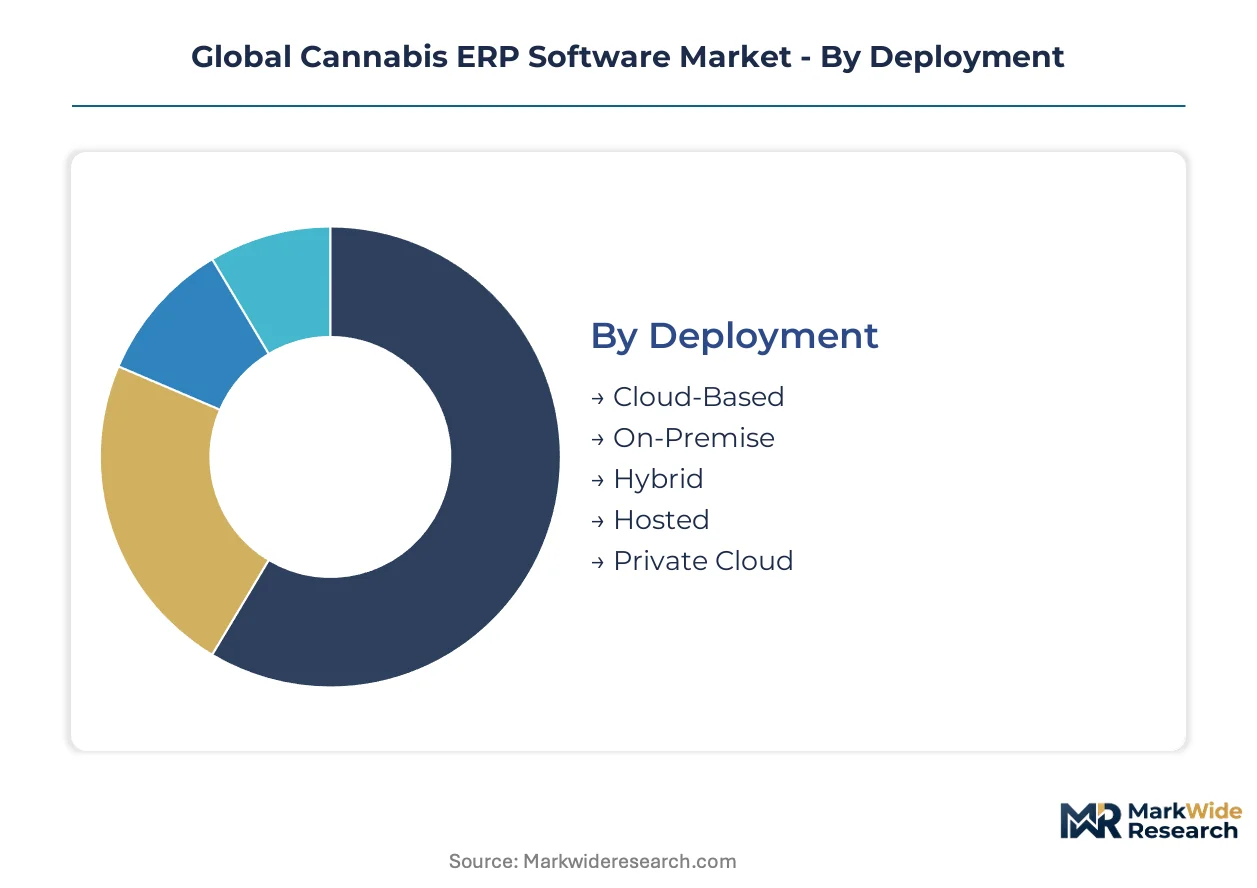
Cannabis ERP software segmentation reflects how operators balance regulatory compliance depth against IT infrastructure constraints. Deployment choices determine integration architecture, while solution types and end-user categories reveal where compliance failure costs concentrate procurement decisions.
Deployment:
Integration depth varies sharply across deployment modes, with standalone cloud offerings serving emerging operators while hybrid and private cloud configurations embed within enterprise technology stacks.
- Cloud-Based:Multi-tenant SaaS architectures remove server maintenance burdens from dispensaries and small cultivators with minimal IT staff. Demand concentrates in newly legalized United States state markets where operators prioritize rapid deployment over customization flexibility. Colorado and Illinois operators favor this mode for its automatic compliance module updates.
- On-Premise:Licensed servers within facility data centers provide maximum control over seed-to-sale data residency. Large multi-state operators in California and Massachusetts select this architecture to satisfy internal audit protocols and reduce third-party data exposure risks.
- Hybrid:Split configurations maintain sensitive compliance data on local infrastructure while pushing analytics workloads to cloud environments. Processors with complex manufacturing workflows deploy this model to balance regulatory data sovereignty against computational scalability.
- Hosted:Dedicated single-tenant cloud instances offer isolated environments without capital hardware investment. Mid-tier distributors in Florida and Pennsylvania favor this middle-ground approach for its compliance-ready isolation.
- Private Cloud:Virtualized infrastructure operated by third-party specialists delivers cloud elasticity with enhanced security boundaries. Pharmaceutical-grade cultivators seeking FDA-aligned data integrity protocols drive adoption in Canada and Germany.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to Hybrid configurations as multi-state operators seek architectural flexibility.
Solution Type:
Cost tier stratification separates mandatory compliance modules from discretionary operational tools, with inventory and compliance functions commanding premium pricing due to penalty exposure.
- Inventory Management:Batch-level tracking with plant-tag synchronization forms the technical core of seed-to-sale compliance. Cultivators in California and Colorado require real-time state portal integration, making this module non-negotiable for license maintenance.
- Compliance Tracking:Automated audit trails and jurisdiction-specific reporting formats address the highest failure-cost function in cannabis operations. State mandate variations between Illinois, Massachusetts, and Michigan force vendors to maintain parallel module variants.
- Supply Chain Management:Procurement and distribution coordination tools reduce operational leakage across vertically integrated license holders. Distributors in Florida leverage these capabilities to manage multi-facility product flows.
- Financial Management:Cannabis-specific tax calculations incorporating Section 280E constraints and cash-handling compliance. Dispensaries in Colorado and Washington deploy these modules to replace patched-together accounting systems.
- Customer Relationship Management:Patient and consumer engagement tools with purchase history tracking and loyalty program management. Adult-use dispensaries in Illinois and Arizona prioritize these capabilities for competitive differentiation.
Revenue concentration sits with Inventory Management; Compliance Tracking is climbing the fastest as state mandate complexity deepens.
End User:
Application intensity diverges by operational stage, with cultivation and retail endpoints facing direct state traceability interface requirements that processors and distributors encounter indirectly.
- Cultivators:Plant-tag generation, growth phase tracking, and harvest batch management constitute the most regulated operational stage. Indoor and greenhouse operators in California and Colorado drive module sophistication through environmental sensor integration demands.
- Dispensaries:Point-of-sale integration with real-time inventory depletion and patient verification workflows. Adult-use and medical retailers in Illinois and Massachusetts require split regulatory handling within unified transaction flows.
- Processors:Extraction and manufacturing workflow tracking with potency testing integration. Concentrate and edible manufacturers in Colorado deploy these capabilities to satisfy batch-specific testing mandate chains.
- Distributors:Third-party logistics coordination with transport manifest generation and chain-of-custody documentation. California's distributor mandate model creates concentrated demand for specialized compliance modules.
- Testing Laboratories:Sample intake tracking, results reporting, and certificate-of-analysis generation with state portal submission. Independent labs in Colorado and Oregon require LIMS-ERP integration for regulatory data integrity.
Platform investment intensity peaks among Cultivators; Dispensaries are gaining share fastest as retail license issuance accelerates across United States state markets.
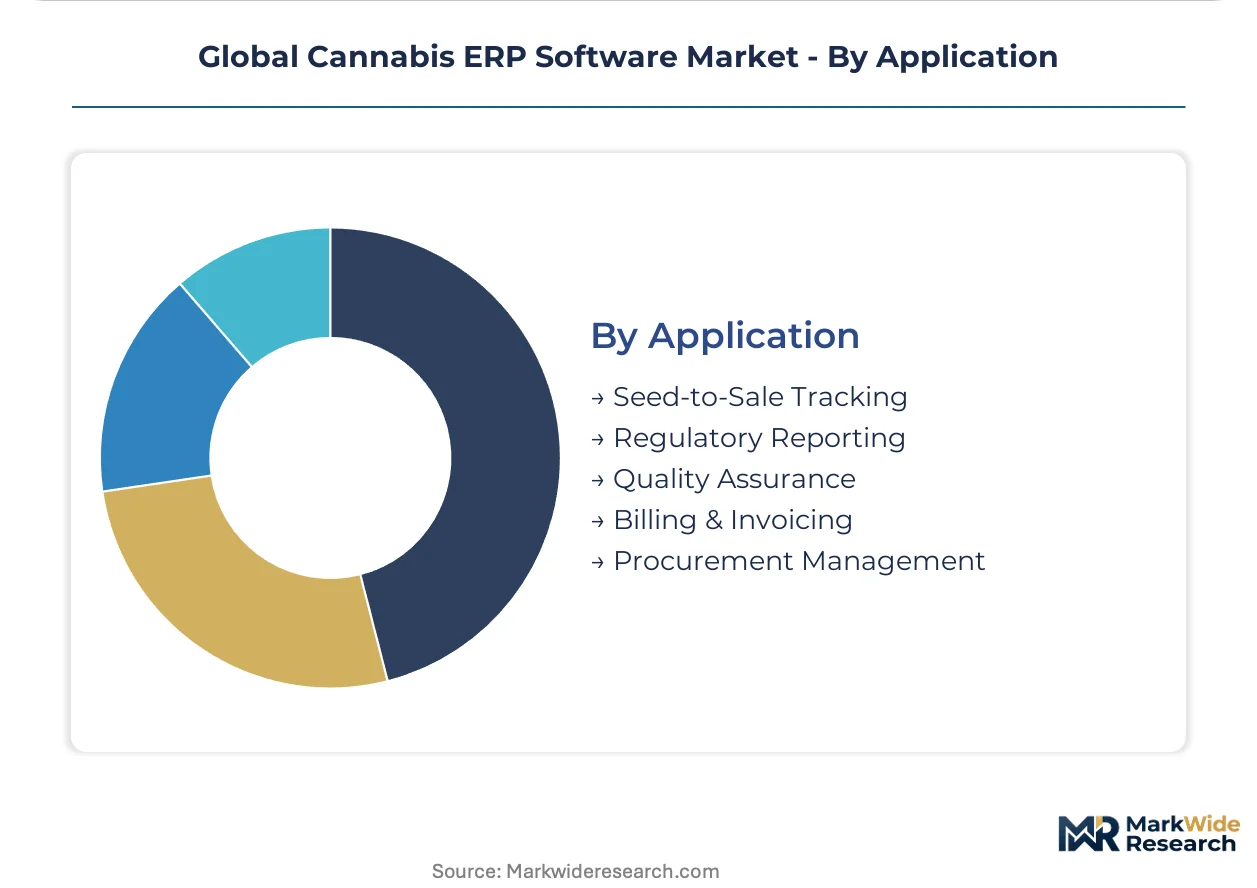
Application:
Maturity gradients separate foundational seed-to-sale functions from emerging quality and procurement capabilities that operators add as operational scale permits.
- Seed-to-Sale Tracking:The mandatory compliance backbone encompassing plant registration, growth monitoring, harvest batching, and final disposition recording. Every licensed operator in Colorado, California, and Illinois must maintain this capability for license continuity.
- Regulatory Reporting:Automated submission formatting for state traceability portals with violation flagging and correction workflows. Multi-state operators prioritize this function to reduce audit preparation labor across dispersed facilities.
- Quality Assurance:Testing result integration, deviation tracking, and corrective action documentation. Pharmaceutical-grade cultivators in Canada and Germany demand GMP-aligned capabilities exceeding baseline seed-to-sale requirements.
- Billing & Invoicing:Cannabis-specific tax calculation and cash-handling documentation for regulatory examination. Dispensaries in cash-restricted banking environments deploy these tools for audit-ready transaction records.
- Procurement Management:Supplier qualification, purchase order tracking, and receiving verification with compliance documentation attachment. Vertically integrated operators in Massachusetts use this capability to manage intra-company supply transfers.
Functional penetration is deepest in Seed-to-Sale Tracking; Quality Assurance is expanding most quickly as pharmaceutical-grade cultivation standards spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for cannabis cultivation in Colorado and California have concentrated ERP vendor development resources. State-level tax incentives for compliant technology adoption accelerate platform deployment timelines. Multi-state operators leverage these zones to standardize inventory management across facilities.
United States
Licensed cultivators in Colorado and Illinois face distinct seed-to-sale reporting formats that force ERP vendors to maintain parallel compliance modules. The FDA oversees pharmaceutical-grade cannabis derivatives while the EPA governs pesticide applications, creating dual regulatory layers. Denver and Chicago anchor the highest concentration of multi-facility operators demanding cross-jurisdictional platform scalability.
Canada
Health Canada's cannabis tracking system mandates standardized data exchange formats that diverge from United States approaches. ERP vendors architect modular compliance engines capable of rapid jurisdiction reconfiguration for export-ready operators. Ontario and British Columbia host pharmaceutical-grade cultivators demanding simultaneous GMP and seed-to-sale system accommodation.
Germany
Evolving cannabis legalization frameworks create demand for compliance templates that anticipate standardized federal requirements. German operators seek ERP systems capable of integrating with both domestic track-and-trace mandates and EU pharmaceutical regulations. Berlin and North Rhine-Westphalia concentrate early-adopter dispensary chains preparing for adult-use market expansion.
Australia
The Therapeutic Goods Administration (TGA) oversees medicinal cannabis licensing with strict batch-level documentation requirements. ERP platforms serving Australian operators emphasize laboratory information management system integration for testing workflow compliance. New South Wales and Victoria host the majority of licensed producers investing in automated regulatory reporting infrastructure.
Netherlands
Established coffee shop supply chain regulations create unique wholesale tracking requirements distinct from full legalization markets. Dutch ERP vendors specialize in closed-loop inventory systems serving government-contracted cultivators. The Randstad region concentrates technology providers developing compliance modules for pilot adult-use programs anticipated in national policy discussions.
Global Cannabis ERP Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the cannabis ERP landscape. The vendor base stratifies between established seed-to-sale platforms and enterprise software incumbents adapting general modules for industry-specific compliance. Three archetypes dominate: state-traceability-integrated specialists, multi-vertical ERP extenders, and cultivator-focused workflow optimizers. Competitive moves concentrate on API reliability investments and jurisdiction-specific module depth expansion.
Among state-traceability-integrated specialists, Flourish Software and BioTrackTHC exemplify platforms anchoring their positions through deep compliance module development. MJ Freeway occupies a position emphasizing geographic coverage across diverse regulatory environments. These three represent the dominant competitive vectors: integration depth, regulatory breadth, and workflow specialization respectively.
| Leading Market Players |
|---|
| BioTrackTHC |
| MJ Freeway |
| Leaf Logix |
| Wherefour |
| Flourish Software |
| Canix |
| Acumatica |
| 365 Cannabis |
| CannaBusiness ERP |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up ERP specialists in Colorado and California anchor supply concentration while enforcing pricing discipline through recurring-revenue lock-in and compliance-module bundling. Their ownership structures prioritize predictable cash flows over volume growth, compressing competitive pricing latitude for emerging vendors seeking market entry.
Pricing Analysis
Cost-down pressure on mid-tier SaaS deployments accelerates because multi-state operators consolidate vendor relationships around proven cross-jurisdictional platforms. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation hinging on state traceability API depth and financial module integration. Price differentiation traces to customization level and after-sales service intensity. Dispensaries in newly legalized Midwest states exhibit highest price sensitivity; pharmaceutical-grade cultivators in Canada and Germany demonstrate lowest sensitivity due to GMP-aligned requirements.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate vendor participation in enterprise procurement cycles, filtering development-stage providers from multi-state operator shortlists. Engineering talent concentrates in the United States, Canada, and Germany, with cloud infrastructure provisioning resting on hyperscaler partnerships with AWS, Azure, and Google Cloud. Single-source vulnerability sits with state traceability API stability, where unannounced format changes in California and Colorado disrupt real-time synchronization. Distribution runs through direct sales teams serving cultivation clusters and channel partners penetrating dispensary networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in cannabis-specific accounting expertise prop pricing power for implementation partners, creating durable margin pools for vendors controlling certified deployment capacity.
For Market Incumbents: Cement API reliability leadership through rapid-response engineering teams dedicated to California and Colorado state portal stability. Deepen vertical integration into financial module development to capture accounting workflow consolidation demand. Regulatory fragmentation across Illinois, Massachusetts, and Michigan seed-to-sale formats presents both defensive moat-building opportunity and feature rollout complexity threat.
For New Entrants and Emerging Players: Cloud-native compliance templates for newly legalized Southeast United States states offer lowest competitive density entry path. Target underpenetrated distributor and testing laboratory segments where incumbent platform saturation remains lowest. Partner with state regulatory consultants to accelerate compliance module certification timelines ahead of license issuance waves.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid-deployment-capable vendors with Health Canada and Germany regulatory module readiness. Long-term viability centers on cross-jurisdictional scalability rather than single-state dominance. Monitor FDA rescheduling discussions as inflection signal for compliance requirement standardization or further fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| State Traceability API Integration | Direct portal connectivity in Colorado and California reduces audit exposure for multi-facility operators. |
| Financial Module Convergence | Section 280E tax automation addresses critical pain point for cash-restricted dispensary banking compliance. |
| EU Regulatory Module Development | Germany's emerging framework and Health Canada alignment position vendors for export-ready operator expansion. |
| Machine Learning Compliance Embedding | Predictive audit risk scoring compresses manual review cycles from weeks to hours for California cultivators. |
| Hybrid Deployment Architecture | Split configurations balance regulatory data sovereignty against computational scalability for Massachusetts processors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with ERP implementation partners, state compliance officers, multi-state operator CTOs, and cannabis-specific accounting specialists combined with secondary validation from FDA guidance documents, state seed-to-sale mandate texts, and Health Canada tracking system specifications. Bottom-up deployment counts and top-down vendor revenue estimates underwent triangulation to converge market sizing.
Reconciliation across license issuance databases, facility count surveys, and platform penetration studies informed the analytical framework across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, end-user category, and jurisdictional regulatory maturity. CAGRs derived from license growth trajectories, state legalization timelines, and replacement cycle compression patterns in legacy point solution bases.
The model holds under continued state-level regulatory fragmentation; deviation toward federal rescheduling standardization would shift compliance module development economics. Forecasts reflect assumptions regarding API stability, license issuance velocity, and accounting talent availability. A model refresh is warranted upon material change in FDA scheduling determination or Health Canada data exchange format revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Cannabinoid CB2 Products Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
Global Cannabis Market