
 Cannabidiol (CBD) Market | 2026-2036
Cannabidiol (CBD) Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabidiol (CBD) Market Analysis
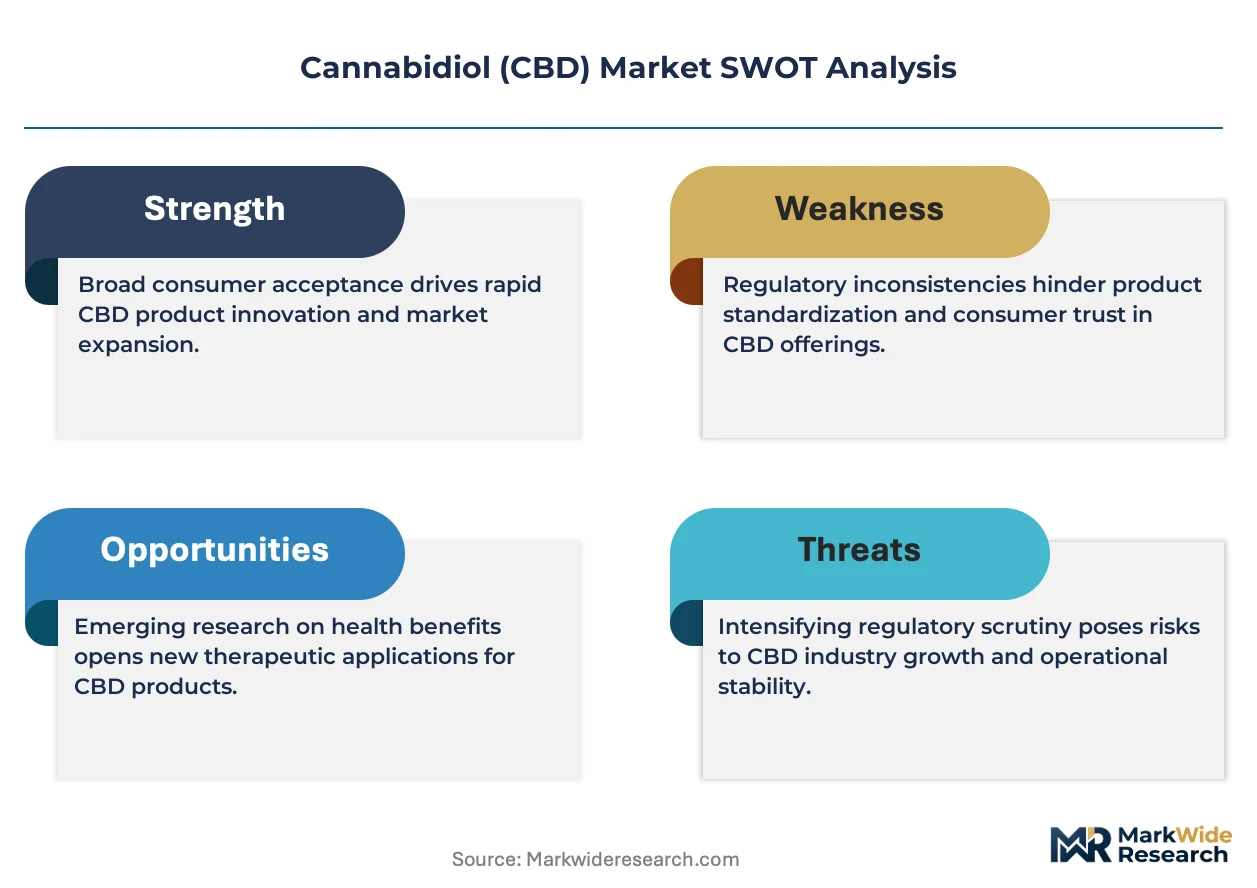
Buyer concentration among wellness centers and healthcare providers is hardening as institutional procurement replaces fragmented consumer purchasing. Charlotte's Web leverages its seed-to-shelf vertical integration to secure pharmacy shelf space. Medterra anchors its position through third-party certification and U.S. hemp sourcing controls. Lazarus Naturals competes on accessibility via direct-to-patient assistance programs and bulk formulations.
Cannabidiol denotes a non-psychoactive phytocannabinoid extracted primarily from hemp cultivars containing less than 0.3% THC by dry weight, typically isolated through CO2 or ethanol extraction for use in therapeutic and wellness formulations. Oils and tinctures occupy the dominant product position due to dosing precision and bioavailability advantages, while edibles represent the fastest-expanding category as food-grade formulation standards mature. Pain relief and anxiety reduction command the largest application share, though skincare applications are gaining traction among dermatology clinics seeking non-steroidal topical alternatives.
The FDA maintains a restrictive stance on CBD in dietary supplements and food products, creating compliance bottlenecks that favor companies with dedicated regulatory affairs capacity. EFSA's ongoing novel food assessment process in Europe similarly constrains market entry for unvalidated applications. State-level hemp programs and the 2018 Farm Bill framework provide partial operational clarity in the United States, though interstate commerce remains legally contested. Stakeholders must monitor enforcement priority shifts and novel food authorization timelines to calibrate inventory and geographic expansion decisions.
Market Dynamics
Institutional procurement from wellness centers and healthcare providers is displacing fragmented consumer purchasing, forcing manufacturers to build regulatory affairs capacity and pharmacy-grade certification to secure shelf space.
Growth Catalysts
- FDA pathway uncertainty:The FDA's 2023 decision to defer CBD rulemaking to Congress has triggered state-level hemp program expansions in Colorado and Oregon, creating operational clarity for interstate distributors.
- Germany's cannabis liberalization:The CanG law permits non-prescription cannabis products, opening pharmacy channels for CBD oils and topicals previously restricted to specialty retailers.
- Nanoemulsion technology:Lipid-based delivery systems are improving bioavailability in beverage formulations, attracting functional drink manufacturers seeking water-compatible CBD inputs.
Market Restraints
- EFSA novel food deadlock:The European Food Safety Authority's suspended CBD assessment blocks ingestible product authorization across EU member states, freezing brand expansion.
- Hemp biomass price volatility:Weather-driven crop failures in Kentucky and Tennessee are compressing processor margins and triggering supply contract renegotiations.
- THC contamination risk:Hot crop incidents exceeding 0.3% THC thresholds force destruction of entire harvests, exposing cultivators to catastrophic inventory losses.
Strategic Opportunities
- United Kingdom FSA validation:The Food Standards Agency's pending novel food approvals for synthetic CBD isolate could unlock mass-market retail distribution ahead of EU competitors.
- Dermatology clinic channels:Prescription-grade topicals for eczema and psoriasis represent an underserved indication with reimbursement potential in Switzerland and Australia.
- Direct-to-patient subscription models:Telehealth platforms are creating recurring revenue streams bypassing traditional retail markups in California and Florida.
Industry Challenges
- Analytical chemist shortage:Third-party laboratories face 8-12 week backlogs for potency and contaminant testing, delaying product release schedules.
- Batch record compliance:Current Good Manufacturing Practice documentation requirements for pharmacy listings demand capital investment in ERP systems many mid-tier processors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabidiol (CBD) Market |
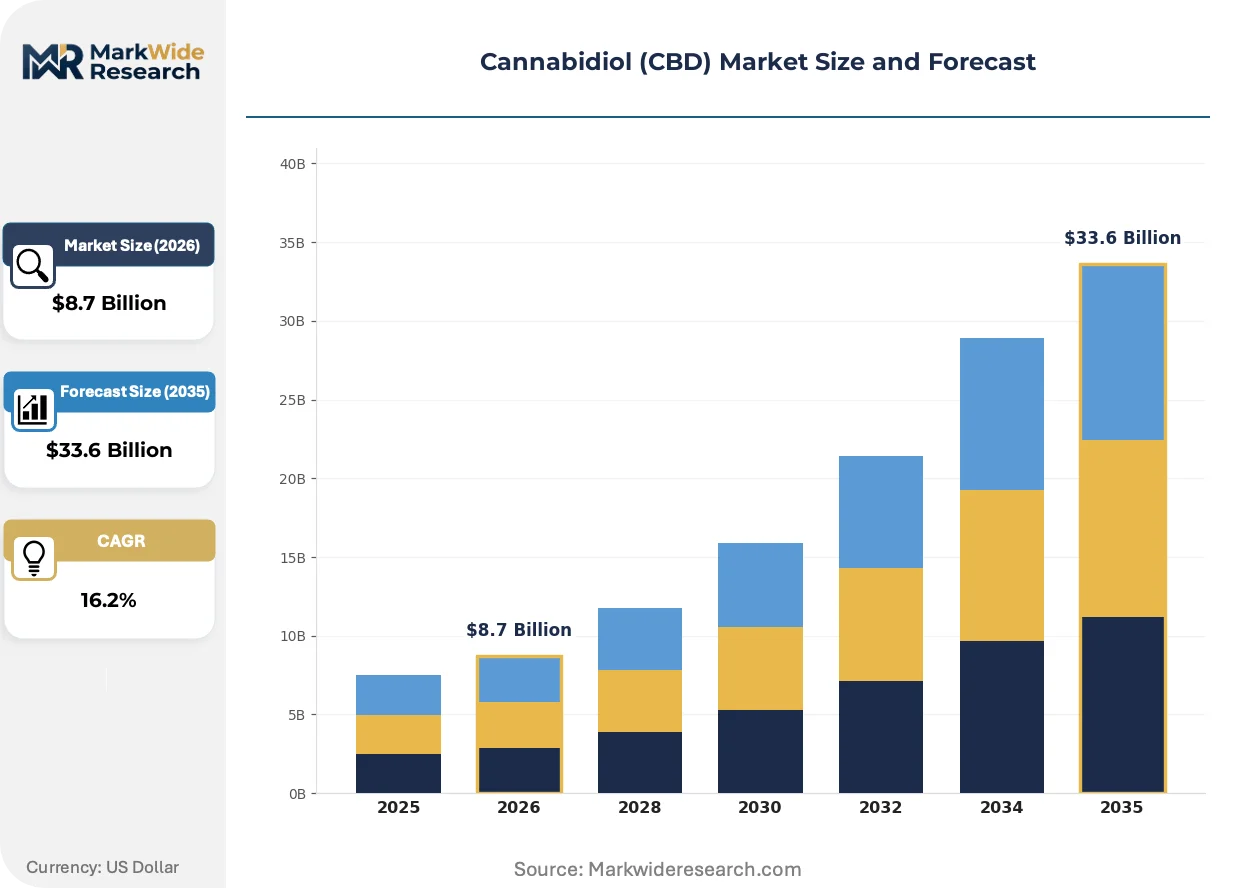
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $33.6 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Tinctures, Capsules, Edibles Application: Pain Relief, Anxiety Reduction, Sleep Aid, Skincare Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Health Stores End User: Consumers, Healthcare Providers, Wellness Centers, Retailers |
| Companies Covered | Charlotte’s Web, Medterra, CBD American Shaman, NuLeaf Naturals, Lazarus Naturals, CBDistillery, CV Sciences, CBDfx, Joy Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabidiol (CBD) Market Emerging Trajectories
Formulation science and distribution infrastructure are converging to reshape competitive positioning, with bioavailability engineering and regulatory compliance emerging as the primary axes of differentiation.
Nanoemulsion technology is electrifying beverage and functional food applications by converting lipophilic CBD into water-dispersible particles below 100 nanometers. CPG manufacturers in California and Colorado are integrating these inputs into sports drinks and ready-to-drink coffees at accelerating volumes. This platform is compressing the performance gap between ingestible and sublingual delivery routes, forcing tincture specialists to defend bioavailability claims with clinical data.
REACH compliance requirements for novel cosmetic ingredients are tightening documentation burdens for CBD skincare manufacturers seeking EU market access. The European Chemicals Agency's extended safety data set demands are extending product development timelines by 18-24 months. German and French formulators are responding by relocating pilot production to Switzerland to leverage Swissmedic's parallel track for botanical therapeutics.
Healthcare systems are consolidating CBD procurement through group purchasing organizations, replacing individual clinic purchasing with centralized formulary management. Hospital networks in Texas and Pennsylvania are negotiating direct supply agreements with GMP-certified processors, squeezing distributor margins. This concentration is most visible in pain management departments seeking standardized dosing protocols and batch traceability.
Cannabidiol (CBD) Market Segmentation
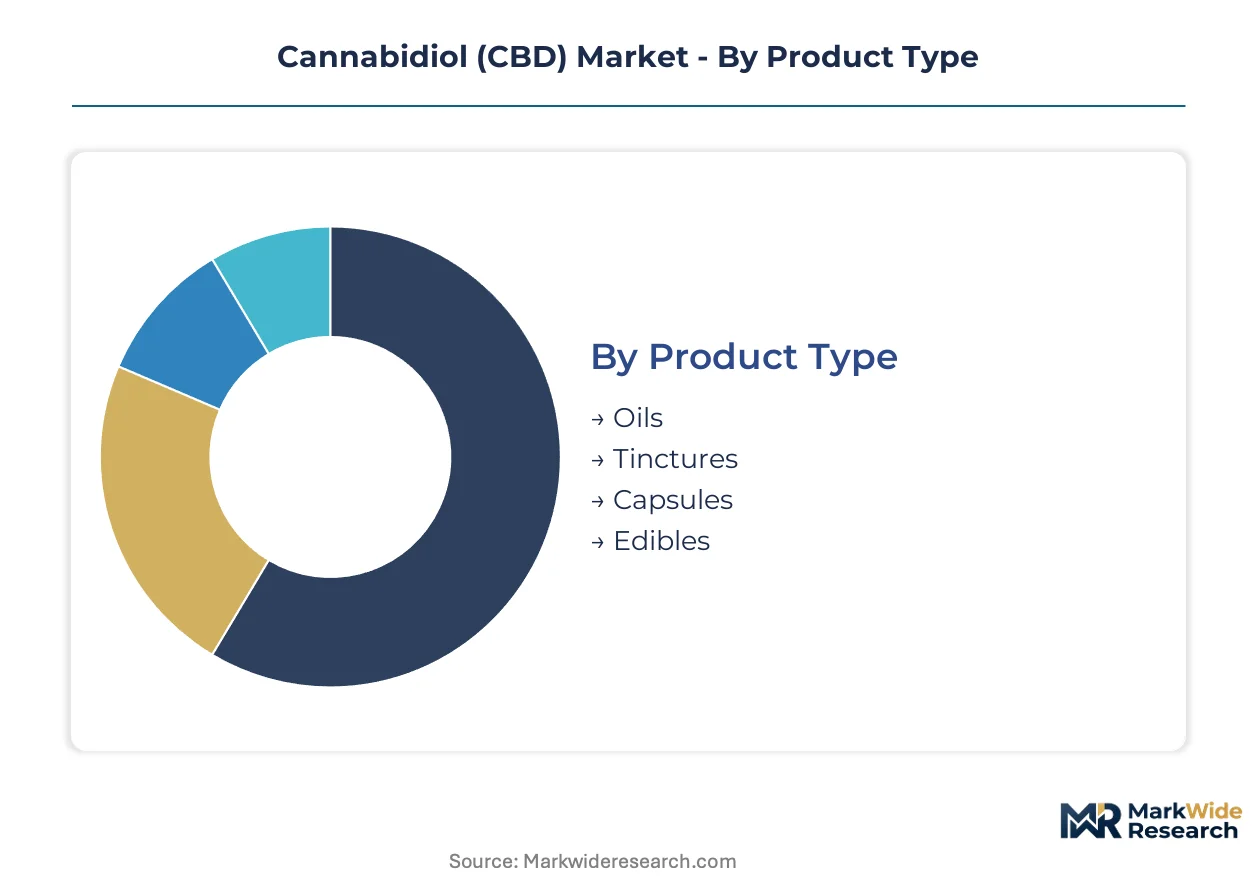
Product differentiation in the CBD market hinges on bioavailability engineering and dosing precision, with manufacturers competing across delivery formats that command distinct regulatory pathways and margin profiles. Segmentation reveals how formulation science and channel access determine competitive positioning across therapeutic and wellness applications.
Product Type:
Delivery technology dictates absorption rates, onset timing, and consumer compliance across oral and sublingual formats.
- Oils:Lipid-based suspensions typically formulated with MCT or hemp seed carrier oils enable sublingual absorption with 15-30 minute onset windows. Pain management clinics in Germany and wellness centers in California standardize procurement around CO2-extracted full-spectrum oils with documented terpene profiles.
- Edibles:Food-grade formulations including gummies and chocolates mask hemp-derived flavors while extending shelf stability through encapsulation. The UK's Food Standards Agency novel food queue is accelerating validation timelines for ingestible formats, attracting CPG manufacturers seeking mass-market retail placement.
- Tinctures:Alcohol or glycerin-based extracts with calibrated dropper dosing serve precision-focused consumers and compounding pharmacies.
- Capsules:Gelatin or vegetable-based shells deliver standardized milligram doses for healthcare providers requiring batch consistency and gastric release profiles.
Oils lead on scale; edibles lead on momentum.
Application:
Clinical validation depth and reimbursement potential vary sharply across therapeutic indications, shaping R&D allocation and regulatory strategy.
- Pain Relief:Topical and systemic formulations target nociceptive and neuropathic pain pathways, with hospital networks in Texas and Pennsylvania consolidating procurement through group purchasing organizations. Batch traceability and GMP documentation are non-negotiable for formulary inclusion.
- Skincare:Non-steroidal topicals for eczema and psoriasis are gaining traction among dermatology clinics in Switzerland and Australia seeking prescription-grade alternatives. REACH compliance requirements extend EU development timelines by 18-24 months.
- Anxiety Reduction:Sublingual oils and rapid-onset formulations target acute stress response modulation, with telehealth platforms in Florida and California driving direct-to-patient subscription growth.
- Sleep Aid:Melatonin-CBD combination products and CBN-enhanced formulations target circadian regulation, competing with established pharmaceutical sleep aids through natural positioning.
Pain relief leads on scale; skincare leads on momentum.
Distribution Channel:
Channel selection determines margin capture, regulatory burden, and customer acquisition economics across fragmented and consolidated retail formats.
- Pharmacies:Germany's CanG law has unlocked pharmacy channels for CBD oils and topicals previously restricted to specialty retailers, with Apotheken requiring novel food compliance or BfArM registration.
- Online Retail:Direct-to-consumer platforms bypass retail markups while navigating FDA enforcement discretion on health claims and state-level hemp program variations.
- Specialty Stores:CBD-dedicated retailers provide education-intensive purchasing environments, concentrating in Colorado and Oregon where state hemp programs offer operational clarity.
- Health Stores:Natural product retailers including Whole Foods and Sprouts face FDA restrictions on ingestible CBD, limiting assortment to topical formats in most jurisdictions.
Online retail leads on scale; pharmacies lead on momentum.
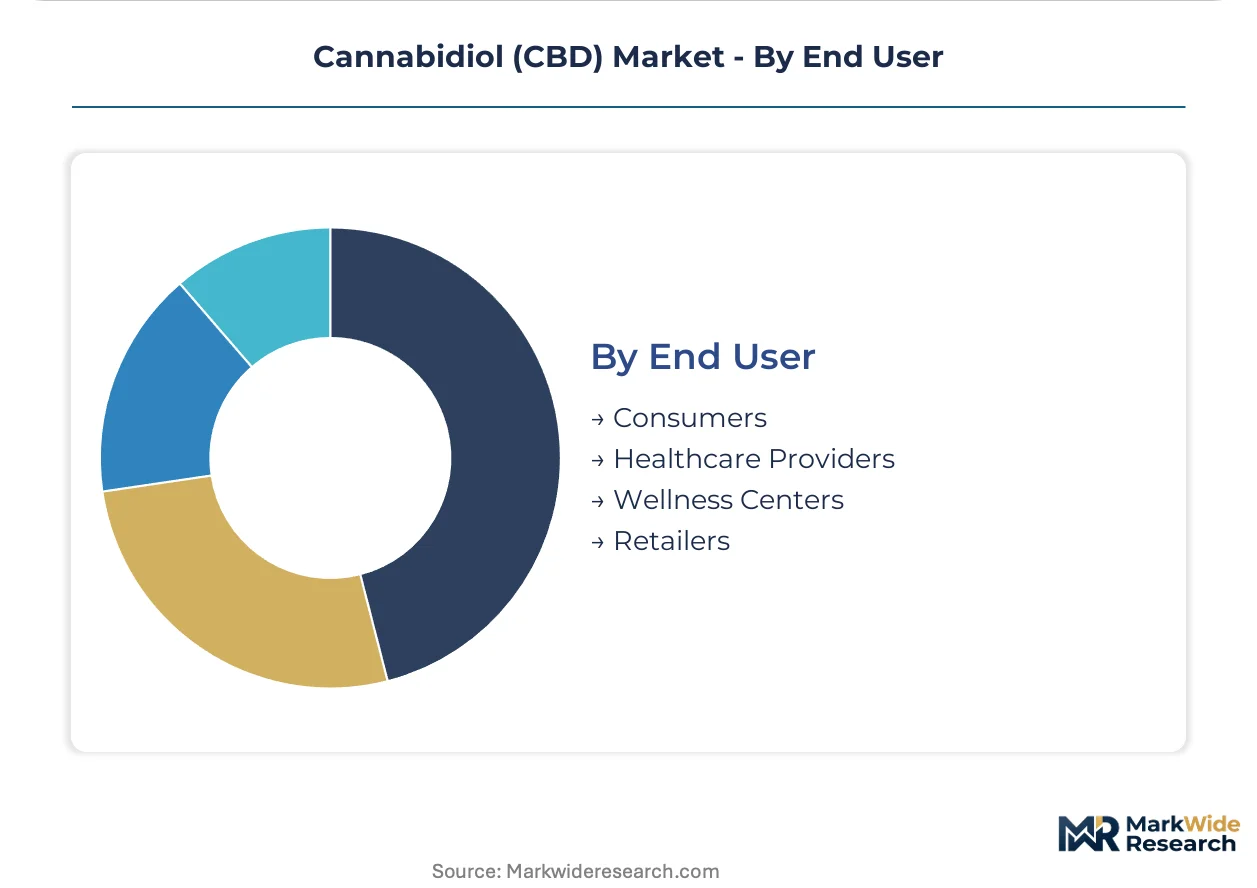
End User:
Procurement sophistication and volume concentration distinguish institutional buyers from fragmented consumer demand.
- Healthcare Providers:Hospital networks and pain management departments are consolidating purchasing through centralized formulary management, demanding GMP certification and standardized dosing protocols.
- Wellness Centers:Spa and integrative medicine clinics are expanding CBD procurement for anxiety reduction and recovery applications, replacing fragmented consumer purchasing with institutional contracts.
- Consumers:Individual purchasers drive trial and brand switching, with price sensitivity highest in online channels and lowest in pharmacy settings.
- Retailers:Distributors and private-label buyers source bulk inputs for house brand development, with margin pressure intensifying as processor capacity expands.
Healthcare providers lead on scale; wellness centers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemists and regulatory specialists concentrate in jurisdictions where hemp processing and pharmaceutical-grade extraction command premium wages. Talent clusters in Colorado, Kentucky, and Oregon in the United States, plus North Rhine-Westphalia and Bavaria in Germany, anchor operational scale.
United States
Wellness centers in California and pain management clinics in Texas drive institutional procurement growth. The FDA's 2023 deferral of CBD rulemaking to Congress triggered state-level hemp program expansions in Colorado and Oregon. Denver and Boulder host the densest concentration of CO2 extraction facilities and third-party testing laboratories.
Germany
Pharmacy channel expansion under the CanG law unlocks non-prescription CBD distribution previously restricted to specialty retailers. BfArM registration requirements and EFSA novel food assessments create compliance bottlenecks favoring established processors. North Rhine-Westphalia and Bavaria concentrate GMP-certified manufacturing infrastructure serving Apotheken networks.
United Kingdom
The Food Standards Agency's novel food validation queue accelerates approval timelines for synthetic CBD isolate, attracting CPG manufacturers seeking mass-market retail placement. Anxiety reduction applications drive wellness center procurement in London and Manchester. The Southeast England corridor clusters formulation science talent and contract manufacturing capacity.
Switzerland
Dermatology clinics in Zurich and Geneva seek prescription-grade topicals for eczema and psoriasis, creating reimbursement-adjacent demand. Swissmedic's parallel track for botanical therapeutics offers faster market access than EU REACH compliance routes. Basel anchors pharmaceutical-grade extraction and cosmetic formulation R&D.
Australia
Telehealth platforms in Sydney and Melbourne drive direct-to-patient subscription growth for anxiety and sleep applications. The TGA's down-scheduling of low-dose CBD enables pharmacy distribution without prescription requirements. Victoria and New South Wales concentrate compounding pharmacy infrastructure and clinical research capacity.
Cannabidiol (CBD) Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction, formulation, and distribution segments. The vendor base organizes into three tiers: seed-to-shelf vertically integrated operators, third-party certified GMP processors, and direct-to-consumer accessibility platforms. Strategic differentiation hinges on regulatory affairs capacity, pharmacy-grade certification, and bioavailability engineering. Competitive moves center on geographic licensing partnerships and capacity expansion into nanoemulsion technology.
Within the vertically integrated tier, Charlotte's Web anchors seed-to-shelf positioning through controlled hemp sourcing and pharmacy shelf space capture. Medterra exemplifies the certification-driven archetype via U.S. hemp sourcing controls and third-party validation protocols. Lazarus Naturals occupies the accessibility-focused position through direct-to-patient assistance programs and bulk formulation supply.
| Leading Market Players |
|---|
| Charlotte's Web |
| Medterra |
| CBD American Shaman |
| NuLeaf Naturals |
| Lazarus Naturals |
| CBDistillery |
| CV Sciences |
| CBDfx |
| Joy Organics |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between pharmacy-channel GMP products and unverified wellness SKUs creates divergent margin architectures that propagate backward into hemp sourcing and extraction investment decisions. Premium tiers command three-to-five-fold markups over commodity oils by tethering pricing to third-party validation and batch traceability, while price compression in direct-to-consumer channels forces mid-tier processors toward toll manufacturing arrangements.
Pricing Analysis
Capacity additions in Colorado and Kentucky are reshaping price floors for full-spectrum oils as processor competition intensifies. Three-tier pricing structure across pharmacy-certified, wellness-retail, and bulk-ingredient levels stratifies by GMP documentation depth and third-party testing rigor. Cost compression in the wellness tier stems from biomass oversupply and direct-to-consumer subscription proliferation. Healthcare providers exhibit lowest price sensitivity due to formulary standardization requirements, while online retail consumers drive aggressive discounting through comparison shopping.
Supply Chain Analysis
Regional distribution centers in Denver, Louisville, and Rotterdam anchor hub-and-spoke patterns for finished goods, with cold-chain requirements for nanoemulsion concentrates adding complexity. Hemp cultivation concentrates in the United States, China, and Romania, with extraction capacity clustering in Colorado, Kentucky, and Oregon. Processor margins hinge on CO2 equipment utilization rates and hemp biomass contract structures. Single-source vulnerability runs through third-party testing laboratory backlogs, which currently delay product release by 8-12 weeks. Distribution runs through pharmacy wholesalers in Germany, direct-to-consumer platforms in California and Florida, and specialty retailers in Colorado and Oregon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory clarity in Germany and the United Kingdom enables premium pricing unavailable in enforcement-ambiguous US jurisdictions, rewarding early movers who secure novel food validation or BfArM registration ahead of competitors.
For Market Incumbents: To counter margin erosion from toll-manufacturing commoditization, anchor defensibility through captive hemp sourcing in Kentucky and Tennessee coupled with ERP system investments that satisfy pharmacy-grade batch record requirements. Prioritize nanoemulsion capacity additions in Colorado to capture functional beverage formulation demand before ingredient suppliers consolidate.For New Entrants and Emerging Players: Telehealth platform partnerships offer the most penetrable channel for anxiety-reduction subscription models, bypassing retail markup compression and FDA enforcement discretion on health claims. Target dermatology clinic white space in Switzerland and Australia where prescription-grade topical demand outpaces GMP-certified supply. Pursue synthetic CBD isolate positioning ahead of UK FSA validation timelines to secure mass-market retail placement.
For Investors and Strategic Acquirers: Consolidation pressure builds where analytical chemist scarcity and 8-12 week testing backlogs constrain mid-tier processor throughput, creating acquisition opportunities for GMP-certified operators with in-house laboratory capacity. Long-term viability favors vertically integrated seed-to-shelf models with pharmacy channel access over pure-play extraction specialists exposed to biomass price volatility. Watch EFSA novel food assessment resumption as the critical inflection signal for EU market reopening.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Expansion | Germany's CanG law unlocks Apotheken distribution previously restricted to specialty retailers. |
| Nanoemulsion Technology Investment | Lipid-based delivery systems enable water-compatible CBD inputs for functional beverage manufacturers. |
| Third-Party Certification Acquisition | USP or NSF validation differentiates pharmacy-grade products from unverified wellness SKUs. |
| Direct-to-Patient Subscription Launch | Telehealth platforms in California and Florida create recurring revenue streams bypassing retail markups. |
| Synthetic CBD Isolate Positioning | UK FSA novel food queue acceleration enables mass-market retail placement ahead of EU competitors. |
Methodological Framework
Coverage spans the United States, Germany, the United Kingdom, and Switzerland, with primary inputs from each market's regulatory cluster. The research combines structured interviews with extraction facility operators, pharmacy procurement managers, regulatory affairs specialists, and wellness center directors with secondary validation from FDA enforcement discretion records, EFSA novel food assessment documentation, BfArM registration databases, and state-level hemp program filings. Bottom-up volume estimates from processor capacity utilization triangulate against top-down demand projections from healthcare formulary adoption and consumer channel shipment data.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models segmentation dimensions including product type (oils, edibles, tinctures, capsules), application (pain relief, skincare, anxiety reduction, sleep aid), distribution channel (pharmacies, online retail, specialty stores, health stores), and end user (healthcare providers, wellness centers, consumers, retailers). CAGRs derive from regression analysis of historical adoption curves calibrated to regulatory pathway clarity and channel access expansion. Industry-specific forecast inputs include hemp biomass yield volatility and novel food authorization timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA congressional delegation resolution, EFSA assessment resumption, and THC contamination incident frequency. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and state hemp program stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Synthetic Cannabinoids Market
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Germany and Netherlands Medical Marijuana Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
Cannabinoids Market