
 United States Health and Medical Insurance Market | 2026-2036
United States Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
United States Health and Medical Insurance Market Analytics
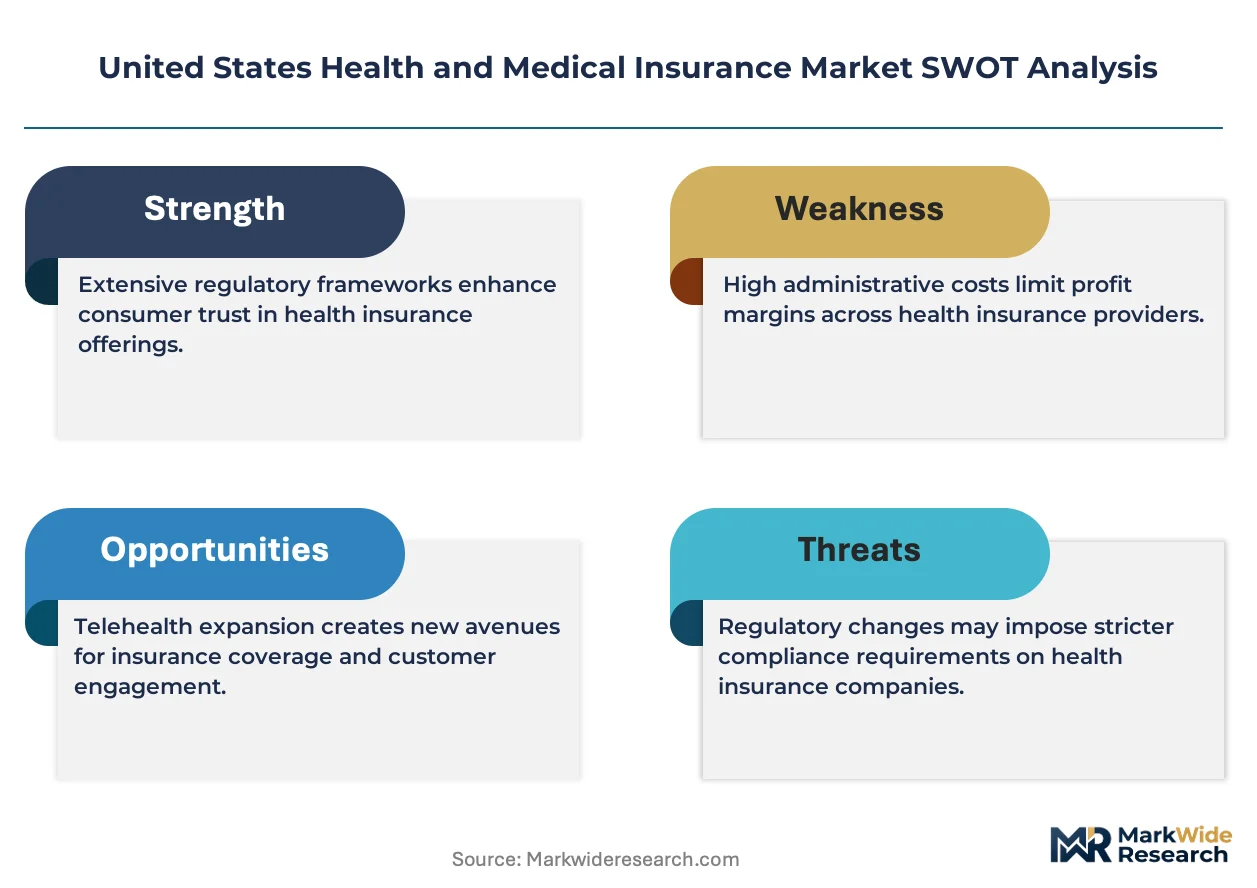
Actuarial talent scarcity is redrawing competitive boundaries across the sector. UnitedHealth Group leverages its Optum analytics division to sustain predictive modeling capabilities that lower medical loss ratios. Elevance Health anchors its growth through state-level Medicaid contracts and Medicare Advantage geographic dominance. CVS Health competes by integrating retail pharmacy footprints with Aetna's insurance infrastructure, creating channel control that smaller rivals struggle to replicate.
Health and medical insurance constitutes a risk-pooling financial instrument where carriers collect premiums to fund beneficiary medical expenditures under defined benefit structures. Policies specify actuarial value, network adequacy requirements, and cost-sharing parameters that determine out-of-pocket exposure for covered services. Managed care plans lead enrollment volume by restricting beneficiaries to contracted provider networks in exchange for lower premiums. High Deductible plans represent the fastest-growing service model as employers shift cost exposure to workers. Individual Plans command premium pricing per beneficiary but remain a smaller pool than Group Coverage, where administrative efficiency and scale economics concentrate margin pools.
CMS administers Medicare and Medicaid programs that shape reimbursement benchmarks and compliance obligations for participating carriers. State insurance commissioners enforce reserve requirements, network adequacy standards, and rate review processes that constrain pricing flexibility. HIPAA portability rules and the Affordable Care Act's essential health benefits mandate define minimum coverage parameters that standardize product design across state markets. Stakeholders must monitor state waiver applications and CMS innovation center pilots that could restructure payment models and competitive positioning without congressional action.
Market Dynamics
Employer-sponsored group coverage expansion is redrawing competitive boundaries as businesses weaponize benefits packages to attract talent in tight labor markets across California, Texas, and Florida.
Growth Catalysts
- Medicaid Expansion Provisions:State-level Medicaid expansion under the Affordable Care Act is pulling millions of uninsured Americans into managed care plans, creating new enrollment pools for regional carriers.
- Telehealth Infrastructure:Remote care delivery platforms are extending network reach into rural counties previously deemed unprofitable for traditional provider contracting.
- High Deductible Health Plans:Employer cost-shifting is accelerating adoption of consumer-directed coverage models that lower premium exposure while maintaining catastrophic protection.
Market Restraints
- Actuarial Talent Scarcity:The specialized workforce required for predictive modeling and risk stratification commands premium compensation that compresses operating margins for mid-tier carriers.
- State Regulatory Fragmentation:Insurance commissioners in all fifty states maintain independent reserve requirements and rate review timelines that complicate national product standardization.
- Medical Cost Inflation:Pharmaceutical pricing and specialty care utilization are outpacing premium growth, threatening the sustainability of current benefit designs.
Strategic Opportunities
- Medicare Advantage Penetration:Aging demographics in Florida and Arizona present expansion opportunities for carriers with established provider network density.
- Value-Based Contracting:CMS innovation center pilots are enabling risk-sharing arrangements that align carrier payments with patient outcomes rather than service volume.
- Retail Health Integration:Pharmacy and urgent care footprints are creating new distribution channels for supplemental benefit products and care navigation services.
Industry Challenges
- Legacy System Modernization:Core administrative platforms at established carriers require capital-intensive replacement to support real-time claims processing and interoperability mandates.
- Network Adequacy Compliance:State-level distance and time standards for specialist access demand continuous provider recruitment that strains contracting resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Health and Medical Insurance Market |
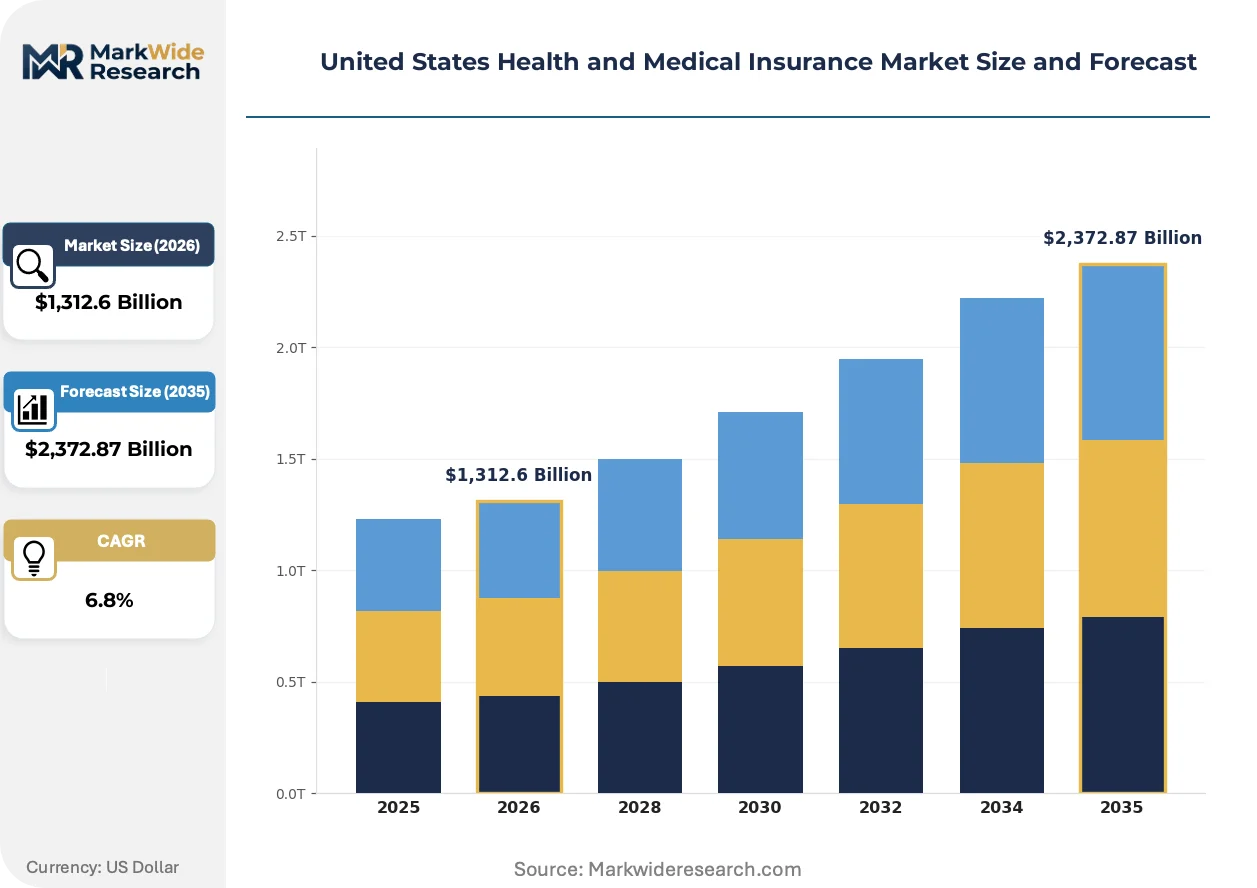
| Market Size in 2026 | $1,312.6 Billion |
| Market Size in 2035 | $2,372.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual Plans, Family Plans, Short-Term Coverage, Group Coverage Service Model: Managed Care, Indemnity, High Deductible, Exclusive Provider Organization Beneficiary Type: Employees, Self-Employed, Retirees, Students Payment Structure: Premiums, Copayments, Coinsurance, Deductibles |
| Companies Covered | UnitedHealth Group, Elevance Health, CVS Health, Centene Corporation, Humana, Cigna, Kaiser Permanente, Health Care Service Corporation, Molina Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Health and Medical Insurance Market Evolving Landscape
Artificial intelligence and alternative payment models are converging to reshape how carriers predict risk, manage utilization, and contract with providers across the United States.
Machine learning algorithms embedded in claims processing workflows are fragmenting traditional actuarial functions into specialized prediction tasks. Large group employers and Medicare Advantage plans are adopting these tools fastest, deploying them for fraud detection and readmission forecasting. This capability diffusion is compressing the competitive advantage historically held by carriers with captive analytics divisions.
CMS innovation center pilots and state Medicaid waivers are accelerating value-based reimbursement adoption. These programs shift financial risk from government payers to managed care organizations through capitated and shared savings arrangements. Medicare Advantage carriers in California and New York are responding by acquiring physician practices to secure cost control.
Consumer digital engagement preferences are forcing channel restructuring across distribution. Individual market enrollment through federally facilitated exchanges is displacing broker-mediated sales in suburban and rural geographies. Florida and Texas beneficiaries are driving this shift, demanding mobile-first plan comparison and automated subsidy eligibility determination.
United States Health and Medical Insurance Market Segmentation
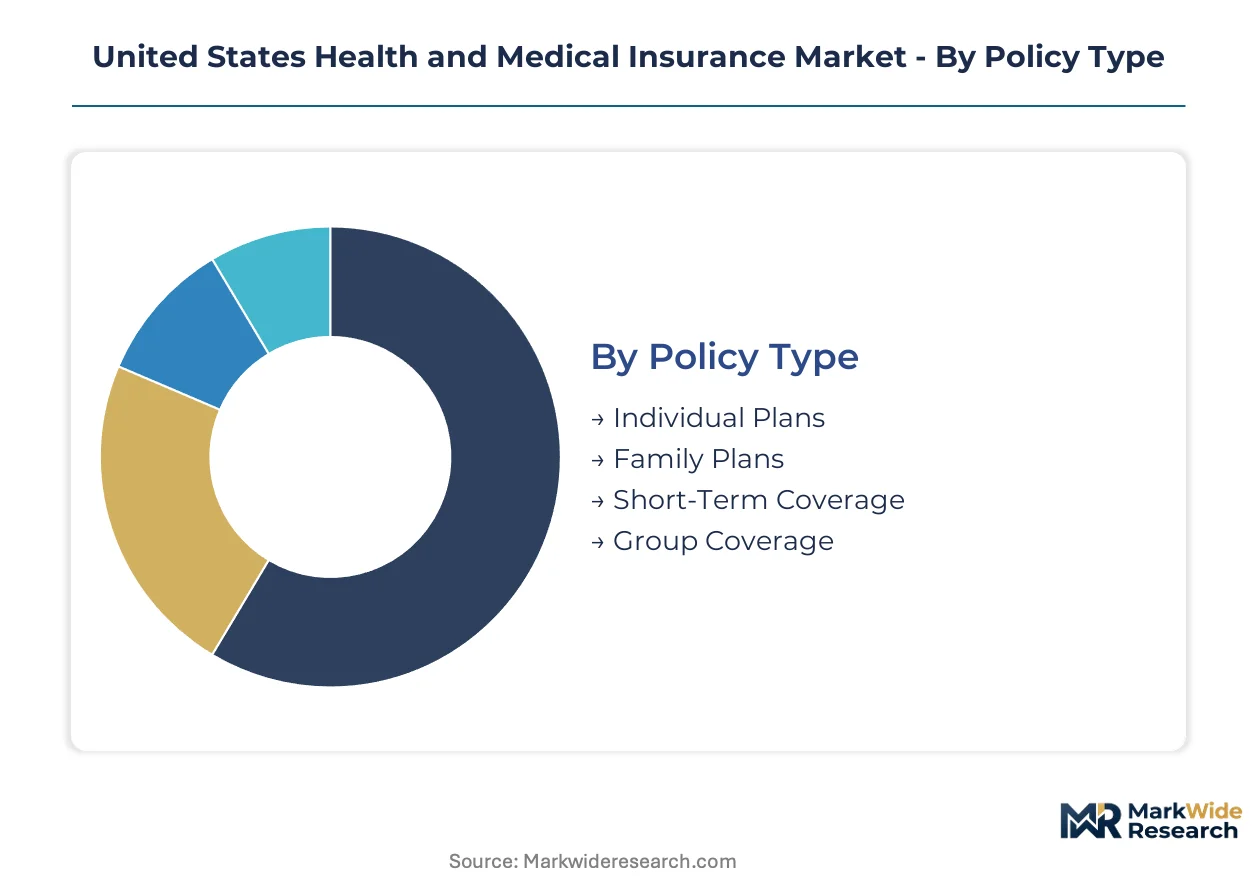
Segmentation in United States health and medical insurance determines pricing mechanics, regulatory compliance burdens, and distribution channel selection. Each dimension reflects distinct risk pools, actuarial requirements, and beneficiary expectations that shape carrier product design and state-level filing strategies.
Policy Type:
HIPAA portability rules and Affordable Care Act essential health benefits mandate create divergent compliance obligations across policy structures, with state insurance commissioners enforcing reserve requirements that vary by enrollment scale.
- Individual Plans:Single-beneficiary contracts sold through federally facilitated exchanges or direct-to-consumer channels. Demand concentrates in Florida and Texas suburbs where mobile-first enrollment platforms displace broker-mediated sales.
- Family Plans:Multi-beneficiary coverage extending dependent protections through age 26 under ACA provisions. California and New York households drive volume where dual-income professionals seek comprehensive pediatric and maternity benefits.
- Short-Term Coverage:Limited-duration policies filling gaps between employer-sponsored or qualified plan enrollment. Bridge coverage for gig workers in Arizona and Nevada facing seasonal employment transitions.
- Group Coverage:Employer-sponsored risk pools leveraging administrative efficiency and scale economics. Tight labor markets across Texas and Florida accelerate adoption as talent acquisition tools.
Established volume favors Group Coverage; emerging adoption favors Individual Plans.
Service Model:
Cost tier differentiation separates premium exposure from network flexibility, with beneficiary trade-offs between out-of-pocket maximums and provider choice breadth driving selection patterns across state markets.
- Managed Care:Restricted provider networks exchanging lower premiums for utilization controls and gatekeeper referrals. Dominant enrollment in California, Texas, and Florida where large risk pools sustain competitive pricing.
- Indemnity:Fee-for-service reimbursement allowing unrestricted provider selection with higher premium exposure. Retirees in Arizona and Florida prioritize choice breadth over cost containment.
- High Deductible:Consumer-directed plans pairing catastrophic coverage with health savings account eligibility. Employer cost-shifting accelerates adoption fastest among mid-market firms in Georgia and North Carolina.
- Exclusive Provider Organization:Hybrid structure mandating in-network utilization except for emergency services, with no referral requirements. Growth corridors in urban Texas and Florida where narrow networks achieve price compression.
Managed Care retains the largest enrollment base; High Deductible plans are expanding most quickly.
Beneficiary Type:
Customer type determines subsidy eligibility, underwriting flexibility, and product bundling opportunities, with CMS programs and employer contribution structures creating distinct access pathways.
- Employees:Wage-earners accessing employer-sponsored coverage with pre-tax premium contributions. Texas and California employers weaponize benefits packages in competitive labor markets.
- Self-Employed:Independent contractors purchasing individual market coverage with limited group risk pooling. Exchange subsidies in Florida and Georgia improve affordability for sole proprietors.
- Retirees:Medicare-eligible beneficiaries selecting supplemental or Medicare Advantage products. Arizona and Florida aging demographics concentrate demand for carrier network density.
- Students:Young adults accessing school-sponsored plans or remaining on parental coverage through age 26. University health systems in California and Massachusetts anchor regional enrollment.
Employees dominate premium volume; Retirees command the highest per-beneficiary margins.
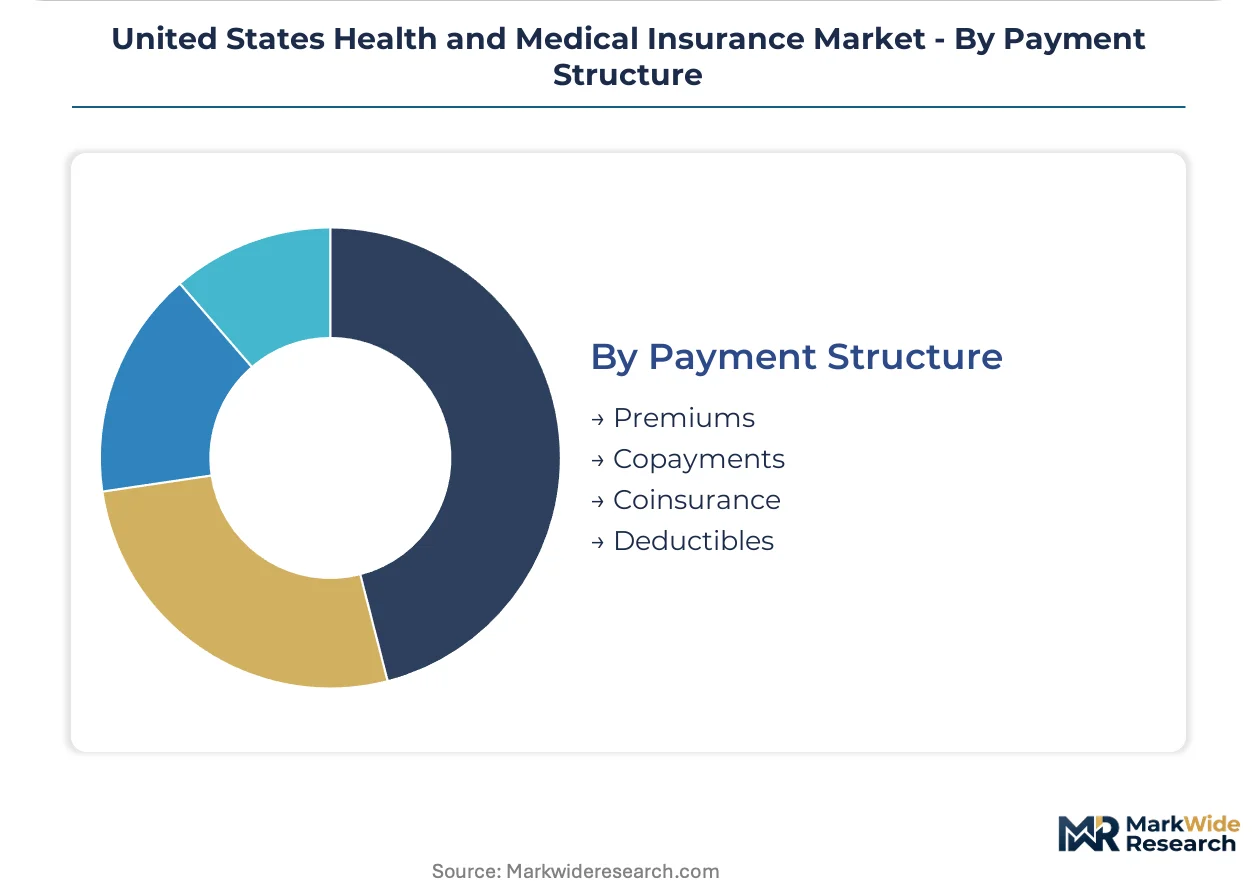
Payment Structure:
Margin concentration varies by payment mechanism, with front-loaded premium revenue contrasting against variable cost-sharing exposure that shapes beneficiary utilization behavior and carrier cash flow timing.
- Premiums:Fixed periodic payments funding risk pool reserves and administrative overhead. State rate review processes in California and New York constrain pricing flexibility.
- Copayments:Flat per-service fees at point of care reducing moral hazard in primary and specialty utilization. Tiered drug formularies in Medicare Advantage plans deploy this mechanism.
- Coinsurance:Percentage-based cost-sharing after deductible satisfaction exposing beneficiaries to specialty care price variation. High Deductible plans in employer markets rely heavily on this structure.
- Deductibles:Annual spending thresholds beneficiaries must satisfy before coverage activation. Employer cost-shifting in Texas and Florida elevates these thresholds fastest.
Premiums generate predictable revenue; Deductibles are climbing the fastest as cost-containment instruments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beneficiary enrollment patterns diverge sharply across state markets, with employer-sponsored coverage dominating Texas and Florida while individual exchange plans capture disproportionate share in California and New York suburbs.
California
Dual-income households in Los Angeles and San Francisco Bay Area drive Family Plan enrollment through employer channels. Covered California exchange subsidies expand individual market access for gig workers and sole proprietors. Kaiser Permanente's integrated delivery network anchors competitive positioning in Sacramento and San Diego corridors.
Texas
Mid-market employers in Dallas-Fort Worth and Houston weaponize benefits packages to attract talent in tight labor markets. State insurance commissioner oversight maintains reserve requirements that constrain pricing flexibility for regional carriers. High Deductible Health Plans accelerate fastest among Georgia and North Carolina transplants relocating to Austin and San Antonio tech corridors.
Florida
Aging demographics in Miami-Dade and Tampa Bay concentrate Medicare Advantage demand for carriers with established provider network density. Federally facilitated exchange enrollment displaces broker-mediated sales in suburban Orlando and Jacksonville. Medicaid managed care contracts under state waiver authority reshape competitive boundaries for regional players.
New York
Metropolitan households seek comprehensive pediatric and maternity benefits through employer-sponsored Family Plans. State rate review processes constrain premium pricing flexibility for commercial carriers. Buffalo and Rochester industrial clusters sustain Group Coverage enrollment despite manufacturing employment volatility.
Arizona
Retirees in Phoenix and Tucson prioritize Indemnity plan choice breadth over cost containment for specialty care access. Telehealth infrastructure extends network reach into rural Cochise and Yuma counties previously deemed unprofitable. Bridge coverage demand surges among seasonal hospitality workers in Scottsdale and Flagstaff facing employment transitions.
United States Health and Medical Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with national carriers commanding scale economics in group coverage while regional Medicaid specialists anchor state-level contracts. The upper tier consolidates predictive analytics capabilities and captive provider networks that compress medical loss ratios. Mid-tier players compete through geographic concentration and regulatory relationships rather than technology differentiation. Dominant competitive moves include vertical integration into physician practice acquisition and retail health footprint expansion.
Within the integrated carrier archetype, UnitedHealth Group and Elevance Health exemplify divergent strategic positioning—one leveraging analytics infrastructure, the other anchoring state Medicaid dominance. CVS Health occupies a hybrid position bridging retail pharmacy distribution with insurance underwriting. These three represent the structural poles around which remaining competitors organize their market presence.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Elevance Health |
| CVS Health |
| Centene Corporation |
| Humana |
| Cigna |
| Kaiser Permanente |
| Health Care Service Corporation |
| Molina Healthcare |
| Others |
Value Network & Pricing Analysis
HIPAA portability rules and Affordable Care Act essential health benefits mandates gate both carrier qualification and product tiering simultaneously, creating compliance-driven price stratification that rewards integrated players with captive provider networks and penalizes thinly capitalized regional entrants.
Pricing Analysis
Long-term group contracts dominate employer-sponsored coverage, locking in multi-year rate guarantees that exchange stability for limited repricing flexibility. Premium differentiation hinges on actuarial value tiers and network density, with narrow-network EPOs in Texas and Florida commanding 15-20% discounts against broad PPO alternatives. Pricing pressure stems from medical cost inflation outpacing premium growth in specialty pharmaceutical categories. Small group employers exhibit highest price sensitivity, while Fortune 500 self-insured plans prioritize network adequacy over premium minimization.
Supply Chain Analysis
Actuarial talent scarcity in India and Ireland creates a chokepoint that underwrites offshore analytics capacity for US carriers seeking predictive modeling scale. Core inputs include proprietary claims databases, CMS reimbursement benchmarks, and licensed provider network directories. Single-source vulnerability concentrates in pharmacy benefit managers controlling formulary placement and rebate aggregation. Distribution runs through employer benefits consultants, federally facilitated exchanges, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as interoperability mandates and API-driven data exchange reshape carrier-provider-payer relationships, with CMS innovation center pilots accelerating ecosystem consolidation around value-based contracting infrastructure.
For Market Incumbents: Secure captive provider network density through physician practice acquisition in Medicare Advantage-heavy geographies like Florida and Arizona. Lock in Medicaid managed care contract renewals before state waiver recompetes intensify. Actuarial talent scarcity threatens margin compression; build offshore analytics capacity in Bangalore and Dublin to sustain predictive modeling advantage against Elevance Health and UnitedHealth Group scale. For New Entrants and Emerging Players: Lead with narrow-network EPO designs targeting price-sensitive mid-market employers in Texas and Georgia tech corridors. Individual exchange enrollment platforms in suburban Florida present the most penetrable white space, displacing broker-mediated sales with mobile-first subsidy eligibility tools. Pursue direct-to-consumer distribution partnerships with retail health footprints rather than competing for employer RFP access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Medicare Advantage geographic expansion plays, favoring scaled incumbents with existing CMS star ratings and provider network density. Target acquisition archetype: regional Medicaid specialists with state contract moats in expansion states lacking national carrier presence. Watch CMS innovation center pilot expansion as the signal for value-based reimbursement inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Physician Practice Acquisition | Secures cost control leverage for Medicare Advantage carriers competing in Florida and Arizona. |
| Medicaid Contract Renewal | Locks in multi-year revenue streams before state waiver recompete cycles intensify pricing pressure. |
| Offshore Analytics Buildout | Addresses actuarial talent scarcity through Bangalore and Dublin capability centers. |
| Retail Health Integration | Creates distribution channel control for supplemental benefits via pharmacy and urgent care footprints. |
| Digital Exchange Platform Launch | Captures individual market enrollment shift away from broker-mediated sales in suburban geographies. |
Research Methodology
A spread of perspectives from actuarial directors, state Medicaid program officers, employer benefits consultants, and hospital system contracting leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with carrier strategy executives and health system CFOs, validated against secondary sources including CMS Medicare Advantage enrollment files, state insurance commissioner rate review filings, and hospital GPO contract databases. Bottom-up enrollment projections triangulated against top-down premium revenue estimates across policy type and service model segments.
Segmentation dimensions modeled include policy structure, service model architecture, beneficiary category, and payment mechanism across the projection horizon. CAGRs derived from historical enrollment velocity, premium trend analysis, and medical cost inflation assumptions. Forecast inputs incorporated state-level Medicaid expansion trajectories, Medicare Advantage penetration ceilings by county, and employer cost-shifting propensity indices.
The analysis sits within stated boundaries; outcomes outside sustained ACA subsidy appropriations and CMS innovation center pilot continuity would require recalibration. Forecasts reflect documented assumptions regarding medical loss ratio floors, network adequacy enforcement intensity, and pharmaceutical pricing negotiation authority expansion. Practitioners should keep alternative scenarios live as state waiver applications and federal administrative rulemaking evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
Healthcare Insurance Market
Health Insurance
UAE Health Insurance Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
Health Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
Germany Health Insurance Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market