
 Europe Medical Cannabis Market | 2026-2036
Europe Medical Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Cannabis Market Intelligence
European cannabis cultivation capacity is consolidating around GMP-certified greenhouse networks in the Netherlands and Portugal. Bedrocan leverages decades of standardized cultivar development to sustain pharmacy channel dominance across Dutch and German markets. Aurora Cannabis anchors North American-European supply corridors with EU-GMP extraction infrastructure in Denmark. Cantourage differentiates through its digital pharmacy platform that controls last-mile distribution to German patients.
Medical cannabis comprises cannabinoid-active pharmaceutical preparations—primarily delta-9-THC and CBD formulations—standardized to specific mg-per-unit doses and manufactured under EU-GMP conditions for therapeutic administration. These products serve as adjuvant or primary therapy for neuropathic pain, spasticity, and chemotherapy-induced symptoms where conventional interventions prove insufficient. Oil formulations capture the dominant margin pool due to physician familiarity with titratable dosing and favorable reimbursement coding in Germany, while inhalation delivery mode leads prescription volumes among experienced pain specialists. Neurology applications represent the fastest-expanding therapy area as multiple sclerosis and epilepsy protocols incorporate nabiximols and CBD isolates into standard care pathways.
EMA's Committee for Medicinal Products for Human Use maintains centralized assessment pathways for novel cannabinoid therapies, while Germany's BfArM oversees domestic cultivation quotas and pharmacy dispensing under the Betäubungsmittelgesetz framework. REACH compliance and EU-GMP Annex 6 guidelines shape extract purity thresholds and solvent residue limits that determine market access eligibility. Stakeholders must monitor how Germany's upcoming cannabis legalization framework differentiates medical and adult-use distribution channels, as regulatory arbitrage opportunities could fragment pricing and patient access across neighboring jurisdictions.
Market Dynamics
Germany's Betäubungsmittelgesicht framework revision is compressing the timeline for domestic cultivation permits while EMA scheduling debates reshape import corridor economics across the continent.
Growth Catalysts
- Neurology protocol expansion:Multiple sclerosis treatment centers in Germany and Italy are integrating nabiximols into first-line spasticity management, expanding addressable patient pools beyond chronic pain.
- Poland's reimbursement pathway maturation:The country's national health fund added cannabis extracts to its drug program, triggering pharmacy network upgrades in Warsaw and Krakow.
- EU-GMP certification harmonization:REACH-aligned solvent residue standards are enabling Portuguese cultivation facilities to supply German pharmacies without batch-specific retesting.
Market Restraints
- Input cost volatility:Pharmaceutical-grade ethanol prices fluctuate with biofuel policy shifts, squeezing extraction margins for EU-GMP processors.
- Supply concentration risk:Dutch greenhouse networks control over sixty percent of standardized cultivar supply, creating geographic vulnerability to energy price shocks.
- Regulatory friction:EMA's centralized assessment timelines for novel cannabinoid therapies extend eighteen to thirty-six months, delaying market access for reformulated products.
Strategic Opportunities
- Underpenetrated geography:Spain's autonomous communities are establishing regional prescription protocols outside Madrid and Barcelona, creating first-mover advantages for distribution infrastructure.
- Technology convergence:Terpene profiling combined with pharmacogenomic testing enables personalized dosing platforms for pain clinics.
- Distribution innovation:Digital pharmacy platforms with integrated reimbursement verification are capturing last-mile prescription fulfillment from traditional wholesale channels.
Industry Challenges
- Talent scarcity in GMP compliance:Qualified persons with EU-GMP Annex 6 expertise command premium compensation, constraining facility expansion timelines.
- Certification timeline compression:REACH registration dossiers for novel extraction solvents require twelve to eighteen month validation cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Cannabis Market |
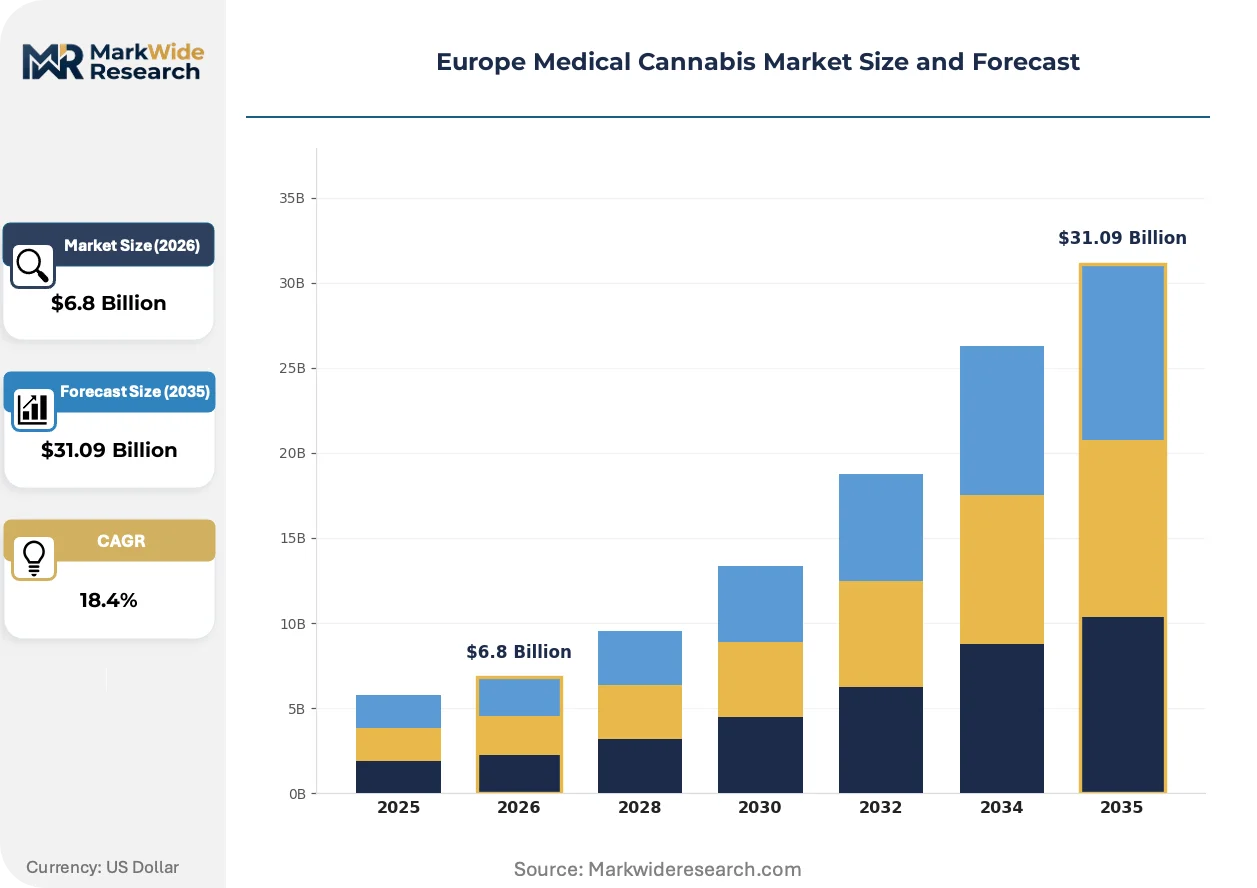
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Capsules, Tinctures, Balms Therapy Area: Pain Management, Neurology, Oncology, Mental Health Delivery Mode: Inhalation, Oral, Topical, Sublingual End User: Clinics, Hospitals, Home Care, Research Institutions |
| Companies Covered | Cansativa, Medios AG, Canopy Growth Corporation, GW Pharmaceuticals, Little Green Pharma, Aurora Cannabis, Cantourage, Bedrocan, Tilray, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Cannabis Market Strategic Shifts & Innovations
Standardized cultivar development and extraction technology maturation are converging to reduce batch variability, while digital distribution infrastructure captures margin from legacy wholesale networks.
Supercritical CO2 extraction systems with integrated terpene recovery modules are electrifying pharmaceutical-grade oil production. Dutch and Portuguese processors are deploying these units at fifty-liter scale to meet German pharmacy demand for consistent cannabinoid ratios. The technology is electrifying margin capture by eliminating ethanol recovery steps and reducing solvent residue compliance costs.
EMA's evolving cannabis scheduling assessments under the Committee for Medicinal Products for Human Use are creating parallel pathways for botanical and synthetic cannabinoid approvals. This regulatory development forces manufacturers to maintain dual dossier strategies, increasing compliance overhead but enabling broader indication claims. German and Dutch regulators are responding with accelerated national assessment procedures for well-established cultivars.
Chronic pain clinics are consolidating procurement through specialized pharmacy platforms that bundle prescription fulfillment with reimbursement administration. This channel shift displaces traditional wholesale relationships in Berlin and Munich metropolitan areas. The transformation is most visible in Germany's statutory health insurance system, where digital platforms reduce patient out-of-pocket processing delays.
Europe Medical Cannabis Market Segmentation
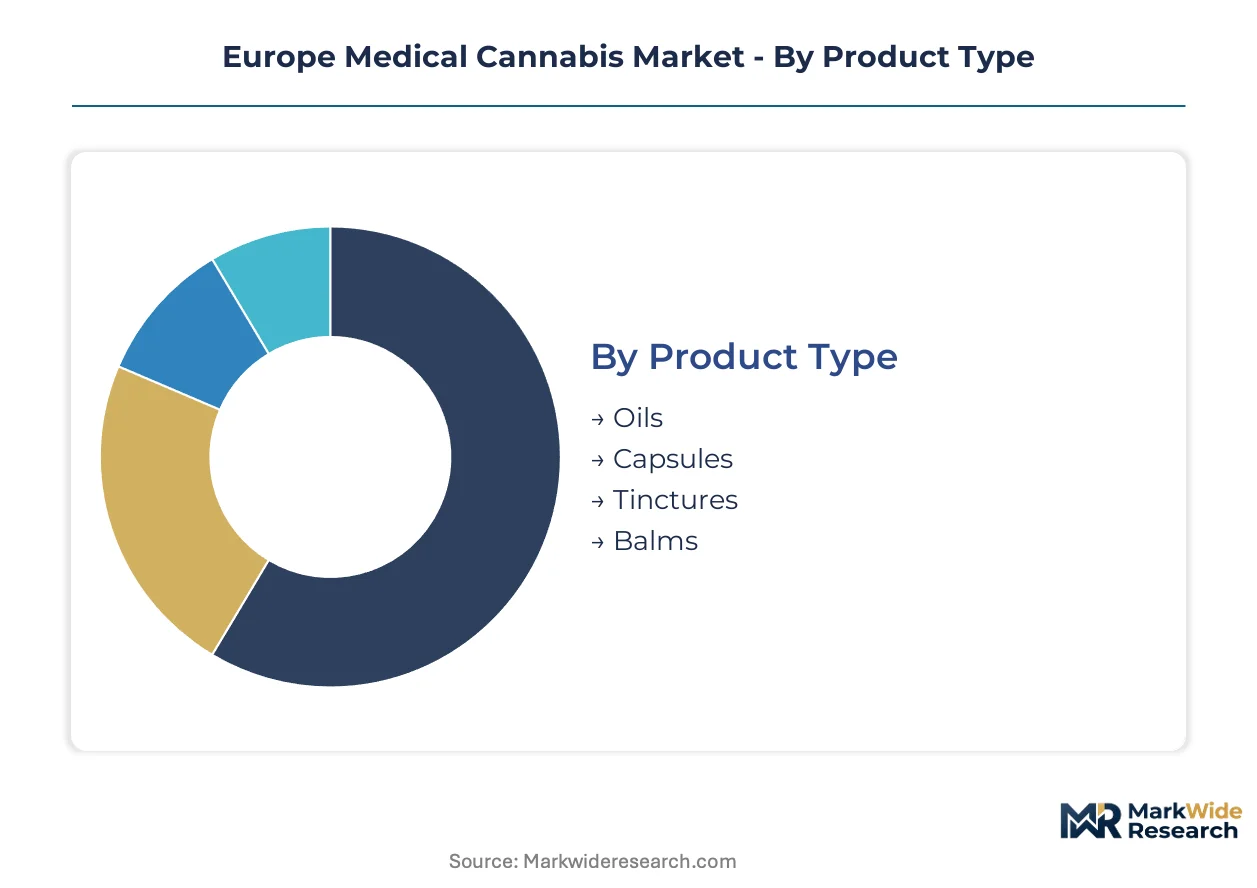
Segmentation in European medical cannabis reveals how capital allocation, regulatory pathways, and reimbursement codes concentrate value across distinct product and channel configurations. Understanding these divisions exposes where EU-GMP compliance costs create barriers and where digital distribution unlocks margin capture.
Product Type:
Capital intensity varies sharply across product categories, with extraction infrastructure and stability testing demanding the heaviest upfront investment for oil formulations.
- Oils:Liquid cannabinoid suspensions in pharmaceutical-grade carrier oils enable precise titration and dominate German pharmacy dispensing. Demand clusters in Berlin and Munich pain clinics where statutory health insurance reimbursement codes favor standardized dosing protocols.
- Capsules:Encapsulated formulations with fixed-dose THC-CBD ratios appeal to polypharmacy patients seeking discreet administration. Polish and Italian markets are expanding capsule volumes as national health funds add these products to reimbursement lists.
- Tinctures:Alcohol-based extracts with rapid buccal absorption serve experienced patients in Dutch pharmacy networks.
- Balms:Topical preparations with localized anti-inflammatory claims occupy niche positioning in Spanish regional markets.
Oils absorb the bulk of installed capacity; capsules are expanding most quickly.
Therapy Area:
Application focus determines clinical evidence requirements and thus regulatory submission costs, with neurology demanding the most extensive trial dossiers.
- Pain Management:Chronic neuropathic and cancer-related pain represents the foundational indication driving prescription volumes across German and Dutch reimbursement systems. German pain clinics in Cologne and Hamburg are consolidating procurement through specialized pharmacy platforms.
- Neurology:Multiple sclerosis spasticity and treatment-resistant epilepsy protocols incorporate nabiximols and CBD isolates as adjuvant therapy. Italian MS treatment centers are expanding cannabinoid integration into first-line management.
- Oncology:Chemotherapy-induced nausea and appetite stimulation applications serve secondary indications with narrower addressable populations.
- Mental Health:PTSD and anxiety protocols remain exploratory across European jurisdictions with limited reimbursement coverage.
Pain management commands the deepest clinical infrastructure investment; neurology is gaining share fastest.
Delivery Mode:
Patient adherence patterns and pharmacy dispensing economics shape channel preference, with oral formulations capturing margin through reimbursement efficiency.
- Inhalation:Vaporized dried flower and oil formulations deliver rapid onset for breakthrough pain episodes. Dutch pharmacies maintain dominant dispensing volumes through standardized Bedrocan cultivar supply.
- Oral:Capsules and oils enable predictable pharmacokinetics preferred by German statutory insurers for chronic dosing regimens.
- Topical:Localized delivery without systemic absorption appeals to musculoskeletal applications in Spanish autonomous communities.
- Sublingual:Rapid absorption without hepatic first-pass metabolism serves patients with compromised liver function in specialized Belgian clinics.
Oral delivery anchors reimbursement-optimized dispensing; inhalation retains volume leadership among experienced prescribers.
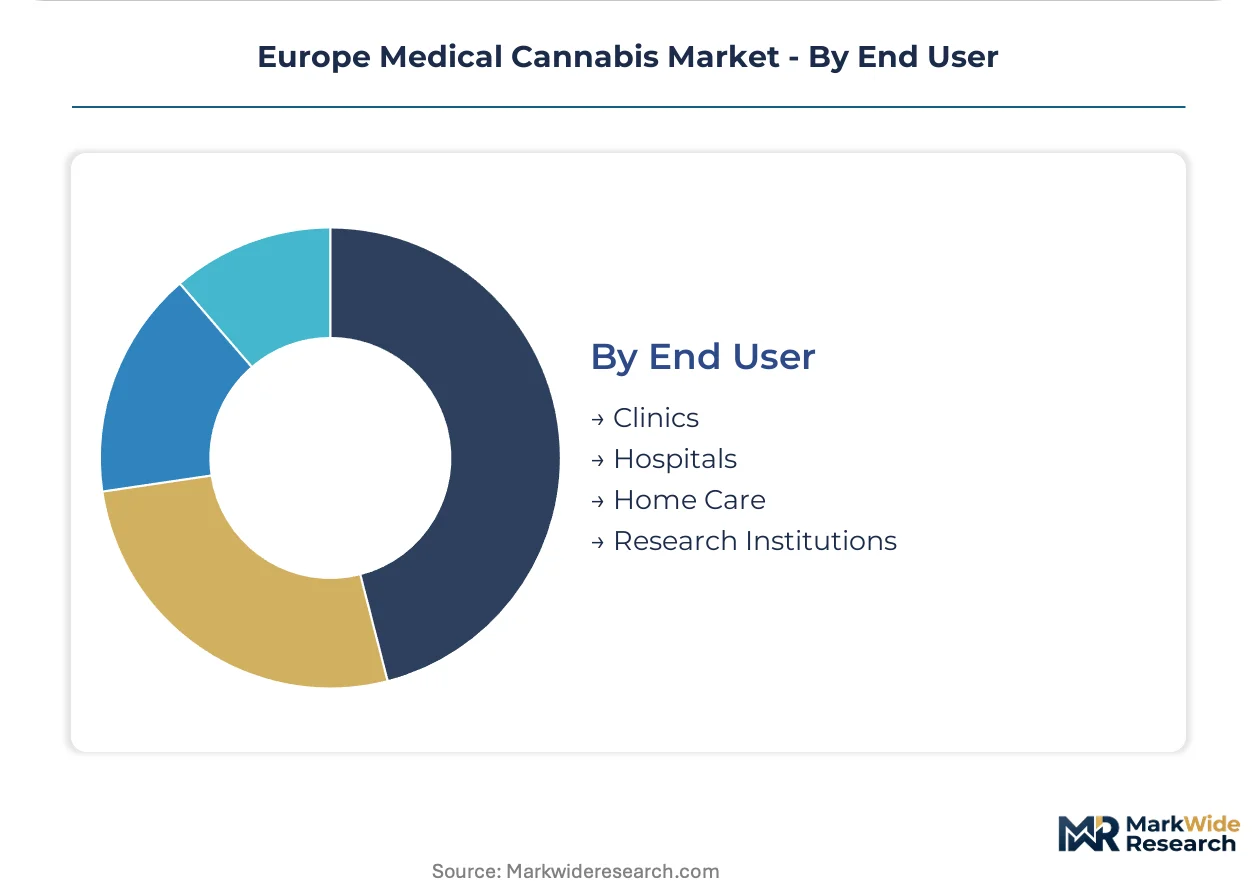
End User:
Procurement concentration and reimbursement verification complexity determine platform economics, with clinics offering the most attractive customer lifetime value.
- Clinics:Specialized pain and neurology centers in Germany and the Netherlands generate recurring prescription volumes with streamlined prior authorization. Cantourage and similar digital platforms target this channel with integrated reimbursement administration.
- Hospitals:Inpatient oncology and palliative care units require batch-level traceability and emergency stock protocols that strain legacy wholesale relationships.
- Home Care:Direct-to-patient delivery models are emerging in Poland as pharmacy network density remains uneven outside Warsaw and Krakow.
- Research Institutions:Academic medical centers in Denmark and the Netherlands drive protocol development but represent limited commercial volume.
Clinics concentrate platform investment; home care is climbing the fastest as digital infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch greenhouse complexes in the Westland region supply standardized cultivars to German pharmacies under EU-GMP protocols. Portugal's Alentejo cultivation zones are scaling capacity to serve continental demand. Danish extraction infrastructure anchors North American-European supply corridors.
Germany
Chronic pain clinics in Berlin and Munich drive prescription volumes through statutory health insurance reimbursement. The BfArM oversees domestic cultivation quotas and pharmacy dispensing under the Betäubungsmittelgesetz framework. Cologne and Hamburg pain centers are consolidating procurement through specialized digital pharmacy platforms.
Netherlands
Standardized Bedrocan cultivars dominate Dutch pharmacy networks with decades of pharmaceutical-grade consistency. The Dutch Office of Medicinal Cannabis regulates export quotas to German and Italian markets. Westland greenhouse clusters maintain over sixty percent of Europe's standardized medical cannabis supply.
Poland
The national health fund added cannabis extracts to its drug program, triggering pharmacy network upgrades in Warsaw and Krakow. Poland's pharmaceutical regulator aligns product registration with EMA centralized assessment pathways. Regional prescription protocols are expanding beyond major metropolitan centers into secondary cities.
Italy
Multiple sclerosis treatment centers in Milan and Rome are integrating nabiximols into first-line spasticity management. The Italian Medicines Agency oversees import authorization for EU-GMP certified products. Northern Italian hospital networks are building dedicated cannabinoid therapy units for neurology applications.
Spain
Autonomous communities outside Madrid and Barcelona are establishing regional prescription protocols for neuropathic pain. Spanish regional health authorities operate outside centralized national frameworks, creating fragmented access pathways. Andalusian and Catalan pharmacy networks are upgrading cold-chain infrastructure for oil formulation distribution.
Europe Medical Cannabis Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital distribution and specialized extraction capabilities. The market structure concentrates around GMP-certified greenhouse operators with decades of cultivar development heritage alongside North American-European supply corridor specialists. Three archetypes dominate: legacy Dutch cultivar standardizers, North American integrated multinationals, and digital pharmacy platform operators. Competitive moves center on EU-GMP certification acquisition and last-mile distribution infrastructure capture.
Among Dutch heritage cultivators, Bedrocan anchors the standardized product tier with pharmaceutical-grade consistency protocols. Aurora Cannabis and Cantourage occupy distinct positioning vectors—Aurora through Danish extraction infrastructure serving cross-continental supply needs, Cantourage through digital pharmacy platforms controlling German patient last-mile access. These three represent the structural segmentation between legacy cultivation expertise, integrated multinational scale, and technology-enabled distribution innovation.
| Leading Market Players |
|---|
| Cansativa |
| Medios AG |
| Canopy Growth Corporation |
| GW Pharmaceuticals |
| Little Green Pharma |
| Aurora Cannabis |
| Cantourage |
| Bedrocan |
| Tilray |
| Others |
Cost & Logistics Intelligence
Captive EU-GMP greenhouse networks in the Netherlands and Portugal anchor supply positions and pricing power through batch-to-batch consistency guarantees that German pharmacies demand. This vertical integration into pharmaceutical-grade cultivation insulates standardized cultivar suppliers from spot-market volatility while commanding reimbursement-optimized price premiums.
Pricing Analysis
Reimbursement-bundled service tiers separate pharmacy-dispensed oils with statutory health insurance coverage from self-pay tinctures and balms without prior authorization support. Price differentiation hinges on EU-GMP certification grade and volume scale, with large clinic contracts securing favorable per-unit rates. Cost compression in inhalation-grade dried flower is intensifying because Portuguese cultivation capacity is scaling faster than German prescription growth. Statutory health insurance patients exhibit lowest price sensitivity due to capped out-of-pocket obligations, while self-pay segments in Spanish autonomous communities demonstrate highest elasticity.
Supply Chain Analysis
Pharmaceutical-grade ethanol supply rests on biofuel policy shifts in Brazil and European agricultural commodity markets, creating input cost volatility for extraction processors. Dutch greenhouse clusters, Portuguese Alentejo cultivation zones, and Danish extraction facilities form the geographic supply backbone. Raw material dependencies include standardized cultivar genetics, GMP-certified packaging components, and analytical reference standards. Single-source vulnerability concentrates in Dutch cultivar supply controlling over sixty percent of standardized medical-grade output. Distribution runs through digital pharmacy platforms with integrated reimbursement verification, displacing legacy wholesale channels in German metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU-GMP Annex 6 certification creates a barrier-to-entry moat that rewards incumbent investment while filtering out undercapitalized entrants.
For Market Incumbents: Deploy cultivar portfolio expansion as the primary defensive lever. Bedrocan and Aurora Cannabis should deepen proprietary genetics libraries to preempt biosimilar competition from emerging Portuguese cultivators. Channel control through captive digital pharmacy platforms protects against wholesale margin erosion. Capacity addition in Danish extraction infrastructure secures North American-European corridor dominance against tariff-exposed import alternatives. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Spanish autonomous communities offers the most penetrable white-space opportunity. Regional prescription protocols outside Madrid and Barcelona lack established pharmacy networks, enabling first-mover distribution infrastructure capture. Target home care delivery models in Polish secondary cities where pharmacy density remains uneven. A direct-to-clinic go-to-market angle bypasses wholesale channel congestion. For Investors and Strategic Acquirers: Exit pathways concentrate in digital pharmacy platform operators with last-mile control over German patient access. Long-term viability favors EU-GMP-certified cultivators with decade-plus genetics heritage over speculative extraction plays. Acquisition target archetype: Portuguese greenhouse operators with REACH-aligned solvent residue capabilities and uncontracted capacity expansion rights. The signal to watch is Germany's Betäubungsmittelgesetz framework differentiation between medical and adult-use channels.| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Acquisition | EMA-aligned manufacturing standards unlock German pharmacy reimbursement pathways and export quotas. |
| Digital Pharmacy Platform Integration | Cantourage-style last-mile control captures margin from legacy wholesale relationships in Berlin and Munich. |
| Standardized Cultivar Development | Bedrocan's decades-long genetics investment sustains pharmacy channel dominance through batch consistency. |
| Portuguese Cultivation Scale-Up | Alentejo greenhouse expansion diversifies supply beyond Dutch concentration risk and energy price exposure. |
| Reimbursement Strategy Alignment | Polish national health fund integration and German statutory insurance coding determine addressable patient pools. |
Research Approach
Multi-period observation of prescription volume trajectories, reimbursement code expansions, and cultivation permit issuances anchored the trend analysis, supplemented by interviews with regulatory affairs specialists at EMA and BfArM, pharmacy procurement managers in German statutory health insurance networks, pain clinic prescribing physicians, and EU-GMP qualified persons. Secondary validation drew from EMA centralized assessment databases, German Betäubungsmittelgesetz regulatory filings, REACH registration dossiers, and hospital procurement contract disclosures. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated against cultivation capacity and import corridor data.
Segment-weighting applied therapy area, product type, delivery mode, and end-user channel dimensions across the projection horizon. Pain management, neurology, oncology, and mental health applications were modeled separately with distinct regulatory submission timelines and reimbursement pathways. Oral, inhalation, topical, and sublingual delivery modes carried different pharmacy dispensing economics and patient adherence assumptions. CAGRs were derived from prescription volume elasticity to reimbursement expansion events and cultivation capacity commissioning schedules. Forecast inputs included EMA scheduling assessment timelines, German domestic cultivation quota allocations, and Polish national health fund formulary additions.
Inputs from EMA centralized procedure databases and German BfArM permit registries were available through the study window; gaps in Spanish autonomous community-level prescription protocol standardization introduce uncertainty bands around regional market sizing. Forecasts reflect assumptions regarding reimbursement pathway maturation and EU-GMP certification harmonization that regulatory friction or policy reversal could revise. A small set of named triggers—Germany's adult-use legalization differentiation, EMA cannabinoid rescheduling decisions, and Portuguese cultivation capacity commissioning—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Global Cannabis Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
US Minor Cannabinoids Market