
 Healthcare Application Programming Interfaces Market | 2026-2036
Healthcare Application Programming Interfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Application Programming Interfaces Market Analysis
Buyer concentration among hospital networks and integrated delivery systems is restructuring procurement patterns for healthcare APIs. Epic Systems Corporation anchors enterprise EHR connectivity through its proprietary integration frameworks. Microsoft leverages cloud infrastructure to extend Azure API for FHIR services across provider organizations. Cerner Corporation competes on open-API architectures that support third-party developer ecosystems.
Healthcare Application Programming Interfaces are software intermediaries that enable structured data exchange between disparate health information systems using protocols such as HL7 FHIR R4, OAuth 2.0 security frameworks, and JSON-based payload formats to support real-time clinical workflow integration. Public APIs dominate transaction volumes by exposing standardized endpoints for payer-provider data exchange, while private APIs command premium positioning through customized security layers and dedicated infrastructure for sensitive patient records. REST technology leads deployment simplicity for mobile health applications, whereas middleware integration levels capture margin pools by resolving legacy system interoperability challenges.
The FDA, ONC, and CMS collectively enforce interoperability mandates that shape API certification requirements, data blocking penalties, and patient access standards across the United States healthcare landscape. HIPAA security rule amendments and the 21st Century Cures Act information blocking provisions compel vendors to embed audit logging, token-based authentication, and granular consent management into API architectures. Stakeholders must monitor evolving TEFCA framework implementations and state-level health data exchange policies to anticipate compliance-driven procurement cycles and partnership requirements.
Market Dynamics
ONC's information blocking enforcement is compressing vendor timelines for FHIR R4 compliance, forcing health systems to accelerate API procurement cycles and restructure IT budgets around interoperability mandates rather than discretionary upgrades.
Growth Catalysts
- CMS Medicare Advantage data exchange rules:Payers must implement patient access APIs by 2026, creating immediate procurement demand for OAuth 2.0 authentication infrastructure and standardized claims data endpoints.
- Remote patient monitoring expansion:Cardiology and diabetes management programs require real-time biometric data streams, pulling RESTful API deployments into ambulatory care networks.
- United States hospital consolidation:Merged delivery systems demand unified API gateways across acquired EHR silos, consolidating vendor relationships toward enterprise-wide platform contracts.
Market Restraints
- Legacy HL7 v2 integration costs:Middleware translation layers for decades-old hospital information systems consume 40-60% of API project budgets, constraining rollout velocity.
- Specialized cybersecurity talent scarcity:HIPAA security rule compliance requires dedicated personnel for audit logging and token management that provider organizations cannot source at scale.
- Cloud infrastructure concentration:Three hyperscalers dominate healthcare API hosting, creating single-point-of-failure risk for mission-critical clinical data exchange.
Strategic Opportunities
- Behavioral health platform integration:Mental health providers lack standardized APIs for therapy notes and crisis intervention workflows, representing greenfield deployment potential.
- Social determinants data networks:TEFCA framework expansion into housing and nutrition data exchange creates new revenue pools for API vendors beyond traditional clinical records.
- Edge computing convergence:IoT medical devices paired with 5G networks enable point-of-care API processing without cloud round-trips, opening rural and mobile health segments.
Industry Challenges
- FHIR R4 implementation variability:Vendors interpret core data elements differently, forcing costly custom mapping for each payer-provider connection.
- Consent management engineering:Granular patient permission workflows across state privacy laws require substantial DevOps investment that stretches mid-market health IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Application Programming Interfaces Market |
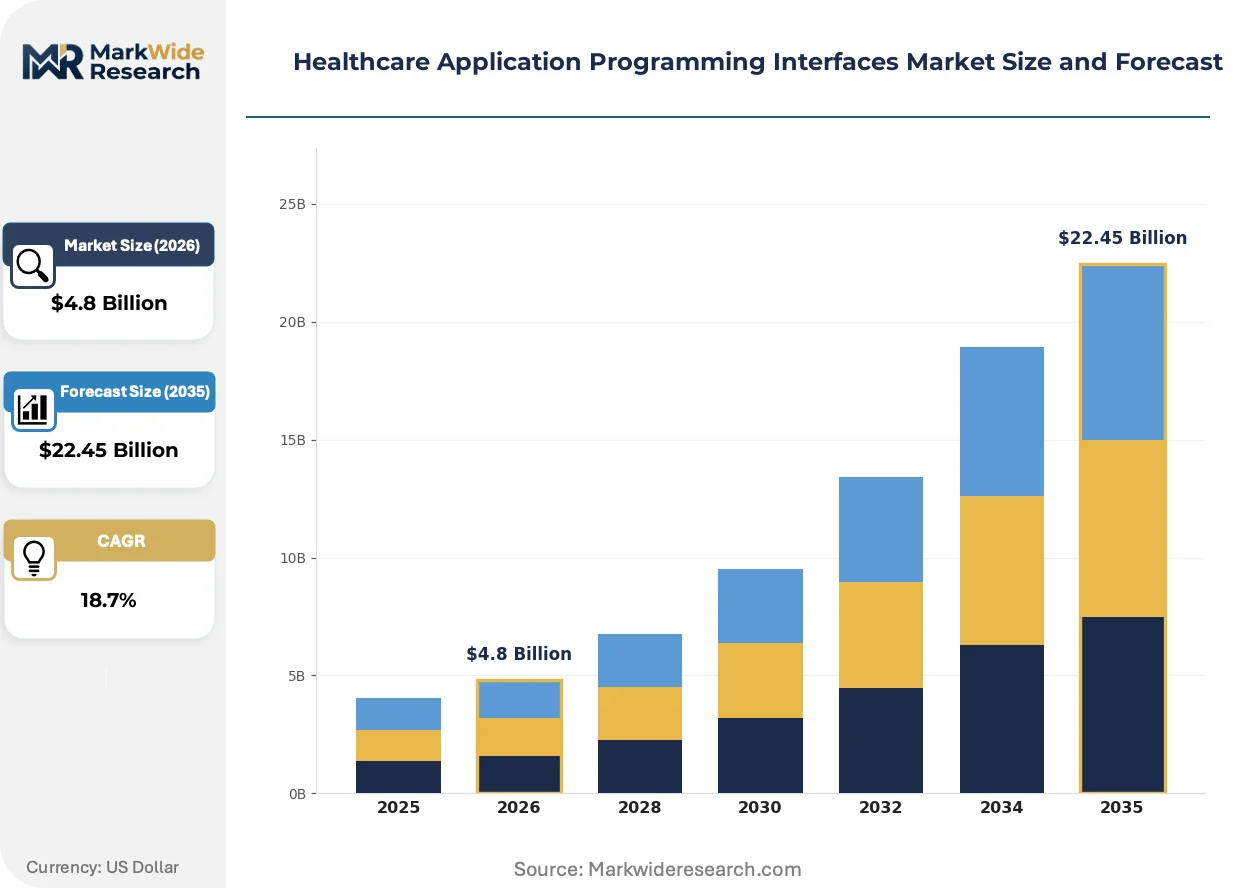
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Public APIs, Private APIs, Partner APIs, Composite APIs Technology: REST, SOAP, GraphQL, WebSocket End User: Hospitals, Clinics, Diagnostic Labs, Telehealth Providers Integration Level: Point-to-Point, Middleware, Cloud-Based, Hybrid |
| Companies Covered | Microsoft, Apple Inc., Epic Systems Corporation, GE HealthCare, Oracle, athenahealth Inc., Cerner Corporation, eClinicalWorks, Greenway Health, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Application Programming Interfaces Market Emerging Trajectories
Healthcare API architectures are pivoting from centralized EHR-centric models toward distributed data fabrics that embed interoperability directly into clinical workflow tools rather than requiring separate integration layers.
FHIR R4 resource profiles are decentralizing data ownership across care teams. Specialist practices and post-acute facilities now maintain independent FHIR endpoints rather than routing through hospital-controlled gateways. This fragmentation is compressing vendor margins on enterprise integration contracts while expanding addressable market volume for lightweight API middleware.
The 21st Century Cures Act information blocking provisions are reshaping liability exposure for health systems. Penalties now attach to API access denials, compelling CIOs to prioritize patient-facing endpoint stability over internal workflow optimization. United States provider networks are responding by embedding compliance monitoring directly into DevOps pipelines rather than treating interoperability as a post-deployment certification step.
Subscription-based API access models are displacing perpetual license structures in payer procurement. UnitedHealthcare and regional Blue Cross plans now negotiate consumption-tiered contracts that scale with transaction volume, transferring infrastructure risk to vendors. This shift is most visible in Medicaid managed care states where budget volatility makes fixed-cost IT commitments untenable for state agencies.
Healthcare Application Programming Interfaces Market Segmentation
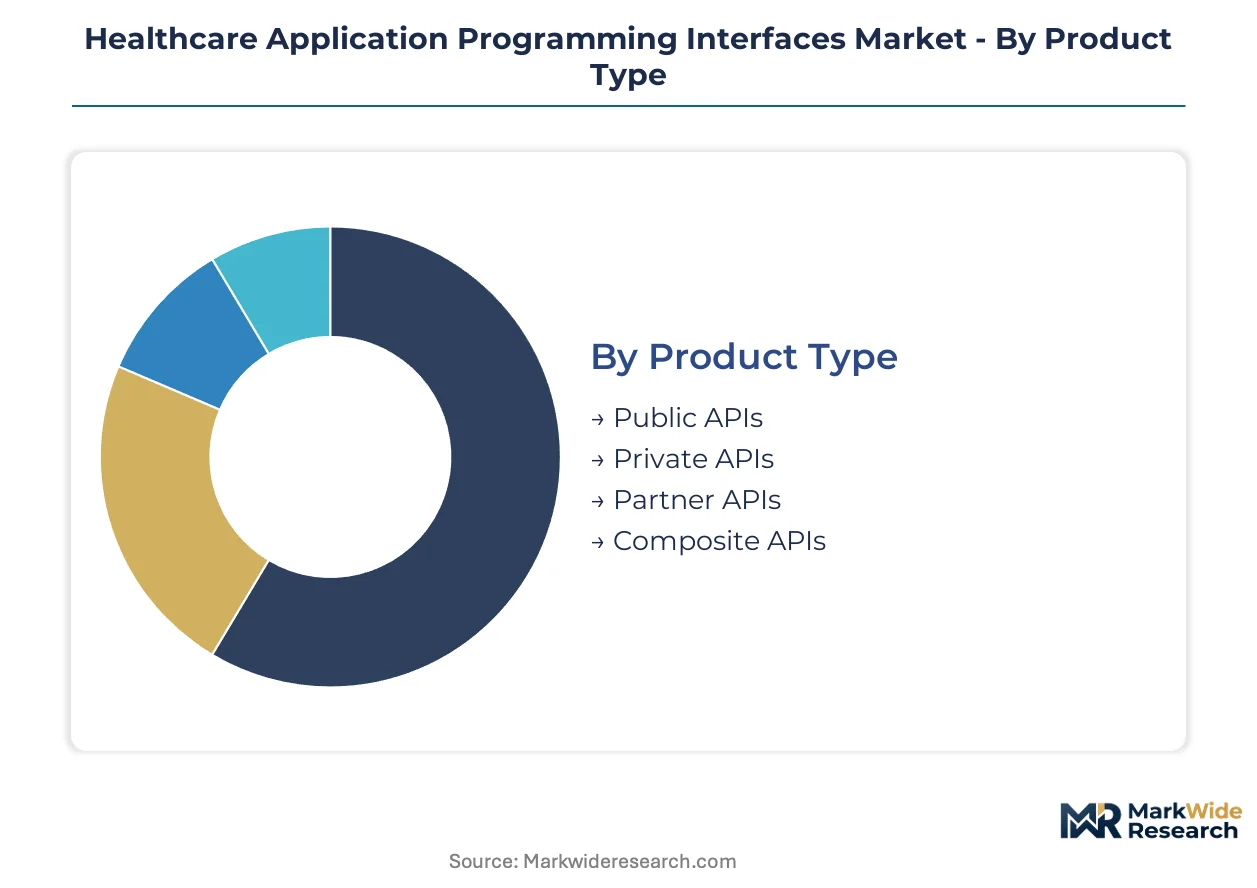
Healthcare API segmentation reveals how procurement priorities diverge across security models, architectural protocols, and infrastructure maturity levels. Understanding these divides exposes where vendor margins concentrate and which integration patterns health systems will retire versus reinforce.
Product Type:
Upgrade cycles in healthcare API procurement favor modular security architectures over monolithic platforms, pushing buyers toward composable endpoint strategies that isolate patient data exposure.
- Public APIs:These endpoints expose standardized FHIR resources to external developers through OAuth 2.0 authentication frameworks. Payer-provider data exchange in United States Medicare Advantage networks drives procurement volume, with CMS mandates forcing deployment timelines that compress vendor implementation windows.
- Private APIs:Dedicated infrastructure with customized security layers restricts access to internal clinical systems and vetted partners. Hospital networks in California and Texas prioritize these for protected health information workflows, accepting premium pricing to maintain audit trail control.
- Partner APIs:B2B integrations between EHR vendors and specialty application developers. These facilitate closed-loop referrals between acute and post-acute facilities without exposing full patient records.
- Composite APIs:Aggregated endpoints that orchestrate multiple backend services into unified responses. These reduce mobile application latency for remote patient monitoring dashboards.
Public APIs sit at the top of the volume ranking, with Composite APIs climbing the fastest as health systems consolidate fragmented point solutions.
Technology:
Architectural choices in healthcare API deployment increasingly hinge on mobile performance requirements and legacy system constraints rather than theoretical elegance.
- REST:HTTP-based stateless communication using JSON payloads dominates ambulatory care deployments. The simplicity of RESTful endpoints accelerates telehealth integration across rural health clinics lacking dedicated integration teams.
- SOAP:XML-based messaging with built-in security standards persists in enterprise EHR backbones. Large hospital systems in the Northeast retain these for HL7 v2 translation layers where message-level encryption remains non-negotiable.
- GraphQL:Query language allowing clients to request precise data structures. Emerging adoption in patient-facing applications where bandwidth constraints limit payload sizes on consumer mobile devices.
- WebSocket:Persistent bidirectional connections enabling real-time biometric streaming. Critical for ICU monitoring and surgical robotics where sub-second latency affects clinical decision-making.
REST commands the dominant share of new deployments, though WebSocket is gaining share fastest among academic medical centers building next-generation surgical platforms.
End User:
Buyer sophistication and procurement authority vary sharply across care settings, reshaping vendor sales motion from technical specification to compliance certification.
- Hospitals:Enterprise IT departments with dedicated integration teams and capital budgets. These buyers negotiate multi-year platform contracts anchored to EHR vendor relationships, prioritizing 24/7 uptime guarantees over per-transaction pricing.
- Clinics:Smaller ambulatory practices with limited technical staff. Federally qualified health centers in underserved regions drive demand for managed API services where vendors assume infrastructure burden.
- Diagnostic Labs:High-volume data generators requiring automated results distribution. These facilities prioritize bidirectional ordering interfaces that reduce manual entry errors in specimen processing workflows.
- Telehealth Providers:Virtual-first care models with cloud-native architectures. Behavioral health platforms represent the steepest expansion trajectory as interstate licensing compels multi-jurisdiction data routing capabilities.
Hospitals anchor procurement value, while Telehealth Providers are expanding most quickly as virtual care carve-outs proliferate in employer benefit designs.
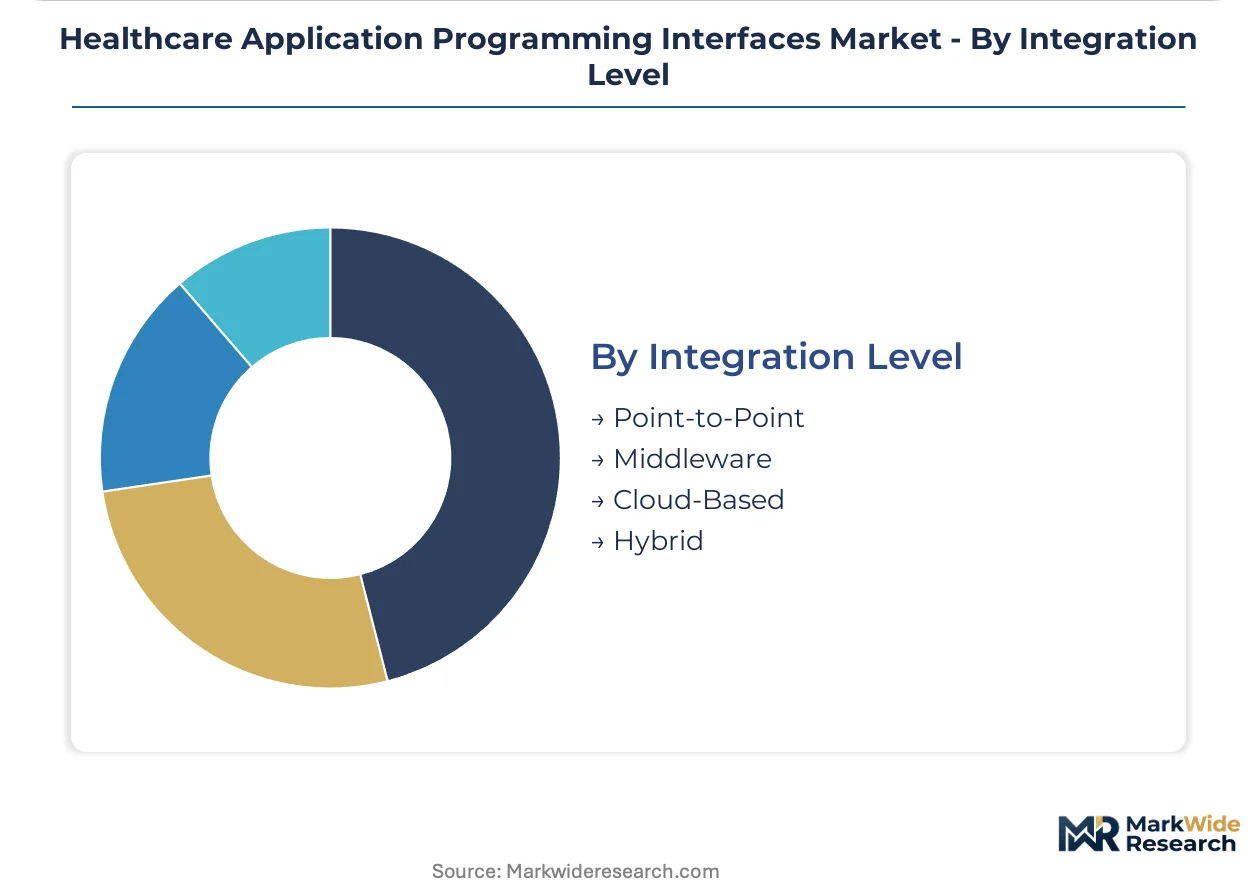
Integration Level:
Infrastructure decisions reflect technical debt accumulation and cloud migration status more than greenfield architectural preferences.
- Point-to-Point:Direct system-to-system connections without intermediary layers. Legacy laboratory information systems in community hospitals retain these despite maintenance burdens, as replacement costs exceed operational pain.
- Middleware:Translation engines resolving protocol mismatches between HL7 v2 and FHIR standards. These capture substantial project budgets as health systems bridge decades-old hospital information systems with modern endpoints.
- Cloud-Based:Serverless API gateways hosted on hyperscaler infrastructure. Regional health information exchanges in the Midwest favor these for elastic capacity during public health emergency surges.
- Hybrid:Mixed deployments preserving on-premises control for sensitive records while offloading non-clinical workloads. Large integrated delivery systems pursuing phased cloud migration adopt this architecture to manage risk exposure.
Middleware integration commands the largest current spend, with Cloud-Based deployment gaining share fastest as TEFCA implementation accelerates health information exchange consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater API procurement volume than Germany, reflecting divergent health system digitization timelines and regulatory enforcement intensity across these markets.
United States
Hospital consolidation and Medicare Advantage expansion drive enterprise API gateway procurement across integrated delivery networks. CMS patient access mandates and ONC information blocking rules compress vendor implementation timelines for FHIR R4 compliance. The Boston-Cambridge corridor anchors health IT innovation clusters where academic medical centers pilot edge computing integrations for surgical robotics.
Germany
Teilhabebericht federal digitization targets accelerate EHR interoperability investments across university hospital networks. The national pharmaceutical regulator enforces MDR compliance requirements for connected medical devices that stream biometric data through standardized endpoints. The Rhine-Ruhr metropolitan region concentrates health IT vendor development activity around Cologne and Düsseldorf enterprise software clusters.
United Kingdom
NHS England's Federated Data Platform procurement reshapes national API infrastructure standards for secondary care data exchange. The national pharmaceutical regulator enforces GDPR-aligned patient consent architectures that complicate cross-border data routing with European partners. London's King's Cross health tech corridor hosts emerging interoperability startups focused on primary care workflow integration.
Japan
Aging population demographics and hospital bed reduction targets pull remote patient monitoring API deployments into home care networks. METI's Society 5.0 framework subsidizes FHIR-based health information exchange pilots across prefectural hospital alliances. The Osaka-Kobe medical device manufacturing belt supplies IoT-enabled diagnostic equipment requiring real-time API connectivity for cloud analytics.
India
AB-PMJAY insurance expansion creates procurement demand for claims processing APIs linking public hospitals with regional payer systems. The national pharmaceutical regulator enforces data localization requirements that mandate domestic cloud infrastructure for patient records. Hyderabad's HealthTech Valley cluster concentrates API development talent serving Middle Eastern and Southeast Asian export markets.
Healthcare Application Programming Interfaces Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement segments in healthcare API markets. Enterprise cloud providers anchor high-volume platform contracts through bundled infrastructure offerings, while EHR-native vendors retain sticky integration relationships within hospital IT departments. Three strategic archetypes dominate: hyperscaler-backed platform generalists, EHR-embedded connectivity incumbents, and interoperability middleware specialists. Competitive positioning hardens around M&A-driven capability expansion and strategic partnership networks that pre-empt rival access to payer-provider data exchange workflows.
Among cloud infrastructure providers, Microsoft and Oracle exemplify platform generalists that extend enterprise software relationships into healthcare-specific API services. Epic Systems Corporation occupies a position within the EHR-native tier, anchoring proprietary integration frameworks that resist third-party disintermediation. Cerner Corporation represents the open-architecture alternative, situating within vendor ecosystems that accommodate external developer access.
| Leading Market Players |
|---|
| Microsoft |
| Apple Inc. |
| Epic Systems Corporation |
| GE HealthCare |
| Oracle |
| athenahealth Inc. |
| Cerner Corporation |
| eClinicalWorks |
| Greenway Health, LLC |
| Others |
Supply Flow & Price Mechanics
Hospital network procurement concentration in the United States favors consumption-based API pricing over perpetual licenses, compressing vendor margins while transferring infrastructure risk to hyperscaler-backed platforms. Medicare Advantage data exchange mandates accelerate this shift as merged delivery systems negotiate enterprise-wide contracts anchored to transaction volume tiers.
Pricing Analysis
Capacity additions in cloud infrastructure are reshaping price floors for healthcare API services as Microsoft, Oracle, and Amazon expand healthcare-specific offerings. Three-tier pricing structure across premium, standard, and economy levels separates dedicated private API deployments from shared public endpoints and basic FHIR gateway access. Cost compression in standard-tier middleware is intensifying because hyperscalers bundle API services with existing enterprise cloud commitments. Federally qualified health centers exhibit the highest price sensitivity, while academic medical centers building surgical robotics platforms accept premium positioning for sub-second latency guarantees.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale buyer demand for EHR-embedded API connectivity, while managed service routes serve clinic networks lacking integration teams. Software development talent concentrates in the United States, India, and Germany, with Hyderabad's HealthTech Valley and Boston-Cambridge corridor anchoring specialized health IT engineering pools. API gateway hardware draws from Taiwanese semiconductor fabrication, U.S.-based server assembly, and Irish data center infrastructure equipment. Single-source vulnerability in cloud infrastructure creates concentration risk as three hyperscalers host mission-critical clinical data exchange. Distribution runs through EHR vendor partnership programs, direct vendor sales teams, and health IT systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare API procurement has shifted toward late-cycle quality specifications as hospital networks prioritize FHIR R4 compliance certification and 24/7 uptime guarantees over lowest-cost vendor selection. Buyers now demand audit-ready security architectures that preempt ONC information blocking penalties.
For Market Incumbents: Deepen vertical integration into edge computing infrastructure to defend against cloud-native entrants targeting IoT medical device connectivity. Anchor enterprise relationships through multi-year platform contracts that bundle API services with EHR maintenance agreements. Invest in dedicated compliance engineering teams that embed interoperability certification into DevOps pipelines, neutralizing the threat of mid-market vendors offering faster implementation timelines.
For New Entrants and Emerging Players: Capture behavioral health platform integration as the most penetrable segment, where therapy notes and crisis intervention workflows lack standardized API coverage. Target Medicaid managed care states where budget volatility makes consumption-based pricing attractive to state agencies. Lead with managed API services that assume infrastructure burden for federally qualified health centers lacking technical staff.
For Investors and Strategic Acquirers: Hyperscaler strategic buyers are the most active acquirer in this space, seeking interoperability middleware specialists that resolve legacy HL7 v2 translation challenges. Long-term viability rests on vendors that bridge decades-old hospital information systems with modern FHIR endpoints rather than greenfield cloud-native architectures. Watch TEFCA framework implementation velocity as the signal indicating whether health information exchange consolidation accelerates or stalls.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 Certification Investment | ONC information blocking penalties now attach to access denials, compelling compliance-first engineering. |
| Hospital System Partnership | Epic and Cerner anchor procurement through embedded integration frameworks that resist disintermediation. |
| Software Companion Development | Remote patient monitoring dashboards require composite APIs that orchestrate multiple backend services. |
| Reimbursement Strategy Alignment | CMS Medicare Advantage rules create immediate demand for OAuth 2.0 authentication infrastructure. |
| Strategic Partnership Network | Microsoft extends Azure API for FHIR through existing enterprise software relationships with provider organizations. |
Methodological Framework
Coverage spans the United States, Germany, United Kingdom, Japan, and India, with primary inputs from each market's health IT procurement landscape. The analysis combines structured interviews with hospital CIOs, health system integration specialists, EHR vendor product managers, and GPO contracts managers with secondary validation against FDA 21st Century Cures Act guidance documents, ONC information blocking rule filings, CMS Medicare Advantage data exchange specifications, and hospital procurement database records. Bottom-up sizing of API transaction volumes triangulates against top-down health IT spending forecasts.
Segmentation modeling operates at the deployment model, security architecture, end-user facility type, and integration complexity levels across the projection horizon. CAGRs derive from fitted growth curves applied to vendor-reported implementation timelines and payer-provider data exchange volume trajectories. Forecast inputs include health system consolidation velocity, TEFCA framework adoption rates, and cloud infrastructure capacity expansion announcements.
Regulatory enforcement intensity, legacy system replacement cycles, and cybersecurity talent availability are the dominant revision risks that could alter trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Global E-Health Market
Health Informatics
EHR EMR Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Global Laboratory Information Management System (LIMS) Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
AI in Epidemiology Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
Healthcare Human Resources (HR) Software Market