
 Cannabinoid CB2 Products Market | 2026-2036
Cannabinoid CB2 Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabinoid CB2 Products Market Outlook
Specialty pharmaceutical buyers is collapsing into a narrower set of indication-focused prescribers as wellness retail consumers retreat from unregulated CB2 wellness claims. Cara Therapeutics leverages its kappa opioid receptor expertise to anchor clinical credibility in pruritus and pain programs. InMed Pharmaceuticals sustains rare cannabinoid biosynthesis capabilities that differentiate its supply position from agricultural extraction competitors.
Cannabinoid CB2 products comprise formulations engineered to modulate the G protein-coupled CB2 receptor without significant CB1 psychoactivity, typically involving synthetic or highly purified phytocannabinoid ligands with defined binding affinities below 100 nM Ki values for therapeutic selectivity. Their primary commercial purpose centers on immunomodulation and nociception pathways where peripheral receptor engagement avoids central nervous system liability. Oils currently dominate prescription volumes due to established titration protocols and pharmacy reimbursement familiarity, while transdermal delivery modes represent the fastest-expanding structural category as clinicians seek steady-state plasma profiles without hepatic first-pass metabolism. Neurological support applications remain early-phase with concentrated margin pools in orphan indication subsets rather than broad neurodegenerative claims.
FDA evaluates CB2-targeting drug candidates through the botanical drug development pathway with additional Controlled Substances Act scheduling reviews for cannabis-derived starting materials. Germany's BfArM maintains distinct narcotics licensing requirements under the Betäubungsmittelgesetz that constrain pharmacy distribution for certain cannabinoid formulations. Australia's TGA Schedule 8 controls and Special Access Scheme create parallel import and domestic manufacturing compliance layers. Stakeholders must monitor how evolving cannabinoid scheduling harmonization across FDA, EMA, and TGA frameworks reshapes cross-border clinical trial recruitment and commercialization sequencing.
Market Dynamics
The CB2 product landscape is compressing around pharmaceutical-grade selectivity as wellness retailers retreat from unregulated positioning, forcing manufacturers to demonstrate receptor-binding specificity below 100 nM Ki values to maintain prescriber credibility and pharmacy reimbursement access.
Growth Catalysts
- Peripheral receptor selectivity:Synthetic ligand engineering eliminates CB1 psychoactivity liability, enabling hospital formulary inclusion and pain management protocol adoption.
- Germany's BfArM narcotics licensing:Distinct approval pathways under the Betäubungsmittelgesetz create differentiated commercialization routes for non-psychoactive formulations.
- Transdermal delivery mode expansion:Steady-state plasma profiles without hepatic first-pass metabolism attract clinician preference in chronic pain applications.
Market Restraints
- Agricultural extraction cost volatility:Rare cannabinoid supply dependence on hemp biomass exposes margins to weather-driven input price swings.
- Controlled Substances Act scheduling friction:Cannabis-derived starting materials trigger DEA review layers that extend clinical trial initiation timelines.
- Recombinant biosynthesis substitution:Microbial production platforms threaten phytocannabinoid extraction economics at commercial scale.
Strategic Opportunities
- Australia's Special Access Scheme:Parallel import and domestic manufacturing compliance layers create early-mover positioning for orphan indication development.
- Neurological orphan subsets:Concentrated margin pools in pruritus and rare neurodegenerative conditions outyield broad therapeutic claims.
- Specialty pharmacy channel consolidation:Narrowing prescriber concentration enables targeted medical science liaison deployment and reimbursement navigation services.
Industry Challenges
- GPCR pharmacology talent scarcity:Limited pool of scientists with cannabinoid receptor allosteric modulation expertise constrains pipeline velocity.
- Botanical drug development pathway complexity:FDA's multi-component characterization requirements demand extended analytical validation timelines.
- Cross-border scheduling harmonization friction:Divergent EMA, FDA, and TGA cannabinoid classifications complicate multi-regional clinical trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabinoid CB2 Products Market |
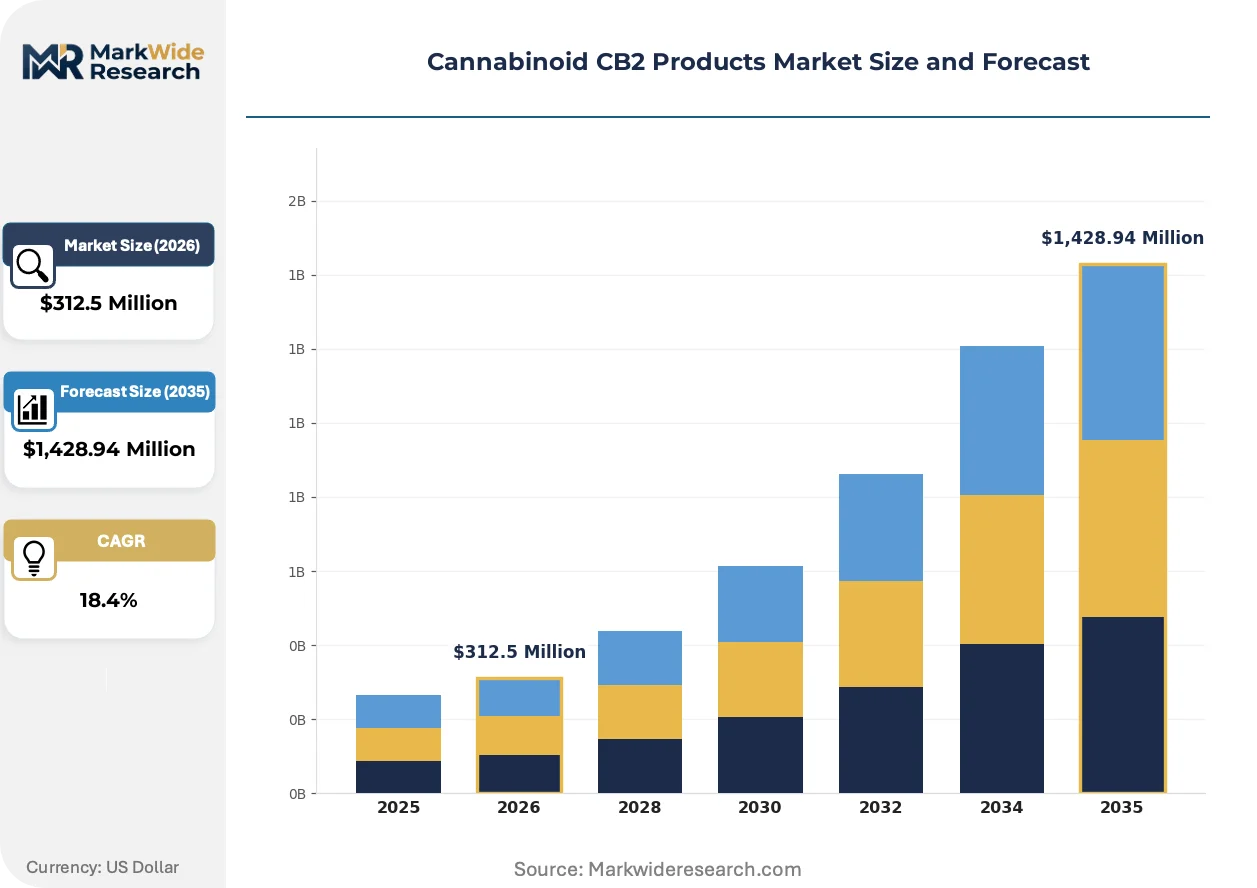
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,428.94 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Capsules, Topicals, Edibles Application: Pain Management, Inflammation Relief, Sleep Aid, Neurological Support Delivery Mode: Transdermal, Oral, Sublingual, Inhalation End User: Healthcare Providers, Retail Consumers, Pharmacies, Wellness Centers |
| Companies Covered | Cara Therapeutics, InMed Pharmaceuticals, Artelo Biosciences, IGC Pharma, Oxford Cannabinoid Technologies Holdings, SciSparc, Corbus Pharmaceuticals, Cardiol Therapeutics, Apurano Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabinoid CB2 Products Market Strategic Shifts
Receptor engineering and delivery modality advances are splitting the market between pharmaceutical precision and wellness commoditization, with regulatory differentiation determining which trajectory captures sustainable margin.
Synthetic CB2 ligand development is bifurcating the supply base between biosynthesis specialists and agricultural extractors. Pain management protocols in North American specialty pharmacies are adopting defined-binding-affinity formulations at accelerating rates. This selectivity standard is compressing wellness-oriented suppliers into commodity positioning while rewarding pharmaceutical-grade credentialing.
EMA's evolving cannabinoid scheduling harmonization discussions are reshaping cross-border trial recruitment strategies. Industrial sponsors must now sequence regulatory submissions across FDA botanical drug pathways and EMA centralized procedures to optimize approval timelines. Early-phase developers with EU manufacturing footprints are securing competitive positioning through parallel scientific advice procedures.
Hospital procurement systems are consolidating CB2 product selection around established titration protocols. Specialty pharmacy buyers are displacing wellness retail channels as the dominant volume path, with reimbursement familiarity determining formulary access. This channel rotation is most visible in Germany and Australia, where narcotics licensing frameworks privilege pharmaceutical distribution over direct-to-consumer models.
Cannabinoid CB2 Products Market Segmentation
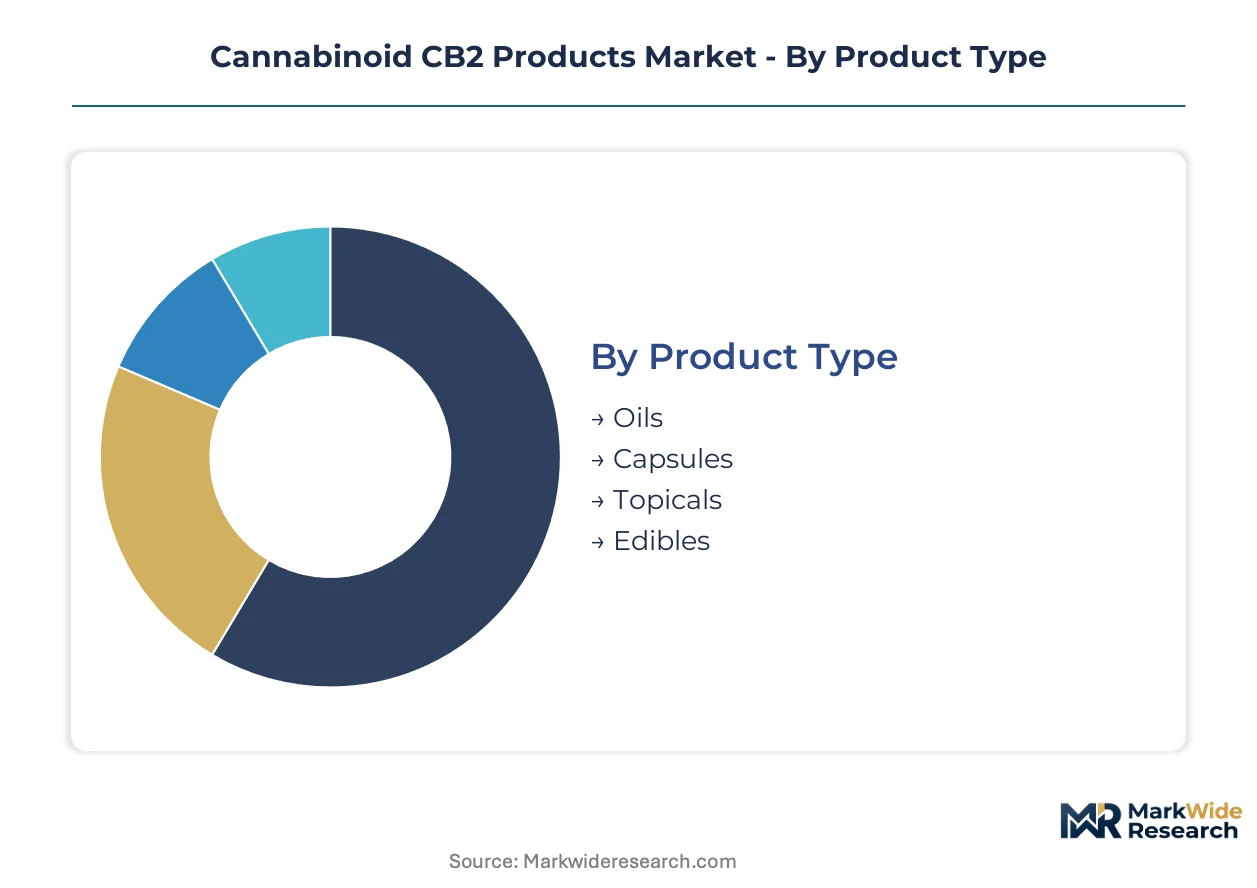
CB2 product segmentation reveals where pharmaceutical-grade selectivity commands premium pricing versus wellness commoditization erodes margins. Receptor-binding specificity and delivery precision determine which segments secure formulary access and reimbursement coverage.
Product Type:
Margin pools concentrate in formulations with defined analytical specifications and established titration protocols that satisfy pharmacy reimbursement requirements.
- Oils:Liquid formulations with standardized cannabinoid concentrations enable precise dose titration and carry established pharmacy reimbursement codes. Demand concentrates in North American specialty pharmacy channels where clinicians require flexibility in chronic pain management protocols.
- Capsules:Fixed-dose solid oral dosage forms provide batch-to-batch consistency critical for clinical trial enrollment and hospital formulary inclusion. German hospital procurement systems favor these for standardized pain management protocols under BfArM oversight.
- Topicals:Localized delivery systems target peripheral CB2 receptors in dermatological and musculoskeletal applications with minimal systemic exposure.
- Edibles:Food-matrix formulations face regulatory complexity around stability testing and controlled-substance diversion controls that limit pharmaceutical adoption.
The dominant share belongs to Oils, while Capsules is closing the gap fastest as hospital formularies prioritize fixed-dose standardization.
Application:
Volume distribution tracks directly to regulatory approval pathways and prescriber concentration in reimbursed therapeutic areas.
- Pain Management:Peripheral nociception modulation without CB1 psychoactivity liability attracts hospital pain protocol adoption and workers compensation coverage. United States specialty pharmacies drive volume through established prior authorization pathways for non-opioid alternatives.
- Inflammation Relief:Immunomodulation applications target cytokine pathway modulation with emerging clinical evidence in autoimmune subsets. Australian Special Access Scheme creates early-mover positioning for orphan inflammatory indications.
- Sleep Aid:Circadian and nociceptive interaction claims face wellness-commoditization pressure without robust polysomnography endpoints.
- Neurological Support:Neurodegenerative and pruritus applications concentrate in rare disease subsets where orphan drug economics justify development costs.
Pain Management holds the dominant position, though Inflammation Relief is expanding most quickly through autoimmune protocol adoption.
Delivery Mode:
Pharmacokinetic precision determines prescriber preference and formulary tier placement across acute and chronic therapeutic contexts.
- Transdermal:Steady-state plasma concentration profiles eliminate hepatic first-pass metabolism and enable around-the-clock dosing in chronic conditions. German pain clinics and Australian hospital systems are adopting these for opioid-sparing protocols.
- Oral:Gastrointestinal absorption routes carry established bioequivalence frameworks but variable onset limits acute pain utility.
- Sublingual:Buccal mucosa absorption offers intermediate onset with bypass of first-pass metabolism for rapid titration scenarios.
- Inhalation:Pulmonary delivery achieves rapid onset but faces respiratory safety scrutiny and controlled-substance diversion concerns that constrain pharmaceutical positioning.
Oral delivery retains the dominant share, yet Transdermal is gaining share fastest through chronic pain protocol expansion.
End User:
Channel economics split sharply between reimbursed healthcare procurement and direct-to-consumer wellness retail with divergent margin structures.
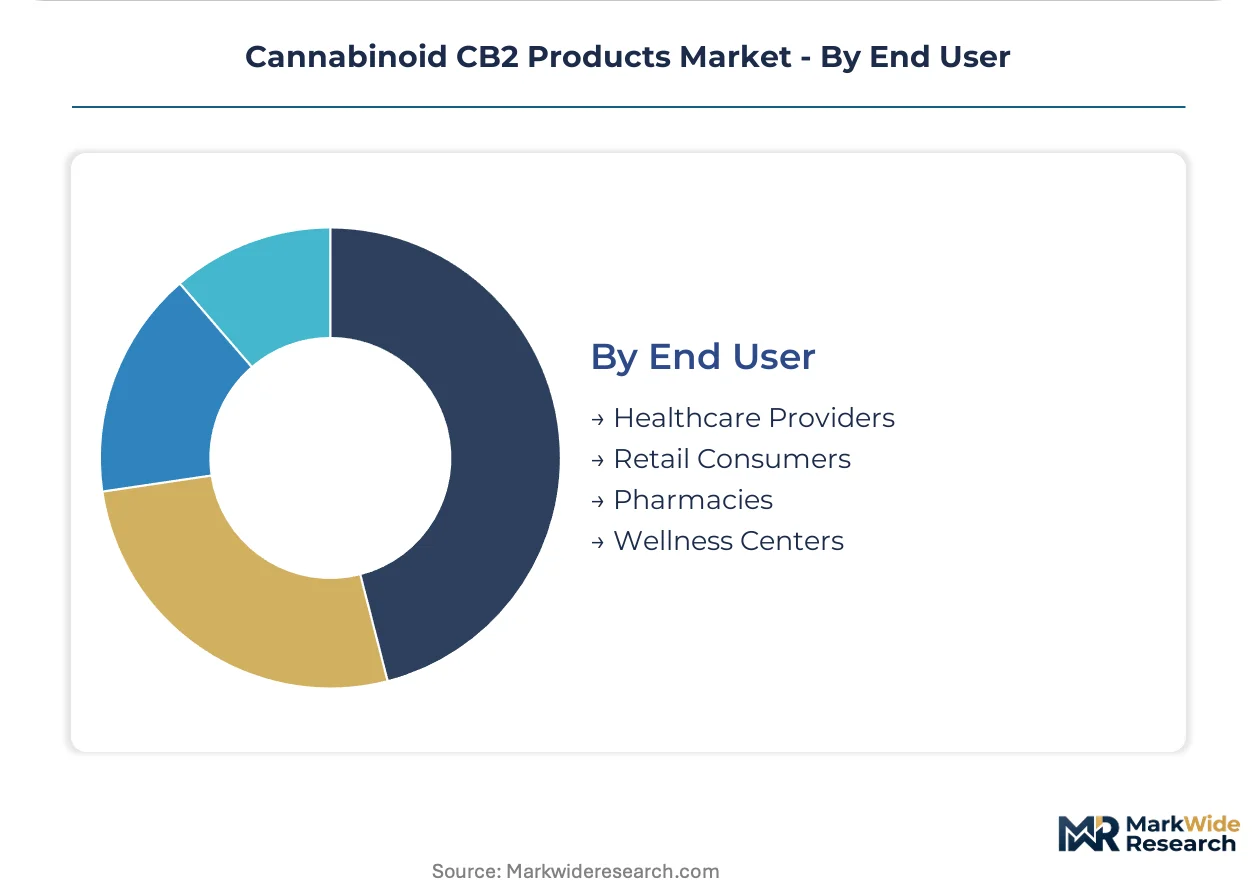
- Healthcare Providers:Hospital systems and pain clinics require documented receptor selectivity below 100 nM Ki values for formulary inclusion. United States academic medical centers and German university hospitals anchor pharmaceutical-grade demand.
- Pharmacies:Specialty and hospital pharmacy channels command reimbursement navigation expertise and medical science liaison support for prior authorization success.
- Retail Consumers:Direct-to-consumer wellness positioning faces regulatory retreat from unregulated CB2 claims and margin compression.
- Wellness Centers:Non-clinical service providers lack prescribing authority and reimbursement access, limiting sustainable volume.
Healthcare Providers capture the dominant share, while Pharmacies is climbing the fastest as specialty channel consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmaceutical buyers in the United States, Germany, and Australia concentrate procurement authority for CB2-targeting therapeutics, with hospital formulary committees and pain clinic networks filtering demand through receptor-selectivity standards.
United States
FDA botanical drug pathway reviews and DEA Controlled Substances Act scheduling create dual regulatory gates for cannabis-derived candidates. Academic medical centers in Massachusetts and California anchor clinical trial recruitment for peripheral pain indications. Specialty pharmacy networks in these states prioritize prior authorization pathways for non-opioid alternatives.
Germany
BfArM narcotics licensing under the Betäubungsmittelgesetz constrains pharmacy distribution for certain cannabinoid formulations while privileging non-psychoactive candidates. University hospitals in Berlin and Munich standardize pain management protocols around fixed-dose oral dosage forms. Hospital procurement systems in North Rhine-Westphalia consolidate purchasing around established titration protocols.
Australia
TGA Schedule 8 controls and the Special Access Scheme create parallel import and domestic manufacturing compliance layers for early-phase developers. Melbourne and Sydney host clinical research organizations specializing in orphan inflammatory indication trials. The country's narcotics licensing framework directs volume through pharmaceutical rather than wellness retail channels.
United Kingdom
MHRA licensing requirements and NHS reimbursement negotiations filter market access for CB2-targeting formulations. London-based biotech clusters concentrate rare cannabinoid biosynthesis capabilities. The country's specialized pain clinic networks in the Southeast prioritize peripheral receptor selectivity in formulary decisions.
Switzerland
Swissmedic's distinct narcotics control framework creates differentiated approval timelines for synthetic versus phytocannabinoid-derived candidates. Basel and Zurich anchor pharmaceutical manufacturing and clinical trial infrastructure. The country's hospital procurement systems favor documented receptor-binding specificity below 100 nM Ki values.
Cannabinoid CB2 Products Market Competitive Environment
Player mix skews toward clinical-stage biotechs with GPCR pharmacology expertise, creating a fragmented structure where no single entity commands dominant share. The competitive terrain splits between synthetic ligand engineers, rare cannabinoid biosynthesis specialists, and repurposed-agenda pharmaceutical developers. Strategic moves concentrate on receptor selectivity patent filings and transdermal delivery partnerships rather than capacity expansion.
Within the synthetic ligand engineering tier, Cara Therapeutics and Artelo Biosciences occupy positions anchored by peripheral receptor selectivity programs. InMed Pharmaceuticals exemplifies the rare cannabinoid biosynthesis archetype, differentiating supply economics from agricultural extraction competitors. These three entities represent the dominant strategic postures: kappa opioid receptor crossover expertise, defined-binding-affinity formulation development, and microbial production platform deployment.
| Leading Market Players |
|---|
| Cara Therapeutics |
| InMed Pharmaceuticals |
| Artelo Biosciences |
| IGC Pharma |
| Oxford Cannabinoid Technologies Holdings |
| SciSparc |
| Corbus Pharmaceuticals |
| Cardiol Therapeutics |
| Apurano Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Recombinant biosynthesis substitution for agricultural hemp extraction redraws supply geography toward microbial production facilities in Switzerland and Canada while collapsing price premiums previously sustained by rare cannabinoid scarcity. This input transition simultaneously erodes phytocannabinoid extraction margins and elevates synthetic ligand pricing power through receptor-selectivity credentialing.
Pricing Analysis
Cost-plus contracts with hemp biomass indexation dominate agricultural-derived supply agreements, while synthetic ligand pricing follows value-based models tied to Ki selectivity thresholds below 100 nM. Price differentiation rests on FDA botanical drug pathway certification and GMP manufacturing compliance rather than brand positioning. Pricing pressure intensifies in wellness retail channels as prescriber concentration funnels volume toward pharmaceutical-grade suppliers with documented bioequivalence. Hospital procurement managers exhibit lowest price sensitivity due to formulary standardization protocols, while wellness retailers face acute margin compression from regulatory retreat.
Supply Chain Analysis
Strategic stockpiling of hemp biomass characterizes agricultural-dependent producers facing weather-driven input volatility, whereas biosynthesis specialists maintain just-in-time microbial feedstock flows. Supply concentrates in Switzerland, Canada, and Germany for synthetic ligand manufacturing, with agricultural extraction anchored in United States hemp cultivation regions. Raw material dependencies span hemp biomass, yeast fermentation substrates, and chromatography resins for purification. Single-source vulnerability pervades rare cannabinoid supply where biosynthesis capacity remains concentrated among three specialized developers. Distribution runs through specialty pharmacy channels and hospital procurement systems rather than direct-to-consumer retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a regulatory-entrenchment defensive moat where DEA scheduling reviews and FDA botanical drug pathway compliance create multi-year barriers to competitive replication. Incumbents with established narcotics licensing and GMP manufacturing footprints capture sustainable margin pools.
For Market Incumbents: Secure receptor-selectivity patent estates in peripheral CB2 allosteric modulation to block biosynthesis competitor entry. Fortify transdermal delivery partnerships with German and Australian hospital systems before orphan indication protocols standardize. Vertical integration into microbial production platforms neutralizes agricultural extraction cost volatility threatening margin stability.
For New Entrants and Emerging Players: Medical science liaison service gaps in United States specialty pharmacy prior authorization navigation present exploitable white-space where incumbents under-resource reimbursement support. Target Australia's Special Access Scheme orphan inflammatory indications where regulatory familiarity concentrates among Melbourne clinical research organizations. Pursue licensing partnerships with established GMP manufacturers rather than greenfield facility investment.
For Investors and Strategic Acquirers: Capital is best deployed toward clinical-stage biotechs with demonstrated Ki selectivity below 100 nM and transdermal formulation partnerships already contracted. Long-term viability across the projection horizon hinges on regulatory scheduling harmonization rather than manufacturing scale. Watch DEA botanical substance review timelines as the critical inflection signal for portfolio rebalancing between synthetic and phytocannabinoid exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Peripheral pain indication enrollment accelerates hospital formulary adoption ahead of competitors. |
| Regulatory Approval Pathway | FDA botanical drug submission de-risks DEA scheduling friction for cannabis-derived candidates. |
| Manufacturing Scale-Up | GMP microbial production capacity secures supply economics against agricultural extraction volatility. |
| Pipeline Diversification | Pruritus and orphan neurodegenerative programs concentrate margin pools outside commoditized pain claims. |
| Strategic Partnership | Transdermal delivery collaborations with German pain clinics establish steady-state plasma protocol standards. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Primary interviews engaged drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and specialty pharmacy procurement managers. Secondary validation drew from SEC 10-K disclosures, BfArM narcotics licensing registers, TGA Special Access Scheme approvals, and customs trade data for hemp biomass flows. Bottom-up patient-volume modeling and top-down pharmaceutical spending allocation were triangulated against manufacturer-reported pipeline milestones.
Segmentation dimensions modeled span product type, application, delivery mode, and end user across the analysis window. Treatment line positioning, dosage form standardization, and regional regulatory cluster differentiation informed volume and value projections. CAGRs were derived from segment-level growth rate reconciliation against macro pharmaceutical spending trends. Forecast inputs incorporated DEA scheduling timeline assumptions, BfArM licensing velocity, and biosynthesis platform commercialization readiness.
Forecasts assume regulatory continuity in FDA botanical drug pathways, DEA Controlled Substances Act frameworks, and BfArM narcotics licensing regimes; material policy shifts would require re-modeling. Revision becomes warranted when DEA scheduling determinations for cannabis-derived candidates cross statutory review thresholds or when EMA-TGA harmonization discussions yield concrete implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Synthetic Cannabinoids Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Legal Cannabis Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market