
 Global Cannabis Extract Market | 2026-2036
Global Cannabis Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cannabis Extract Market Foresight
A capital-intensity divergence between fully integrated cultivator-extractors and contract processors is bifurcating competitive dynamics in the sector. Canopy Growth Corporation leverages its in-house biomass supply and extraction infrastructure across Canadian and international operations. Tilray Brands Inc. anchors its position through pharmaceutical-grade manufacturing certifications and European distribution reach. Curaleaf sustains scale advantages via controlled retail channels that secure offtake for extracted products.
Cannabis extract comprises concentrated bioactive compounds—primarily cannabinoids such as CBD and THC—derived from plant material through mechanical, chemical, or thermal processes, with purity grades ranging from crude resin to crystalline isolate exceeding 99%. These extracts serve pharmaceutical formulation, consumer wellness products, and regulated adult-use markets requiring standardized dosing and consistent potency profiles. CO2 extraction commands premium positioning due to solvent-free residue profiles and scalability for pharmaceutical-grade output, while solvent-based methods occupy cost-sensitive volume tiers. Pharmaceutical companies represent the most structurally attractive end-user segment, given their purchasing power and demand for GMP-certified supply chains that lock in multi-year contracts.
FDA enforcement discretion on CBD, combined with Health Canada's Cannabis Act licensing framework and Germany's BfArM narcotics scheduling reforms, collectively determines market access thresholds and product registration costs. EMA guidelines on cannabinoid-based medicines and state-level US THC regulations create a fragmented compliance landscape that favors operators with dedicated regulatory affairs capabilities. Stakeholders must monitor pending rescheduling decisions and evolving pharmaceutical reimbursement policies as the primary variables that will reshape competitive boundaries and capital allocation priorities.
Market Dynamics
Pharmaceutical procurement of GMP-certified cannabinoid isolates is compressing supply chains toward vertically integrated cultivator-extractors with captive biomass and in-house CO2 infrastructure, displacing contract processors dependent on spot-market feedstock.
Growth Catalysts
- Germany's BfArM narcotics rescheduling:The April 2024 reform enabling pharmacy distribution of cannabis extracts for medical use is unlocking institutional reimbursement pathways across German statutory health insurance funds.
- Supercritical CO2 extraction scaling:Equipment manufacturers are delivering throughput modules exceeding 10,000 kilograms daily, collapsing unit economics for pharmaceutical-grade isolate production.
- United States state-level THC legalization:Mature distribution infrastructure in Colorado, California, and Illinois is creating offtake certainty for extracted product volumes previously constrained by retail channel scarcity.
Market Restraints
- FDA CBD enforcement discretion:The agency's refusal to establish a regulatory pathway for non-pharmaceutical CBD ingestibles perpetuates interstate commerce uncertainty and deters CPG brand entry.
- Biomass supply concentration:Premium flower cultivation clusters in British Columbia, California, and the Netherlands control feedstock pricing for high-THC extract categories.
- Solvent residue testing thresholds:EMA pharmacopoeia standards for residual hydrocarbons below 50 parts per million impose capital burdens on ethanol and butane extraction operators seeking pharmaceutical certification.
Strategic Opportunities
- Brazil's ANVISA medical cannabis framework:The 2023 import authorization expansion for finished pharmaceutical products creates first-mover advantage for isolate suppliers with established GMP documentation.
- Minor cannabinoid isolation:CBG, CBN, and THCV extraction at scale is opening formulation white space in dermatology and sleep therapeutics previously monopolized by CBD and THC.
- Direct-to-clinic distribution:Bypassing wholesale intermediaries to supply compounding pharmacies and pain management clinics is capturing margin previously absorbed by multi-tier distribution.
Industry Challenges
- Analytical chemist scarcity:HPLC and mass spectrometry proficiency for cannabinoid quantification and terpene profiling remains concentrated among a limited pool of technicians trained in both cannabis matrices and pharmaceutical validation protocols.
- EU-GMP certification timelines:The 18-to-24-month audit and facility qualification process for European Medicines Agency compliance delays revenue recognition for extractors targeting pharmaceutical contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cannabis Extract Market |
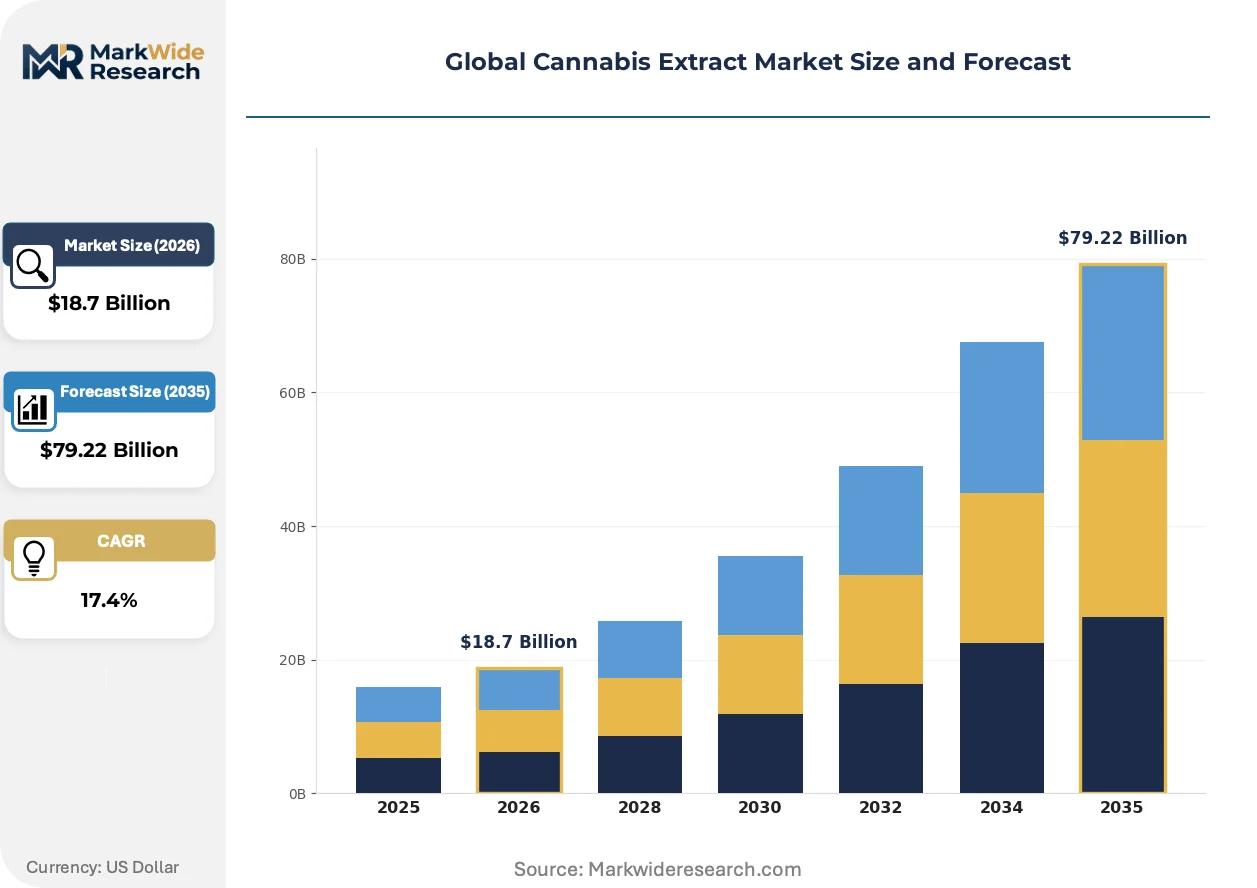
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $79.22 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CBD Oil, THC Concentrates, Hash, Tinctures, Vape Cartridges Extraction Technology: CO2 Extraction, Solvent-Based Extraction, Rosin Press, Steam Distillation, Ultrasonic Extraction End User: Pharmaceutical Companies, Personal Care Brands, Nutraceutical Firms, Research Institutions Application: Pain Management, Anxiety Relief, Sleep Aid, Skin Care, Appetite Stimulation |
| Companies Covered | Canopy Growth Corporation, Tilray Brands Inc., Aurora Cannabis Inc., Curaleaf, Green Thumb Industries, The Cronos Group Inc., Organigram Holdings Inc., Cresco Labs, Tikun Olam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cannabis Extract Market Shifts & Advancements
Extraction technology convergence with pharmaceutical manufacturing standards is compressing batch-to-batch variability while regulatory clarity in major jurisdictions is enabling institutional capital deployment previously constrained by policy ambiguity.
Supercritical CO2 extraction with integrated winterization and distillation is miniaturizing into skid-mounted units deployable at cultivation sites, enabling pharmaceutical manufacturers to secure captive supply chains without multi-year offtake negotiations with third-party processors.
Health Canada's Cannabis Act licensing amendments are mandating GMP-equivalent standards for all medical extract production, forcing legacy processors to retrofit facilities or exit the pharmaceutical segment entirely, with compliance costs favoring operators with existing quality management infrastructure.
Hospital and clinic procurement of standardized cannabinoid APIs is displacing bulk wholesale purchasing, as formulary committees demand certificate-of-analysis documentation and stability data that only vertically integrated extractors with in-house analytical laboratories can consistently deliver.
Global Cannabis Extract Market Segmentation
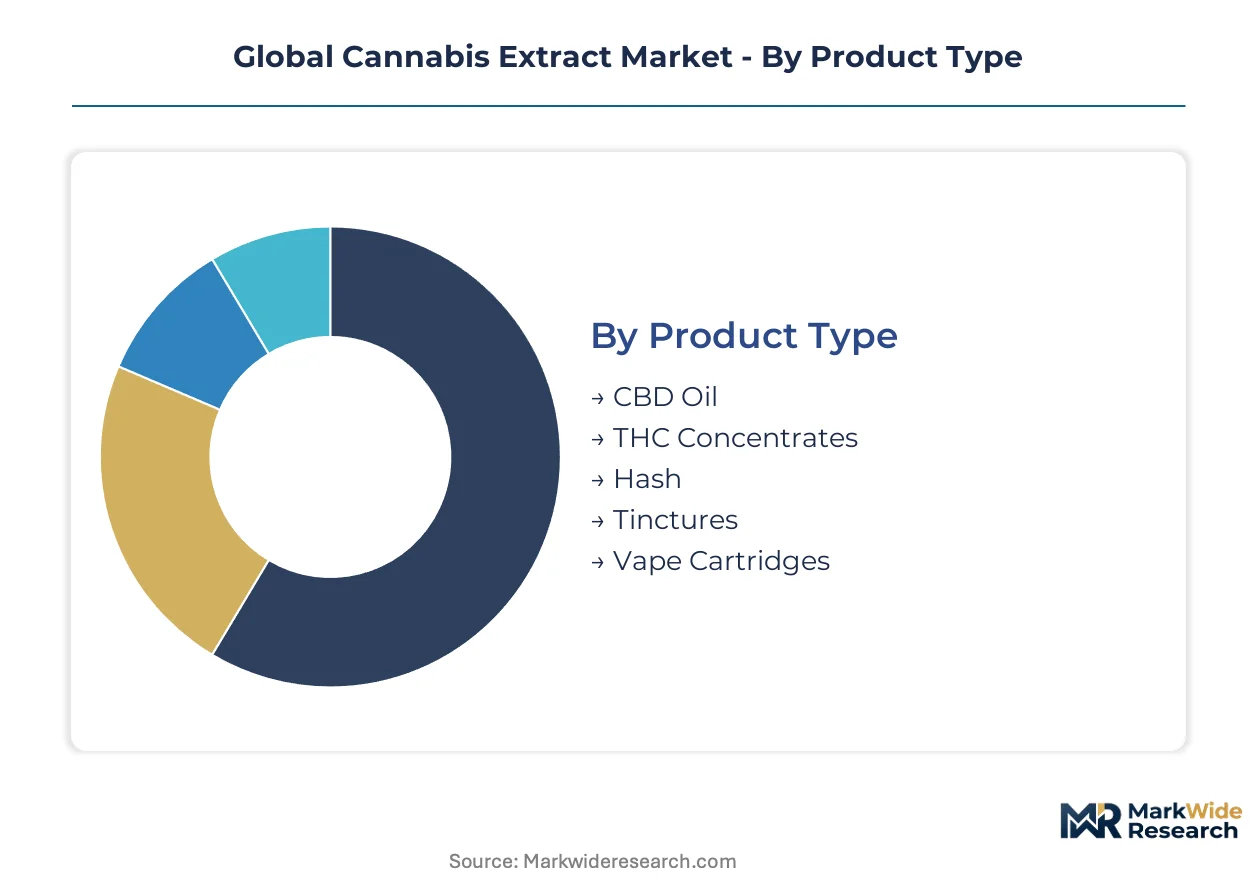
Cannabis extract segmentation reflects divergent regulatory pathways across jurisdictions, with pharmaceutical-grade isolates facing GMP certification requirements while wellness products navigate FDA enforcement discretion. Extraction technology and end-user specifications determine compliance thresholds and capital intensity for operators targeting specific revenue tiers.
Product Type:
FDA's refusal to establish a regulatory pathway for non-pharmaceutical CBD ingestibles creates a bifurcated compliance landscape where pharmaceutical-grade products command premium positioning against wellness-category alternatives.
- CBD Oil:Non-psychoactive cannabinoid formulations standardized to specific milligram concentrations, typically suspended in carrier oils for sublingual or topical delivery. Pharmaceutical procurement from Germany's BfArM-authorized suppliers is compressing supply chains toward vertically integrated cultivator-extractors with captive biomass and in-house CO2 infrastructure.
- THC Concentrates:High-potency resinous extracts containing delta-9-tetrahydrocannabinol as the primary active compound, ranging from waxes to crystalline isolates. Colorado and California state-level distribution infrastructure is creating offtake certainty for volumes previously constrained by retail channel scarcity.
- Hash:Traditional solventless concentrates produced through mechanical separation of trichomes from plant material. European adult-use markets in the Netherlands and Spain sustain demand for artisanal production methods.
- Tinctures:Alcohol-based or glycerin-based liquid extracts with standardized cannabinoid potency for precise dosing. Nutraceutical firms in the United States are the primary offtake channel pending FDA clarity on interstate commerce.
- Vape Cartridges:Pre-filled inhalation devices containing distilled cannabis oil with added terpenes for flavor profiles. Illinois and Michigan state regulations mandate heavy metal and residual solvent testing that favors CO2-extracted inputs.
CBD Oil handles the majority of throughput; THC Concentrates is the fastest mover on share.
Extraction Technology:
Capital deployment intensity separates scalable pharmaceutical-grade methods from artisanal approaches, with equipment throughput directly determining unit economics for isolate production.
- CO2 Extraction:Supercritical fluid processing using carbon dioxide as a tunable solvent for selective cannabinoid recovery. Equipment manufacturers are delivering throughput modules exceeding 10,000 kilograms daily, collapsing unit economics for pharmaceutical-grade isolate production in Canada and Germany.
- Solvent-Based Extraction:Hydrocarbon or ethanol processing for high-yield cannabinoid recovery from bulk biomass. EMA pharmacopoeia standards for residual hydrocarbons below 50 parts per million impose capital burdens on operators seeking pharmaceutical certification.
- Rosin Press:Mechanical extraction using heat and pressure to express resinous compounds without chemical solvents. California craft operators favor this method for premium flower inputs where terpene preservation justifies lower yields.
- Steam Distillation:Thermal separation for volatile terpene recovery prior to cannabinoid extraction. Personal care brands in France specify steam-distilled terpenes for fragrance compliance under ANSM guidelines.
- Ultrasonic Extraction:Cavitation-assisted processing for accelerated compound release at ambient temperatures. Research institutions in Switzerland utilize this method for minor cannabinoid preservation in analytical samples.
CO2 Extraction dominates pharmaceutical contract volumes; Solvent-Based Extraction retains cost-sensitive wellness segment leadership.
End User:
Purchasing power and quality documentation requirements stratify the customer base, with GMP-certified supply chains locking in multi-year pharmaceutical contracts against spot-market wellness sales.
- Pharmaceutical Companies:Formulators of cannabinoid-based medicines requiring API-grade isolates with certificate-of-analysis documentation and stability data. The 18-to-24-month EU-GMP audit timeline delays revenue recognition for extractors targeting German statutory health insurance reimbursement.
- Personal Care Brands:Cosmetic and dermatology product developers incorporating CBD and minor cannabinoids into topical formulations. Sephora and Ulta distribution partnerships in the United States are creating volume anchors for compliant suppliers.
- Nutraceutical Firms:Dietary supplement manufacturers navigating FDA enforcement discretion on CBD ingestibles. Health Canada's Cannabis Act licensing amendments are mandating GMP-equivalent standards that force legacy processors to retrofit facilities or exit.
- Research Institutions:Academic and clinical investigators studying cannabinoid pharmacokinetics and therapeutic mechanisms. ANVISA's 2023 import authorization expansion for finished pharmaceutical products in Brazil is creating first-mover advantage for isolate suppliers with established documentation.
Pharmaceutical Companies anchor contract value; Research Institutions are expanding most quickly on procurement volume.
Application:
Therapeutic indication drives formulation specifications and regulatory pathway selection, with pain management commanding the most mature clinical evidence base.
- Pain Management:Neuropathic and inflammatory pain formulations leveraging THC-CBD combination therapies. Germany's BfArM narcotics rescheduling enabling pharmacy distribution is unlocking institutional reimbursement across statutory health insurance funds.
- Anxiety Relief:CBD-dominant products targeting GABA modulation without psychoactive effects. The FDA's refusal to approve non-pharmaceutical CBD ingestibles perpetuates interstate commerce uncertainty for wellness-positioned suppliers.
- Sleep Aid:CBN and THC formulations for sleep latency and maintenance disorders. Direct-to-clinic distribution bypassing wholesale intermediaries is capturing margin previously absorbed by multi-tier distribution.
- Skin Care:Topical anti-inflammatory and sebum-regulation applications. CBG isolation at scale is opening formulation white space in dermatology previously monopolized by CBD.
- Appetite Stimulation:THC-based therapies for cachexia and eating disorder management. Health Canada maintains distinct regulatory requirements for medical versus adult-use appetite stimulation claims.
Pain Management handles the majority of clinical trial investment; Sleep Aid is gaining share fastest on minor cannabinoid formulation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmacy-distribution model for medical cannabis extracts diverges sharply from the United States' state-fragmented adult-use infrastructure, while Canada's integrated supply chain serves both pharmaceutical and wellness channels under federal licensing.
United States
Colorado, California, and Illinois operate mature distribution networks that absorb extracted product volumes previously constrained by retail scarcity. The FDA's evolving enforcement discretion on CBD interstate commerce perpetuates regulatory uncertainty for wellness-positioned suppliers. Los Angeles and Denver anchor concentrated processing capacity serving multi-state operators.
Germany
BfArM's April 2024 narcotics rescheduling unlocked statutory health insurance reimbursement for pharmacy-distributed cannabis extracts. EMA pharmacopoeia standards for residual solvents below 50 parts per million impose certification burdens on imported supply. Cologne and Berlin cluster pharmaceutical-grade extraction infrastructure serving statutory insurance funds.
Canada
Health Canada's Cannabis Act amendments mandate GMP-equivalent standards for medical extract production, forcing facility retrofits or segment exit. British Columbia's premium flower cultivation controls feedstock pricing for high-THC categories. Ontario and Alberta concentrate integrated cultivator-extractor operations with in-house CO2 infrastructure.
Brazil
ANVISA's 2023 import authorization expansion for finished pharmaceutical products creates first-mover positioning for GMP-documented isolate suppliers. Compounding pharmacies and pain management clinics emerge as direct distribution channels bypassing wholesale intermediaries. São Paulo anchors demand concentration for medical cannabinoid formulations.
Switzerland
Swissmedic's narcotics licensing framework permits low-THC cannabis extract commerce with distinct regulatory treatment from high-THC medical products. Research institutions in Basel and Zurich drive minor cannabinoid isolation for dermatology applications. The country's pharmaceutical manufacturing heritage supports GMP-certified supply chain development.
Global Cannabis Extract Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital intensity bifurcating between cultivator-extractors with captive biomass and contract processors dependent on spot-market feedstock. The sector exhibits tiered consolidation around pharmaceutical certification holders versus wellness-category commodity suppliers. Three archetypes dominate: vertically integrated Canadian operators with international reach, US multi-state operators controlling retail offtake, and Israeli research-linked specialists with clinical trial heritage. Competitive moves concentrate on EU-GMP certification pursuit for German pharmaceutical contracts and supercritical CO2 capacity expansion for isolate unit economics.
Within the integrated Canadian tier, Canopy Growth Corporation and Tilray Brands Inc. exemplify operators leveraging in-house biomass and extraction infrastructure across federal jurisdictions. Curaleaf anchors the US multi-state operator archetype through controlled retail channels that secure offtake certainty for extracted products. These three entities represent divergent geographic and regulatory positioning strategies within a market where pharmaceutical-grade certification increasingly separates premium-tier suppliers from wellness-commodity competitors.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Tilray Brands Inc. |
| Aurora Cannabis Inc. |
| Curaleaf |
| Green Thumb Industries |
| The Cronos Group Inc. |
| Organigram Holdings Inc. |
| Cresco Labs |
| Tikun Olam |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German statutory health insurance funds and GMP-certified extractors lock in both biomass supply access and price visibility across multi-year horizons, insulating pharmaceutical-grade operators from spot-market volatility while compressing margins for contract processors dependent on feedstock spot purchases.
Pricing Analysis
After-sales revenue from stability data packages and certificate-of-analysis documentation drives lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across EU-GMP certified, Health Canada equivalent, and wellness-grade tiers reflects certification investment and analytical capability. Cost compression in wellness-grade CBD oil intensifies because FDA enforcement discretion perpetuates interstate commerce barriers. Nutraceutical firms exhibit highest price sensitivity; pharmaceutical formulators prioritize supply security over unit cost.
Supply Chain Analysis
Canada and Germany anchor pharmaceutical-grade extraction infrastructure, while California and Colorado concentrate high-THC processing capacity. Supercritical CO2 equipment, analytical instrumentation, and GMP-certified facility qualification draw from specialized manufacturing bases in Switzerland and the United States. Single-source vulnerability in premium flower biomass from British Columbia and the Netherlands creates feedstock pricing volatility. Distribution runs through pharmacy channels in Germany, controlled retail in US state markets, and direct-to-clinic models in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as regulatory clarity in Germany and Brazil unlocks institutional capital deployment previously constrained by policy ambiguity.
For Market Incumbents: Fortify EU-GMP certification moats through accelerated facility qualification timelines to capture German statutory insurance reimbursement contracts. Expand captive biomass cultivation in British Columbia and Ontario to reduce feedstock spot-market exposure. Prioritize analytical laboratory capacity to meet formulary committee documentation demands.
For New Entrants and Emerging Players: Differentiate on minor cannabinoid isolation capabilities targeting CBG and CBN formulation white space in dermatology and sleep therapeutics. Brazil's ANVISA import authorization expansion represents the most penetrable geography for GMP-documented isolate suppliers. Pursue direct-to-clinic distribution partnerships with compounding pharmacies to bypass wholesale margin absorption.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated cultivator-extractors with existing Health Canada licensing and in-house CO2 infrastructure. Long-term viability over the next decade hinges on pharmaceutical contract anchoring rather than wellness-category commodity positioning. Monitor FDA rescheduling deliberations as the primary inflection signal for US interstate commerce normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Pursuit | Unlocks German statutory health insurance reimbursement pathways for pharmacy-distributed extracts. |
| Supercritical CO2 Capacity Expansion | Collapses unit economics for pharmaceutical-grade isolate production in Canada and Germany. |
| Minor Cannabinoid Isolation Scale-Up | Opens formulation white space in dermatology and sleep therapeutics beyond CBD and THC. |
| Direct-to-Clinic Distribution Buildout | Captures margin previously absorbed by multi-tier wholesale intermediaries in Brazil and Germany. |
| Captive Biomass Cultivation Integration | Secures feedstock supply certainty against British Columbia and California spot-market volatility. |
Research Methodology
The analysis maps pharmaceutical-grade isolates, wellness-category extracts, and minor cannabinoid formulations, each validated through extraction technology providers, regulatory affairs consultants, and pharmaceutical procurement managers. Primary interviews with GMP facility operators, cannabis cultivation executives, and formulary committee members combined with secondary validation against Health Canada licensing databases, EMA submission records, and ANVISA import authorization filings. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. Segmentation dimensions include extraction technology tier, end-user purchasing power, and application therapeutic indication. CAGRs derived from installed capacity trajectories, regulatory pathway timelines, and reimbursement policy evolution. Forecast inputs incorporate supercritical CO2 equipment throughput scaling and EU-GMP audit completion rates.
Material uncertainties — FDA rescheduling decisions, German narcotics framework amendments, and biomass supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and certification timeline stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Trichome Separator/Extractor Market
Cannabis/Marijuana
Missouri Legal Cannabis Market
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
Africa Medical Cannabis Market