
 Europe CBD Oil Market | 2026-2036
Europe CBD Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Europe CBD Oil Market Intelligence
Pharmacy distribution channels across Europe are reconfiguring as national regulators clarify CBD's legal status for human consumption. Candropharm leverages its GMP-certified extraction infrastructure to supply compound pharmacies in German-speaking markets. Endoca anchors its position through vertically controlled hemp cultivation in Denmark, ensuring batch traceability from seed to oil. Sanobiotec competes on biosynthetic cannabinoid research, differentiating its pipeline from agricultural-derived competitors.
CBD oil comprises hemp-derived cannabidiol extract suspended in a carrier oil, typically containing specified concentrations of active cannabinoids alongside controlled tetrahydrocannabinol levels below regulatory thresholds. Full spectrum formulations retain the complete phytocannabinoid profile including trace terpenes and flavonoids, commanding premium positioning in wellness retail. Healthcare providers increasingly specify CBD isolate for therapeutic applications where THC content must reach absolute zero, creating a bifurcated demand structure between wellness and clinical segments. Online retailers represent the fastest-growing distribution channel, though pharmacy sales sustain higher margin pools due to professional endorsement requirements.
EMA guidance on cannabinoid-based medicines and the EU Novel Food Catalogue shape product compliance pathways, while REACH and national food safety agencies enforce purity and labeling standards. Germany's BfArM and the Netherlands' Office of Medicinal Cannabis operate contrasting licensing models that fragment market access rules. Stakeholders must monitor pending harmonization efforts under the EU Green Deal's bioeconomy framework and anticipate how national transpositions of the CSRD will mandate supply chain disclosure for hemp-derived inputs.
Market Dynamics
The EU Court of Justice's 2020 ruling that CBD is not a narcotic continues to fracture national licensing frameworks, forcing pharmaceutical distributors to rebuild compliance architectures around divergent BfArM, OMC, and ANSM interpretations.
Growth Catalysts
- EMA Guidance on Cannabinoid Medicines:Clarified quality standards for pharmaceutical-grade formulations accelerate hospital formulary inclusion in Germany and the Netherlands.
- Wellness Retail Penetration:French and British consumers deepen familiarity with full-spectrum products, expanding addressable demand beyond clinical applications.
- Denmark:Vertically controlled hemp cultivation infrastructure enables batch traceability from seed to oil, satisfying REACH disclosure requirements.
Market Restraints
- Input Cost Volatility:Organic hemp biomass prices fluctuate with weather-induced yield compression in Eastern European growing regions.
- Regulatory Friction:The EU Novel Food Catalogue classification dispute blocks product entry in member states pending EFSA safety assessments.
- THC Threshold Divergence:National limits ranging from 0.2% to 0.3% THC fragment formulation standardization across Germany, France, and Italy.
Strategic Opportunities
- Poland:Underdeveloped pharmacy channel penetration offers first-mover positioning as national regulators clarify CBD's legal status.
- Biosynthetic Production:Precision fermentation technologies converge with pharmaceutical GMP standards to enable THC-free isolate at industrial scale.
- CSRD Supply Chain Disclosure:Pending EU Green Deal bioeconomy mandates create competitive advantage for vertically traceable hemp sourcing.
Industry Challenges
- Analytical Chemistry Talent Gap:Shortage of phytocannabinoid quantification specialists delays batch release timelines for pharmaceutical clients.
- Certification Timeline Compression:REACH registration and EFSA novel food approval cycles extend 18-36 months, locking working capital in pre-revenue inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe CBD Oil Market |
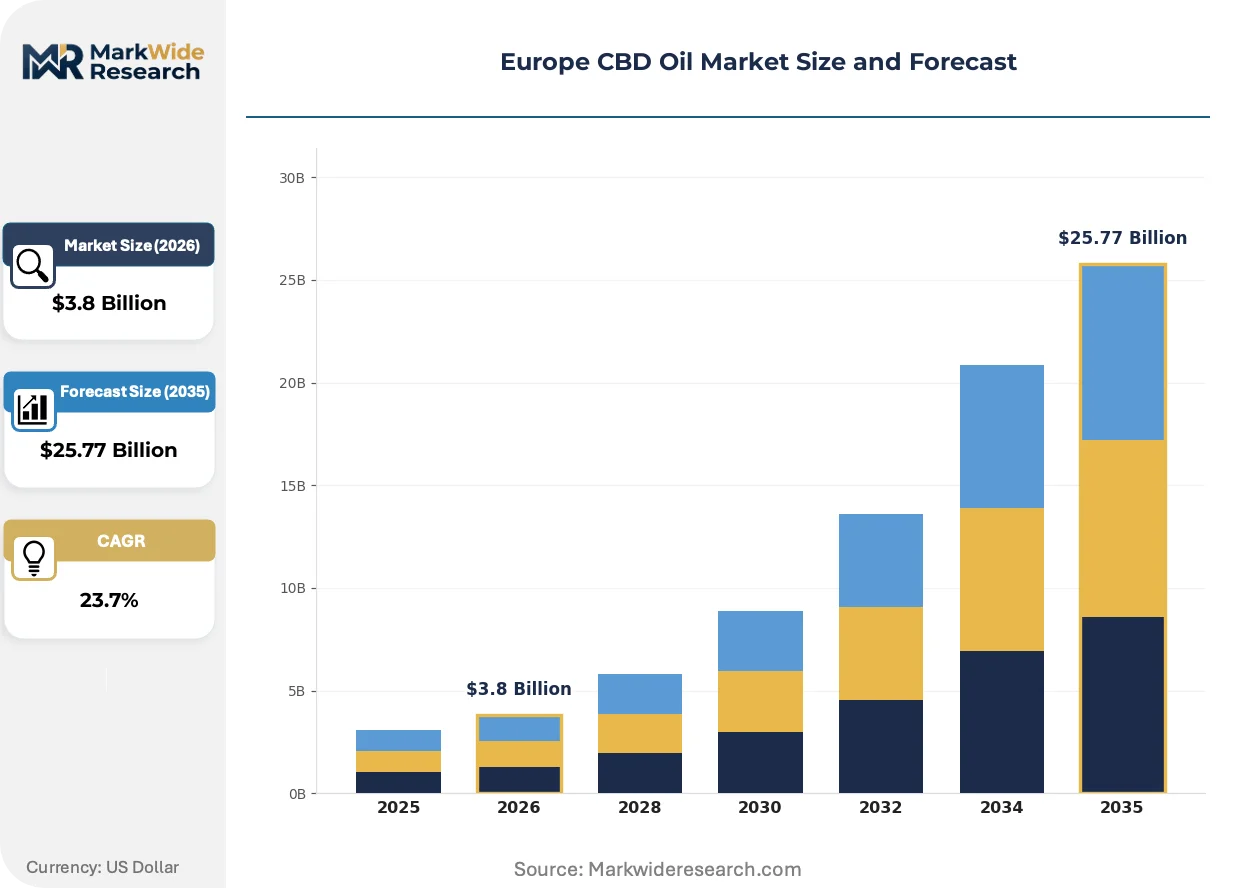
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Spectrum, Broad Spectrum, CBD Isolate, CBD Distillate End User: Retail Consumers, Healthcare Providers, Wholesalers, Online Retailers Application: Health Supplements, Skincare Products, Food & Beverages, Therapeutics Distribution Channel: Online Sales, Retail Stores, Distributors, Pharmacies |
| Companies Covered | Sanobiotec, Candropharm, Essentia Pura, Cibdol, Endoca, Pure Production AG, Green Exchange Lab, Formula Swiss, HemPoland, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe CBD Oil Market Strategic Shifts & Innovations
Extraction technology maturation and regulatory clarity are compressing the gap between agricultural commodity and pharmaceutical ingredient, reshaping competitive positioning around purity verification and chain-of-custody documentation.
Supercritical CO2 extraction systems with inline chromatographic separation are virtualizing traditional ethanol-based processing. German pharmaceutical compounders adopt these platforms to achieve EU GMP Annex 1 compliance for sterile cannabinoid preparations. The technology is virtualizing batch-to-batch variability, enabling specification-grade supply contracts previously impossible with agricultural-derived inputs.
REACH enforcement on residual solvent limits tightens purity thresholds for all hemp-derived extracts entering European commerce. ECHA's 2023 updated guidance on chronic toxicity testing forces reformulators to abandon legacy hexane extraction methods. Full-spectrum wellness brands face the steepest compliance costs, driving consolidation toward integrated extraction-cum-testing facilities.
Healthcare procurement teams now specify CBD isolate over full-spectrum formulations for therapeutic applications requiring absolute THC absence. Hospital pharmacy committees in the Netherlands and Germany rewrite formularies around pharmacokinetic consistency rather than entourage effect claims. This specification shift concentrates contract awards among suppliers with dedicated pharmaceutical manufacturing licenses.
Europe CBD Oil Market Segmentation
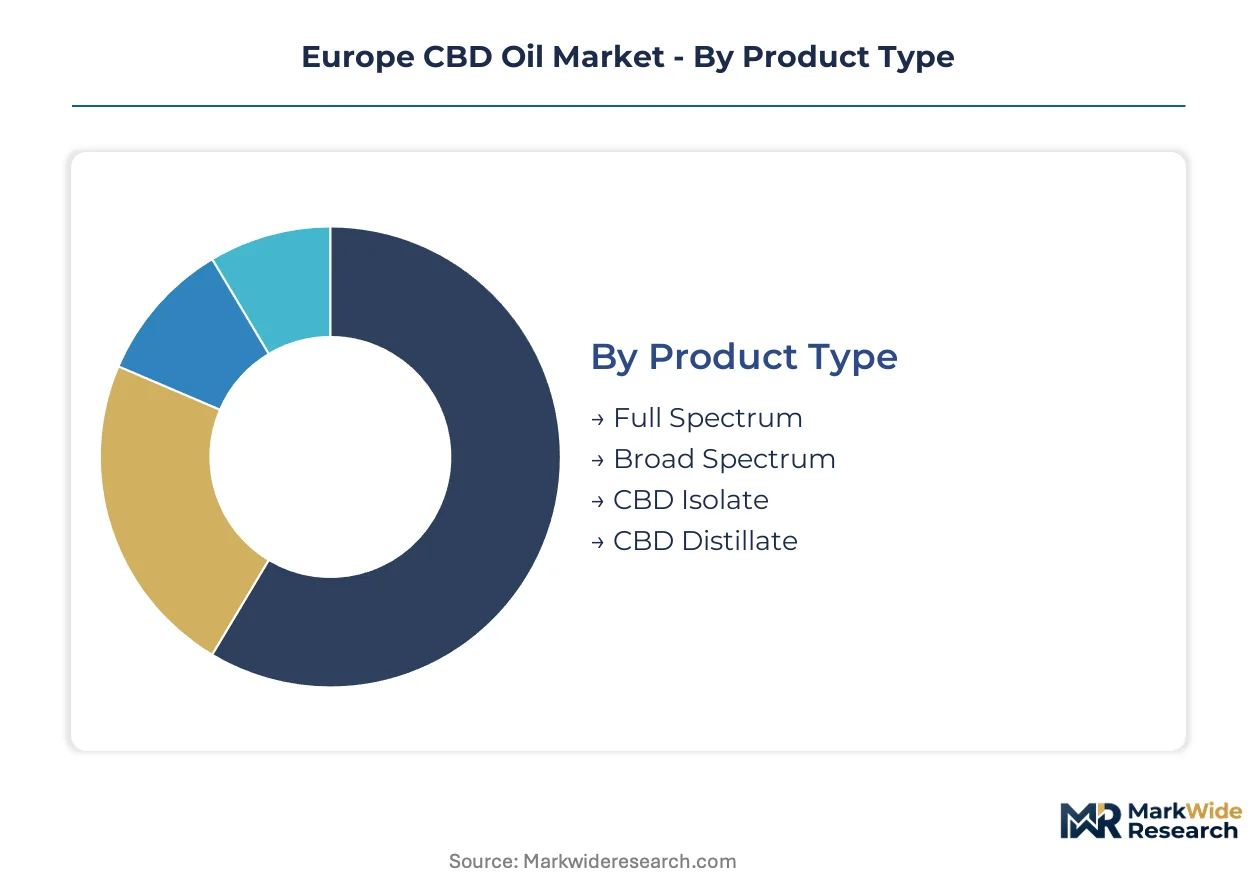
Segmentation reveals how formulation chemistry, procurement authority, and channel economics split the European CBD oil market into distinct competitive arenas. Each dimension carries divergent margin profiles and compliance burdens that reshape supplier strategy across Germany, France, and the Netherlands.
Product Type:
Cost tier differentiation separates commodity-grade extracts from specification-controlled pharmaceutical inputs, with purity verification driving price multiples.
- Full Spectrum:Retains complete phytocannabinoid profile including trace terpenes and flavonoids below 0.2% THC thresholds. French and British wellness retailers command premium positioning where consumers seek entourage effect benefits, though REACH solvent residue limits tighten extraction compliance costs.
- CBD Isolate:Crystalline powder achieving 99%+ cannabidiol purity with absolute THC absence. Hospital pharmacy committees in Germany and the Netherlands specify isolate for therapeutic applications requiring pharmacokinetic consistency, displacing full-spectrum formulations from clinical procurement.
- Broad Spectrum:THC-free formulation retaining select minor cannabinoids and terpenes for enhanced therapeutic profile without narcotic classification risk.
- CBD Distillate:Semi-refined extract containing 70-85% cannabidiol with controlled cannabinoid ratios, serving intermediate processing demand from cosmetic and nutraceutical formulators.
Full Spectrum holds installed capacity. CBD Isolate is rotating up the share rankings.
End User:
Customer type determines specification rigor, with professional procurement demanding chain-of-custody documentation that retail channels rarely require.
- Healthcare Providers:Hospital pharmacy committees and compound pharmacies in German-speaking markets enforce EU GMP Annex 1 compliance for sterile cannabinoid preparations. EMA guidance on cannabinoid medicines accelerates formulary inclusion where batch-to-batch variability is virtualized through chromatographic separation.
- Online Retailers:Direct-to-consumer platforms bypass pharmacy margin pools but face national food safety agency enforcement on novel food classification. The channel gains share fastest where regulators delay clarity on CBD's legal status for human consumption.
- Retail Consumers:Individual purchasers seeking wellness applications with limited technical specification knowledge, price-sensitive to full-spectrum premium positioning.
- Wholesalers:Intermediate distributors aggregating volume across fragmented brand portfolios, exposed to THC threshold divergence between 0.2% and 0.3% national limits.
Healthcare Providers concentrate contract awards. Online Retailers are climbing the fastest in volume terms.
Application:
Application scope defines the regulatory pathway, with therapeutics facing EMA medicinal product classification while wellness categories navigate novel food disputes.
- Therapeutics:Pharmaceutical-grade formulations targeting specific medical indications under centralized marketing authorization procedures. BfArM and the Netherlands' Office of Medicinal Cannabis operate contrasting licensing models that fragment market access for prescription-grade products.
- Skincare Products:Cosmetic applications bypass novel food classification but face REACH enforcement on residual solvent limits and ECHA chronic toxicity testing requirements for dermal exposure.
- Health Supplements:Nutraceutical positioning in regulatory gray zone pending EFSA safety assessments, with member state divergence blocking harmonized entry.
- Food & Beverages:EU Novel Food Catalogue classification dispute locks working capital in pre-revenue inventory across 18-36 month approval cycles.
Therapeutics concentrates R&D investment. Skincare Products are advancing fastest in commercial deployment.
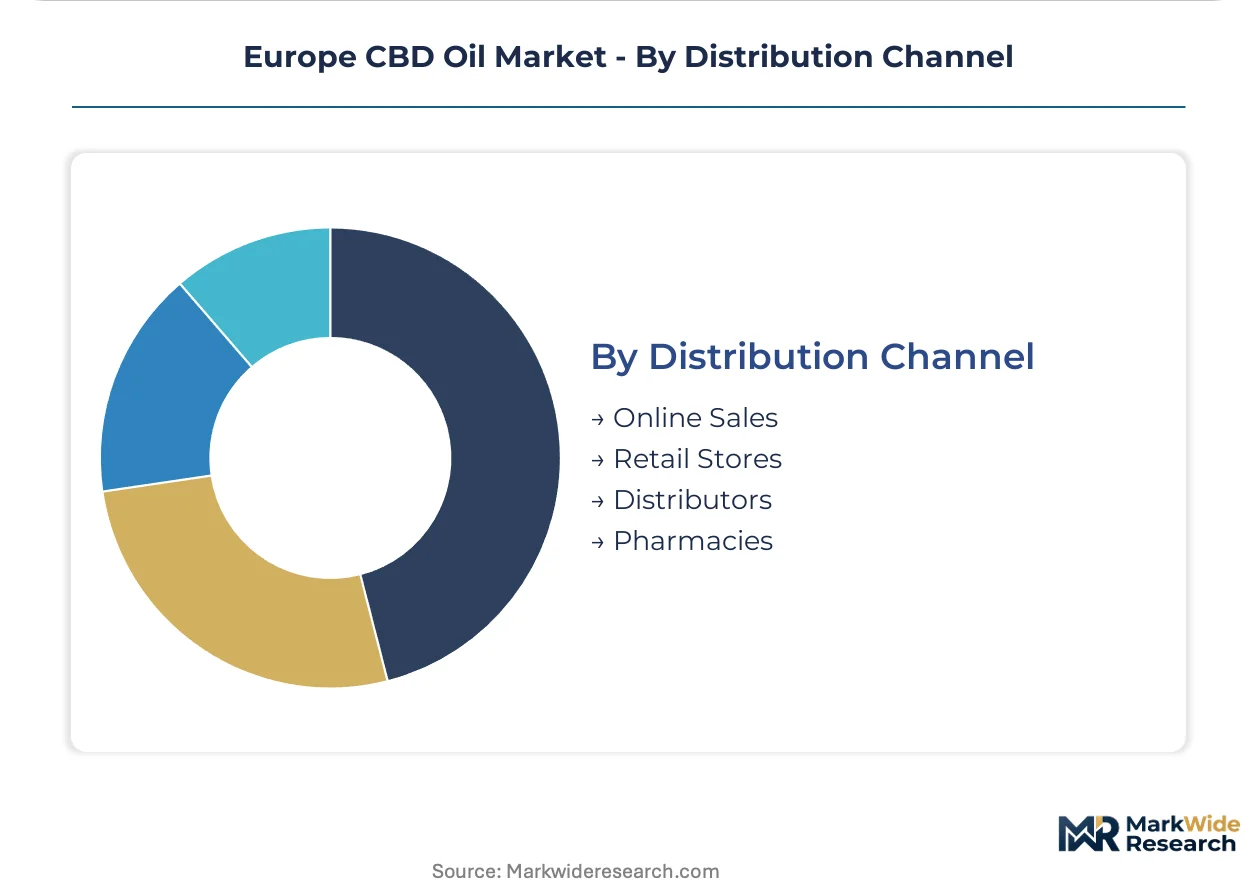
Distribution Channel:
Channel selection determines margin capture and professional endorsement access, with pharmacies sustaining premium pools despite online volume expansion.
- Pharmacies:Professional endorsement requirements and GMP-certified supply contracts sustain higher margin pools in Germany and the Netherlands. Candropharm leverages GMP extraction infrastructure to serve compound pharmacy demand in German-speaking markets.
- Online Sales:Platform economics enable rapid geographic expansion where national regulators clarify CBD's legal status, though professional credibility remains absent from the transaction.
- Retail Stores:Wellness-focused brick-and-mortar presence in France and the United Kingdom where consumer familiarity with cannabinoid products deepens through tactile brand experience.
- Distributors:Logistics intermediaries managing THC threshold compliance across fragmented national regulations, adding cost without value capture for originators.
Pharmacies retain margin leadership. Online Sales are expanding most quickly in addressable reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network underwrites Germany's central role in European CBD oil distribution, connecting Rotterdam's hemp import terminals to pharmaceutical manufacturing clusters across the continent.
Germany
Hospital pharmacy committees in Cologne and Berlin drive specification-grade demand for THC-free isolates. BfArM operates Europe's most structured licensing pathway for cannabinoid medicines, requiring EU GMP Annex 1 compliance for sterile preparations. The North Rhine-Westphalia chemical corridor hosts supercritical CO2 extraction facilities serving compound pharmacies across German-speaking markets.
Netherlands
Amsterdam's logistics hub concentrates wholesale distribution for wellness-grade full-spectrum oils entering French and British retail channels. The Office of Medicinal Cannabis maintains a contrasting licensing model to Germany's BfArM, fragmenting market access rules for pharmaceutical distributors. Rotterdam's hemp biomass import terminals supply extraction facilities in the Randstad metropolitan region.
France
Parisian wellness retailers command premium positioning for entourage-effect products among consumers with deepening cannabinoid familiarity. ANSM maintains stricter THC thresholds than neighboring jurisdictions, forcing reformulation for cross-border products. The Île-de-France region anchors cosmetic applications where REACH dermal exposure standards shape skincare formulation trends.
United Kingdom
London's FSA novel food pre-market consultation process locks working capital in extended approval cycles for ingestible CBD products. Online retail platforms based in the Southeast bypass pharmacy margin pools while navigating enforcement uncertainty. The Midlands hosts contract manufacturers serving brands awaiting regulatory clarity on CBD's legal status for human consumption.
Poland
Warsaw's emerging pharmacy channel offers first-mover positioning as national regulators transpose EU Court of Justice rulings into domestic frameworks. The country's agricultural ministry pilots hemp cultivation subsidies under EU Green Deal bioeconomy mandates. Lower Silesia's processing infrastructure remains underdeveloped relative to Western European extraction capacity.
Europe CBD Oil Market Key Industry Players
On the supply side, the industry is bifurcating between pharmaceutical-grade isolates and wellness-oriented full-spectrum formulations. Agricultural-derived extraction dominates volume, yet biosynthetic production platforms are converging with GMP standards to enable THC-free output at specification-grade consistency. Three archetypes define competitive positioning: vertically integrated hemp cultivators, pharmaceutical compounders with chromatographic separation capabilities, and platform distributors aggregating fragmented brand portfolios. Capacity expansion and REACH compliance certification constitute the dominant competitive moves as registration timelines extend working capital deployment.
Within the pharmaceutical-compounder tier, Candropharm and Endoca anchor contrasting sourcing strategies—Candropharm leverages GMP-certified extraction infrastructure while Endoca exemplifies vertically controlled cultivation from seed to oil. Sanobiotec occupies a position in the biosynthetic research vector, differentiating from agricultural-derived competitors through precision fermentation approaches. These three entities represent the spectrum from commodity biomass processing to specification-controlled pharmaceutical supply.
| Leading Market Players |
|---|
| Sanobiotec |
| Candropharm |
| Essentia Pura |
| Cibdol |
| Endoca |
| Pure Production AG |
| Green Exchange Lab |
| Formula Swiss |
| HemPoland |
| Others |
Cost & Logistics Intelligence
Rotterdam's hemp biomass import terminals concentrate upstream supply capacity, translating into asymmetric pricing power for Dutch extraction facilities serving compound pharmacies across German-speaking markets. Downward cost pressure on full-spectrum wellness formulations intensifies as REACH solvent residue compliance adds fixed-cost burdens that commodity-grade processors cannot absorb.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade isolate, premium full-spectrum, and economy distillate levels anchors contract negotiations. Price differentiation hinges on EU GMP Annex 1 certification status and batch-to-batch chromatographic consistency. Pricing pressure stems from organic hemp biomass yield compression in Eastern European growing regions. Retail consumers exhibit highest price sensitivity, while hospital pharmacy committees prioritize pharmacokinetic reliability over unit cost.
Supply Chain Analysis
THC threshold divergence between Germany, France, and Italy fragments cross-border product standardization and inflates compliance overhead. Denmark, the Netherlands, and Poland anchor extraction capacity. Raw material dependencies center on organic hemp biomass, supercritical CO2 equipment, and chromatographic separation media. Distribution runs through Rotterdam's logistics hub for wellness-grade oils and direct GMP-certified channels for pharmaceutical isolates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hospital pharmacy committees in Cologne and Berlin, fragmenting pricing leverage for agricultural-derived suppliers unable to meet specification-grade consistency requirements.
For Market Incumbents: Entrench pharmaceutical manufacturing licenses through dedicated EU GMP Annex 1 sterile preparation capabilities. Biosynthetic competitors threaten agricultural-derived market share through THC-free isolate consistency. Backward integration into Danish hemp cultivation secures batch traceability for REACH disclosure mandates. For New Entrants and Emerging Players: Poland's underdeveloped pharmacy channel represents the most penetrable entry point as national regulators transpose EU Court of Justice rulings. Biosynthetic production platforms bypass agricultural yield volatility. Direct-to-clinic sampling programs accelerate formulary inclusion ahead of wholesale distribution relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation platforms converging with pharmaceutical GMP standards. Long-term viability rests on specification-grade consistency rather than entourage effect marketing. Acquisition targets should demonstrate chromatographic separation capabilities and existing hospital formulary contracts. Watch EFSA novel food safety assessment timelines as inflection indicators for ingestible product working capital recovery.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | EU GMP Annex 1 compliance unlocks hospital pharmacy committee contracts in German-speaking markets. |
| Precision Fermentation Scale-Up | Biosynthetic cannabinoid production achieves THC-free isolate consistency beyond agricultural variability. |
| Vertical Cultivation Control | Danish seed-to-oil traceability satisfies REACH disclosure and CSRD supply chain mandates. |
| Pharmacy Channel Expansion | Polish first-mover positioning captures margin pools before regulatory clarity attracts competitors. |
| Novel Food Approval Pathway | EFSA safety assessment completion releases working capital locked in pre-revenue inventory cycles. |
Research Approach
Initial hypotheses were tested against primary input from extraction facility operators, pharmaceutical compound pharmacy managers, regulatory affairs specialists at national cannabis offices, and hospital procurement committees, then refined through secondary validation against EMA guidance documents, EFSA novel food safety assessments, BfArM licensing records, and REACH registration databases. Bottom-up volume estimates from hemp cultivation acreage and extraction capacity were triangulated against top-down pharmaceutical procurement value flows.
Demand-supply balance dynamics across the projection horizon were modeled through segmented analysis by formulation chemistry, procurement authority, and channel economics. The analytical framework incorporated pharmaceutical-grade isolate, full-spectrum wellness, and broad-spectrum intermediate tiers alongside healthcare provider, online retailer, and pharmacy channel dimensions. CAGRs were derived from regression analysis of historical regulatory approval timelines and penetration rate trajectories, with inputs including EMA cannabinoid medicine guidance adoption curves and BfArM licensing velocity.
Practitioners should monitor EFSA novel food safety assessment completions, BfArM licensing queue progression, and biosynthetic production platform scale-up announcements for early signals of forecast deviation. Forecasts reflect assumptions regarding regulatory harmonization velocity and pharmaceutical procurement specification stability. Material shifts in EU Court of Justice ruling national transposition timelines or REACH solvent residue limit enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market