
 CBD Oil Market | 2026-2036
CBD Oil Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Oil Market Analysis
Licensed extraction technicians is unwinding production bottlenecks across the CBD oil industry, as state-level cannabis programs expand faster than vocational training pipelines can supply qualified operators. Charlotte's Web Holdings, Inc. leverages its proprietary hemp genetics to maintain seed-to-shelf quality control. Folium Biosciences anchors large-scale cannabinoid extraction capacity in Colorado. Medterra CBD, LLC competes through broad-spectrum formulations targeting drug-tested athletes and professionals.
CBD oil comprises hemp-derived cannabinoid extracts suspended in carrier oils, typically containing less than 0.3% delta-9 THC by dry weight and standardized to specific cannabidiol concentrations measured in milligrams per milliliter. The substance serves primarily as an active ingredient in wellness products, pharmaceuticals, and functional foods requiring precise dosing consistency. Full spectrum formulations command premium positioning due to entourage-effect claims, while isolate segments attract pharmaceutical-grade buyers seeking single-molecule purity. Water-soluble CBD technology is gaining fastest among beverage manufacturers, though dropper bottles remain the dominant packaging format for retail consumer channels.
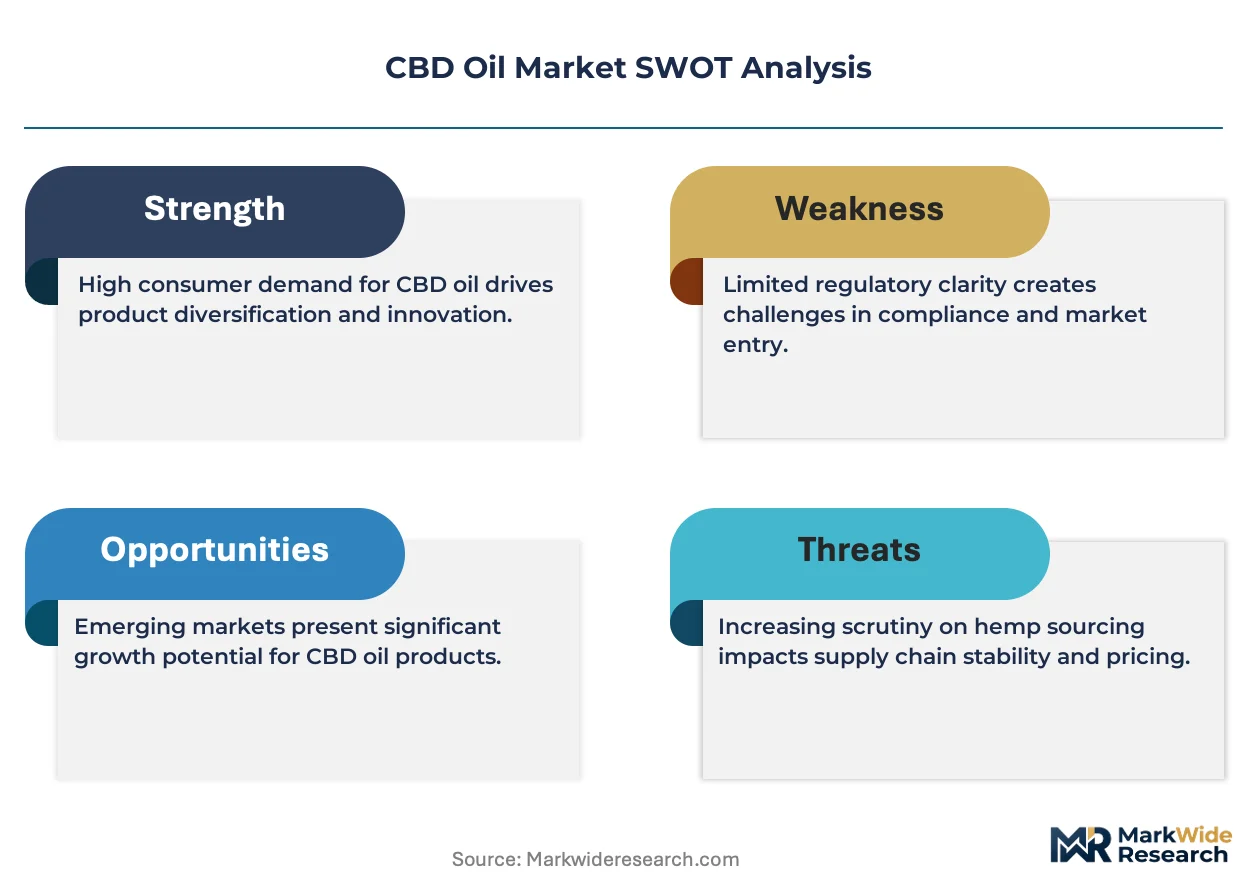
The FDA maintains restrictive oversight of CBD in food and dietary supplements under the Federal Food, Drug, and Cosmetic Act, while the USDA administers hemp cultivation compliance through its Domestic Hemp Production Program. State regulators in California, Colorado, and Oregon impose additional testing protocols for residual solvents and heavy metals that exceed federal minimums. Stakeholders must monitor pending Congressional action on CBD regulatory pathways to determine whether to prioritize pharmaceutical drug development or consumer product expansion strategies.
Market Dynamics
FDA's evolving stance on cannabidiol in dietary supplements is compressing strategic timelines for domestic producers, forcing capital allocation decisions between pharmaceutical drug development and consumer wellness expansion before regulatory clarity arrives.
Growth Catalysts
- Wellness Center Procurement:Therapeutic applications in North American wellness centers are expanding institutional buying pools for high-purity formulations. These facilities require batch-tested certificates of analysis that favor licensed suppliers.
- USDA Hemp Cultivation Framework:The Domestic Hemp Production Program standardizes interstate commerce compliance, reducing cultivation fragmentation that previously trapped processors in single-state supply bases.
- Water-Soluble Nanoemulsion Technology:Beverage manufacturers are adopting lipid encapsulation processes that bypass first-pass metabolism limitations, opening functional drink categories previously inaccessible to oil-soluble cannabinoids.
Market Restraints
- Residual Solvent Testing Costs:Colorado and Oregon state protocols mandate sub-ppm detection thresholds for hydrocarbon extraction agents, raising batch release costs for mid-scale processors without in-house chromatography.
- California Supply Chain Concentration:Vertically licensed operators controlling cultivation through retail distribution create procurement bottlenecks for independent brands seeking biomass access.
- Federal Food, Drug, and Cosmetic Act Restrictions:FDA's prohibition on CBD in interstate food commerce blocks mainstream retail channel penetration, confining growth to supplement and topical categories.
Strategic Opportunities
- Drug-Tested Professional Segments:Broad-spectrum formulations with non-detectable THC thresholds are capturing athletic and corporate wellness contracts where zero-tolerance policies previously excluded cannabinoid products.
- Pending Congressional Pathway Legislation:Federal CBD regulatory clarity would unlock conventional food and beverage channels currently restricted by the FD&C Act's drug exclusion clause.
- Seed-to-Shelf Genetics Control:Proprietary hemp cultivars with optimized cannabinoid ratios enable consistent chemotype output that commodity biomass sourcing cannot replicate.
Industry Challenges
- Licensed Extraction Technician Shortage:State-level cannabis program expansion outpaces vocational training pipeline output, creating production bottlenecks at facility commissioning stages.
- Entourage-Effect Standardization Gap:Full spectrum positioning lacks consensus analytical methods for minor cannabinoid and terpene profiling, complicating premium pricing justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Oil Market |
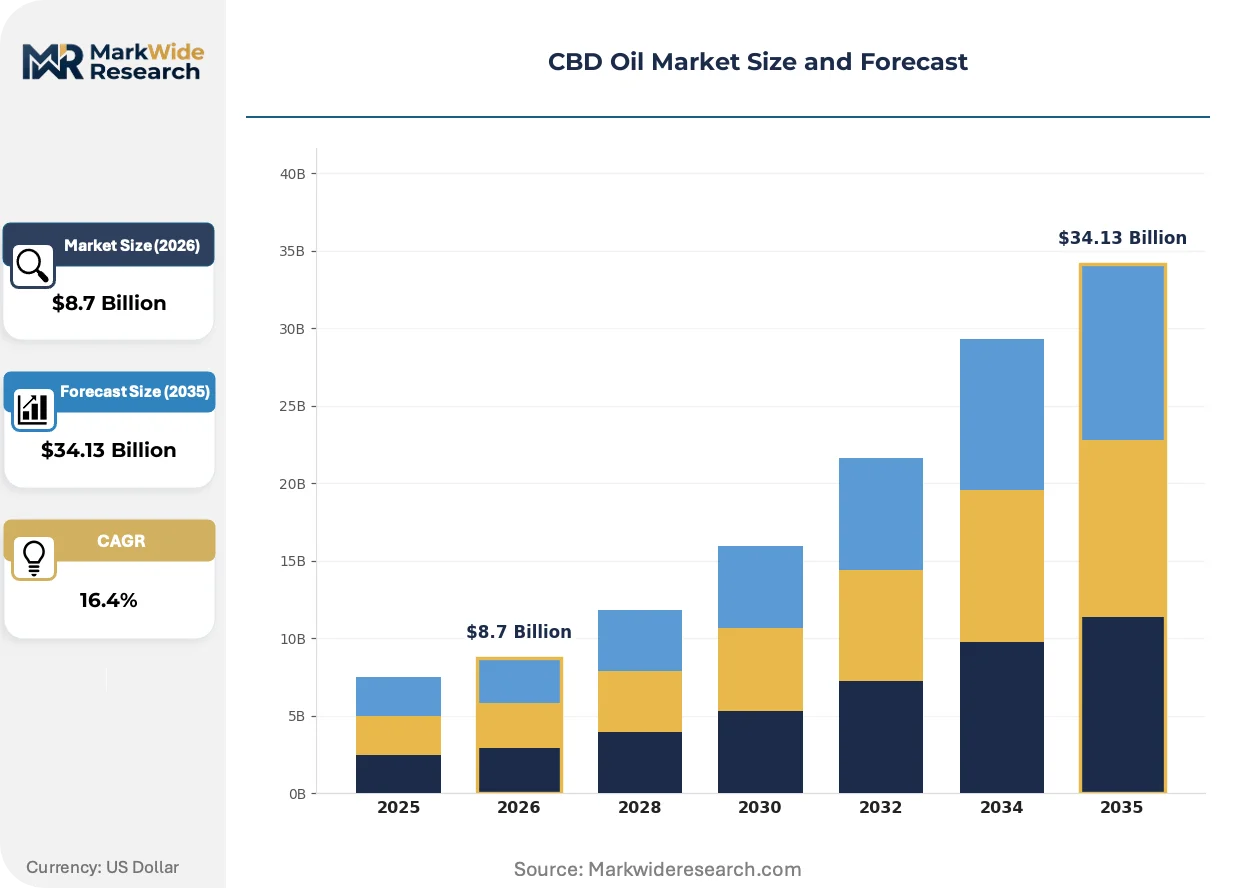
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Spectrum, Broad Spectrum, Isolate, Water-Soluble Distribution Channel: Online, Retail Stores, Wholesalers, Specialty Shops End User: Healthcare Providers, Retail Consumers, Wellness Centers, Research Institutions Packaging Type: Dropper Bottles, Capsules, Topicals, Edibles |
| Companies Covered | Charlotte’s Web Holdings, Inc., CV Sciences, Inc., Medical Marijuana, Inc., Elixinol Wellness Ltd, Medterra CBD, LLC, Aurora Cannabis Inc., ENDOCA, Canopy Growth Corporation, Folium Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Oil Market Emerging Trajectories
Technology convergence between pharmaceutical delivery science and botanical extraction is redefining product format possibilities, while regulatory uncertainty forces parallel investment in compliance infrastructure across multiple approval pathways.
Nanoemulsion technology is fragmenting traditional oil-based delivery dominance by enabling water-compatible cannabinoid suspensions. Beverage manufacturers in California and Colorado are adopting lipid encapsulation systems at accelerating rates. This dispersion chemistry is compressing the addressable market for conventional tincture formats while creating new formulation service intermediaries.
The FDA's pending rulemaking on CBD as a dietary supplement ingredient is reshaping quality system investments. Domestic producers are building pharmaceutical-grade documentation capacity in anticipation of New Dietary Ingredient notification requirements. Full spectrum extractors face the steepest compliance burden, as variable minor cannabinoid content complicates safety substantiation packages.
Certification-driven procurement is displacing price-first buying in institutional channels. Wellness centers and corporate wellness programs now require third-party testing documentation that ISO 17025-accredited laboratories provide. This verification infrastructure preference concentrates contract awards among suppliers with captive analytical capabilities, particularly in North American metropolitan markets.
CBD Oil Market Segmentation
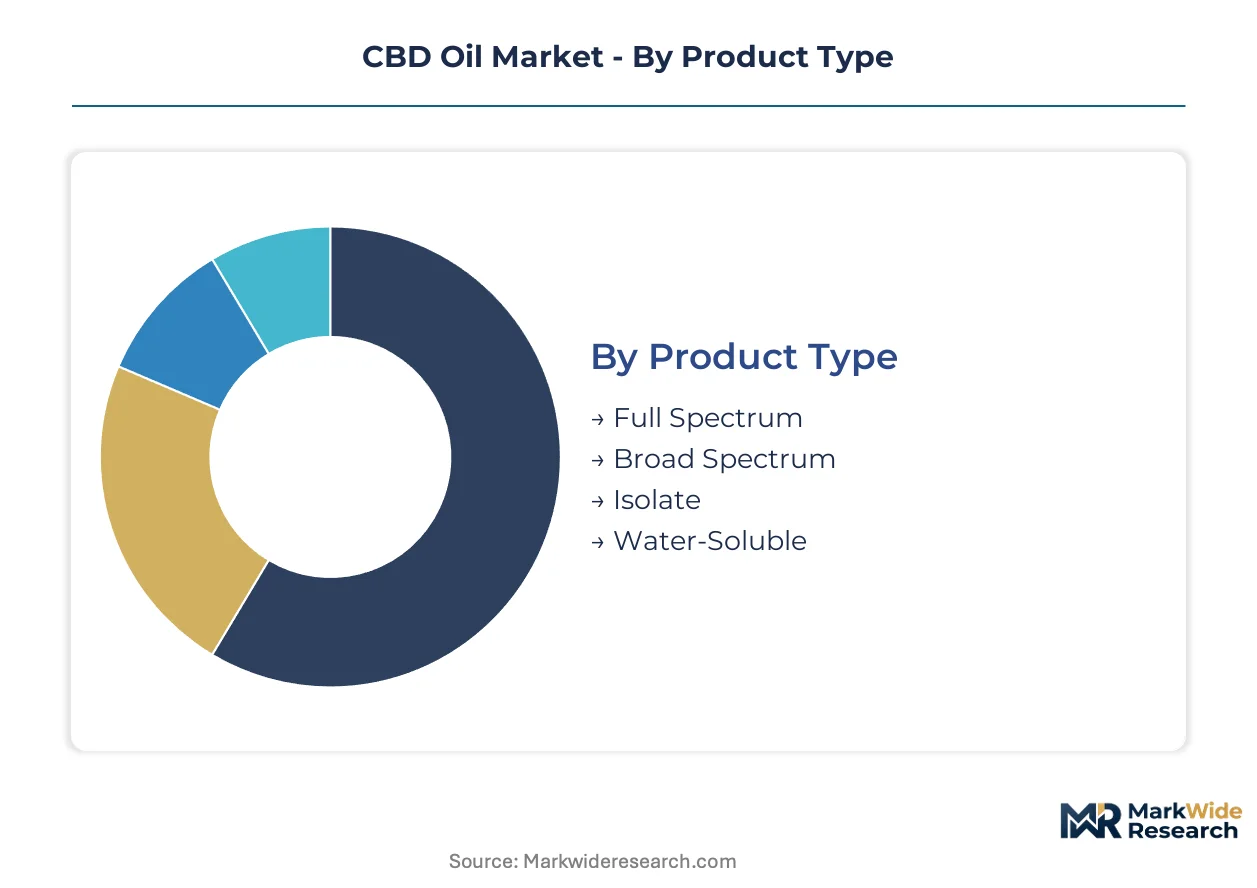
CBD oil segmentation reflects competing pressures from pharmaceutical standardization and consumer wellness diversification. Product chemistry, channel access, and end-use certification requirements create distinct competitive arenas with diverging margin profiles and regulatory exposure.
Product Type:
Substitution pressure from nanoemulsion technology and synthetic cannabinoid alternatives is reshaping formulation hierarchies, with oil-based formats facing the strongest displacement risk in beverage applications.
- Full Spectrum:Contains hemp-derived cannabinoids, terpenes, and flavonoids with less than 0.3% delta-9 THC, leveraging entourage-effect claims for premium positioning. Demand concentrates in California's vertically integrated dispensaries where batch-specific terpene profiles justify price premiums over isolate alternatives.
- Broad Spectrum:Multi-cannabinoid formulations with THC removed to non-detectable levels, targeting athletic and corporate wellness contracts with zero-tolerance drug policies. Procurement from North American wellness centers is expanding fastest for this segment as institutional buyers require documented THC absence.
- Isolate:Crystalline cannabidiol at 99%+ purity serves pharmaceutical-grade applications requiring single-molecule consistency. Manufacturers in Colorado utilize isolate for precise dosing in clinical research settings.
- Water-Soluble:Lipid-encapsulated nanoemulsions enable beverage integration with accelerated bioavailability. Functional drink manufacturers in Colorado and California are adopting this technology to bypass first-pass metabolism limitations of conventional oils.
Full spectrum retains volume leadership; water-soluble holds the steepest expansion curve.
Distribution Channel:
Channel economics stratify sharply by compliance burden, with direct-to-consumer models capturing margin advantages where regulatory clarity remains absent.
- Online:E-commerce platforms dominate broad-spectrum and isolate sales to drug-tested professionals, leveraging certificate-of-analysis documentation that institutional procurement requires. California-based operators utilize online channels to circumvent retail licensing bottlenecks.
- Retail Stores:Brick-and-mortar presence concentrates in states with mature hemp frameworks, where USDA compliance documentation enables interstate product placement. Shelf space competition is intensifying as FDA dietary supplement pathways remain unresolved.
- Wholesalers:Bulk distribution serves mid-scale processors lacking captive cultivation, though California supply chain concentration limits biomass access for independent brands.
- Specialty Shops:Curated wellness boutiques emphasize seed-to-shelf provenance and third-party testing, commanding price premiums through ISO 17025-accredited laboratory partnerships.
Online channels retain volume leadership; specialty shops hold the steepest expansion curve.
End User:
User sophistication divides the market between clinical-grade documentation requirements and consumer accessibility priorities.
- Healthcare Providers:Medical practitioners require FDA-compliant labeling and pharmaceutical-grade manufacturing standards that only isolate formulations currently satisfy. Prescription cannabinoid protocols remain limited by Schedule V controlled substance classification.
- Retail Consumers:Direct purchasing concentrates in tincture and topical formats, with dropper bottles maintaining dominance despite nanoemulsion technology emergence. Consumer education gaps persist around full spectrum versus isolate distinctions.
- Wellness Centers:Institutional procurement mandates batch-tested certificates of analysis, favoring suppliers with captive analytical capabilities in North American metropolitan markets. Broad-spectrum formulations are displacing full spectrum in corporate wellness contracts.
- Research Institutions:Academic and clinical studies require DEA-registered sourcing and documented chemotype consistency, limiting eligible suppliers to vertically integrated operators with proprietary genetics.
Retail consumers retain volume leadership; wellness centers hold the steepest expansion curve.
Packaging Type:
Format innovation is compressing traditional delivery dominance as beverage manufacturers adopt water-compatible suspensions.
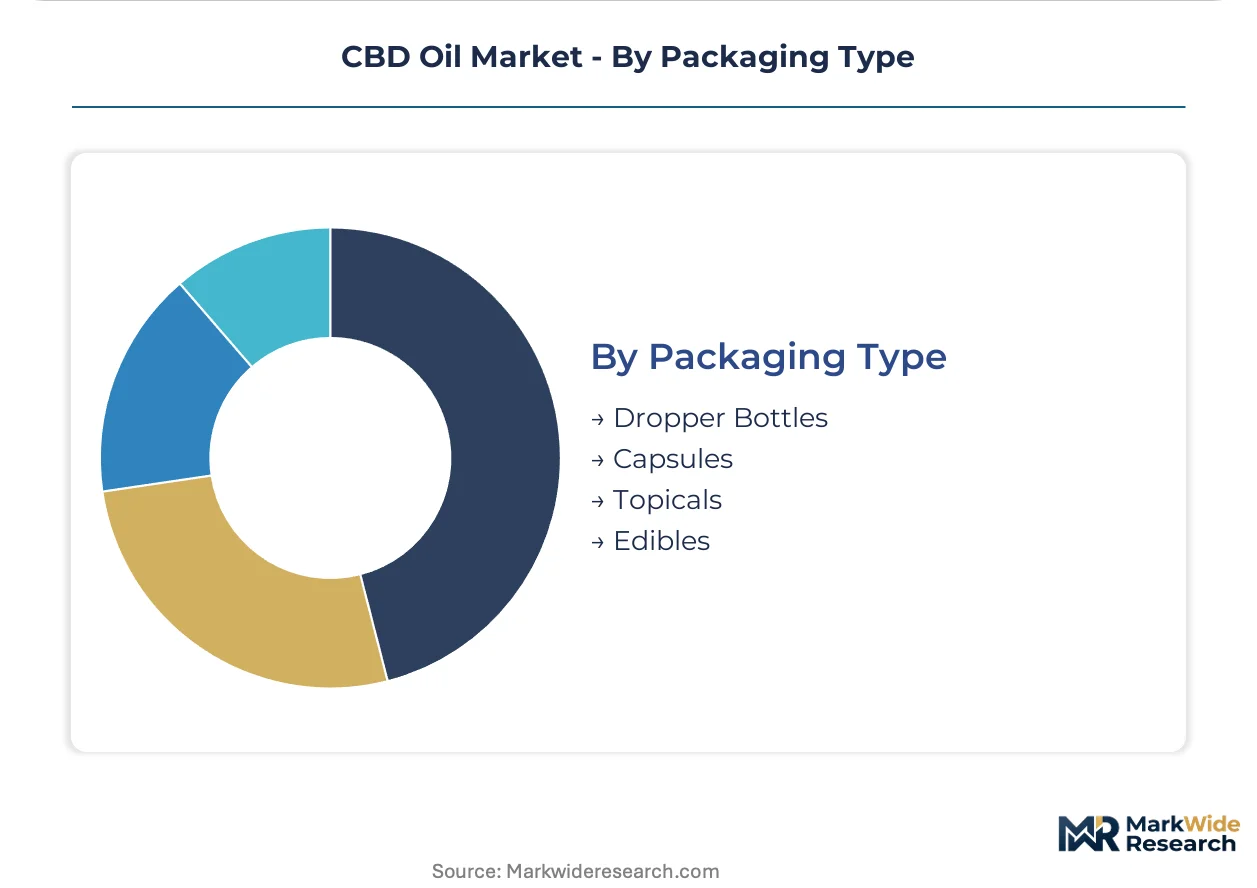
- Dropper Bottles:Glass or plastic vessels with calibrated droppers remain the standard for sublingual administration, though growth is decelerating relative to alternative formats. Tincture packaging dominates California's retail dispensary channels.
- Capsules:Gelatin or vegetable-based shells enable precise milligram dosing for consumers avoiding taste profiles of oil-based products. Sports nutrition manufacturers in Colorado are incorporating broad-spectrum capsules into athletic recovery lines.
- Topicals:Transdermal creams and balms target localized application with minimal systemic absorption, appealing to wellness center procurement for therapeutic massage applications.
- Edibles:Gummies and infused food products face FDA interstate commerce prohibitions under the FD&C Act, confining growth to state-legal cannabis markets with established manufacturing frameworks.
Dropper bottles retain volume leadership; capsules hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography, with wellness center procurement dominating North American institutional channels while European demand concentrates in pharmaceutical-grade applications. Asia-Pacific markets remain nascent, constrained by divergent national narcotics classifications.
United States
Wellness center chains and corporate wellness programs drive institutional procurement of broad-spectrum formulations. FDA oversight under the Federal Food, Drug, and Cosmetic Act restricts interstate food commerce, channeling growth into supplements and topicals. California's vertically licensed operators from cultivation through retail distribution control biomass access, creating procurement bottlenecks for independent brands in Los Angeles and San Francisco metropolitan markets.
Canada
Licensed producers leverage Health Canada's regulatory framework for both recreational and wellness channels. The country's national pharmaceutical regulator maintains distinct pathways for prescription cannabinoids versus consumer products. British Columbia and Ontario host concentrated extraction capacity, with Vancouver-area facilities serving domestic and export markets under federal cannabis legislation.
Germany
Pharmaceutical-grade demand dominates, with BfArM licensing requirements favoring isolate formulations for medical applications. The country's narcotics regulator enforces strict documentation for THC-containing products. Industrial clusters in North Rhine-Westphalia and Bavaria house GMP-certified processing facilities supplying pharmacy distribution networks across the European Union.
Switzerland
Low-THC hemp frameworks enable differentiated product positioning absent in neighboring jurisdictions. Swissmedic oversees novel food approvals, with Geneva and Zurich-based laboratories driving analytical standardization. The country's cantonal licensing system permits retail channels unavailable under stricter narcotics regimes, supporting specialty shop expansion in Basel and Bern.
United Kingdom
Food Standards Agency novel food authorization requirements filter market entry, with validated applications concentrating among established suppliers. The Medicines and Healthcare products Regulatory Agency maintains separate pharmaceutical pathways. London metropolitan wellness centers and corporate programs represent the primary institutional demand vector, requiring ISO 17025-accredited testing documentation.
CBD Oil Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with proprietary genetics and captive extraction capacity defining upper-tier positioning. Mid-scale processors compete through formulation differentiation and certification-driven procurement relationships. Three archetypes dominate: seed-to-shelf genetics controllers, large-scale extraction capacity operators, and broad-spectrum formulation specialists. Competitive moves concentrate on backward integration into cultivation and strategic partnerships with wellness center networks.
Within the genetics-control archetype, Charlotte's Web Holdings, Inc. exemplifies proprietary cultivar development, while Folium Biosciences anchors large-scale extraction positioning. Medterra CBD, LLC occupies the broad-spectrum specialist tier, targeting institutional buyers requiring non-detectable THC thresholds. These three represent divergent strategic bets on regulatory pathway outcomes.
| Leading Market Players |
|---|
| Charlotte's Web Holdings, Inc. |
| CV Sciences, Inc. |
| Medical Marijuana, Inc. |
| Elixinol Wellness Ltd |
| Medterra CBD, LLC |
| Aurora Cannabis Inc. |
| ENDOCA |
| Canopy Growth Corporation |
| Folium Biosciences |
| Others |
Supply Flow & Price Mechanics
ISO 17025 laboratory accreditation gates both supply qualification and price differentiation simultaneously, as wellness centers and corporate procurement officers require third-party testing documentation that only certified facilities can provide. This certification barrier stratifies pricing across premium-validated and uncertified tiers while concentrating contract awards among suppliers with captive analytical capabilities.
Pricing Analysis
Long-term offtake agreements dominate institutional procurement from North American wellness centers, while spot purchasing persists for retail consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates seed-to-shelf genetics controllers from commodity biomass processors and isolate traders. Cost compression in mid-scale processor tiers is intensifying because Colorado and Oregon residual solvent testing mandates raise batch release expenses. Drug-tested professional segments exhibit lowest price sensitivity due to zero-tolerance policy requirements, while retail consumers drive volume through price-first comparison shopping.
Supply Chain Analysis
Strategic stockpiling of certified hemp biomass characterizes large-scale extraction operators, while just-in-time procurement dominates independent brands lacking cultivation control. Supply concentrates in the United States, Canada, and Switzerland, with Colorado and California hosting primary extraction capacity. The chain draws from proprietary hemp genetics, hydrocarbon extraction solvents, and lipid encapsulation chemicals. Single-source vulnerability runs through California's vertically licensed operators controlling biomass access. Distribution runs through direct-to-consumer e-commerce platforms, specialty wellness boutiques, and institutional procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across federal and state jurisdictions creates white-space opportunities for specialists targeting certification-driven procurement segments. Wellness center institutional buying pools expand fastest where documentation standards filter out uncertified competitors.
For Market Incumbents: Fortify seed-to-shelf genetics control through proprietary cultivar development, as synthetic cannabinoid alternatives and nanoemulsion technology threaten traditional oil-based formats. Expand captive ISO 17025 laboratory capacity to capture wellness center contracts requiring batch-tested certificates of analysis. Deepen backward integration into Colorado and California cultivation assets to secure biomass access against California supply chain concentration. For New Entrants and Emerging Players: Anchor in broad-spectrum formulation services for drug-tested athletic and corporate wellness contracts, the most penetrable segment given zero-tolerance policy expansion. Target European pharmaceutical-grade applications in Germany and Switzerland where BfArM and Swissmedic frameworks favor isolate specialists with GMP documentation. Pursue go-to-market partnerships with ISO 17025-accredited testing laboratories to bypass capital-intensive analytical infrastructure requirements. For Investors and Strategic Acquirers: Pending Congressional CBD regulatory pathway legislation reshapes the acquisition landscape, determining whether pharmaceutical drug development or consumer wellness expansion strategies command premium valuations. Long-term viability favors vertically integrated operators with proprietary genetics and captive extraction capacity over formulation-as-a-service intermediaries. Target acquisition archetype: mid-scale processors with wellness center procurement relationships and pending ISO 17025 accreditation. Watch FDA dietary supplement rulemaking timing as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Hemp Cultivation | Charlotte's Web Holdings exemplifies how seed-to-shelf genetics control commands wellness center premium pricing. |
| ISO 17025 Laboratory Accreditation Investment | Certification-driven procurement from North American wellness centers filters contract awards to accredited suppliers exclusively. |
| Broad-Spectrum THC Removal Technology Licensing | Medterra CBD's non-detectable THC formulations capture athletic and corporate wellness contracts with zero-tolerance policies. |
| Nanoemulsion Lipid Encapsulation Partnership | Colorado and California beverage manufacturers adopt water-soluble technology to bypass first-pass metabolism limitations. |
| EU GMP Certification for German Pharmaceutical Entry | BfArM licensing requirements in North Rhine-Westphalia favor isolate specialists supplying pharmacy distribution networks. |
Methodological Framework
Desk research of FDA guidance documents, USDA hemp cultivation reports, and state regulatory filings preceded structured interviews with licensed extraction technicians, wellness center procurement officers, and hemp cultivation operators. Primary fieldwork with Colorado and California facility managers, North American wellness center directors, and pharmaceutical regulatory consultants combined with secondary validation from customs records, SEC 10-K disclosures, and ISO 17025 laboratory accreditation databases. Bottom-up volume modeling across product chemistry tiers triangulated against top-down market sizing from trade association estimates.
Variance decomposition across product type, distribution channel, end user certification requirements, and regional regulatory frameworks shaped the analytical approach over the projection horizon. Segmentation dimensions modeled include full spectrum versus isolate versus water-soluble chemistry, online versus retail versus institutional channel access, and wellness center versus retail consumer versus healthcare provider end-use sophistication. CAGRs derived from regression analysis of historical state program expansion rates and pending regulatory pathway probability assessments, with hemp biomass yield improvements and extraction efficiency gains as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued state-level cannabis program expansion and stable FDA enforcement posture; material deviation would warrant model refresh. Forecasts incorporate base-case assumptions regarding Congressional legislative timing and state testing protocol harmonization. Revision becomes warranted when federal CBD dietary supplement pathway clarity crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Europe Medical Cannabis Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Global Marijuana Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market