
 Paediatric Spasticity Treatment Market | 2026-2036
Paediatric Spasticity Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Paediatric Spasticity Treatment Market Analytics
The paediatric neurorehabilitation specialist workforce is bifurcating between academic medical centers and community-based programmes, constraining equitable access to advanced spasticity interventions. Allergan plc leverages its established botulinum toxin platform to sustain dominance in intramuscular injection protocols across North American paediatric hospitals. Ipsen Biopharmaceuticals Inc. anchors its competitive position through deep specialization in movement disorder biologics, while Medtronic plc competes via integrated intrathecal pump and catheter systems that control device-mediated drug delivery workflows.
Paediatric spasticity treatment encompasses pharmacologic, physical, and surgical modalities designed to reduce pathologically increased muscle tone in children with upper motor neuron lesions, with botulinum toxin serotype A formulations typically dosed by body weight and targeted via electromyographic guidance to specific motor endplates. Oral medications such as baclofen and diazepam serve as first-line systemic options, though their cognitive side-effect profiles limit long-term utility in school-age populations. Botulinum Toxin captures the dominant share of ambulatory intervention volume, while Intrathecal Delivery represents the fastest-growing delivery mode as programmable pump technology improves dosing precision for severe cases. Cerebral Palsy anchors indication-specific demand, with Rehabilitation Centers capturing expanding margin pools as payors shift toward site-of-care optimization.
The FDA's paediatric exclusivity provisions under the Best Pharmaceuticals for Children Act shape development incentives, while the EMA's Paediatric Investigation Plans mandate age-appropriate trial designs for European market access. ISO 14155 governs clinical investigation standards for intrathecal device trials, directly influencing regulatory submission timelines for pump manufacturers. Stakeholders must monitor evolving CMS reimbursement thresholds for combination drug-device therapy in home care settings, as these determinations will dictate capital deployment toward ambulatory versus institutional delivery infrastructure.
Market Dynamics
Programmable intrathecal pump technology is compressing the clinical threshold for device-mediated intervention, pulling severe cerebral palsy cases from institutional infusion centers toward ambulatory care settings and rewiring reimbursement negotiations between manufacturers and payors.
Growth Catalysts
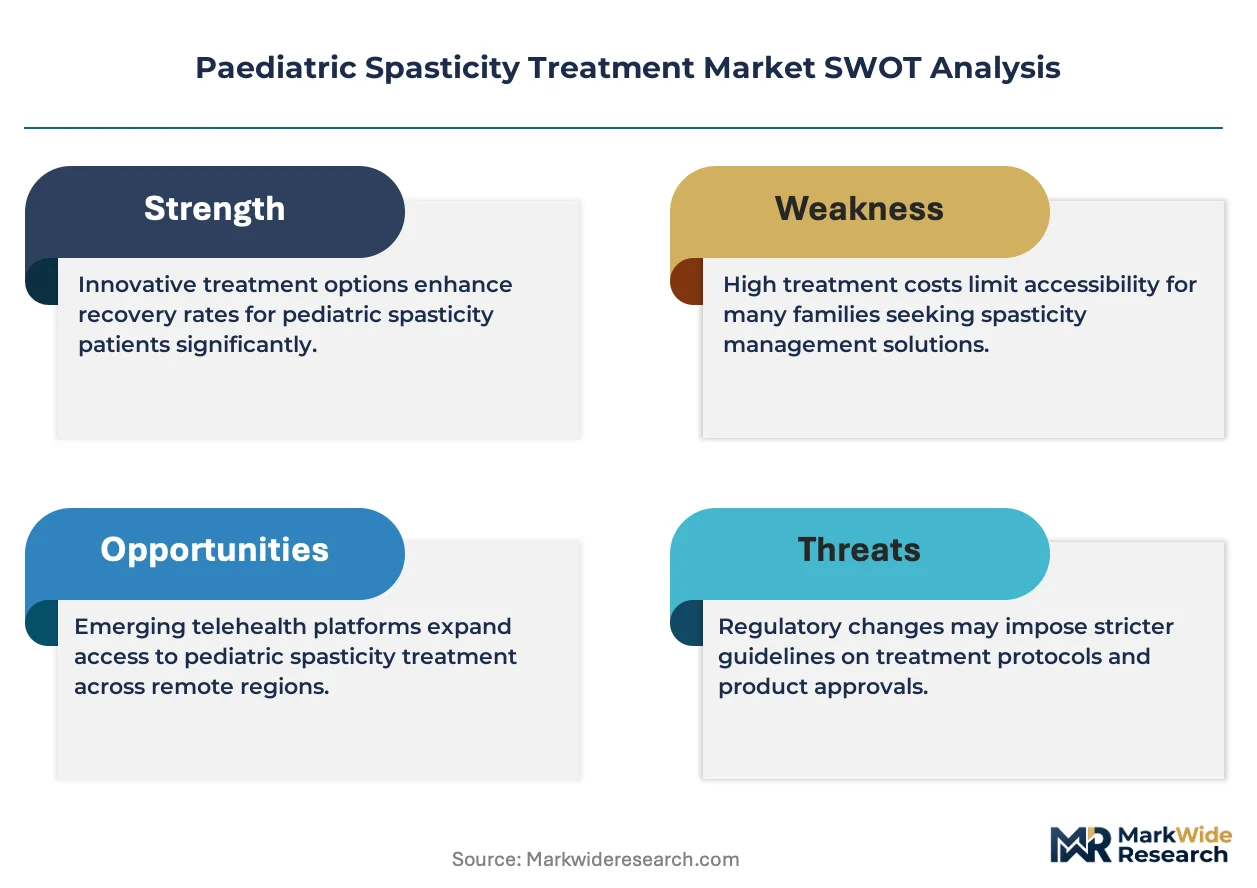
- Orphan drug incentives:The FDA's expanded designations for spasticity indications compress development timelines for biologic formulations targeting paediatric populations.
- Rehabilitation center expansion:Specialized cerebral palsy treatment networks in the United States are scaling intrathecal delivery infrastructure to capture site-of-care optimization payments.
- Electromyographic targeting:Motor endplate localization technology improves injection precision for botulinum toxin protocols, extending therapeutic windows between interventions.
Market Restraints
- Specialist workforce bifurcation:Paediatric neurorehabilitation expertise concentrates in academic medical centers, leaving community-based programmes with limited access to advanced intervention protocols.
- Cognitive side-effect limitations:Oral baclofen and diazepam face restricted long-term utility in school-age populations due to sedation and academic performance impacts.
- Pump system capital intensity:Programmable intrathecal devices require substantial upfront investment and specialized surgical implantation capacity, constraining adoption outside tertiary centers.
Strategic Opportunities
- Home care reimbursement evolution:CMS threshold determinations for combination drug-device therapy in residential settings will dictate capital deployment toward ambulatory delivery infrastructure.
- Paediatric Investigation Plan alignment:EMA mandates for age-appropriate trial designs create first-mover advantages for sponsors with established European regulatory pathways.
- Device-biologic convergence:Integration of closed-loop sensing with programmable pumps enables real-time titration against spasticity episodes, opening premium positioning.
Industry Challenges
- ISO 14155 compliance timelines:Clinical investigation standards for intrathecal device trials extend regulatory submission schedules, compressing effective patent life for pump manufacturers.
- Catheter failure modes:Intrathecal delivery systems face mechanical complication rates requiring revision surgeries, generating liability exposure and utilization review scrutiny.
- Cross-modal training requirements:Optimal spasticity management demands proficiency across pharmacologic, physical, and surgical modalities, creating workforce development bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paediatric Spasticity Treatment Market |
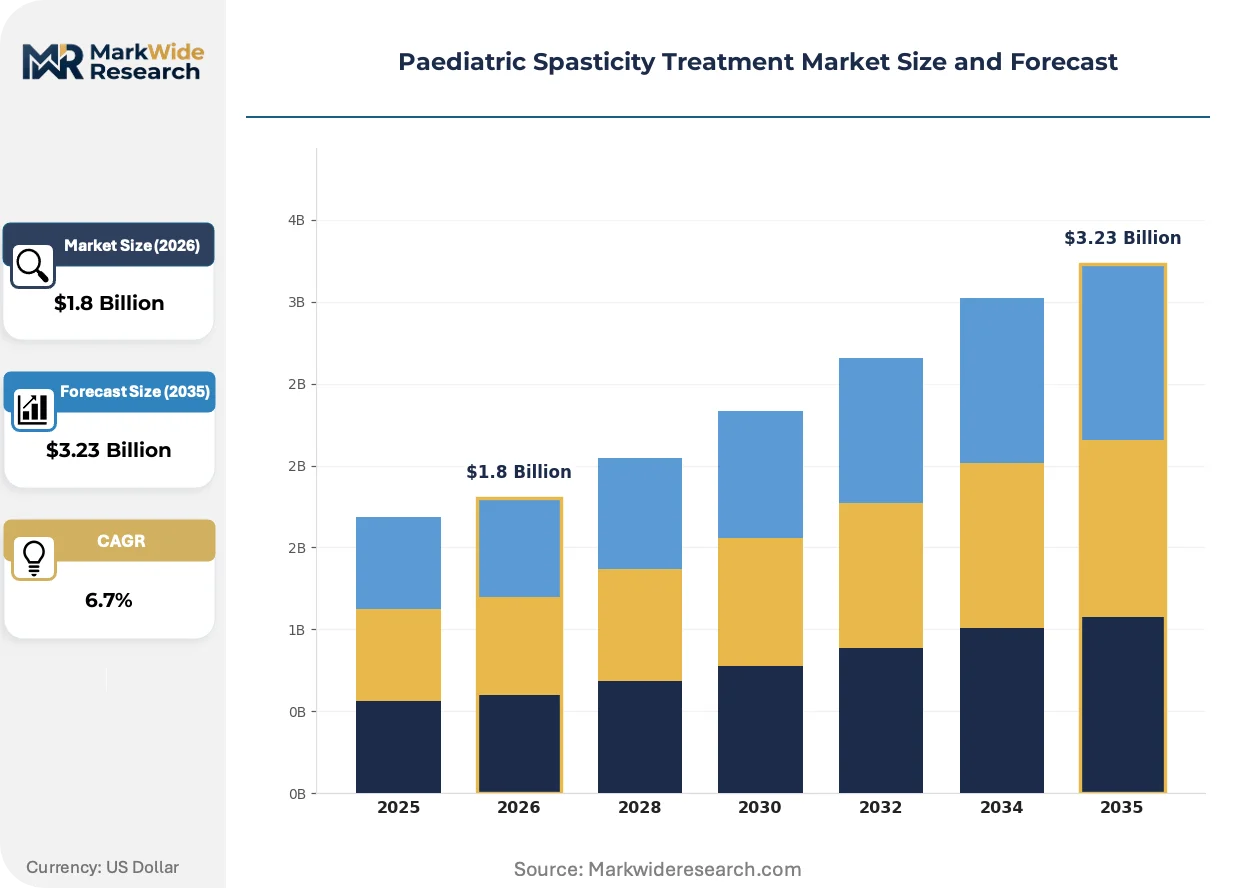
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Botulinum Toxin, Physical Therapy, Oral Medications, Surgical Interventions Indication: Cerebral Palsy, Stroke, Traumatic Brain Injury, Other Neuromuscular Disorders Delivery Mode: Intramuscular Injection, Oral Administration, Intrathecal Delivery, Transcutaneous Stimulation End User: Pediatric Specialists, Rehabilitation Centers, Hospitals, Home Care Settings |
| Companies Covered | Allergan plc, Ipsen Biopharmaceuticals Inc., Medtronic plc, Merz Pharmaceuticals GmbH, Sanofi, Genentech Inc., Piramal Critical Care, Inc., Saol Therapeutics, US WorldMeds, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paediatric Spasticity Treatment Market Evolving Landscape
Delivery mechanism precision and regulatory pathway efficiency are converging to shift intervention settings from hospitals toward ambulatory and home-based care, compressing the traditional site-of-care hierarchy in paediatric neurorehabilitation.
Implantable pump systems with closed-loop sensing capability are miniaturizing, enabling subcutaneous reservoir placement with reduced surgical footprint. Paediatric rehabilitation centers in the United States are piloting these platforms for ambulatory patients previously managed through institutional infusion. The technology is miniaturizing hardware requirements while expanding the addressable population for device-mediated therapy beyond the most severe cases.
The FDA's paediatric exclusivity provisions under the Best Pharmaceuticals for Children Act are accelerating biologic development timelines for spasticity indications. Sponsors capturing these incentives compress competitive windows for follow-on entrants. Botulinum toxin serotype A formulations with paediatric-specific labeling are capturing disproportionate regulatory investment, reshaping R&D prioritization across the neuromodulation sector.
Site-of-care optimization contracts are displacing fee-for-service reimbursement for complex spasticity interventions. United States payors are bundling device, drug, and professional components into episode-based payments, forcing manufacturers to integrate across delivery modalities. This shift concentrates procurement authority within specialized cerebral palsy treatment networks and marginalizes standalone product vendors.
Paediatric Spasticity Treatment Market Segmentation
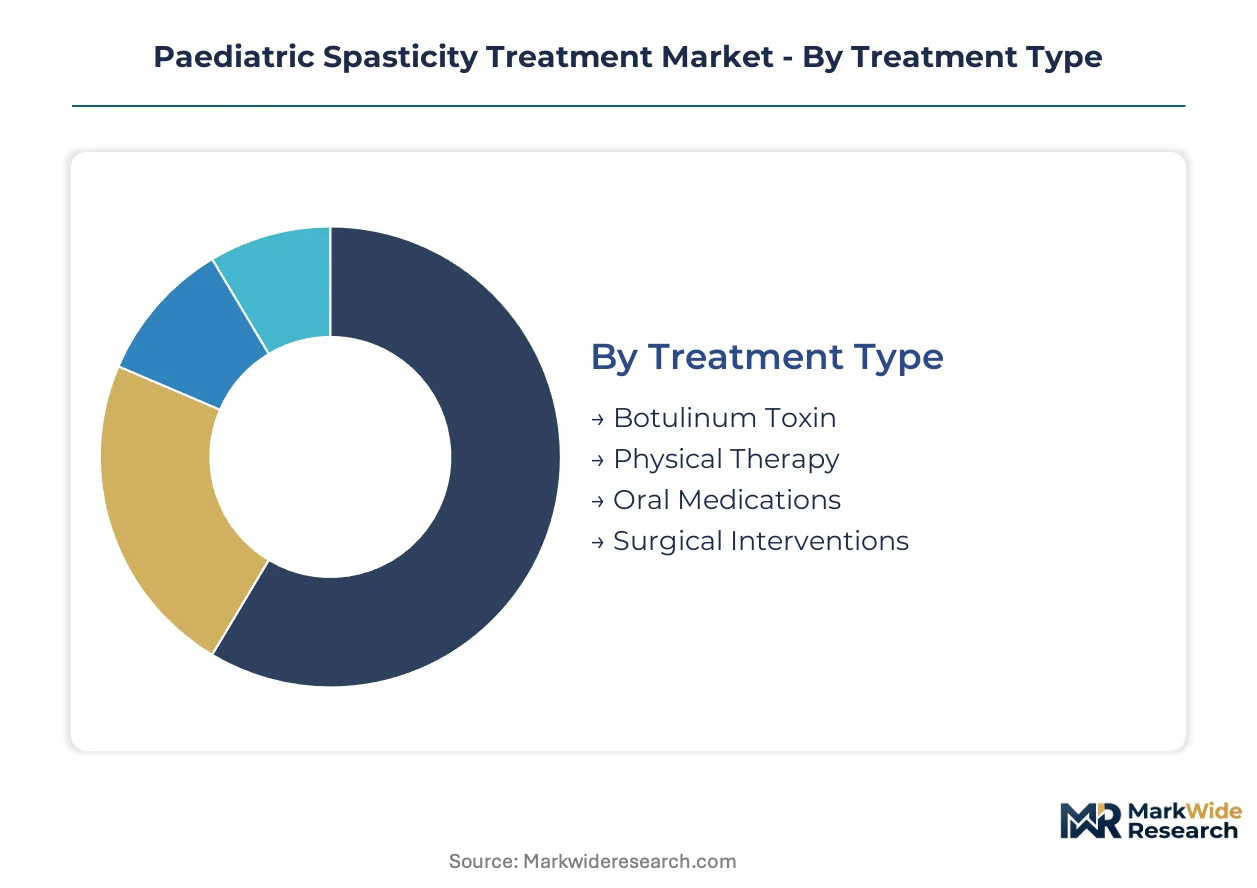
Segmentation in paediatric spasticity treatment reveals how margin pools migrate across intervention modalities and care settings. Understanding these divisions exposes where capital deployment yields highest returns and which delivery infrastructures command pricing power.
Treatment Type:
Margin concentration tracks toward minimally invasive modalities with repeat dosing potential and away from capital-intensive surgical alternatives.
- Botulinum Toxin:Serotype A formulations target specific motor endplates under electromyographic guidance. Demand clusters in United States paediatric hospitals where specialized injection protocols support premium reimbursement.
- Physical Therapy:Stretching protocols and orthotic management require minimal pharmaceutical outlay but demand sustained specialist labor. Rehabilitation centers in academic medical centers capture the highest-margin cases through bundled episode payments.
- Oral Medications:Baclofen and diazepam serve as first-line systemic options with established generic availability.
- Surgical Interventions:Selective dorsal rhizotomy and tendon lengthening procedures concentrate in tertiary centers with dedicated neurosurgical capacity.
The dominant share belongs to Botulinum Toxin, while Physical Therapy is closing the gap fastest through site-of-care optimization contracts.
Indication:
Volume distribution reflects the underlying epidemiology of paediatric upper motor neuron lesions across developed healthcare systems.
- Cerebral Palsy:Spastic diplegia and quadriplegia variants generate sustained intervention demand from infancy through adolescence. United States cerebral palsy treatment networks in Philadelphia, Houston, and Cincinnati anchor clinical trial recruitment and device adoption.
- Stroke:Perinatal arterial ischemic stroke produces hemiparetic spasticity requiring asymmetric intervention protocols. Academic medical centers with dedicated paediatric stroke programs concentrate this addressable population.
- Traumatic Brain Injury:Motor vehicle accidents and non-accidental trauma create acquired spasticity with variable recovery trajectories.
- Other Neuromuscular Disorders:Hereditary spastic paraplegia and metabolic encephalopathies represent scattered etiologies with limited trial evidence.
Cerebral Palsy commands the volume base, though Stroke indications are climbing the fastest as neuroimaging protocols expand detection.
Delivery Mode:
Precision in drug targeting and programmability determines which modalities capture severe-case referrals and associated reimbursement premiums.
- Intrathecal Delivery:Programmable pump systems with catheter-based baclofen infusion enable continuous titration against severe spasticity. United States paediatric rehabilitation centers in Baltimore and Los Angeles are piloting closed-loop sensing integration for ambulatory patients.
- Intramuscular Injection:Botulinum toxin administration via electromyographic or ultrasound guidance permits focal targeting without systemic exposure. Community-based programmes lacking advanced imaging capacity face exclusion from this intervention tier.
- Oral Administration:Systemic distribution produces cognitive side effects that limit school-age utility.
- Transcutaneous Stimulation:Non-invasive neuromodulation devices offer home-based adjunctive therapy with minimal regulatory burden.
Intramuscular Injection retains the dominant share, yet Intrathecal Delivery is gaining share fastest as pump miniaturization expands the addressable population.
End User:
Procurement authority is consolidating within specialized networks that can demonstrate outcome metrics to payors.
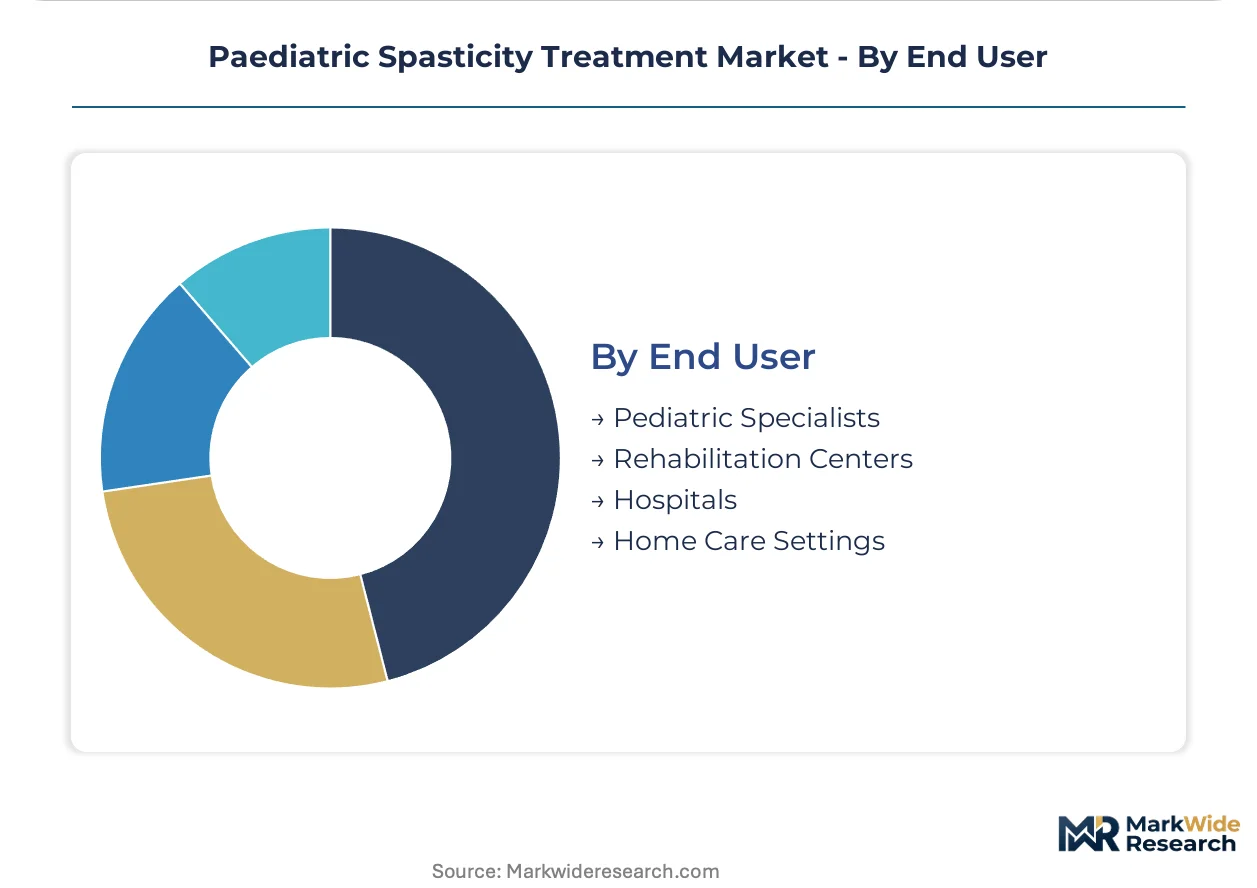
- Rehabilitation Centers:Dedicated paediatric facilities in the United States are capturing site-of-care optimization payments through bundled episode design. Centers in Chicago, Atlanta, and Seattle have invested in intrathecal pump programming capacity to manage severe cases outside hospital walls.
- Pediatric Specialists:Paediatric physiatrists and neurologists in academic medical centers control referral flows for advanced interventions. Their prescribing patterns determine botulinum toxin brand selection and device implantation candidacy.
- Hospitals:Inpatient admission for spasticity crises or surgical revision generates episodic revenue with high fixed-cost overhead.
- Home Care Settings:Family-administered oral medications and transcutaneous devices operate at the lowest reimbursement tier.
Rehabilitation Centers hold the dominant share, while Pediatric Specialists are expanding their share fastest through direct-to-payor contracting arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's paediatric exclusivity provisions and specialized cerebral palsy treatment networks anchor market development in the United States. Regulatory pathways in Europe and Asia-Pacific diverge in trial design mandates and reimbursement structures, fragmenting competitive entry timelines across jurisdictions.
United States
Philadelphia, Houston, and Cincinnati host the dominant cerebral palsy treatment networks driving clinical trial recruitment and device adoption. The FDA's Best Pharmaceuticals for Children Act accelerates biologic development timelines through paediatric exclusivity incentives. CMS reimbursement thresholds for combination drug-device therapy in home care settings are reshaping capital deployment toward ambulatory delivery infrastructure.
Germany
Academic medical centers in Berlin and Munich concentrate paediatric neurorehabilitation expertise and intrathecal pump implantation capacity. The EMA's Paediatric Investigation Plans mandate age-appropriate trial designs for European market access, creating compliance barriers for sponsors lacking established regulatory pathways. Site-of-care optimization contracts are displacing fee-for-service reimbursement, bundling device, drug, and professional components into episode-based payments.
United Kingdom
London and Manchester anchor specialized paediatric spasticity intervention programs with integrated botulinum toxin and intrathecal delivery protocols. NICE technology appraisals determine reimbursement eligibility for novel neuromodulation devices, compressing effective market access windows. Rehabilitation centers in the National Health Service are piloting closed-loop sensing integration for ambulatory patients previously managed through institutional infusion.
Japan
PMDA consultation procedures for paediatric indications require dedicated juvenile toxicology studies, extending preclinical timelines for spasticity biologics. Tokyo and Osaka medical centers concentrate electromyographic-guided injection expertise and programmable pump programming capacity. METI funding for rare disease innovation supports domestic development of miniaturized intrathecal delivery systems.
Australia
TGA priority review pathways for orphan indications accelerate market entry for paediatric spasticity therapies with limited treatment alternatives. Sydney and Melbourne rehabilitation centers are expanding intrathecal pump infrastructure to capture severe cerebral palsy cases from institutional settings. The Pharmaceutical Benefits Scheme reimbursement determinations for combination therapies dictate prescribing patterns across state-based healthcare networks.
Paediatric Spasticity Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical manufacturers controlling biologic formulations and medical device companies anchoring delivery infrastructure. The market structure bifurcates between botulinum toxin platforms requiring repeat dosing and capital-intensive intrathecal pump systems with long implantation cycles. Strategic archetypes include integrated neuromodulation platforms, specialized movement disorder biologics, and programmable drug-device combination systems. Competitive moves center on site-of-care contracting authority and regulatory pathway efficiency for paediatric indications.
Among integrated device manufacturers, Medtronic plc occupies a position anchoring programmable pump and catheter system workflows. Allergan plc and Ipsen Biopharmaceuticals Inc. exemplify the biologic specialization tier, with the former representing established botulinum toxin platforms and the latter occupying deep movement disorder focus. These three companies collectively illustrate how competitive positioning diverges between device-mediated delivery control and pharmacologic repeat-intervention models.
| Leading Market Players |
|---|
| Allergan plc |
| Ipsen Biopharmaceuticals Inc. |
| Medtronic plc |
| Merz Pharmaceuticals GmbH |
| Sanofi |
| Genentech Inc. |
| Piramal Critical Care, Inc. |
| Saol Therapeutics |
| US WorldMeds, LLC |
| Others |
Value Network & Pricing Analysis
Site-of-care optimization contracts lock in both supply access and price visibility for paediatric spasticity interventions, bundling device, drug, and professional components into episode-based payments that United States cerebral palsy treatment networks negotiate directly with manufacturers.
Pricing Analysis
United States pricing for botulinum toxin formulations runs substantially above European and Asia-Pacific levels due to FDA paediatric exclusivity premiums and specialized injection protocol reimbursement. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center contracts from community rehabilitation programs and home-based oral medication tiers. Cost compression in the oral medication tier is intensifying because generic baclofen and diazepam face formulary restriction pressure from payors prioritizing site-of-care outcomes. Rehabilitation centers demonstrate the lowest price sensitivity due to bundled episode authority, while home care settings face the highest sensitivity as family-administered alternatives compete on out-of-pocket burden.
Supply Chain Analysis
Catheter manufacturing precision requirements concentrate programmable pump component sourcing in Germany, Switzerland, and the United States, where ISO 13485-certified medical device suppliers maintain sterile production lines. Baclofen active pharmaceutical ingredient production draws from India and Italy, while botulinum toxin bulk biologic processing rests on captive fermentation capacity in Ireland and France. Single-source vulnerability in programmable pump electronics creates exposure to semiconductor foundry allocation decisions. Distribution runs through specialized neurological device distributors serving paediatric rehabilitation centers, with direct-to-hospital contracting displacing traditional wholesale channels for high-value implantable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating within specialized cerebral palsy treatment networks that command episode-based procurement authority, fragmenting access for standalone product vendors unable to integrate across delivery modalities.
For Market Incumbents: Secure site-of-care contracting authority by embedding pump programming services within rehabilitation center workflows, defending against emerging closed-loop sensing platforms through backward integration into ambulatory monitoring technology. Deepen vertical integration of catheter manufacturing to reduce revision surgery liability exposure and utilization review scrutiny. For New Entrants and Emerging Players: Differentiate on paediatric-specific labeling pathways that compress FDA development timelines through Best Pharmaceuticals for Children Act incentives. Target stroke indication expansion as neuroimaging protocols widen detection and academic medical centers build dedicated paediatric stroke programs. Pursue European regulatory alignment early via EMA Paediatric Investigation Plans to capture first-mover positioning. For Investors and Strategic Acquirers: Capital is best deployed toward device-biologic convergence platforms that integrate closed-loop sensing with programmable drug delivery, positioning for premium reimbursement as ambulatory care shifts accelerate. Monitor CMS threshold determinations for combination drug-device therapy in home care settings as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Paediatric Exclusivity Pathway Capture | FDA incentives under the Best Pharmaceuticals for Children Act compress competitive windows for follow-on entrants. |
| Closed-Loop Sensing Integration | Real-time titration capability against spasticity episodes opens premium positioning in ambulatory settings. |
| Site-of-Care Optimization Contracting | Bundled episode payments with United States cerebral palsy treatment networks concentrate procurement authority. |
| EMA Paediatric Investigation Plan Alignment | Age-appropriate trial designs create first-mover advantages for European market access. |
| Catheter Failure Mode Mitigation | Mechanical complication reduction lowers revision surgery liability and utilization review exposure. |
Research Methodology
A spread of perspectives from paediatric physiatrists, hospital purchasing committee members, GPO contracts managers, and intrathecal pump programming specialists converged on the working assumptions underpinning intervention volume and reimbursement trajectory estimates. Primary interview data combined with secondary validation from FDA orphan drug designation filings, CMS Medicare reimbursement determinations, ClinicalTrials.gov paediatric spasticity trial records, and EMA Paediatric Investigation Plan documentation. Bottom-up demand modeling across treatment modalities triangulated against top-down healthcare expenditure allocation patterns.
Treatment type, indication severity, delivery mode precision, and end-user procurement authority segmentation dimensions modeled volume and value outputs across the projection horizon. CAGRs derived from regression analysis of historical intervention growth rates adjusted for regulatory pathway acceleration effects and site-of-care shift elasticities. Forecast inputs incorporated FDA paediatric exclusivity grant timelines and CMS episode-based payment expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained orphan drug incentive continuity and rehabilitation center infrastructure investment would require recalibration. Practitioners should keep alternative scenarios live as CMS reimbursement threshold determinations and catheter failure rate trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric MRI Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Perfusion Products Market