
 Asia-Pacific CBD Patch Market | 2026-2036
Asia-Pacific CBD Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific CBD Patch Market Outlook
Good Manufacturing Practice certification for transdermal pharmaceutical products is unwinding competitive access across the Asia-Pacific CBD Patch landscape. Hisamitsu Pharmaceutical Co., Inc. leverages decades of patch-manufacturing expertise to anchor its position in Japan's regulated pharmacy channel. Tilray competes through controlled-cultivation supply chains that sustain formulation consistency for medical-grade products. Charlotte's Web differentiates via brand recognition and broad-spectrum formulations that occupy premium positioning in Australian online retail.
A CBD patch is an adhesive transdermal delivery system containing cannabidiol extract, typically formulated with permeation enhancers such as terpenes or chemical absorption promoters to achieve steady-state plasma concentrations over 24–96 hours. The device releases cannabinoids through the stratum corneum into systemic circulation, primarily serving pain management, inflammation reduction, and anxiety modulation in medical and wellness applications. Transdermal patches lead product type revenue due to superior bioavailability and dosing precision, while full-spectrum formulations command margin premiums through the entourage effect. Online retail channels represent the fastest-growing distribution vector, though pharmacies retain structural importance for medical-user segments requiring prescriber oversight.
Australia's Therapeutic Goods Administration, Japan's Ministry of Health, Labour and Welfare, and South Korea's Ministry of Food and Drug Safety collectively shape market access through divergent scheduling, import licensing, and domestic cultivation rules. These frameworks fragment product registration pathways and elevate compliance costs for cross-border suppliers. Stakeholders must monitor rescheduling momentum, patch-specific clinical trial requirements, and evolving GMP harmonization between national regulators to anticipate priority market entry sequencing.
Market Dynamics
Rescheduling momentum across Australia's TGA and Japan's MHLW is fragmenting competitive access, forcing suppliers to pursue parallel GMP certifications while domestic cultivation rules in South Korea and Thailand create divergent supply base configurations.
Growth Catalysts
- TGA Rescheduling Pathway:Australia's low-dose CBD down-scheduling to Schedule 3 enables pharmacy distribution without prescription requirements, expanding addressable patient populations in chronic pain management.
- Aging Demographics:Japan's super-aged prefectures in Hokkaido and rural Honshu generate concentrated demand for non-opioid pain alternatives, with transdermal delivery preferred by polypharmacy patients.
- Permeation Enhancer Advances:Terpene-based absorption promoters and microneedle array technologies improve bioavailability coefficients, reducing required CBD loading per patch and manufacturing input costs.
Market Restraints
- Import Licensing Friction:Japan's MHLW maintains strict narcotics-control alignment for CBD isolates, requiring import permits that add 90-180 days to product registration timelines versus domestic synthetic alternatives.
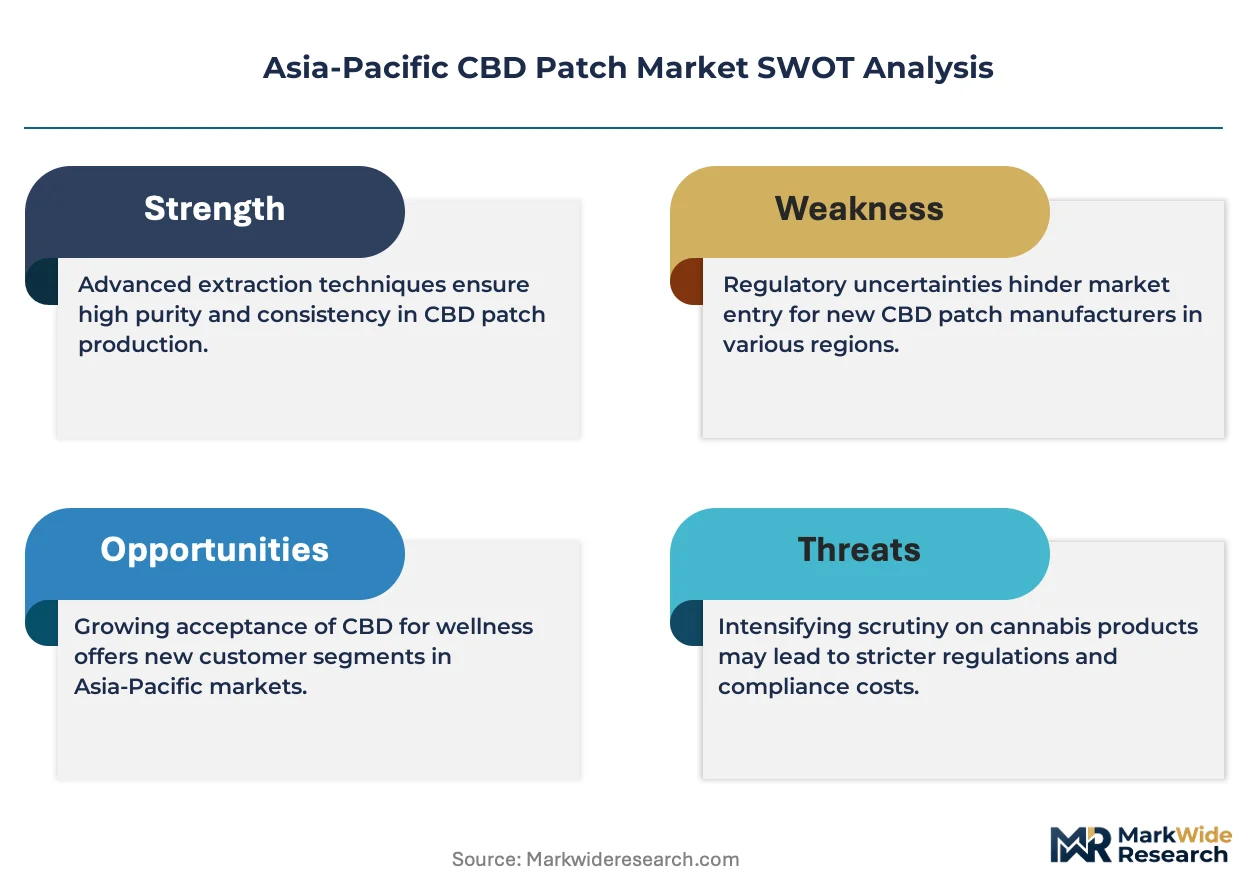
- Cultivation Supply Concentration:Australia's limited licensed cannabis cultivation creates raw material bottlenecks, with TGA GMP-certified extractors representing fewer than twelve operational facilities nationally.
- Pharmaceutical Substitution:Hisamitsu Pharmaceutical's existing lidocaine and fentanyl patch portfolios command pharmacy shelf space and prescriber familiarity, creating switching friction for CBD entrants.
Strategic Opportunities
- Thailand's Medical Cannabis Liberalization:The Thai FDA's 2022 removal of cannabis from Category 5 narcotics list enables domestic manufacturing and ASEAN export positioning for patch producers establishing GMP facilities in Bangkok-Phuket corridor.
- South Korea's MFDS Conditional Approval:Epidiolex-derived regulatory precedents create pathway for CBD patches in rare epilepsy adjunct therapy, with reimbursement negotiations opening public hospital procurement channels.
- Online Retail Channel Expansion:Australian e-commerce platforms bypass pharmacy margin structures, enabling direct-to-consumer subscription models for wellness-positioned broad-spectrum formulations.
Industry Challenges
- Transdermal Formulation Talent Scarcity:Polymer chemistry and skin permeation modeling expertise concentrates in Osaka-Kobe pharmaceutical cluster and Sydney biotech corridor, creating recruitment competition with established dermatology patch manufacturers.
- Clinical Trial Requirements:Japan's PMDA demands patch-specific pharmacokinetic studies with Japanese subjects, duplicating bioequivalence costs already incurred for FDA or EMA submissions.
- Cross-Border GMP Harmonization:Australia's TGA, Japan's PMDA, and South Korea's MFDS maintain non-mutual recognition of manufacturing inspections, forcing redundant facility audits for multi-country market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific CBD Patch Market |
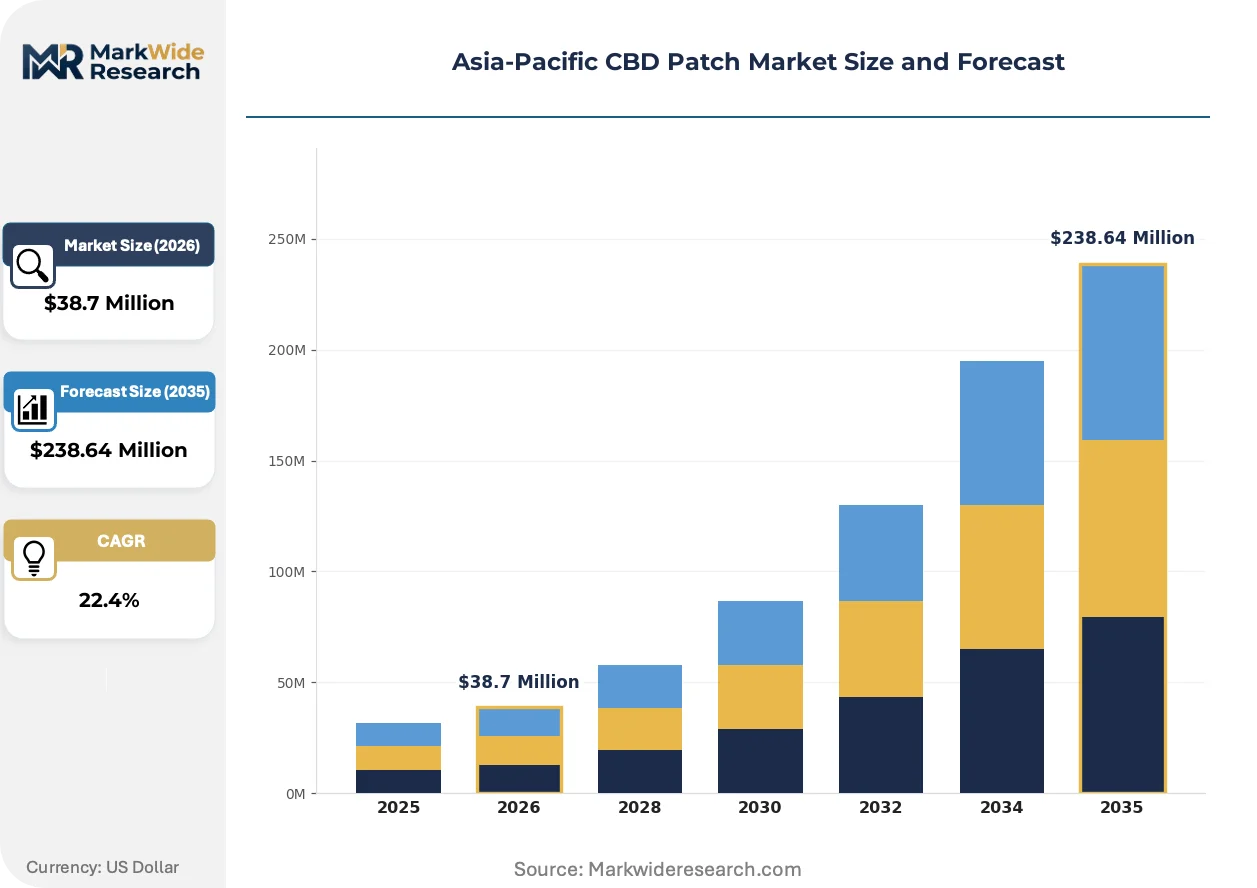
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $238.64 Million |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transdermal, Topical, Edible, Inhalable Target Audience: Medical Users, Recreational Users, Wellness Enthusiasts, Elderly Distribution Channel: Pharmacies, Online Retail, Convenience Stores, Specialty Shops Formulation: Isolate, Full-Spectrum, Broad-Spectrum, Others |
| Companies Covered | Aurora Cannabis, Tilray, CV Sciences, Inc., Charlotte's Web, Canopy Growth Corporation, Hisamitsu Pharmaceutical Co., Inc., Pure Kana, Pacific Roots, Mary’s Medicinals, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific CBD Patch Market Strategic Shifts
Permeation science advances and regulatory arbitrage strategies are compressing traditional product development cycles, while channel disintermediation reconfigures margin capture between manufacturers and end-users.
Microneedle-assisted CBD patches is supplanting conventional reservoir-type transdermal systems in Japan's hospital procurement evaluations. Osaka-based pain management clinics are piloting dissolvable hyaluronic acid microneedle arrays that breach the stratum corneum without dermal sensation, achieving therapeutic plasma levels at 40% lower CBD loading. This technology is supplanting oil-based permeation enhancers that require extended wear times and carry skin irritation liabilities.
Australia's TGA has introduced a dedicated cannabis therapeutic goods manufacturing standard that exceeds general pharmaceutical GMP in traceability and contamination control requirements. The standard mandates batch-level cannabinoid profiling and heavy metal screening for all imported raw materials, elevating compliance costs for offshore suppliers. Australian contract manufacturers with early certification are capturing formulation partnerships from multinational entrants seeking accelerated market entry.
Subscription-based replenishment models are displacing single-unit pharmacy purchases among Australian wellness consumers aged 35-55. Melbourne and Sydney direct-to-consumer platforms offer 90-day patch supplies with telehealth prescriber integration, capturing recurring revenue streams that pharmacy distribution cannot replicate. This behavioral shift concentrates in metropolitan wellness corridors where brand discovery occurs through social channels rather than clinician recommendation.
Asia-Pacific CBD Patch Market Segmentation
Channel fragmentation across the Asia-Pacific CBD Patch Market demands precise segment-channel alignment. Pharmacy and online retail pathways serve divergent user profiles with distinct regulatory requirements and margin structures.
Product Type:
Pharmacy channels favor reservoir-type systems requiring prescriber oversight, while online retail accelerates microneedle and topical formats for wellness consumers seeking self-administration convenience.
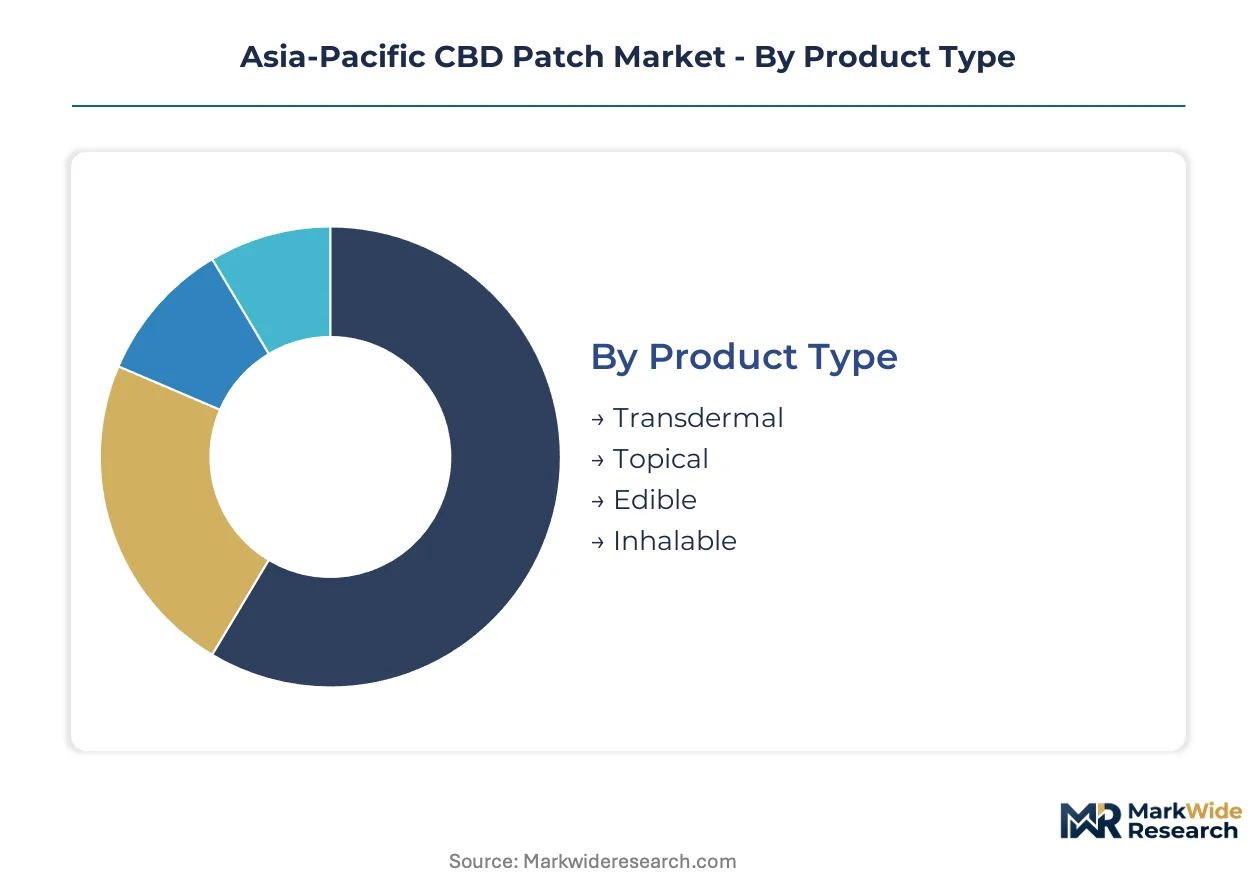
- Transdermal:Reservoir or matrix-type adhesive systems achieving steady-state plasma concentrations through stratum corneum penetration over 24–96 hour wear periods. Japan's polypharmacy elderly in Hokkaido prefectures drive hospital procurement of these systems as opioid alternatives.
- Topical:Surface-acting formulations delivering localized cannabinoid effects without systemic absorption. Australian metropolitan wellness corridors concentrate demand for topical patches through direct-to-consumer subscription platforms bypassing pharmacy margins.
- Edible:Oral delivery formats including gummies and capsules with delayed onset profiles.
- Inhalable:Vaporization and combustion-based delivery with rapid pharmacokinetics but pulmonary exposure liabilities.
Transdermal dominates installed base. Topical is where expansion concentrates.
Target Audience:
Cost tier stratification separates premium medical-grade products from mass-market wellness positioning, with reimbursement eligibility creating sharp price boundaries between segments.
- Medical Users:Patients with chronic pain, epilepsy, or inflammation conditions requiring TGA or MHLW-sanctioned products with batch-level cannabinoid profiling. Australia's Schedule 3 rescheduling expanded pharmacy access for this cohort without prescription requirements.
- Wellness Enthusiasts:Preventive health consumers aged 35–55 in Sydney and Melbourne seeking broad-spectrum formulations for stress modulation and sleep optimization. This segment purchases primarily through e-commerce subscription models with telehealth integration.
- Recreational Users:Adult consumers in Thailand's Bangkok-Phuket corridor accessing liberalized cannabis markets.
- Elderly:Super-aged populations in Japan's rural Honshu prefectures requiring transdermal delivery to avoid polypharmacy complications.
Medical Users command premium pricing through reimbursement channels. Wellness Enthusiasts are gaining share fastest through direct-to-consumer displacement.
Distribution Channel:
Volume concentration favors pharmacy procurement in regulated medical markets, while customer acquisition costs and margin capture favor online retail in wellness segments.
- Pharmacies:Regulated dispensing points requiring TGA Schedule 3 compliance or MHLW import licensing, with Hisamitsu Pharmaceutical's established patch portfolios commanding shelf space and prescriber familiarity in Japan.
- Online Retail:Direct-to-consumer platforms enabling subscription replenishment and brand discovery through social channels, concentrated in Australian metropolitan corridors where Melbourne and Sydney platforms capture recurring revenue streams.
- Convenience Stores:Limited low-dose product availability in Thailand's liberalized retail environment.
- Specialty Shops:Cannabis-focused retailers serving recreational demand in Bangkok-Phuket corridor.
Pharmacies dominate medical-grade volume. Online Retail is where margin expansion concentrates.
Formulation:
Maturity gradients separate established isolate products from emerging full-spectrum offerings, with certification requirements and supply base configuration determining competitive access.
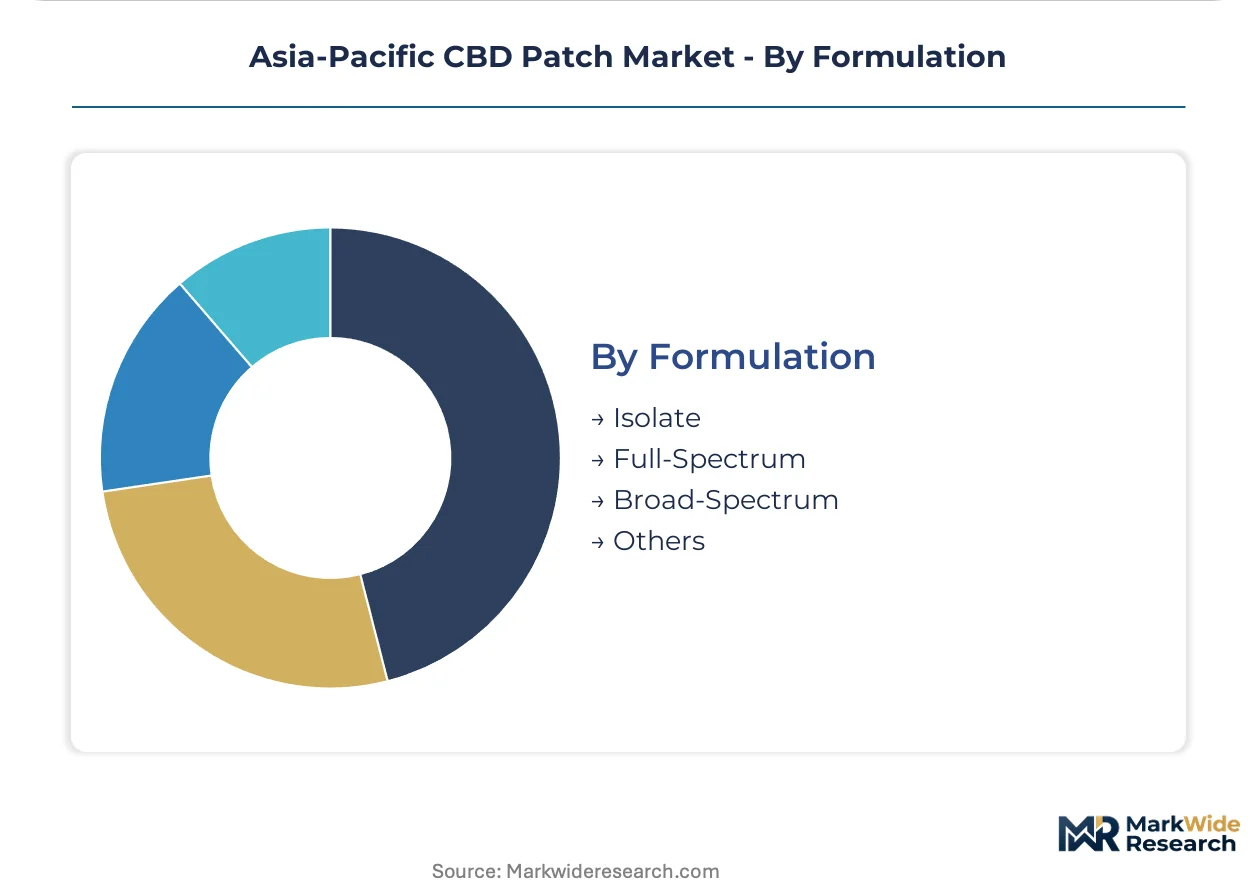
- Isolate:Purified CBD without additional cannabinoids or terpenes, favored by Japan's MHLW for narcotics-control alignment and standardized dosing in clinical settings. Import licensing friction of 90–180 days favors domestic synthetic alternatives.
- Full-Spectrum:Whole-plant extracts retaining THC within legal thresholds to leverage entourage effect synergies. Australian online retail platforms position these formulations at premium price points for wellness consumers seeking enhanced bioactivity.
- Broad-Spectrum:THC-free whole-plant extracts preserving minor cannabinoids and terpenes for entourage benefits without psychoactive liability.
- Others:Nano-emulsion and liposomal delivery formats in early commercialization.
Isolate dominates regulatory-cleared supply. Full-Spectrum is where premium positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rescheduling momentum across Australia's TGA and Japan's MHLW is fragmenting competitive access, forcing suppliers to pursue parallel GMP certifications while domestic cultivation rules in South Korea and Thailand create divergent supply base configurations.
Australia
Chronic pain management clinics in Sydney and Melbourne drive transdermal patch procurement. TGA's Schedule 3 down-scheduling of low-dose CBD products opened pharmacy distribution pathways without prescription requirements. Melbourne's biotech corridor hosts fewer than twelve TGA GMP-certified extractors, creating raw material bottlenecks for multinational entrants.
Japan
Super-aged prefectures in Hokkaido and rural Honshu generate concentrated demand for non-opioid pain alternatives. MHLW maintains strict narcotics-control alignment for CBD isolates, requiring import permits that add 90-180 days to product registration timelines. Osaka-Kobe pharmaceutical cluster concentrates polymer chemistry and skin permeation modeling expertise.
South Korea
MFDS conditional approval pathways for Epidiolex-derived products create entry vectors for rare epilepsy adjunct therapy. Seoul's hospital procurement channels open through reimbursement negotiations for medical-grade formulations. Domestic cultivation restrictions force reliance on imported raw materials with batch-level cannabinoid profiling requirements.
Thailand
Thai FDA's 2022 removal of cannabis from Category 5 narcotics list enables domestic manufacturing. Bangkok-Phuket corridor attracts patch producers establishing GMP facilities for ASEAN export positioning. Convenience store distribution of low-dose products supplements pharmacy channels in liberalized retail environments.
China
Industrial hemp cultivation in Yunnan and Heilongjiang provinces supplies CBD isolate feedstock for regional export markets. NMPA maintains prohibition on cannabinoid pharmaceutical products, limiting domestic demand to cosmetics and wellness applications. Shanghai and Guangzhou contract manufacturers serve as formulation hubs for Asia-Pacific re-export.
Asia-Pacific CBD Patch Market Competitive Environment
Player mix skews toward pharmaceutical incumbents with transdermal manufacturing heritage and cannabis-specialized suppliers with controlled-cultivation supply chains. Market structure exhibits tiered concentration, with established patch manufacturers commanding pharmacy shelf space while wellness-positioned brands capture online retail margins. Two strategic archetypes dominate: pharmaceutical patch specialists leveraging decades of permeation science expertise, and cannabis pure-plays competing through formulation consistency and brand recognition. Competitive moves center on GMP certification racing and direct-to-consumer channel disintermediation.
Within the pharmaceutical heritage tier, Hisamitsu Pharmaceutical Co., Inc. anchors Japan's regulated pharmacy channel through established lidocaine and fentanyl patch portfolios. Among North American cannabis pure-plays, Tilray and Charlotte's Web occupy positions representing controlled-cultivation supply chain models and premium broad-spectrum formulation strategies respectively. Aurora Cannabis and Canopy Growth Corporation exemplify diversified cannabis conglomerates with Asia-Pacific market development capabilities.
| Leading Market Players |
|---|
| Aurora Cannabis |
| Tilray |
| CV Sciences, Inc. |
| Charlotte's Web |
| Canopy Growth Corporation |
| Hisamitsu Pharmaceutical Co., Inc. |
| Pure Kana |
| Pacific Roots |
| Mary's Medicinals |
| Others |
Value Chain & Pricing Dynamics
GMP-certified extraction capacity under 12 operational facilities across Australia concentrates upstream supply and establishes hard price floors for medical-grade formulations. Japan's 90-180 day import licensing timelines for CBD isolates amplify this concentration effect, forcing multinational entrants to absorb premium contract manufacturing markups or pursue parallel domestic certification investments.
Pricing Analysis
Certification level creates the primary spread between medical-grade and wellness-positioned products, with TGA Schedule 3 compliance commanding 40-60% premiums over unregulated online alternatives. Three-tier pricing structure across premium full-spectrum, standard broad-spectrum, and economy isolate levels reflects formulation complexity and batch-level cannabinoid profiling requirements. Cost compression in the wellness tier intensifies as Australian direct-to-consumer platforms bypass pharmacy margin structures, while medical users exhibit lowest price sensitivity due to reimbursement eligibility and prescriber-directed procurement.
Supply Chain Analysis
Strait of Malacca transit routes for imported raw materials expose patch manufacturers to logistics chokepoint risks, with Australian and Japanese facilities drawing from Chinese industrial hemp cultivation in Yunnan and Heilongjiang provinces. Active pharmaceutical ingredient dependencies center on CBD isolate feedstock, terpene permeation enhancers, and medical-grade adhesive polymers sourced from Osaka-Kobe and Sydney biotech clusters. Single-source vulnerability concentrates in TGA GMP-certified extractors, with distribution running through pharmacy procurement in regulated channels and direct-to-consumer platforms in wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through GMP certification creates durable defensive moats, as TGA, PMDA, and MFDS maintain non-mutual recognition of manufacturing inspections that force redundant facility audits for multi-country access.
For Market Incumbents: Fortify pharmacy channel control through prescriber education programs and formulary placement investments, countering direct-to-consumer disintermediation threats from Australian wellness platforms. Deepen backward integration into domestic cultivation by securing licensed extractor partnerships in Melbourne's biotech corridor, reducing raw material bottlenecks that constrain formulation capacity.
For New Entrants and Emerging Players: Telehealth integration gaps in chronic pain management workflows offer white-space entry vectors, with Japanese super-aged prefectures presenting the most penetrable medical segment due to polypharmacy-driven demand for non-opioid alternatives. Australian metropolitan wellness corridors enable lowest customer acquisition costs through social-channel brand discovery, with subscription-based replenishment models capturing recurring revenue streams unavailable to pharmacy-dependent incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with early TGA cannabis therapeutic goods certification, as patch-specific formulation expertise concentrates in Sydney and Osaka-Kobe clusters with limited talent mobility. Acquisition targets should demonstrate established GMP facilities, existing prescriber relationships, and microneedle array development capabilities. The signal to watch is MFDS reimbursement negotiation momentum for rare epilepsy adjunct therapy, which would unlock public hospital procurement channels and validate medical-grade pricing premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Racing | Early TGA cannabis manufacturing standard compliance captures multinational formulation partnerships seeking accelerated Australian market entry. |
| Microneedle Technology Licensing | Osaka-based dissolvable hyaluronic acid arrays achieve therapeutic plasma levels at reduced CBD loading, displacing conventional reservoir systems. |
| Direct-to-Consumer Platform Launch | Melbourne and Sydney subscription models bypass pharmacy margins and capture recurring revenue from wellness consumers aged 35-55. |
| Domestic Cultivation Integration | Backward integration into licensed Australian extractors mitigates raw material bottlenecks from fewer than twelve TGA-certified facilities. |
| ASEAN Export Hub Establishment | Bangkok-Phuket corridor GMP facilities leverage Thai FDA liberalization for regional manufacturing and cross-border distribution positioning. |
Study Parameters
Cross-validation between primary interviews with regulatory affairs leads, hospital procurement managers, pharmacy formulary directors, and pain management clinicians and secondary validation through TGA scheduling determinations, MFDS conditional approval filings, and Thai FDA narcotics reclassification records anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down macroeconomic indicators and demographic projections across the analysis window.
Sensitivity analysis on rescheduling momentum, patch-specific clinical trial requirements, and GMP harmonization progress shapes the analytical framework. Segmentation dimensions include product type, target audience, distribution channel, and formulation complexity, with CAGRs derived from installed base growth rates and pricing trajectory assumptions. Industry-specific inputs incorporate permeation enhancer technology adoption curves and online retail channel penetration patterns.
Underlying assumptions cover regulatory rescheduling timelines, domestic cultivation license issuance rates, and microneedle array commercialization progress, with deviation risk concentrated in import licensing friction duration and cross-border GMP inspection recognition agreements. Practitioners should keep alternative scenarios live as TGA-PMDA-MFDS regulatory convergence and Thai ASEAN export positioning evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Global Marijuana Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Cannabis Vaporizers Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Morocco Medical Cannabis Market
Cannabis/Marijuana
Global Cannabis Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Legal Cannabis Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
North America Medical Cannabis Market