
 Cannabinoids Market | 2026-2036
Cannabinoids Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabinoids Market Analysis
Project finance and revenue-sharing partnerships with cultivation facilities is reshaping competitive entry in the cannabinoids sector, lowering capital barriers for mid-tier operators. Curaleaf leverages vertically integrated cultivation and retail networks across multiple state jurisdictions. Tilray Brands anchors its position through pharmaceutical-grade manufacturing capacity and European medical cannabis distribution. Green Thumb Industries competes via tightly controlled retail footprints and proprietary brand portfolios in regulated state markets.
Cannabinoids comprise bioactive compounds—primarily cannabidiol, tetrahydrocannabinol, and minor phytocannabinoids—extracted from Cannabis sativa and formulated to specified purity thresholds for therapeutic or wellness applications. These compounds modulate endocannabinoid receptor activity for pain management, seizure reduction, and anxiolytic effect. CBD Oil dominates product-type revenue pools due to broad regulatory acceptance and wellness-category placement, while THC Oil captures premium margins in state-legal medical and adult-use channels. Oral delivery modes sustain the fastest growth trajectory as healthcare providers and pharmacies seek standardized dosing formats over inhalation methods.
FDA oversight of cannabidiol-based therapeutics and state-level cannabis regulatory frameworks in the United States collectively determine product formulation standards, testing protocols, and interstate commerce permissions. EMA's Committee for Medicinal Products for Human Use shapes European medical cannabis access through centralized marketing authorization pathways. Stakeholders must monitor evolving scheduling decisions and Good Manufacturing Practice enforcement as these regulatory instruments directly dictate addressable market boundaries and competitive qualification requirements.
Market Dynamics
State-level dispensary licensing waves and FDA cannabidiol pathway maturation are compressing competitive qualification timelines while fragmenting addressable market boundaries across United States jurisdictions.
Growth Catalysts
- FDA Epidiolex Precedent:The agency's plant-derived therapeutic approval framework established manufacturing and clinical trial benchmarks that pharmaceutical developers now replicate for seizure and chronic pain indications.
- Germany Medical Cannabis Expansion:BfArM reimbursement listings and pharmacy distribution mandates pulled insured patient volumes into standardized cannabinoid protocols.
- Supercritical CO2 Extraction Scaling:Equipment throughput improvements at cultivation facilities reduced cannabinoid isolation costs while hitting pharmaceutical-grade purity thresholds.
Market Restraints
- Input Cost Volatility:Energy-intensive indoor cultivation in Colorado and California faces electricity rate spikes that compress margin structures for THC-dominant flower production.
- Interstate Commerce Prohibition:The United States Controlled Substances Act maintains state-boundary barriers that prevent California cultivation surplus from reaching New York patient demand.
- Banking Access Limitations:Federal Schedule I classification blocks FDIC-insured lending to cultivation operators, forcing reliance on private credit at premium rates.
Strategic Opportunities
- Brazil ANVISA Import Pathway:The regulator's medical cannabis import authorization framework opened patient access for standardized oil formulations with documented stability data.
- Oral Solid Dose Convergence:Pharmaceutical contract manufacturers with tablet and capsule lines are repurposing equipment for cannabinoid microencapsulation, enabling pharmacy shelf placement.
- Australia TGA Special Access Scheme:The streamlined prescriber approval process accelerated specialist physician adoption for chemotherapy-induced nausea and palliative care applications.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Cannabinoid quantification and terpene profiling require mass spectrometry expertise that competes with broader pharmaceutical quality control hiring pools.
- Batch Release Timeline Compression:State-mandated testing backlogs in Oklahoma and Michigan delay product movement from cultivation to retail, trapping working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabinoids Market |
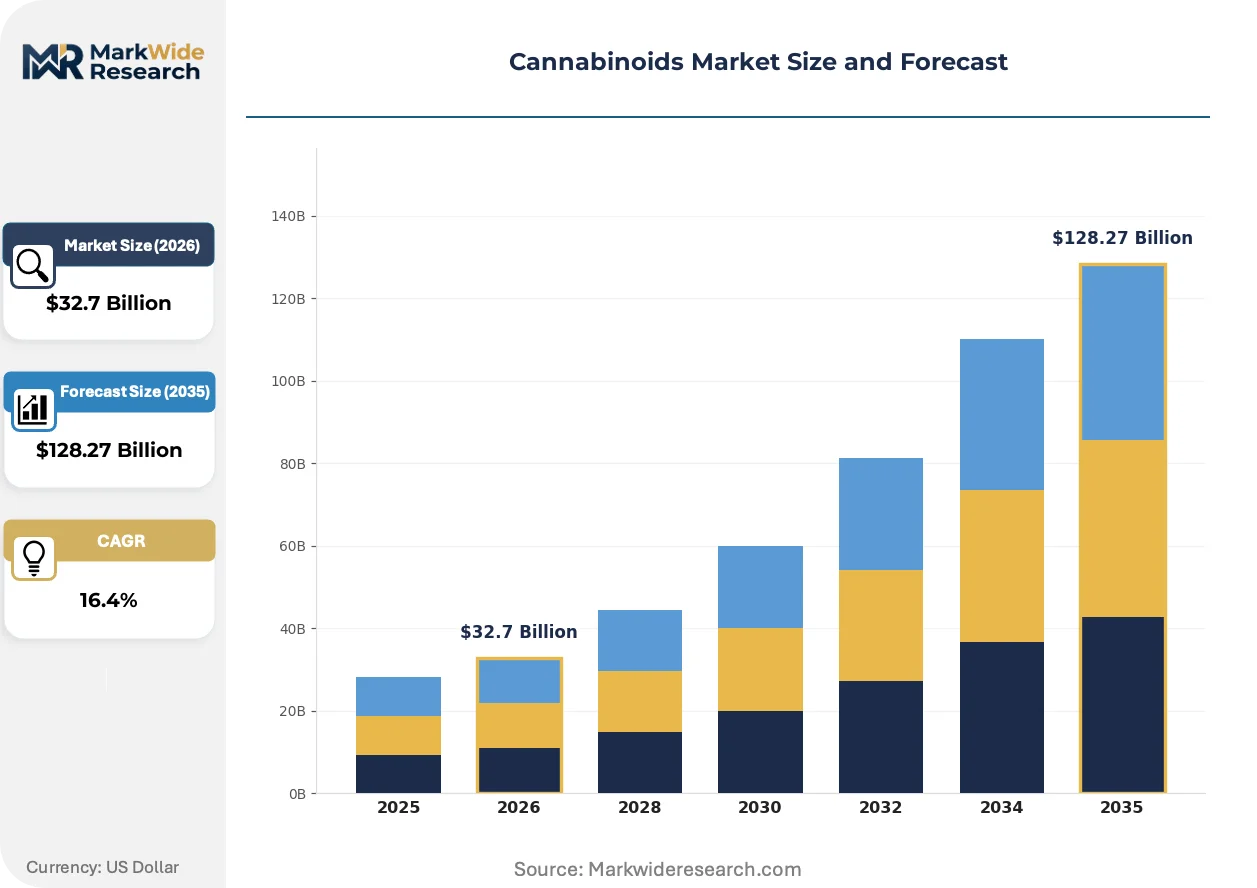
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $128.27 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CBD Oil, THC Oil, Capsules, Edibles Therapy Area: Chronic Pain, Anxiety, Epilepsy, Cancer Delivery Mode: Topical, Inhalation, Oral, Sublingual End User: Retail Consumers, Healthcare Providers, Dispensaries, Pharmacies |
| Companies Covered | Curaleaf, Green Thumb Industries, Trulieve, Tilray Brands, Canopy Growth Corporation, Cresco Labs, Cronos Group, Aurora Cannabis, Charlotte’s Web Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabinoids Market Emerging Trajectories
Precision agriculture systems and pharmaceutical manufacturing standards are converging to reshape how cannabinoid content gets standardized, traced, and dosed across medical and wellness channels.
Blockchain seed-to-sale tracking is digitizing custody documentation across California and Colorado supply chains. State regulators mandate immutable transaction records for plant material movement. Cultivation operators adopting distributed ledger platforms compress audit preparation timelines while satisfying FDA supply chain security guidance for investigational drug applications.
EMA's centralized marketing authorization pathway for medical cannabis extracts is harmonizing stability testing and bioequivalence requirements across Germany, Italy, and Poland. Manufacturers must now submit Module 3 quality documentation mirroring synthetic pharmaceutical standards. Dutch and Danish cultivation facilities are restructuring GMP cleanroom capacity to meet batch release specifications.
Healthcare provider prescribing patterns are consolidating around standardized oil tinctures with documented cannabinoid ratios. Dispensary buyers in Florida and Pennsylvania now reject flower SKUs lacking certificate of analysis transparency. This preference compression favors operators with in-house analytical laboratories over wholesale-dependent competitors.
Cannabinoids Market Segmentation
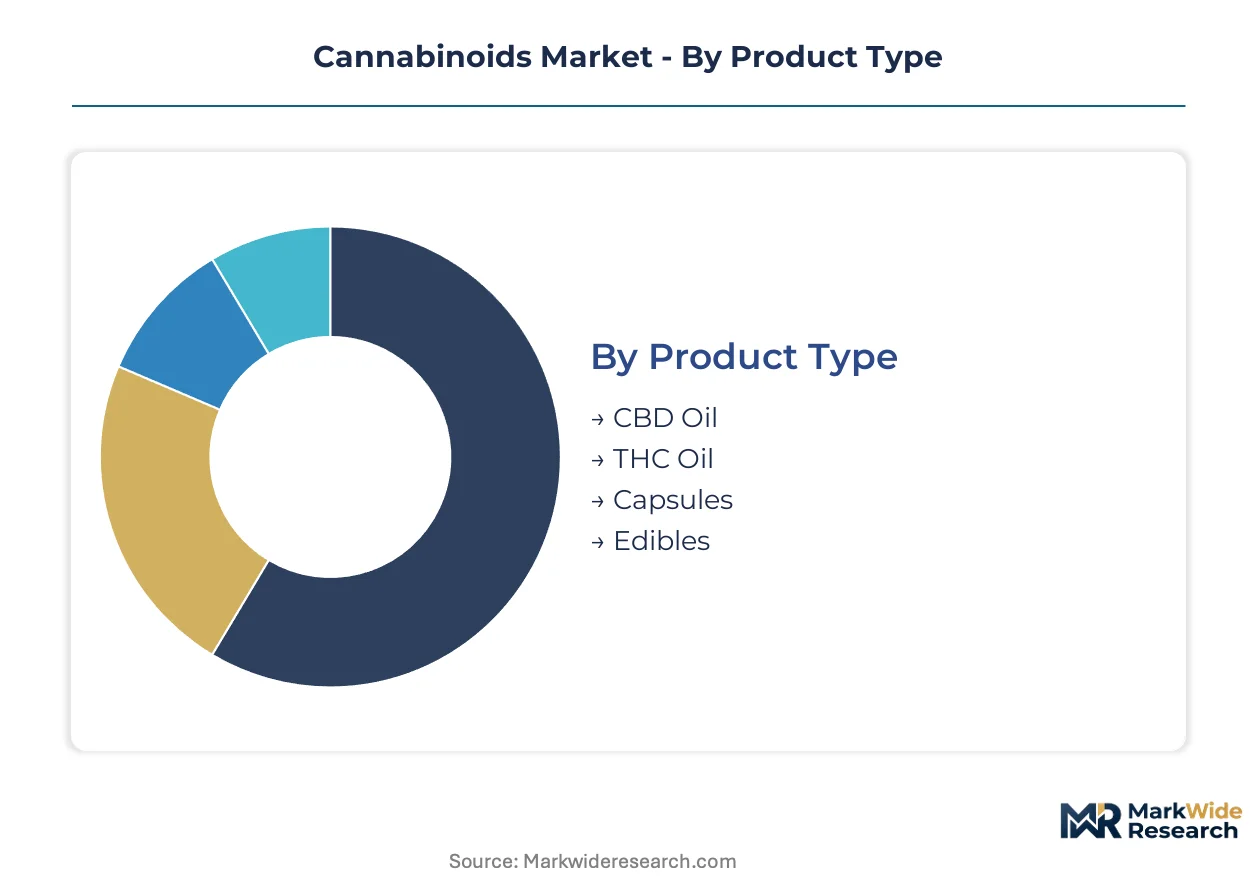
Cannabinoid market boundaries fragment across formulation chemistry, clinical application, and distribution channel. Each segmentation dimension carries distinct regulatory requirements and margin structures that reshape competitive positioning.
Product Type:
Cost tier differentiation separates wellness-accessible formats from prescription-grade therapeutics with GMP certification overhead.
- CBD Oil:Broad-spectrum and isolate formulations dominate wellness retail placement with THC thresholds below 0.3 percent. United States pharmacy chains now stock standardized tinctures as OTC adjacent products, though FDA marketing restrictions limit explicit therapeutic claims.
- THC Oil:Full-spectrum extracts with documented cannabinoid ratios command premium positioning in state-legal medical channels. California and Colorado extraction facilities scale supercritical CO2 throughput to meet pharmaceutical purity specifications for Epidiolex-class development pipelines.
- Capsules:Microencapsulation enables precise dosing compliance for clinical trial protocols.
- Edibles:Gummy and beverage formats face variable onset-time criticism from pain management specialists.
CBD Oil commands the established base. The steepest expansion runs through THC Oil.
Therapy Area:
Application maturity determines reimbursement pathway availability and prescriber comfort thresholds across medical systems.
- Chronic Pain:Opioid-sparing protocols in Germany and Australia now list cannabinoid extracts as second-line options. BfArM reimbursement codes and TGA Special Access Scheme approvals pulled standardized oil formulations into pain clinic formularies.
- Epilepsy:FDA Epidiolex approval established the regulatory precedent for plant-derived anticonvulsants. GW Pharmaceuticals demonstrated that CBD isolation meets pharmaceutical bioequivalence standards, opening follow-on trials for Dravet and Lennox-Gastaut variants.
- Anxiety:Wellness marketing dominates with clinical evidence gaps limiting prescription penetration.
- Cancer:Chemotherapy-induced nausea applications concentrate in palliative care settings with limited curative integration.
Chronic Pain anchors current revenue pools. Epilepsy applications are climbing the fastest toward formalized reimbursement.
Delivery Mode:
Volume concentration shifts toward standardized dosing formats as healthcare systems prioritize pharmacokinetic predictability over onset speed.
- Oral:Capsules and tablets enable exact milligram specification for clinical documentation. Pennsylvania and Florida dispensary buyers now reject flower SKUs lacking certificate of analysis transparency, consolidating procurement around ingestible formats.
- Inhalation:Vaporization delivers rapid onset for breakthrough pain episodes. Colorado and California retail channels maintain flower dominance, though medical prescribers increasingly discourage pulmonary administration.
- Topical:Transdermal patches target localized inflammation with minimal systemic absorption.
- Sublingual:Tincture strips compete with oil drops on convenience metrics.
Inhalation retains the legacy installed base. Oral formats are gaining share fastest through pharmacy channel expansion.
End User:
Customer type segmentation maps directly to regulatory qualification requirements and pricing power differentials.
- Healthcare Providers:Specialist physicians in Australia and Germany now initiate cannabinoid protocols through streamlined approval frameworks. TGA and BfArM prescriber registration systems capture patient outcome data that reinforces formulary inclusion.
- Pharmacies:German pharmacy distribution mandates pull insured patient volumes into standardized cannabinoid protocols with full reimbursement coverage.
- Dispensaries:State-licensed retail in United States jurisdictions faces testing backlog constraints in Oklahoma and Michigan.
- Retail Consumers:Wellness-category placement in United States health food channels competes on price per milligram of CBD content.
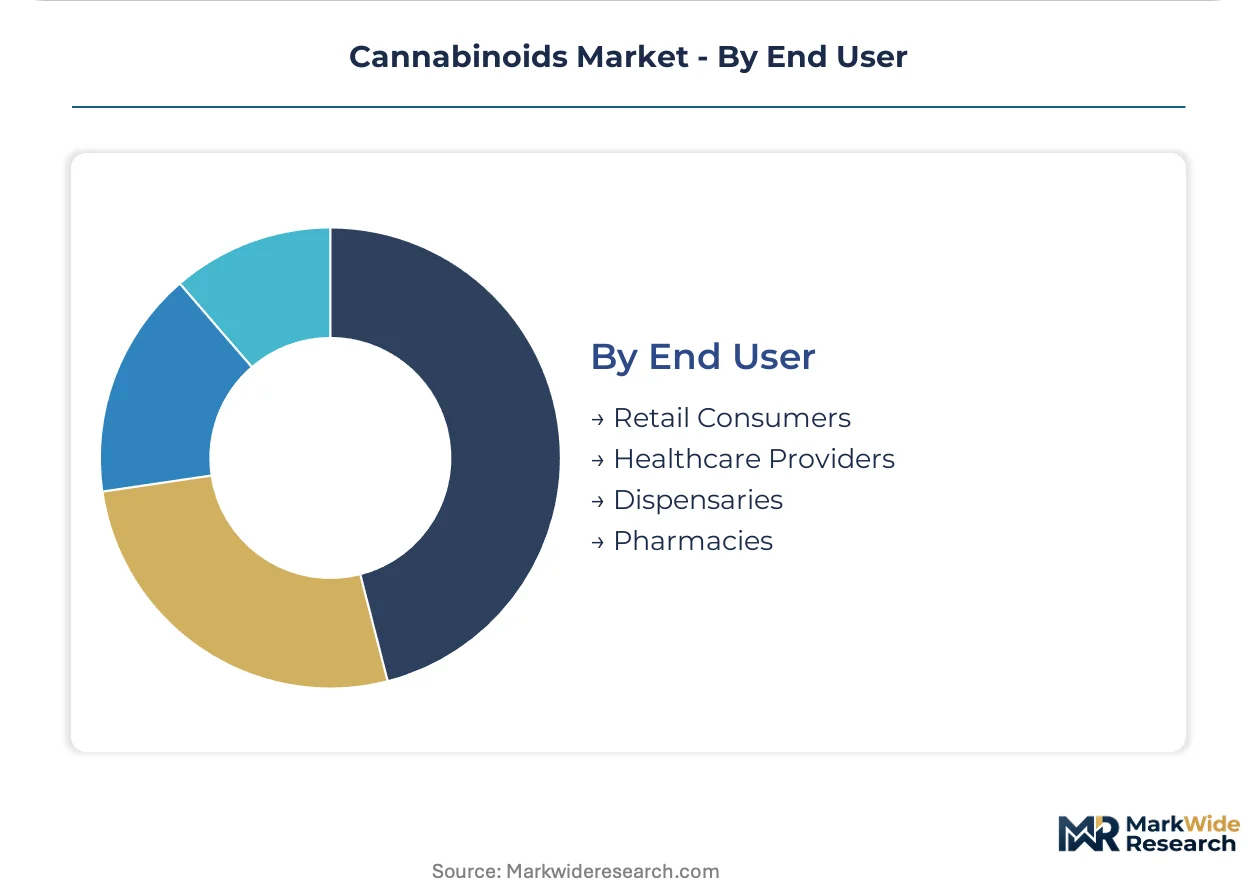
Retail Consumers command the established base. Healthcare Providers represent the steepest expansion trajectory through reimbursement integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pathway maturation and EMA centralized authorization are pulling capital toward jurisdictions with clarified reimbursement frameworks. State-level licensing waves in the United States and pharmacy distribution mandates in Germany concentrate operational scale where regulatory visibility exists.
United States
State dispensary licensing expansions in Florida and Pennsylvania drive patient volume growth. FDA Epidiolex approval established pharmaceutical-grade manufacturing benchmarks for plant-derived therapeutics. California and Colorado extraction clusters scale supercritical CO2 capacity to meet purity specifications for clinical trial supply chains.
Germany
BfArM reimbursement listings pull insured chronic pain patients into standardized cannabinoid protocols. EMA centralized marketing authorization harmonizes stability testing requirements across member states. Dutch and Danish cultivation facilities restructure GMP cleanroom capacity to serve German pharmacy distribution mandates.
Australia
TGA Special Access Scheme streamlined prescriber approvals for chemotherapy-induced nausea applications. Specialist physician adoption concentrates in New South Wales and Victoria oncology networks. Sydney and Melbourne analytical laboratories build mass spectrometry capacity for batch release testing under import substitution pressure.
Canada
Health Canada licensing frameworks support export-oriented pharmaceutical-grade production. Ontario and British Columbia cultivation facilities redirect output toward European medical cannabis markets as domestic adult-use pricing compresses. Toronto contract manufacturers repurpose tablet lines for cannabinoid microencapsulation.
Brazil
ANVISA import authorization frameworks opened patient access for documented oil formulations. Private healthcare coverage expansion in São Paulo and Rio de Janeiro drives specialist prescriber adoption. Local distribution partnerships with Portuguese-speaking suppliers reduce customs clearance timelines for stability-validated products.
Cannabinoids Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented jurisdictional boundaries. United States multi-state operators leverage retail footprint density against Canadian licensed producers with pharmaceutical manufacturing credentials. Three archetypes dominate: vertically integrated cultivators with dispensary networks, pharmaceutical-grade manufacturers with GMP certification, and wellness-focused brands with retail distribution partnerships. Competitive moves concentrate on state-level license acquisitions and European distribution partnerships.
Among North American operators, Curaleaf and Green Thumb Industries exemplify multi-state retail density strategies, while Tilray Brands occupies a position bridging pharmaceutical manufacturing scale with European medical cannabis distribution. These three anchors represent contrasting responses to regulatory fragmentation: captive retail networks versus GMP-certified export capacity.
| Leading Market Players |
|---|
| Curaleaf |
| Green Thumb Industries |
| Trulieve |
| Tilray Brands |
| Canopy Growth Corporation |
| Cresco Labs |
| Cronos Group |
| Aurora Cannabis |
| Charlotte's Web Holdings |
| Others |
Supply Flow & Price Mechanics
Federal Schedule I banking restrictions tether capital costs to extraction facility economics, compressing margin structures at cultivation-dependent operators while widening spreads between GMP-certified pharmaceutical grades and wellness-category CBD oils. This regulatory chokepoint forces private credit reliance at premium rates, which feeds backward into supply chain configuration favoring vertically integrated operators with captive financing capacity.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and wellness-category products. Three-tier pricing structure across GMP-certified extracts, state-compliant medical oils, and broad-spectrum CBD isolates dominates transactional flows. Pricing pressure stems from electricity rate volatility at indoor cultivation facilities in Colorado and California, which compresses THC-dominant flower margins. Retail consumers exhibit highest price sensitivity per milligram of CBD content, while healthcare providers prioritize batch consistency over unit cost.
Supply Chain Analysis
Tariff exposure between Canadian extraction facilities and German pharmacy distributors dominates cross-border risk assessment. Supply concentrates in California, Colorado, and Ontario cultivation clusters that feed pharmaceutical-grade output toward European medical cannabis markets. Raw material dependencies rest on supercritical CO2 equipment, analytical chemistry reagents, and climate-controlled logistics infrastructure. Single-source vulnerability sits with mass spectrometry expertise for batch release testing. Distribution runs through state-licensed dispensary networks in the United States and pharmacy mandates in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass spectrometry proficiency for cannabinoid quantification and terpene profiling represents the binding constraint on batch release velocity, with qualified analytical chemists competing against broader pharmaceutical quality control hiring pools.
For Market Incumbents: Entrench position through GMP cleanroom capacity expansion in jurisdictions with clarified EMA centralized authorization pathways. Acquire in-house analytical laboratory capabilities to compress batch release timelines against Oklahoma and Michigan testing backlogs. Prioritize backward integration into supercritical CO2 extraction equipment to isolate margin from energy cost volatility. For New Entrants and Emerging Players: Pursue white-space opportunities in Brazil's ANVISA import pathway for stability-documented oil formulations. Target Australia's TGA Special Access Scheme prescriber networks in New South Wales and Victoria oncology clusters. Lead with oral solid dose formats that enable pharmacy shelf placement through pharmaceutical contract manufacturing partnerships. For Investors and Strategic Acquirers: The market sits at a regulatory-clarification phase that favors GMP-certified manufacturers with European distribution partnerships over multi-state retail operators facing interstate commerce barriers. Long-term viability hinges on reimbursement pathway integration across German BfArM and Australian TGA frameworks. Target acquisition archetype: mid-tier extraction facilities with pharmaceutical-grade capacity and underutilized cleanroom infrastructure. Monitor FDA scheduling decisions as the critical inflection signal for capital reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | EMA centralized marketing authorization requires Module 3 quality documentation mirroring synthetic pharmaceutical standards. |
| Oral Solid Dose Development | Pennsylvania and Florida dispensary buyers reject flower SKUs lacking certificate of analysis transparency. |
| European Distribution Partnership | German pharmacy distribution mandates pull insured patient volumes into standardized cannabinoid protocols. |
| Blockchain Seed-to-Sale Tracking | California and Colorado regulators mandate immutable transaction records for plant material movement. |
| Supercritical CO2 Capacity Expansion | Equipment throughput improvements reduce isolation costs while hitting pharmaceutical-grade purity thresholds. |
Methodological Framework
Operator-level perspectives from extraction facility managers, pharmaceutical regulatory affairs leads, dispensary procurement directors, and analytical laboratory directors anchored the qualitative base. Secondary validation drew from FDA Epidiolex approval documentation, EMA centralized marketing authorization submissions, BfArM reimbursement listings, and TGA Special Access Scheme prescriber registration data. Bottom-up patient volume modeling across state jurisdictions triangulated against top-down pharmaceutical manufacturing capacity assessments.
Scenario-bracketing around FDA scheduling decisions and EMA pathway maturation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product formulation chemistry, therapy area application, delivery mode standardization, end-user channel type, and regional regulatory cluster. CAGRs derived from patient volume trajectories, pricing tier elasticity, and manufacturing capacity expansion schedules. Forecast inputs incorporated supercritical CO2 equipment throughput improvements and German pharmacy distribution mandate compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in electricity rate trajectories at indoor cultivation facilities or private credit availability terms would shift the trajectory. Forecasts reflect assumptions around regulatory pathway maturation and prescriber adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Cannabis Vaporizers Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market