
 Cannabis Edibles Market | 2026-2036
Cannabis Edibles Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Edibles Market Analytics
Recreational consumers is reorganizing demand away from legacy flower buyers toward precisely dosed, discreet formats. WYLD dominates fruit-infused gummy production with multi-state distribution. Cresco Labs anchors supply through backward integration into cultivation and extraction. Curaleaf Holdings, Inc. extends reach via owned retail footprints across high-velocity markets.
Cannabis edibles comprise food and beverage products infused with extracted cannabinoids, typically formulated with measured THC or CBD concentrations and stabilized through lipid-based emulsification or nanoencapsulation for bioavailability. These products serve both recreational intoxication and therapeutic symptom management, with onset times ranging from thirty minutes to two hours depending on formulation chemistry. Gummies lead volume due to shelf stability and dose precision, while chocolates capture premium margin pools through artisan positioning. Beverages represent the fastest-growing category as nanoemulsion technology compresses onset latency. Baked goods remain mature with slower growth, constrained by shorter shelf life and inconsistent cannabinoid distribution.
FDA maintains prohibition on interstate commerce and novel food additive claims, while individual state cannabis regulators such as Colorado's Marijuana Enforcement Division and California's Department of Cannabis Control enforce testing, labeling, and packaging standards that directly shape product form factors and market access. The 2018 Farm Bill created a parallel pathway for hemp-derived CBD edibles under USDA oversight, fragmenting compliance requirements. Stakeholders must monitor state legislative sessions for potency limit adjustments and track FDA rulemaking on CBD as a dietary supplement, as these decisions will determine which product formats remain viable and where capital should deploy next.
Market Dynamics
State-level THC potency caps and child-resistant packaging mandates are compressing product development cycles while nanoemulsion technology accelerates onset speed in beverage formulations. These dual pressures force manufacturers to reformulate faster and invest in precision dosing infrastructure.
Growth Catalysts
- Nanoencapsulation:Lipid-based emulsification and nanoencapsulation technologies compress onset latency from ninety minutes to fifteen minutes in beverage applications. Recreational consumers in California and Colorado prioritize these rapid-onset formats.
- Colorado's Marijuana Enforcement Division testing protocols:Standardized potency verification builds dispensary and consumer confidence in labeled THC content. Uniform testing reduces batch rejection rates and accelerates shelf placement.
- Recreational dispensary density:High-velocity retail footprints in Illinois and California create immediate distribution access for precisely dosed gummies and chocolates. Shelf stability of gummy formats matches dispensary inventory turnover requirements.
Market Restraints
- FDA interstate commerce prohibition:Federal prohibition prevents cross-border shipment of THC-infused products, fragmenting production into state-specific facilities. Manufacturers must replicate extraction and formulation capacity in each operating state.
- Cannabinoid input cost volatility:Wholesale isolate and distillate prices fluctuate with seasonal biomass harvests and extraction capacity constraints. Margin pressure concentrates in chocolate and baked goods categories with higher cannabinoid load per unit.
- Short shelf-life baked goods:Inconsistent cannabinoid distribution and oxidation sensitivity limit distribution radius for brownies and cookies. Retailers in Colorado and California favor stable gummy inventory over perishable alternatives.
Strategic Opportunities
- Underpenetrated Illinois beverage segment:Nanoemulsion-equipped production lines remain scarce in Midwest markets despite recreational legalization. First-mover beverage capacity captures premium positioning before competitive saturation.
- Hemp-derived CBD pathway under 2018 Farm Bill:USDA oversight permits interstate commerce and broader retail channel access compared to state-THC frameworks. National grocery and convenience store distribution becomes viable for compliant CBD edibles.
- Direct-to-consumer subscription models:California and Colorado consumers demonstrate repeat purchase loyalty for precisely dosed microdose formats. Automated replenishment bypasses dispensary shelf competition and captures lifetime value.
Industry Challenges
- Formulation chemist talent scarcity:Cross-functional expertise spanning food science, lipid chemistry, and cannabinoid stability remains concentrated in legacy cannabis markets. Recruitment competition intensifies between multi-state operators and craft producers.
- Child-resistant packaging compliance timelines:California's Department of Cannabis Control and Colorado's Marijuana Enforcement Division issue iterative packaging redesign mandates. Each revision requires six-to-twelve month retooling and inventory write-offs.
- Batch-to-batch homogeneity validation:Nanoemulsion stability testing and cannabinoid uniformity verification extend quality control cycles. Failed homogeneity tests trigger full batch destruction under state testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Edibles Market |
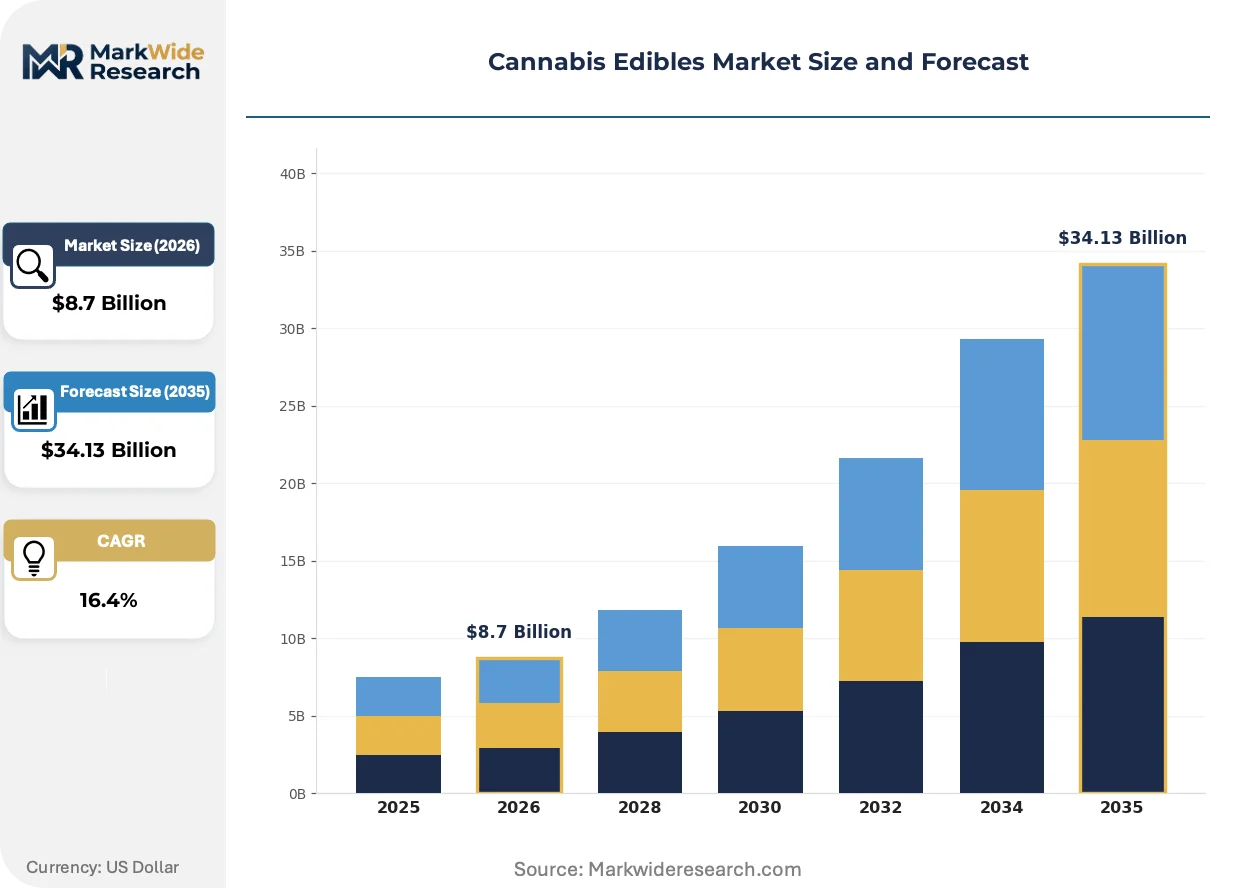
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummies, Chocolates, Baked Goods, Beverages Ingredients: THC, CBD, Flavoring Agents, Sweeteners Packaging Type: Bottles, Pouches, Boxes, Tins End User: Recreational Consumers, Medical Patients, Retailers, Dispensaries |
| Companies Covered | Cresco Labs, Cronos Group Inc., Curaleaf Holdings, Inc., WYLD, SNDL, Green Thumb Industries Inc., Tilray Inc., Kanha, Trulieve Cannabis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Edibles Market Evolving Landscape
Nanoemulsion technology is compressing onset windows while regulatory fragmentation intensifies state-specific formulation requirements. These forces reshape capital allocation toward rapid-onset beverage capacity and compliant packaging infrastructure.
Water-compatible nanoemulsion formulations are supplanting traditional lipid-based edibles in recreational consumer preference. Dispensary buyers in California and Colorado now prioritize fifteen-minute onset beverages over sixty-to-ninety minute gummy alternatives. This shift is compressing shelf space allocation and forcing legacy manufacturers to license nanoencapsulation patents or risk category exclusion.
California's Department of Cannabis Control potency cap deliberations and child-resistant packaging mandates are accelerating product format standardization. Manufacturers must redesign molds, labels, and closure systems to comply with quarterly regulatory updates. Gummy and chocolate producers with in-house packaging engineering capabilities capture faster approval timelines than outsourced alternatives.
Recreational consumers now prioritize discreet, precisely dosed microdose formats over legacy macrodose flower alternatives. Dispensary purchasing patterns in Illinois and Colorado show unit volume growth in 2.5mg and 5mg SKUs while 50mg-plus formats stagnate. This rotation pressures manufacturers to retool production lines for small-batch precision and invest in dose-verification automation.
Cannabis Edibles Market Segmentation
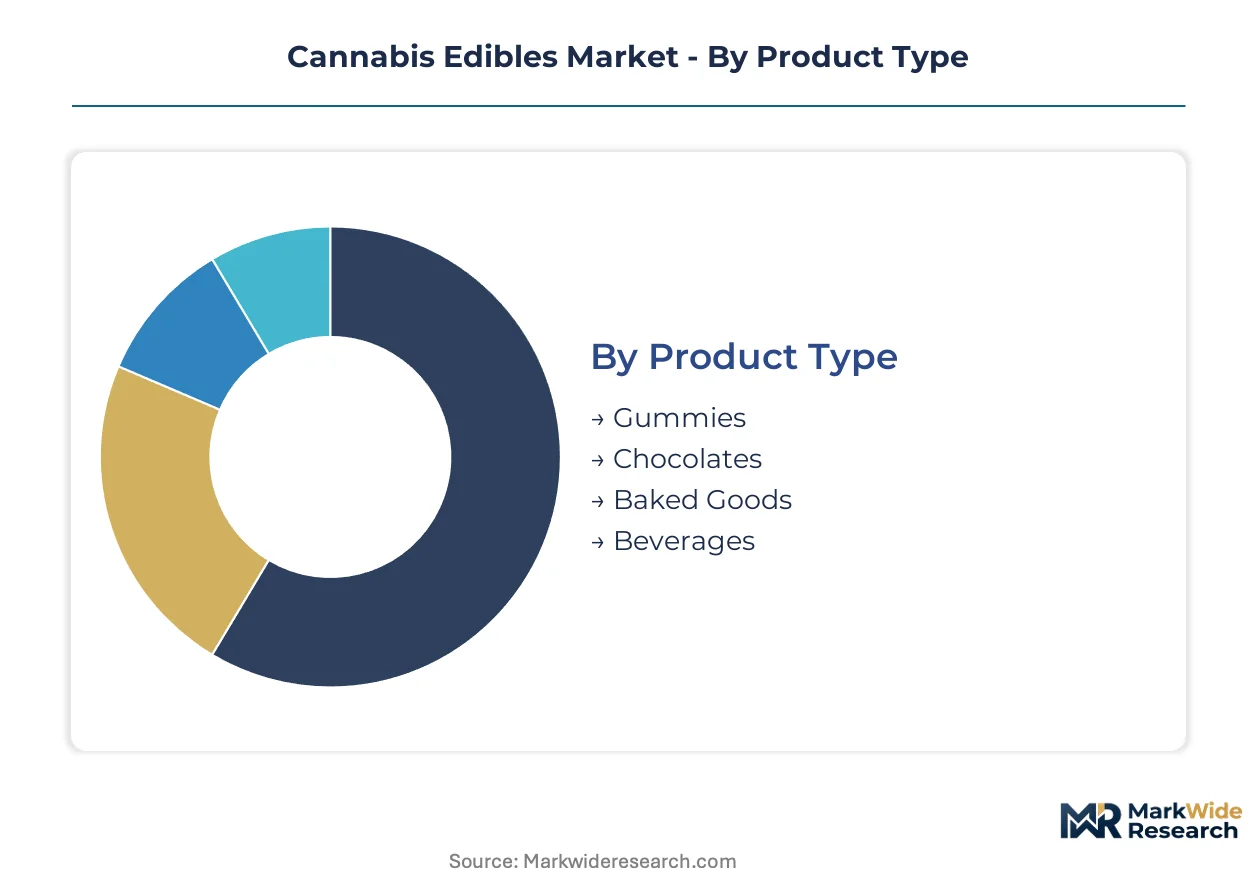
Cannabis edibles manufacturers segment production to align formulation chemistry with distinct consumption occasions and regulatory constraints. Product format, cannabinoid payload, and packaging architecture each determine shelf placement, margin capture, and compliance viability across state-level markets.
Product Type:
Gummies and chocolates face intensifying substitution pressure from nanoemulsion beverages as recreational consumers prioritize onset speed over shelf stability.
- Gummies:Gelatin or pectin matrices suspend measured cannabinoid doses with six-to-twelve month shelf stability. California and Colorado dispensaries prioritize gummy SKUs for inventory turnover velocity and child-resistant packaging compatibility.
- Chocolates:Lipid-based cocoa butter matrices deliver premium positioning through artisan craftsmanship and precise tempering. Illinois consumers demonstrate willingness-to-pay premiums for single-origin chocolate formulations with verified THC homogeneity.
- Baked Goods:Brownies and cookies suffer from inconsistent cannabinoid distribution and fourteen-day shelf ceilings. Colorado retailers increasingly reject baked goods in favor of stable alternatives.
- Beverages:Nanoemulsion technology enables water-compatible THC delivery with fifteen-minute onset latency. California recreational buyers are rotating shelf preferences toward rapid-onset formats.
Gummies retain volume leadership; beverages hold the steepest expansion curve.
Ingredients:
Input cost tiering separates commodity cannabinoid formulations from precision-dosed premium positioning.
- THC:Delta-9-tetrahydrocannabinol isolate and distillate dominate recreational intoxication applications. Colorado's Marijuana Enforcement Division mandates third-party potency verification for all THC inputs.
- CBD:Hemp-derived cannabidiol operates under USDA oversight per the 2018 Farm Bill, permitting interstate commerce absent from THC frameworks. National grocery channel access distinguishes CBD edibles from state-confined alternatives.
- Flavoring Agents:Natural fruit extracts and terpene profiles differentiate brand positioning in saturated gummy markets. WYLD leverages Pacific Northwest berry sourcing for regional identity.
- Sweeteners:Cane sugar, tapioca syrup, and sugar alcohol formulations balance taste with caloric positioning. Medical patients in Illinois demonstrate preference for low-glycemic sweetener alternatives.
THC inputs anchor revenue concentration; CBD ingredients are climbing the fastest as federal pathway clarity improves.
Packaging Type:
Compliance-driven packaging redesign cycles are reshaping supplier relationships and capital allocation.
- Bottles:Amber glass and opaque PET containers protect beverage nanoemulsions from UV degradation. California's Department of Cannabis Control mandates child-resistant closures with specific torque requirements.
- Pouches:Multi-layer barrier films extend shelf life for gummy formats while reducing shipping cube. Colorado regulators require opaque materials preventing product visibility.
- Boxes:Folding carton structures accommodate chocolate assortments with individual cavity protection. Premium chocolate producers favor rigid box formats for gift positioning.
- Tins:Metal slip-lid containers deliver vintage aesthetic for microdose mint and lozenge formats. Child-resistant tin mechanisms require six-to-twelve month engineering validation.
Pouches dominate unit volume; bottles are gaining share fastest with beverage category expansion.
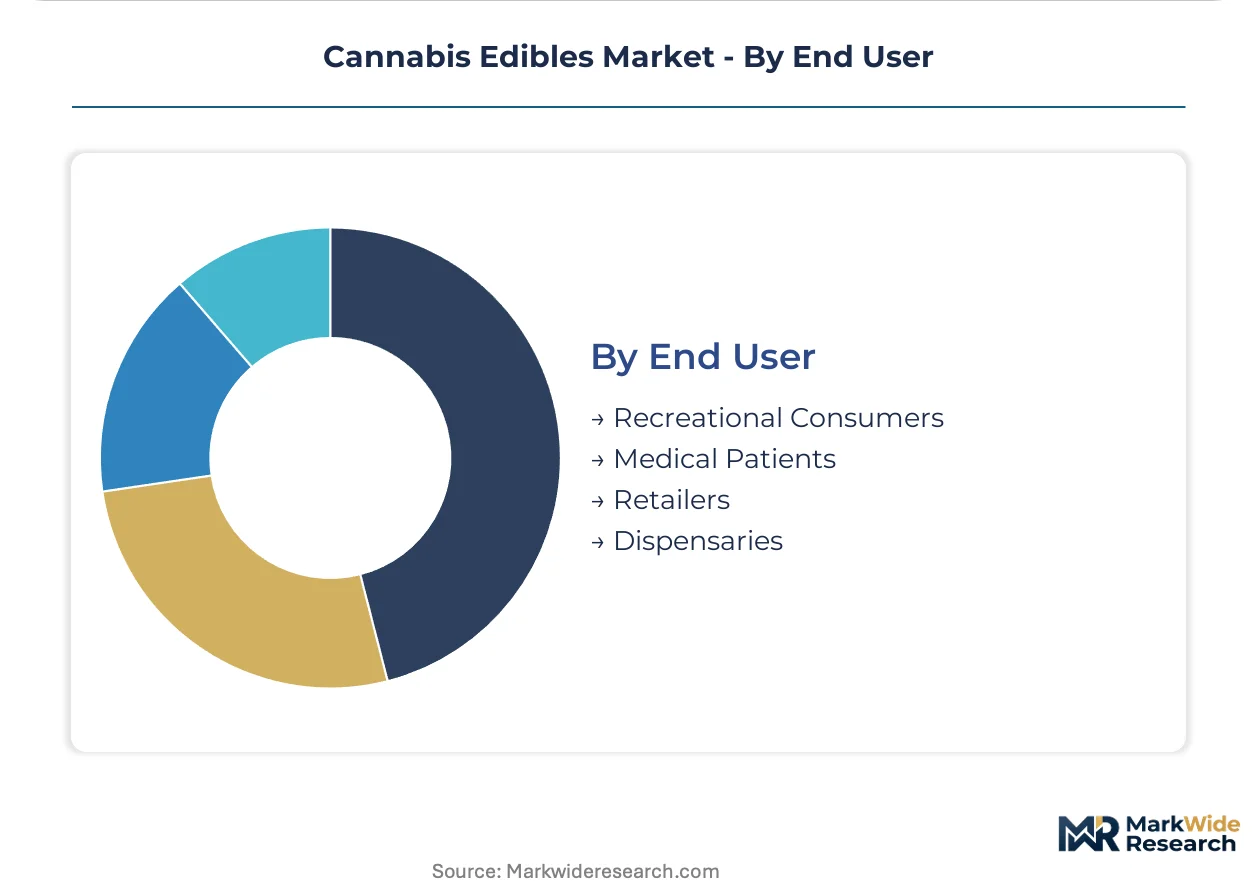
End User:
Customer type determines dose precision requirements, purchase frequency, and channel access constraints.
- Recreational Consumers:Adult-use buyers prioritize discreet formats, rapid onset, and social consumption compatibility. Nanoemulsion beverages capture this segment through fifteen-minute activation windows.
- Medical Patients:Therapeutic users require consistent dosing for symptom management with documented batch certificates. Illinois medical program participants favor 2.5mg microdose chocolates for daytime functionality.
- Retailers:Dispensary buyers optimize inventory turns against perishability risk and regulatory compliance burden. Shelf-stable gummies minimize write-off exposure.
- Dispensaries:Vertical retail operators demand backward-integrated supply security and exclusive SKU differentiation. Cresco Labs and Curaleaf negotiate captive production arrangements.
Recreational consumers retain volume leadership; medical patients hold the steepest expansion curve as therapeutic applications broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction and formulation capacity clusters in jurisdictions with mature regulatory frameworks, forcing manufacturers to replicate production infrastructure across state lines rather than centralize operations.
United States
California and Colorado dispensary networks drive premium gummy and chocolate demand through high-velocity retail footprints. Colorado's Marijuana Enforcement Division and California's Department of Cannabis Control enforce potency verification and child-resistant packaging standards that reshape product form factors quarterly. Los Angeles and Denver anchor multi-state operator distribution strategies, with nanoemulsion-equipped beverage lines capturing shelf space from legacy formats.
Canada
Federal legalization permits nationwide distribution of THC edibles through provincial retail monopolies, compressing the illicit market faster than fragmented U.S. state frameworks. Health Canada mandates plain packaging and strict THC limits per package that constrain premium positioning. Ontario and British Columbia concentrate licensed production capacity, with Vancouver-area extractors supplying nanoencapsulation inputs to formulation partners.
Germany
The 2024 cannabis legalization pilot programs create demand for precisely dosed edibles among adult-use consumers transitioning from unregulated sources. Germany's Federal Institute for Drugs and Medical Devices oversees quality standards that mirror pharmaceutical-grade requirements. Berlin and Hamburg emerge as early retail concentration points, with domestic manufacturers investing in EU-GMP certified extraction to serve both local and export demand.
Israel
Medical cannabis patient growth drives therapeutic edibles demand, with reimbursement coverage accelerating pharmacy channel penetration. Israel's Medical Cannabis Agency regulates production licensing and export permits that limit market entry to established operators. Tel Aviv-area formulation specialists supply cannabinoid stability expertise to European and North American partners seeking proven nanoencapsulation methods.
Australia
Prescription cannabis access expansion creates niche demand for consistent-dose edibles among chronic pain and palliative care patients. Australia's Therapeutic Goods Administration schedules cannabis products that constrain over-the-counter availability. Sydney and Melbourne host the primary compounding pharmacies and specialist clinics prescribing edible formats, with import dependencies creating opportunities for domestic manufacturing investment.
Cannabis Edibles Market Competitive Landscape
Concentration sits with multi-state operators controlling backward integration into cultivation and extraction. The vendor base stratifies across three tiers: capital-heavy vertical integrators with owned retail footprints, specialist formulators licensing nanoemulsion technology, and regional craft producers competing on localized flavor profiles. Competitive moves center on state-by-state capacity replication and packaging engineering capabilities that accelerate regulatory compliance timelines.
Among North American operators, Cresco Labs and Curaleaf Holdings exemplify the vertically integrated archetype through captive supply chains and owned dispensary networks. WYLD occupies a distinct position as a brand-centric formulator prioritizing fruit-infused gummy production with multi-state distribution partnerships rather than owned retail. These three anchors demonstrate divergent capital allocation strategies—retail ownership versus manufacturing specialization—within the same regulatory fragmentation constraints.
| Leading Market Players |
|---|
| Cresco Labs |
| Cronos Group Inc. |
| Curaleaf Holdings, Inc. |
| WYLD |
| SNDL |
| Green Thumb Industries Inc. |
| Tilray Inc. |
| Kanha |
| Trulieve Cannabis |
| Others |
Value Network & Pricing Analysis
Extraction capacity utilization in California and Colorado anchors price floors across state-confined markets, with manufacturers replicating formulation infrastructure rather than capturing interstate scale economies. This geographic fragmentation forces price differentiation across identical product formats based solely on local input costs and regulatory compliance burdens.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs cannabis edibles, with nanoemulsion beverages commanding premium positioning against commodity gummies. Price differentiation rests on onset speed verification and child-resistant packaging engineering rather than cannabinoid payload alone. Pricing pressure stems from wholesale distillate cost volatility as seasonal biomass harvests swing input availability. Medical patients in Illinois demonstrate highest price sensitivity to per-milligram THC costs, while recreational consumers in California prioritize rapid onset over unit economics.
Supply Chain Analysis
Inbound logistics costs spike where state-specific extraction facilities must replicate equipment across non-contiguous jurisdictions, with California-to-Colorado equipment shipments facing prolonged customs-style inspections at state borders. Supply concentration clusters in California, Colorado, and Illinois, with each state hosting captive cultivation, extraction, and formulation capacity. Raw material dependencies center on seasonal cannabis biomass, lipid emulsifiers, and nanoencapsulation surfactants. Single-source vulnerability concentrates in nanoemulsion equipment suppliers serving multiple state-confined producers. Distribution runs through licensed dispensary networks rather than conventional retail, with inventory ownership transferring at warehouse dock to vertically integrated retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cannabis edibles constitute a regulatory-entrenchment defensive moat, where early licensing advantages and state-specific compliance expertise create durable barriers against later entrants lacking operational track records.
For Market Incumbents: Fortify market position by deepening backward integration into in-house nanoemulsion production capacity before patent licensing windows narrow. Accelerate child-resistant packaging engineering capabilities to compress six-to-twelve month compliance cycles against Colorado's Marijuana Enforcement Division iterative mandates. Cresco Labs and Curaleaf demonstrate how captive retail footprints lock in shelf space against emerging formulators. For New Entrants and Emerging Players: Lead with underpenetrated beverage segments in Illinois and emerging Midwest markets where nanoemulsion-equipped production lines remain scarce despite recreational legalization. Target direct-to-consumer subscription models in California and Colorado, where automated replenishment bypasses dispensary shelf competition and captures lifetime value from microdose-loyal consumers. Emphasize rapid-onset technology partnerships rather than owned extraction infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialist formulators licensing nanoencapsulation patents over capital-heavy vertical integrators facing state-by-state replication costs. Long-term viability hinges on regulatory pathway clarity for interstate commerce and CBD dietary supplement classification. Acquisition targets should demonstrate proven batch homogeneity validation and packaging engineering capabilities. Watch FDA rulemaking on CBD as dietary supplement as the critical inflection signal for national grocery channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Nanoemulsion Patent Licensing | Accelerates beverage onset speed to fifteen minutes, displacing legacy gummy formats in California dispensaries. |
| Child-Resistant Packaging Engineering | Compresses compliance timelines against California Department of Cannabis Control iterative redesign mandates. |
| Direct-to-Consumer Subscription Launch | Bypasses dispensary shelf competition and captures lifetime value from microdose-loyal Colorado consumers. |
| Backward Integration into Extraction | Secures cannabinoid input supply against wholesale distillate price volatility from seasonal biomass swings. |
| Illinois Beverage Capacity Buildout | Captures premium positioning in underpenetrated Midwest market before competitive saturation emerges. |
Research Methodology
Cross-validation between primary interviews with extraction facility operators, formulation chemists, dispensary purchasing managers, and state regulatory affairs directors anchors the qualitative findings against secondary validation. Secondary sources include FDA rulemaking dockets, Colorado Marijuana Enforcement Division testing protocols, California Department of Cannabis Control packaging mandates, and state-level cannabis licensing databases. Bottom-up demand modeling from dispensary SKU-level velocity data triangulates against top-down market sizing from state tax revenue disclosures and licensed production capacity filings.
Sensitivity analysis across potency cap scenarios and interstate commerce policy alternatives frames the projection horizon, with segmentation modeling across product format, cannabinoid payload tier, packaging architecture, and end-user type. CAGRs derive from fitted growth curves against historical state-level adoption patterns, adjusted for nanoemulsion technology diffusion rates and regulatory timeline uncertainty. Forecast inputs incorporate dispensary density trajectories, formulation chemist labor market tightness, and child-resistant packaging compliance cost inflation.
Forecasts assume regulatory continuity in California, Colorado, and Illinois state frameworks; material federal preemption or interstate commerce liberalization would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Medical Cannabis Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Missouri Legal Cannabis Market
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Trichome Separator/Extractor Market