
 Middle East and Africa Cannabidiol (CBD) Market | 2026-2036
Middle East and Africa Cannabidiol (CBD) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cannabidiol (CBD) Market Foresight
Good Manufacturing Practice certification for active pharmaceutical ingredients is redrawing competitive boundaries across the Middle East and Africa CBD landscape. Aurora Cannabis leverages its EU-GMP certified cultivation facilities to anchor supply relationships with licensed distributors in Israel and South Africa. ENDOCA specializes in pharmaceutical-grade extraction protocols that differentiate its product portfolio from wellness-oriented competitors. Elixinol Wellness sustains brand recognition through health store channels despite regulatory fragmentation between Gulf Cooperation Council states and sub-Saharan markets.
Cannabidiol denotes a non-psychoactive cannabinoid extracted from Cannabis sativa L., typically refined to concentrations exceeding 98% purity through supercritical CO2 or ethanol extraction for therapeutic formulations. Its primary commercial purpose centers on anxiolytic, anti-inflammatory, and anticonvulsant applications across human and veterinary health segments. Oils and tinctures dominate current revenue pools due to established dosing protocols and physician familiarity, while topicals capture expanding cosmetics sector interest in Israel and the UAE. Wellness applications through nutraceutical channels represent the fastest-growing end-user segment as consumer education accelerates in urban South African and Israeli markets.
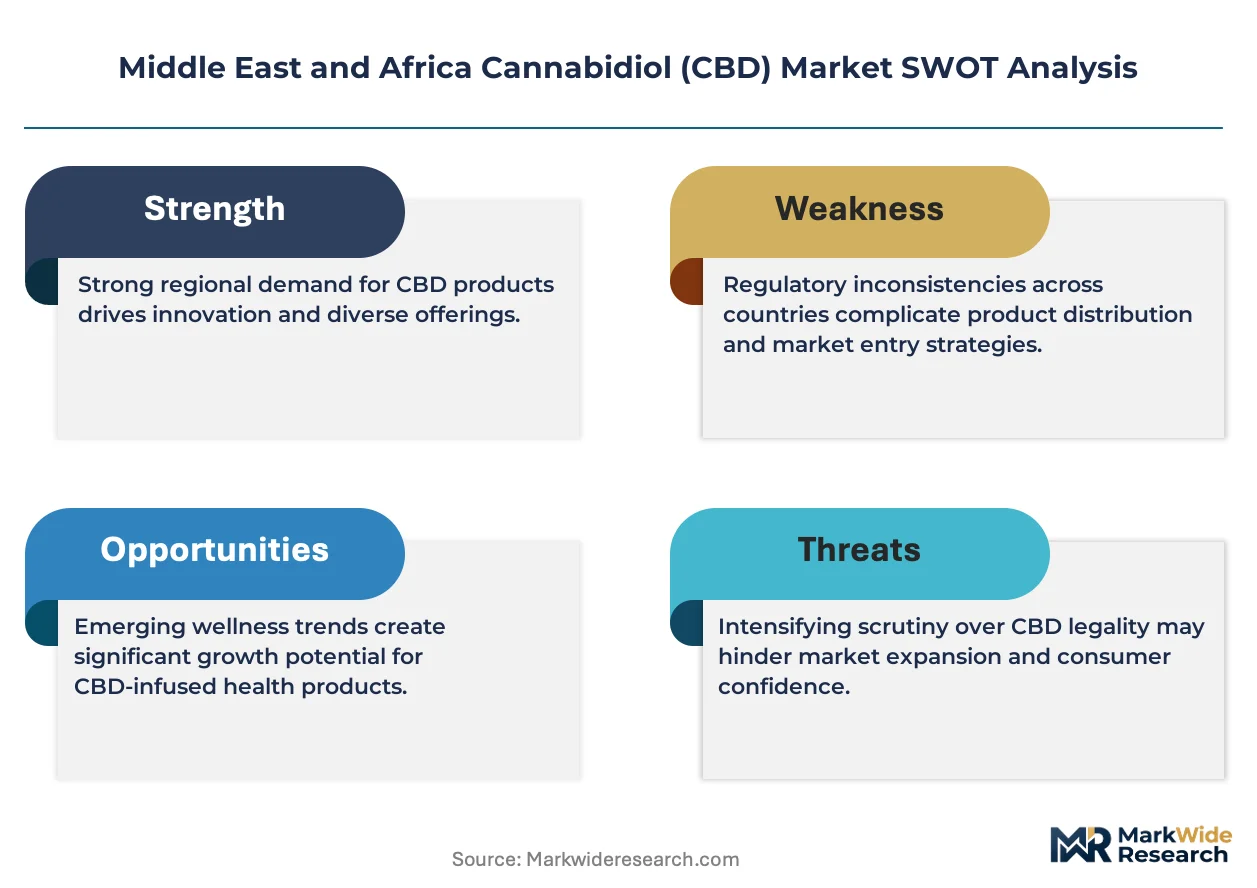
South Africa's SAHPRA governs CBD scheduling with tiered concentration thresholds, while Israel's Medical Cannabis Unit under the Ministry of Health maintains stringent cultivation and export licensing frameworks. The UAE's Ministry of Health and Prevention permits only zero-THC isolate formulations, creating product standard divergence that complicates cross-border formulation strategies. Saudi Arabia's SFDA maintains prohibition on psychoactive cannabis derivatives, though industrial hemp derivatives for cosmetic use face evolving interpretation. Stakeholders must monitor harmonization efforts between SAHPRA and Israel's Medical Cannabis Unit, as bilateral recognition agreements would reshape regional supply chain economics and manufacturing location decisions.
Market Dynamics
SAHPRA's tiered scheduling framework is decomposing traditional pharmaceutical distribution hierarchies across South Africa, forcing manufacturers to rebuild compliance infrastructure around concentration-based licensing tiers rather than blanket prohibitions.
Growth Catalysts
- Epilepsy formulation demand:South African pharmaceutical manufacturers are expanding procurement of pharmaceutical-grade CBD isolates for anticonvulsant drug development, creating pull-through for EU-GMP certified suppliers.
- SAHPRA rescheduling:The regulator's 2019 amendment to Schedules 4 and 6 opened regulated pathways for low-dose CBD products, shifting previously illicit trade into taxable commercial channels.
- Israeli export licensing:The Medical Cannabis Unit's streamlined export protocols are attracting contract manufacturing investment from Middle Eastern distributors seeking GMP-compliant supply.
Market Restraints
- THC threshold fragmentation:UAE's MOHAP mandates zero-THC isolates while SAHPRA permits trace concentrations, forcing manufacturers to maintain separate formulation lines for adjacent markets.
- Supercritical CO2 equipment scarcity:Pharmaceutical-grade extraction machinery concentrates among Israeli and South African facilities, creating input bottlenecks for new market entrants.
- Synthetic CBD substitution:Chemically synthesized cannabidiol from Chinese and Indian suppliers is compressing margins for agricultural-derived products in cosmetics applications.
Strategic Opportunities
- Veterinary therapeutics:Israeli veterinary clinics are piloting CBD formulations for canine osteoarthritis and equine anxiety, opening a regulatory pathway with lower compliance burdens than human pharmaceuticals.
- Topical cosmeceuticals:Dubai's luxury retail channels are absorbing premium CBD-infused skincare lines, exploiting MOHAP's cosmetic-use interpretation for non-psychoactive hemp derivatives.
- SAHPRA-Israeli harmonization:Bilateral recognition agreements under discussion would enable mutual GMP certification acceptance, collapsing duplicate facility audit costs for cross-border suppliers.
Industry Challenges
- Analytical chemistry talent scarcity:South African laboratories face acute shortages of chromatography specialists capable of validating THC content below 0.001% for export certification.
- EU-GMP audit timelines:Israeli cultivation facilities report 18-24 month backlogs for certification renewal, freezing capacity expansion plans despite order book growth.
- Cold chain integrity:Temperature excursions during trans-African logistics are degrading tincture potency, requiring capital deployment into refrigerated distribution infrastructure that lacks regional density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cannabidiol (CBD) Market |
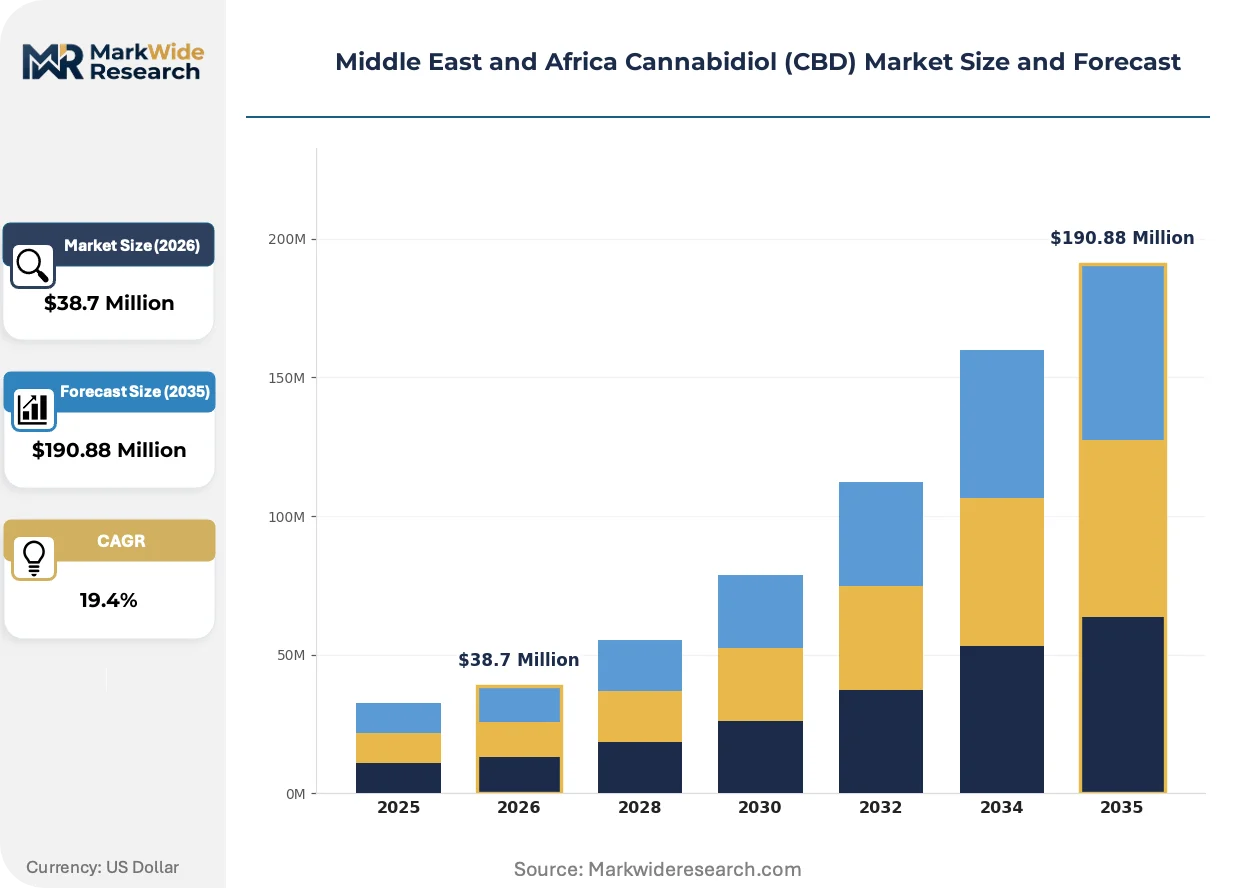
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $190.88 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
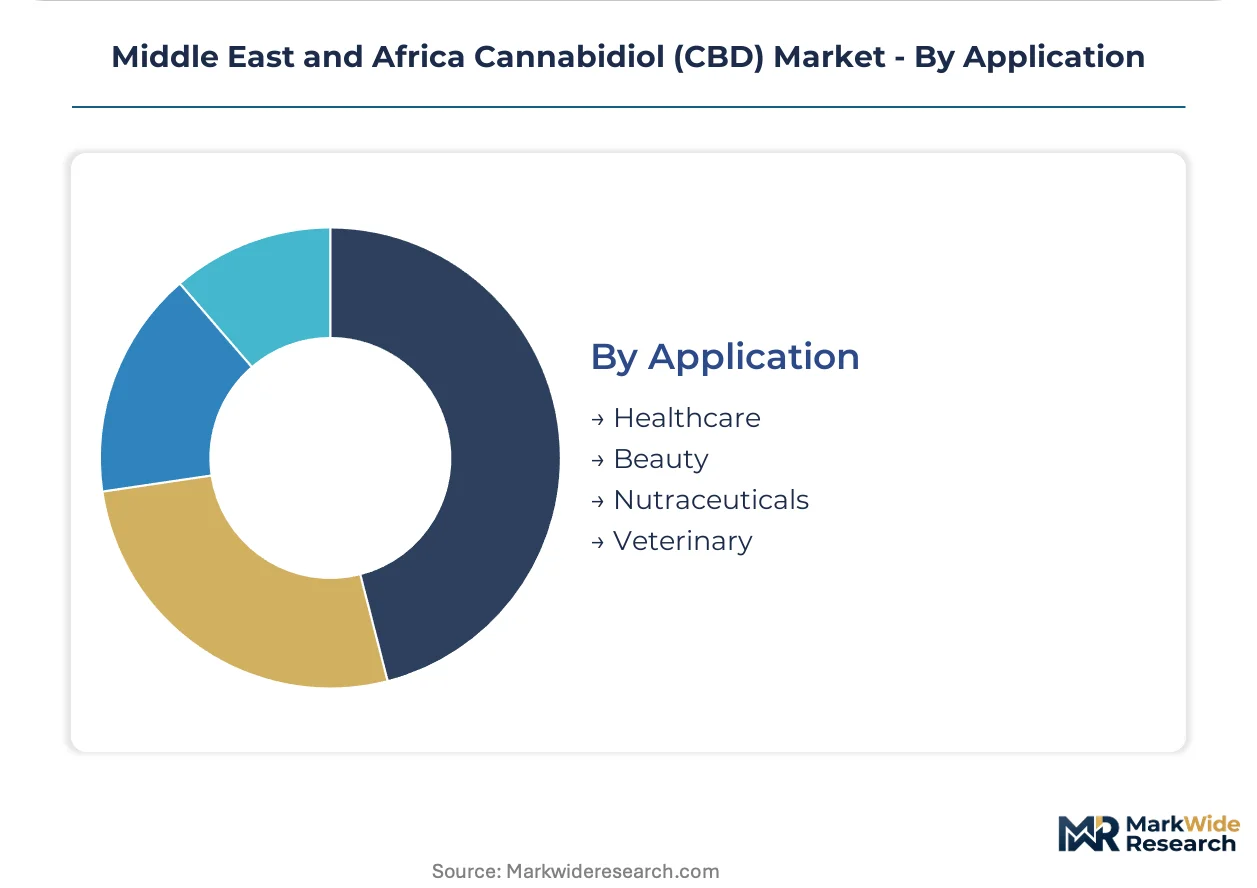
| Segmentation | Product Type: Oils, Tinctures, Edibles, Topicals End User: Pharmaceuticals, Cosmetics, Food & Beverage, Wellness Distribution Channel: Online Retail, Health Stores, Pharmacies, Dispensaries Application: Healthcare, Beauty, Nutraceuticals, Veterinary |
| Companies Covered | CV Sciences, VIVO Cannabis, Gaia Herbs, Hemp Phoena Holdings, Medical Marijuana, Elixinol Wellness, Medterra CBD, Aurora Cannabis, ENDOCA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cannabidiol (CBD) Market Shifts & Advancements
Supercritical CO2 extraction protocols are fragmenting competitive advantage across the Middle East and Africa CBD landscape, separating pharmaceutical-grade suppliers from wellness-oriented competitors through purity thresholds and certification depth.
Supercritical CO2 extraction with inline winterization is decomposing the traditional trade-off between throughput and pharmaceutical purity. Israeli contract manufacturers are retrofitting extraction trains to achieve 99.5% CBD isolate consistency, enabling supply relationships with European pharmaceutical distributors that ethanol-based competitors cannot satisfy. This technology compression is marginalizing mid-scale ethanol operators in South Africa's wellness segment.
SAHPRA's 2023 technical guidance on stability testing is forcing reformulation of oil-based tinctures previously marketed under provisional registrations. The regulation mandates 24-month shelf-life validation with THC degradation tracking, compelling manufacturers to invest in accelerated aging infrastructure. South African distributors are responding by consolidating supplier relationships around facilities with in-house ICH-compliant stability chambers.
Physician education programs sponsored by Israeli medical cannabis clinics are compressing patient acquisition cycles for CBD-dominant therapies. Traditional reliance on wellness retail channels is yielding to hospital-based pain management referrals in Tel Aviv and Johannesburg, where formulary inclusion decisions follow clinical trial data rather than consumer marketing. This channel rotation is elevating documentation requirements for batch-specific certificates of analysis.
Middle East and Africa Cannabidiol (CBD) Market Segmentation
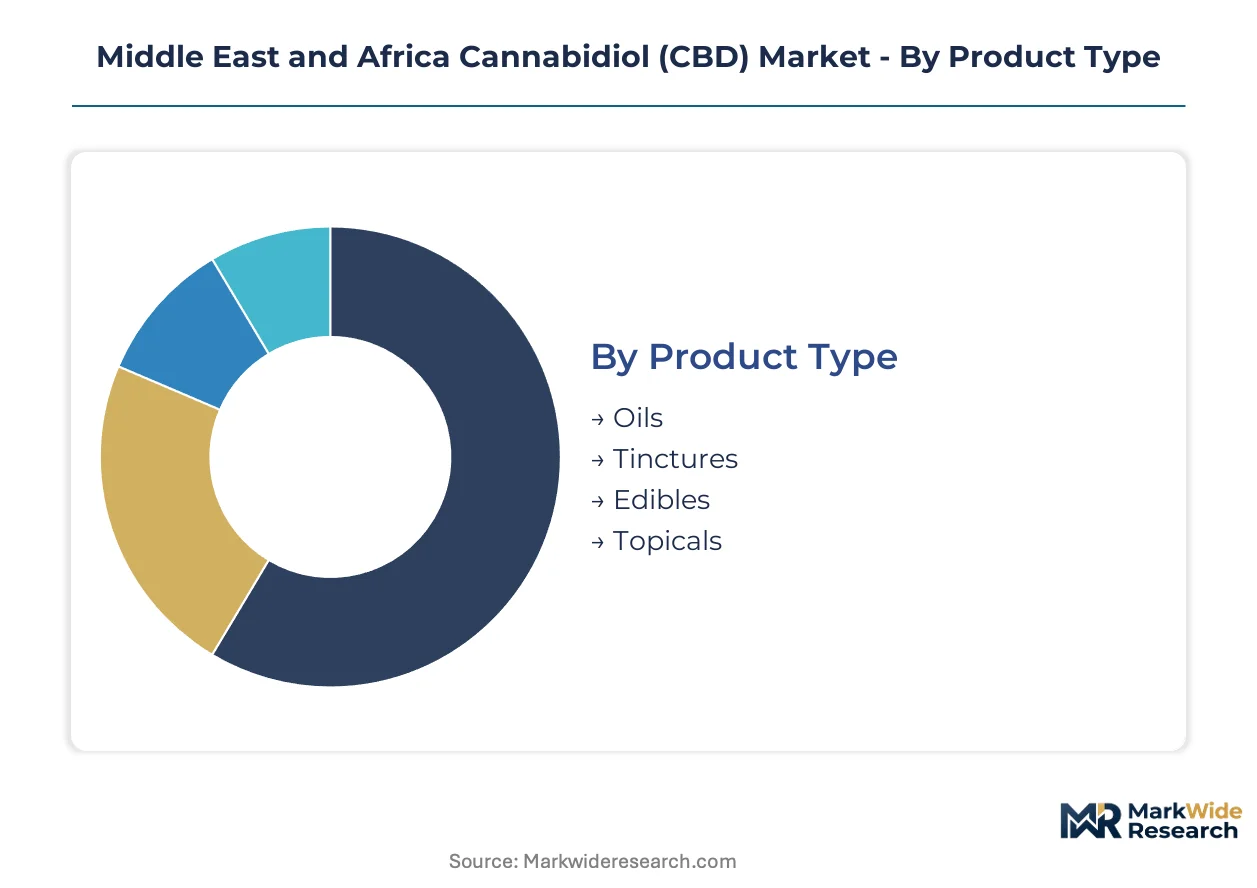
Regulatory fragmentation across SAHPRA, Israel's Medical Cannabis Unit, and UAE's MOHAP creates divergent product specifications that reshape segment economics. Manufacturers must configure formulation lines around jurisdiction-specific THC thresholds rather than unified regional standards.
Product Type:
SAHPRA's concentration-based scheduling tiers fragment manufacturing requirements, with Schedule 4 and Schedule 6 pathways demanding distinct purity certifications and stability documentation.
- Oils:Lipid-based formulations dominate pharmaceutical procurement in South Africa, where SAHPRA mandates 24-month shelf-life validation with THC degradation tracking for anticonvulsant applications. Israeli distributors favor oils for hospital formulary inclusion due to established physician dosing protocols.
- Tinctures:Alcohol-extracted suspensions capture wellness channel volume in urban South African markets, though cold chain deficiencies during trans-African logistics degrade potency and elevate rejection rates at retail.
- Edibles:Gummy and capsule formats face MOHAP prohibition in the UAE, restricting addressable markets to South Africa and Israel where food-grade GMP certification suffices.
- Topicals:CBD-infused skincare lines exploit MOHAP's cosmetic-use interpretation for non-psychoactive hemp derivatives in Dubai's luxury retail channels.
Oils handle the majority of throughput; topicals are the fastest mover on share.
End User:
Customer procurement sophistication varies sharply between pharmaceutical formulators demanding EU-GMP certification and wellness retailers accepting provisional registrations.
- Pharmaceuticals:South African manufacturers expanding epilepsy and chronic pain formulations drive demand for 98%+ purity isolates with batch-specific certificates of analysis. SAHPRA's rescheduling shifted previously illicit trade into taxable channels with full GMP compliance requirements.
- Cosmetics:Dubai's premium retail sector absorbs high-margin skincare lines, though synthetic CBD substitution from Asian suppliers compresses margins for agricultural-derived inputs.
- Food & Beverage:Israeli regulatory clarity on novel food status lags behind cosmetics, constraining product development timelines relative to topical applications.
- Wellness:Health store channels in Johannesburg and Cape Town sustain volume despite regulatory fragmentation, with consumer education accelerating urban adoption.
Pharmaceuticals command the highest certification burden; cosmetics are climbing the fastest on margin contribution.
Distribution Channel:
Channel selection determines compliance documentation depth, with pharmacies and dispensaries requiring full SAHPRA or Medical Cannabis Unit licensing versus lighter wellness retail obligations.
- Online Retail:E-commerce platforms face SAHPRA enforcement gaps for cross-border shipments, though Israeli operators leverage streamlined export protocols to serve Middle Eastern distributors.
- Health Stores:Physical wellness retail in South Africa consolidates supplier relationships around facilities with in-house ICH-compliant stability chambers following SAHPRA's 2023 technical guidance.
- Pharmacies:Hospital-based pain management referrals in Tel Aviv and Johannesburg rotate demand toward formulary inclusion decisions based on clinical trial data rather than consumer marketing.
- Dispensaries:Licensed cannabis-specific outlets in Israel concentrate CBD-dominant therapy distribution under Medical Cannabis Unit oversight.
Pharmacies anchor prescription volume; online retail is expanding most quickly on reach.
Application:
End-use specifications fragment around human versus veterinary regulatory pathways, with animal health applications offering lower compliance burdens and faster commercialization timelines.
- Healthcare:Anticonvulsant and anxiolytic formulations in South Africa and Israel require full pharmaceutical registration with stability testing infrastructure that mid-scale ethanol operators cannot satisfy.
- Beauty:Cosmeceutical absorption in Dubai exploits regulatory ambiguity around hemp-derived ingredients, though zero-THC MOHAP mandates constrain formulation flexibility.
- Nutraceuticals:Wellness applications through supplement channels represent the steepest expansion trajectory as consumer education accelerates in urban South African and Israeli markets.
- Veterinary:Israeli veterinary clinics pilot canine osteoarthritis and equine anxiety formulations, opening a regulatory pathway with reduced documentation requirements relative to human pharmaceuticals.
Healthcare absorbs the largest compliance investment; nutraceuticals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAHPRA's tiered scheduling framework and Israel's export licensing reforms are redirecting investment flows across the Middle East and Africa CBD landscape, with regulatory clarity in specific jurisdictions creating concentrated manufacturing clusters.
South Africa
Pharmaceutical manufacturers in Johannesburg and Cape Town are expanding procurement of pharmaceutical-grade CBD isolates for epilepsy formulations. SAHPRA's 2019 amendment to Schedules 4 and 6 established concentration-based licensing tiers that shifted previously illicit trade into taxable commercial channels. The Western Cape industrial zone hosts extraction facilities retrofitting for EU-GMP certification to serve export markets.
Israel
The Medical Cannabis Unit's streamlined export protocols are attracting contract manufacturing investment from Middle Eastern distributors seeking GMP-compliant supply. Tel Aviv's hospital-based pain management clinics are rotating demand toward formulary inclusion decisions based on clinical trial data. Israeli cultivation facilities report certification renewal backlogs that freeze capacity expansion despite order book growth.
United Arab Emirates
Dubai's luxury retail channels are absorbing premium CBD-infused skincare lines exploiting MOHAP's cosmetic-use interpretation for non-psychoactive hemp derivatives. The Ministry of Health and Prevention mandates zero-THC isolate formulations, creating product standard divergence from adjacent markets. Jebel Ali free zone operators are configuring separate formulation lines to satisfy this regulatory threshold.
Saudi Arabia
Industrial hemp derivatives for cosmetic use face evolving interpretation under SFDA oversight, though psychoactive cannabis derivatives remain prohibited. Riyadh-based distributors are monitoring regulatory signals for potential market entry timing. The Eastern Province petrochemical cluster offers precursor chemical access should synthetic CBD pathways open.
Egypt
Cairo's pharmaceutical import distributors are observing SAHPRA-Israeli harmonization discussions for bilateral recognition agreement signals that would reshape regional supply chain economics. The country's national pharmaceutical regulator maintains conservative scheduling that limits domestic formulation opportunities. Alexandria's port infrastructure positions for transshipment should regulatory barriers ease.
Middle East and Africa Cannabidiol (CBD) Market Competitive Landscape
Player mix skews toward vertically integrated cultivation-extraction operators and specialized pharmaceutical-grade suppliers. Market structure concentrates around facilities with EU-GMP certification that can satisfy hospital formulary requirements in Tel Aviv and Johannesburg. Two strategic archetypes dominate: Israeli contract manufacturers leveraging streamlined export protocols, and South African operators rebuilding compliance infrastructure around SAHPRA's concentration tiers. Competitive moves center on certification depth expansion and supplier relationship consolidation following the regulator's 2023 stability testing guidance.
Among North American-listed operators, Aurora Cannabis and CV Sciences occupy positions within the certified-supplier tier, with Aurora leveraging cultivation infrastructure and CV Sciences representing the wellness-oriented segment. ENDOCA anchors the pharmaceutical-grade extraction archetype, while Elixinol Wellness exemplifies brand recognition sustained through health store channels despite regulatory fragmentation. These three companies represent distinct competitive vectors: certified supply, wellness retail, and pharmaceutical extraction protocols.
| Leading Market Players |
|---|
| CV Sciences |
| VIVO Cannabis |
| Gaia Herbs |
| Hemp Phoena Holdings |
| Medical Marijuana |
| Elixinol Wellness |
| Medterra CBD |
| Aurora Cannabis |
| ENDOCA |
| Others |
Supply & Pricing Matrix
Synthetic CBD substitution from Chinese and Indian chemical manufacturers is compressing agricultural-derived product margins while simultaneously shifting procurement geography toward petrochemical clusters and away from hemp cultivation belts. This input displacement forces South African and Israeli formulators to defend pricing power through certification depth rather than feedstock origin.
Pricing Analysis
Certification grade creates the primary spread between pharmaceutical and wellness tiers, with EU-GMP isolates commanding substantial premiums over provisional registrations. Three-tier pricing structure separates hospital formulary grades from health store channels and unlicensed wellness products. Cost compression in cosmetics applications intensifies as synthetic alternatives penetrate skincare formulations. Wellness retailers exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize batch documentation over unit economics.
Supply Chain Analysis
Israel and South Africa anchor pharmaceutical-grade extraction capacity, with Israeli facilities specializing in supercritical CO2 protocols and South African operators retrofitting for EU-GMP compliance. Extraction machinery draws from German and Italian engineering suppliers, while chromatography reagents feed from Swiss and US chemical manufacturers. Single-source vulnerability concentrates in supercritical equipment where 18-24 month lead times freeze expansion timelines. Distribution runs through licensed distributors in Tel Aviv and Johannesburg before reaching hospital formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAHPRA's tiered rescheduling framework constitutes a regulatory inflection that transforms previously illicit CBD trade into taxable pharmaceutical channels, creating a high-growth disruption window for compliance-ready operators.
For Market Incumbents: Consolidate supplier relationships around facilities with in-house ICH-compliant stability chambers following SAHPRA's 2023 technical guidance. Deepen backward integration into captive hemp cultivation in South Africa's Western Cape to secure feedstock against synthetic substitution. Defend market position by accelerating EU-GMP certification renewal timelines before competitor capacity freezes ease. For New Entrants and Emerging Players: SAHPRA's Schedule 4 fast-track pathway offers the most penetrable entry point for low-dose wellness products with reduced documentation burdens. Target veterinary therapeutics in Israel, where canine osteoarthritis formulations face lower compliance barriers than human pharmaceuticals. Pursue white-label manufacturing partnerships with Dubai luxury retailers seeking zero-THC skincare lines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Israeli contract manufacturers holding export licenses but facing certification renewal backlogs. Five-to-ten year viability hinges on bilateral SAHPRA-Israeli harmonization enabling mutual GMP recognition. Monitor stability testing infrastructure deployment as the signal for manufacturing consolidation readiness.| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Fast-Track | Enables supply relationships with Johannesburg hospital formularies previously closed to provisional registrations. |
| Veterinary Therapeutic Pilot Programs | Opens regulatory pathway with reduced documentation for Israeli canine osteoarthritis formulations. |
| Stability Testing Infrastructure Investment | Satisfies SAHPRA's 24-month shelf-life validation mandate for anticonvulsant oil formulations. |
| Backward Integration into Hemp Cultivation | Secures agricultural feedstock against synthetic CBD margin compression in cosmetics applications. |
| Bilateral Harmonization Lobbying | Collapses duplicate facility audit costs for cross-border suppliers serving SAHPRA and Israeli Medical Cannabis Unit. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAHPRA scheduling amendments, Israeli Medical Cannabis Unit export protocols, and UAE MOHAP cosmetic guidance documents. Conversations with pharmaceutical procurement managers at Johannesburg manufacturers, regulatory affairs leads at Cape Town extraction facilities, and formulary directors at Tel Aviv hospital systems informed demand-side calibration. Customs records, stability testing laboratory certifications, and GMP audit timelines provided supply-side anchors. Bottom-up facility capacity estimates triangulated against top-down market value reconstructions.
Segmentation dimensions modeled include product purity tier, end-use application, distribution channel licensing depth, and jurisdiction-specific THC threshold compliance. CAGRs derive from regression analysis of historical procurement volumes against regulatory event timing across the analysis window. Forecast inputs incorporate SAHPRA concentration tier adoption curves and Israeli export license issuance rates.
Decision-makers should treat outputs as directional under assumptions of sustained SAHPRA-Israeli regulatory divergence and stable synthetic CBD pricing; material deviation in harmonization timelines or feedstock cost shifts would warrant model refresh. Recalibration cycles align with material shifts in scheduling amendments and bilateral recognition agreement announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market